
 Clouding Agents Market | 2026-2036
Clouding Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Clouding Agents Market Outlook
Specialty ingredient distribution is reconfiguring as regional distributors consolidate procurement for beverage compounders across Southeast Asia and Latin America. Cargill leverages its integrated citrus oil supply chain to anchor natural clouding agent production at scale. Kerry Ingredients competes through formulation partnerships that extend beyond commodity supply into customized emulsion systems. ADM Wild Flavours sustains R&D intensity in polymeric clouding technologies for reduced-calorie drink applications.
Clouding agents are colloidal dispersions—typically oil-in-water emulsions or suspended microparticles—that scatter light to impart turbidity and visual body to otherwise transparent liquids. These systems generally comprise modified starches, gum arabic, or titanium dioxide at particle sizes between 0.1 and 10 micrometers, manufactured through high-pressure homogenization or microfluidization to achieve stable opacity without sedimentation. The food and beverage application category dominates volume as processors reformulate away from artificial additives toward label-friendly opacity solutions. Natural product types are expanding fastest as formulators replace synthetic and inorganic alternatives with citrus fiber, whey protein, or modified starch systems that satisfy clean-label positioning.
EFSA maintains active evaluation protocols for titanium dioxide food applications, while FDA continues to monitor GRAS status for novel plant-derived clouding systems entering the US supply chain. REACH registration requirements in Europe constrain synthetic polymer introductions, shifting development investment toward bio-based emulsion technologies. ASEAN's harmonized food additive standards under the AEC Blueprint create both compliance thresholds and market access pathways for regional suppliers. Stakeholders must track evolving permissible daily intake rulings across multiple jurisdictions to anticipate reformulation cycles and raw material qualification timelines.
Market Dynamics
Clean-label mandates across ASEAN food additive regulations are forcing beverage formulators to abandon titanium dioxide and synthetic opacity systems, compressing qualification timelines for natural alternatives and redrawing procurement relationships between ingredient distributors and tropical juice processors.
Growth Catalysts
- EFSA Titanium Dioxide Re-evaluation:The European regulator's scrutiny of E171 food applications creates immediate displacement demand for citrus fiber and modified starch clouding systems in export-oriented beverage facilities.
- ASEAN Economic Community Harmonization:The AEC Blueprint's standardized food additive approvals reduce cross-border compliance friction, enabling Indonesian and Thai processors to source regionally without reformulating for each market.
- High-Pressure Homogenization Advances:Equipment manufacturers have refined microfluidization parameters for natural emulsions, achieving particle size stability previously exclusive to synthetic systems.
Market Restraints
- Citrus Oil Supply Concentration:Brazil and Florida account for the majority of d-limonene feedstock, exposing natural clouding agent producers to climate-driven harvest volatility and price spikes.
- REACH Registration Burden:ECHA requirements for novel synthetic polymers constrain European development investment, slowing innovation cycles for engineered opacity solutions.
- Technical Performance Gap:Whey protein and starch-based systems exhibit inferior shelf-life stability compared to titanium dioxide, limiting adoption in ambient-distribution beverage formats.
Strategic Opportunities
- Reduced-Calorie Beverage Formats:Polymeric clouding technologies enable opacity in water-based drinks without caloric load from juice solids, opening positioning in wellness-oriented product lines.
- Direct-to-Processor Digital Procurement:Specialty ingredient platforms are bypassing traditional distributor layers, allowing compounders in Vietnam and Philippines to access qualified natural systems faster.
- US GRAS Pathway Acceleration:FDA's streamlined review for plant-derived opacity ingredients creates entry opportunity for ASEAN suppliers seeking North American market access.
Industry Challenges
- Emulsion Stability Expertise Shortage:Formulation chemistry talent capable of optimizing natural colloidal systems remains concentrated at legacy ingredient houses, constraining independent processor capabilities.
- Clean-Label Certification Complexity:Multiple competing standards—organic, non-GMO, natural flavor—require parallel documentation streams, extending product qualification timelines by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clouding Agents Market |
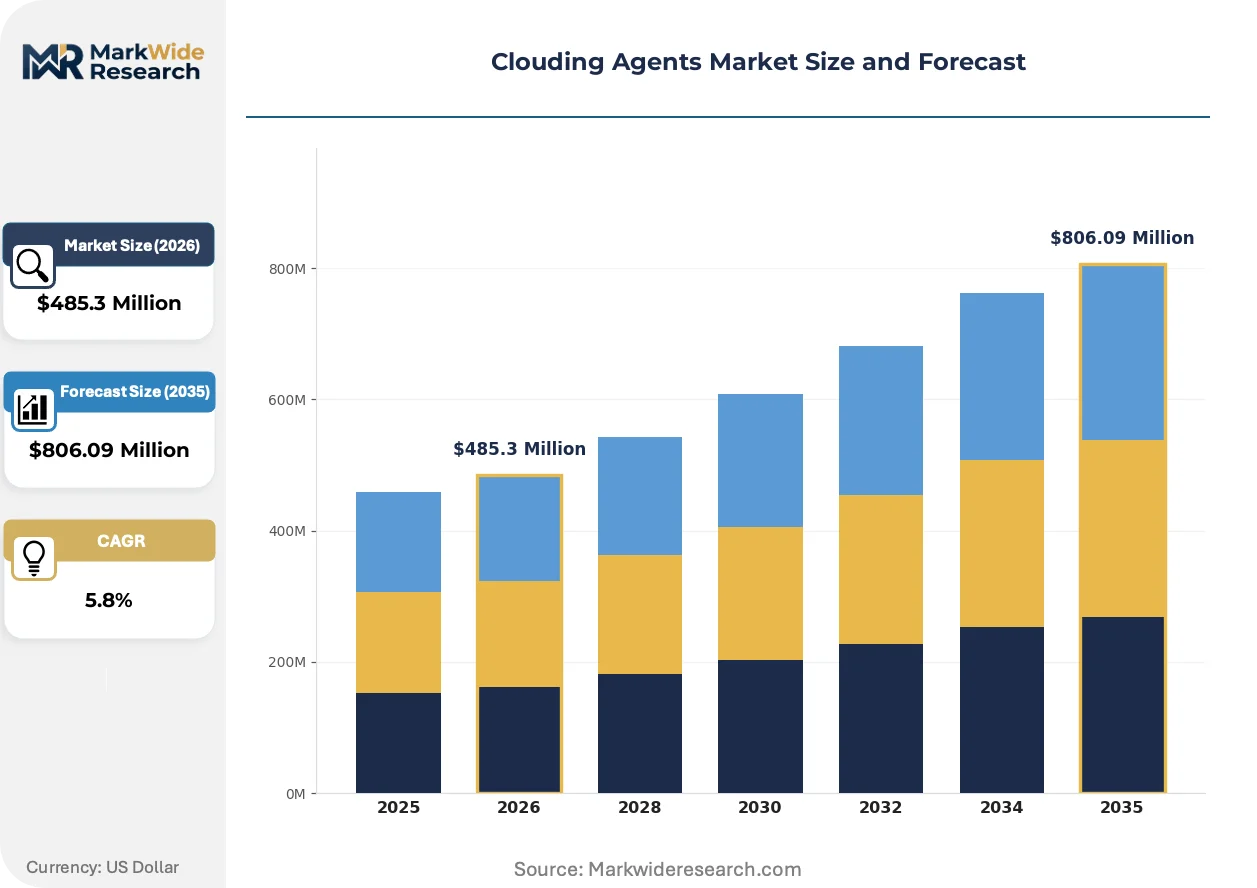
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $806.09 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric, Natural, Synthetic, Inorganic Application: Food & Beverage, Personal Care, Pharmaceutical, Household Form: Liquid, Powder, Granular, Emulsion End User: Food Manufacturers, Cosmetic Companies, Pharma Firms, Cleaning Product Makers |
| Companies Covered | Cargill, ADM Wild Flavours, Kerry Ingredients, Givaudan, Chr. Hansen Holding, Danisco (DuPont), Gat Foods, GLCC, Eastman Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clouding Agents Market Strategic Shifts
Active reformulation across beverage categories is compressing the window for synthetic-to-natural ingredient transitions, with technical innovation focused on matching performance thresholds rather than incremental improvement.
Citrus fiber opacity systems are hybridizing with modified starch carriers to achieve the 0.1-10 micrometer particle distribution essential for stable turbidity without sedimentation. Tropical juice processors in Indonesia and Thailand are piloting these hybrid emulsions in ambient-stable product lines. The technology is hybridizing what were previously separate supply chains for natural positioning and functional performance.
EFSA's ongoing E171 re-evaluation protocol is accelerating titanium dioxide phase-outs across European beverage exports, forcing reformulation commitments before final rulings. Manufacturers serving EU markets are pre-qualifying natural alternatives to avoid supply disruption. The regulation is compressing adoption timelines most severely in carbonated soft drink categories where opacity convention is strongest.
Ingredient procurement is consolidating through regional distributor alliances that aggregate volume for mid-sized beverage compounders. Traditional spot-buying relationships are giving way to annual framework contracts with technical service attachments. This pattern is most visible in Vietnam and Philippines, where processors lack in-house formulation resources and depend on distributor-provided emulsion customization.
Clouding Agents Market Segmentation
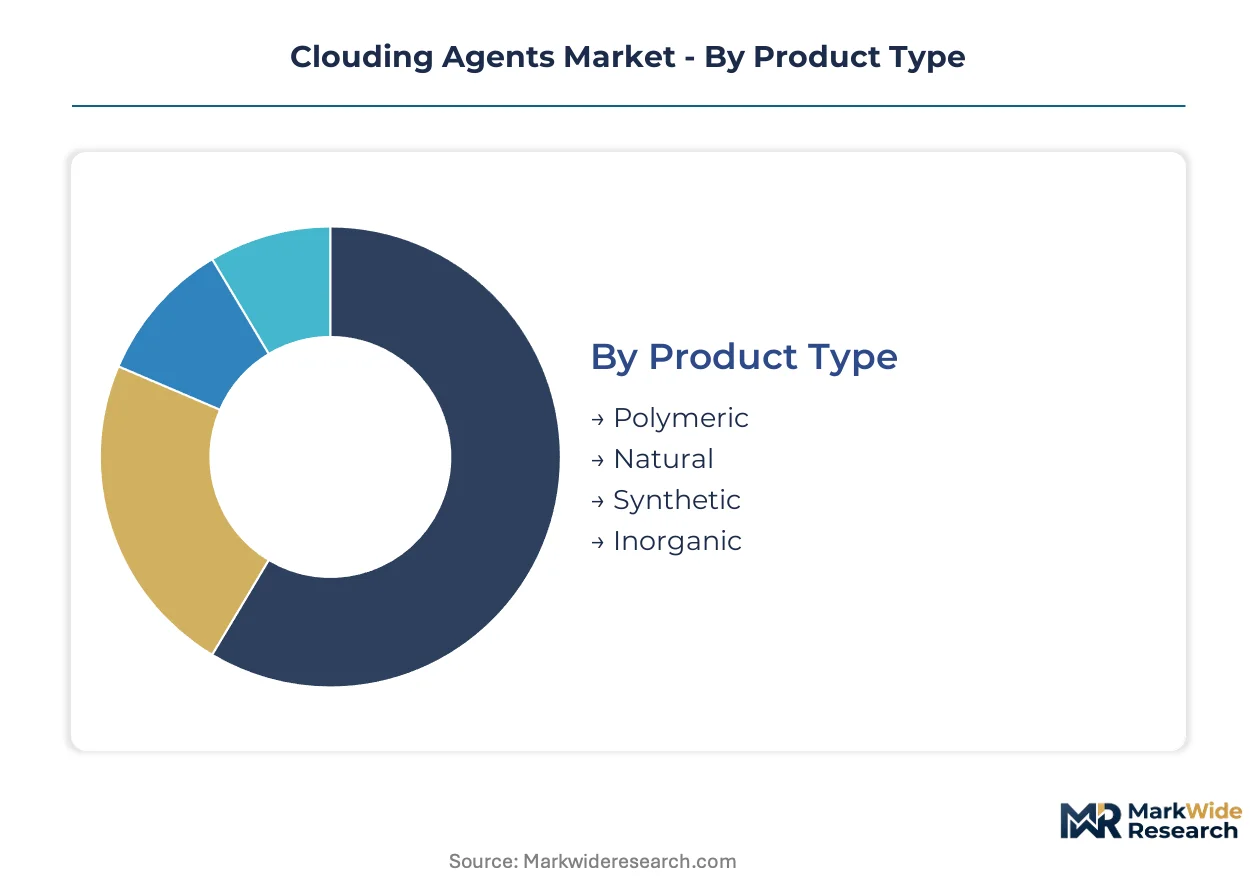
Clouding agent procurement patterns diverge sharply across product chemistry and application requirements, with beverage formulators prioritizing label-friendly opacity systems while industrial users emphasize cost efficiency and shelf stability. Segmentation clarity enables suppliers to align R&D investment with the technical specifications and regulatory constraints governing each end-use channel.
Product Type:
Cost tier positioning determines formulation chemistry selection, with premium natural systems commanding price multiples over commodity synthetic alternatives.
- Polymeric:Engineered carbohydrate or protein-based colloids manufactured to precise particle size distributions between 0.1-10 micrometers. Polymeric systems concentrate demand in reduced-calorie beverage lines across Indonesia and Thailand, where processors require opacity without juice solids caloric load.
- Natural:Citrus fiber, whey protein, and modified starch dispersions that satisfy clean-label positioning. Natural systems are expanding most quickly in ASEAN export facilities serving EU markets, driven by EFSA scrutiny of titanium dioxide alternatives.
- Synthetic:Chemically modified emulsion systems offering cost efficiency and extended ambient stability. These formulations retain share in price-sensitive household and industrial cleaning applications where label transparency carries lower priority.
- Inorganic:Titanium dioxide microparticle suspensions facing regulatory displacement across European and select ASEAN jurisdictions. Inorganic systems maintain residual demand in pharmaceutical coating applications where opacity performance outweighs substitution pressure.
Polymeric holds installed capacity. Natural is rotating up the share rankings.
Application:
Application-specific performance thresholds dictate emulsion architecture, with beverage processors requiring light-scattering stability under thermal stress that personal care formulators rarely encounter.
- Food & Beverage:The dominant volume channel encompassing tropical juice, carbonated soft drinks, and dairy analogues. Food & Beverage procurement concentrates in Vietnam and Philippines, where mid-sized compounders rely on distributor-provided technical service for emulsion customization.
- Personal Care:Opacity systems for shampoos, lotions, and cosmetic emulsions where visual richness signals product quality. Personal Care demand clusters with ASEAN cosmetic manufacturers seeking natural positioning to align with EU export requirements.
- Pharmaceutical:Highly regulated opacity applications in oral suspensions and tablet coatings requiring documented purity and stability validation. Pharmaceutical procurement prioritizes synthetic and inorganic systems with established pharmacopeial monographs.
- Household:Cleaning product opacity where cost minimization dominates formulation decisions. Household applications source predominantly synthetic clouding agents through high-volume annual contracts.
Food & Beverage commands current volume leadership. Personal Care is climbing the fastest as cosmetic clean-label mandates tighten.
Form:
Physical state selection reflects processing infrastructure compatibility and supply chain efficiency considerations across diverse manufacturing footprints.
- Liquid:Ready-to-disperse emulsions requiring minimal hydration or shear for incorporation. Liquid concentrates serve beverage processors in Indonesia lacking in-house high-pressure homogenization equipment.
- Powder:Spray-dried or agglomerated systems offering extended shelf life and reduced shipping costs. Powder formats dominate procurement from Philippine compounders with limited cold-chain logistics.
- Granular:Intermediate physical form balancing dispersibility with storage stability. Granular systems find niche adoption in mid-scale food manufacturers seeking processing flexibility.
- Emulsion:Pre-homogenized colloidal dispersions optimized for immediate incorporation without additional processing. Emulsion formats concentrate with Thai juice processors running continuous production lines.
Liquid maintains formulation service attachments. Powder is gaining share fastest through distributor consolidation.
End User:
Customer type segmentation reveals divergent technical capabilities, with resource-constrained mid-tier processors dependent on supplier-provided formulation support.
- Food Manufacturers:Beverage and dairy processors driving natural system adoption across Southeast Asia. Food Manufacturers in Thailand and Vietnam are pre-qualifying citrus-derived alternatives ahead of anticipated regulatory phase-outs.
- Cosmetic Companies:Personal care formulators prioritizing label-friendly opacity for ASEAN domestic and export markets. Cosmetic procurement emphasizes natural positioning to satisfy EU retailer clean-label requirements.
- Pharma Firms:Pharmaceutical manufacturers with stringent stability and documentation requirements. Pharma Firms maintain conservative sourcing patterns favoring established synthetic and inorganic suppliers.
- Cleaning Product Makers:Household and industrial cleaner producers where cost efficiency supersedes natural positioning. Cleaning Product Makers source through consolidated distributor channels with minimal technical service expectations.
Food Manufacturers anchor current procurement volume. Cosmetic Companies represent the steepest expansion trajectory as clean-label personal care penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Brazilian citrus oil suppliers while Southeast Asian beverage processors absorb cost volatility through long-term procurement contracts. This asymmetry shapes regional investment patterns across clouding agent value chains.
Indonesia
Tropical juice processors in Jakarta and Surabaya drive natural clouding agent procurement as clean-label mandates tighten under ASEAN harmonization. The country's national food and drug regulator enforces AEC Blueprint additive standards that facilitate cross-border sourcing. Processing clusters in East Java pilot hybrid citrus-starch emulsions for ambient-stable product lines.
Thailand
Bangkok-based beverage compounders pre-qualify citrus-derived alternatives ahead of anticipated titanium dioxide phase-outs. The Thai Food and Drug Administration aligns with ASEAN Economic Community protocols for standardized food additive approvals. Manufacturing corridors in Pathum Thani host continuous production lines optimized for pre-homogenized emulsion formats.
Vietnam
Mid-sized processors in Ho Chi Minh City and Hanoi rely on distributor-provided technical service for emulsion customization. The Ministry of Health implements national food safety standards that incorporate ASEAN harmonized additive lists. Procurement consolidation through regional distributor alliances accelerates in the Mekong Delta processing belt.
Philippines
Limited cold-chain logistics drive powder-format clouding agent preference among compounders in Metro Manila and Cebu. The Food and Drug Administration Philippines maintains active evaluation protocols for novel plant-derived opacity ingredients. Distributor networks in Central Luzon aggregate volume for processors lacking in-house formulation resources.
Brazil
d-limonene feedstock concentration exposes natural clouding agent producers to climate-driven harvest volatility. The national health surveillance agency, ANVISA, monitors GRAS-equivalent pathways for export-oriented ingredient suppliers. Citrus oil processing clusters in São Paulo state anchor regional supply security negotiations.
Clouding Agents Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying emulsion chemistry and raw material inputs. The vendor base separates into consolidated multinational ingredient houses and regional distributors with formulation service attachments. Three archetypes dominate: integrated citrus supply chain operators, specialty emulsion technology licensors, and procurement-aggregation platforms. Competitive moves concentrate on backward integration into citrus oil sourcing and strategic partnerships that bundle technical service with supply contracts.
Within the integrated supply chain tier, Cargill exemplifies platform-scale operation through captive citrus oil infrastructure. Kerry Ingredients and ADM Wild Flavours occupy positions as formulation-technology specialists, anchoring the emulsion-systems segment through customized partnership models. These three entities represent distinct competitive vectors: upstream raw material security, midstream formulation capability, and downstream technical service integration.
| Leading Market Players |
|---|
| Cargill |
| ADM Wild Flavours |
| Kerry Ingredients |
| Givaudan |
| Chr. Hansen Holding |
| Danisco (DuPont) |
| Gat Foods |
| GLCC |
| Eastman Chemical |
| Others |
Value Chain & Pricing Dynamics
Brazilian d-limonene concentration anchors upstream pricing power, squeezing margin pools toward citrus oil processors while Southeast Asian beverage compounders absorb volatility through long-term procurement contracts. This asymmetry forces natural clouding agent producers to choose between captive supply investment or margin compression.
Pricing Analysis
Configured-to-order pricing for customized emulsion systems commands a premium over standard citrus fiber dispersions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from EFSA-driven titanium dioxide displacement as processors pre-qualify natural alternatives before final rulings. Mid-sized beverage compounders in Vietnam and Philippines exhibit highest price sensitivity due to limited formulation resources, while EU-exporting Thai processors accept premium tiers for clean-label compliance.
Supply Chain Analysis
Tariff exposure between Brazil and Southeast Asian processing hubs dominates supply chain risk assessment for natural clouding agent procurement. Geographic supply concentration centers on Brazil, Florida, and Indonesia for citrus oil feedstock, with modified starch inputs drawing from Thailand and Vietnam. Single-source vulnerability in d-limonene extraction constrains formulation flexibility during climate-driven harvest disruptions. Distribution runs through regional distributor alliances that aggregate volume and bundle technical service for resource-constrained processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label regulatory disruption across ASEAN and European markets creates a high-growth inflection for natural opacity systems, with EFSA's E171 re-evaluation compressing adoption timelines from years to quarters.
For Market Incumbents: Harden citrus oil supply security through backward integration into Brazilian or Indonesian extraction infrastructure. Anchor formulation partnerships with Thai and Indonesian juice processors to lock in pre-qualification commitments ahead of competitor entry. Certification investment in organic and non-GMO standards defends premium positioning against emerging regional suppliers. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's mid-sized processor segment where distributor technical service gaps create procurement friction. Target Philippine compounders with powder-format natural systems optimized for limited cold-chain logistics. A direct-to-processor digital procurement platform bypasses traditional distributor layers and accelerates customer acquisition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors possessing formulation service capabilities but lacking captive raw material supply. The five-to-ten year viability window favors platforms integrating citrus oil sourcing with emulsion technology licensing. Watch EFSA's final E171 ruling timeline as the signal for accelerated consolidation among natural system suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Oil Supply | Captive d-limonene feedstock insulates margin pools from Brazilian harvest volatility. |
| Hybrid Emulsion Technology Launch | Citrus-starch systems bridge clean-label positioning with ambient shelf-life performance. |
| Direct-to-Processor Digital Platform | Bypassing distributor layers accelerates procurement cycles for Vietnamese compounders. |
| Regulatory Pre-Qualification Partnership | Early reformulation commitments with Thai exporters secure volume ahead of EFSA rulings. |
| Certification Stack Investment | Parallel organic, non-GMO, and natural flavor documentation defends premium tier access. |
Study Parameters
A spread of perspectives from beverage formulation chemists, procurement directors at ASEAN juice processors, technical service leads at regional distributors, and regulatory affairs specialists at ingredient houses converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs trade data, ASEAN food additive harmonization protocols, EFSA evaluation documentation, and SEC filings from publicly traded ingredient suppliers. Bottom-up volume modeling triangulated against top-down market sizing from production capacity assessments.
Demand-supply balance dynamics across natural and synthetic clouding agent categories anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product chemistry tier, application format, physical state, and end-user technical capability. CAGRs derived from weighted average growth rates across these segments, with specific inputs from high-pressure homogenization equipment deployment rates and clean-label certification penetration curves.
Macroeconomic conditions sit as an overlay; deviation in citrus oil commodity prices, ASEAN regulatory harmonization pace, or EFSA ruling timelines would shift the trajectory. Forecasts reflect documented assumptions about displacement rates from titanium dioxide alternatives. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Binder Excipients Market
Additives
Antiblock Agents Market
Additives
Polysorbate-80 Market
Additives
Global Corrosion Inhibitor Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Global Anti-Fog Additives Market
Additives
Global Butyric Acid Derivatives Market
Additives
Driveline Additives Market
Additives
Flux Injection System Market
Additives
Global Slip Additives Market
Additives
Biosaccharide Gum Market
Additives
Global Synthetic Tackifier Market
Additives
Guanylic Acid Market
Additives
Global Zinc Stearate Market
Additives
Propyl Gallate Market
Additives
Automotive Additives Market