
 Russia Sodium Reduction Ingredient Market | 2026-2036
Russia Sodium Reduction Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Sodium Reduction Ingredient Market Analytics
Russia's updated consumer protection standards on food labeling is decoupling sodium content from traditional taste expectations in processed food manufacturing. Chr. Hansen Holding A/S leverages its fermentation-derived flavor systems to occupy premium positions among reformulating meat processors. Kerry Group plc anchors its presence through localized application labs in the Moscow region, while Cargill Incorporated competes on potassium salt supply security for national bakery chains.
Russia sodium reduction ingredients encompass mineral salt substitutes, yeast-derived flavor enhancers, and amino acid-based taste modulators formulated to replicate sodium chloride's sensory profile at reduced concentrations, typically achieving 25-50% sodium reduction without compromising microbial stability or shelf life. Potassium salts lead volume consumption due to established processing compatibility and cost economics across large-scale food manufacturing, while yeast extracts capture expanding margins in clean-label sauce and snack applications where E-number avoidance commands formulation priority. Powder formulations dominate industrial procurement for their blending precision and storage stability, though liquid concentrates gain traction in dairy and ready-meal segments requiring homogeneous dispersion.
Russia's Federal Service for Surveillance on Consumer Rights Protection and Human Wellbeing (Rospotrebnadzor) enforces mandatory nutritional labeling that exposes sodium content to consumer scrutiny, while national technical regulations under the Eurasian Economic Union harmonize maximum sodium thresholds across processed food categories. The country's national standards body (GOST R) certifies ingredient purity and heavy metal limits for potassium-based substitutes, creating compliance gatekeeping that favors suppliers with documented traceability systems. Stakeholders must monitor evolving EAEU technical regulations and Rospotrebnadzor enforcement patterns to anticipate reformulation deadlines and procurement cycle timing.
Market Dynamics
Russia's sodium reduction ingredient sector faces intense pressure from Rospotrebnadzor's tightening nutritional labeling mandates, which force processed food manufacturers into accelerated reformulation cycles. The Central Federal District's concentration of industrial buyers creates procurement bottlenecks as suppliers scramble to certify potassium salt alternatives under GOST R standards.
Growth Catalysts
- EAEU Technical Regulations:Harmonized maximum sodium thresholds across processed food categories compel cross-border manufacturers to standardize reformulation programs, expanding addressable demand for mineral salt substitutes.
- Yeast Extract Systems:Clean-label sauce and snack producers in Moscow Oblast prioritize E-number avoidance, driving premium adoption of fermentation-derived flavor modulators that replicate sodium's sensory profile.
- Central Federal District Procurement:Industrial buyer concentration around Moscow accelerates technology transfer and shortens certification timelines for novel ingredient systems.
Market Restraints
- Potassium Chloride Price Volatility:Input cost swings for mined potassium salts compress margins for bakery chain suppliers locked into annual procurement contracts.
- GOST R Certification Bottlenecks:Heavy metal testing and purity documentation requirements create 12-18 month approval delays for imported yeast extract formulations.
- Bitter Aftertaste Limitations:Potassium salt substitutes above 30% sodium replacement ratios trigger consumer rejection in meat applications, capping maximum feasible reduction levels.
Strategic Opportunities
- Volga Federal District Expansion:Underpenetrated processed meat corridors in Nizhny Novgorod and Samara offer first-mover positioning for localized application technical service.
- Amino Acid-Based Modulators:Convergence of enzymatic processing with precision fermentation enables next-generation taste systems that bypass potassium's sensory limitations entirely.
- Direct-to-Manufacturer Distribution:Bypassing traditional ingredient distributors through on-site blending facilities captures margin and accelerates reformulation response times.
Industry Challenges
- Food Technologist Shortage:Scarce formulation expertise in salt replacement and microbial stability testing extends product development cycles for regional processors.
- Legacy Equipment Retrofit Costs:Hygroscopic potassium salts require humidity-controlled handling systems that demand capital outlays exceeding smaller meat processors' annual maintenance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Sodium Reduction Ingredient Market |
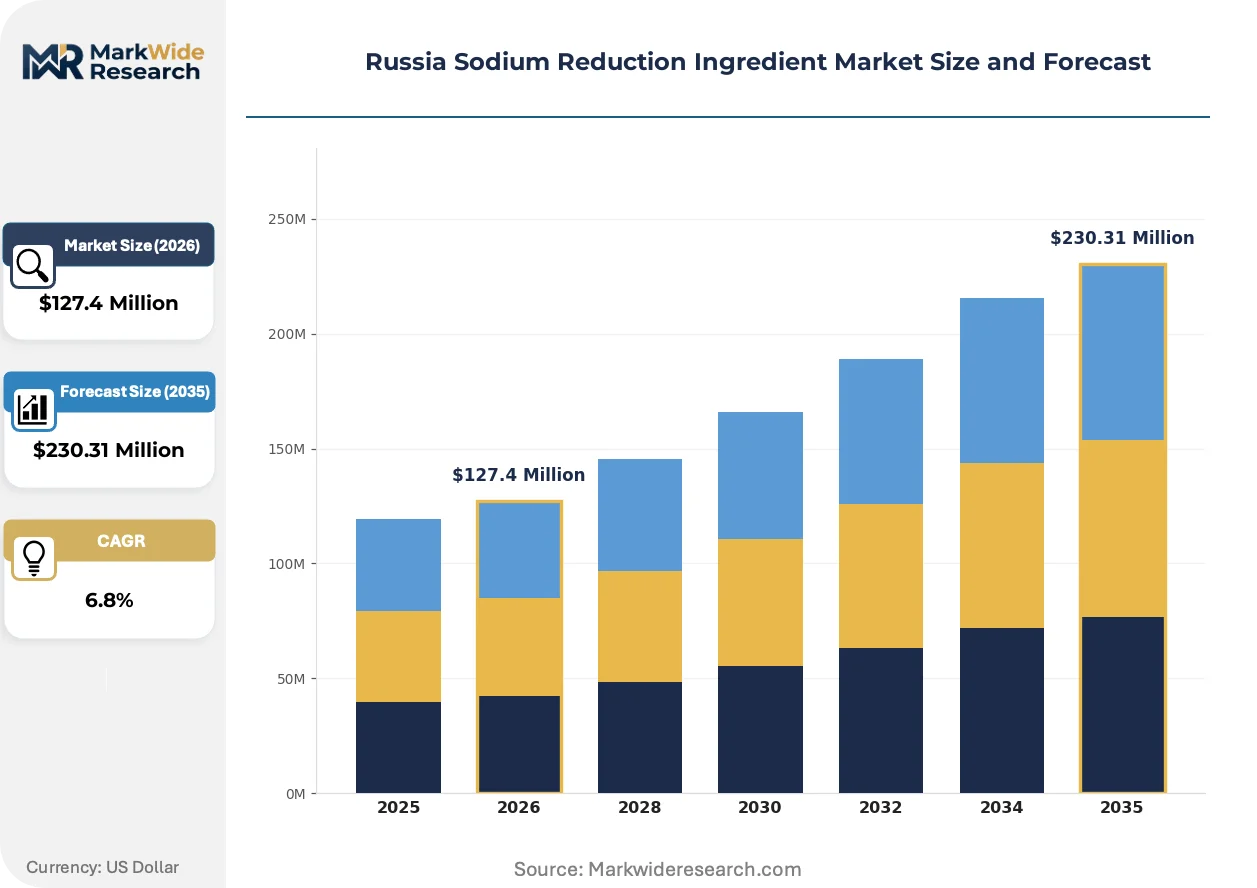
| Market Size in 2026 | $127.4 Million |
| Market Size in 2035 | $230.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Potassium Salts, Calcium Salts, Amino Acids, Yeast Extracts Application: Processed Foods, Snack Foods, Sauces, Dairy Products Formulation: Liquid Form, Powder Form, Granular Form, Concentrates Distribution Channel: Direct Sales, Online Retail, Distributors, Supermarkets |
| Companies Covered | Chr. Hansen Holding A/S, Armor Proteines SAS, Koninklijke DSM N.V., Corbion N.V., Angel Yeast Co., Ltd, Jungbunzlauer Holding AG, Kerry Group plc, Cargill Incorporated, NPO Pishchevye Technologii, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Sodium Reduction Ingredient Market Evolving Landscape
Fermentation-derived taste systems are displacing mineral salts as the dominant technological platform in Russia's reformulation race. Three interconnected developments define current competitive positioning.
Potassium chloride-lysine complexes are consolidating as the standard industrial formulation for large-scale bakery and meat processing. Moscow-based national chains have adopted these blends at 35-40% sodium replacement ratios without equipment modification. The technology is consolidating procurement decisions around suppliers with captive potassium mining and amino acid fermentation capabilities.
Rospotrebnadzor's 2023 consumer protection standards on mandatory front-of-pack sodium disclosure have triggered defensive reformulation across ready-meal manufacturers. Industrial kitchens in Saint Petersburg and Yekaterinburg now require documented sodium reduction roadmaps from ingredient vendors. Sauces and condiments face the steepest compliance deadlines, compressing supplier qualification windows to six months.
Ingredient sourcing is fragmenting as procurement teams bypass distributors for direct manufacturer relationships. Volga Federal District meat processors now mandate on-site technical support as a contract condition, displacing traditional broker-dependent purchasing. This pattern is most visible in Nizhny Novgorod, where three major processors have consolidated vendor panels to single-source potassium salt suppliers with localized warehousing.
Russia Sodium Reduction Ingredient Market Segmentation
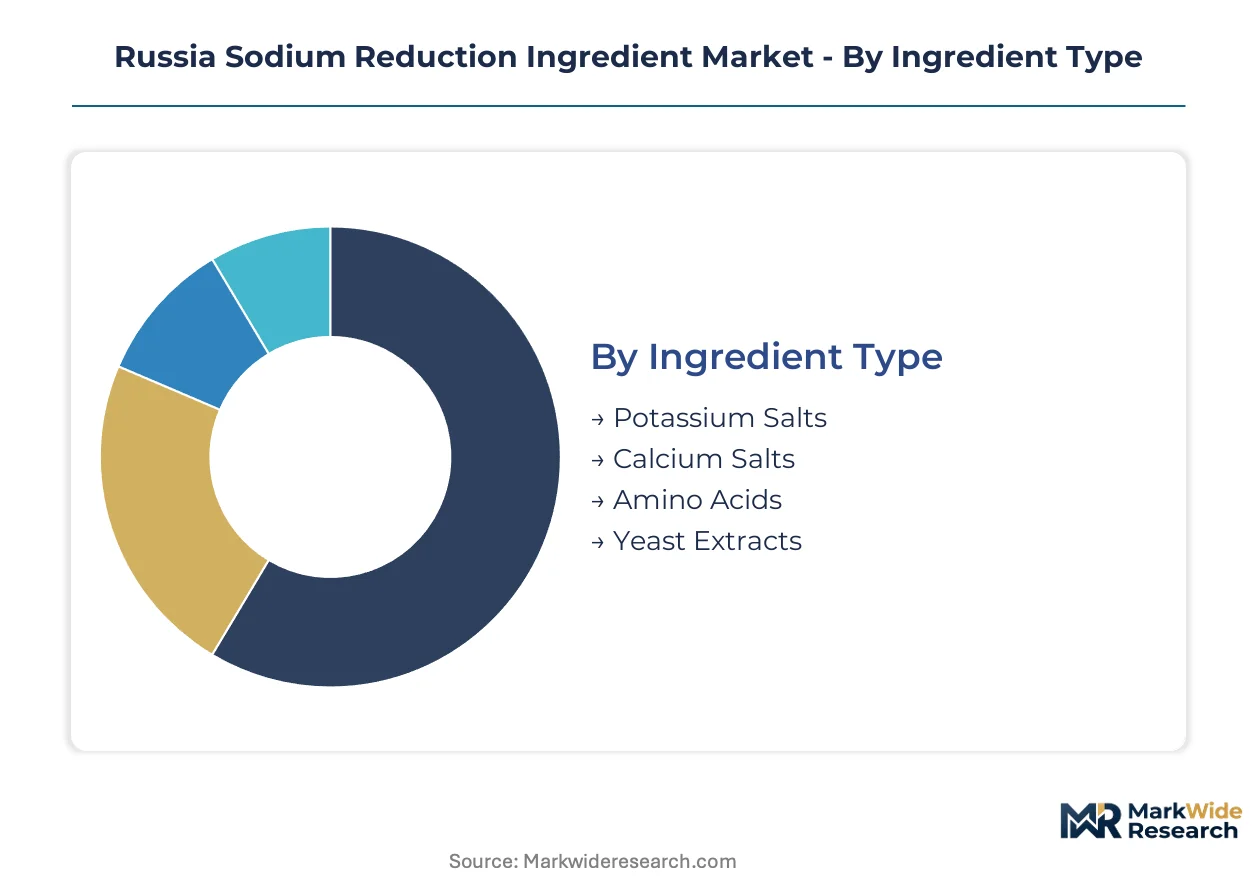
Sodium reduction ingredient procurement in Russia fragments across technical specifications, end-use applications, and supply chain configurations. Each segmentation dimension reveals distinct margin structures and reformulation priorities that shape vendor selection and pricing negotiations.
Ingredient Type:
Standalone mineral salts dominate volume consumption, while fermentation-derived systems embed into premium clean-label formulations requiring deeper technical integration.
- Potassium Salts:Blends of potassium chloride with anti-caking agents and flow conditioners constitute the baseline industrial specification. Moscow-based bakery chains and national meat processors standardize procurement around 30-35% sodium replacement ratios, though Rospotrebnadzor's tightening thresholds are pushing reformulation toward 40-50% replacement ceilings.
- Yeast Extracts:Autolyzed and hydrolyzed yeast proteins deliver umami intensity without E-number classification. Clean-label sauce manufacturers in Saint Petersburg prioritize these systems where front-of-pack ingredient transparency commands retail shelf positioning.
- Calcium Salts:Calcium chloride and calcium carbonate variants serve niche dairy applications requiring mineral fortification alongside sodium reduction.
- Amino Acids:L-lysine and L-glutamic acid derivatives function as taste modulators in high-end ready-meal segments.
Potassium salts lead volumes today; yeast extracts are gaining share fastest.
Application:
Cost-tier segmentation separates commodity-scale manufacturing from premium positioning where reformulation investment recovers through price premiums.
- Processed Foods:Large-scale meat and bakery operations in the Central Federal District consume mineral salt blends at the highest tonnage. Annual procurement contracts lock suppliers into volume commitments with limited price escalation clauses.
- Snacks:Extruded and fried product categories face acute sodium reduction pressure due to Rospotrebnadzor's front-of-pack disclosure mandates. Nizhny Novgorod processors are consolidating supplier panels to three qualified vendors maximum.
- Sauces:Condiment manufacturers require homogeneous dispersion systems for viscous matrices, favoring liquid concentrate formats.
- Dairy Products:Fermented milk and cheese applications demand microbial stability verification that extends GOST R certification timelines.
Processed foods anchor procurement volumes; snacks show the steepest expansion trajectory.
Formulation:
Volume economics favor powder handling infrastructure, while liquid systems penetrate applications where dispersion precision outweighs logistics cost.
- Powder Form:Free-flowing crystalline and agglomerated powders dominate industrial procurement for blending precision and extended shelf stability. Volga Federal District meat processors specify bulk silo delivery with pneumatic transfer systems.
- Liquid Form:Aqueous concentrates and suspensions serve dairy and ready-meal segments requiring immediate homogeneity without dry-mix hydration steps.
- Granular Form:Coarse particle sizes reduce dust generation in high-speed packaging lines.
- Concentrates:High-potency dilutable systems minimize transport cost for remote regional processors.
Powder formulations command the installed base; liquid concentrates are climbing the fastest.
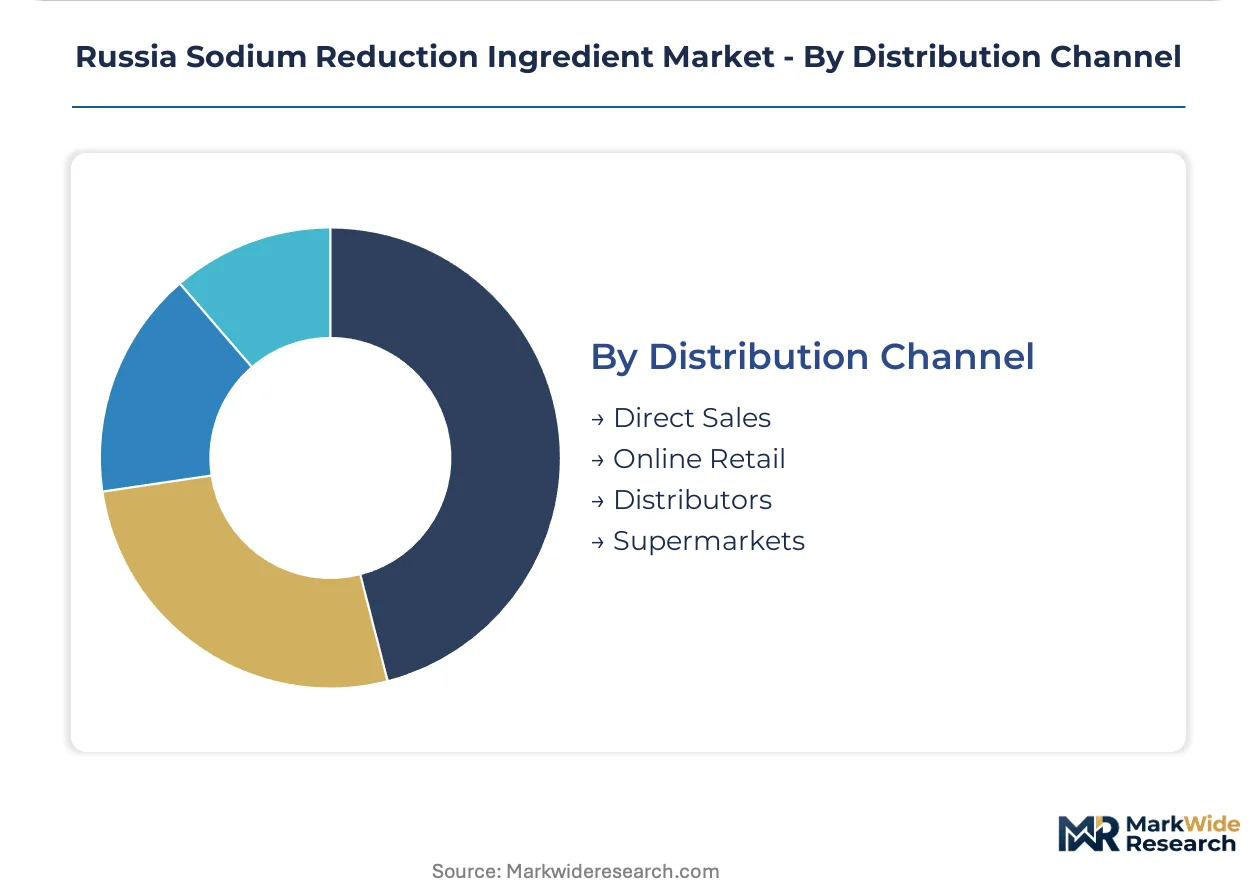
Distribution Channel:
Customer-type segmentation separates direct manufacturer relationships from intermediary-dependent purchasing with distinct service-level expectations.
- Direct Sales:National bakery chains and meat processors negotiate annual frame contracts with technical service attachments. On-site application laboratories in Moscow Oblast anchor these relationships.
- Distributors:Regional processors in Yekaterinburg and Samara rely on stocked inventory and credit terms that direct manufacturers rarely extend.
- Online Retail:Small-scale artisan food producers source sample quantities and specialty ingredients through B2B platforms.
- Supermarkets:Private-label development teams procure finished sodium-reduced ingredient blends for captive manufacturing.
Direct sales capture margin concentration; distributor channels retain widest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and regulatory compliance specialists cluster around Moscow and Saint Petersburg, anchoring Russia's sodium reduction ingredient demand in these metropolitan centers. Their concentration accelerates reformulation cycles and shortens supplier certification timelines. Peripheral federal districts rely on technical service outposts from these hubs.
Central Federal District
National bakery chains and meat processors in Moscow Oblast drive bulk procurement of potassium chloride blends. Rospotrebnadzor's front-of-pack sodium disclosure mandates compel annual contract renegotiations with documented reduction roadmaps. Industrial kitchens in the Moscow metropolitan area now require six-month supplier qualification windows for novel yeast extract systems.
Northwestern Federal District
Saint Petersburg's sauce and condiment manufacturers prioritize clean-label fermentation-derived flavor enhancers. The Eurasian Economic Union's harmonized sodium thresholds apply equally to cross-border processors operating through Baltic port logistics. Ready-meal producers in the Neva River industrial corridor face compressed compliance deadlines for Rospotrebnadzor's 2023 labeling standards.
Volga Federal District
Nizhny Novgorod and Samara meat processors are consolidating supplier panels to single-source potassium salt vendors with localized warehousing. GOST R certification bottlenecks for imported yeast extracts create 12-18 month approval delays that favor domestic mineral salt alternatives. Extruded snack manufacturers in this corridor specify bulk silo delivery with pneumatic transfer systems.
Ural Federal District
Yekaterinburg's regional processors rely on distributor channels for stocked inventory and credit terms that direct manufacturers rarely extend. The district's dairy applications demand microbial stability verification extending GOST R certification timelines. Fermented milk and cheese producers here favor calcium salt variants serving mineral fortification alongside sodium reduction.
Southern Federal District
Rostov-on-Don's emerging processed food corridor offers first-mover positioning for localized application technical service. The district's underpenetrated meat processing sector lacks formulation expertise in salt replacement and microbial stability testing. Procurement teams here increasingly mandate on-site technical support as a contract condition, displacing traditional broker-dependent purchasing.
Russia Sodium Reduction Ingredient Market Competitive Landscape
Capital-heavy producers with captive mineral extraction compete with asset-light fermentation technology licensors across Russia's sodium reduction ingredient sector. The supplier base fragments between integrated mining-chemical conglomerates and specialized biotech flavor houses. Three archetypes dominate: potassium salt miners with downstream blending capabilities, yeast extract fermenters with clean-label positioning, and application service providers with localized technical laboratories. Competitive moves center on backward integration into potassium mining and geographic expansion through on-site blending facilities.
Among European fermentation specialists, Chr. Hansen Holding A/S and Kerry Group plc exemplify the premium-tier flavor systems archetype, occupying positions among reformulating meat processors through documented traceability systems. Cargill Incorporated anchors the mineral salt supply security segment, competing on potassium salt availability for national bakery chains. Koninklijke DSM N.V. and Corbion N.V. represent the biotechnology licensing tier, while Angel Yeast Co., Ltd. and Jungbunzlauer Holding AG sit within the Asian fermentation specialist category. Armor Proteines SAS occupies a position in dairy-derived taste modulation. NPO Pishchevye Technologii represents the domestic Russian supplier archetype with localized GOST R certification advantages.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Armor Proteines SAS |
| Koninklijke DSM N.V. |
| Corbion N.V. |
| Angel Yeast Co., Ltd |
| Jungbunzlauer Holding AG |
| Kerry Group plc |
| Cargill Incorporated |
| NPO Pishchevye Technologii |
| Others |
Value Network & Pricing Analysis
Premium yeast extract systems and commodity potassium chloride blends occupy opposite ends of Russia's sodium reduction ingredient pricing spectrum, with certification-grade fermentation products commanding three-to-four-fold premiums over mineral salt substitutes while both tiers face divergent supply chain configurations around Moscow warehousing hubs versus direct mine-to-processor potassium sourcing.
Pricing Analysis
Contract-based long-term offtake dominates procurement for Central Federal District bakery chains, with pricing stratifying across premium, standard, and economy tiers based on GOST R certification status and bundled technical service attachments. Price differentiation hinges on documented traceability systems and on-site application laboratory access, with least price sensitivity among clean-label sauce manufacturers in Saint Petersburg and acute sensitivity among Volga Federal District meat processors locked into annual volume commitments. Cost compression in standard-grade potassium salts is intensifying because imported yeast extract alternatives face 12-18 month approval delays, forcing reformulators toward domestic mineral substitutes.
Supply Chain Analysis
Freight cost escalation from Belarus and Kazakhstan potash mining regions to Moscow Oblast blending facilities is reshaping procurement geography, with rail tariff exposure now embedded in annual contract negotiations. Supply draws from captive potassium mining in Belarus, ammonia feedstock from Togliatti, and fermentation capacity in Western Europe, creating single-source vulnerability for yeast-derived systems during GOST R certification bottlenecks. Distribution runs through direct manufacturer relationships for national chains and regional distributor networks for Yekaterinburg and Samara processors lacking silo handling infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's sodium reduction ingredient sector offers margin expansion through fermentation-derived premium tier capture, as Rospotrebnadzor's tightening disclosure mandates force reformulators toward higher-value clean-label systems that bypass potassium chloride's sensory limitations.
For Market Incumbents: Acquire captive potassium mining assets or long-term offtake agreements to secure supply security against Belarusian export volatility. Defend market position by embedding on-site application laboratories in Nizhny Novgorod and Samara before first-movers establish technical service standards, while accelerating GOST R certification documentation for imported yeast extract portfolios to close the 12-18 month approval gap favoring domestic mineral salt competitors. For New Entrants and Emerging Players: Amino acid-based taste modulators built on precision fermentation platforms offer the most penetrable wedge against incumbent potassium chloride dominance, particularly in meat applications where bitter aftertaste caps replacement ratios below 30%. Target underpenetrated Southern Federal District processors in Rostov-on-Don lacking formulation expertise, with go-to-market anchored on documented sodium reduction roadmaps as mandatory contract deliverables displacing traditional ingredient broker relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where GOST R certification timelines create stranded asset risk for import-dependent yeast extract specialists lacking domestic regulatory navigation capabilities. Long-term viability favors vertically integrated operators with captive mineral extraction and fermentation licensing partnerships. The signal to watch is Rospotrebnadzor enforcement pattern acceleration, which would compress supplier qualification windows and favor acquirers with pre-positioned compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potassium Mining | Secures supply security against Belarusian export volatility for Moscow-based bakery chains. |
| Localized Application Laboratory Expansion | Captures Volga Federal District meat processors mandating on-site technical support as contract condition. |
| GOST R Certification Fast-Track Investment | Closes 12-18 month approval gap disadvantaging imported yeast extract formulations. |
| Precision Fermentation Partnership | Enables amino acid-based modulators bypassing potassium chloride sensory limitations in meat. |
| Direct-to-Manufacturer Distribution Buildout | Displaces traditional broker-dependent purchasing in Southern Federal District emerging corridor. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with food technologists at Moscow Oblast meat processors, procurement leads at national bakery chains, regulatory affairs specialists navigating Rospotrebnadzor enforcement, and distribution channel partners in Yekaterinburg with secondary validation through EAEU technical regulation filings, GOST R certification databases, and customs trade records for potassium salt imports. Bottom-up ingredient consumption estimates triangulated against top-down processed food production statistics.
Segment-weighting across ingredient type, application, formulation, and distribution channel dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from modeled consumption trajectories calibrated to reformulation cycle timing under tightening Rospotrebnadzor thresholds, with cross-validation against EAEU harmonization schedules and industrial kitchen procurement patterns in Saint Petersburg and Nizhny Novgorod.
The model holds under stable EAEU technical regulation enforcement and continued Rospotrebnadzor front-of-pack disclosure implementation; deviation in geopolitical trade flows or accelerated regulatory deadlines would shift supplier qualification windows and procurement concentration patterns. Stakeholders should weight assumptions against their own operating context and certification pipeline visibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Liquid Thickeners Market
Additives
Phthalate Plasticizer Market
Additives
Global Metal Scavenging Agents Market
Additives
Thermal Conductive Additives Market
Additives
Ascorbyl Stearate Market
Additives
Chitosan Powder Market
Additives
North America Pectin Market
Additives
Crosslinking Agents Market
Additives
Asia Pacific Plastic Additives Market
Additives
Anti-Block Additives Market
Additives
Middle East Feed Additives Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Global Pour Point Depressant Market
Additives
Conditioning Agent Market
Additives
Additives for Floor Coatings Market
Additives
Feed Additives Market