
 Shortstop Inhibitor Market | 2026-2036
Shortstop Inhibitor Market Size, Share, and Industry Trends Forecast 2026-2036
Shortstop Inhibitor Market Analytics
The shortstop inhibitor category is rebalancing between premium selective inhibitors and commodity broad-spectrum formulations as payers sharpen reimbursement criteria. Solvay leverages its polymer chemistry heritage to sustain supply chain control over high-purity raw materials. Nufarm anchors its position in agricultural-adjacent synthesis pathways that feed pharmaceutical precursor markets. Syensqo competes through specialized catalyst technologies that reduce manufacturing impurities in dual inhibitor production.
Shortstop inhibitors are synthetic or semi-synthetic compounds engineered to arrest specific enzymatic or signaling pathways, typically requiring purity thresholds above 99.5% and validated stability profiles under cGMP conditions for pharmaceutical use. Their primary purpose centers on interrupting disease progression in targeted therapeutic applications, particularly where genetic biomarkers identify responsive patient populations. Selective inhibitors command the deepest margin pools due to complex stereoselective synthesis requirements, while broad-spectrum formulations face commoditization pressure from multi-source supply. Oncology applications lead therapy area demand as immuno-oncology combinations expand the addressable patient base for checkpoint and pathway inhibitors.
The FDA's accelerated approval framework and EMA's adaptive pathways program shape clinical development strategies and pre-market evidence requirements for shortstop inhibitor developers. ISO 17025 analytical standards and ICH Q3D elemental impurity guidelines govern batch release specifications and cross-border market access for active pharmaceutical ingredients. Stakeholders must monitor evolving pharmacovigilance obligations under the EU Clinical Trials Regulation as these compound classes enter broader commercial distribution.
Market Dynamics
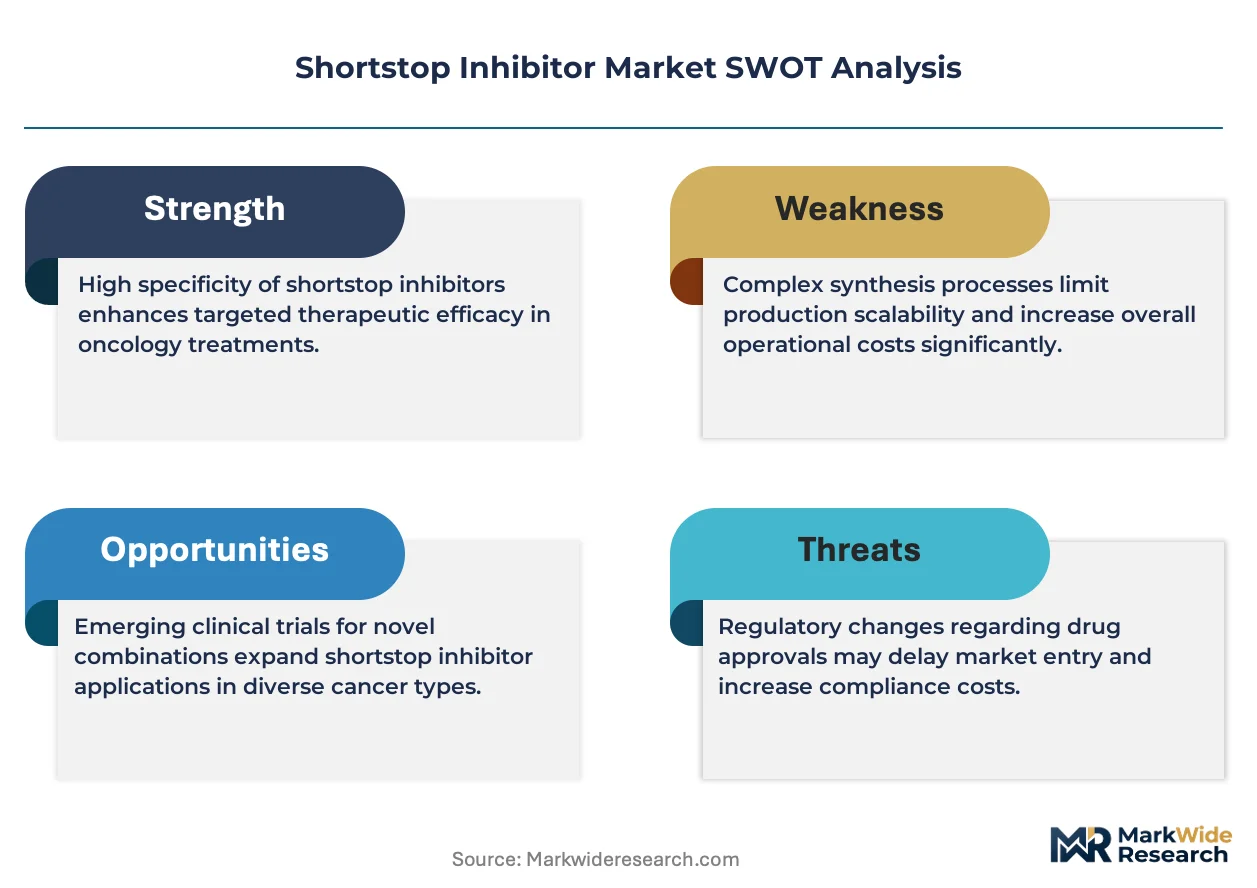
Selective inhibitor pipelines are compressing development timelines as FDA accelerated approval pathways reward biomarker-defined patient populations with earlier market entry, forcing contract manufacturers to expand high-purity synthesis capacity ahead of traditional scale-up schedules.
Growth Catalysts
- Oncology Pipeline Expansion:Immuno-oncology combinations are widening the addressable patient base for pathway-specific inhibitors, with combination therapy protocols now standard in Phase II trial designs.
- EMA Adaptive Pathways:The European Medicines Agency's conditional marketing authorization framework is enabling earlier patient access while generating real-world evidence, compressing traditional Phase III-to-launch intervals.
- Biomarker Testing Proliferation:Companion diagnostic adoption in United States academic medical centers is identifying responsive patient subsets with precision, concentrating demand for matched selective inhibitors.
Market Restraints
- High-Purity Solvent Volatility:Pharmaceutical-grade acetonitrile and tetrahydrofuran supply disruptions in Asian manufacturing hubs are inflating raw material costs for stereoselective synthesis batches.
- Specialized Catalyst Concentration:Chiral phase-transfer catalyst production concentrates among three European specialty chemical suppliers, creating single-source vulnerability for dual inhibitor manufacturers.
- Substitution by Biosimilars:Monoclonal antibody biosimilars are capturing share in certain oncology indications previously served by small-molecule shortstop inhibitors, pressuring pricing in commoditized segments.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are building US FDA-inspected facilities for high-potency API production, offering cost-competitive alternatives to Western manufacturing.
- Continuous Flow Synthesis:Microreactor technology convergence with real-time analytical feedback is enabling on-demand production of unstable intermediates, reducing inventory risk for niche inhibitors.
- Japan PMDA Sakigake:Japan's priority review designation for innovative pharmaceuticals is attracting early filing strategies for selective inhibitors with demonstrated biomarker correlation.
Industry Challenges
- Stereochemistry Specialist Scarcity:PhD-level synthetic organic chemists with chiral resolution expertise command premium compensation, constraining R&D expansion at mid-scale developers.
- cGMP Validation Timelines:ICH Q3D elemental impurity method validation requires 12-18 month qualification periods, delaying batch release for new manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shortstop Inhibitor Market |
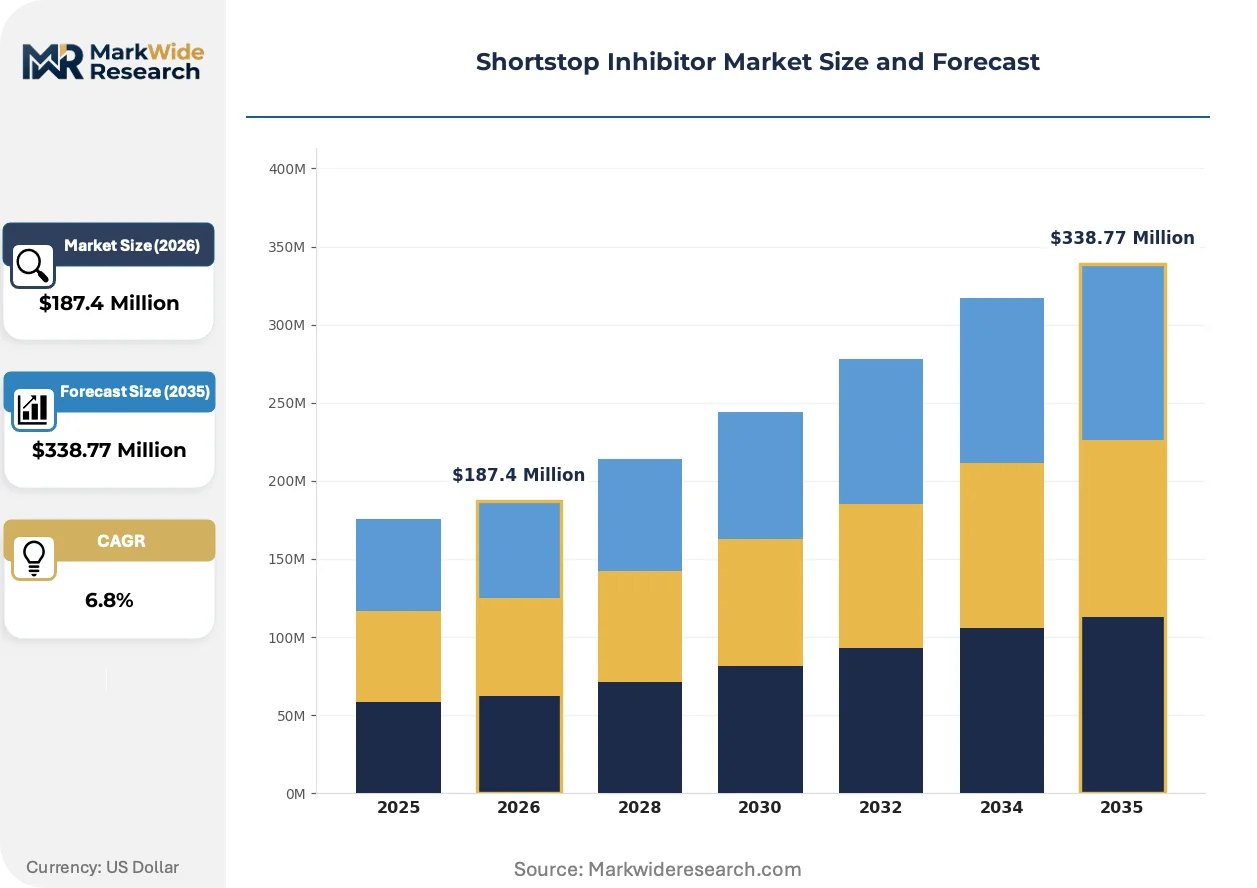
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selective Inhibitors, Dual Inhibitors, Broad-Spectrum Inhibitors, Targeted Therapies Therapy Area: Oncology, Neurology, Cardiovascular, Metabolic Disorders End User: Pharmaceutical Companies, Research Institutions, Hospitals, Contract Research Organizations Formulation: Injectables, Oral Tablets, Topical Creams, Lyophilized Products |
| Companies Covered | TCI Chemicals, Nufarm, Solvay, Nalco, Chemtura, Kawaguchi Chemical, Addivant, Syensqo, FUJIFILM Wako Pure Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shortstop Inhibitor Market Evolving Landscape
Artificial intelligence is reshaping target identification and lead optimization workflows, compressing discovery timelines while raising the bar for computational chemistry infrastructure investment across the developer landscape.
AI-driven molecular docking platforms are electrifying early-stage inhibitor design by predicting protein-ligand binding affinities with accuracy previously requiring months of laboratory screening. Mid-cap pharmaceutical developers are adopting these tools fastest, outsourcing computation to cloud-based providers rather than building in-house supercomputing clusters. The technology is electrifying competitive positioning by enabling smaller players to pursue targets previously reserved for well-capitalized competitors with established high-throughput screening infrastructure.
REACH authorization requirements for persistent organic pollutants are forcing reformulation of certain process solvents used in inhibitor synthesis, with ECHA substance evaluation driving substitution timelines. Manufacturers serving European markets are accelerating adoption of bio-based solvent alternatives and closed-loop recovery systems to maintain registration compliance. The regulatory pressure falls heaviest on broad-spectrum inhibitor producers with legacy process chemistry, while selective inhibitor specialists with newer synthetic routes adapt more fluidly.
Buyers are consolidating procurement of high-purity APIs under single-source master service agreements with integrated analytical testing, displacing fragmented spot purchasing across multiple suppliers. Large pharmaceutical sponsors now require contract manufacturers to assume stability study and regulatory filing support responsibilities previously retained in-house. This consolidation pattern is most pronounced in the United States, where vertical integration between discovery biotechs and specialized CDMOs is tightening supplier relationships and raising switching costs for both parties.
Shortstop Inhibitor Market Segmentation
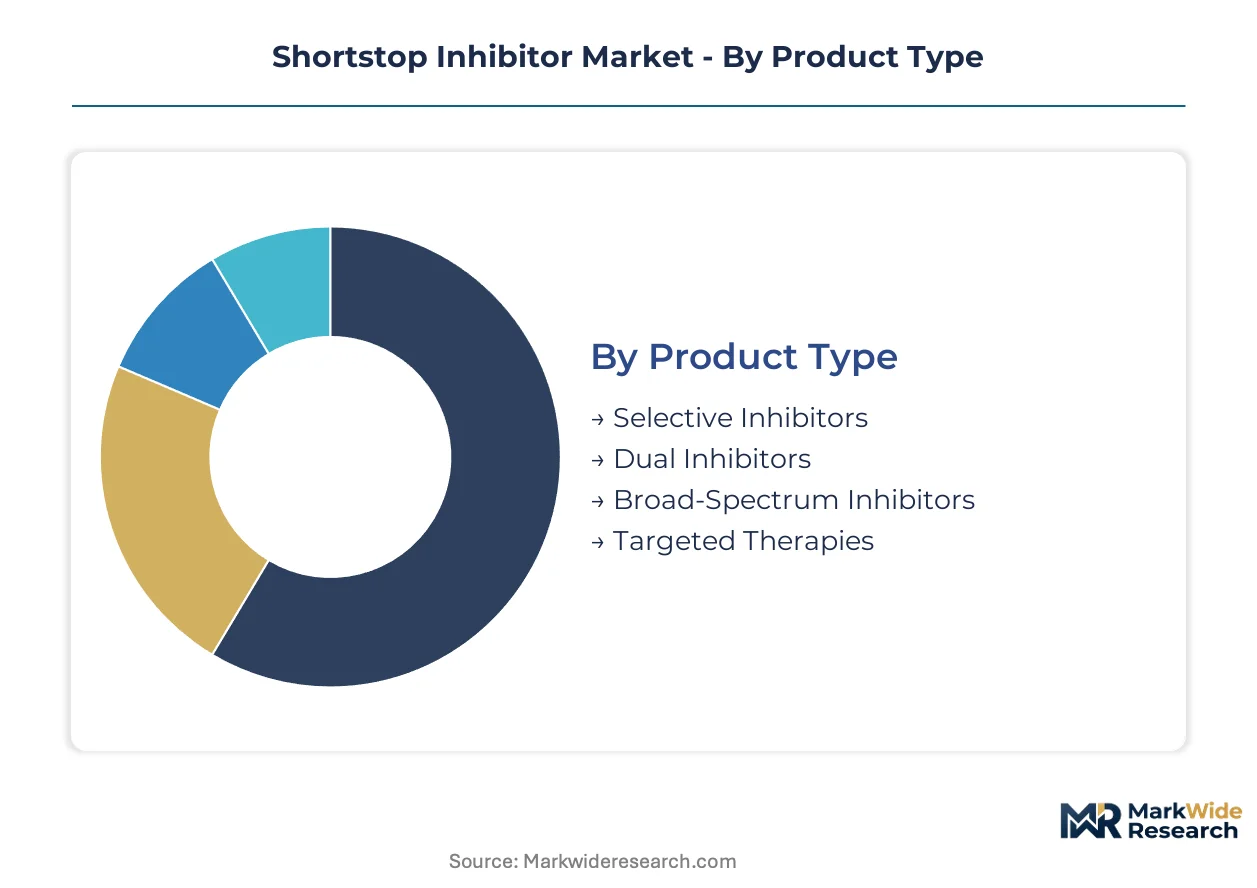
Segmentation in shortstop inhibitors reflects the tension between precision medicine requirements and manufacturing scalability. Each dimension carries distinct regulatory, pricing, and supply chain implications that shape competitive positioning across developer portfolios.
Product Type:
Customization intensity varies sharply across this spectrum, from bespoke stereoselective synthesis for selective inhibitors to standardized batch production for broad-spectrum formulations.
- Selective Inhibitors:These compounds target single enzymatic nodes with >99.5% stereochemical purity, requiring chiral chromatography validation under ICH Q3D guidelines. Demand concentrates in United States oncology biotechs pursuing FDA accelerated approval pathways, where biomarker-defined populations justify premium pricing despite complex manufacturing.
- Dual Inhibitors:Engineered to block parallel signaling pathways simultaneously, these agents demand specialized phase-transfer catalysts currently sourced from concentrated European suppliers. Japanese pharmaceutical sponsors under PMDA Sakigake designation are driving fastest adoption for combination-resistant malignancies.
- Broad-Spectrum Inhibitors:Multi-target agents serving commoditized infectious disease applications with lower purity thresholds.
- Targeted Therapies:Patient-specific formulations matched to companion diagnostic outputs, requiring adaptive manufacturing protocols.
Most installed capacity flows through Broad-Spectrum Inhibitors. Expansion is steepest in Selective Inhibitors.
Therapy Area:
Application maturity determines margin structure, with established oncology protocols supporting predictable reimbursement versus exploratory metabolic indications bearing higher clinical risk.
- Oncology:Checkpoint inhibitor combinations have normalized shortstop co-administration in immuno-oncology protocols across United States academic medical centers. EMA adaptive pathways are compressing Phase III-to-launch intervals for biomarker-responsive subpopulations, intensifying demand for matched selective inhibitors.
- Neurology:Blood-brain barrier penetration requirements favor small-molecule inhibitors over biologics in Alzheimer's and Parkinson's pipelines. Contract research organizations in Germany and Switzerland are expanding dedicated neuropharmacology units to serve this resurgent development activity.
- Cardiovascular:Established statin-adjunct applications with mature regulatory pathways and price-sensitive payer environments.
- Metabolic Disorders:Emerging NASH and diabetes complications targeting, requiring novel biomarker validation.
Revenue concentration sits with Oncology. Pipeline velocity is accelerating most quickly in Neurology.
End User:
Procurement sophistication separates large pharmaceutical sponsors with integrated quality systems from fragmented research buyers with spot purchasing patterns.
- Pharmaceutical Companies:Vertically integrated developers are consolidating API procurement under single-source master service agreements that bundle analytical testing, stability studies, and regulatory filing support. This pattern is most pronounced among United States mid-cap biotechs with PEGylated inhibitor platforms.
- Contract Research Organizations:CDMOs in Hyderabad and Ahmedabad are building US FDA-inspected high-potency facilities to capture outsourced synthesis from Western sponsors. Real-time batch release capabilities and ICH Q3D pre-validation are becoming table stakes for vendor qualification.
- Research Institutions:Academic medical centers with limited GMP requirements and grant-funded purchasing cycles.
- Hospitals:Compounding pharmacy demand for approved-agent reformulations with localized stability testing.
Manufacturing volume flows predominantly through Pharmaceutical Companies. Capacity addition is climbing fastest at Contract Research Organizations.
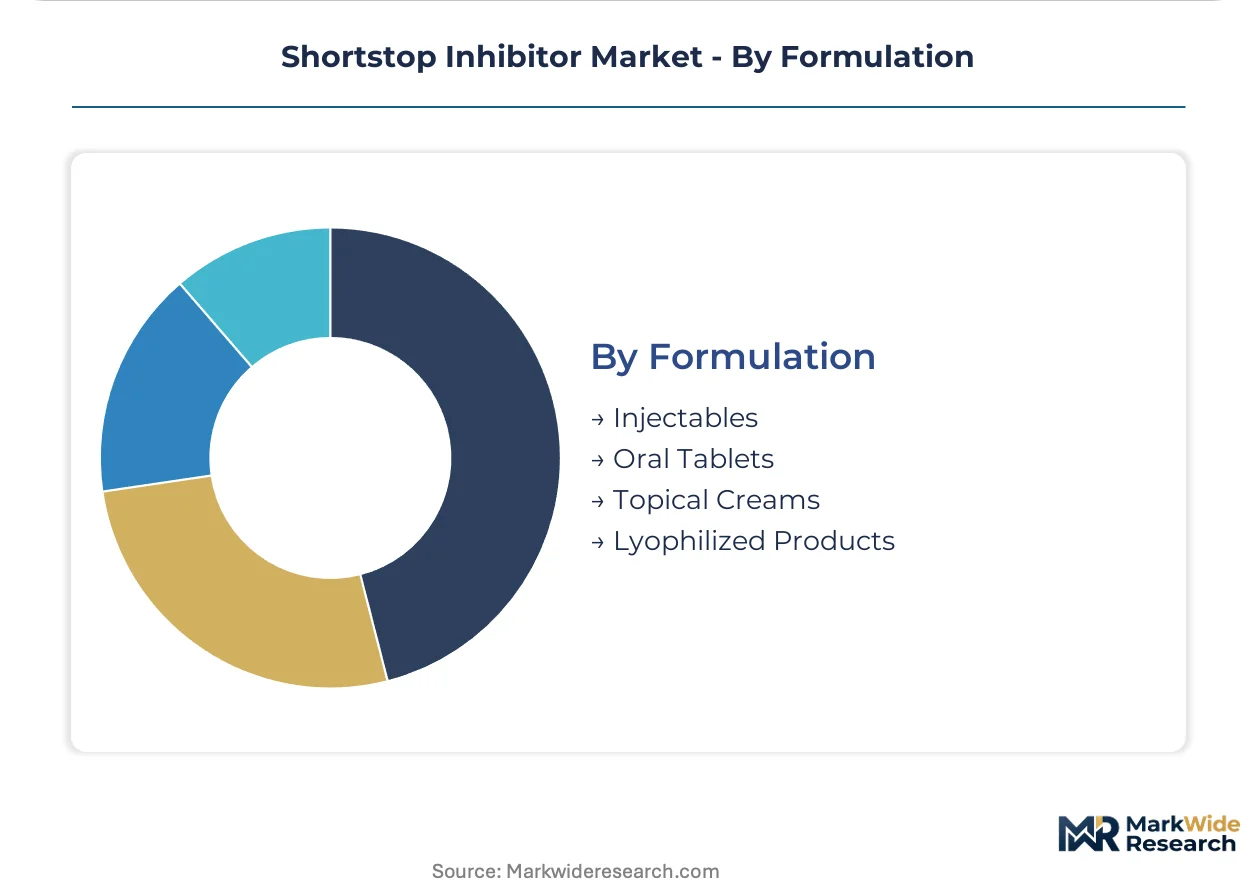
Formulation:
Delivery technology selection constrains active ingredient stability requirements and dictates cold chain infrastructure investment across distribution networks.
- Injectables:Parenteral formulations demand endotoxin control and sterile fill-finish capabilities that concentrate among specialized CDMOs with isolator technology. United States biotechs developing immuno-oncology combinations favor this route for rapid systemic exposure.
- Lyophilized Products:Freeze-dried presentations extend shelf life for unstable intermediates, enabling global distribution without continuous cold chain. Japanese and Swiss manufacturers lead in automated lyophilization scale-up for niche inhibitors with limited production runs.
- Oral Tablets:Conventional solid dosage with established bioequivalence pathways and lowest manufacturing complexity.
- Topical Creams:Dermal delivery for localized inflammatory indications with permeation enhancement requirements.
Production throughput centers on Oral Tablets. Technical investment is expanding most aggressively in Lyophilized Products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PhD-level synthetic organic chemists with chiral resolution expertise concentrate disproportionately in Germany, Switzerland, and the United States, anchoring high-purity inhibitor synthesis capacity. This talent distribution shapes where contract manufacturers invest in cGMP-validated facilities and where sponsors locate critical-path development programs.
United States
FDA accelerated approval pathways reward biomarker-defined patient populations with earlier market entry, compressing traditional Phase III-to-launch intervals. The agency's oncology center of excellence prioritizes pathway-specific inhibitors for immuno-oncology combinations. Greater Boston and San Francisco Bay Area biotech clusters house the densest concentrations of PEGylated inhibitor developers pursuing single-source master service agreements.
Germany
EMA adaptive pathways and conditional marketing authorization frameworks enable earlier patient access while generating real-world evidence. ECHA substance evaluation under REACH authorization requirements is forcing reformulation of process solvents used in inhibitor synthesis. The Rhine-Main and Upper Bavaria regions host specialized CDMOs expanding dedicated neuropharmacology units for blood-brain barrier penetration programs.
Switzerland
Swissmedic's alignment with EMA centralized procedures streamlines market access for high-purity APIs destined for European distribution. The country's dual-track apprenticeship system produces analytical chemists qualified in ICH Q3D elemental impurity method validation. Basel and Zurich pharmaceutical corridors concentrate lyophilization scale-up capabilities for niche inhibitors with limited production runs.
Japan
PMDA Sakigake priority review designation attracts early filing strategies for selective inhibitors with demonstrated biomarker correlation. METI funding for innovative pharmaceutical manufacturing supports adoption of continuous flow synthesis and microreactor technologies. Osaka and Tokyo pharmaceutical belts anchor domestic demand for dual inhibitors targeting combination-resistant malignancies.
India
CDSCO's streamlined approval pathways for APIs manufactured in US FDA-inspected facilities are accelerating export-oriented capacity expansion. The country's national pharmaceutical regulator harmonizes with ICH guidelines to facilitate cross-border market access. Hyderabad and Ahmedabad contract development organizations are building high-potency production facilities with real-time batch release capabilities.
Shortstop Inhibitor Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the shortstop inhibitor landscape, with integrated chemical manufacturers maintaining captive synthesis capabilities while biotech sponsors outsource to specialized contract manufacturers. The vendor base separates into three strategic archetypes: diversified chemical conglomerates with polymer heritage, agricultural-chemical hybrids leveraging precursor synthesis pathways, and pure-play pharmaceutical fine chemical specialists. Competitive moves concentrate on backward integration into high-purity raw materials and geographic expansion of US FDA-inspected manufacturing footprints.
Among diversified chemical manufacturers, Solvay occupies a position exemplifying supply chain control over high-purity raw materials through polymer chemistry heritage. Nufarm sits within the agricultural-adjacent synthesis tier, representing pathways that feed pharmaceutical precursor markets. Syensqo anchors the specialized catalyst technology segment, occupying a position in manufacturing impurity reduction for dual inhibitor production.
| Leading Market Players |
|---|
| TCI Chemicals |
| Nufarm |
| Solvay |
| Nalco |
| Chemtura |
| Kawaguchi Chemical |
| Addivant |
| Syensqo |
| FUJIFILM Wako Pure Chemical Corporation |
| Others |
Value Network & Pricing Analysis
Pharmaceutical company procurement consolidation under single-source master service agreements is forcing contract manufacturers to absorb analytical testing and regulatory filing support costs, compressing margins on high-purity API batches while elevating switching costs for both parties.
Pricing Analysis
Bundled service contracts now dominate selective inhibitor procurement, with large sponsors requiring CDMOs to assume stability study and regulatory filing responsibilities previously retained in-house. Price differentiation hinges on stereochemical purity certification above 99.5% and real-time batch release capabilities validated under ICH Q3D guidelines. Cost compression in broad-spectrum formulations is intensifying because multi-source supply has commoditized multi-target agents. Research institutions with grant-funded purchasing cycles exhibit highest price sensitivity, while United States mid-cap biotechs pursuing FDA accelerated approval pathways prioritize quality assurance over unit cost.
Supply Chain Analysis
Direct-to-pharmaceutical-sponsor channels handle high-volume selective inhibitor demand, with spot purchasing displaced by integrated master service agreements. Manufacturing concentration sits with India, Germany, and Switzerland, where PhD-level synthetic organic chemists anchor chiral resolution capacity. Production draws from pharmaceutical-grade acetonitrile and tetrahydrofuran feedstocks, plus specialized European-sourced chiral phase-transfer catalysts. Single-source vulnerability in catalyst supply creates structural risk for dual inhibitor manufacturers. Distribution runs through vertically integrated CDMOs with captive analytical testing and regulatory filing support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: CDMOs in Hyderabad and Ahmedabad offer US FDA-inspected high-potency production at cost structures 40-50% below Western equivalents, while Japanese PMDA Sakigake designation accelerates regulatory timelines for sponsors filing there first.
For Market Incumbents: Deploy backward integration into high-purity raw materials to defend margin position against Solvay's polymer chemistry heritage and Nufarm's agricultural-adjacent precursor pathways. Expand US FDA-inspected capacity in India to match cost structures emerging from Hyderabad and Ahmedabad contract manufacturers. Chiral phase-transfer catalyst supply concentration among three European specialty chemical suppliers represents existential vulnerability requiring dual-sourcing or captive production.
For New Entrants and Emerging Players: Capture white-space in continuous flow synthesis technology convergence with real-time analytical feedback, where microreactor-enabled on-demand production of unstable intermediates remains underdeveloped. Target neurology applications requiring blood-brain barrier penetration, as German and Swiss CROs expand dedicated neuropharmacology units and competition lags oncology saturation. Lead with Japan PMDA Sakigake early-filing strategies to compress development timelines for biomarker-correlated selective inhibitors.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized catalyst technology developers capable of reducing manufacturing impurities in dual inhibitor production, as REACH authorization requirements for persistent organic pollutants force solvent reformulation across legacy process chemistry. Five-to-ten year viability favors pure-play pharmaceutical fine chemical specialists over diversified chemical conglomerates with divided capital allocation priorities. Monitor EMA adaptive pathways adoption rates as inflection indicator for real-world evidence generation compressing traditional Phase III-to-launch intervals.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | US FDA-inspected high-potency capacity in India captures outsourced synthesis from Western sponsors. |
| Regulatory Approval Pathway | Japan PMDA Sakigake designation accelerates selective inhibitor filings with demonstrated biomarker correlation. |
| Backward Integration | Captive supply of pharmaceutical-grade acetonitrile and tetrahydrofuran insulates against Asian manufacturing hub disruptions. |
| Long-term Supply Agreement | Single-source master service agreements bundle analytical testing and regulatory filing support, elevating switching costs. |
| Green Manufacturing Transition | Bio-based solvent alternatives and closed-loop recovery systems maintain REACH registration compliance for European market access. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads at EMA and FDA, CDMO procurement managers, and hospital formulary directors with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and ICH Q3D guideline documentation. Bottom-up API production volume estimates triangulated against top-down therapeutic area demand projections.
Segment-weighting across product type, therapy area, end user, and formulation dimensions shaped volume and value outputs over the projection horizon. CAGRs derived from fitted growth curves incorporating oncology pipeline expansion rates, biomarker testing proliferation trajectories, and CDMO capacity addition schedules. Continuous flow synthesis adoption curves and AI-driven molecular docking platform penetration supplied technology-specific forecast inputs.
Underlying measurement precision varies by segment; selective inhibitors with validated stability profiles carry tighter precision than exploratory metabolic disorder applications. Forecasts reflect assumptions regarding FDA accelerated approval pathway continuity, EMA adaptive pathways expansion, and REACH authorization timeline adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Friction Modifier Additives Market
Additives
Calcium Acetate Market
Additives
Extruded Inclusions Market
Additives
Global Glass Additives Market
Additives
Tire Additives Market
Additives
Agrochemicals Additives Market
Additives
Inorganic Rheology Modifiers Market
Additives
Additives for Metalworking Fluids Market
Additives
Additives for Floor Coatings Market
Additives
Plastic Fillers Market
Additives
Citric Acid Anhydrous Market
Additives
Sorbitan Tristearate Market
Additives
Chelating Agents Market
Additives
Global Peptone Market
Additives
Global Polyurethane Additives Market
Additives
Global Pearlizing Agent Market