
 United Kingdom Feed Additives Market | 2026-2036
United Kingdom Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Feed Additives Market Analytics
Poultry integrators is bifurcating demand away from traditional ruminant-focused suppliers across the United Kingdom feed additives sector. Cargill Inc. leverages its integrated supply chain to control distribution into large-scale broiler operations throughout East Anglia. BASF SE anchors its position through specialized enzyme formulations that improve phosphorus digestibility in wheat-based UK rations. Alltech differentiates via yeast-based bioactive platforms that address gut health challenges in antibiotic-free production systems.
Feed additives comprise biologically active substances incorporated into compound feeds at inclusion rates typically ranging from grams to kilograms per tonne to enhance nutritional value, animal performance, or feed preservation. These compounds function through enzymatic catalysis, microbial population modulation, or direct nutrient supplementation to optimize feed conversion efficiency in commercial livestock operations. Enzymes command structural attention due to their specificity in degrading non-starch polysaccharides prevalent in UK cereal co-products. Amino acids represent the fastest-expanding category as formulators reduce crude protein levels to comply with nitrogen emission commitments. Dry form dominates physical distribution through compatibility with existing feed mill pelleting and grinding infrastructure.
DEFRA oversees feed additive registration through retained EU legislation transitioning toward independent Great Britain assessment procedures, while the Veterinary Medicines Directorate evaluates zootechnical additive efficacy claims. The Food Standards Agency enforces maximum residue limits that constrain growth promoter categories and shape formulation choices across poultry and swine sectors. Farm assurance schemes such as Red Tractor impose additional additive disclosure requirements that influence procurement specifications. Stakeholders must monitor divergence between GB and Northern Ireland regulatory pathways under the Windsor Framework to anticipate compliance cost fragmentation.
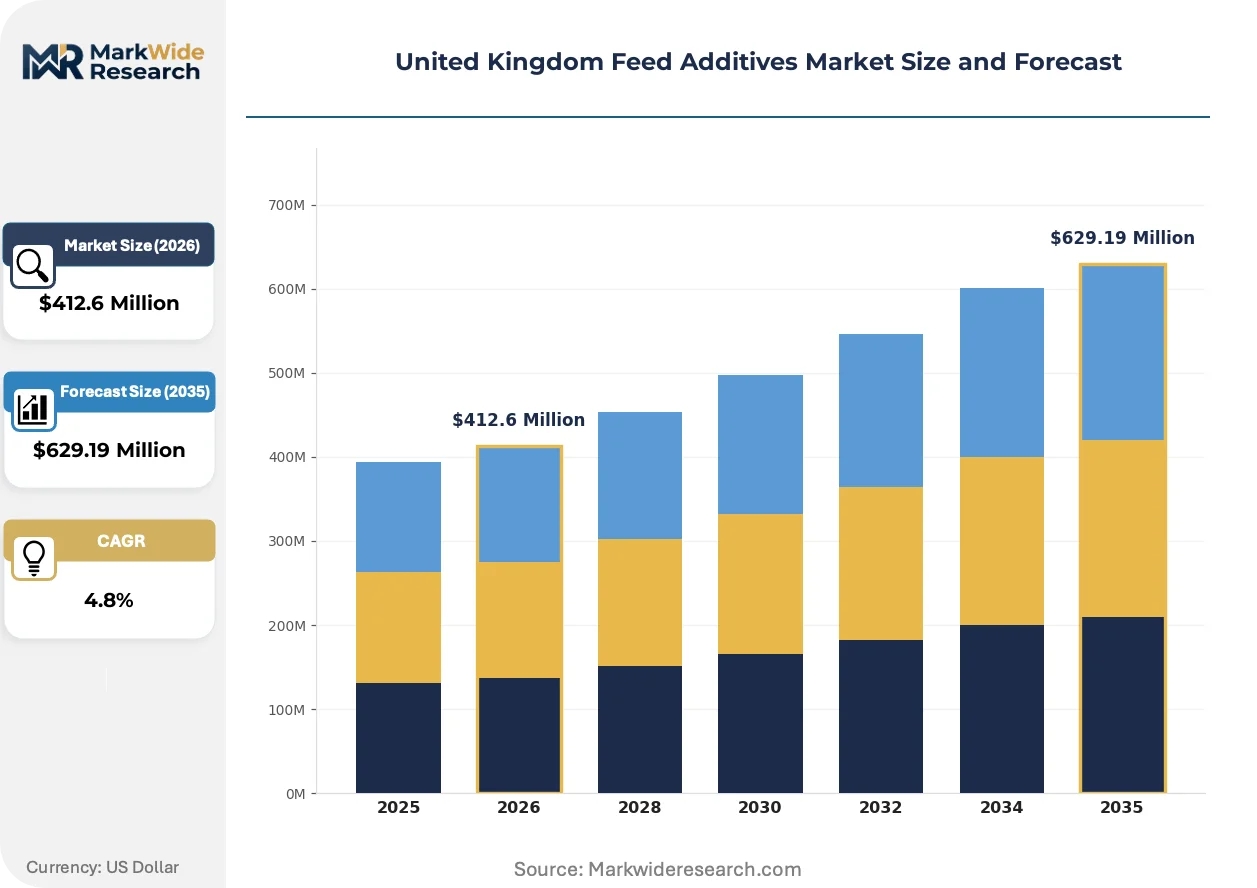
Market Dynamics
DEFRA's transition from retained EU legislation toward independent Great Britain assessment procedures is restructuring approval timelines and fragmenting compliance pathways between Great Britain and Northern Ireland under the Windsor Framework.
Growth Catalysts
- Nitrogen emission commitments:DEFRA's Environmental Improvement Plan mandates crude protein reduction in livestock rations. Amino acid supplementation enables formulators to maintain performance while cutting nitrogen excretion.
- Antibiotic-free production systems:Red Tractor assurance schemes and retailer specifications prohibit growth-promoting antibiotics. Yeast-based bioactives and probiotic additives capture substitution demand across poultry integrators.
- East Anglia cluster expansion:Intensive broiler operations concentrate near Norwich and Peterborough feed milling infrastructure. Proximity to crushing capacity and port access via Great Yarmouth reduces logistics friction for additive distribution.
Market Restraints
- Feed-grade phosphate volatility:Moroccan and Russian supply concentration exposes UK formulators to price swings. Phytase adoption partially offsets this but requires capital-intensive reformulation.
- Dual regulatory burden:The Windsor Framework preserves EU-aligned rules in Northern Ireland while Great Britain diverges. Manufacturers face parallel registration costs with the Veterinary Medicines Directorate and retained EU procedures.
- Enzyme specificity limitations:Wheat-barley-rye mixes in UK rations vary by harvest. Single-activity xylanase products underperform against variable arabinoxylan structures, forcing over-dosing or blend complexity.
Strategic Opportunities
- Wales and South West penetration:Dairy and sheep sectors in these regions lag poultry in additive intensity. Precision feeding and methane inhibitor deployment remain underdeveloped outside East Anglia clusters.
- DEFRA sustainable farming incentive:The scheme rewards environmental outcomes including reduced feed waste. Additive suppliers can bundle enzymes and probiotics into outcome-based contracts tied to feed conversion improvements.
- Digital-microbial convergence:Near-infrared spectroscopy and real-time microbiome monitoring enable dynamic dosing. Integration of sensor hardware with live-culture additives creates subscription service potential.
Industry Challenges
- Veterinary prescription bottlenecks:Zootechnical additive claims require Veterinary Medicines Directorate efficacy trials. Qualified assessor scarcity extends approval timelines beyond product development cycles.
- Mill integration complexity:Liquid enzyme application systems demand retrofitting of pelleting lines above 85°C. Thermal stability trade-offs between cost and performance constrain adoption at smaller independent mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Feed Additives Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Amino Acids, Vitamins, Enzymes End User: Poultry, Ruminants, Swine, Aquaculture Form: Dry, Liquid, Pelleted, Powdered Nutritional Purpose: Growth Promoters, Nutrient Absorption, Immunity Boosters, Digestive Aids |
| Companies Covered | Dupont Danisco, Archer Daniels Midland Co., Alltech, Evonik Industries AG, DSM Nutritional Products Inc., Cargill Inc., Nutreco, Volac International Ltd., BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Feed Additives Market Evolving Landscape
Multi-enzyme complexes and live microbial formulations are displacing single-activity products as feed formulators pursue compound performance claims and simplified procurement.
Next-generation phytase variants with enhanced thermostability are fragmenting the enzyme category. Poultry integrators in Suffolk and Norfolk are adopting these products at accelerated rates to protect phosphorus release through high-temperature pelleting. The technology is fragmenting supplier tiers as patent-protected premium products separate from commodity generics on price and performance guarantees.
DEFRA's Great Britain assessment pathway for feed additives is diverging from EFSA procedures. The retained EU legislation transition creates regulatory uncertainty for products pending approval. Northern Ireland operations remain bound to EU timelines, forcing manufacturers to maintain dual dossier strategies and anticipate compliance cost fragmentation.
Buying concentration among the four major UK poultry integrators is compressing supplier negotiation cycles. Long-term enzyme supply agreements with fixed volume commitments are displacing spot purchasing. This shift is most visible across East Anglia broiler operations where integrators leverage scale to demand outcome-based pricing tied to measured feed conversion improvements.
United Kingdom Feed Additives Market Segmentation
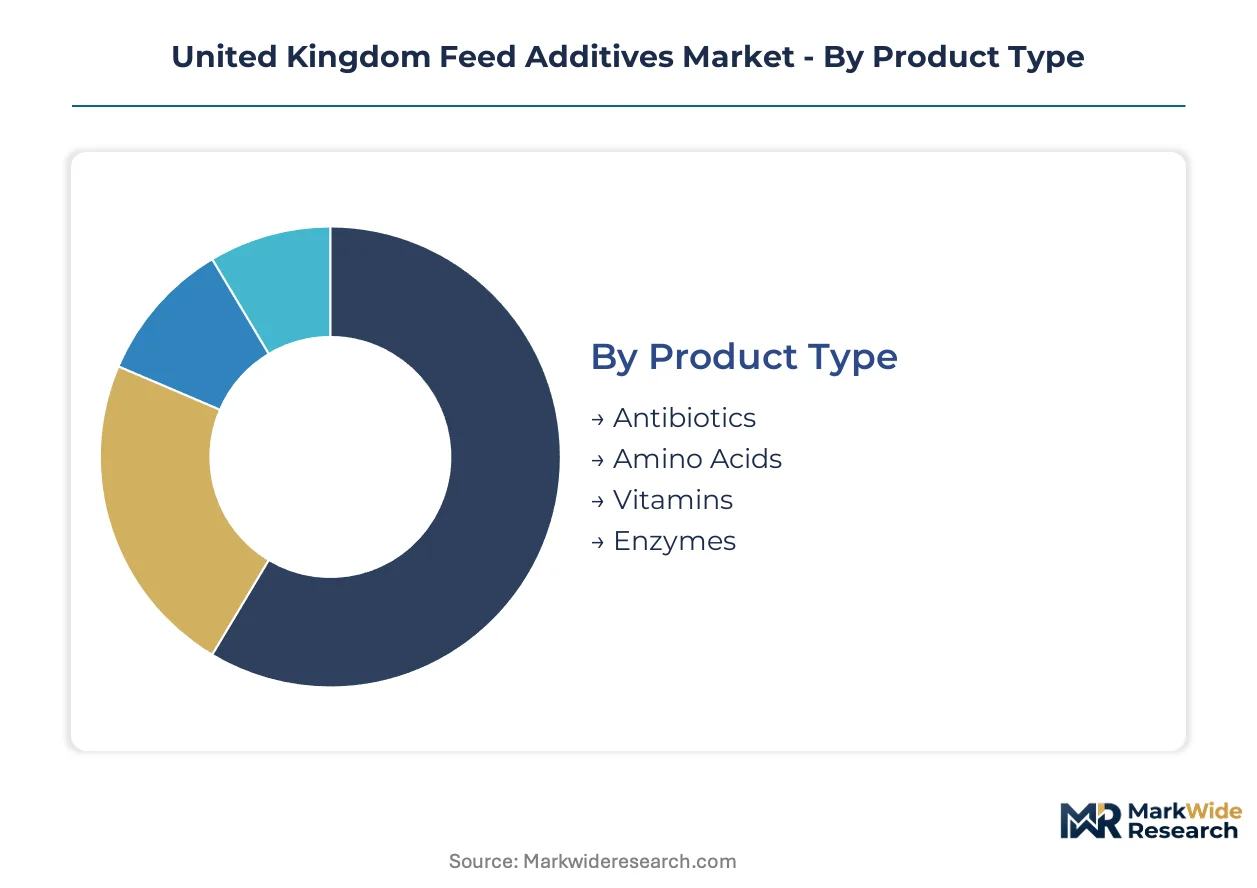
Feed additive purchasing patterns in the United Kingdom diverge sharply across livestock sectors and application formats. Understanding these segmentation boundaries clarifies where formulation investments concentrate and which regulatory pathways shape commercial access.
Product Type:
Channel mix varies substantially by product chemistry — enzymes and amino acids flow predominantly through integrator-direct contracts, while antibiotics and vitamins distribute via merchant wholesalers serving independent farms.
- Enzymes:Protein catalysts degrade non-starch polysaccharides in wheat-barley rations prevalent across East Anglia. Suffolk and Norfolk poultry integrators specify thermostable phytase variants to protect phosphorus release through high-temperature pelleting lines. Phytase adoption partially offsets volatile feed-grade phosphate costs from concentrated Moroccan supply.
- Amino Acids:Crystalline lysine, methionine, and threonine enable crude protein reduction without performance loss. DEFRA's Environmental Improvement Plan nitrogen commitments accelerate demand as formulators cut nitrogen excretion across East Midlands dairy operations. Suppliers bundle these into precision premix contracts tied to measured milk urea reductions.
- Antibiotics:Growth-promoting applications face Red Tractor prohibition and Veterinary Medicines Directorate prescription controls. Therapeutic use concentrates in swine weaning phases where veterinary oversight remains mandatory.
- Vitamins:Fat-soluble and water-soluble micronutrients stabilize against oxidation in extended storage. Dry premix integration dominates channel access for smaller independent mills lacking liquid dosing infrastructure.
By volume, enzymes lead. By growth pace, amino acids are climbing the fastest.
End User:
Cost tier stratification separates intensive contract operations from extensive grazing systems — poultry and swine integrators absorb premium additive pricing while ruminant and aquaculture sectors prioritize commodity formulations.
- Poultry:Broiler integrators in East Anglia deploy multi-enzyme complexes and live microbial formulations at scale. Cargill's integrated supply chain controls distribution into large-scale operations near Norwich and Peterborough milling infrastructure. Outcome-based pricing tied to feed conversion ratios compresses supplier margins.
- Ruminants:Dairy and beef sectors lag poultry in additive intensity. Wales and South West England operations underutilize precision feeding and methane inhibitors. DEFRA sustainable farming incentive rewards create bundling opportunities for enzyme-probiotic combinations.
- Swine:Post-weaning diarrhea management drives probiotic and organic acid demand. Antibiotic-free retailer specifications from major supermarkets reshape formulation procurement.
- Aquaculture:Scottish salmon operations represent concentrated demand for immunity boosters and digestive aids. Marine-specific enzyme formulations remain underdeveloped relative to terrestrial livestock applications.
Poultry commands current volume leadership. Aquaculture presents the steepest expansion trajectory as Scottish production scales.
Form:
Application maturity separates established dry formats from liquid systems requiring mill retrofit investment — thermal stability trade-offs constrain adoption at smaller independent operations.
- Dry:Compatible with existing pelleting and grinding infrastructure across UK feed mills. Powdered and granulated enzymes dominate procurement specifications for thermal resilience above 85°C processing temperatures.
- Liquid:Post-pelleting enzyme application systems demand capital-intensive line modifications. Concentration among four major poultry integrators enables volume commitments justifying retrofit investment.
- Pelleted:Pre-mixed additive concentrates simplify handling for smaller compounders. Uniform dispersion challenges limit precision relative to liquid dosing systems.
- Powdered:Fine particle sizing optimizes homogeneity in high-inclusion applications. Dust exposure and handling losses constrain adoption in automated mill environments.
Dry formats retain volume dominance. Liquid systems are gaining share fastest among East Anglia integrators with dedicated application infrastructure.
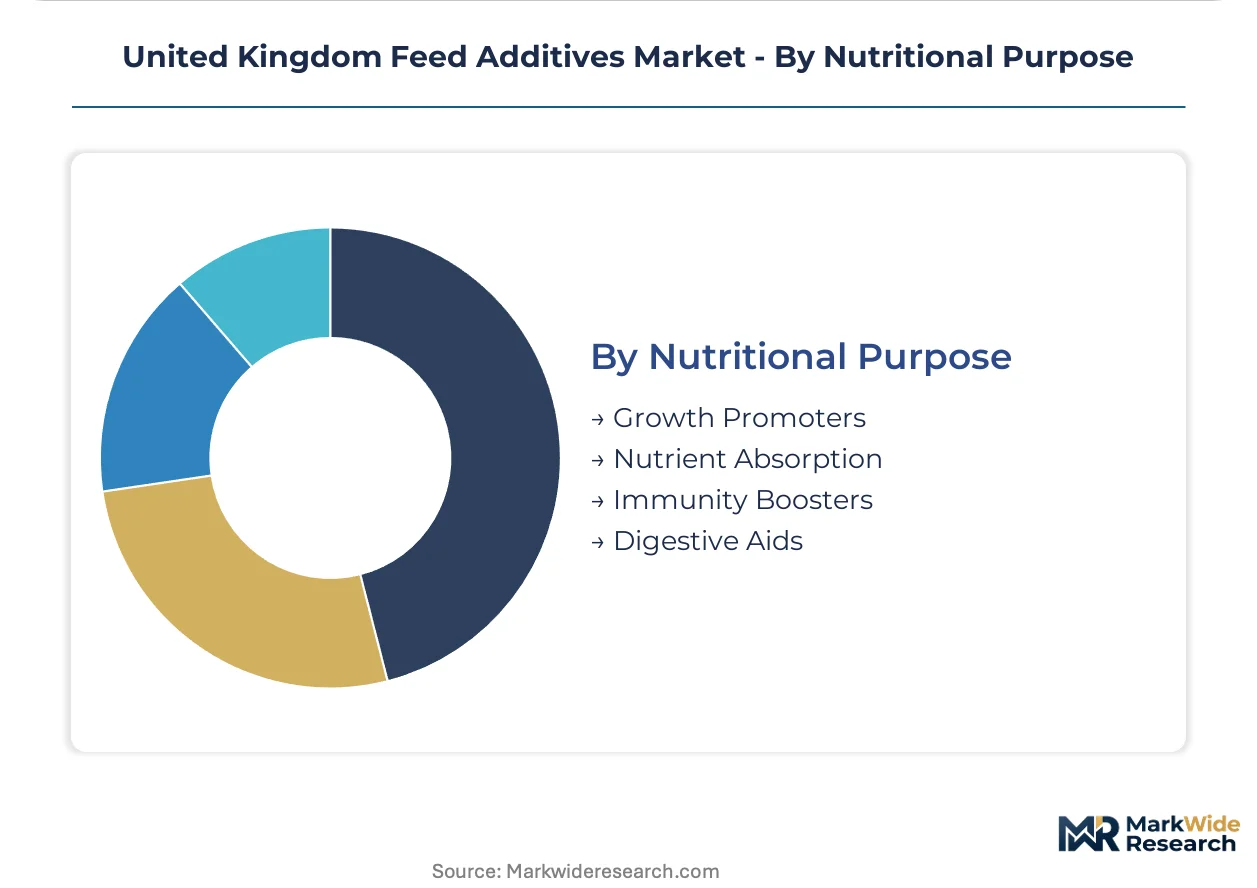
Nutritional Purpose:
Customer type segmentation splits performance-guaranteed integrator contracts from specification-driven assurance scheme compliance — Red Tractor and retailer standards reshape category prioritization.
- Nutrient Absorption:Phytase and carbohydrase enzymes improve phosphorus and energy digestibility in wheat-based UK rations. BASF's specialized formulations anchor supplier positioning through guaranteed matrix release values.
- Digestive Aids:Yeast-based bioactives and probiotic cultures address gut health in antibiotic-free production systems. Alltech differentiates via live-culture platforms capturing substitution demand across poultry assurance schemes.
- Growth Promoters:Regulatory compression from DEFRA and Food Standards Agency maximum residue limits constrains category scope. Zootechnical additive claims require Veterinary Medicines Directorate efficacy trials with extended approval timelines.
- Immunity Boosters:Beta-glucans and nucleotide supplements target stress periods in transition feeding. Aquaculture and weaning swine applications concentrate demand.
Nutrient absorption leads by volume. Digestive aids are expanding most quickly as antibiotic-free commitments harden across retailer specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in the United Kingdom Feed Additives Market clusters around intensive poultry integrators in East Anglia, with secondary demand nodes emerging in dairy-intensive sub-regions and aquaculture operations along Scottish coastlines.
East Anglia
Broiler integrators near Norwich and Peterborough drive phytase and probiotic consumption at scale. DEFRA's Environmental Improvement Plan nitrogen commitments accelerate amino acid adoption across Norfolk and Suffolk feed mills. Cargill's integrated supply chain controls distribution into large-scale operations concentrated near Great Yarmouth port access.
East Midlands
Dairy operations in Lincolnshire and Leicestershire deploy precision premix contracts tied to measured milk urea reductions. The Veterinary Medicines Directorate evaluates zootechnical additive efficacy claims for regional formulators. Feed milling infrastructure near Nottingham supports enzyme distribution into crude protein reduction programs.
Scotland
Scottish salmon operations represent concentrated demand for immunity boosters and digestive aids in aquaculture applications. The Food Standards Agency enforces maximum residue limits that constrain growth promoter categories across Highland and Grampian production zones. Marine-specific enzyme formulations remain underdeveloped relative to terrestrial livestock applications.
Wales
Dairy and sheep sectors in Wales lag poultry in additive intensity, creating penetration opportunities for precision feeding systems. DEFRA's sustainable farming incentive rewards environmental outcomes including reduced feed waste. Methane inhibitor deployment remains underdeveloped outside established East Anglia clusters.
Northern Ireland
The Windsor Framework preserves EU-aligned regulatory rules while Great Britain diverges toward independent assessment procedures. Dual registration costs with the Veterinary Medicines Directorate and retained EU procedures fragment compliance pathways. Feed formulators face parallel dossier strategies for cross-border distribution.
United Kingdom Feed Additives Market Competitive Landscape
Player mix skews toward diversified nutrition conglomerates with captive enzyme research pipelines, creating tiered competition between integrated multinationals and specialized microbial technology developers. Market structure concentrates procurement leverage among four major poultry integrators, compressing supplier negotiation cycles and displacing spot purchasing with long-term fixed-volume agreements. Strategic archetypes include vertically integrated feed-nutrition hybrids, thermostable enzyme patent holders, and live-culture probiotic specialists. Dominant competitive moves encompass backward integration into fermentation capacity and outcome-based pricing contracts tied to measured feed conversion improvements.
Within the integrated nutrition tier, Cargill Inc., BASF SE, and Alltech occupy anchor positions. Cargill leverages its supply chain control across East Anglia broiler operations. BASF exemplifies specialized enzyme formulation capabilities through thermostable phytase variants. Alltech represents the live-culture specialist archetype with yeast-based bioactive platforms. These three entities collectively illustrate how procurement concentration among poultry integrators rewards scale, thermal stability IP, and antibiotic-free production system alignment.
| Leading Market Players |
|---|
| Dupont Danisco |
| Archer Daniels Midland Co. |
| Alltech |
| Evonik Industries AG |
| DSM Nutritional Products Inc. |
| Cargill Inc. |
| Nutreco |
| Volac International Ltd. |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Red Tractor assurance scheme certification gates both supplier qualification and price tiering simultaneously across United Kingdom feed additive procurement. DEFRA's independent assessment pathway for Great Britain adds parallel registration costs that suppliers recover through premium positioning against non-certified alternatives.
Pricing Analysis
Long-term cost-plus contracts with feed-grade phosphate indexation dominate poultry integrator agreements in East Anglia. Three-tier pricing structure across premium thermostable phytase, standard xylanase blends, and economy vitamin premixes reflects thermal stability IP and guaranteed matrix release values. Pricing pressure stems from Moroccan phosphate supply concentration forcing reformulation toward enzyme substitution. Independent dairy farms in Wales exhibit highest price sensitivity while East Anglia broiler integrators absorb premium enzyme pricing through outcome-based feed conversion contracts.
Supply Chain Analysis
Just-in-time enzyme delivery prevails among East Anglia integrators with dedicated liquid application infrastructure, while smaller mills maintain strategic stockpiles of dry premixes against harvest variability. Supply concentrates in Germany, Netherlands, and China for fermentation-derived amino acids and enzyme concentrates. UK formulators draw from Danish probiotic culture banks and American yeast bioactive platforms. Single-source vulnerability runs through Moroccan phosphate rock and Russian phosphate derivative supply. Distribution runs through Cargill's integrated supply chain into large-scale broiler operations near Norwich and Peterborough milling clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom feed additives market sits in early-cycle expansion as DEFRA's Environmental Improvement Plan nitrogen commitments accelerate amino acid adoption ahead of regulatory deadlines.
For Market Incumbents: Secure thermostable phytase patent positions against next-generation generic entrants fragmenting the enzyme category. Deepen backward integration into fermentation capacity to control input costs against volatile phosphate markets. Lock long-term fixed-volume contracts with the four major poultry integrators before spot purchasing fully displaces. For New Entrants and Emerging Players: DEFRA's fast-track sustainable farming incentive certification offers regulatory arbitrage against established Veterinary Medicines Directorate timelines. Wales and South West England dairy operations represent the most penetrable geography for precision feeding and methane inhibitor deployment. Bundle enzyme-probiotic combinations into outcome-based contracts tied to measured feed conversion improvements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed live-culture probiotic specialists lacking thermal stability IP or integrator-direct channel control. Five-to-ten year viability hinges on regulatory divergence between Great Britain and Northern Ireland creating dual-dossier cost advantages for scaled players. Watch for Veterinary Medicines Directorate approval timeline compression as the signal indicating consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive enzyme production insulates margins against Moroccan phosphate price volatility. |
| DEFRA Sustainable Farming Incentive Bundling | Outcome-based contracts align additive pricing with measured environmental performance. |
| Thermostable Phytase Patent Extension | IP protection maintains premium positioning through high-temperature pelleting lines. |
| Wales Dairy Sector Penetration | Underdeveloped precision feeding infrastructure creates first-mover advantage for methane inhibitors. |
| Dual Dossier Regulatory Strategy | Parallel Great Britain and Northern Ireland registration preserves cross-border market access. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork with feed formulators, poultry integrator procurement directors, Veterinary Medicines Directorate assessors, DEFRA policy officials, and East Anglia mill operations managers. Secondary validation drew from DEFRA Environmental Improvement Plan filings, retained EU legislation transition documents, Red Tractor assurance scheme specifications, customs trade data on phosphate imports, and compound feed production statistics. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation by livestock species, additive chemistry class, physical form, and nutritional purpose. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and integrator consolidation patterns. Forecast inputs included DEFRA nitrogen commitment implementation schedules, Windsor Framework regulatory divergence timelines, and poultry integrator capacity expansion announcements.
Decision-makers should treat outputs as directional under stable regulatory divergence assumptions; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding Veterinary Medicines Directorate approval velocity and phosphate supply continuity. Revision becomes warranted when Windsor Framework renegotiation or Moroccan supply disruption crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Carboxylic Acids Based Esters Market
Additives
Global Pour Point Depressant Market
Additives
Crystal Growth Modifier Market
Additives
Global Asphalt Additives Market
Additives
Sodium Stearyl Fumarate Market
Additives
Global Acidulants Market
Additives
China Sodium Reduction Ingredient Market
Additives
Global Zinc Stearate Market
Additives
Ammonium Phosphatide Market
Additives
Crosslinking Agents Market
Additives
Dishwashing Additives Market
Additives
Sorbitan Laurate Market
Additives
Printing Ink Additives Market
Additives
Triazine UV Absorber Market
Additives
Guanylic Acid Market
Additives
Plasticizer Alcohols Market