
 Europe Recycled Plastics Market | 2026-2036
Europe Recycled Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Recycled Plastics Market Intelligence
German mechanical recyclers is restructuring capacity networks across the Rhine-Ruhr corridor to serve brand-owner compliance deadlines. Veolia leverages integrated waste-to-resin infrastructure to lock in municipal feedstock contracts. Borealis AG anchors polymer innovation through its Borcycle platform, while MBA Polymers, Inc specializes in automotive-grade recycled ABS from shredded electronics waste.
Recycled plastics denote reprocessed thermoplastic polymers recovered from post-industrial or post-consumer streams, typically re-melted and pelletized to achieve melt-flow indices between 2 and 30 g/10 min for downstream compatibility. These materials displace virgin resin in applications where carbon-footprint reduction or regulatory minimum recycled content thresholds apply. Polyethylene terephthalate dominates beverage packaging due to established bottle-to-bottle collection infrastructure and EFSA food-contact approvals. Polypropylene trails in automotive underbody panels and interior trim where odor control and impact-strength consistency remain technical hurdles. Packaging as an end-use industry commands the deepest margin pools because fast-moving consumer goods brands face explicit recycled-content commitments under the EU Packaging and Packaging Waste Regulation.
The European Chemicals Agency administers REACH compliance for recycled feedstock traceability, while the EU Green Deal sets binding recycled-content floors that channel investment toward chemical recycling scale-up. EFSA food-contact assessments determine which post-consumer polyethylene terephthalate grades qualify for beverage applications, directly gatekeeping premium pricing tiers. Stakeholders must track how the F-Gas Regulation intersects with processing energy costs and whether the CSRD disclosure rules will force downstream buyers to audit Scope 3 resin sourcing.
Market Dynamics
The EU Green Deal's binding recycled-content mandates are compressing compliance timelines for packaging converters across Germany, France, and Italy. Mechanical recyclers in the Rhine-Ruhr corridor and chemical recycling investments near Rotterdam and Antwerp are racing to lock in food-grade polyethylene terephthalate capacity before enforcement deadlines harden.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Fast-moving consumer goods brands face explicit recycled-content floors, channeling capital toward bottle-to-bottle collection infrastructure and post-consumer resin offtake agreements.
- Chemical recycling scale-up:Pyrolysis and depolymerization units near Antwerp and Rotterdam are unlocking food-contact-grade feedstock streams that mechanical methods cannot purify, expanding addressable resin pools.
- Automotive lightweighting mandates:Recycled polypropylene from shredded electronics waste is penetrating underbody panels and interior trim as OEMs seek Scope 3 carbon reductions.
Market Restraints
- Feedstock price volatility:Post-consumer bale costs fluctuate with municipal collection efficiency and export competition from Asian buyers, compressing recycler margins.
- Technical odor and impact-strength limitations:Recycled polypropylene retains volatile organic compounds from prior use cycles, restricting deployment in premium automotive interior applications.
- REACH compliance complexity:ECHA traceability requirements for recycled feedstock add documentation burdens that slow batch release and extend qualification timelines.
Strategic Opportunities
- EFSA food-contact approvals:Premium pricing tiers await recyclers who secure beverage-grade polyethylene terephthalate certifications, gating access to Coca-Cola and Danone supply chains.
- Eastern European collection infrastructure:Underdeveloped sorting capacity in Poland and Romania offers first-mover advantages for integrated waste-to-resin platforms.
- CSRD disclosure rules:Scope 3 resin sourcing audits will force downstream buyers to verify recycled content claims, creating demand for blockchain-traceable supply chains.
Industry Challenges
- Polymer chemist and process engineer scarcity:Chemical recycling scale-up requires expertise in catalytic depolymerization that European technical universities have not yet scaled.
- Multi-year capex cycles:Pyrolysis reactors and purification trains demand five-to-seven-year construction timelines, misaligning with brand-owner compliance deadlines.
- EFSA certification bottlenecks:Food-contact safety assessments for novel recycling processes queue for eighteen-to-twenty-four months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Recycled Plastics Market |
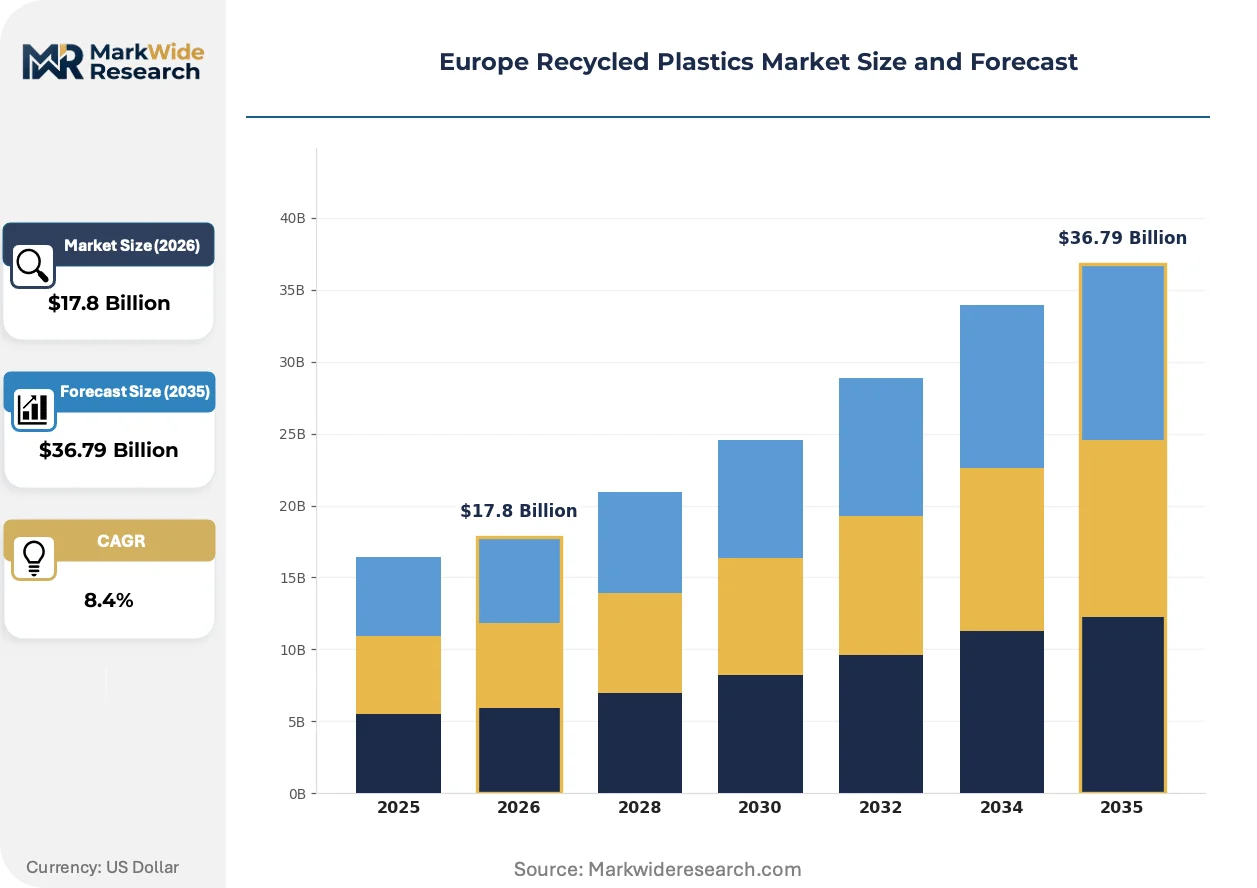
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $36.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyethylene Terephthalate, Polystyrene End Use Industry: Packaging, Automotive, Construction, Consumer Goods Grade: High Density, Low Density, Recycled, Engineering Processing Technique: Extrusion, Injection Molding, Blow Molding, Compression Molding |
| Companies Covered | Veolia, Müller-Guttenbrunn Group, MBA Polymers, Inc, Paprec Group, Morssinkhof Rymoplast, Suez SA, Borealis AG, LyondellBasell Industries Holdings B.V., Berry Global Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Recycled Plastics Market Strategic Shifts & Innovations
Chemical recycling technologies are overtaking mechanical reprocessing for food-contact applications. Three interconnected developments are compressing technology adoption curves and reshaping competitive positioning.
Pyrolysis-based polyethylene terephthalate purification is overtaking melt-reprocessing for beverage packaging. Coca-Cola Europacific Partners and Danone are qualifying resin from depolymerization units in the Netherlands at triple the pace of mechanical alternatives. This technology is overtaking legacy extrusion-pelletizing lines by unlocking EFSA-approved food-contact grades that mechanical methods cannot achieve.
CSRD disclosure rules are tightening Scope 3 audit requirements for downstream buyers. The EU Green Deal mandates force fast-moving consumer goods brands to document recycled resin percentages in packaging, redirecting procurement toward blockchain-traceable supply chains. German and French retailers are responding by demanding batch-level certificates from converters.
Automotive OEMs are consolidating recycled polypropylene suppliers around odor-controlled grades. Tier-1 interior trim manufacturers in Stuttgart and Munich are switching from virgin to post-consumer resin for underbody panels, compressing qualification cycles from thirty-six to eighteen months. This shift concentrates most visibly in German premium vehicle platforms.
Europe Recycled Plastics Market Segmentation
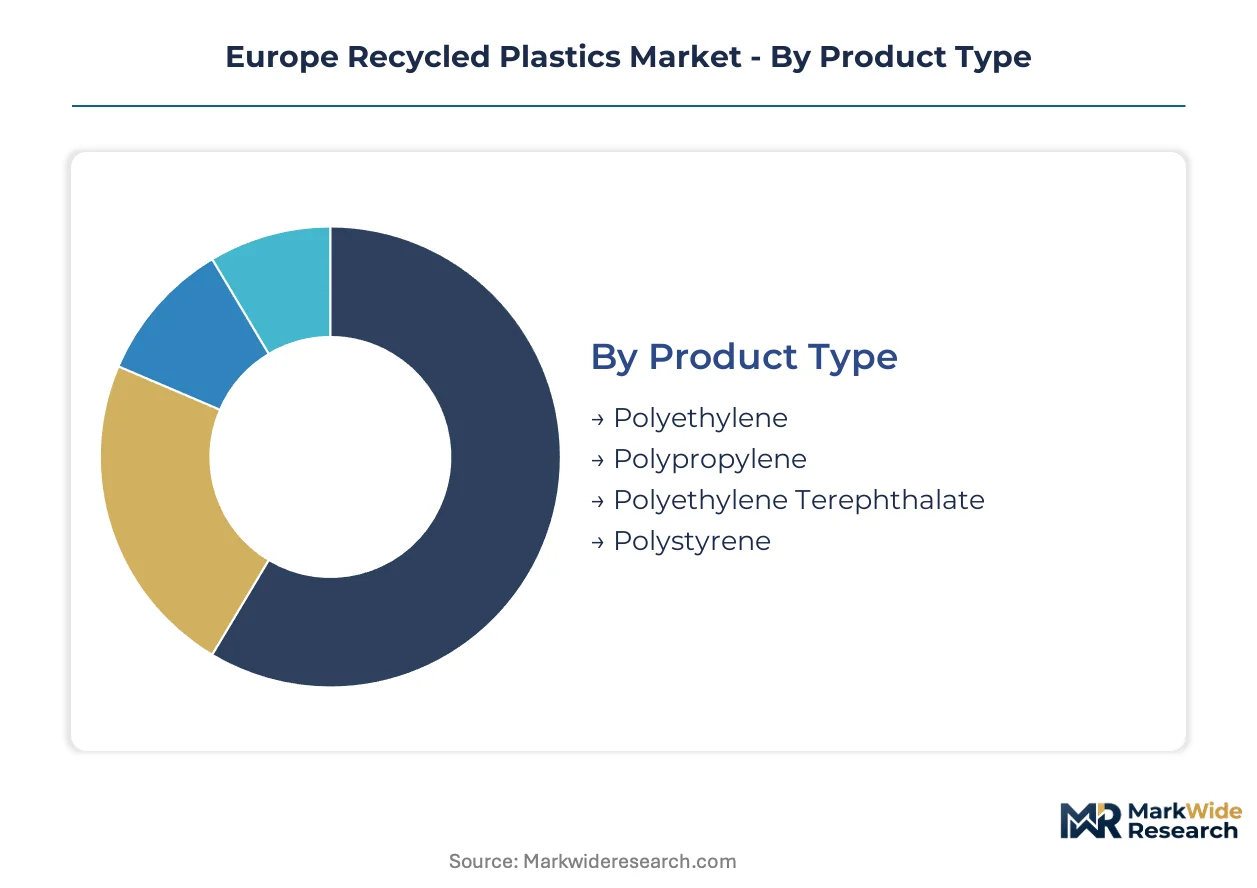
Segmentation in Europe's recycled plastics market reveals divergent margin profiles across polymer chemistry and processing intensity. Packaging converters prioritize EFSA-certified polyethylene terephthalate grades, while automotive buyers negotiate odor-controlled polypropylene supply contracts. Understanding these splits enables targeted capacity investments and compliance positioning.
Product Type:
Polyethylene terephthalate commands premium pricing through food-contact approvals, whereas polyethylene and polypropylene compete on volume throughput across industrial applications.
- Polyethylene Terephthalate:Depolymerization-purified resin achieves EFSA beverage-grade certification, unlocking bottle-to-bottle闭环 in Germany and the Netherlands. Coca-Cola Europacific Partners and Danone procurement teams concentrate offtake agreements around Rotterdam-Antwerp chemical recycling clusters to meet EU Packaging and Packaging Waste Regulation deadlines.
- Polypropylene:Post-consumer automotive and electronics waste streams supply underbody panels and interior trim for German OEM platforms. Odor control and impact-strength consistency remain unresolved technical barriers that restrict penetration into premium cabin applications despite Scope 3 carbon reduction mandates.
- Polyethylene:Film and rigid container applications dominate demand across French and Italian packaging converters. Mechanical reprocessing infrastructure in the Rhine-Ruhr corridor supplies lower-cost grades where food-contact certification is not required.
- Polystyrene:Insulation board and protective packaging applications absorb output from expanded polystyrene densification facilities. Construction sector demand in Poland and Romania offers expansion potential for integrated waste-to-resin platforms.
Today's leader: Polyethylene Terephthalate. Tomorrow's challenger: Polypropylene.
End Use Industry:
Packaging converters absorb the deepest volume pools, yet automotive procurement is climbing fastest as OEMs audit Scope 3 resin sourcing.
- Packaging:Fast-moving consumer goods brands face explicit recycled-content floors under EU Green Deal mandates. German and French retailers now demand batch-level blockchain-traceable certificates from converters, redirecting procurement toward qualified post-consumer resin suppliers.
- Automotive:Tier-1 manufacturers in Stuttgart and Munich compress qualification cycles from thirty-six to eighteen months for recycled polypropylene interior components. Lightweighting mandates and carbon footprint reduction targets concentrate demand around odor-controlled grades from shredded electronics waste.
- Construction:Insulation and piping applications utilize lower-grade polyethylene and polystyrene where mechanical properties are less critical. Eastern European infrastructure build-out in Poland and Romania creates feedstock collection opportunities.
- Consumer Goods:Electronics housings and furniture applications source recycled ABS from MBA Polymers' Austrian facility. REACH compliance documentation burdens slow batch release for complex multi-polymer assemblies.
Packaging anchors current revenue. Automotive represents the steepest expansion trajectory.
Grade:
High-density grades capture structural applications, while recycled-grade certification gates access to premium pricing tiers.
- Recycled:Post-consumer and post-industrial resin streams require ECHA traceability documentation under REACH. Food-contact approvals from EFSA separate beverage-grade polyethylene terephthalate pricing from industrial-grade alternatives.
- High Density:Rigid packaging and construction piping demand melt-flow indices optimized for extrusion stability. German mechanical recyclers in the Rhine-Ruhr corridor specialize in consistent pellet supply for these applications.
- Low Density:Film and flexible packaging applications prioritize clarity and seal strength. Collection infrastructure limitations in Eastern Europe constrain feedstock availability for these grades.
- Engineering:Automotive and electronics applications specify impact-modified and flame-retardant compounds. Chemical recycling scale-up near Antwerp and Rotterdam targets these higher-margin specialty grades.
Recycled grade dominates volume. Engineering grade captures margin.
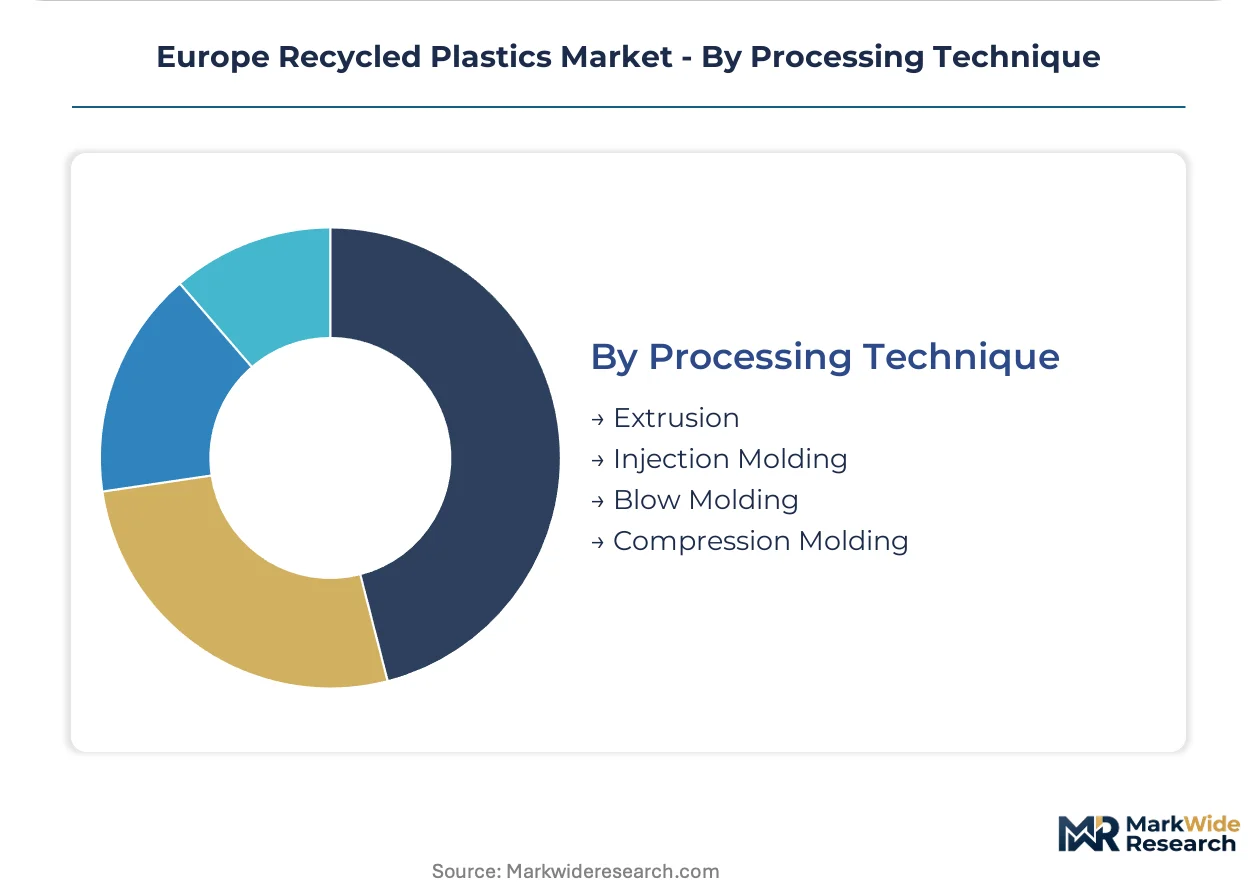
Processing Technique:
Extrusion and injection molding split the market between packaging film and automotive structural components.
- Extrusion:Sheet and film production for flexible packaging runs through twin-screw compounding lines optimized for polyethylene terephthalate flake. French and Italian converters integrate inline quality monitoring to maintain thickness tolerance.
- Injection Molding:Automotive underbody panels and consumer goods housings require pellet consistency within narrow melt-flow ranges. German Tier-1 suppliers enforce statistical process control protocols for recycled polypropylene feedstock.
- Blow Molding:Bottle production demands EFSA-certified polyethylene terephthalate with controlled acetaldehyde levels. Chemical recycling output from Netherlands-based depolymerization units is overtaking mechanically reprocessed alternatives for this application.
- Compression Molding:Thermoset replacement and large-format construction components utilize glass-fiber-reinforced recycled grades. Lower throughput volumes limit dedicated capacity investment.
Extrusion leads in installed base. Blow molding is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where REACH compliance costs and municipal feedstock contracts create arbitrage opportunities. German recyclers leverage established waste-to-resin infrastructure while Dutch chemical recycling clusters capture premium food-grade certification premiums.
Germany
Mechanical recyclers restructure capacity networks across the Rhine-Ruhr corridor to serve brand-owner compliance deadlines. The EU Packaging and Packaging Waste Regulation forces fast-moving consumer goods brands to secure post-consumer resin offtake agreements. Stuttgart and Munich automotive clusters compress qualification cycles for recycled polypropylene interior components.
Netherlands
Depolymerization units near Rotterdam unlock EFSA-approved food-contact grades that mechanical methods cannot achieve. The EU Green Deal's binding recycled-content mandates channel capital toward pyrolysis infrastructure. Coca-Cola Europacific Partners and Danone procurement teams concentrate offtake agreements around Rotterdam-Antwerp chemical recycling clusters.
France
Packaging converters absorb deep volume pools as retailers demand batch-level blockchain-traceable certificates. EFSA food-contact assessments determine which post-consumer polyethylene terephthalate grades qualify for beverage applications. French converters integrate inline quality monitoring to maintain thickness tolerance for flexible packaging film.
Italy
Mechanical reprocessing infrastructure supplies lower-cost polyethylene grades where food-contact certification is not required. The F-Gas Regulation intersects with processing energy costs for Italian extrusion operators. Northern Italian packaging clusters specialize in rigid container applications for fast-moving consumer goods brands.
Belgium
Chemical recycling investments near Antwerp concentrate demand for food-grade recycled polyethylene terephthalate. ECHA traceability requirements for recycled feedstock add documentation burdens that slow batch release. Antwerp-based purification trains target engineering-grade compounds for automotive and electronics applications.
Europe Recycled Plastics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue chemical recycling scale-up and blockchain-traceable supply chains. The vendor base splits between integrated waste-to-resin platforms and specialized polymer innovators. Three archetypes dominate: municipal feedstock aggregators, catalytic depolymerization specialists, and automotive-grade compounders. Competitive moves center on locking in long-term municipal contracts and securing EFSA food-contact certifications before enforcement deadlines harden.
Within the integrated infrastructure tier, Veolia leverages captive waste-to-resin platforms to secure municipal feedstock contracts across multiple jurisdictions. Borealis AG anchors polymer innovation through its Borcycle platform, representing the specialty compounder archetype that bridges mechanical and chemical processing. MBA Polymers, Inc exemplifies the focused specialist model, concentrating on automotive-grade recycled ABS from specific waste streams. These three occupy distinct competitive positions without direct overlap in core feedstock categories.
| Leading Market Players |
|---|
| Veolia |
| Müller-Guttenbrunn Group |
| MBA Polymers, Inc |
| Paprec Group |
| Morssinkhof Rymoplast |
| Suez SA |
| Borealis AG |
| LyondellBasell Industries Holdings B.V. |
| Berry Global Inc |
| Others |
Cost & Logistics Intelligence
Fast-moving consumer goods procurement teams concentrate purchasing power through long-term offtake agreements, anchoring contract-based pricing for EFSA-certified polyethylene terephthalate grades. This buyer concentration compresses spot-market premiums while channeling volume toward integrated waste-to-resin platforms with locked municipal feedstock contracts.
Pricing Analysis
Distributor margins for recycled resin narrow as direct converter-offtake agreements proliferate under EU Packaging and Packaging Waste Regulation deadlines. Pricing stratifies across EFSA food-contact certification tiers, with beverage-grade polyethylene terephthalate commanding substantial premiums over industrial-grade alternatives. Cost compression in mechanical reprocessing stems from post-consumer bale cost volatility and Asian export competition. Small packaging converters exhibit highest price sensitivity, while Coca-Cola Europacific Partners and Danone absorb premium tiers for supply security.
Supply Chain Analysis
Polymer chemist and process engineer scarcity in the Netherlands and Belgium constrains chemical recycling scale-up near Rotterdam and Antwerp. Supply concentrates in Germany, the Netherlands, and Belgium, drawing from municipal collection systems and shredded automotive electronics waste streams. Feedstock rests on baled post-consumer plastics, catalytic depolymerization reagents, and purification train components. Single-source vulnerability around EFSA certification bottlenecks threatens batch release timelines. Distribution runs through integrated waste-to-resin platforms and specialized compounders serving converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal recycled-content mandates harden enforcement timelines and force capital deployment toward compliant capacity.
For Market Incumbents: Hedge against chemical recycling disruption by securing municipal feedstock contracts in Eastern Europe before integrated platforms consolidate collection infrastructure. Borealis AG and Veolia should accelerate Borcycle platform investments to defend mechanical reprocessing margins from pyrolysis-based competition. EFSA certification bottlenecks represent the critical threat to revenue recognition timelines. For New Entrants and Emerging Players: Capture underdeveloped sorting capacity in Poland and Romania where first-mover advantages await integrated waste-to-resin platforms. Automotive-grade recycled polypropylene for German OEM platforms offers the most penetrable segment given odor-control technical barriers that incumbent compounders have not fully resolved. Pursue direct qualification partnerships with Tier-1 suppliers in Stuttgart and Munich to bypass distributor margin layers. For Investors and Strategic Acquirers: Chemical companies with circular-economy mandates are the most active acquirer in this space, consolidating catalytic depolymerization capabilities ahead of enforcement deadlines. The five-to-ten-year viability window favors platforms with locked feedstock and EFSA pipeline clearance. Watch EFSA food-contact approval queue lengths as the inflection signal for revenue recognition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Food-Contact Certification | Unlocks beverage-grade polyethylene terephthalate premiums for Coca-Cola and Danone supply chains. |
| Chemical Recycling Scale-Up | Pyrolysis units near Rotterdam achieve purification levels mechanical methods cannot match. |
| Eastern European Collection Infrastructure | Poland and Romania offer first-mover aggregation advantages before integrated platforms arrive. |
| Blockchain-Traceable Supply Chains | CSRD disclosure rules force downstream buyers to verify recycled content claims batch-by-batch. |
| Automotive Odor-Control R&D | German OEMs compress qualification cycles for recycled polypropylene interior components. |
Research Approach
Multiple input streams — executive interviews with packaging converters, technical discussions with chemical recycling operators, and regulatory tracking across ECHA and EFSA proceedings — were reconciled against customs data and EU waste shipment records. Primary engagement targeted polymer procurement leads at fast-moving consumer goods brands, plant managers at Rhine-Ruhr mechanical recyclers, and regulatory affairs directors navigating REACH compliance. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, EFSA food-contact safety assessments, and national waste statistics. Bottom-up resin demand modeling and top-down circular-economy policy impact assessment were cross-referenced for triangulation.
Historical capacity expansion patterns were cross-referenced against panel input from chemical recycling technology providers and municipal waste authority planning officers. The analytical framework segments across polymer chemistry, processing technique, and end-use industry throughout the projection horizon. CAGRs were derived from elasticity modeling against EU Green Deal mandate enforcement curves. Key forecast inputs include EFSA certification queue projections and automotive OEM recycled-content commitment timelines.
Feedstock price volatility, EFSA approval delays, and chemical recycling technology yield uncertainty are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about regulatory enforcement timing and technology scale-up trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Recycled Leather Market
Recycled Plastics
North America Plastic Recycling Market
Recycled Plastics
Industrial Plastic Market
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
Plastic Waste Management Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
Recycled Carbon Fiber Market
Recycled Plastics
Engineering Plastic Recycling Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Plastic Color Sorter Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
India Plastic Market