
 Global Cement Additives Market | 2026-2036
Global Cement Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cement Additives Market Foresight
The gap between performance-grade formulations and baseline commodity blends is realigning procurement patterns across major construction corridors. Sika AG leverages its European R&D footprint to dominate specialty grouts and shotcrete admixtures in tunneling applications. BASF SE anchors its position through backward integration into polycarboxylate ether polymers, controlling raw material quality for high-range water reducers. GCP Applied Technologies competes on digital dosing systems that tie additive delivery to real-time rheology monitoring on job sites.
Cement additives comprise organic and inorganic compounds dosed at 0.1–5.0% by weight of cementitious content to modify hydration kinetics, workability, or hardened performance, with polycarboxylate ethers and lignosulfonates representing the dominant chemistries in modern water reducer systems. Their primary purpose is to enable clinker factor reduction while meeting compressive strength targets and placement window requirements under variable ambient conditions. Water reducers command the deepest margin pools as contractors face specification pressure for self-consolidating and high-performance concrete in vertical structures. Strength enhancers represent the fastest-expanding chemistry class as producers seek to compensate for lower-grade supplementary cementitious materials in blended cements. Ready-mix concrete absorbs the largest volume share of liquid admixtures due to centralized batching control and just-in-time delivery logistics.
EPA industrial effluent guidelines in the United States restrict phenol and formaldehyde discharge from additive manufacturing facilities, pushing producers toward bio-based dispersant chemistries. REACH registration requirements in Europe compel full toxicological dossiers for novel surfactant chemistries, extending development timelines and favoring incumbents with existing substance portfolios. China's MEE enforces increasingly stringent VOC limits on emulsion-based air entraining agents, reshaping formulation choices for domestic suppliers. Stakeholders must track how divergent chemical registration burdens across Washington, Brussels, and Beijing fragment product standardization and complicate global formulation strategies.
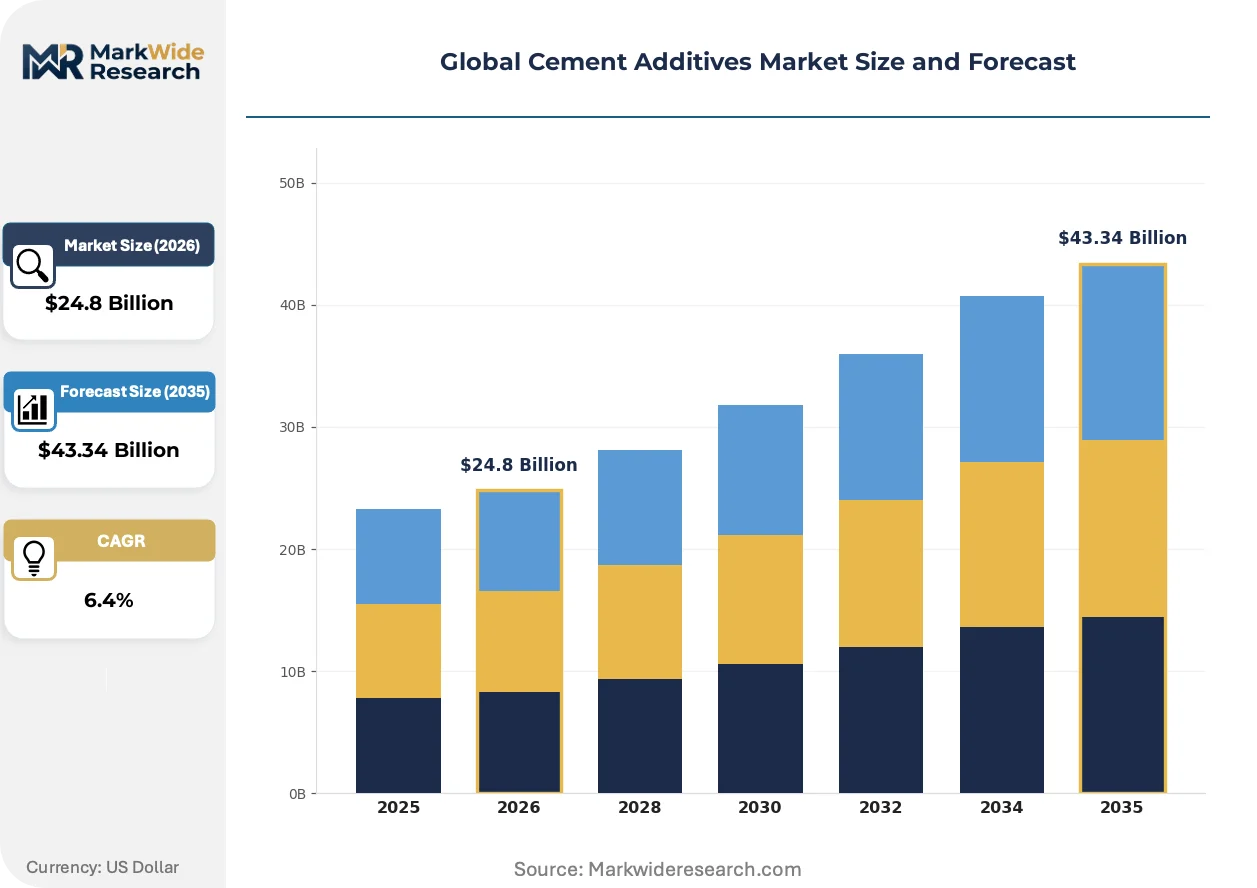
Market Dynamics
China's GB standards on clinker substitution are compressing permissible emissions intensity, forcing additive-intensive concrete formulations into megaproject specifications across Southeast Asian infrastructure corridors.
Growth Catalysts
- Dual carbon goals:China's binding targets on carbon intensity per unit of GDP are accelerating demand for strength enhancers that enable lower clinker factors in blended cements.
- Green building mandates:State-level regulations in Gujarat and Maharashtra are requiring contractors to specify high-range water reducers for public infrastructure durability.
- Shotcrete tunneling:Southeast Asian infrastructure developers are scaling specialty grouts for underground transit and hydropower projects requiring rapid set control.
Market Restraints
- Ethylene oxide volatility:Polycarboxylate ether feedstock costs fluctuate with crude-linked petrochemical spreads, squeezing margin pools on water reducers.
- REACH dossier burdens:ECHA registration requirements for novel surfactant chemistries extend development timelines and favor incumbents with existing substance portfolios.
- Formaldehyde discharge limits:EPA industrial effluent guidelines restrict phenol and formaldehyde emissions from additive manufacturing, pushing reformulation costs onto producers.
Strategic Opportunities
- VOC-compliant air entrainers:China's MEE enforcement on emulsion-based formulations creates first-mover advantage for domestic suppliers with solvent-free chemistries.
- Digital dosing integration:Real-time rheology monitoring systems tied to additive delivery represent white space in ready-mix concrete batching control.
- India's western corridor:Aggressive state-level green building mandates in Gujarat and Maharashtra concentrate demand for certified high-performance admixtures.
Industry Challenges
- Formulation chemist scarcity:The specialized skill set for polycarboxylate ether molecular architecture sits concentrated with European and Japanese technical specialists.
- Legacy batching system integration:Automated dosing hardware requires retrofitting of existing ready-mix plant infrastructure, complicating deployment timelines.
- Multi-jurisdictional compliance:Divergent chemical registration burdens across Washington, Brussels, and Beijing fragment product standardization and complicate global formulation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cement Additives Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Reducers, Set Accelerators, Set Retarders, Air Entraining Agents, Strength Enhancers Application: Precast Concrete, Ready-Mix Concrete, Shotcrete, Roller Compacted Concrete, Civil Engineering Projects Form: Liquid, Powder, Granular, Emulsion, Paste End User: Construction Contractors, Infrastructure Developers, Concrete Producers, Building Material Suppliers |
| Companies Covered | BASF SE, Sika AG, GCP Applied Technologies, Fosroc International Ltd., Mapei S.p.A., CEMEX S.A.B. de C.V., Arkema Group, LafargeHolcim, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cement Additives Market Shifts & Advancements
Bio-based dispersant chemistries are displacing petroleum-derived alternatives as discharge regulations tighten across major manufacturing jurisdictions, reshaping R&D priorities and raw material sourcing.
Polycarboxylate ether superplasticizers with tailored side-chain density are enabling self-consolidating concrete placement in densely reinforced vertical structures. High-rise contractors in Singapore and Dubai are specifying these grades for pumpability at extended distances. The technology is converging with real-time slump monitoring to compress quality control cycles on megaproject sites.
REACH registration requirements in Europe are compelling full toxicological dossiers for novel surfactant chemistries entering the market. Development timelines have extended by 18-36 months for new molecular entities. Specialty admixture producers with grandfathered substance portfolios are widening their formulation lead over challengers.
Centralized procurement of liquid admixtures through ready-mix concrete producers is consolidating specification authority away from individual contractors. Volume commitments and technical service bundling are displacing spot purchasing in urban construction corridors. This concentration is most visible in India's western states, where integrated producers are capturing specification lock-in through performance guarantees.
Global Cement Additives Market Segmentation
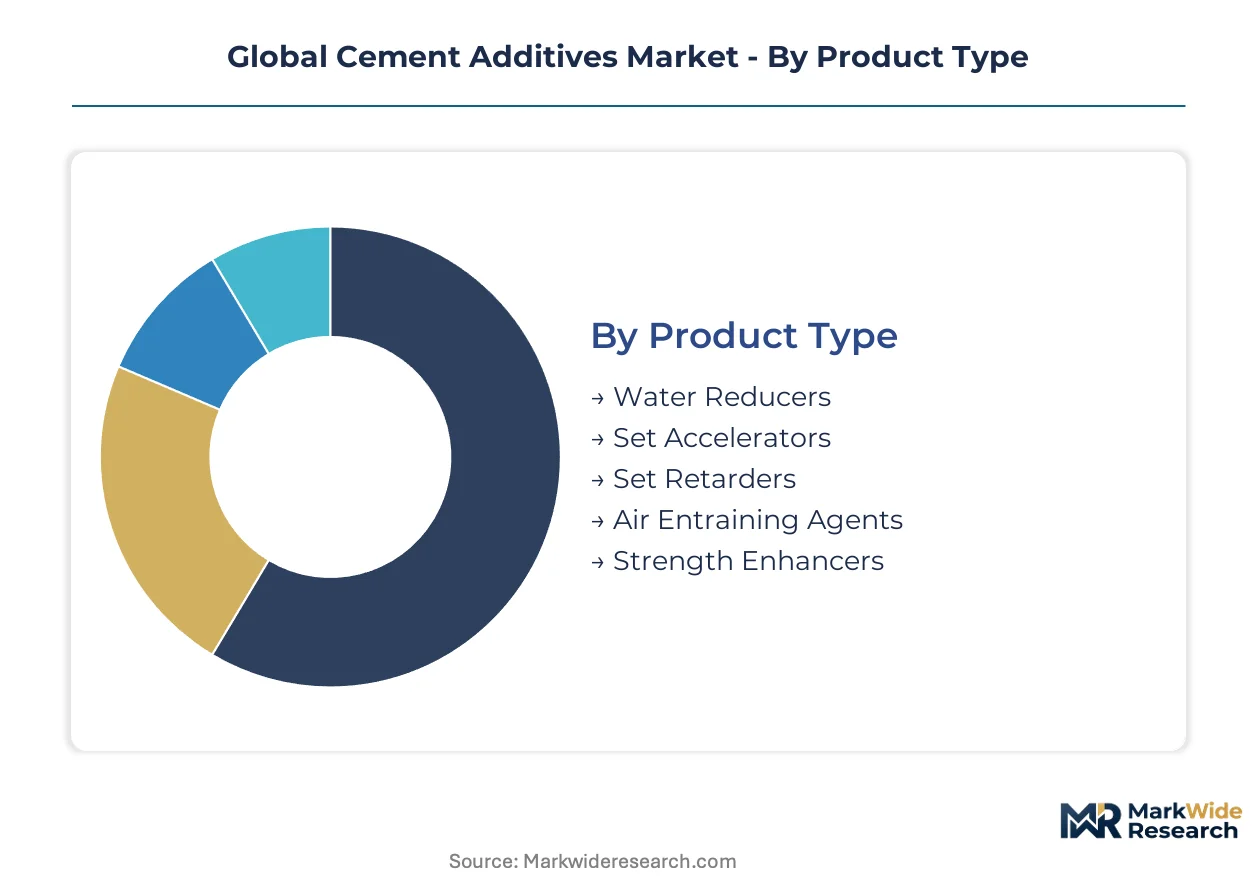
Cement additives fragment across four dimensions that dictate formulation economics and procurement authority. Product chemistry determines margin structure. Application context drives specification power. Form factor shapes logistics costs. End-user concentration influences contract terms.
Product Type:
Supply concentration among polycarboxylate ether producers tilts competitive leverage toward water reducer specialists with captive polymer capacity.
- Water Reducers:Polycarboxylate ether and lignosulfonate chemistries dominate modern high-range systems. Demand concentrates in Singapore and Dubai high-rise construction, where contractors specify self-consolidating concrete for pumpability at extended distances under tight placement windows.
- Strength Enhancers:Alkanolamine and inorganic salt formulations compensate for lower-grade supplementary cementitious materials in blended cements. Gujarat and Maharashtra infrastructure developers are scaling these additives aggressively under state-level green building mandates requiring clinker factor reduction.
- Set Accelerators:Calcium chloride and non-chloride alternatives compress early strength development timelines for cold-weather pours.
- Set Retarders:Hydroxycarboxylic acid and phosphonate chemistries extend workability in hot-climate mass concrete placements.
- Air Entraining Agents:Emulsion-based and solvent-free formulations face tightening VOC enforcement from China's MEE, favoring domestic suppliers with compliant chemistries.
Today's leader: Water Reducers. Tomorrow's challenger: Strength Enhancers.
Application:
Cost tier differentiation separates specification-intensive vertical structures from commodity horizontal placements.
- Ready-Mix Concrete:Centralized batching control enables just-in-time liquid admixture delivery with real-time rheology monitoring. India's western corridor shows the steepest expansion trajectory as integrated producers capture specification lock-in through performance guarantees and technical service bundling.
- Shotcrete:Specialty grouts with rapid set control dominate underground transit and hydropower tunneling across Southeast Asian infrastructure corridors. Sika AG leverages its European R&D footprint to anchor market position in this specification-driven segment.
- Precast Concrete:Controlled factory environments favor automated dosing systems with precise quality control cycles.
- Roller Compacted Concrete:Dam and pavement applications require viscosity-modifying admixtures for low-cement-content mixes.
- Civil Engineering Projects:Mass concrete placements for bridges and marine structures drive demand for hydration control and thermal crack mitigation.
Ready-mix commands volume authority. Shotcrete captures margin premiums.
Form:
Volume economics favor liquid formulations where logistics infrastructure supports bulk delivery and automated dosing integration.
- Liquid:Dominates ready-mix concrete through centralized batching control and pumpable delivery systems. Digital dosing hardware ties additive delivery to real-time slump monitoring, compressing quality control cycles on megaproject sites.
- Powder:Preferred for remote precast operations lacking liquid storage infrastructure and automated handling systems.
- Granular:Enables precise hand-dosing in small-batch mortar and specialty repair applications.
- Emulsion:Air entraining agents in emulsion form face reformulation pressure from China's MEE VOC limits.
- Paste:Concentrated thickeners for specialized rheology modification in underwater and self-leveling applications.
Liquid maintains logistics advantage. Powder serves infrastructure gaps.
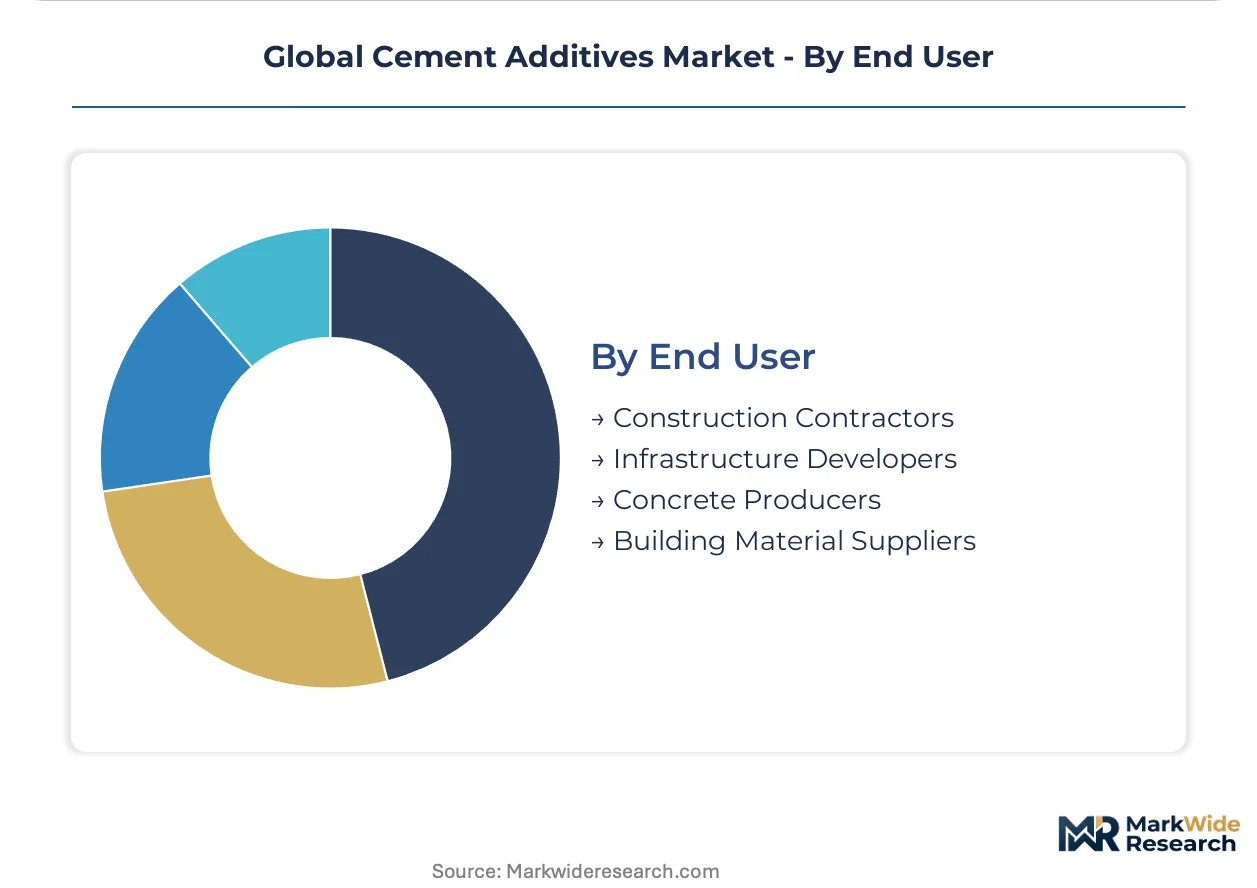
End User:
Customer type determines procurement leverage, with concrete producers consolidating specification authority away from individual contractors.
- Concrete Producers:Centralized procurement through ready-mix operators displaces spot purchasing in urban construction corridors. Volume commitments and technical service bundling create specification lock-in, most visible in India's western states where integrated producers dominate.
- Infrastructure Developers:Megaproject owners in Southeast Asia specify additive-intensive formulations for durability under aggressive procurement terms.
- Construction Contractors:Individual contractors retain limited specification power as procurement authority shifts upstream to batching operations.
- Building Material Suppliers:Distributors serve fragmented small-batch demand with limited technical service attachment.
Concrete producers hold procurement power. Infrastructure developers set performance standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with polycarboxylate ether molecular architecture expertise cluster disproportionately in European and Japanese technical centers, creating talent scarcity that shapes regional competitive dynamics across major construction corridors.
China
Dual carbon goals and tightening GB standards on clinker substitution are compressing permissible emissions intensity across cement production. The Ministry of Ecology and Environment enforces increasingly stringent VOC limits on emulsion-based air entraining agents. Infrastructure developers in the Yangtze River Delta and Pearl River Delta are scaling additive-intensive concrete formulations for megaproject durability under state-mandated green building protocols.
India
State-level green building mandates in Gujarat and Maharashtra are requiring contractors to specify high-range water reducers for public infrastructure durability. The Bureau of Indian Standards certifies admixture performance grades under evolving national construction codes. Ready-mix concrete producers in Mumbai-Ahmedabad corridor are consolidating procurement authority through volume commitments and technical service bundling.
United States
EPA industrial effluent guidelines restrict phenol and formaldehyde discharge from additive manufacturing facilities, pushing producers toward bio-based dispersant chemistries. Infrastructure investment packages are channeling specification demand toward high-performance concrete for bridge and marine structure rehabilitation. Texas and California contractors face specification pressure for self-consolidating concrete in vertical structures.
Germany
REACH registration requirements compel full toxicological dossiers for novel surfactant chemistries, extending development timelines and favoring incumbents with existing substance portfolios. The EU Green Deal carbon border adjustments are reshaping import competitiveness for cementitious materials. Specialty admixture R&D clusters in North Rhine-Westphalia and Bavaria anchor European formulation leadership.
Singapore
High-rise contractors specify polycarboxylate ether superplasticizers with tailored side-chain density for pumpability at extended distances in densely reinforced vertical structures. The Building and Construction Authority mandates durability performance standards for underground transit and hydropower tunneling projects. Southeast Asian infrastructure developers source specialty grouts through Singapore-based technical service hubs.
Global Cement Additives Market Competitive Landscape
Top-tier vendors anchor specialty formulation segments, while commodity water reducer suppliers compete on ethylene oxide feedstock cost management and logistics scale. The market structure tilts toward consolidated procurement authority as ready-mix concrete producers displace individual contractor specification power. Three archetypes dominate: integrated chemical conglomerates with captive polymer capacity, specialty admixture pure-plays with European R&D footprints, and construction material majors with backward integration into dosing system hardware. Competitive moves center on digital dosing integration partnerships and bio-based chemistry reformulation to meet tightening discharge regulations.
Among European-based specialists, Sika AG and BASF SE exemplify divergent strategic positions within the specialty tier. Sika AG represents the dedicated admixture pure-play archetype with concentrated technical service bundling. BASF SE anchors the integrated chemical conglomerate model with upstream control over polycarboxylate ether polymer supply chains. GCP Applied Technologies occupies a position at the intersection of chemical formulation and automated dosing hardware, illustrating the convergence trajectory between additive chemistry and batching control systems.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| GCP Applied Technologies |
| Fosroc International Ltd. |
| Mapei S.p.A. |
| CEMEX S.A.B. de C.V. |
| Arkema Group |
| LafargeHolcim |
| Dow Chemical Company |
| Others |
Supply & Pricing Matrix
Captive polymer production anchors competitive position across water reducer supply tiers. BASF SE controls upstream polycarboxylate ether capacity that shields margin pools from ethylene oxide feedstock volatility. This backward integration feeds pricing power into specialty formulations while commodity suppliers absorb spot market pressure.
Pricing Analysis
Bundled technical service contracts separate premium admixture suppliers from unbundled commodity traders. Three-tier pricing structure across certified performance, standard grade, and economy bulk tiers reflects certification differential and volume scale. Pricing pressure stems from ethylene oxide cost volatility squeezing non-integrated producers. Small-batch contractors show highest price sensitivity; megaproject developers with durability specifications show lowest.
Supply Chain Analysis
Bulk liquid logistics costs dominate total delivered economics for ready-mix concrete producers. Manufacturing concentrates in Germany, China, and India with formulation R&D clustering in European technical centers. Raw material draws from ethylene oxide crackers, alkanolamine refiners, and lignin processors. Single-source vulnerability sits with polycarboxylate ether polymer supply. Distribution runs through integrated ready-mix batching operations with automated dosing hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-burdened European formulation costs and India's state-mandated green building procurement premiums.
For Market Incumbents: Hedge ethylene oxide exposure through captive polymer capacity or long-term offtake agreements with petrochemical suppliers. Defend specification lock-in by embedding digital dosing systems into ready-mix customer operations. Priority lever: technical service bundling that raises switching costs for concrete producers in India's western corridor. For New Entrants and Emerging Players: China's MEE VOC enforcement on emulsion-based air entrainers opens a window for solvent-free chemistry specialists to capture domestic reformulation demand. Target Gujarat and Maharashtra infrastructure contractors facing aggressive state-level green building mandates. Go-to-market angle: performance guarantees tied to clinker factor reduction compliance. For Investors and Strategic Acquirers: Roll-up economics work for regional admixture formulators because procurement authority is consolidating toward ready-mix concrete producers seeking single-source technical service partners. Long-term viability hinges on backward integration into polymer supply or forward integration into dosing hardware. Signal to watch: automated batching system retrofit rates at mid-cap concrete plants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polycarboxylate Ethers | Captive polymer supply insulates margin pools from ethylene oxide volatility at BASF SE scale. |
| Digital Dosing System Partnerships | Real-time rheology monitoring hardware locks in specification authority with ready-mix producers. |
| VOC-Compliant Air Entrainer Reformulation | Solvent-free chemistries capture first-mover advantage under China's MEE enforcement trajectory. |
| Technical Service Bundling Expansion | Performance guarantees consolidate procurement lock-in with Gujarat and Maharashtra contractors. |
| Green Certification Investment | Certified admixture grades command specification priority under India's Bureau of Indian Standards evolution. |
Research Methodology
Direct dialogue with admixture formulation chemists, ready-mix concrete procurement directors, tunneling project engineers, and regulatory compliance officers grounded qualitative findings. Secondary validation drew from EPA industrial effluent filings, ECHA REACH registration databases, China MEE emission standards, and Bureau of Indian Standards construction code updates. Bottom-up volume estimates triangulated against top-down construction spending projections across the analysis window.
Top-down macroeconomic drivers filtered through bottom-up segment granularity across product chemistry, application context, form factor, and end-user concentration. Segmentation modeling captured water reducer, strength enhancer, and air entrainer chemistries against ready-mix, shotcrete, and precast deployment channels. CAGRs derived from elasticity-adjusted demand curves responding to clinker substitution mandates and green building procurement protocols.
Revisions become necessary when regulatory enforcement timelines accelerate, ethylene oxide supply disruptions materialize, or ready-mix consolidation shifts procurement leverage. Forecasts reflect documented assumptions on infrastructure spending trajectories and chemical registration burden evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Lactic Acid Ester Market
Additives
Global Mold Release Agents Market
Additives
Foundry Additives Market
Additives
Global Asphalt Additives Market
Additives
Antiknock Agents Market
Additives
Extrusion Aids Market
Additives
Engine Oil Additive Market
Additives
Ethoxyquin Market
Additives
Anti-Foaming Agent Market
Additives
Plastics Modifiers Market
Additives
Marine Fuel Additives Market
Additives
Feedstuff Additives Market
Additives
Tartaric Acid Market
Additives
Green Polymer Additive Market
Additives
Citric Acid Anhydrous Market
Additives
United States Betaine Market