
 Pectin Market | 2026-2036
Pectin Market Size, Share, and Industry Trends Forecast 2026-2036
Pectin Market Analysis
Pharmaceutical-grade pectin specifications are unwinding new margin pools for suppliers capable of meeting USP and EP monograph standards. CP Kelco leverages its integrated citrus peel supply chain to secure consistent raw material access across hemispheres. Herbstreith & Fox Corporate Group anchors European demand through specialized apple pectin production from regional orchards. Silvateam S.p.A. competes via tannin-pectin synergies that extend its portfolio into natural extract adjacencies.
Pectin denotes a family of complex polysaccharides rich in galacturonic acid units, extracted primarily from citrus peels and apple pomace through acid hydrolysis at controlled temperature and pH, functioning as a gelling agent, stabilizer, and thickener across food, pharmaceutical, and cosmetic matrices. High-methoxyl pectin dominates jam and jelly applications where rapid-set behavior under high-sugar conditions commands established volume. Low-methoxyl pectin captures expanding share in dairy and reduced-sugar confectionery as calcium-reactive gelling meets clean-label formulation requirements. Amidated pectin occupies a specialized niche in pharmaceutical tableting and controlled-release nutraceutical matrices where modified rheology justifies premium positioning.
Food and beverage regulators including the FDA, EFSA, and FSSAI enforce additive purity thresholds and labeling protocols that determine which pectin grades achieve market access in their respective jurisdictions. REACH and EU Green Deal frameworks impose extraction solvent and waste-stream accountability on European producers, elevating compliance costs for non-integrated operators. Stakeholders must monitor evolving clean-label certification schemes and regional pharmaceutical monograph updates to anticipate which specification tiers will command supply priority.
Market Dynamics
Clean-label formulation mandates from EFSA and FDA are compressing synthetic stabilizer volumes while elevating pectin specifications across food and pharmaceutical supply chains. This regulatory convergence with citrus peel supply concentration in Brazil and Spain is restructuring procurement priorities for global manufacturers.
Growth Catalysts
- EU Green Deal solvent standards:REACH-compliant extraction protocols are disqualifying conventional acid-hydrolysis operators, creating volume capture opportunities for certified European producers.
- Reduced-sugar confectionery:Low-methoxyl pectin demand is accelerating in dairy and premium candy segments where calcium-reactive gelling replaces gelatin and synthetic alternatives.
- Pharmaceutical tableting:USP-grade amidated pectin specifications are expanding controlled-release nutraceutical applications with premium margin structures.
Market Restraints
- Citrus peel supply volatility:Brazilian orange harvest fluctuations and Spanish lemon processing concentration create raw material price instability for non-integrated extractors.
- High-methoxyl technical ceiling:Sugar-dependent gelation limits application in sub-55% soluble-solids formulations, capping penetration in health-positioned products.
- Gelatin substitution economics:Bovine and porcine collagen derivatives retain cost advantages in conventional confectionery, constraining pectin volume in price-sensitive segments.
Strategic Opportunities
- India FSSAI clean-label enforcement:Emerging regulatory alignment with Codex standards is opening formulation-switch opportunities in processed dairy and traditional sweets.
- Cell-culture scaffolding:Pharmaceutical-grade pectin hydrogels are converging with regenerative medicine applications, creating adjacent demand beyond conventional matrices.
- Direct-to-manufacturer digital procurement:B2B platform adoption by mid-size food processors is disintermediating traditional distributor channels for specialty pectin grades.
Industry Challenges
- Pharmaceutical monograph certification timelines:USP and EP compliance validation requires 18-24 month qualification cycles, delaying margin capture for new entrants.
- Multi-feedstock process engineering:Switching between citrus peel and apple pomace extraction lines demands specialized equipment reconfiguration and skilled technician availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pectin Market |
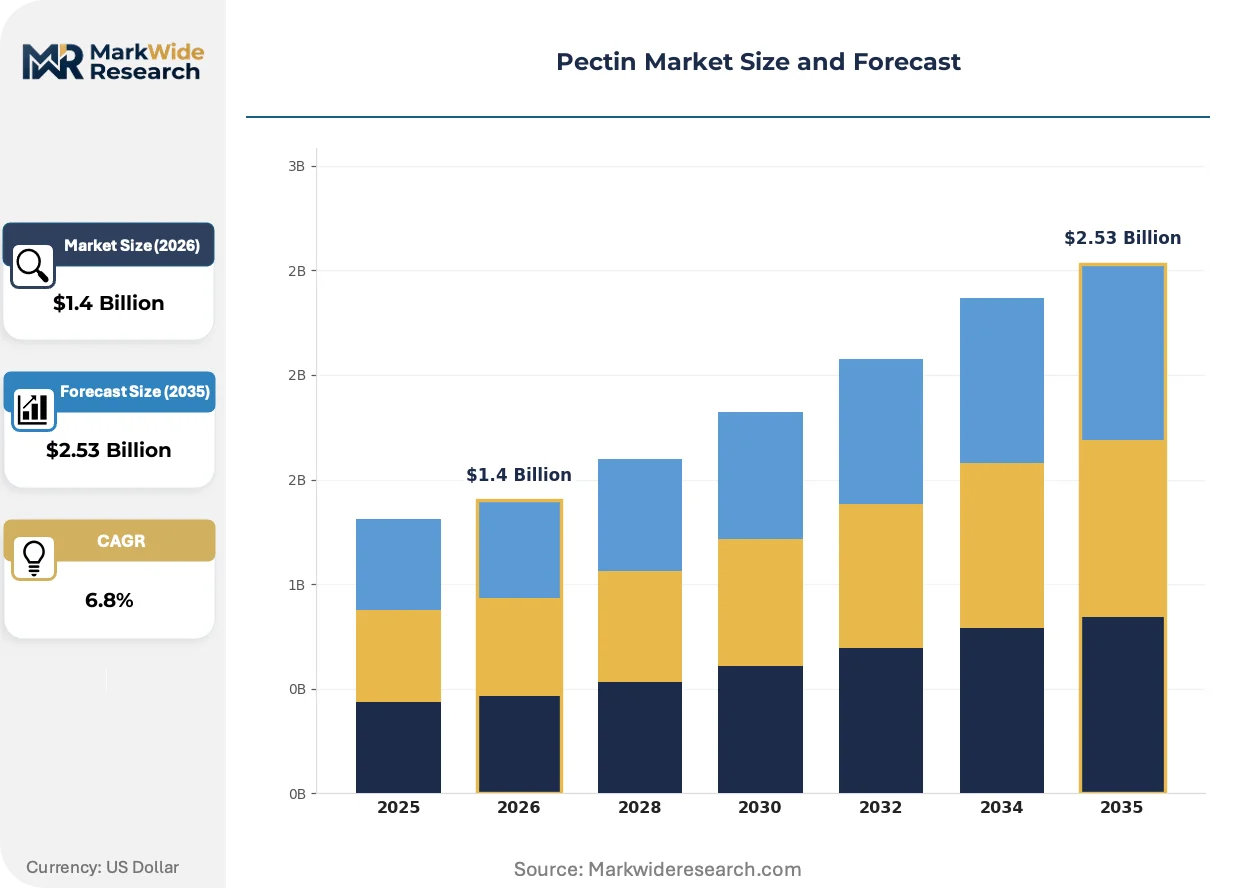
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Methoxyl Pectin, Low-Methoxyl Pectin, Amidated Pectin, Apple Pectin End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Form: Powder, Liquid, Granular, Paste Application: Jams & Jellies, Dairy Products, Confectionery, Sauces |
| Companies Covered | CP Kelco, dsm-firmenich, Cargill Incorporated, International Flavors & Fragrances, Silvateam S.p.A., Herbstreith & Fox Corporate Group, Ingredion Incorporated, CEAMSA, Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pectin Market Emerging Trajectories
Enzymatic extraction technologies and modified pectin architectures are displacing conventional acid-hydrolysis methods while regulatory chemistry restrictions accelerate process reinvestment across manufacturing bases.
Enzymatic pectin extraction using fungal polygalacturonase blends is decomposing the traditional sulfuric-acid process hierarchy in European facilities. German and Dutch processors are retrofitting production lines to meet F-Gas Regulation and REACH solvent-recovery mandates. This technology shift is compressing energy intensity and waste-stream volumes while enabling gentler extraction of high-molecular-weight fractions prized in pharmaceutical applications.
REACH authorization requirements for dichloromethane and other legacy extraction solvents are forcing capital redeployment toward aqueous and enzyme-based systems. The regulation is elevating compliance costs for smaller Mediterranean operators without integrated waste-treatment infrastructure. Spanish and Italian producers are consolidating to share effluent-processing investments, restructuring competitive positioning in regional supply.
Specification-driven procurement is fragmenting buyer-seller relationships as clean-label certifications proliferate beyond organic and non-GMO to include carbon-footprint and water-stewardship credentials. Large food manufacturers are unbundling long-term supply agreements in favor of shorter contracts with audit-rights clauses. This pattern is most pronounced in German dairy and French plant-based yogurt segments where retailer sustainability scorecards dictate ingredient sourcing.
Pectin Market Segmentation
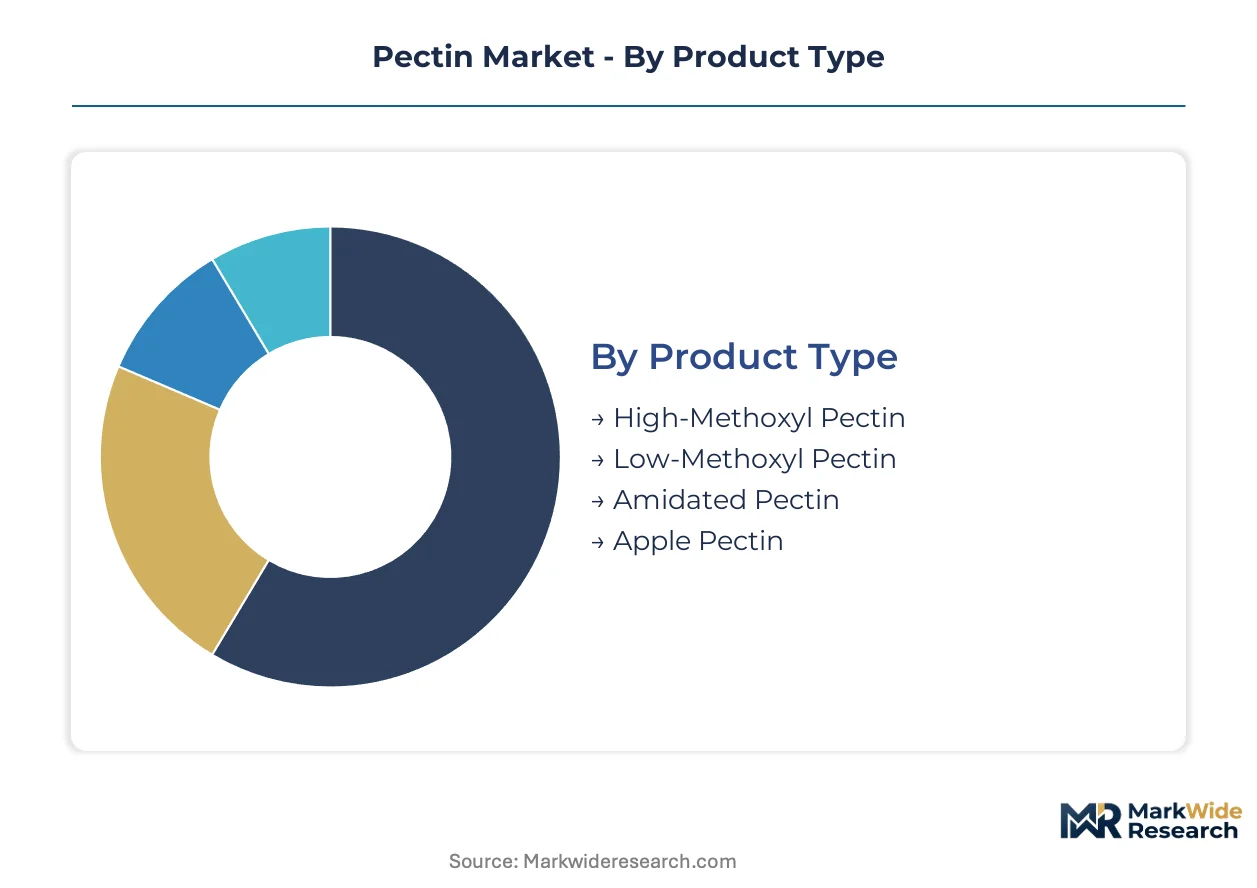
Pectin segmentation reflects divergent technical specifications and regulatory requirements across food, pharmaceutical, and industrial channels. Specification tiers determine pricing power and certification burdens, while form factors and application matrices dictate procurement patterns among end-users.
Product Type:
Domestic production of high-methoxyl and low-methoxyl grades dominates European and Brazilian supply bases, while amidated pectin flows disproportionately through export channels serving pharmaceutical formulators.
- High-Methoxyl Pectin:Traditional acid-extracted polysaccharide requiring sugar concentrations above 55% and pH below 3.5 for gelation. German and French jam manufacturers anchor demand, though sugar-dependent functionality limits penetration in reduced-calorie product lines.
- Low-Methoxyl Pectin:De-esterified variant enabling calcium-reactive gelation without high-sugar matrices. Italian and Spanish dairy processors source this grade for clean-label yogurt and plant-based alternatives, displacing gelatin amid EFSA clean-label mandates.
- Amidated Pectin:Modified amidation degree delivers controlled rheology for pharmaceutical tableting and sustained-release matrices. Swiss and German nutraceutical contract manufacturers drive premium export demand.
- Apple Pectin:Pomace-derived alternative with distinct methyl ester distribution, concentrated in Polish and Chinese production clusters for regional food applications.
High-methoxyl pectin holds the largest share; momentum sits with low-methoxyl grades as calcium-reactive formulations expand.
End Use Industry:
Cost tier stratification separates commodity food applications from pharmaceutical-grade specifications with 3-5x margin multiples.
- Food & Beverage:Volume anchor spanning jam stabilization, dairy texturization, and beverage clouding. EFSA and FDA additive purity thresholds determine which grades achieve formulation approval.
- Pharmaceuticals:USP and EP monograph compliance creates qualification barriers. Controlled-release tablet matrices and excipient applications command premium positioning in German and Swiss manufacturing.
- Cosmetics:Emulsion stabilization and film-forming properties drive demand in French and Italian skincare formulations, typically at lower specification tiers than pharmaceutical grades.
- Nutraceuticals:Gummy vitamin matrices and dietary supplement delivery systems represent the steepest expansion trajectory as gelatin substitution accelerates.
Food and beverage absorbs the highest volume; nutraceuticals are climbing the fastest as clean-label gummy formats proliferate.
Form:
Application requirements and handling economics favor powder for large-scale food manufacturing, while liquid and paste forms concentrate in specialized pharmaceutical and cosmetic compounding.
- Powder:Spray-dried standard for industrial-scale dispersion. Brazilian and Spanish citrus peel processors ship bulk powder to German and Dutch food manufacturers.
- Liquid:Pre-hydrated solutions reducing dust exposure and dissolution time. Preferred by mid-size dairy processors in Italy and France with limited blending infrastructure.
- Granular:Controlled particle size for direct-compression tableting. Swiss pharmaceutical contract manufacturers specify this grade for high-speed production lines.
- Paste:High-moisture format for artisanal jam producers and small-batch cosmetic formulators in regional European markets.
Powder commands the dominant position; liquid forms are gaining share fastest among mid-tier processors seeking operational simplification.
Application:
Customer type fragmentation separates multinational manufacturers with internal R&D capabilities from regional processors dependent on supplier technical support.
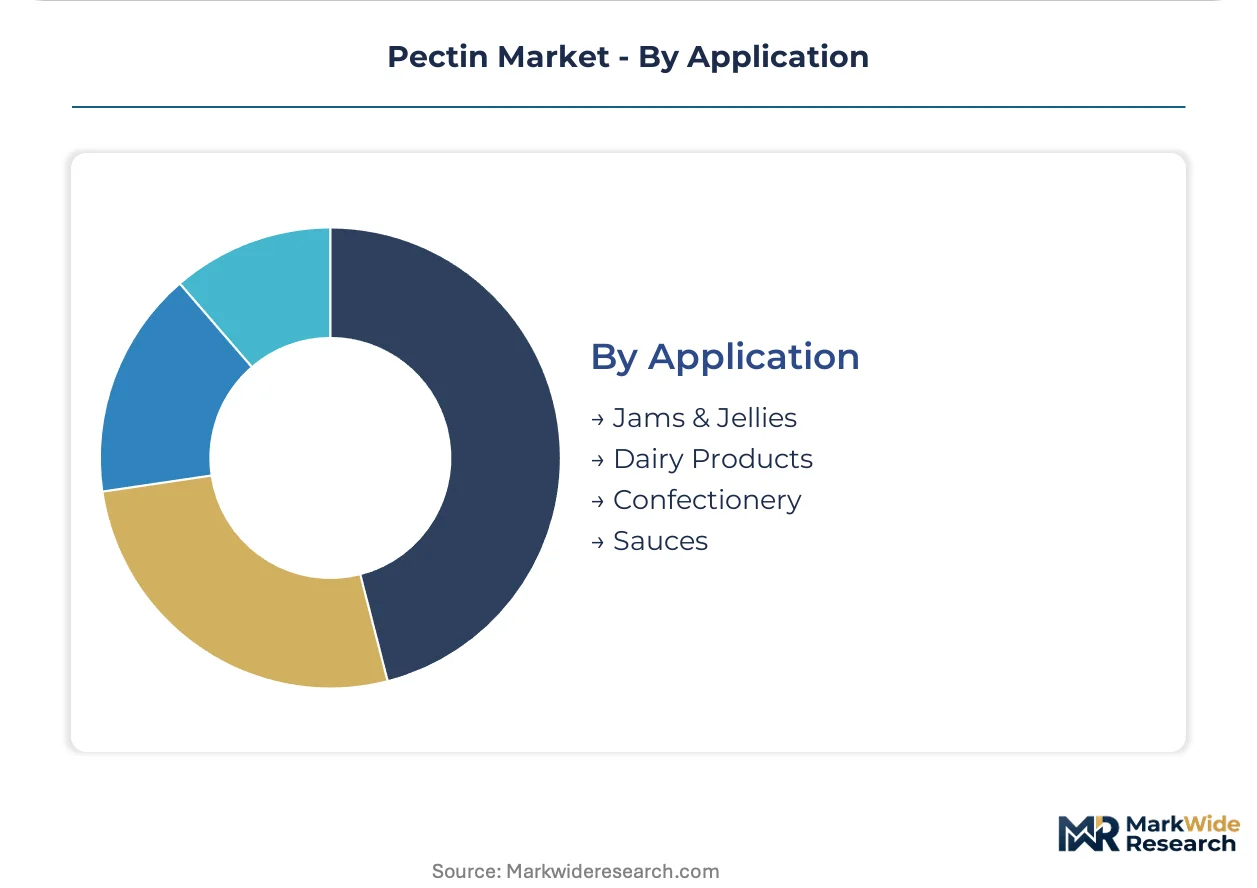
- Jams & Jellies:Heritage application where rapid-set high-methoxyl pectin dominates traditional formulations. British and German retail private-label producers maintain steady procurement.
- Dairy Products:Low-methoxyl calcium gelling enables reduced-sugar fruit preparations and plant-based yogurt textures. French and German dairy leaders specify clean-label grades.
- Confectionery:Pectin jellies compete with gelatin in premium positioning. Italian and Spanish candy manufacturers adopt pectin for vegetarian and halal product lines.
- Sauces:Viscosity modification and emulsion stabilization in condiments and dressings. Regional processors in Poland and Turkey source lower-specification grades.
Jams and jellies retain the largest volume base; dairy applications are expanding most quickly as calcium-reactive formulations displace starch and gelatin alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil and Spain face acute price volatility from citrus peel supply swings, while German and Swiss pharmaceutical formulators absorb premium amidated grades with minimal elasticity.
Germany
Dairy processors in Bavaria and Lower Saxony drive low-methoxyl pectin procurement for clean-label yogurt and plant-based alternatives. The EU Green Deal and F-Gas Regulation enforce REACH-compliant extraction standards that disqualify conventional acid-hydrolysis imports. Cologne and Hamburg host pharmaceutical contract manufacturers specifying USP-grade amidated pectin for controlled-release nutraceutical matrices.
Brazil
Orange harvest fluctuations in São Paulo state generate raw material price instability for non-integrated extractors serving global jam and confectionery markets. ANVISA alignment with Codex additive purity standards shapes export-grade specifications. The São Paulo citrus belt concentrates processing infrastructure for high-methoxyl pectin bound for European food manufacturers.
United States
FDA-enforced additive purity thresholds and clean-label mandates from major retailers compress synthetic stabilizer volumes across processed food channels. The EPA oversees extraction solvent discharge limits affecting import qualification. New Jersey and California host nutraceutical formulators driving pharmaceutical-grade pectin demand for gummy vitamin matrices.
India
FSSAI clean-label enforcement in processed dairy and traditional sweets segments opens formulation-switch opportunities from synthetic thickeners. The PLI scheme for food processing infrastructure accelerates domestic blending capacity expansion. Maharashtra and Gujarat dairy clusters source low-methoxyl grades for reduced-sugar fruit preparations.
Switzerland
Swissmedic pharmaceutical monograph requirements create 18-24 month qualification barriers that filter supplier entry into controlled-release tablet applications. The country's dual focus on precision manufacturing and sustainability credentials attracts premium pectin grades. Basel and Zurich anchor nutraceutical contract manufacturing demand for amidated pectin hydrogels.
Pectin Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated citrus peel processors commanding raw material security while specialized apple pectin producers capture regional clean-label premiums. The vendor base spans three tiers: global multinationals with hemispheric supply chains, mid-cap European specialists with integrated extraction infrastructure, and regional toll processors serving price-sensitive food manufacturers. Dominant competitive moves include backward integration into citrus orchard and processing assets, plus enzymatic extraction technology licensing to meet EU solvent-recovery mandates.
Among integrated supply-chain operators, CP Kelco and Cargill Incorporated exemplify the archetype of global reach through captive raw material access across Brazilian and Spanish citrus belts. European specialists Herbstreith & Fox Corporate Group and Silvateam S.p.A. occupy positions anchored in regional orchard networks and tannin-pectin portfolio adjacencies respectively. These named entities represent the competitive poles between scale-driven procurement power and specialized specification expertise.
| Leading Market Players |
|---|
| CP Kelco |
| dsm-firmenich |
| Cargill Incorporated |
| International Flavors & Fragrances |
| Silvateam S.p.A. |
| Herbstreith & Fox Corporate Group |
| Ingredion Incorporated |
| CEAMSA |
| Tate & Lyle PLC |
| Others |
Supply Flow & Price Mechanics
REACH authorization requirements for dichloromethane and legacy extraction solvents gate both supplier qualification and price differentiation across European pectin procurement. Certification-compliant producers command 3-5x margin multiples over conventional acid-hydrolysis operators, while non-certified imports face disqualification from German and Swiss pharmaceutical formulators.
Pricing Analysis
After-sales technical service contracts drive lifetime value for pharmaceutical-grade pectin suppliers, with formulation support and USP/EP monograph maintenance justifying premium positioning. Three-tier pricing structure across pharmaceutical, food-grade, and industrial specifications separates USP-certified amidated grades from standard low-methoxyl and commodity high-methoxyl tiers. Cost compression in high-methoxyl segments is intensifying because Brazilian citrus peel supply volatility transmits directly to spot pricing. Regional jam manufacturers in Poland and Turkey exhibit highest price sensitivity, while Swiss nutraceutical contract manufacturers absorb premium grades with minimal elasticity.
Supply Chain Analysis
Just-in-time procurement dominates pharmaceutical formulators in Germany and Switzerland, while strategic stockpiling characterizes Brazilian citrus processors hedging against harvest volatility. Supply concentrates in Brazil, Spain, and Poland, with São Paulo orange belt infrastructure and Mediterranean lemon processing anchoring global high-methoxyl output. Raw material dependencies center on citrus peel, apple pomace, and specialized enzyme blends for extraction. Single-source vulnerability runs through Brazilian orange harvest fluctuations, which transmit price instability to non-integrated extractors. Distribution runs through integrated multinational supply chains for pharmaceutical grades, with regional toll processors serving price-sensitive food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label certification proliferation fragments procurement relationships, creating white-space opportunities for specialized suppliers capable of bridging food-grade and pharmaceutical specification tiers.
For Market Incumbents: Shield market position by deepening captive citrus peel supply through Brazilian orchard partnerships and Spanish lemon processing assets. Invest in enzymatic extraction retrofitting to meet F-Gas Regulation solvent-recovery mandates, disqualifying smaller Mediterranean competitors lacking integrated waste-treatment infrastructure. For New Entrants and Emerging Players: USP monograph fast-track programs open qualification pathways into pharmaceutical tableting and controlled-release nutraceutical matrices. Target Indian dairy processors in Maharashtra and Gujarat adopting low-methoxyl grades for FSSAI-compliant reduced-sugar fruit preparations. Lead with direct-to-manufacturer digital procurement platforms disintermediating traditional distributor channels. For Investors and Strategic Acquirers: EU Green Deal solvent standards reshape the acquisition landscape toward integrated extraction operators with REACH-compliant infrastructure. Five-to-ten year viability favors backward-integrated specialists with captive raw material access across hemispheres. Signal to watch: consolidation announcements among Spanish and Italian producers sharing effluent-processing investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Orchards | Captive supply from São Paulo orange belt secures raw material access against harvest volatility. |
| Enzymatic Extraction Technology Licensing | Fungal polygalacturonase retrofitting meets F-Gas Regulation mandates while reducing energy intensity. |
| Pharmaceutical Monograph Certification | USP and EP compliance opens controlled-release nutraceutical applications with premium margin structures. |
| Direct-to-Manufacturer Digital Procurement | B2B platform adoption by mid-size food processors disintermediates traditional distributor channels. |
| Regional Toll Processor Consolidation | Shared effluent-processing investments among Mediterranean operators restructure competitive positioning. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Interviews spanned extraction plant managers at Brazilian and Spanish citrus processors, procurement leads at German dairy manufacturers, regulatory affairs specialists navigating REACH compliance, and technical R&D directors at pharmaceutical contract manufacturers. Secondary sources included customs and trade flow data, EFSA and FDA additive purity filings, EU Green Deal implementation documents, and SEC disclosures from publicly traded ingredient suppliers. Bottom-up volume modeling triangulated against top-down market sizing across grade tiers and application segments.
Across the projection horizon, the analytical framework modeled pectin demand through five segmentation dimensions: product type (high-methoxyl, low-methoxyl, amidated, apple-derived), end-use industry (food and beverage, pharmaceutical, nutraceutical, cosmetic), form factor (powder, liquid, granular, paste), application matrix (jams, dairy, confectionery, tableting), and regional regulatory cluster. CAGRs were derived from weighted average growth across these dimensions, with specific inputs including citrus peel supply forecasts, clean-label adoption curves in processed dairy, and pharmaceutical monograph qualification timelines.
Underlying assumptions cover continued EFSA and FDA clean-label enforcement, Brazilian citrus harvest stability, and enzymatic extraction technology diffusion rates, with deviation risk concentrated in EU solvent regulation acceleration and gelatin substitution economics in price-sensitive confectionery. Revision becomes warranted when Brazilian orange harvest volatility crosses thresholds triggering raw material price spikes or when pharmaceutical monograph certification timelines compress below current 18-24 month baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Anti-Wear Additives Market
Additives
Global Formulation Additives Market
Additives
Global Flame Retardant Masterbatches Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Global Chelated Trace Minerals Market
Additives
Global Rheology Modification Coating Additives Market
Additives
Polymeric Plasticizer Market
Additives
Feed Additives Market
Additives
Tackifier Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Global Anti-Fog Additives Market
Additives
India Feed Additives Market
Additives
Tris Nonylphenyl Phosphite Market
Additives
Allura Red AC Market
Additives
Iso-Butyric Acid Market
Additives
Global Scale Inhibitors Market