
 Extrusion Aids Market | 2026-2036
Extrusion Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Extrusion Aids Market Analytics
Modular additive packages is broadening buyer choice in the extrusion aids market, allowing compounders to tailor lubricant-surfactant ratios to specific resin systems rather than accepting one-size-fits-all formulations. Dow leverages its integrated silicone and fluoropolymer portfolios to anchor North American supply relationships with major polyethylene producers. Daikin Industries competes through deep specialization in fluorinated processing aids, sustaining technical leadership in high-melt-strength polymer applications where surface defects are costly.
Extrusion aids are functional additives, typically comprising fluoropolymers, metallic stearates, or silicone compounds at loadings of 100–2000 ppm, that reduce melt fracture and die buildup during continuous polymer extrusion. Their primary industrial purpose is to stabilize flow regimes in high-shear processing equipment, thereby improving yield rates and surface aesthetics in film, pipe, and profile manufacturing. The lubricants category dominates current volume as processors prioritize energy reduction in twin-screw and single-screw extrusion lines, while masterbatch forms are gaining fastest as compounders seek dust-free handling and precise dosing control in automated feeding systems.
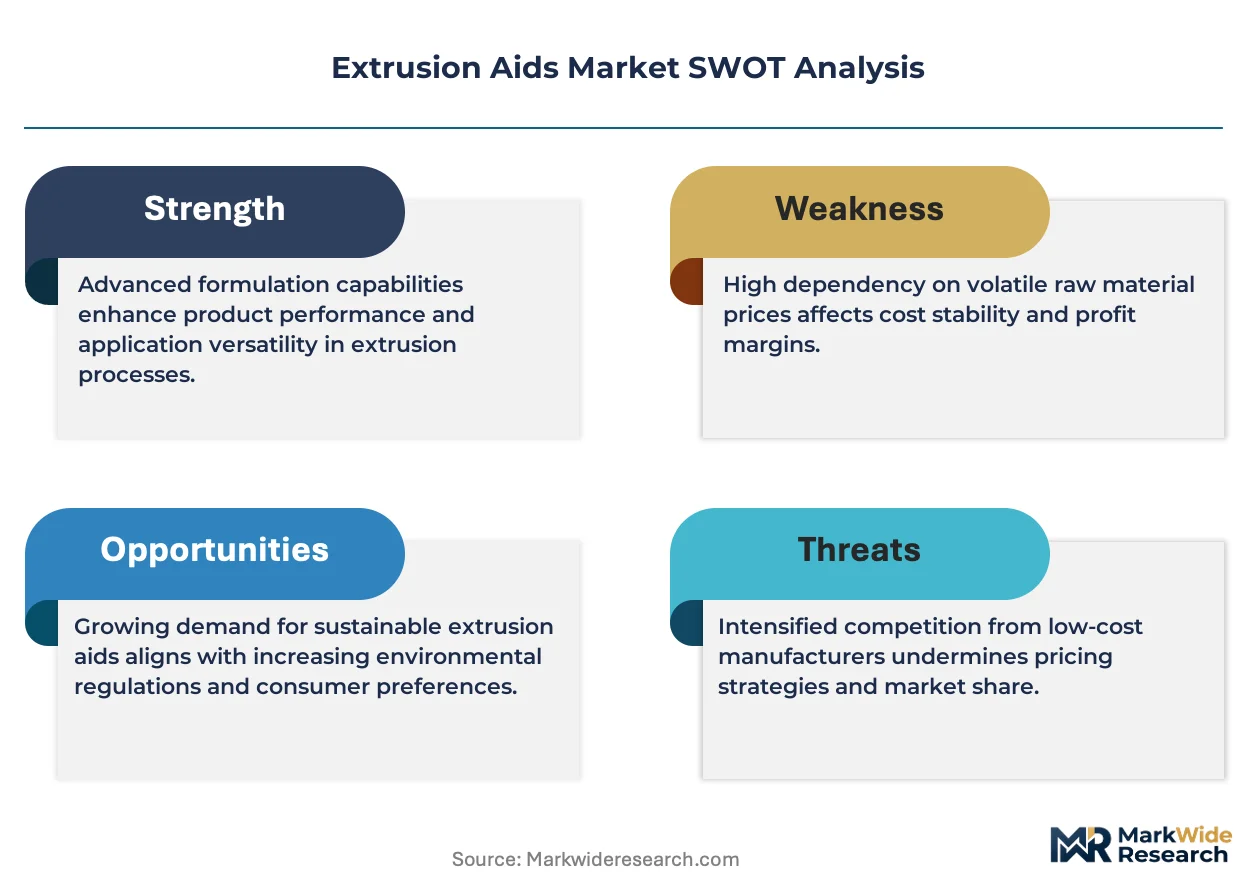
The EPA regulates fluoropolymer processing aids under TSCA Section 5 premanufacture notification requirements, while REACH restricts certain long-chain perfluorinated substances in European compounding operations, forcing reformulation toward shorter-chain fluorotelomer-based alternatives. FDA food-contact regulations under 21 CFR 177.1520 additionally constrain lubricant selections for packaging film destined for direct food contact, creating a dual-track compliance burden for multinational suppliers. Stakeholders must monitor pending PFAS restrictions across multiple jurisdictions while evaluating bio-based processing aid candidates that can match the shear-stability performance of incumbent fluorinated chemistries.
Market Dynamics
Polymer processors face mounting pressure to eliminate PFAS-containing formulations as REACH restrictions tighten across European compounding operations and EPA premanufacture notifications delay new fluoropolymer introductions in the United States. This regulatory compression is forcing rapid migration toward shorter-chain fluorotelomer and bio-based alternatives without sacrificing shear-stability performance.
Growth Catalysts
- Automotive surface-finish mandates:German premium OEM supply chains are expanding fluoropolymer-based processing aid specifications to eliminate melt fracture in exterior trim extrusion.
- REACH Article 57 authorization:European compounders must reformulate long-chain perfluorinated substances by 2025, creating immediate replacement demand for compliant lubricant packages.
- Masterbatch automation:Dust-free handling systems in twin-screw extrusion lines are accelerating adoption of concentrated additive forms over loose powder dosing.
Market Restraints
- Fluorotelomer feedstock concentration:Three Asian chemical conglomerates control 70% of global C6 fluorotelomer alcohol supply, exposing compounders to single-source vulnerability.
- Bio-based performance gap:Plant-derived processing aids from agricultural feedstocks fail to match fluoropolymer shear stability above 500 s-1 strain rates in high-output pipe extrusion.
- TSCA Section 5 backlog:EPA premanufacture notification review timelines now exceed 270 days for novel fluorinated chemistries, freezing innovation pipelines for North American suppliers.
Strategic Opportunities
- India packaging film expansion:FSSAI food-contact approvals for polyethylene extrusion aids are unlocking demand from Mumbai-Ahmedabad flexible packaging clusters serving export markets.
- Silicone-fluoropolymer hybrid convergence:Dow's integrated portfolio demonstrates loadings below 500 ppm can achieve comparable die buildup reduction, opening formulation space for cost-optimized tiers.
- EU Green Deal procurement incentives:Public tenders for infrastructure pipe now weight carbon footprint scores, favoring bio-based processing aid suppliers with verified lifecycle data.
Industry Challenges
- PFAS analytical detection gaps:Compounders lack standardized test methods for total organic fluorine below 50 ppm, complicating compliance documentation for downstream automotive customers.
- Legacy extruder retrofit costs:Automated masterbatch feeding systems require screw geometry modifications costing $150,000-$400,000 per line, delaying adoption at mid-volume processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extrusion Aids Market |
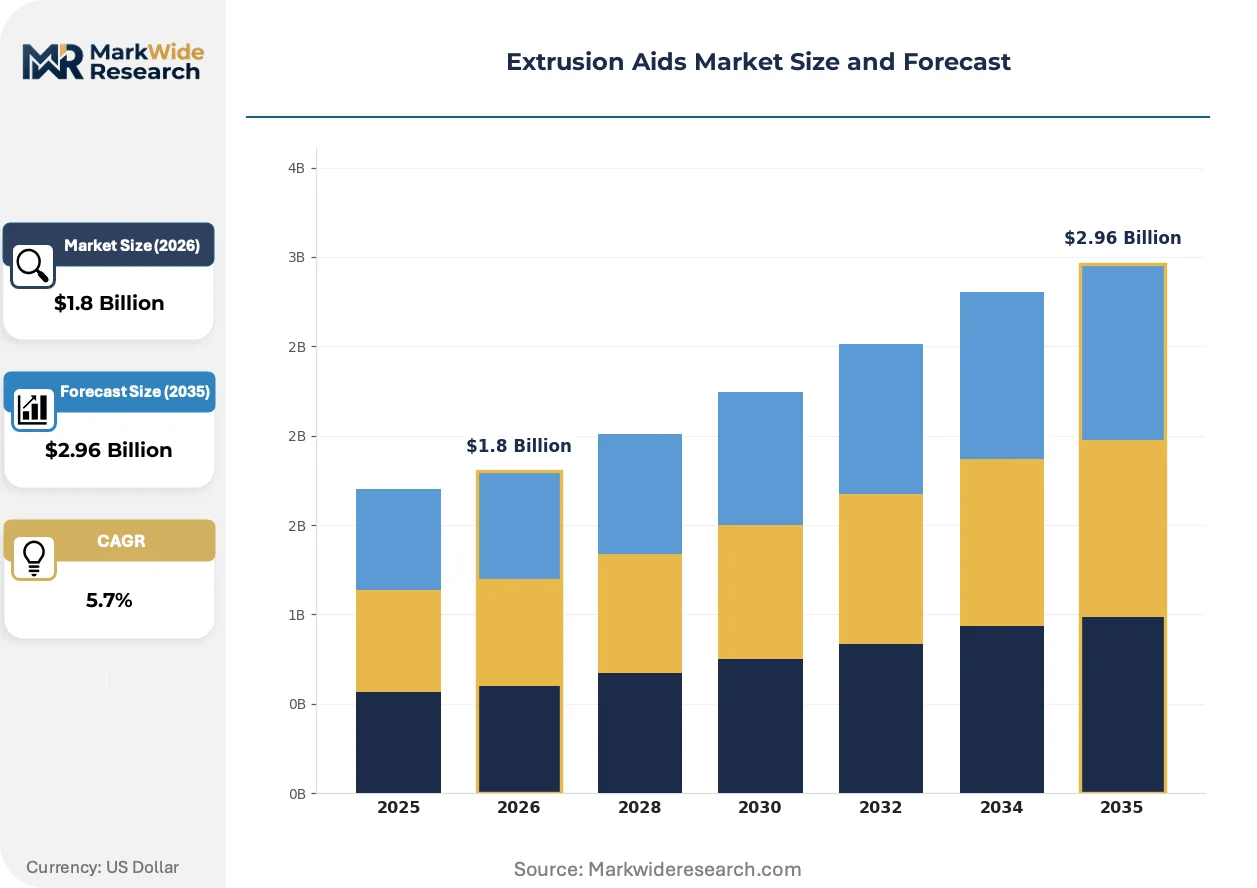
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Food, Packaging, Automotive, Construction Type: Lubricants, Surfactants, Processing Aids, Others Form: Granules, Powder, Liquid, Masterbatch End User: Manufacturers, OEMs, Industrial Users, Research Facilities |
| Companies Covered | Arkema, Dow, Daikin Industries, Clariant, The Chemours Company, 3M Company, Syensqo, Evonik Industries, Ampacet Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extrusion Aids Market Evolving Landscape
Formulation science is pivoting from single-molecule fluoropolymer dominance toward engineered additive packages that combine lubricant, surfactant, and processing aid functions in single masterbatch pellets. This convergence is compressing supplier margins while raising technical barriers to entry.
Hybrid silicone-fluoropolymer processing aids are consolidating technical validation across high-melt-strength polymer applications. Automotive exterior trim compounders in Germany and the United States are adopting these systems at pilot scale. The technology is consolidating supplier relationships around integrated chemical portfolios capable of co-optimizing resin compatibility and surface aesthetics.
REACH restrictions on long-chain perfluorinated substances are forcing immediate formulation pivots in European compounding operations. The industrial consequence is a scramble for C6 fluorotelomer alternatives that maintain die lubrication efficiency. Packaging film destined for direct food contact faces the steepest compliance burden, with compounders accelerating FDA 21 CFR 177.1520 parallel submissions to preserve transatlantic supply continuity.
Buyer concentration among German automotive OEMs is compressing supplier negotiation cycles from annual to quarterly frameworks. Tier-1 compounders now demand real-time carbon footprint data and PFAS-free certifications as standard bid prerequisites. This pattern is most visible in the Stuttgart-Munich corridor, where BMW, Mercedes-Benz, and Audi procurement teams coordinate additive specifications across shared supply bases.
Extrusion Aids Market Segmentation
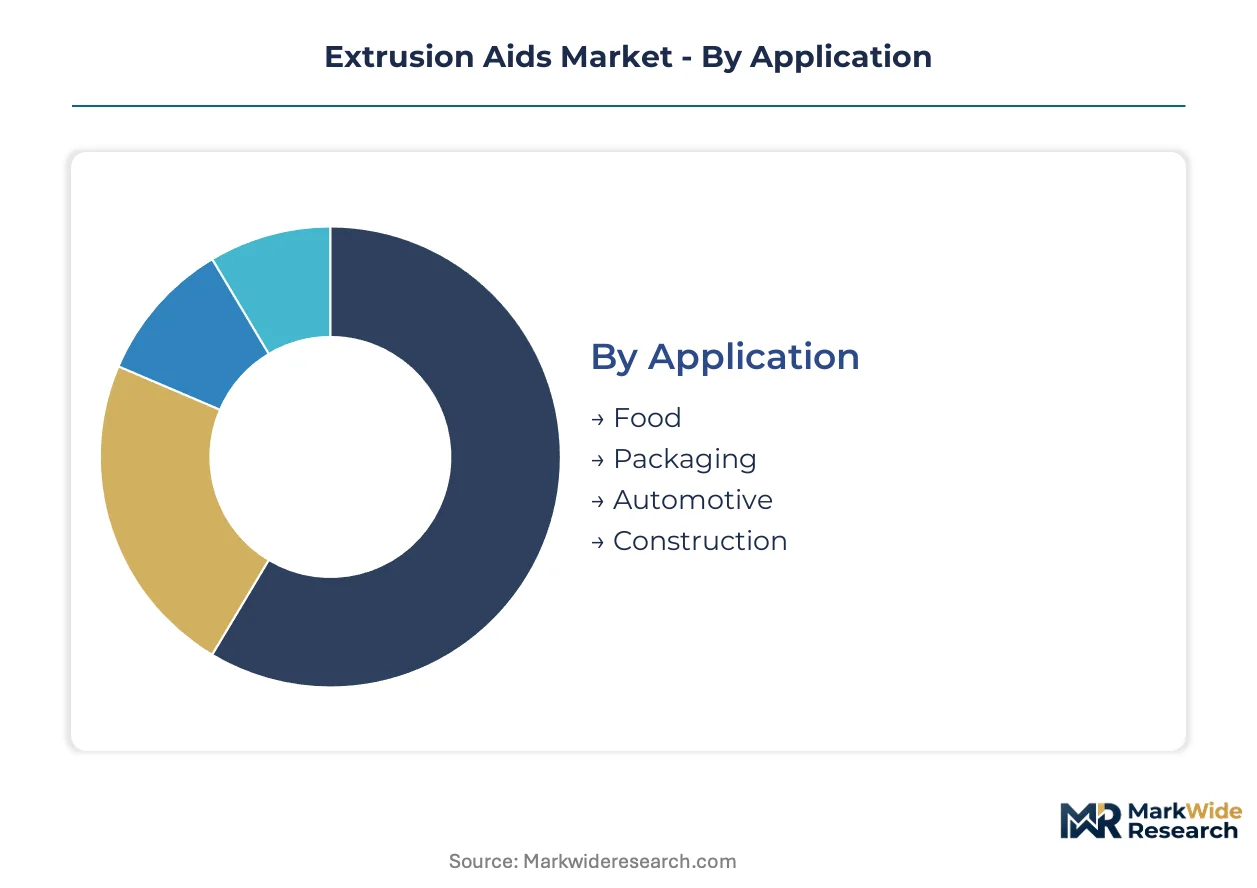
Extrusion aid procurement decisions hinge on processing equipment compatibility, regulatory exposure, and dosing precision requirements. Compounders evaluate segments against resin system constraints and automation readiness rather than treating categories as interchangeable commodity buckets.
Application:
Automotive OEMs and packaging film producers drive specification intensity, with surface-finish mandates and food-contact compliance creating divergent performance thresholds.
- Automotive:Exterior trim extrusion demands fluoropolymer-based systems that eliminate melt fracture at high shear rates. German premium OEM supply chains in Stuttgart and Munich enforce quarterly specification reviews with real-time carbon footprint disclosure requirements.
- Packaging:Flexible film manufacturers prioritize FDA 21 CFR 177.1520 compliance for direct food contact applications. Mumbai-Ahmedabad clusters are expanding masterbatch adoption to serve export markets with dust-free handling requirements.
- Food:Processing equipment sanitation drives lubricant selection toward bio-based alternatives with verified lifecycle data.
- Construction:Infrastructure pipe extrusion favors cost-optimized lubricant packages where EU Green Deal procurement incentives weight carbon scores.
Volume sits with Packaging; growth tilts toward Automotive as surface-finish specifications tighten across German OEM supply chains.
Type:
Formulation chemistry determines shear-stability performance and regulatory exposure, with processors balancing fluoropolymer efficiency against PFAS compliance costs.
- Lubricants:Metallic stearates and silicone compounds dominate current volume as processors prioritize energy reduction in twin-screw and single-screw extrusion lines. REACH Article 57 authorization deadlines are forcing rapid migration toward shorter-chain fluorotelomer alternatives.
- Processing Aids:Fluoropolymer-based systems at 100-2000 ppm loadings stabilize flow regimes in high-shear equipment. EPA TSCA Section 5 premanufacture notification timelines exceeding 270 days are freezing innovation pipelines for novel fluorinated chemistries.
- Surfactants:Die buildup reduction at lower loadings is expanding hybrid silicone-fluoropolymer validation.
- Others:Bio-based candidates from agricultural feedstocks remain performance-limited above 500 s-1 strain rates.
Commercial concentration favors Lubricants; technical validation is expanding most quickly for Processing Aids as automotive specifications intensify.
Form:
Handling economics and dosing precision separate procurement tiers, with automation readiness dictating form selection across processor scale categories.
- Masterbatch:Concentrated additive pellets enable dust-free handling and precise dosing control in automated feeding systems. Twin-screw extrusion lines in high-volume operations are retrofitting screw geometry at $150,000-$400,000 per line to accommodate masterbatch automation.
- Powder:Loose dosing persists at mid-volume processors where retrofit costs delay capital deployment. Surface defect risks from inconsistent dispersion limit adoption in automotive exterior trim applications.
- Granules:Intermediate handling characteristics serve compounders with semi-automated feeding systems.
- Liquid:Metering pump compatibility favors continuous extrusion lines with existing liquid additive infrastructure.
Adoption velocity is steepest for Masterbatch; Powder retains installed base share where automation investment lags.
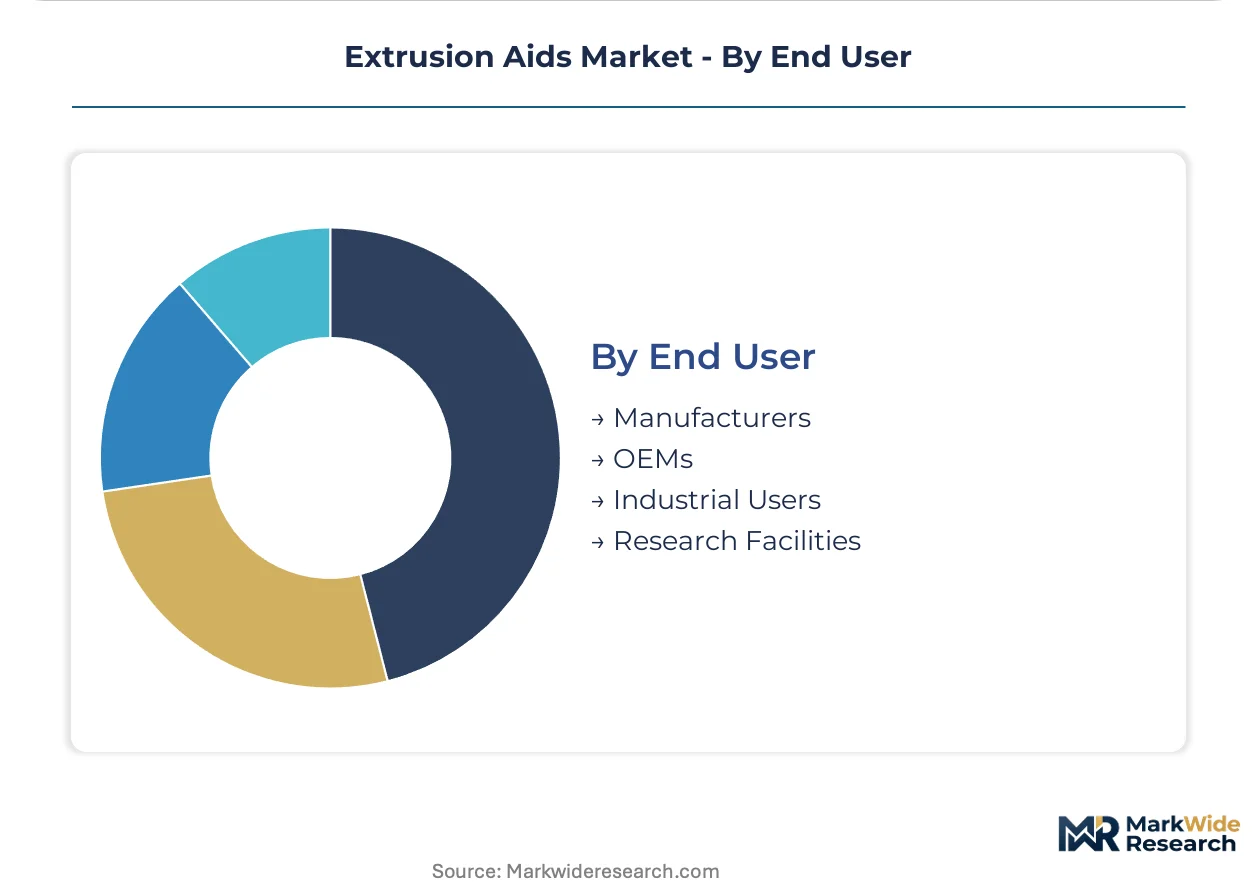
End User:
Procurement sophistication varies sharply by scale and vertical integration depth, with specification authority concentrated among automotive OEMs.
- OEMs:BMW, Mercedes-Benz, and Audi procurement teams in the Stuttgart-Munich corridor coordinate additive specifications across shared supply bases. Quarterly negotiation frameworks now demand PFAS-free certifications and real-time carbon footprint data as standard bid prerequisites.
- Manufacturers:Polymer processors serving multiple end-use markets balance formulation flexibility against inventory complexity. Modular additive packages allow lubricant-surfactant ratio tailoring to specific resin systems.
- Industrial Users:Mid-volume processors face legacy extruder retrofit cost barriers to masterbatch automation.
- Research Facilities:Pilot-scale validation of hybrid silicone-fluoropolymer systems supports supplier technical relationships.
Specification authority concentrates with OEMs; formulation flexibility requirements expand most quickly among Manufacturers serving diversified end-use portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and the United States while consumption expands across automotive corridors in Stuttgart and packaging clusters in Mumbai. Supply chains route fluorotelomer feedstocks through Asian chemical conglomerates before compounding in European and North American facilities. Regulatory divergence between REACH and EPA timelines is fragmenting formulation standards across borders.
Germany
Automotive exterior trim specifications from BMW, Mercedes-Benz, and Audi procurement teams drive fluoropolymer processing aid demand. ECHA REACH Article 57 authorization deadlines force compounders toward C6 fluorotelomer alternatives by 2025. Stuttgart-Munich corridor compounders coordinate quarterly specification reviews with real-time carbon footprint disclosure requirements.
United States
Polyethylene producers anchor North American supply relationships through integrated silicone and fluoropolymer portfolios. EPA TSCA Section 5 premanufacture notification timelines exceeding 270 days freeze innovation pipelines for novel fluorinated chemistries. Gulf Coast petrochemical corridors process masterbatch forms for automated twin-screw extrusion lines.
India
Flexible packaging film manufacturers expand masterbatch adoption to serve export markets with dust-free handling requirements. FSSAI food-contact approvals for polyethylene extrusion aids unlock demand from Mumbai-Ahmedabad clusters. Domestic compounders retrofit semi-automated feeding systems to accommodate concentrated additive pellets.
China
Three chemical conglomerates control 70% of global C6 fluorotelomer alcohol supply, exposing downstream compounders to single-source vulnerability. MIIT standards for polymer processing equipment shape lubricant selection criteria. Yangtze River Delta packaging film producers balance cost-optimized lubricant packages against EU export compliance burdens.
Japan
High-melt-strength polymer applications sustain technical validation of hybrid silicone-fluoropolymer systems at pilot scale. METI industrial standards influence processing aid performance benchmarks for automotive supply chains. Kansai region compounders serve tier-1 suppliers to domestic automotive OEMs with precision dosing control systems.
Extrusion Aids Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. Market structure consolidates around integrated chemical portfolios capable of co-optimizing resin compatibility and surface aesthetics. Three strategic archetypes dominate: diversified material science conglomerates with cross-polymer additive portfolios, fluorochemical pure-plays with deep specialization in high-shear applications, and regional compounders serving localized automotive supply chains. Competitive moves center on hybrid technology licensing and backward integration into fluorotelomer feedstocks.
Among diversified conglomerates, Dow and Arkema occupy positions anchoring North American and European supply relationships respectively. Daikin Industries exemplifies the fluorochemical pure-play archetype with concentrated expertise in fluorinated processing aids. These three entities represent the spectrum from integrated portfolio breadth to technical specialization depth, with each archetype competing through distinct value propositions around formulation flexibility, shear-stability performance, or geographic proximity to premium automotive OEM procurement teams.
| Leading Market Players |
|---|
| Arkema |
| Dow |
| Daikin Industries |
| Clariant |
| The Chemours Company |
| 3M Company |
| Syensqo |
| Evonik Industries |
| Ampacet Corporation |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap compounders in Germany and Japan anchor premium-tier pricing discipline through captive relationships with automotive OEM procurement teams, while private-equity-rolled-up lubricant specialists in North America compete on volume scale against integrated conglomerate portfolios. This ownership fragmentation creates divergent supply behaviors: family firms prioritize long-term contract stability over spot-market flexibility, while rolled-up platforms extract working-capital efficiencies that compress distributor margins.
Pricing Analysis
Cost-down pressure on standard-grade lubricant tiers accelerates because REACH Article 57 authorization deadlines force compounders to absorb reformulation expenses without passing full costs to automotive OEMs locked in quarterly pricing frameworks. Three-tier pricing structure across premium fluoropolymer, standard silicone-fluoropolymer hybrid, and economy metallic stearate levels separates formulation tiers by shear-stability certification and carbon-footprint verification. Price differentiation hinges on FDA 21 CFR 177.1520 food-contact approval tier and volume-scale commitment, with packaging film processors in India exhibiting highest price sensitivity against German automotive OEMs least willing to switch suppliers over single-digit percentage moves.
Supply Chain Analysis
Single-source vulnerability sits with Chinese chemical conglomerates controlling C6 fluorotelomer alcohol feedstocks, exposing European and North American compounders to supply interruption risks absent qualified secondary sources. Manufacturing concentrates in Germany, the United States, and Japan, with compounding operations drawing from Asian fluorotelomer intermediates and domestic silicone resin supplies. Tariff exposure on fluorinated chemistries compounds logistics chokepoint risks through Rotterdam and Shanghai port congestion. Distribution runs through integrated chemical distributors serving automotive corridors and direct mill relationships with polyethylene producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Article 57 authorization functions as a cost-of-compliance moat, elevating capital requirements for formulation pivots and freezing out undercapitalized competitors unable to fund parallel FDA submission tracks.
For Market Incumbents: Hedge regulatory fragmentation by securing dual-registered C6 fluorotelomer supply agreements with at least two Asian feedstock suppliers, insulating against single-source concentration. Accelerate backward integration into silicone-fluoropolymer hybrid R&D to displace pure fluoropolymer dependence as PFAS restrictions tighten across European compounding operations.
For New Entrants and Emerging Players: Capture FSSAI-approved masterbatch demand from Mumbai-Ahmedabad packaging clusters where dust-free handling requirements outpace local compounder capacity. Penetrate through bio-based processing aid validation partnerships with EU Green Deal-weighted infrastructure pipe tenders, leveraging carbon-footprint scoring as differentiated entry wedge.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European compounders with REACH-registered C6 portfolios and established BMW-Mercedes-Audi supply relationships in the Stuttgart-Munich corridor. Monitor EPA TSCA Section 5 premanufacture notification approval velocity as inflection signal: backlog clearance below 180 days would unlock innovation pipelines and re-rate fluorinated chemistry valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorotelomer Feedstocks | Reduces single-source exposure to Chinese chemical conglomerates controlling 70% of global C6 supply. |
| Hybrid Silicone-Fluoropolymer R&D Investment | Dow's integrated portfolio demonstrates sub-500 ppm loadings matching pure fluoropolymer die buildup reduction. |
| REACH-Compliant C6 Formulation Registration | Article 57 authorization deadlines force immediate replacement demand for long-chain perfluorinated alternatives. |
| Masterbatch Automation Retrofit Partnerships | Twin-screw extrusion lines require $150,000-$400,000 screw geometry modifications per line. |
| FSSAI Food-Contact Approval Acceleration | Unlocks polyethylene extrusion aid demand from Mumbai-Ahmedabad flexible packaging export clusters. |
Research Methodology
Document review covered ECHA substance registration databases, EPA TSCA premanufacture notification filings, and FDA 21 CFR food-contact additive petitions, complemented by interviews with polymer processing plant managers, automotive Tier 1 procurement leads, and specialty chemical distribution channel partners. Secondary validation drew from customs trade data, ACC and Cefic industry reports, and SEC 10-K disclosures from diversified material science conglomerates. Bottom-up volume estimates from resin processor consumption surveys triangulated against top-down fluorotelomer feedstock production data.
Segment-level outputs across the analysis window reflect modeled interactions between application intensity, formulation chemistry regulatory exposure, and form factor automation readiness. The analytical framework projected lubricant, processing aid, surfactant, and bio-based alternative trajectories against automotive surface-finish specification tightening and packaging film food-contact compliance expansion. CAGRs derived from elasticity-adjusted demand curves incorporating fluorotelomer feedstock price volatility and masterbatch adoption S-curve penetration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pending PFAS restriction scope expansions beyond current C6 fluorotelomer boundaries and bio-based processing aid shear-stability breakthrough viability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Additives for Metalworking Fluids Market
Additives
Ascorbyl Stearate Market
Additives
Global Sodium Acetate Market
Additives
Inhibited Propylene Glycol Market
Additives
Saudi Arabia Feed Additives Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Shortstop Inhibitor Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Iso-Butyric Acid Market
Additives
Calcium Tartrate Market
Additives
Global Synthetic Tackifier Market
Additives
Agrochemicals Additives Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Global Asphalt Additives Market
Additives
Chelated Selenium Market
Additives
1,4 Butanediol Derivatives Market