
 Powder Induction and Dispersion Systems Market | 2026-2036
Powder Induction and Dispersion Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Powder Induction and Dispersion Systems Market Outlook
Pharmaceutical-grade containment specifications is unwinding legacy equipment replacement cycles across process industries. Admix Inc. leverages its inline induction expertise to serve dairy and beverage processors requiring hygienic powder incorporation. Silverson Machines Inc. anchors high-shear mixer supply to coatings and adhesives formulators in North America and Europe. Ystral GmbH dominates specialized dispersion systems for battery slurry and pharmaceutical applications from its German manufacturing base.
Powder induction and dispersion systems are engineered equipment that use vacuum-assisted powder feeding, high-shear rotor-stator assemblies, or pneumatic conveying to incorporate dry solids into liquid phases without dusting or lump formation, typically operating at tip speeds exceeding 3,000 rpm for fine emulsion and suspension production. These systems serve primary industrial purposes in achieving homogeneous particle distribution, minimizing air entrainment, and enabling continuous processing that reduces batch cycle times in high-volume manufacturing. Batch systems still occupy the largest installed base across food and beverage applications where recipe flexibility dominates, while continuous systems are recording the fastest expansion in chemical and plastics processing driven by throughput efficiency targets. Inline systems concentrate margin pools in pharmaceutical and nutraceutical end uses where containment validation and clean-in-place protocols command premium pricing over standard hygienic configurations.
FDA cGMP guidelines and EMA's Annex 1 sterile manufacturing requirements shape equipment validation protocols, forcing suppliers to document powder containment integrity and surface finish compliance for pharmaceutical market access. REACH chemical safety obligations in Europe and OSHA combustible dust standards in the United States further constrain material selection and explosion protection design in chemical processing deployments. Stakeholders must monitor evolving battery materials processing standards and biologics manufacturing guidelines to anticipate which dispersion technologies will capture next-wave capital expenditure in cell therapy and solid-state battery production.
Market Dynamics
Pharmaceutical containment mandates under FDA cGMP and EMA Annex 1 are compressing equipment replacement cycles, forcing process manufacturers to retire legacy mixing infrastructure before end-of-life.
Growth Catalysts
- EMA Annex 1 sterile manufacturing updates:Powder containment validation requirements are accelerating capital deployment in European pharmaceutical facilities.
- Battery slurry processing:Solid-state electrolyte dispersion demands are pulling high-shear inline systems into gigafactory production lines.
- Rotor-stator tip speed advancement:Exceeding 5,000 rpm in pharmaceutical-grade configurations is opening fine emulsion applications previously served by homogenizers.
Market Restraints
- Stainless steel 316L supply concentration:German and Italian specialty steel mills control pharmaceutical-grade surface finish material availability.
- Clean-in-place protocol complexity:FDA validation documentation for containment integrity extends equipment qualification timelines.
- Mechanical seal maintenance costs:High-shear rotor-stator assemblies require quarterly replacement in abrasive battery material processing.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO compliance pathways for imported dispersion equipment remain underdeveloped relative to formulation demand.
- Cell therapy media preparation:Aseptic powder induction for bioreactor feeding represents unserved demand in regenerative medicine manufacturing.
- ISO 14644-1 cleanroom integration:Pre-validated skid-mounted systems reduce facility engineering costs for greenfield biologics sites.
Industry Challenges
- ATEX certification timelines:Explosion protection validation for combustible dust applications delays chemical industry deployments.
- Legacy DCS integration:Batch control system compatibility gaps complicate continuous system retrofits in established food processing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powder Induction and Dispersion Systems Market |
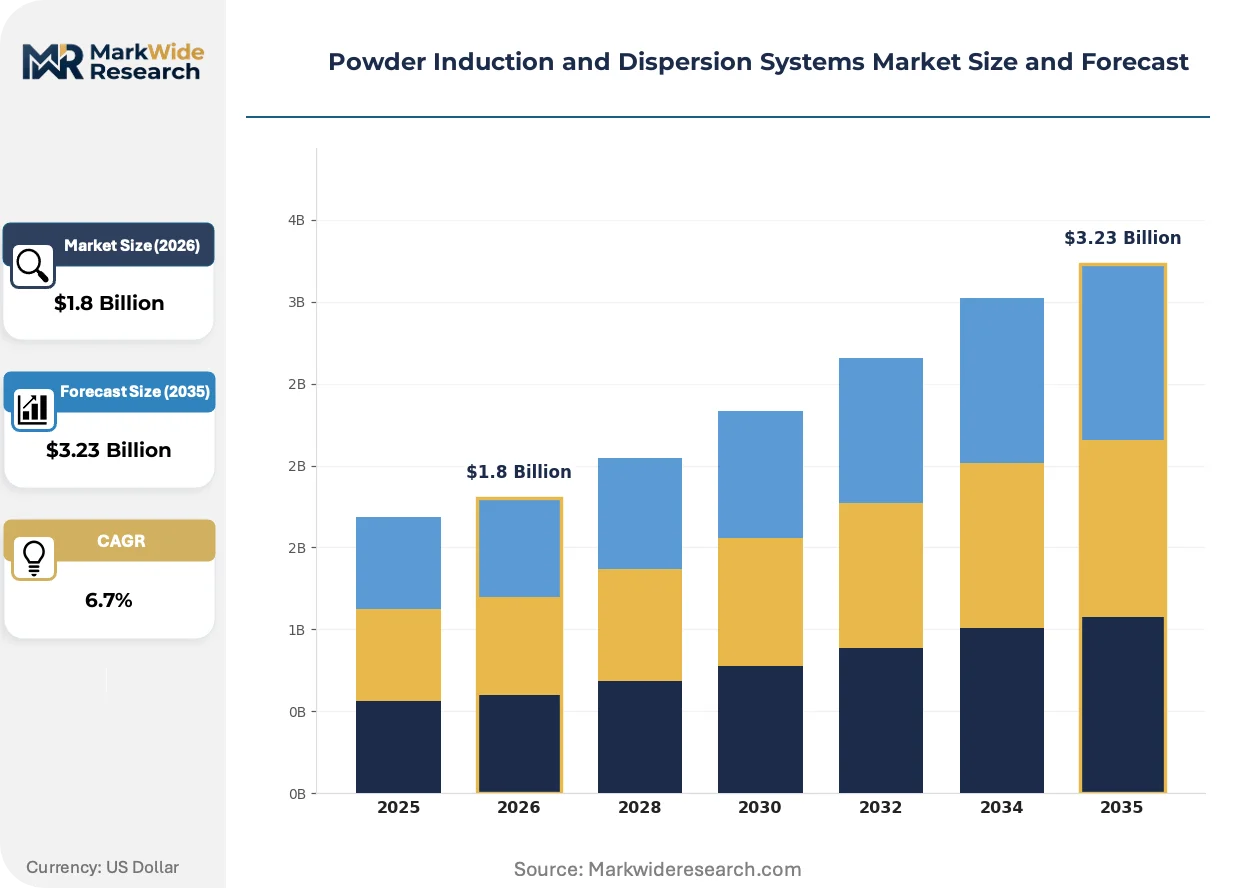
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Systems, Continuous Systems, Portable Systems, Inline Systems End User: Food & Beverage, Pharmaceuticals, Chemicals, Cosmetics Technology: Mechanical Dispersion, Pneumatic Conveying, Magnetic Induction, Ultrasonic Mixing Application: Coatings, Adhesives, Nutraceuticals, Plastics |
| Companies Covered | Admix Inc., Silverson Machines Inc., Ystral GmbH, SPX Flow, IKA Werke GmbH, IDEX Corporation, Charles Ross & Son Co., John Bean Technologies Ltd., Hayward Gordon Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powder Induction and Dispersion Systems Market Strategic Shifts
Equipment architecture is pivoting from standalone batch units to modular continuous skids, driven by throughput efficiency targets in chemical processing and aseptic manufacturing constraints in biologics.
Vacuum-assisted powder feeding technology is fragmenting the traditional high-shear mixer category. Inline induction systems eliminate dusting and lump formation in dairy protein hydration. Pharmaceutical manufacturers in Germany and Switzerland are specifying these configurations for containment-critical applications, compressing demand for conventional top-entry batch mixers.
REACH chemical safety obligations are reshaping material selection protocols. ECHA substance restrictions on certain polymer additives are forcing seal and gasket specification changes in European chemical processing deployments. Battery material processors in Germany are responding with fluoropolymer alternatives validated for lithium salt compatibility.
Service contract unbundling is altering vendor-customer relationships. After-sales maintenance agreements are separating from capital equipment purchases in North American dairy and beverage processing. Large cooperatives in Wisconsin and California are negotiating multi-site service frameworks independent of original equipment procurement, compressing supplier margin capture on initial sales.
Powder Induction and Dispersion Systems Market Segmentation
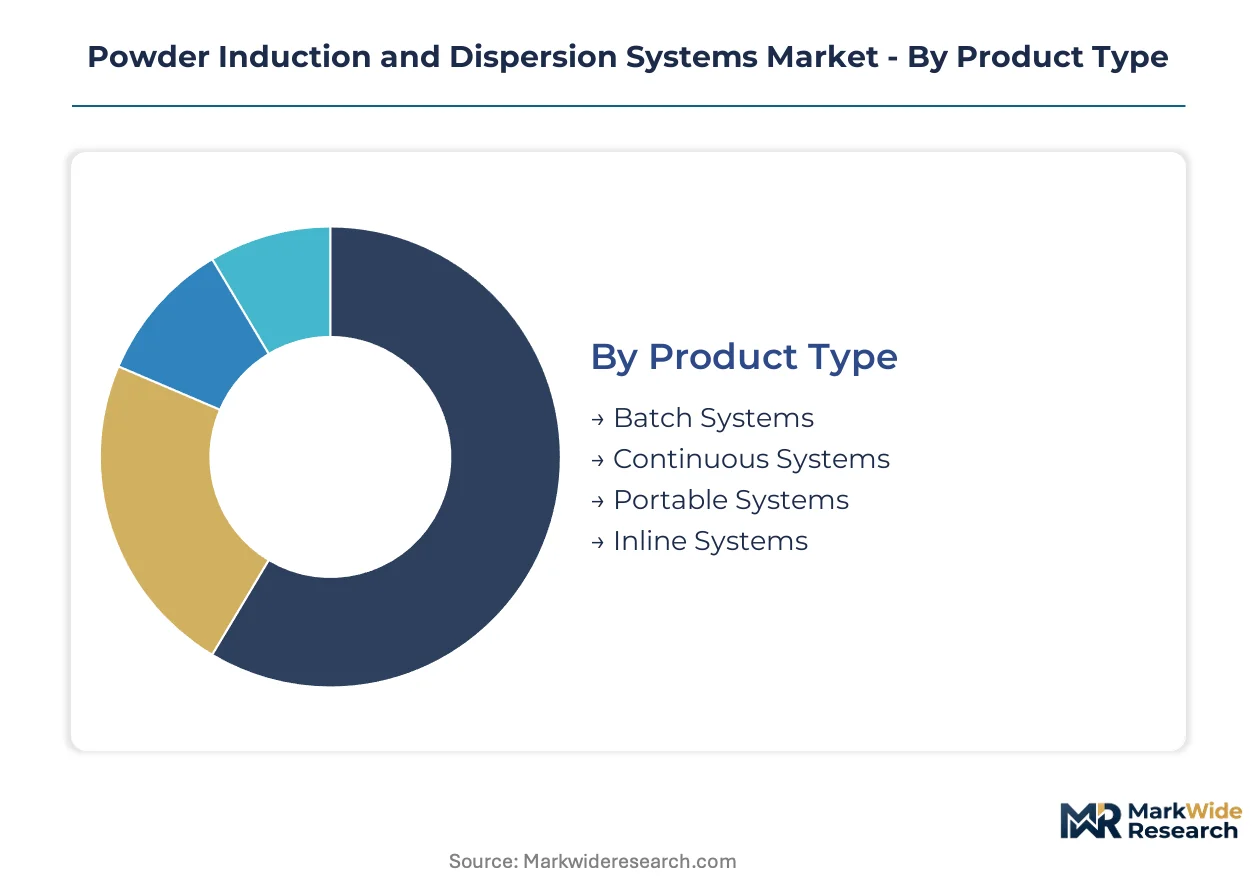
Powder induction and dispersion systems fragment across four critical dimensions, each governing distinct procurement criteria and competitive dynamics. Technology selection dictates containment capability and energy intensity, while end-user verticals impose divergent regulatory validation burdens.
Product Type:
Batch systems face mounting substitution pressure from continuous alternatives in high-throughput chemical processing, though recipe flexibility preserves their position in food manufacturing. Inline configurations are displacing conventional top-entry units in pharmaceutical containment applications.
- Batch Systems:Stationary vessels with top-mounted agitation accommodate variable recipes and intermediate quality checks. Demand concentrates in Wisconsin and California dairy cooperatives where formulation flexibility outweighs throughput optimization.
- Continuous Systems:Inline rotor-stator configurations enable uninterrupted powder feeding into liquid streams. German chemical processors around Ludwigshafen specify these for REACH-compliant high-volume production, driven by energy efficiency mandates.
- Portable Systems:Skid-mounted units with quick-connect utilities serve contract manufacturers requiring equipment mobility across multi-product suites.
- Inline Systems:Vacuum-assisted powder induction eliminates dusting in pharmaceutical-grade configurations, capturing premium positioning in Swiss and German aseptic manufacturing clusters.
Batch systems anchor the volume base while inline configurations gain share at the steepest rate.
End User:
Cost tier stratification separates pharmaceutical procurement—where containment validation commands 40-60% price premiums—from commodity food processing emphasizing capital efficiency.
- Pharmaceuticals:FDA cGMP and EMA Annex 1 compliance mandates drive specification toward validated containment and surface finish documentation. German manufacturers around Stuttgart lead European demand for integrated dispersion skids with clean-in-place protocols.
- Chemicals:ATEX explosion protection requirements and abrasive material handling dominate specification criteria. Battery slurry processors in Germany's gigafactory corridors specify fluoropolymer-sealed rotor-stator assemblies for lithium salt compatibility.
- Food & Beverage:Hygienic powder incorporation for dairy protein hydration and beverage emulsification emphasizes rapid changeover and washdown compatibility.
- Cosmetics:Pigment dispersion and fragrance encapsulation applications prioritize batch flexibility for seasonal SKU variation.
Pharmaceutical demand commands margin concentration while chemical processing expands most quickly on battery materials investment.
Technology:
Application intensity separates high-shear mechanical dispersion—ubiquitous in coatings and adhesives—from emerging magnetic induction methods gaining traction in heat-sensitive nutraceutical processing.
- Mechanical Dispersion:Rotor-stator assemblies operating above 3,000 rpm tip speeds achieve fine emulsion droplet sizes. Coatings formulators in North American industrial clusters specify these for pigment wet-out and stabilizer incorporation.
- Pneumatic Conveying:Vacuum-assisted powder transport into liquid phases eliminates dusting and lump formation. Dairy processors leverage this technology for protein powder hydration without air entrainment.
- Magnetic Induction:Contactless energy transfer enables heating during dispersion, serving temperature-critical biologic media preparation.
- Ultrasonic Mixing:Cavitation-based particle size reduction addresses nanoscale dispersion requirements in specialty coatings.
Mechanical dispersion retains the broadest installed base while pneumatic conveying climbs the fastest on containment and hygiene priorities.
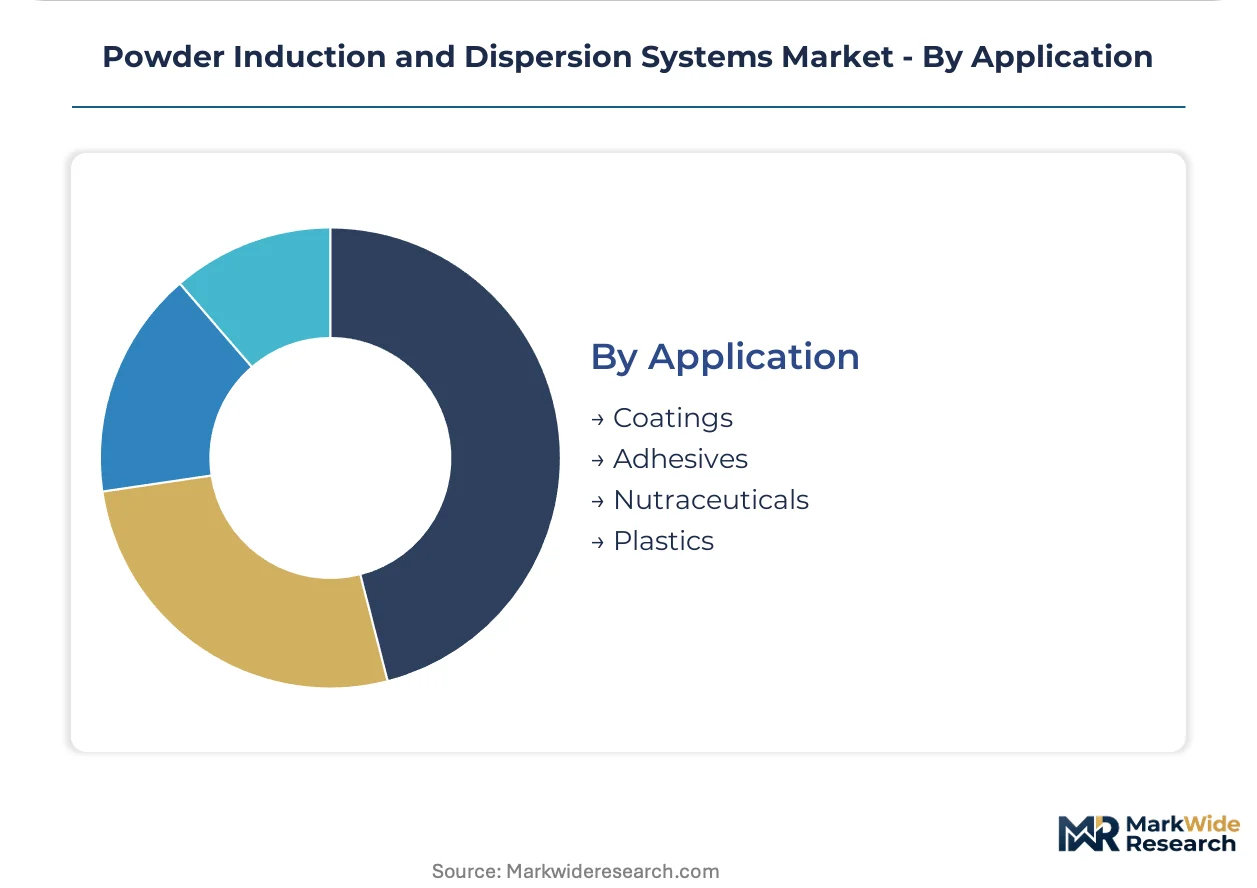
Application:
Customer type bifurcation separates specification-driven coatings procurement—where OEM automotive relationships dictate performance standards—from nutraceutical contract manufacturing emphasizing rapid formulation turnaround.
- Coatings:Pigment dispersion and resin incorporation demand consistent particle size distribution for film formation integrity. Automotive OEM supply chains in Germany specify inline systems for high-solids waterborne formulations.
- Adhesives:Filler wet-out and tackifier dispersion require controlled shear to prevent polymer degradation. Hot-melt and reactive adhesive formulators balance throughput against thermal exposure limits.
- Nutraceuticals:Bioactive compound dispersion into functional beverages and supplement matrices emphasizes clean-label processing without synthetic stabilizers.
- Plastics:Masterbatch and additive compounding applications prioritize throughput scale and color consistency across continuous extrusion lines.
Coatings applications concentrate equipment value while nutraceuticals demonstrate the steepest expansion trajectory on functional food investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in powder induction equipment tilt toward surplus in Germany and deficit in India, reflecting precision engineering concentration versus formulation demand growth. Equipment flows from Stuttgart and Hamburg clusters supply European process industries while Asian pharmaceutical expansion pulls imports.
Germany
Battery gigafactory corridors around Ludwigshafen and pharmaceutical clusters near Stuttgart drive specification of fluoropolymer-sealed inline systems. REACH chemical safety obligations and EMA Annex 1 sterile manufacturing requirements constrain material selection and validation protocols. Hamburg precision engineering suppliers export integrated dispersion skids to Swiss and Benelux biologics manufacturers.
United States
Dairy cooperatives in Wisconsin and California emphasize recipe flexibility and rapid changeover in batch system procurement. OSHA combustible dust standards and FDA cGMP guidelines shape equipment validation for pharmaceutical and chemical processing deployments. Coatings formulators in Midwest industrial clusters specify high-shear rotor-stator assemblies for pigment wet-out applications.
India
Contract manufacturing expansion for global pharmaceutical supply chains creates unserved demand for validated containment systems. CDSCO compliance pathways for imported dispersion equipment remain underdeveloped relative to formulation capacity growth. Maharashtra and Gujarat pharmaceutical clusters rely on European equipment imports for aseptic powder induction capabilities.
China
Battery materials processing for solid-state electrolyte dispersion pulls high-shear inline systems into domestic gigafactory production lines. NMPA pharmaceutical manufacturing guidelines and MIIT industrial equipment standards shape local supplier qualification. Yangtze River Delta chemical processors specify continuous systems for energy efficiency mandates under dual carbon goals.
Switzerland
Biologics manufacturing clusters around Basel specify pre-validated skid-mounted systems for cleanroom integration under ISO 14644-1 protocols. Swissmedic sterile manufacturing requirements exceed standard EMA Annex 1 specifications, commanding premium positioning for containment-validated equipment. Precision engineering partnerships with German suppliers anchor regional supply security for aseptic applications.
Powder Induction and Dispersion Systems Market Competitive Environment
Listed leaders compete with private specialists across technology depth and geographic coverage dimensions, producing tiered market structure. Publicly traded diversified industrials anchor volume segments through broad distribution networks while private German and US specialists capture margin pools in containment-critical pharmaceutical applications. Three archetypes dominate: precision engineering specialists with pharmaceutical validation expertise, diversified process equipment conglomerates serving commodity verticals, and regional batch system fabricators emphasizing capital efficiency. Competitive moves concentrate on M&A for technology access and capacity expansion in battery materials processing corridors.
Among German-based precision specialists, Ystral GmbH exemplifies the containment-validation archetype through its Baden-Württemberg manufacturing base, while IKA Werke GmbH occupies a position in laboratory-to-production scale equipment. US-based Admix Inc. represents the inline induction specialization vector for hygienic powder incorporation in dairy and beverage processing. These three anchors illustrate geographic clustering around Stuttgart precision engineering, Hamburg dispersion technology, and New Hampshire hygienic equipment expertise respectively.
| Leading Market Players |
|---|
| Admix Inc. |
| Silverson Machines Inc. |
| Ystral GmbH |
| SPX Flow |
| IKA Werke GmbH |
| IDEX Corporation |
| Charles Ross & Son Co. |
| John Bean Technologies Ltd. |
| Hayward Gordon Group |
| Others |
Value Chain & Pricing Dynamics
Fourteen-week lead times for pharmaceutical-grade 316L stainless steel from German and Italian specialty mills concentrate pricing power with upstream material suppliers, compressing margin capture for equipment fabricators serving containment-critical applications. Inventory buffers at Hamburg and Stuttgart precision engineering clusters insulate battery materials processors from spot volatility, though dairy cooperatives in North America face elongated procurement cycles for hygienic configurations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with FDA cGMP validation documentation and ATEX explosion protection certification commanding 40-60% premiums over standard hygienic configurations. Price differentiation rests on surface finish grade and clean-in-place protocol complexity, with pharmaceutical manufacturers in Switzerland and Germany exhibiting lowest price sensitivity due to containment mandates. Cost compression in mid-tier chemical processing equipment is intensifying because battery gigafactory procurement teams leverage volume scale for rotor-stator assembly discounts.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Indian and Chinese pharmaceutical manufacturers sourcing from German precision engineering clusters. Supply concentrates in Germany, Italy, and the United States for high-shear rotor-stator assemblies, with fluoropolymer seals and magnetic drive couplings drawing from Japanese and German component specialists. Single-source vulnerability around pharmaceutical-grade 316L surface finish material creates structural exposure. Distribution runs through direct OEM relationships for large chemical processors and regional distributor networks for food and beverage applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic induction dispersion technology threatens mechanical rotor-stator incumbents in heat-sensitive nutraceutical processing, forcing established suppliers to defend installed base relationships through certification breadth and aftermarket service lock-in.
For Market Incumbents: Secure pharmaceutical validation documentation for inline vacuum induction configurations before magnetic induction alternatives gain EMA Annex 1 precedent. Anchor aftermarket service contracts to initial equipment sales through multi-site frameworks with North American dairy cooperatives, compressing independent maintenance procurement that erodes lifetime value capture from battery materials processing deployments. For New Entrants and Emerging Players: CDSCO fast-track pathways for imported containment equipment represent the most penetrable entry vector, as Indian contract manufacturers expand formulation capacity ahead of validated dispersion supply. Target Maharashtra and Gujarat pharmaceutical clusters with skid-mounted systems pre-configured for ISO 14644-1 cleanroom integration, bypassing lengthy facility engineering timelines that delay European competitor deployments. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA cGMP and EMA Annex 1 validation timelines create moats around incumbent certification libraries that compound over decade-long replacement cycles. Acquisition candidates should demonstrate existing pharmaceutical containment documentation and established rotor-stator tip speed advancement roadmaps. Monitor solid-state battery electrolyte dispersion yield rates as the inflection signal for capital deployment timing in chemical processing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical Containment Validation Investment | FDA cGMP documentation libraries create multi-year competitive moats in sterile manufacturing equipment supply. |
| Battery Materials Processing Capacity Expansion | German gigafactory corridors pull high-shear inline systems into lithium salt dispersion applications. |
| Aftermarket Service Contract Unbundling | Multi-site maintenance frameworks with Wisconsin dairy cooperatives compress supplier margin on initial equipment sales. |
| Cleanroom Integration Pre-validation | Skid-mounted systems reduce facility engineering costs for Swiss biologics manufacturers under ISO 14644-1 protocols. |
| Fluoropolymer Seal Technology Advancement | REACH-compliant alternatives address ECHA substance restrictions in European chemical processing deployments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical plant engineers, chemical processing procurement leads, dairy cooperative maintenance directors, battery materials R&D specialists, and coatings formulator technical managers. Secondary validation drew from FDA 483 inspection observations, EMA Annex 1 revision commentaries, SEC 10-K equipment supplier disclosures, and German mechanical engineering association trade flow data. Bottom-up equipment shipment tallies were triangulated against top-down process industry capital expenditure estimates.
Across the analysis window, value projections were derived from segmented modeling across product type, end-user vertical, technology category, and application intensity, with CAGRs calibrated to historical replacement cycle compression under regulatory mandate acceleration. Battery slurry processing throughput requirements and pharmaceutical containment validation timelines served as industry-specific demand elasticity inputs.
Decision-makers should treat outputs as directional under sustained EMA Annex 1 enforcement and OSHA combustible dust standard maintenance; material deviation through regulatory relaxation or alternative dispersion technology validation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Sodium Potassium Tartrate Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Tragacanth Market
Additives
Glacial Acetic Acid Market
Additives
Global Butyric Acid Derivatives Market
Additives
Global Mold Release Agents Market
Additives
Global Feed Acidifiers Market
Additives
India Feed Additives Market
Additives
North America Phosphate Esters Market
Additives
Sorbitan Tristearate Market
Additives
Oxygen Scavengers Market
Additives
Global Packaging Additives Market
Additives
Europe Feed Additives Market
Additives
Global Sizing Agents Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
Extruded Inclusions Market