
 Global Cement and Concrete Additives Market | 2026-2036
Global Cement and Concrete Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cement and Concrete Additives Market Analysis
The EU Green Deal's embodied carbon thresholds for construction materials is repositioning demand toward supplementary cementitious materials and advanced plasticizers. Sika AG leverages its European manufacturing footprint to sustain leadership in low-carbon admixture supply. BASF SE anchors its position through R&D intensity in polycarboxylate ether chemistry. MAPEI S.p.A. competes by dominating specialty formulations for infrastructure-grade concrete across Mediterranean markets.
Cement and concrete additives comprise chemical and mineral compounds—typically dosed at 0.5% to 5% by weight of cement—that modify hydration kinetics, rheology, or durability performance in fresh and hardened concrete. Their primary industrial purpose is to enable specified mechanical properties, placement characteristics, and service-life extension under varying environmental exposures. Plasticizers command the largest product-type position due to universal demand for workability enhancement in high-strength mixes, while accelerators represent the fastest-growing category driven by cold-weather construction protocols and precast manufacturing throughput targets. Infrastructure applications concentrate the deepest margin pools because of specification complexity and long-term performance bonding requirements.
The US EPA regulates volatile organic compound emissions from admixture production facilities, while REACH in Europe governs chemical substance registration and hazard communication for imported formulations. China's MEE enforces GB standards on cement product energy consumption that indirectly constrain additive selection for clinker reduction. India's BIS certification mandates for concrete admixtures create compliance barriers for unqualified imports. Stakeholders must monitor evolving carbon-border adjustment mechanisms and their cascading effects on regional formulation costs and sourcing strategies.
Market Dynamics
Decarbonization mandates across construction supply chains are compressing formulation cycles for cement and concrete additives, forcing suppliers to requalify products under stricter embodied-carbon accounting protocols.
Growth Catalysts
- Mass Transit Infrastructure:Southeast Asian rail and metro projects specify high-performance superplasticizers for extended workability in tropical climates, pulling volumes from commodity admixtures.
- EU Green Deal Thresholds:Embodied carbon limits for public procurement redirect demand toward low-clinker compatible additives and supplementary cementitious material activators.
- Smart City Investments:India's urbanization targets concentrate additive procurement for durable concrete in coastal and seismic zones, prioritizing corrosion inhibitors and shrinkage reducers.
Market Restraints
- Naphtha and Ethylene Feedstock Volatility:Polycarboxylate ether superplasticizers depend on petrochemical derivatives, exposing margins to crude-linked input swings without pass-through mechanisms in fixed-price infrastructure contracts.
- Clinker Substitution Limits:Technical ceilings on supplementary cementitious material replacement rates in structural concrete constrain the addressable market for certain activator chemistries.
- REACH Registration Burden:ECHA substance registration requirements for novel admixture molecules extend commercialization timelines and elevate compliance costs for European market entry.
Strategic Opportunities
- Carbon Capture Utilization:Mineralization-derived calcium carbonate additives for concrete curing represent an emerging white space as hard-tech developers partner with admixture formulators.
- 3D Construction Printing:Specialized rheology modifiers and set-control admixtures for extrusion-based building methods open premium pricing in demonstration projects across the Netherlands and the UAE.
- India BIS Certification Gaps:Unqualified import barriers create protected market share for domestic producers who achieve Bureau of Indian Standards certification ahead of multinational entrants.
Industry Challenges
- Formulation Chemist Scarcity:Deep expertise in cement-admixture compatibility testing remains concentrated among retiring specialists, constraining R&D throughput for novel low-carbon blends.
- Multi-Jurisdiction Certification Lags:Parallel validation requirements under EPA, REACH, and BIS regimes delay global product rollouts and fragment regional SKU portfolios.
- Legacy Concrete Specification Inertia:Prescriptive standards in mature markets resist performance-based admixture substitution, forcing costly parallel testing to displace entrenched product approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cement and Concrete Additives Market |
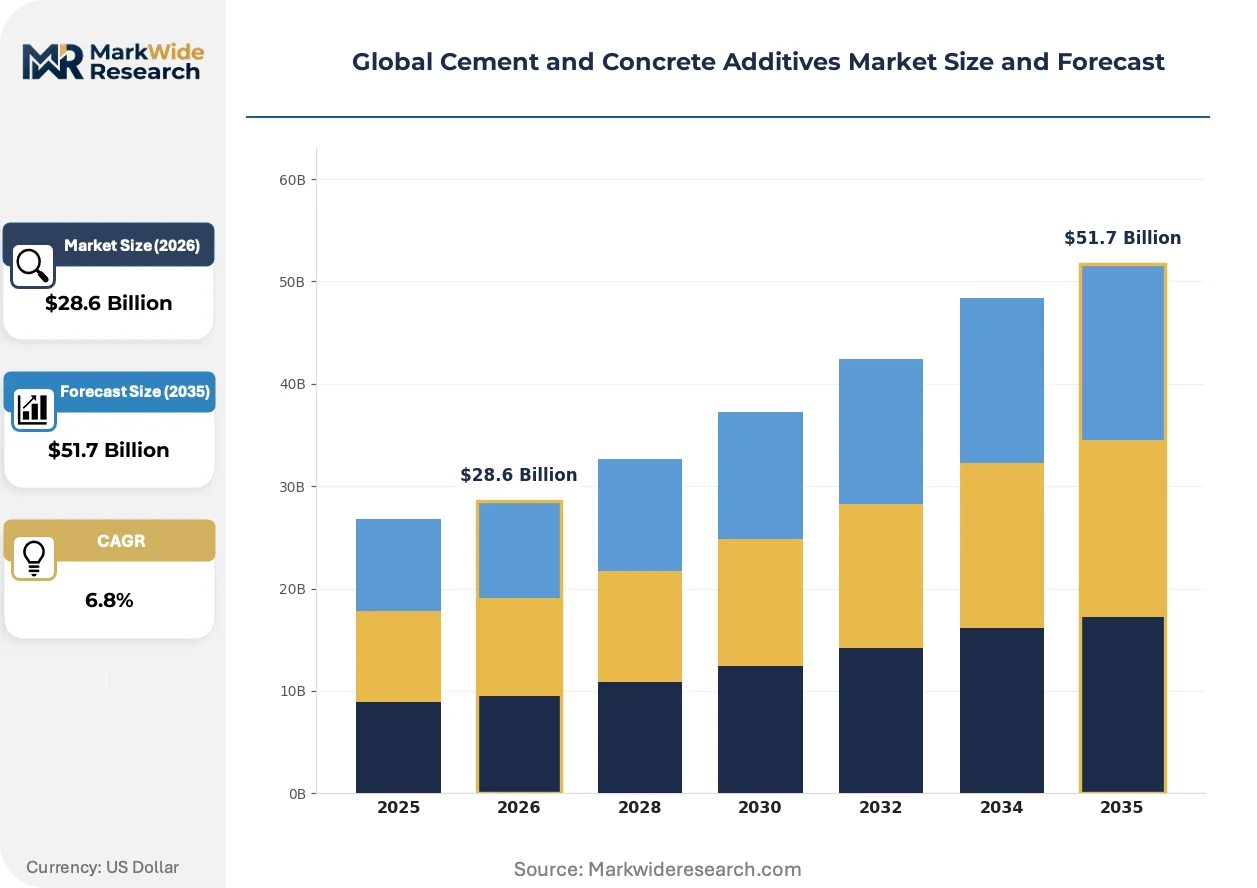
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Retarders, Accelerators, Air-Entraining Agents Application: Residential Construction, Commercial Construction, Infrastructure, Industrial Applications End User: Construction Firms, Real Estate Developers, Engineering Companies, Government Projects Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Outlets |
| Companies Covered | RPM International Inc., Fosroc International Limited, Sika AG, Chryso S.A.S., Saint-Gobain, BASF SE, MAPEI S.p.A., Sobute New Materials Co., Ltd., GCP Applied Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cement and Concrete Additives Market Emerging Trajectories
Electrification of construction equipment and processes is reshaping concrete placement windows, compressing set-time requirements and accelerating demand for precision-controlled admixture dosing systems.
Alkali-activated binder chemistry is electrifying competitive positioning in the precast segment. German and Dutch infrastructure contractors specify these systems for bridge elements requiring rapid demolding. The technology compresses production cycle times from twenty-four hours to under six, enabling overnight casting schedules that conventional Portland cement cannot match.
REACH authorization procedures for boron-based retarders are tightening supply security for European ready-mix producers. The regulation forces substitution toward alternative chemistries, elevating R&D intensity among formulators serving the Benelux and German markets. Specialty admixture houses accelerate bio-based retarder development to preempt authorization sunset dates.
Specification-driven procurement is consolidating buyer power among engineering-procurement-construction firms managing mega-projects. Tier-one contractors in Saudi Arabia and Qatar now mandate certified low-carbon concrete for gigaproject portfolios, displacing commodity admixture relationships with performance-guaranteed supply contracts. This compression of the vendor base favors integrated suppliers with in-house testing capabilities.
Global Cement and Concrete Additives Market Segmentation
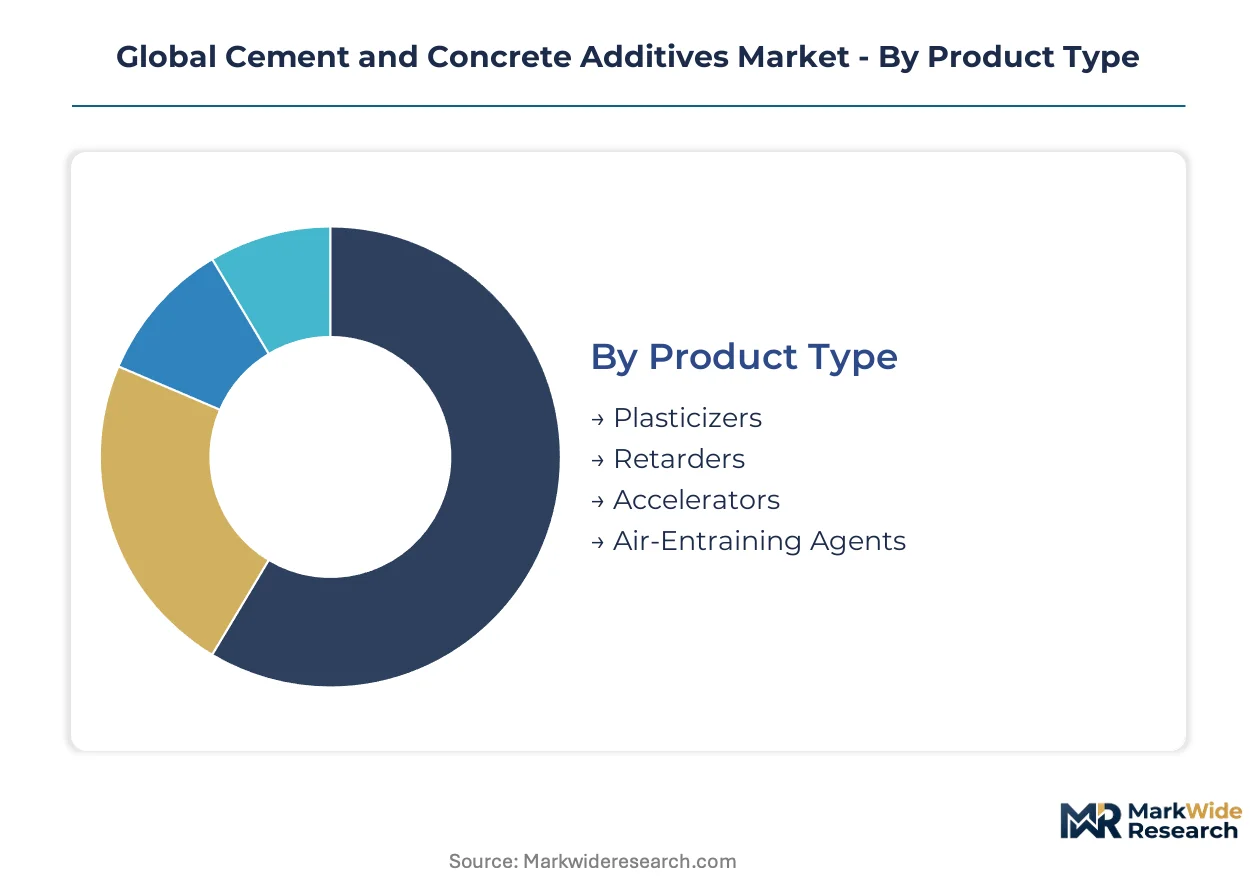
Cement and concrete additives exhibit divergent margin profiles and specification complexity across product categories. Segmentation reveals where capital deployment concentrates and which channels capture value from infrastructure megaprojects.
Product Type:
Capital intensity escalates sharply with molecular complexity and regulatory testing burdens for novel chemistries.
- Plasticizers:Polycarboxylate ether and lignosulfonate formulations reduce water demand by 15-40% while maintaining slump. Demand clusters in Germany and the Netherlands for self-consolidating concrete in complex formwork. EU Green Deal carbon thresholds intensify procurement of high-range water reducers compatible with low-clinker blends.
- Accelerators:Calcium chloride, calcium nitrate, and alkali-free formulations compress set times for cold-weather pours and precast throughput. Norwegian and Swedish infrastructure contractors specify non-chloride variants for bridge decks exposed to de-icing salts. Electrification of construction schedules is compressing casting windows and pulling volumes from conventional Portland systems.
- Retarders:Organic acids and phosphates extend workability in tropical climates and mass concrete pours. REACH authorization pressures on boron-based chemistries are forcing substitution toward bio-derived alternatives in Benelux markets.
- Air-Entraining Agents:Synthetic surfactants and natural resins entrain microscopic air voids for freeze-thaw durability. Canadian and Finnish specifications mandate inclusion for exposed horizontal surfaces.
Most installed capacity flows through Plasticizers. Expansion is steepest in Accelerators.
Application:
Specification complexity and performance bonding requirements stratify margin capture across construction verticals.
- Infrastructure:Bridge decks, tunnels, and marine structures demand corrosion inhibitors, shrinkage reducers, and sulfate-resistant formulations with 50-100 year service-life guarantees. India's coastal smart city investments concentrate procurement of durability-enhancing admixtures for seismic zones. Saudi gigaproject contractors now mandate certified low-carbon concrete with performance-guaranteed supply contracts.
- Commercial Construction:High-rise cores and composite floor systems specify superplasticizers for high-strength, pumpable mixes with extended slump retention. UAE and Qatar demonstration projects for 3D construction printing create premium pricing for specialized rheology modifiers.
- Residential Construction:Standard ready-mix applications favor commodity plasticizers and basic set-control admixtures. Volume concentration in Indian urbanization corridors prioritizes cost-efficient formulations over performance premiums.
- Industrial Applications:Precast manufacturing and paving operations specify rapid-setting accelerators and surface retarders for production cycle compression. German precasters specify alkali-activated binder activators for overnight demolding schedules.
Infrastructure commands the deepest margin pools. Commercial Construction is gaining share fastest through specification-driven procurement consolidation.
End User:
Buyer sophistication and testing capabilities determine whether additive supply relationships remain transactional or evolve into performance partnerships.
- Construction Firms:Tier-one engineering-procurement-construction firms in Saudi Arabia and Qatar consolidate vendor bases through certified low-carbon concrete mandates. In-house testing laboratories displace commodity supplier relationships.
- Government Projects:Public procurement protocols in India and EU member states embed embodied carbon thresholds that redirect additive selection toward SCM-compatible formulations. BIS certification requirements create protected market share for qualified domestic suppliers.
- Real Estate Developers:Private sector developers in Southeast Asian mass transit corridors specify high-performance superplasticizers for extended workability in tropical climates.
- Engineering Companies:Design-build contractors with specialized geotechnical expertise specify custom admixture blends for ground improvement and soil stabilization applications.
Government Projects concentrate the most rigid compliance requirements. Construction Firms are expanding procurement authority fastest through vertical integration of testing capabilities.
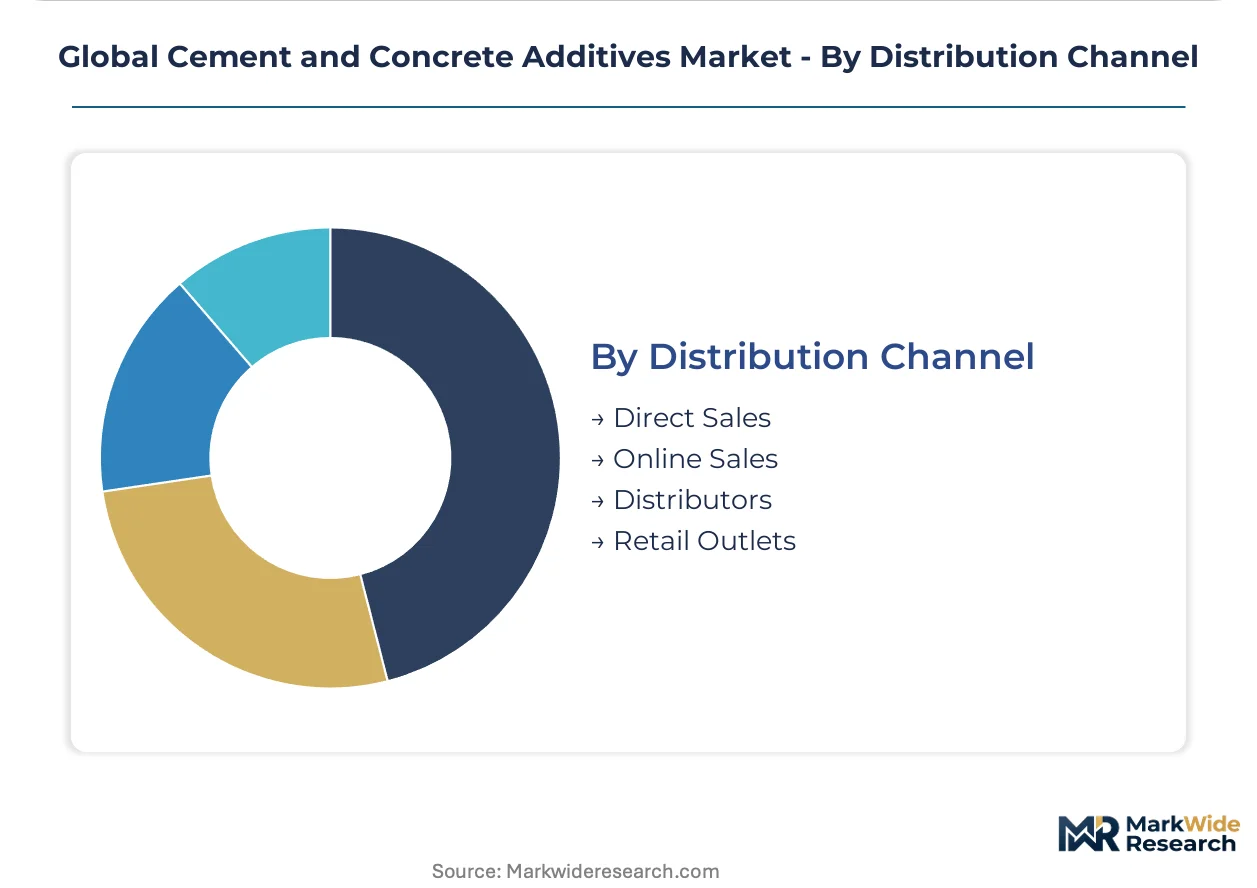
Distribution Channel:
Channel economics reflect batch size, technical service intensity, and geographic dispersion of demand.
- Direct Sales:Bulk supply agreements with ready-mix producers and precast manufacturers capture volume through dedicated technical service teams. Sika AG and BASF SE anchor European market presence through direct relationships with major contractors.
- Distributors:Regional stocking points serve fragmented ready-mix and contractor bases in secondary Indian and Southeast Asian markets. Inventory carrying costs concentrate among distributors with cold-chain requirements for temperature-sensitive formulations.
- Online Sales:Digital procurement platforms emerge for standardized commodity admixtures in mature markets with transparent specifications. Limited penetration for performance-critical formulations requiring compatibility testing.
- Retail Outlets:Small-package sales to residential contractors and repair specialists concentrate in North American home improvement channels. Margins compress against bulk direct pricing.
Direct Sales channels capture the highest value-add per ton. Distributors are expanding geographic coverage fastest into underpenetrated Indian states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portland cement chemistry originated in Britain during the 1820s, establishing European technical leadership that persists in today's admixture formulation standards. Regional demand now fragments across climate zones, regulatory regimes, and infrastructure investment cycles.
United States
Federal infrastructure spending under the Infrastructure Investment and Jobs Act channels procurement toward high-performance concrete for bridge rehabilitation and coastal resilience. EPA volatile organic compound regulations constrain admixture manufacturing in the Gulf Coast petrochemical corridor. Texas and California concentrate ready-mix demand, with Houston contractors specifying corrosion inhibitors for marine exposure zones.
Germany
Alkali-activated binder specifications for precast bridge elements compress production cycles and pull volumes from conventional Portland systems. REACH authorization pressures on boron-based retarders force substitution toward bio-derived alternatives. The Rhine-Ruhr industrial cluster hosts formulation R&D facilities serving Benelux infrastructure markets.
China
MEE enforcement of GB standards on cement energy consumption indirectly constrains additive selection for clinker reduction in Yangtze River Delta megaprojects. Dual carbon goals redirect provincial procurement toward low-clinker compatible admixtures. Shanghai and Shenzhen smart city investments concentrate demand for durability-enhancing formulations in coastal seismic zones.
India
Bureau of Indian Standards certification mandates create protected market share for qualified domestic suppliers in Maharashtra and Gujarat infrastructure corridors. Smart city investments in coastal seismic zones prioritize corrosion inhibitors and shrinkage reducers. Mumbai and Chennai urbanization targets intensify additive procurement for mass transit concrete specifications.
Saudi Arabia
Gigaproject contractors mandate certified low-carbon concrete with performance-guaranteed supply contracts, displacing commodity admixture relationships. SFDA chemical substance regulations govern imported formulation safety documentation. Riyadh and NEOM construction sites specify extended-workability superplasticizers for desert climate placement windows.
Global Cement and Concrete Additives Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and certification burden. The vendor base stratifies into integrated multinational suppliers with in-house testing laboratories, regional specialists with protected domestic certification, and commodity distributors serving fragmented ready-mix markets. Three archetypes dominate: European technology leaders with REACH-registered novel chemistries, Asian scale players with cost-optimized lignosulfonate and naphthalene formulations, and Gulf-based project specialists with performance-bonding capabilities for megaproject procurement. Competitive moves concentrate on M&A for technology access and vertical integration into raw material supply.
Among European-anchored formulators, Sika AG, BASF SE, and MAPEI S.p.A. exemplify the premium-tier archetype through established manufacturing footprints and R&D intensity in polycarboxylate ether chemistry. These entities occupy positions aligned with EU Green Deal compliance requirements and low-carbon specification trends. Their geographic concentration in Germany, Switzerland, and Italy reflects historical cement chemistry lineage and proximity to infrastructure demand clusters.
| Leading Market Players |
|---|
| RPM International Inc. |
| Fosroc International Limited |
| Sika AG |
| Chryso S.A.S. |
| Saint-Gobain |
| BASF SE |
| MAPEI S.p.A. |
| Sobute New Materials Co., Ltd. |
| GCP Applied Technologies Inc. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal embodied carbon thresholds gate both qualified supply and premium-tier pricing access, compressing formulation cycles while elevating certification burdens that stratify admixture procurement across European infrastructure markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates admixture procurement, with REACH-registered polycarboxylate ether formulations commanding substantial premiums over commodity lignosulfonate blends. Price differentiation hinges on certification grade under EU Green Deal protocols and volume scale in fixed-price infrastructure contracts. Cost compression in commodity tiers is intensifying because naphtha and ethylene feedstock volatility lacks pass-through mechanisms. Government project buyers exhibit least price sensitivity due to performance bonding requirements, while residential construction channels remain most cost-conscious.
Supply Chain Analysis
REACH registration and BIS certification gating fragments global supply into qualified regional pools, with Germany, Switzerland, and Italy anchoring European formulation capacity while India and China concentrate cost-optimized production. Raw material sourcing draws from petrochemical derivatives including ethylene oxide and naphtha streams, plus mineral inputs like calcium nitrate and lignin sulfonates. Single-source vulnerability concentrates around polycarboxylate ether precursor supply from Gulf Coast petrochemical complexes. Distribution runs through direct technical service relationships with ready-mix producers and precast manufacturers, supplemented by regional distributors in fragmented secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play: REACH compliance costs in Europe run substantially higher than BIS certification investments in India, creating margin capture opportunities for dual-qualified suppliers.
For Market Incumbents: Deepen backward integration into ethylene oxide and naphtha precursor supply to insulate margins from petrochemical volatility. Fortify in-house cement-admixture compatibility testing capabilities to displace commodity relationships with performance-guaranteed supply contracts. Accelerate bio-based retarder development to preempt REACH authorization sunset dates for boron-based chemistries. For New Entrants and Emerging Players: Tier-two engineering-procurement-construction firms in Indian smart city corridors represent underserved buyer archetypes with specification complexity but limited incumbent loyalty. Capture protected market share through early BIS certification ahead of multinational entrants. Lead with corrosion inhibitor and shrinkage reducer formulations for coastal seismic zones where durability premiums outweigh cost sensitivity. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with protected domestic certification but limited export capability. Long-term viability centers on dual-qualified suppliers spanning REACH and BIS regimes with alkali-activated binder technology access. Watch for carbon-border adjustment mechanism implementation as inflection indicator for low-clinker compatible formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive ethylene oxide production insulates Sika AG and BASF SE from Gulf Coast feedstock volatility. |
| REACH-Registered Novel Chemistry Development | Bio-based retarder pipelines preempt ECHA authorization pressures on boron-based formulations in Benelux markets. |
| BIS Certification Acceleration | Domestic Indian producers lock out multinational entrants in Maharashtra and Gujarat infrastructure corridors. |
| Alkali-Activated Binder Partnership | German precasters compress production cycles from twenty-four hours to under six through specialized activator supply. |
| Carbon Capture Utilization Integration | Mineralization-derived calcium carbonate additives open premium positioning as hard-tech developers partner with formulators. |
Methodological Framework
Bottom-up infrastructure and precast modeling reconciled against top-down chemical production tracking forms the analytical core of this study. Primary interviews with admixture formulation chemists, ready-mix procurement directors, EPC contractor technical officers, and BIS certification auditors combined with secondary validation from customs trade data, SEC 10-K filings, ECHA substance registration databases, and infrastructure project procurement disclosures. Triangulation across these sources reconciles volume estimates with disclosed capacity expansions.
Historical trendline analysis of admixture consumption per ton of cement shipped establishes baseline growth patterns across the projection horizon. Segmentation modeling spans product type complexity, application durability requirements, end-user testing sophistication, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating clinker substitution limits and embodied carbon threshold compliance trajectories. Industry-specific inputs include electrification-driven casting window compression and 3D construction printing specification emergence.
Underlying measurement precision varies by segment; plasticizer and accelerator categories carry tighter precision than emerging carbon capture utilization additives due to established trade flow documentation. Forecasts reflect assumptions on EU Green Deal enforcement timing, REACH authorization sunset schedules, and BIS certification processing throughput. Deviation in carbon-border adjustment mechanism implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Lauroyl Methyl Glucamide Market
Additives
Sodium Benzoate Market
Additives
Calcium Acetate Market
Additives
Europe Citric Acid Market
Additives
Low VOC Coating Additives Market
Additives
Disodium Guanylate Market
Additives
Global Propyl Acetate Market
Additives
Glyceryl Caprylate Market
Additives
Binding Agents Market
Additives
Allura Red AC Market
Additives
Global Carboxylic Acids Based Esters Market
Additives
Global Butylated Hydroxytoluene Market
Additives
Canada Water Enhancer Market
Additives
Volatile Corrosion Inhibitors Market
Additives
Cassia Gum Market