
 Inorganic Rheology Modifiers Market | 2026-2036
Inorganic Rheology Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Inorganic Rheology Modifiers Market Outlook
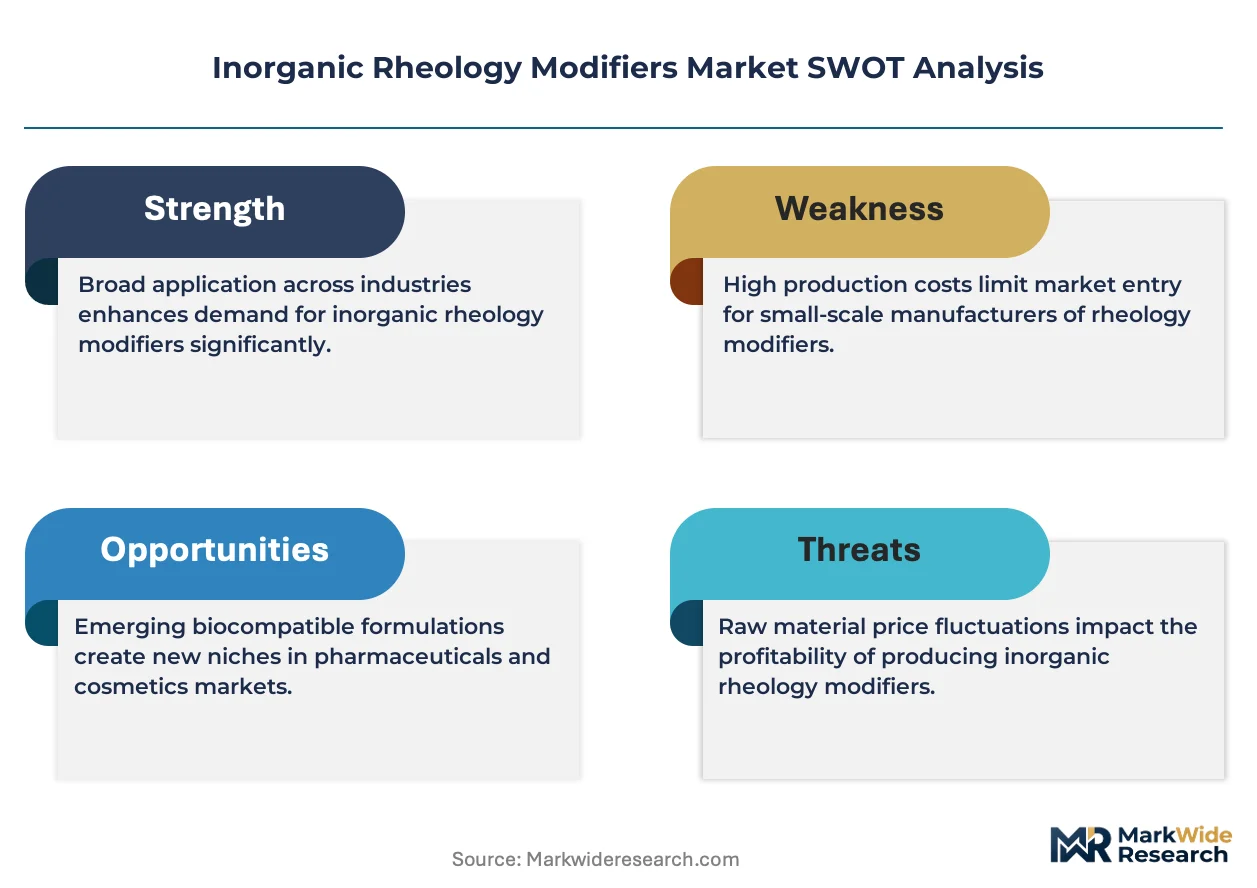
Specialty coatings formulators is bifurcating from commodity paint producers as the primary volume anchor for inorganic rheology modifiers. BASF SE leverages its integrated pigment-additive complexes to dominate supply to European automotive clearcoat lines. Clariant specializes in organoclay derivatives for solvent-free adhesive systems, while Elementis Plc. anchors its position through mining-linked talc and hectorite assets that sustain raw material security.
Inorganic rheology modifiers encompass particulate and lamellar solids—principally bentonite clays, fumed silica, calcined alumina, and platy talc—dispersed within liquid matrices to control viscosity, sag resistance, and storage stability through particle network formation and interfacial interactions. These materials function as cost-efficient alternatives to organic thickeners in high-shear industrial processes where thermal stability and UV resistance are mandatory. Silica grades command premium positioning in coatings applications where transparency and scratch resistance define performance tiers, while clay-based systems occupy volume leadership in construction sealants where cost minimization governs procurement. Talc and calcined alumina segments compete on modulus enhancement in automotive underbody coatings, with margin pools shifting toward surface-treated grades that reduce dispersion energy.
REACH registration requirements and EU Green Deal chemical sustainability protocols are forcing reformulation of solvent-borne systems toward waterborne and high-solids alternatives that favor silica and organoclay modifiers. EPA VOC regulations in the United States and China's MEE emission standards similarly restrict traditional organic thickener use in architectural coatings, redirecting specification toward inorganic options. Stakeholders must monitor evolving classification of nanoscale silica under ECHA's nanomaterial reporting obligations and align R&D pipelines with outcome-based regulatory acceptance criteria for next-generation dispersions.
Market Dynamics
Waterborne coating reformulation under REACH and EU Green Deal timelines is concentrating procurement around silica and organoclay modifiers, compressing demand for traditional organic thickeners and rewarding suppliers with integrated pigment-additive complexes.
Growth Catalysts
- REACH solvent restrictions:EU chemical sustainability protocols are forcing architectural coatings toward high-solids and waterborne systems that favor inorganic rheology control. Formulators are abandoning cellulosic thickeners for fumed silica in premium clearcoats.
- Automotive OEM specification:German automotive clearcoat lines are mandating scratch-resistant silica grades for transparency-critical applications. BASF SE and Evonik Industries AG anchor supply chains serving Stuttgart and Munich production clusters.
- Construction chemical volume:Bentonite clays dominate sealant procurement where cost minimization governs specification. German construction chemical blenders are expanding offtake for infrastructure waterproofing systems.
Market Restraints
- Raw material concentration:High-purity hectorite deposits concentrate in Nevada and Turkey, creating geographic supply vulnerability for organoclay producers. Elementis Plc. maintains mining-linked asset security that smaller competitors cannot replicate.
- Energy-intensive calcination:Calcined alumina production requires natural gas-fired kilns operating above 1,000°C. European energy price volatility is compressing margins for surface-treated grades.
- Organic thickener substitution threat:Associative polyurethane thickeners are retaining share in DIY architectural coatings where application simplicity outweighs UV resistance requirements.
Strategic Opportunities
- India infrastructure buildout:The country's PLI scheme for specialty chemicals is attracting investment in localized bentonite processing. Construction sealant demand in Maharashtra and Gujarat is outpacing domestic modifier supply.
- EV battery thermal interface materials:Fumed silica is penetrating thermal paste formulations for electric vehicle battery modules. Automotive OEMs are qualifying grades that balance viscosity control with dielectric performance.
- Japan METI carbon neutrality roadmap:Japanese coatings manufacturers are reformulating under national dual carbon alignment. Waterborne industrial coatings in Osaka and Nagoya clusters are specifying low-dispersion-energy organoclays.
Industry Challenges
- ECHA nanomaterial reporting complexity:Colloidal silica dispersions face evolving classification thresholds that delay product registration. Formulators are suspending new grade introductions pending regulatory clarity.
- High-shear dispersion capex:Surface-treated grades require bead mill investments that mid-tier coatings producers cannot justify. Equipment financing constraints are fragmenting technology adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inorganic Rheology Modifiers Market |
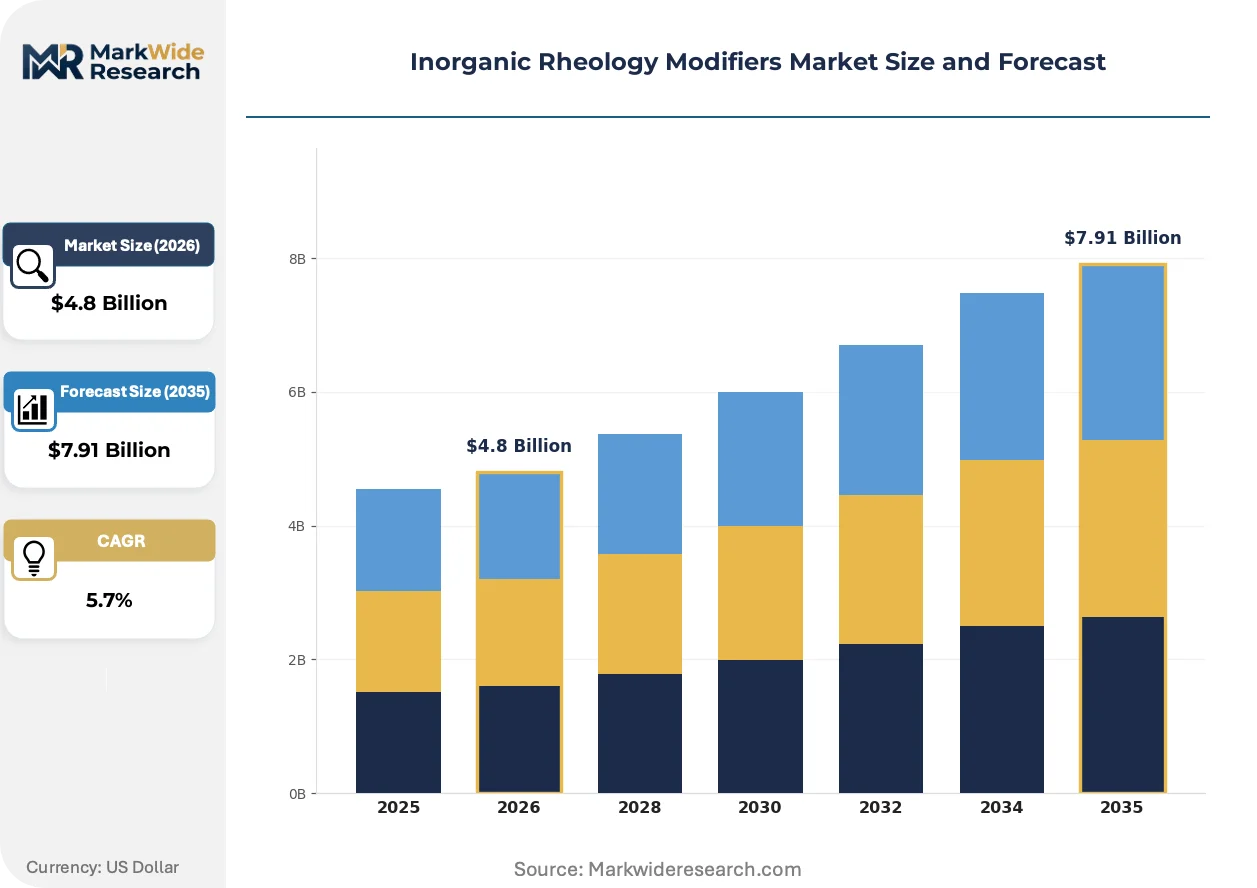
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clays, Silica, Calcined Alumina, Talc Application: Coatings, Adhesives, Sealants, Personal Care End Use Industry: Construction, Automotive, Cosmetics, Pharmaceuticals Form: Powder, Granules, Liquid, Paste |
| Companies Covered | Clariant, Akzo Nobel N.V., BASF SE, BYK Additives & Instruments, Elementis Plc., The Dow Chemical Company, Ashland, Evonik Industries AG, Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inorganic Rheology Modifiers Market Strategic Shifts
Formulation science is pivoting from viscosity management toward multifunctional performance, with modifiers now expected to deliver scratch resistance, thermal conductivity, and regulatory compliance simultaneously.
Surface-treated fumed silica is decomposing the traditional separation between rheology control and mechanical property enhancement. Automotive OEMs are specifying dual-function grades that eliminate separate scratch-resistant additive packages. This convergence is compressing formulation complexity while elevating performance thresholds for Tier 1 suppliers.
China's MEE emission standards are accelerating solvent-borne system phase-out in architectural coatings. Provincial enforcement in Jiangsu and Zhejiang is disqualifying traditional organic thickeners from government project specifications. Domestic coatings leaders are qualifying organoclay alternatives to maintain public infrastructure contract eligibility.
Specification consolidation around integrated pigment-additive suppliers is shortening qualified vendor lists for specialty coatings formulators. Procurement teams at German automotive OEMs are consolidating spend with BASF SE and Evonik Industries AG to secure REACH-aligned documentation packages. This concentration is visible across Stuttgart, Munich, and Wolfsburg production clusters.
Inorganic Rheology Modifiers Market Segmentation
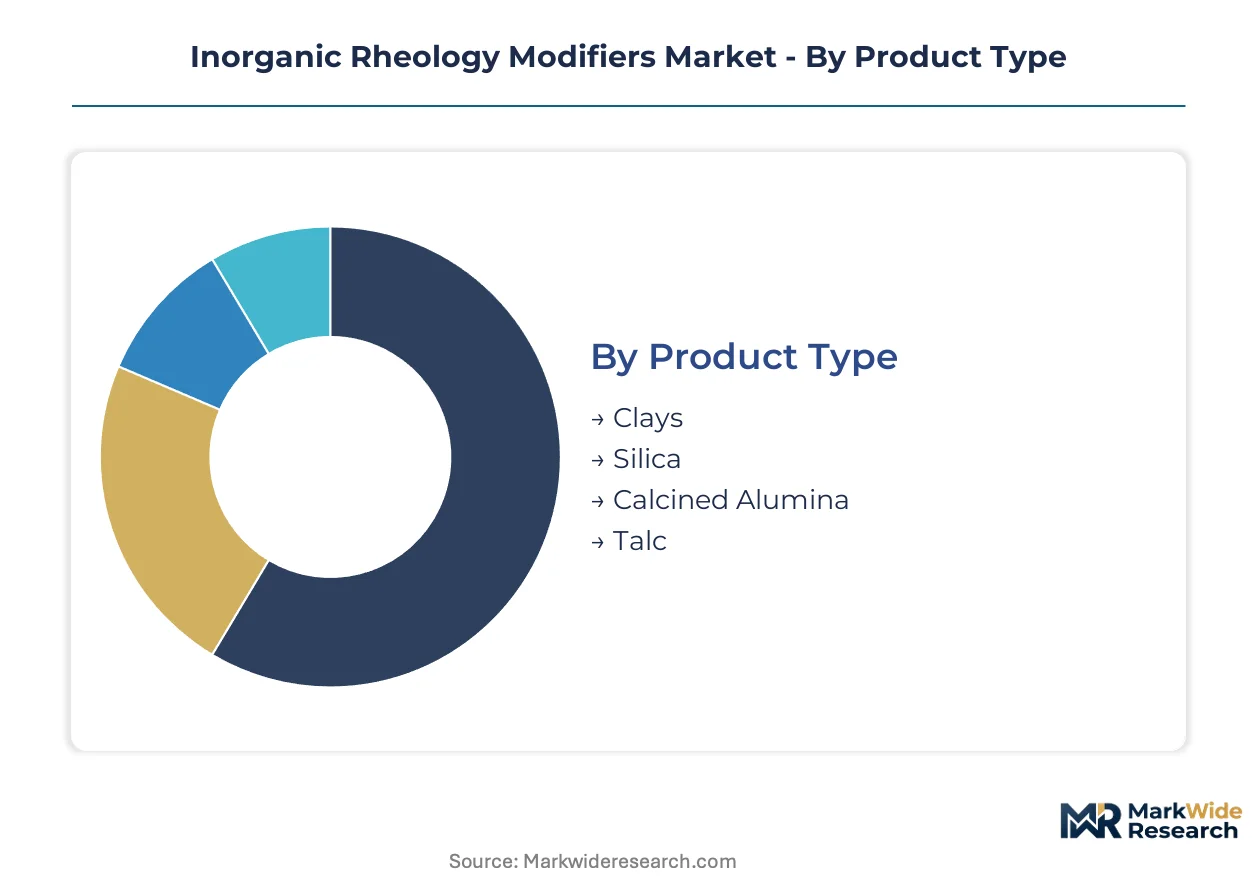
Formulators select modifiers based on shear stability requirements, thermal processing constraints, and regulatory compliance timelines. Segment boundaries are blurring as suppliers develop surface-treated grades that span multiple application categories. Procurement teams now evaluate total formulation cost rather than unit price alone.
Product Type:
Substitute pressure from associative polyurethane thickeners is most acute in powder-grade clays, where DIY architectural coatings favor application simplicity over UV resistance.
- Clays:Bentonite and hectorite derivatives form thixotropic networks through platelet edge-face interactions. German construction chemical blenders specify organoclay grades for infrastructure waterproofing where REACH solvent restrictions disqualify cellulosic alternatives.
- Silica:Fumed and precipitated grades deliver transparency-critical performance in automotive clearcoats. Stuttgart and Munich OEM clusters mandate scratch-resistant silica for premium coating tiers, compressing demand for organic thickeners in high-visibility applications.
- Calcined Alumina:High-temperature processed grades enhance modulus in underbody coatings. European energy price volatility above 1,000°C kiln operations is compressing margin pools for surface-treated variants.
- Talc:Platy morphology provides barrier properties and cost efficiency in sealant formulations. Elementis Plc. mining-linked assets secure raw material access that smaller competitors cannot replicate.
Clays anchor the volume base while silica gains share at the steepest rate.
Application:
Cost tier differentiation separates specification-grade coatings from commodity architectural applications, with premium tiers absorbing higher modifier costs for regulatory compliance.
- Coatings:Waterborne architectural and automotive clearcoat formulations dominate silica procurement. BASF SE integrated pigment-additive complexes supply German OEM lines under EU Green Deal timelines.
- Adhesives:Solvent-free systems specify organoclay modifiers for sag resistance. Clariant derivatives serve industrial bonding applications where VOC elimination is mandatory.
- Sealants:Bentonite clays control cost in construction waterproofing. Maharashtra and Gujarat infrastructure buildout is outpacing domestic Indian modifier supply.
- Personal Care:Colloidal silica stabilizes emulsions in premium cosmetic formulations. ECHA nanomaterial reporting thresholds delay new grade introductions in this segment.
Coatings command the largest value pool while adhesives expand most quickly under solvent-free mandates.
End Use Industry:
Customer type concentration is elevating automotive OEM specification power, with procurement consolidation around integrated suppliers shortening qualified vendor lists.
- Construction:Sealant and waterproofing systems drive bentonite clay volume. German infrastructure investment concentrates demand with regional construction chemical blenders.
- Automotive:Clearcoat transparency and scratch resistance specifications favor premium silica grades. EV battery thermal interface materials represent an emerging qualification pathway for fumed silica in thermal paste formulations.
- Cosmetics:Personal care formulators balance sensory performance with regulatory documentation requirements. ECHA nanomaterial classification complexity constrains new product development pipelines.
- Pharmaceuticals:Excipient-grade modifiers require GMP-compliant manufacturing and validated supply chains. Regulatory documentation burdens favor established suppliers with existing pharmaceutical customer relationships.
Construction anchors absolute volume while automotive drives specification intensity and margin expansion.
Form:
Supply concentration in powder processing equipment is fragmenting technology adoption, as surface-treated grades require bead mill investments that mid-tier producers cannot justify.
- Powder:Standard grades serve cost-sensitive construction sealants. Dry handling infrastructure is widely available across regional production facilities.
- Granules:Low-dust alternatives improve workplace safety in high-volume manufacturing environments. Japanese METI carbon neutrality roadmap is accelerating specification in Osaka industrial coatings clusters.
- Liquid:Pre-dispersed colloidal silica eliminates high-shear dispersion capex for smaller formulators. ECHA evolving classification thresholds create registration delays for new liquid grade introductions.
- Paste:High-solids concentrates reduce transportation costs and storage footprint. Premium automotive clearcoat lines specify paste grades for batch consistency in Stuttgart production facilities.
Powder forms dominate shipment volumes while liquid dispersions climb fastest as formulators seek to bypass capital equipment constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty chemical exports dominate supply to European automotive OEMs, while Chinese bentonite processors feed construction sealant demand across Southeast Asian infrastructure markets.
Germany
Automotive clearcoat specifications from Stuttgart and Munich OEM clusters drive premium silica procurement. EU Green Deal chemical sustainability protocols force waterborne coating reformulation by 2030. BASF SE and Evonik Industries AG anchor integrated supply chains serving Baden-Württemberg production facilities.
China
Provincial MEE emission enforcement in Jiangsu and Zhejiang accelerates solvent-borne system phase-out. Domestic coatings leaders qualify organoclay alternatives to maintain public infrastructure contract eligibility. Shanghai and Guangzhou industrial clusters concentrate modifier demand for architectural coatings.
United States
EPA VOC regulations redirect architectural coating specification toward inorganic thickeners. High-purity hectorite deposits in Nevada create geographic supply concentration for organoclay producers. Automotive underbody coating lines in Michigan and Ohio specify calcined alumina for modulus enhancement.
India
PLI scheme incentives for specialty chemicals attract localized bentonite processing investment. Maharashtra and Gujarat infrastructure buildout outpaces domestic modifier supply. Construction chemical blenders in Mumbai and Ahmedabad expand procurement for waterproofing systems.
Japan
METI carbon neutrality roadmap drives industrial coating reformulation toward waterborne systems. Osaka and Nagoya manufacturing clusters specify low-dispersion-energy organoclays. Japanese coatings manufacturers align procurement with national dual carbon targets.
Inorganic Rheology Modifiers Market Competitive Environment
Player mix skews toward integrated chemical conglomerates with captive mineral processing assets. Three to five diversified multinationals control premium-grade supply through backward integration into mining and calcination. The competitive terrain separates into pigment-additive integrators, specialty clay miners, and additive-instrument hybrids. Capacity expansion and strategic partnerships dominate competitive moves as firms secure raw material access.
Among European chemical conglomerates, BASF SE and Evonik Industries AG occupy positions as integrated pigment-additive suppliers serving automotive OEM specification chains. Elementis Plc. represents the mining-linked archetype with asset-backed raw material security. Clariant exemplifies specialty derivative producers focused on solvent-free system qualification. These three anchors illustrate how supply concentration favors players with upstream control over mineral deposits or captive silica production.
| Leading Market Players |
|---|
| Clariant |
| Akzo Nobel N.V. |
| BASF SE |
| BYK Additives & Instruments |
| Elementis Plc. |
| The Dow Chemical Company |
| Ashland |
| Evonik Industries AG |
| Lubrizol Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH registration tiers and EU Green Deal chemical sustainability protocols gate both supplier qualification and price differentiation simultaneously, forcing formulators to absorb premium documentation costs for integrated pigment-additive complexes while compressing margins on commodity clay grades.
Pricing Analysis
Surface-treated fumed silica commands substantial premiums over standard precipitated grades, while unprocessed bentonite clays trade at economy tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and dispersion energy requirements. Cost compression in calcined alumina intensifies because European natural gas price volatility above 1,000°C kiln operations erodes margin pools. Construction sealant blenders exhibit highest price sensitivity, while German automotive OEM procurement teams prioritize REACH-aligned documentation over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for pre-dispersed liquid silica grades. High-purity hectorite concentrates in Nevada and Turkey, while fumed silica production clusters in Germany and China. Raw material security draws from mining-linked assets, natural gas supply contracts, and surface treatment chemical feedstocks. Single-source vulnerability in Nevada hectorite deposits threatens organoclay producers without captive mineral rights. Distribution runs through integrated chemical conglomerates serving automotive OEM specification chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service and formulation support contracts represent a service-attach opportunity expanding faster than base modifier volumes, as procurement teams outsource REACH documentation and dispersion optimization to qualified suppliers.
For Market Incumbents: Shield margin pools by deepening backward integration into Nevada and Turkish hectorite mining assets before competitors replicate Elementis Plc.'s raw material security model. Prioritize certification investment for ECHA nanomaterial reporting compliance to delay new entrant grade introductions pending regulatory clarity.
For New Entrants and Emerging Players: Anchor in India's PLI scheme for specialty chemicals, where Maharashtra and Gujarat infrastructure buildout outpaces domestic bentonite processing capacity. Target construction sealant procurement at regional blenders seeking to reduce import dependency from Chinese suppliers. Pursue toll-processing partnerships with existing grinding facilities to bypass bead mill capex barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across surface-treated grade production as bead mill requirements and energy-intensive calcination compress returns on mid-tier assets. Acquisition candidates should demonstrate captive mineral deposits or long-term offtake agreements with Nevada or Turkish hectorite miners. Monitor ECHA nanomaterial classification thresholds as the signal indicating when regulatory clarity will unlock new product development pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | Captive hectorite deposits in Nevada secure supply for organoclay producers against Turkish competition. |
| Surface Treatment Capacity Expansion | Bead mill investments enable premium silica grades for Stuttgart automotive clearcoat specifications. |
| Long-term Supply Agreement | Fixed-price natural gas contracts protect calcined alumina margins from European energy volatility. |
| Joint Venture with Regional Processor | Localized bentonite grinding in Gujarat serves Maharashtra infrastructure buildout under PLI incentives. |
| Green Manufacturing Transition | Renewable-powered kilns align calcined alumina production with EU Green Deal carbon neutrality timelines. |
Study Parameters
A spread of perspectives from coatings formulators, construction chemical procurement leads, mining operations managers, and automotive OEM specification engineers converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with technical directors at integrated pigment-additive suppliers and downstream blenders, validated against secondary sources including customs trade data, Cefic chemical industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up triangulation across product-grade shipment data and top-down reconciliation with end-use industry consumption patterns anchored the analytical framework.
Segmentation dimensions modeled include product type, application category, end-use industry vertical, physical form, and regional production hub across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH compliance timelines, automotive OEM specification refresh cycles, and infrastructure investment trajectories. Industry-specific forecast inputs captured EV battery thermal interface material qualification pathways and Japanese METI carbon neutrality roadmap implementation rates.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and stable automotive OEM specification continuity; material deviation in regulatory stringency or energy price trajectories would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Citric Acid Market
Additives
Hexyl Acetate Market
Additives
Shortstop Inhibitor Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Ethoxyquin Market
Additives
Surface Modifiers Market
Additives
Acrylamide Reducing Ingredients Market
Additives
Amino Acids Premixes Market
Additives
Silage Additives Market
Additives
Disodium Guanylate Market
Additives
Gluconic Acid and Derivatives Market
Additives
Viscosity Index Improvers Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
Pearlizers Market
Additives
Rosin Ester Market
Additives
Metal Modifiers Market