
 Sodium Benzoate Market | 2026-2036
Sodium Benzoate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Benzoate Market Intelligence
Asset-light toll manufacturing and third-party leasing of GMP-certified production lines is reconfiguring competitive entry barriers for mid-scale sodium benzoate suppliers. Emerald Kalama Chemical leverages its backward-integrated benzoic acid supply chain to sustain margin control across food-grade and pharmaceutical-grade streams. Wuhan Youji Holdings Ltd. anchors its position through specialized powder and granule form capabilities serving domestic Chinese food processors. Tengzhou Aolong Chemical Co., Ltd. competes on manufacturing scale in Shandong Province's chemical cluster, where feedstock access lowers unit costs.
Sodium benzoate is the sodium salt of benzoic acid (C7H5NaO2), synthesized through neutralization of benzoic acid with sodium hydroxide and typically supplied at minimum 99.0% purity for food-grade applications. It functions primarily as a broad-spectrum antimicrobial preservative effective in acidic pH environments below 4.5, inhibiting yeast, mold, and bacterial proliferation in processed goods. The food additive product category leads volume shipments globally, though pharmaceutical ingredient grades command substantially higher unit margins due to compendial testing burdens. Beverage preservation applications are growing fastest as carbonated and functional drink formulations expand in emerging markets, while paints and coatings demand remains mature with cyclical industrial exposure.
FDA food additive regulations under 21 CFR 184.1733 govern permissible use levels in US-processed foods, while REACH registration and EFSA purity standards constrain European import sourcing. China's SAMR enforces GB 2760 food safety standards that align sodium benzoate maximum usage rates with CODEX principles, creating compliance convergence for exporters. Stakeholders must monitor evolving clean-label consumer sentiment against regulatory maintenance of proven preservative safety dossiers, as this tension will determine whether natural alternative investments or conventional benzoate efficiency improvements attract capital allocation.
Market Dynamics
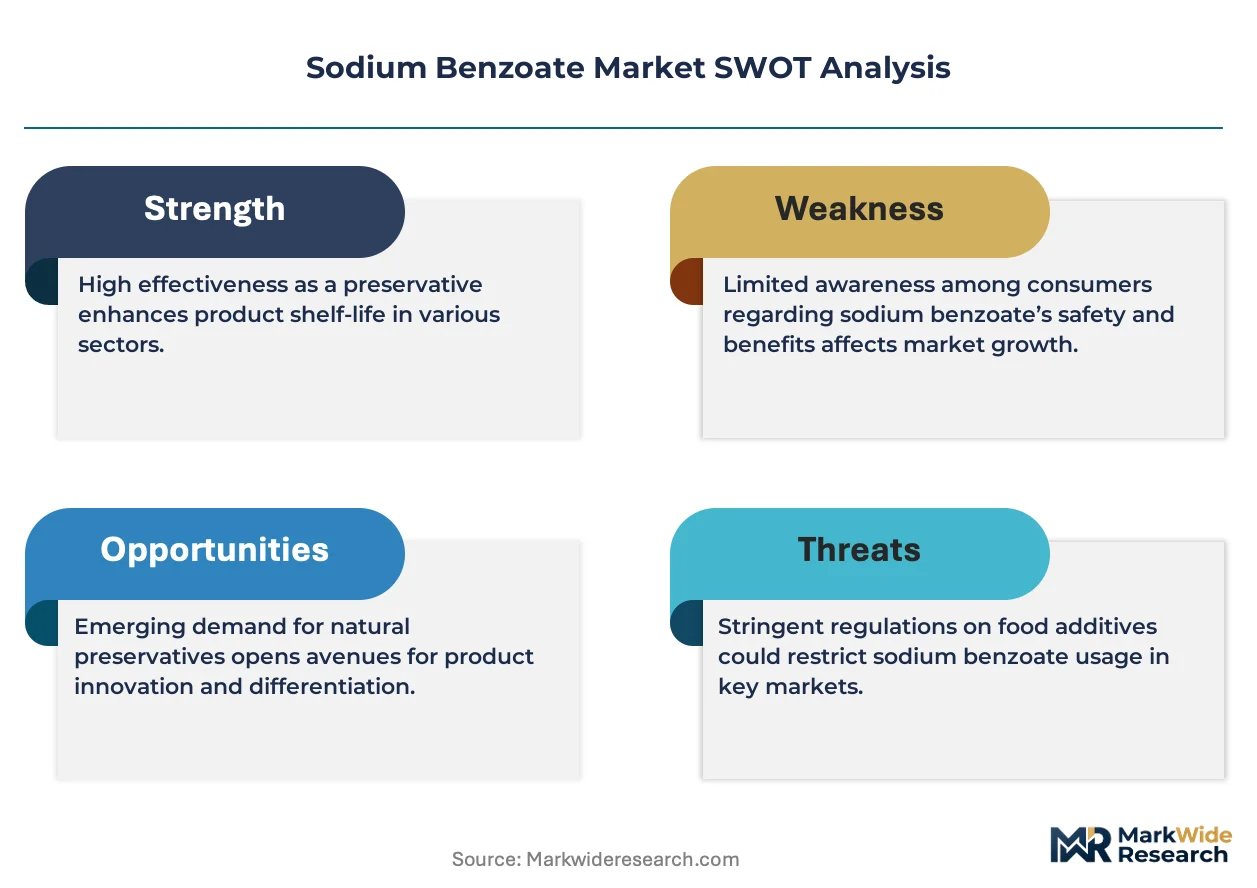
The sodium benzoate market is reconfiguring around captive benzoic acid supply chains, as food-grade and pharmaceutical-grade purity requirements diverge under tightening regulatory frameworks across multiple jurisdictions.
Growth Catalysts
- REACH registration tiers:ECHA's differentiated registration requirements for food-contact substances are consolidating import channels toward compliant suppliers, favoring established European distributors with dossier completion capabilities.
- Carbonated beverage expansion:Functional drink formulations in Southeast Asia and Latin America are extending sodium benzoate utilization rates, particularly in pH-stabilized energy drink categories.
- Shandong chemical cluster concentration:Feedstock-adjacent production in China's eastern province is compressing delivered costs for export-oriented benzoate manufacturers with captive acid supply.
Market Restraints
- Toluene price volatility:Benzoic acid synthesis depends on oxidation-grade toluene feedstock, whose refining margins fluctuate with crude differentials and aromatics demand cycles.
- Clean-label substitution pressure:Consumer packaged goods brands are reformulating with cultured dextrose, rosemary extract, and fermented preservatives to displace synthetic benzoate in visible ingredient declarations.
- Import purity friction:EFSA's tightened specifications for benzene impurity limits are rejecting marginal production from non-GMP certified facilities, constraining spot market liquidity.
Strategic Opportunities
- Pharmaceutical compendial grades:USP-NF and EP certification for injectable-grade sodium benzoate commands 3-4x food-grade unit economics, with barrier entry protected by analytical validation timelines.
- India food processing scale-up:FSSAI's alignment with CODEX additive maximum levels is enabling direct import substitution as domestic sauce, pickle, and beverage manufacturing capacity expands.
- Granule and micro-encapsulated formats:Specialized physical forms for automated dosing in high-speed bottling lines are differentiating technical service capabilities among specialty chemical distributors.
Industry Challenges
- Analytical chemistry talent scarcity:Compendial testing for pharmacopeial grades requires HPLC-UV and GC-MS expertise that competes with broader pharmaceutical quality assurance labor markets.
- Dual-use export classification complexity:Sodium benzoate's precursor status for illicit synthesis triggers end-user certification requirements that elongate order-to-delivery cycles for cross-border shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Benzoate Market |
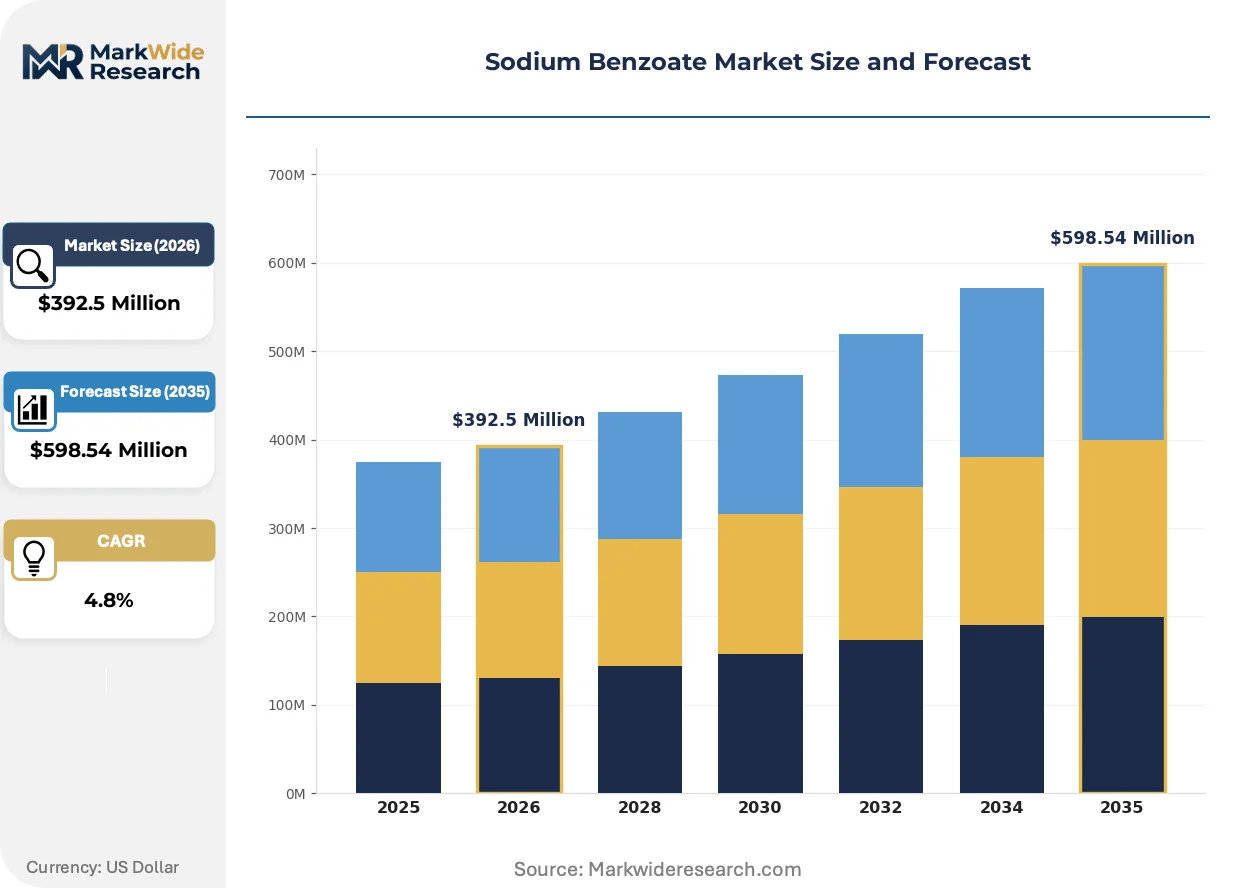
| Market Size in 2026 | $392.5 Million |
| Market Size in 2035 | $598.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Additive, Industrial Chemical, Pharmaceutical Ingredient, Cosmetic Component Application: Beverage Preservation, Food Preservation, Personal Care Products, Paints & Coatings End User: Food & Beverage Industry, Cosmetics Industry, Pharmaceuticals Industry, Chemical Manufacturing Form: Powder, Granules, Liquid, Tablets |
| Companies Covered | Tianjin Dongda Chemical Group Co., Ltd., Emerald Kalama Chemical, LANXESS AG, Ganesh Benzoplast Ltd., FBC Industries Inc., Eastman Chemical Company, Tengzhou Tenglong Food Technology Development Co., Ltd., Tengzhou Aolong Chemical Co., Ltd., Wuhan Youji Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Benzoate Market Strategic Shifts & Innovations
Preservation technology is fragmenting across synthetic efficiency and natural positioning, with formulation science bridging the gap through pH management and synergistic antioxidant systems.
Continuous flow neutralization reactors are replacing batch benzoic acid conversion. Mid-scale Indian and Brazilian food processors are adopting these systems to reduce solvent carryover and energy intensity. The technology is migrating from pharmaceutical fine chemical applications into commodity food-grade production, compressing capital recovery periods for toll manufacturers.
EFSA's 2023 re-evaluation of benzoic acid and its salts imposed revised exposure assessments that tightened acceptable daily intake calculations. European beverage formulators are responding with reduced dosage rates and acidulant substitution to maintain antimicrobial efficacy. Low-pH functional drink categories face the steepest compliance recalibration, driving joint supplier-customer formulation development programs.
Ingredient sourcing decisions now prioritize supplier audit transparency over spot price minimization. North American and Western European packaged food manufacturers are consolidating vendor lists to three approved benzoate suppliers per region, replacing the previous five-to-seven sourcing pattern. This concentration is most visible in private-label retail supply chains, where retailer responsible sourcing scorecards weight certification documentation above unit cost.
Sodium Benzoate Market Segmentation
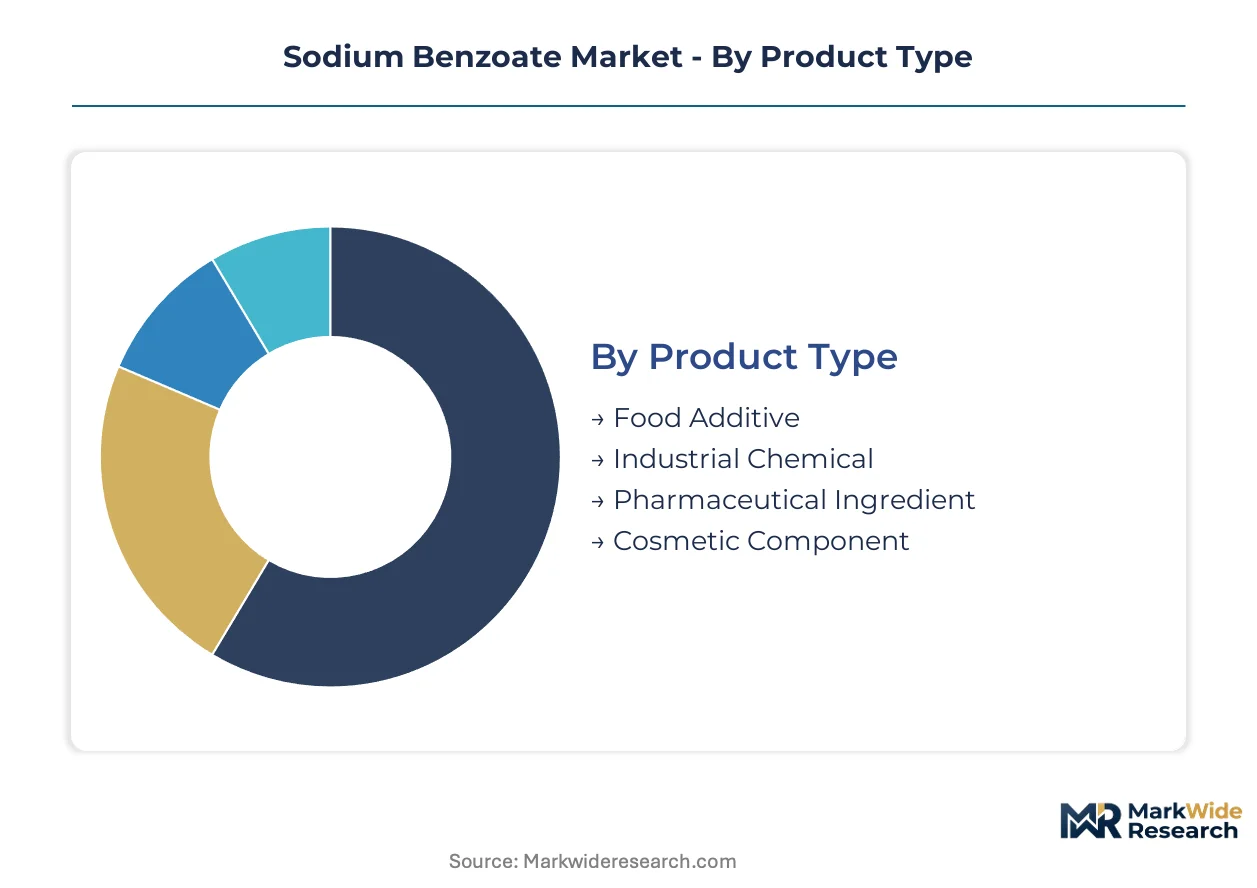
Sodium benzoate segmentation reveals divergent margin structures and regulatory burdens across purity grades. Pharmaceutical and food additive streams operate on fundamentally different commercial timelines and certification requirements.
Product Type:
Food additive grades turn inventory fastest through beverage and sauce manufacturing channels, while pharmaceutical grades require extended analytical validation cycles that stretch working capital deployment.
- Food Additive:Minimum 99.0% purity specification with antimicrobial efficacy in pH environments below 4.5. Demand concentrates in carbonated beverage bottling facilities across Southeast Asia and Latin America where acidulant-stabilized formulations dominate. FDA's 21 CFR 184.1733 framework governs permissible use levels, creating compliance convergence for exporters.
- Pharmaceutical Ingredient:USP-NF and EP compendial certification with HPLC-UV and GC-MS validation protocols. Injectable-grade production commands premium unit economics protected by analytical chemistry talent scarcity and extended dossier preparation timelines.
- Industrial Chemical:Technical-grade specifications serving paints and coatings manufacturers with cyclical demand exposure to construction activity.
- Cosmetic Component:Preservative function in personal care formulations regulated under EU REACH cosmetic ingredient frameworks.
Food additive grades dominate installed base volume. Pharmaceutical ingredient certification is where expansion concentrates for margin-focused suppliers.
Application:
Cost tier stratification separates commodity beverage preservation from specialized pharmaceutical and personal care applications with divergent testing burdens.
- Beverage Preservation:Carbonated and functional drink formulations in emerging markets drive fastest volume expansion. pH-stabilized energy drink categories in Southeast Asia extend utilization rates through acidulant synergy systems.
- Food Preservation:Processed sauces, pickles, and condiments represent mature demand with clean-label substitution pressure from cultured dextrose and fermented alternatives.
- Personal Care Products:Cosmetic preservative function in lotions and creams regulated through ECHA REACH registration tiers.
- Paints & Coatings:Technical-grade consumption tied to industrial construction cycles with mature, price-sensitive procurement patterns.
Beverage preservation dominates installed base growth velocity. Food preservation is where substitution risk concentrates.
End User:
Customer type segmentation maps directly to certification requirements and supplier audit intensity levels.
- Food & Beverage Industry:High-volume procurement with consolidated vendor lists narrowing to three approved suppliers per region in North American and Western European retail supply chains.
- Pharmaceuticals Industry:Compendial-grade demand with 3-4x food-grade unit economics and barrier entry through analytical validation timelines.
- Cosmetics Industry:REACH-registered sourcing with responsible sourcing scorecard weighting above spot price minimization.
- Chemical Manufacturing:Technical-grade offtake for downstream derivative production with feedstock-adjacent procurement preferences.
Food and beverage industry dominates installed base volume. Pharmaceutical industry is where margin expansion concentrates.
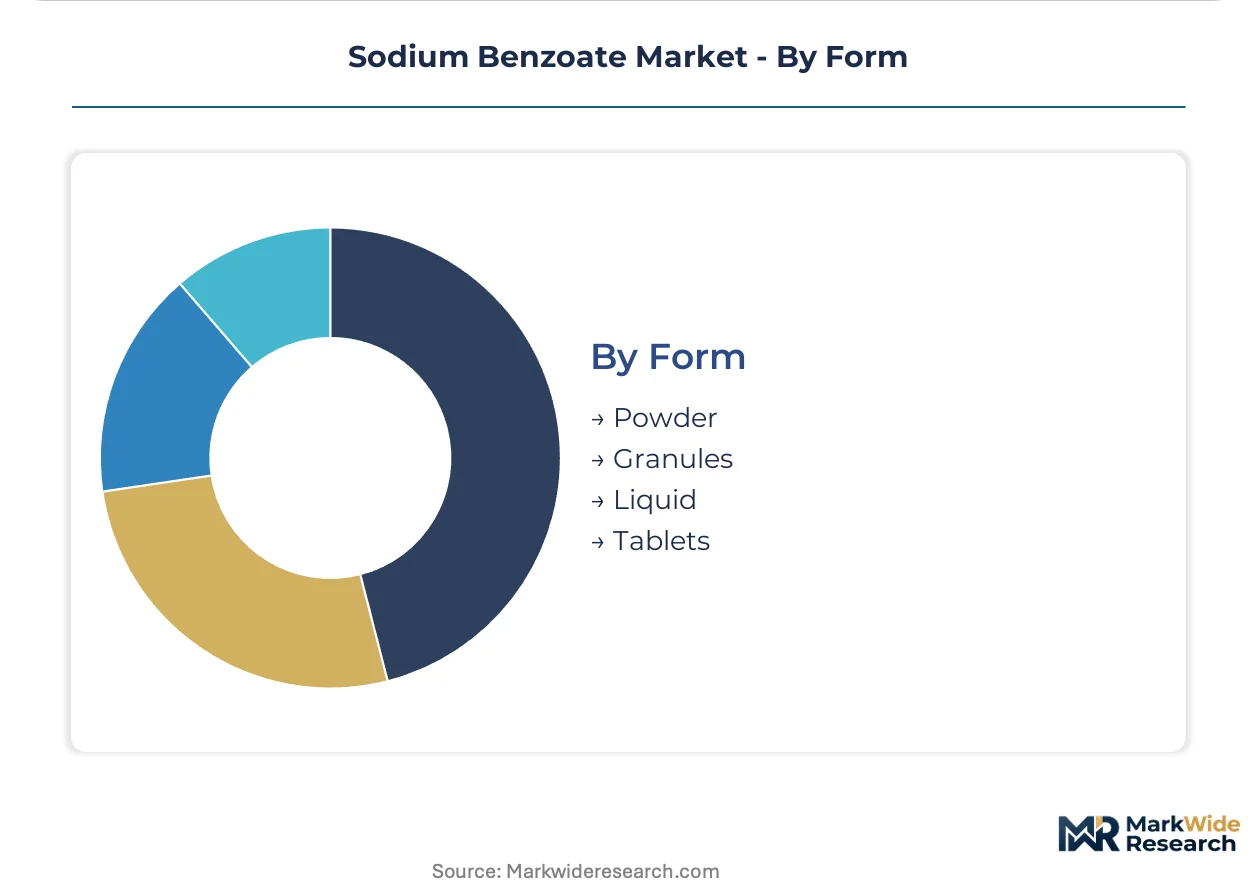
Form:
Physical format selection determines dosing automation compatibility and technical service differentiation potential.
- Powder:Standard bulk format for general food preservation with established handling infrastructure across processing facilities.
- Granules:Specialized physical form for automated high-speed bottling lines differentiating Wuhan Youji Holdings' technical service capabilities.
- Liquid:Pre-dissolved solutions reducing solvent carryover in continuous flow neutralization systems adopted by mid-scale Indian and Brazilian processors.
- Tablets:Compressed format for pharmaceutical compounding with precise dosage control requirements.
Powder format dominates installed base volume. Granule and liquid forms are where automation-driven expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows are rebalancing as Shandong Province's benzoic acid clusters reduce China's import dependency while European beverage bottlers consolidate sourcing toward REACH-registered suppliers. The United States maintains net importer status for pharmaceutical-grade material. India and Brazil are scaling domestic food processing capacity.
China
Carbonated beverage production and sauce manufacturing drive food-grade consumption. SAMR enforces GB 2760 standards aligning with CODEX principles for additive maximum levels. Shandong Province's chemical cluster hosts captive benzoic acid facilities that compress delivered costs for export-oriented sodium benzoate manufacturers.
United States
Pharmaceutical compounding and beverage preservation sustain import demand for high-purity grades. FDA's 21 CFR 184.1733 framework governs permissible use levels in processed foods. New Jersey and Pennsylvania pharmaceutical corridors concentrate USP-NF certified sourcing for injectable-grade applications.
Germany
EFSA's tightened benzene impurity specifications are rejecting marginal imports from non-GMP facilities. REACH registration tiers consolidate distribution toward dossier-compliant suppliers. Leverkusen and Ludwigshafen chemical hubs anchor pharmaceutical-grade formulation demand for EU compendial markets.
India
FSSAI's CODEX-aligned additive regulations enable direct import substitution as domestic sauce and pickle manufacturing scales. Beverage bottling expansion in Maharashtra and Gujarat drives granule-format procurement for automated dosing lines. Mumbai-Pune industrial corridor concentrates food processing capacity buildout.
Brazil
Mid-scale processors adopt continuous flow neutralization systems to reduce solvent carryover. ANVISA's preservative registration frameworks align with Mercosur technical standards. São Paulo state's beverage manufacturing belt extends sodium benzoate utilization in pH-stabilized energy drink categories.
Sodium Benzoate Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with feedstock-adjacent production economics. The vendor base organizes around three strategic archetypes: backward-integrated benzoic acid producers, toll manufacturers with GMP-certified asset access, and regional distributors with dossier completion capabilities. Competitive moves concentrate on captive acid supply construction and pharmaceutical compendial certification timelines.
Within the integrated production tier, Emerald Kalama Chemical exemplifies margin control through captive benzoic acid supply chain positioning. Wuhan Youji Holdings Ltd. occupies a specialist position in automated dosing-compatible physical formats. Tengzhou Aolong Chemical Co., Ltd. represents scale-driven manufacturing concentration within Shandong Province's feedstock-advantaged chemical cluster.
| Leading Market Players |
|---|
| Tianjin Dongda Chemical Group Co., Ltd. |
| Emerald Kalama Chemical |
| LANXESS AG |
| Ganesh Benzoplast Ltd. |
| FBC Industries Inc. |
| Eastman Chemical Company |
| Tengzhou Tenglong Food Technology Development Co., Ltd. |
| Tengzhou Aolong Chemical Co., Ltd. |
| Wuhan Youji Holdings Ltd. |
| Others |
Cost & Logistics Intelligence
Shandong Province's benzoic acid cluster concentration anchors downstream margin pools in pharmaceutical-grade certification tiers, where USP-NF and EP validation protocols command substantial premiums over commodity food-additive streams. Toluene oxidation economics at the feedstock level transmit directly into sodium benzoate pricing architecture, with captive acid producers capturing margin that toll manufacturers forfeit to spot market volatility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with pharmaceutical compendial grades separating from food-additive specifications through analytical validation burdens. Price differentiation centers on certification tier and volume scale, with injectable-grade USP-NF material commanding multiples of technical-grade industrial supply. Pricing pressure stems from toluene feedstock volatility and clean-label substitution campaigns in Western European retail supply chains. Mid-scale beverage processors in emerging markets exhibit highest price sensitivity, while pharmaceutical compounders prioritize supply security over unit cost minimization.
Supply Chain Analysis
Toluene feedstock availability shapes production economics, with oxidation-grade material sourcing from petroleum refining complexes in China, South Korea, and the United States. Sodium benzoate manufacturing draws from benzoic acid, sodium hydroxide, and specialized analytical reagents for compendial testing. Single-source vulnerability concentrates in Shandong Province's chemical cluster, where environmental compliance disruptions ripple through global supply. Distribution runs through specialty chemical distributors with REACH dossier completion capabilities serving European pharmaceutical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sodium benzoate market tracks a cyclical recovery pattern as toluene refining margins compress and pharmaceutical-grade demand stabilizes inventory positions. Construction activity in emerging Asian economies and beverage bottling expansion in Latin America provide demand-side ballast against feedstock volatility.
For Market Incumbents: Insulate margin structures through backward integration into captive benzoic acid capacity and accelerated pharmaceutical compendial certification timelines. Clean-label substitution pressure from cultured dextrose and fermented alternatives threatens food-additive revenue streams; defensive investment in granule-format technical capabilities for automated dosing lines preserves technical service differentiation against toll manufacturing entrants.
For New Entrants and Emerging Players: India's Maharashtra-Gujarat beverage manufacturing belt offers underpenetrated procurement consolidation opportunities as FSSAI alignment with CODEX principles enables direct import substitution. Pharmaceutical-grade toll manufacturing with GMP-certified asset leasing represents the most penetrable segment, with analytical chemistry talent scarcity protecting incumbent positions less than in fully integrated supply chains. Joint formulation development programs with pH-stabilized energy drink brands provide go-to-market traction.
For Investors and Strategic Acquirers: Capital is best deployed toward REACH-registered distributors with dossier completion capabilities and established European pharmaceutical corridor relationships. Long-term viability over a multi-year horizon favors asset-light platforms with technical service differentiation over commodity scale players exposed to Shandong cost compression. The signal to watch is EFSA benzene impurity specification tightening, which would accelerate vendor list consolidation and strand non-GMP certified capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Benzoic Acid | Captive feedstock supply insulates margin control against toluene volatility and refinery margin cycles. |
| Pharmaceutical Compendial Certification | USP-NF and EP validation unlocks 3-4x unit economics in injectable-grade applications with protected analytical barriers. |
| Granule Format Capacity Expansion | Automated dosing compatibility differentiates technical service capabilities for high-speed beverage bottling lines. |
| REACH Registration Completion | ECHA dossier compliance consolidates European distribution channels toward registered suppliers and rejects marginal imports. |
| Continuous Flow Reactor Adoption | Neutralization technology migration from pharmaceutical fine chemicals reduces solvent carryover and energy intensity for mid-scale processors. |
Research Approach
Initial hypotheses were tested against primary input from plant managers at benzoic acid facilities, procurement leads at downstream beverage and pharmaceutical OEMs, distribution channel partners with REACH dossier capabilities, and technical R&D directors specializing in preservation formulation. These perspectives were refined against secondary validation from customs and trade flow databases, Cefic and ACC chemical industry reports, SEC 10-K filings from listed specialty chemical producers, and EFSA exposure assessment documentation. Bottom-up volume modeling across grade tiers and end-use segments was triangulated with top-down market sizing from production capacity and trade flow analysis.
Demand-supply balance dynamics across the analysis window were modeled through segmented projection frameworks incorporating grade tier stratification, end-use industry growth differentials, packaging format evolution, and regional production hub competitiveness. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and substitution elasticity parameters. Forecast inputs included toluene refining margin trajectories, EFSA re-evaluation implementation timelines, and FSSAI regulatory alignment progress in India.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Shandong cluster producers or accelerated pharmaceutical certification investments by Indian toll manufacturers would shift outcomes beyond modeled ranges. Cross-checking against customs trade data and pharmaceutical import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Low Melt Inclusions Market
Additives
Defoaming Coating Additives Market
Additives
Asia Pacific Plastic Additives Market
Additives
Benzoates Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Disodium Guanylate Market
Additives
Impact Modifier Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Nucleating and Clarifying Agents Market
Additives
Shortstop Inhibitor Market
Additives
Tackifier Market
Additives
Citric Acid Market
Additives
Surface Modifiers Market
Additives
Pearlizers Market
Additives
Sodium Metabisulfite Market
Additives
Foundry Additives Market