
 Butyl Reclaimed Rubber Market | 2026-2036
Butyl Reclaimed Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Butyl Reclaimed Rubber Market Analysis
Tire manufacturing is broadening its reclaimed butyl rubber intake beyond inner tubes into curing bladders and tire liner compounds. HUXAR leverages European regulatory tailwinds to sustain premium-grade reclaim output for automotive OEMs. GRP Ltd. anchors South Asian supply chains through backward integration into crumb rubber sourcing. Swani Rubber Industries specializes in compounded rubber grades that compete on consistency with virgin butyl feedstock.
Butyl reclaimed rubber consists of devulcanized butyl polymer recovered from used inner tubes, industrial gloves, and roofing membranes, typically retaining 40-55% of original elastomeric properties after thermal-mechanical processing. Its primary commercial purpose is cost reduction in gas-impermeable rubber formulations where full virgin polymer performance is unnecessary. Reclaimed Butyl Rubber leads product type revenue due to established tire industry certification pathways, while Blend grades capture fastest volume growth as compounders seek to optimize cost-performance ratios. The Tires end user segment occupies the dominant margin pool, though Automotive Components is reshaping procurement patterns as sealant and gasket makers qualify reclaim grades for under-hood applications.
EPA industrial waste guidelines in the United States, REACH substance restrictions in Europe, and BIS certification mandates in India collectively elevate product standards and filter subscale reclaim producers from approved supplier lists. The EU F-Gas Regulation indirectly reinforces butyl reclaim demand by tightening specifications for gas-barrier materials in HVAC and automotive systems. Stakeholders must monitor evolving polymer purity thresholds across jurisdictions to anticipate which reclaim grades will retain qualified supplier status.
Market Dynamics
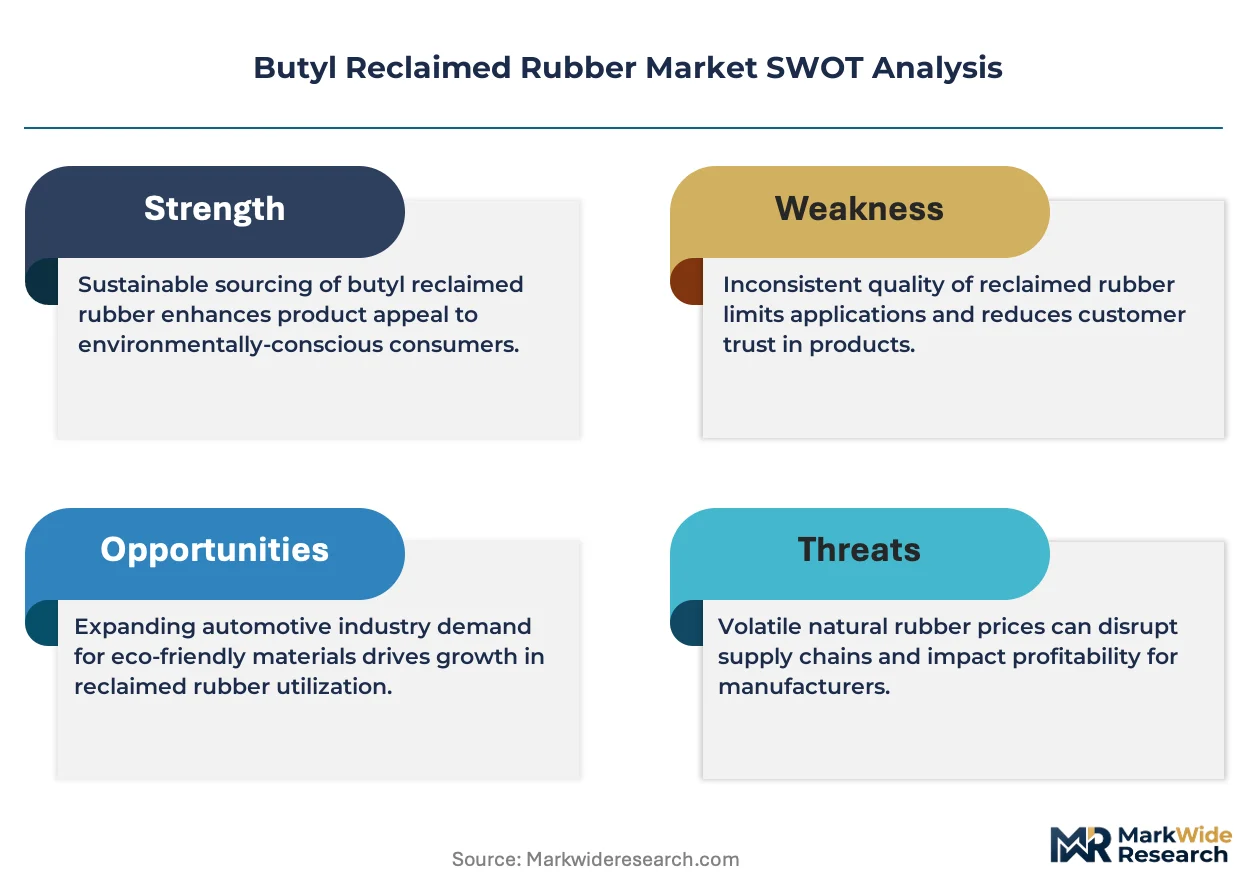
Extended producer responsibility frameworks are compressing virgin polymer margins and forcing compounders to certify reclaimed feedstock for gas-barrier applications previously reserved for virgin butyl.
Growth Catalysts
- REACH substance restrictions:ECHA's tightening thresholds for SVHCs in automotive rubber are disqualifying uncertified reclaim producers from OEM supplier lists.
- Tire liner qualification pathways:Inner tube reclaim now meets curing bladder specifications, opening secondary demand from retread operations.
- India:BIS quality guidelines are formalizing domestic reclaim grades, enabling tire makers to substitute imported virgin butyl with local reclaim.
Market Restraints
- Crumb rubber supply volatility:Used inner tube collection rates fluctuate with retread cycle timing, compressing reclaim plant utilization.
- Devulcanization energy costs:Thermal-mechanical processing requires sustained heat input, exposing margins to natural gas price swings.
- EPDM substitution in HVAC:Specifiers are qualifying non-butyl membranes for gas-barrier roles, capping reclaim price premiums.
Strategic Opportunities
- Automotive under-hood gaskets:Sealant makers are qualifying reclaim grades for fluid-resistant compounds, expanding beyond tire applications.
- EU F-Gas Regulation:Tightened specifications for refrigerant barrier materials are redirecting HVAC compounders toward certified reclaim sources.
- Roofing membrane recovery:Post-consumer EPDM-butyl blends from commercial buildings represent untapped feedstock for specialized reclaim grades.
Industry Challenges
- Polymer purity certification timelines:BIS and REACH documentation requirements delay new reclaim grade commercialization by 12-18 months.
- Devulcanization chemist scarcity:Formulation expertise for property retention in thermal processing is concentrated among retiring specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butyl Reclaimed Rubber Market |
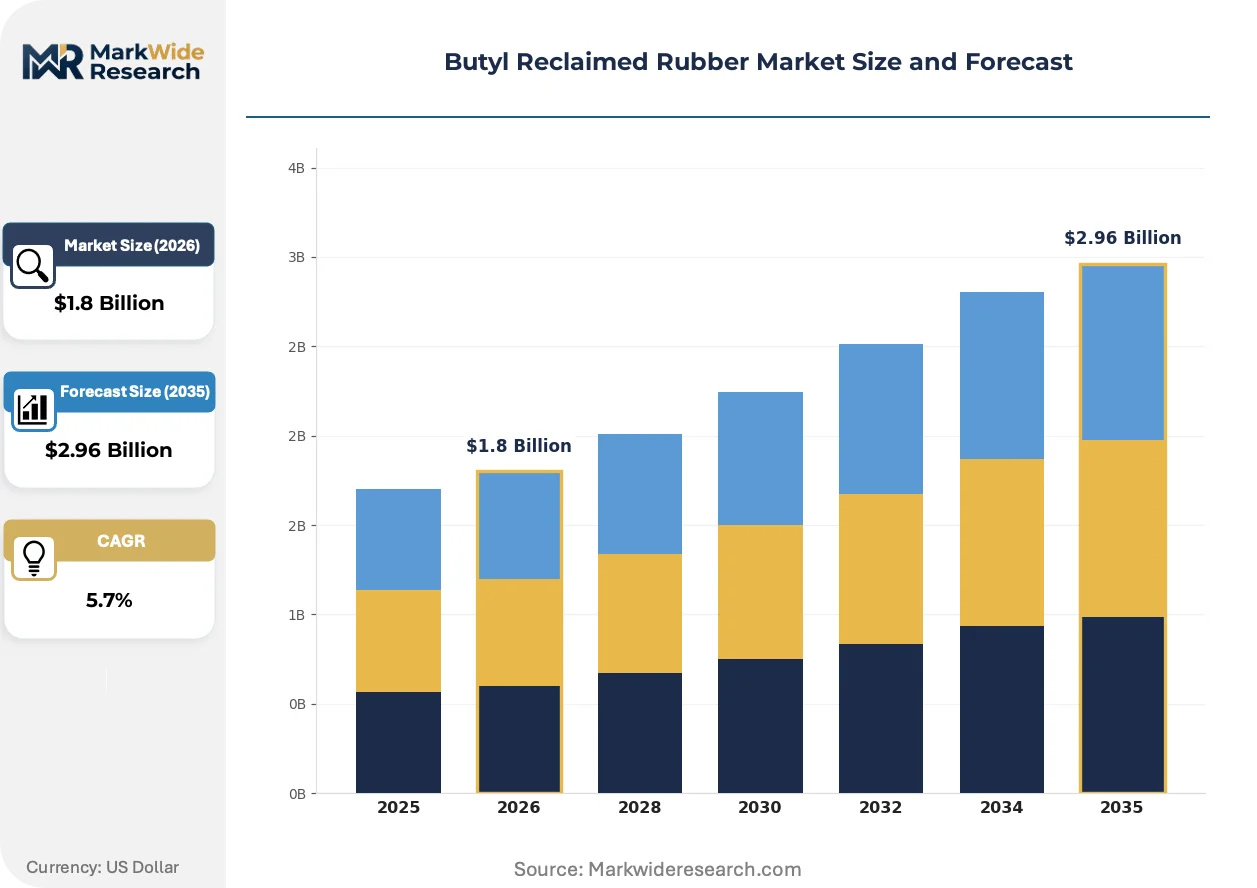
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reclaimed Butyl Rubber, Reclaimed Natural Rubber, Blend, Compounded Rubber End User: Tires, Automotive Components, Footwear, Industrial Products Application: Manufacturing, Recycling, Construction, Sealants Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | HUXAR, High Tech Reclaim Pvt. Ltd., GRP Ltd., Swani Rubber Industries, Allcock & Sons Ltd., Fishfa Rubbers Ltd., SNR Reclamations Pvt. Ltd., Star Polymers Inc., Rolex Reclaim Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butyl Reclaimed Rubber Market Emerging Trajectories
Continuous devulcanization reactor design is compressing processing cycles while regulatory pressure on virgin polymer sourcing intensifies qualification demands for reclaimed alternatives.
Continuous thermal-mechanical reactors are replacing batch kettle processing for property consistency. Tire compounders in Germany and France are adopting these systems to meet REACH documentation requirements. The technology is integrating real-time rheology monitoring that reduces batch-to-batch variation below 5%.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubber articles are tightening testing protocols. Compounders must now demonstrate sub-ppm PAH levels in reclaim destined for consumer contact applications. Automotive sealant manufacturers in Italy and Spain are accelerating supplier audits to preempt compliance gaps.
Compounders are consolidating reclaim purchases through qualified supplier programs rather than spot markets. Tier-1 automotive suppliers are disqualifying uncertified reclaim sources from RFQ participation. This concentration is most visible in Germany, where KBA type-approval documentation now requires traceable reclaim chain-of-custody records.
Butyl Reclaimed Rubber Market Segmentation
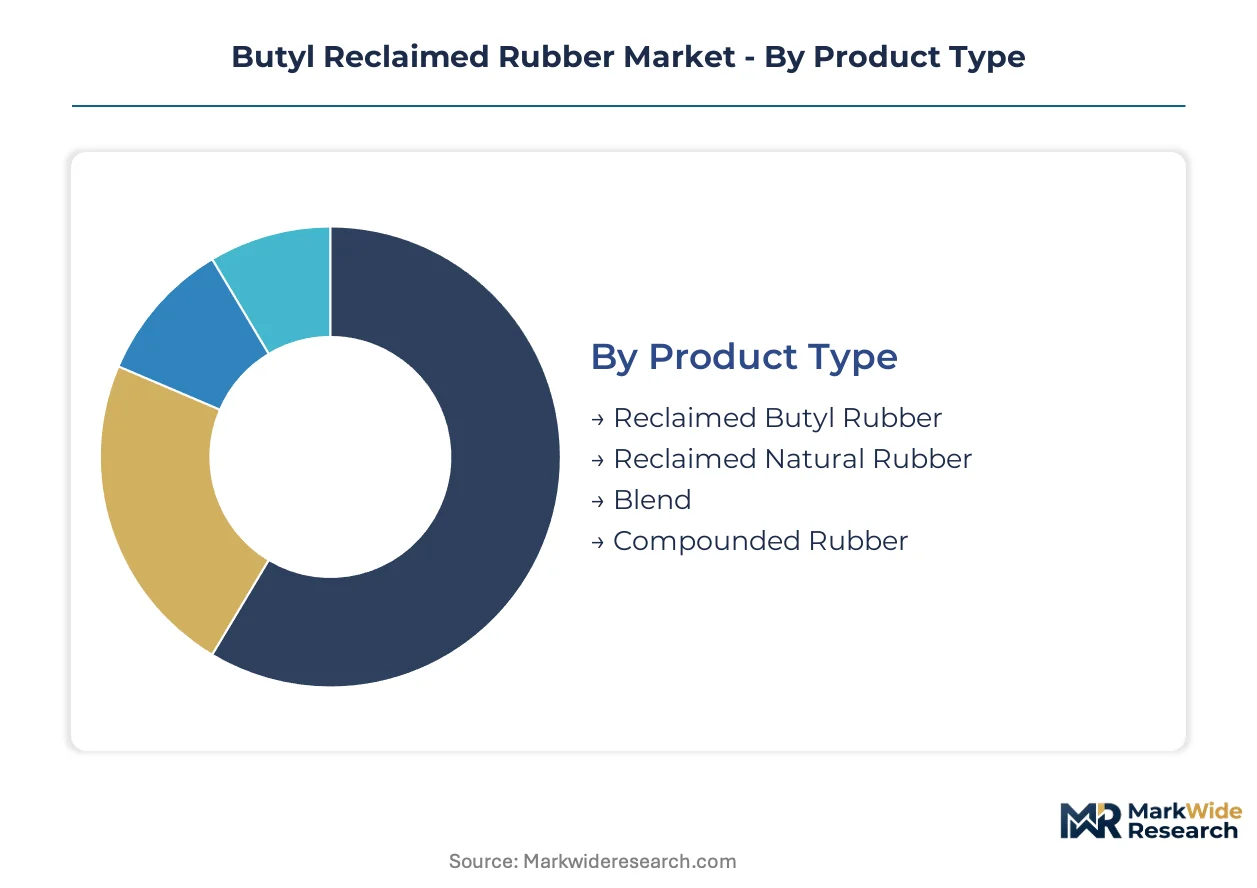
Segmentation in butyl reclaimed rubber reflects divergent technical requirements across gas-barrier applications and cost-sensitive formulations. Specification tiers separate tire-grade certified material from general-purpose reclaim used in construction and industrial goods.
Product Type:
Standardization dominates at the commodity end while compounded grades demand formulation partnerships with end-users.
- Reclaimed Butyl Rubber:Devulcanized polymer recovered from used inner tubes and curing bladders, retaining 40-55% of original elastomeric properties. Tire manufacturers in India and Germany concentrate procurement here, driven by BIS certification pathways and KBA type-approval documentation that lock in supplier qualification status.
- Blend:Mixed polymer formulations combining butyl reclaim with natural rubber or EPDM to optimize cost-performance ratios. Compounders seeking REACH Annex XVII compliance for PAH thresholds are migrating procurement toward certified blend suppliers with documented chain-of-custody records.
- Reclaimed Natural Rubber:Recovered isoprene polymer from latex waste streams with distinct rheological properties from butyl grades.
- Compounded Rubber:Pre-formulated reclaim with curatives and fillers added by the producer, competing on batch-to-batch consistency with virgin feedstock.
Most installed capacity flows through Reclaimed Butyl Rubber. Expansion is steepest in Blend.
End User:
Margin concentration follows gas-impermeability requirements, with tire applications commanding premium certification costs.
- Tires:Inner liner and curing bladder compounds where reclaim substitutes for virgin butyl in cost-sensitive formulations. Retread operations in France and Spain are qualifying reclaim grades previously reserved for new tire production, opening secondary demand channels.
- Automotive Components:Under-hood gaskets, seals, and HVAC barrier materials where fluid resistance specifications are tightening. The EU F-Gas Regulation is redirecting refrigerant system compounders toward certified reclaim sources with traceable purity documentation.
- Footwear:Soling compounds and waterproofing layers where reclaim cost advantages outweigh performance premiums.
- Industrial Products:Conveyor belts, hoses, and molded goods with less stringent elastomeric property requirements.
Volume leadership sits with Tires. Automotive Components is climbing the fastest as sealant makers expand reclaim qualification.
Application:
Process stage determines specification intensity, with manufacturing applications demanding pre-certification versus post-consumer recovery streams.
- Manufacturing:Direct integration into virgin compound production at tire and automotive sealant plants. Continuous devulcanization reactor adoption in Germany is compressing processing cycles while meeting REACH documentation requirements for real-time rheology monitoring.
- Recycling:Post-consumer collection and crumb rubber preprocessing before devulcanization. Used inner tube supply volatility from retread cycle timing compresses reclaim plant utilization rates.
- Construction:Roofing membrane and waterproofing applications with lower elastomeric property thresholds.
- Sealants:Caulk and adhesive formulations where gas-barrier properties create niche demand.
Manufacturing commands the dominant share of qualified reclaim offtake. Recycling is gaining share fastest as EPR frameworks mandate producer responsibility for end-of-life collection.
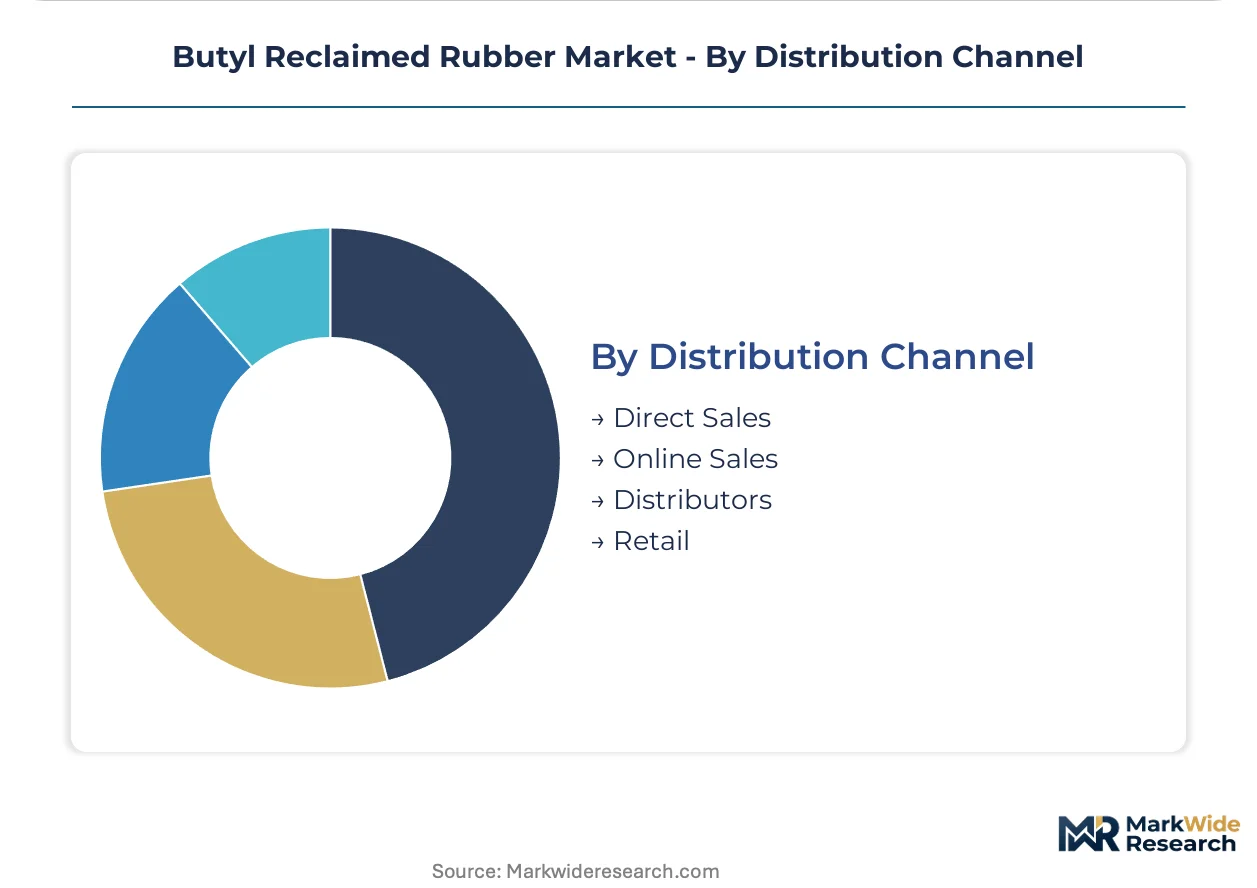
Distribution Channel:
Relationship depth separates direct supply chains for certified grades from transactional spot markets for uncertified material.
- Direct Sales:Long-term contracts between reclaim producers and tire compounders with locked-in volume and specification commitments. Tier-1 automotive suppliers in Italy are disqualifying uncertified sources from RFQ participation, consolidating purchases through qualified supplier programs.
- Distributors:Regional stockists serving mid-size compounders without direct mill relationships. Spot market exposure here creates price volatility when crumb rubber feedstock costs swing with natural gas prices.
- Online Sales:Digital procurement platforms for standardized grades with published technical datasheets.
- Retail:Small-volume sales to workshops and specialty compounders.
Direct Sales carries the majority of certified reclaim volume. Distributors are expanding fastest in India as domestic tire producers scale local sourcing of butyl reclaim feedstock.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial belt around Cologne and Leverkusen anchors the European reclaim rubber sector, where tire compounders and automotive sealant manufacturers cluster near major polymer research centers. REACH enforcement through ECHA continues tightening purity thresholds for gas-barrier applications. The analysis tracks qualification dynamics across five strategic markets.
Germany
KBA type-approval documentation now mandates traceable chain-of-custody records for reclaim used in tire inner liners. ECHA's SVHC threshold reductions are disqualifying uncertified producers from OEM supplier lists. Continuous devulcanization reactor adoption in the Cologne-Leverkusen corridor is compressing processing cycles while meeting real-time rheology monitoring requirements.
India
Domestic tire producers in Gujarat and Maharashtra are scaling local sourcing of butyl reclaim feedstock to substitute imported virgin polymer. BIS quality guidelines formalized in 2024 enable certification pathways previously blocked by specification gaps. Mumbai-Pune industrial clusters host compounders integrating certified reclaim into curing bladder formulations for export markets.
United States
EPA industrial waste guidelines elevate product standards and filter subscale reclaim producers from approved supplier lists. Retread operations in Ohio and Tennessee are qualifying reclaim grades previously reserved for new tire production. The Southeast manufacturing corridor sees compounders consolidating purchases through qualified supplier programs rather than spot markets.
France
Extended producer responsibility frameworks compress virgin polymer margins and force compounders to certify reclaimed feedstock for gas-barrier applications. ANSM oversight of consumer contact applications tightens PAH testing protocols below REACH baseline requirements. Lyon-based automotive sealant manufacturers are accelerating supplier audits to preempt compliance gaps in under-hood gasket specifications.
Italy
Tier-1 automotive suppliers in Turin and Milan are disqualifying uncertified reclaim sources from RFQ participation. The EU F-Gas Regulation redirects HVAC compounders toward certified reclaim sources with documented purity for refrigerant barrier materials. Emilia-Romagna industrial districts see sealant makers qualifying reclaim grades for fluid-resistant compounds beyond traditional tire applications.
Butyl Reclaimed Rubber Market Vendor Landscape
Capacity expansion dominates the current landscape as producers install continuous devulcanization reactors to meet REACH documentation requirements. The vendor base organizes around three tiers: integrated reclaim-to-compound specialists, crumb rubber preprocessors with backward integration, and regional toll processors serving spot markets. Strategic archetypes include certification-first premium suppliers, cost-optimized volume players, and niche blend formulators. M&A activity concentrates in India and Germany, while technology licensing agreements spread continuous reactor designs across European facilities.
Among European reclaim specialists, HUXAR occupies a position exemplifying the certification-first archetype for automotive OEM supply. GRP Ltd. and Swani Rubber Industries represent the integrated model, with the former anchoring South Asian supply chains and the latter specializing in compounded grades competing on batch consistency. High Tech Reclaim Pvt. Ltd. sits within India's expanding tier of domestic producers scaling to meet BIS quality guidelines.
| Leading Market Players |
|---|
| HUXAR |
| High Tech Reclaim Pvt. Ltd. |
| GRP Ltd. |
| Swani Rubber Industries |
| Allcock & Sons Ltd. |
| Fishfa Rubbers Ltd. |
| SNR Reclamations Pvt. Ltd. |
| Star Polymers Inc. |
| Rolex Reclaim Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between REACH-compliant reclaim and uncertified spot material splits pricing power between qualified suppliers and toll processors, with premium tiers capturing long-term automotive contracts while commodity grades trade on crumb rubber input costs and natural gas processing spreads.
Pricing Analysis
Natural gas pass-through dominates thermal-mechanical processing economics, exposing margins to energy cost swings across European and Indian production clusters. Three-tier pricing structure across premium certified, standard BIS-compliant, and economy spot grades reflects documentation burden and batch consistency investment. Price erosion runs through economy tiers as crumb rubber collection volatility compresses reclaim plant utilization. Tier-1 automotive suppliers exhibit lowest price sensitivity due to KBA type-approval lock-in, while mid-size compounders in distributor channels face spot market exposure.
Supply Chain Analysis
Regional distribution centers in Cologne-Leverkusen, Mumbai-Pune, and Ohio-Tennessee anchor hub-and-spoke patterns for certified reclaim offtake. Germany, India, and the United States concentrate devulcanization capacity, with feedstock sourcing drawing from retread cycle timing in each market. Used inner tube collection, natural gas supply, and specialty devulcanization chemist availability constitute critical input dependencies. Single-source vulnerability sits with retiring formulation specialists concentrated among European processors. Distribution runs through direct mill relationships for certified grades, with spot-market distributors serving uncertified demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH SVHC threshold reductions and BIS quality guidelines mechanically expand qualified reclaim demand regardless of virgin polymer price cycles.
For Market Incumbents: Lock in crumb rubber preprocessing capacity through backward integration into collection networks before retread cycle volatility consolidates feedstock access. Invest in continuous devulcanization reactor deployment to compress processing cycles and meet real-time rheology documentation requirements for KBA type-approval retention. EPDM substitution in HVAC applications threatens butyl reclaim price premiums in non-tire segments.
For New Entrants and Emerging Players: Begin with roofing membrane recovery streams in commercial building retrofit corridors, where post-consumer EPDM-butyl blends represent uncertified feedstock outside incumbent collection networks. Automotive under-hood gasket qualification offers the most penetrable application expansion, with fluid-resistant compound specifications tightening faster than supplier audit capacity. Partner with Tier-2 automotive sealant makers seeking traceable chain-of-custody documentation for EU F-Gas Regulation compliance.
For Investors and Strategic Acquirers: Consolidation pressure builds where BIS and REACH certification timelines stretch 12-18 months and retiring devulcanization chemists concentrate expertise among legacy European producers. Five-to-ten-year viability favors integrated reclaim-to-compound specialists with captive crumb rubber sourcing and documented automotive OEM relationships. Watch for ECHA SVHC threshold announcements as inflection indicators for disqualification-driven supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crumb Rubber Collection | Captive feedstock sourcing insulates margins from retread cycle volatility and collection rate swings. |
| Continuous Devulcanization Reactor Installation | Real-time rheology monitoring reduces batch variation below REACH documentation thresholds for automotive qualification. |
| BIS Certification Pathway Investment | Formalized quality guidelines enable Indian tire makers to substitute imported virgin butyl with domestic reclaim. |
| Automotive Under-Hood Gasket Qualification | EU F-Gas Regulation redirects HVAC compounders toward certified reclaim sources with traceable purity documentation. |
| Long-Term Direct Supply Agreements | Tier-1 automotive suppliers in Germany and Italy disqualify uncertified sources from RFQ participation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tire compounder procurement leads, automotive sealant R&D directors, reclaim plant operations managers, and BIS certification auditors with secondary validation. Customs and trade data, ECHA substance restriction filings, BIS guideline publications, and automotive OEM supplier documentation formed the secondary foundation. Bottom-up capacity and offtake modeling triangulated against top-down end-use demand segmentation.
Segment-weighting across product type, end user, and application dimensions anchored the analytical framework across the projection horizon. Reclaimed Butyl Rubber, Blend, and Compounded Rubber categories carried distinct certification burden assumptions. Tire, Automotive Components, and Industrial Products end-use segments modeled divergent gas-barrier specification intensity. CAGRs derived from elasticity-adjusted substitution rates for virgin polymer displacement, with continuous reactor adoption curves and EPR framework implementation timelines as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption to natural gas supply, abrupt EPDM formulation breakthroughs displacing butyl in HVAC applications, and unannounced ECHA SVHC threshold accelerations. Forecasts reflect documented assumptions on crumb rubber collection rate stability and devulcanization energy efficiency trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Elastomers Market
Rubber
Europe Silicone Rubber Market
Rubber
Plastomers Market
Rubber
Rubber Molding Market
Rubber
Europe Rubber Hose Market
Rubber
Metallurgical Rubber Roller Market
Rubber
Polybutadiene Market
Rubber
Rubber Foam Materials Market
Rubber
Solution Styrene Butadiene Rubber (S-SBR) Market
Rubber
Global Crumb Rubber Market
Rubber
Europe Neoprene Market
Rubber
Oil Saver Rubber Market
Rubber
Nitrile Butadiene Rubber (NBR) Latex Market
Rubber
Rubber Roller Cleaner Market
Rubber
Global Rubber Additives Market
Rubber
Flexible Rubber Sheets Market