
 Zinc Dialkyldithiophosphates Additive Market | 2026-2036
Zinc Dialkyldithiophosphates Additive Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Dialkyldithiophosphates Additive Market Intelligence
Specialty chemical producers' capacity for primary and secondary ZDDPs is broadening to meet specific performance tiers in modern lubricants. This expansion addresses the need for tailored anti-wear protection in new engine designs. The Lubrizol Corporation leverages its extensive formulation expertise to serve diverse end-user industries. Afton Chemical sustains its market position through a focus on proprietary driveline and engine oil additive packages.
Zinc Dialkyldithiophosphates are a class of chemical compounds primarily used as multifunctional additives in lubricants. They function by forming a protective tribofilm on metal surfaces, providing critical anti-wear and antioxidant properties. Engine oils constitute the largest application segment, driven by automotive and industrial machinery requirements. While the anti-wear agent function is its core product type, its use in hydraulic fluids for construction equipment is also significant.
Product formulation is heavily influenced by regulations limiting phosphorus content to protect vehicle emission control systems. Compliance with standards set by the EPA in the United States and ECHA's REACH framework in Europe is mandatory for market access. Lubricant formulators must therefore balance the need for robust wear protection with evolving environmental and hardware compatibility constraints.
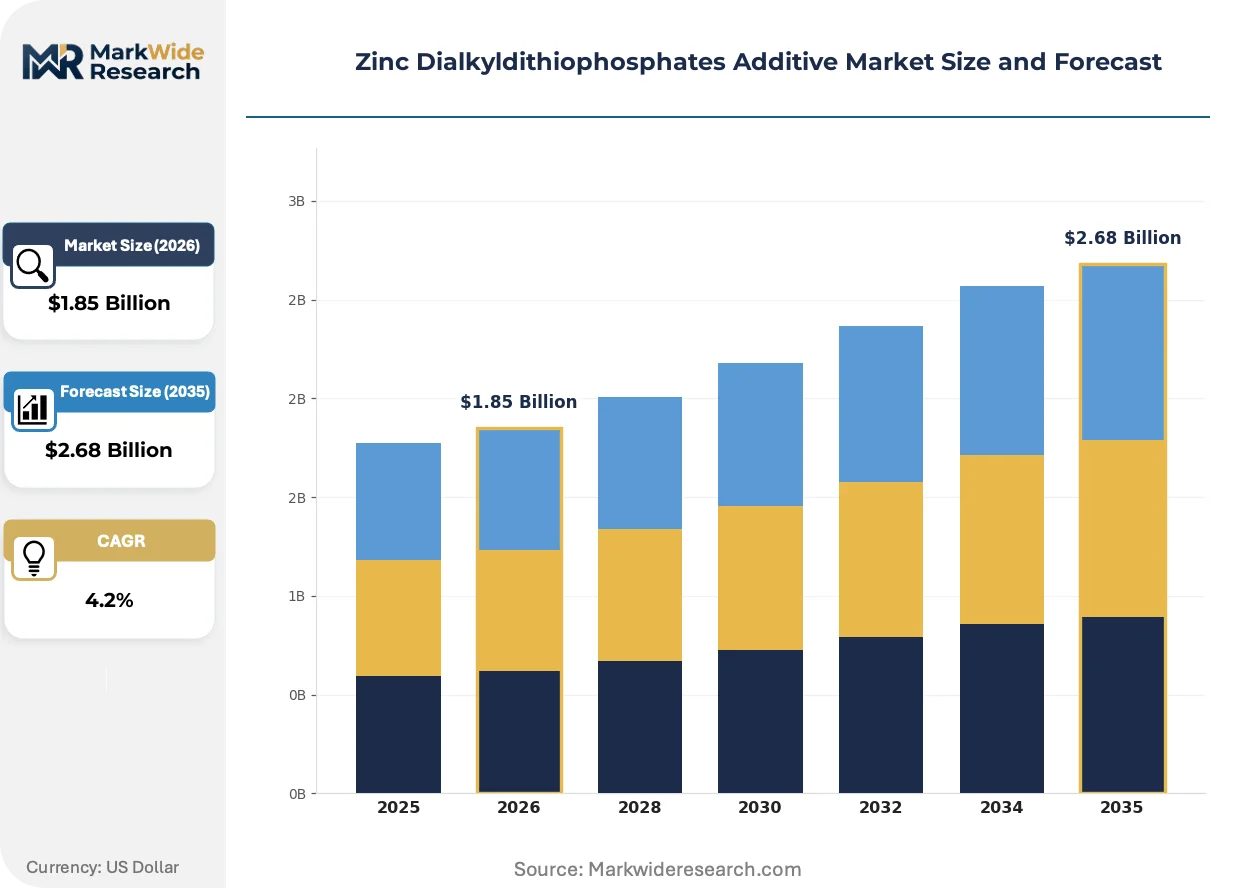
Market Dynamics
The central structural force shaping the Zinc Dialkyldithiophosphates Additive market is the escalating tension between the demand for enhanced engine protection in modern automotive designs and the tightening regulatory limits on phosphorus emissions to preserve aftertreatment system functionality.
Growth Catalysts
- Automotive Engine Modernization:The proliferation of smaller, higher-power engines, such as turbocharged gasoline direct injection (TGDI) units, requires advanced lubricant formulations with specific ZDDPs to mitigate low-speed pre-ignition (LSPI) and wear.
- Stringent Emission Standards:Regulations like the EU Green Deal and EPA mandates push formulators toward more advanced lubricant tiers, which paradoxically sustains demand for specialized ZDDPs that can perform effectively at lower concentrations.
- Industrialization in Asia:Rapid growth in China's manufacturing and automotive production sectors creates sustained, high-volume demand for engine oils and hydraulic fluids containing ZDDPs for machinery and vehicle fleets.
Market Restraints
- Phosphorus Content Regulation:Industry standards from bodies like API and ACEA impose strict caps on phosphorus levels in engine oils to prevent damage to catalytic converters and gasoline particulate filters, directly limiting ZDDP treat rates.
- Alternative Additive Development:The emergence of ashless or low-SAPS anti-wear alternatives, while not always a direct performance substitute, poses a threat in applications where phosphorus limits are the primary constraint.
- Raw Material Price Volatility:The costs of key precursors, including zinc oxide and specific alcohols, are subject to commodity market fluctuations, which can compress margins for ZDDP producers without long-term supply contracts.
Strategic Opportunities
- Specialized Industrial Lubricants:Formulating ZDDPs for industrial applications like hydraulic fluids and gear oils, which often have less stringent phosphorus limits than passenger car engine oils, offers a significant growth avenue.
- Synergistic Additive Packages:Combining ZDDPs with novel additives like molybdenum compounds or organic friction modifiers creates synergistic packages that meet new performance standards while respecting phosphorus limits.
- Expansion in Developing Economies:Modernizing industrial and vehicle fleets in regions like Southeast Asia and Latin America presents an opportunity for higher-performance lubricants, increasing the addressable market for ZDDPs.
Industry Challenges
- Complex Formulation Science:Balancing anti-wear efficacy with lower phosphorus content demands significant R&D investment, extending lubricant development timelines for formulators and increasing the cost of innovation.
- OEM Certification Hurdles:Securing approvals from individual automotive original equipment manufacturers (OEMs) is a costly and time-consuming process that adds complexity beyond meeting general industry standards.
- Production Process Adjustments:The shift in demand from primary to secondary ZDDPs requires producers to adapt their manufacturing capabilities and supply chains to create more thermally stable molecules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Dialkyldithiophosphates Additive Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dispersant, Anti-wear Agent, Antioxidant, Extreme Pressure Additive Application: Engine Oils, Hydraulic Fluids, Gear Oils, Metalworking Fluids, Compressor Oils End User Industry: Manufacturing, Agricultural Machinery, Marine Operations, Construction Equipment Packaging Type: Drums, Bulk Containers, Totes, Intermediate Bulk Containers |
| Companies Covered | Infineum, Yasho Industries, Chevron Oronite, Prasol Chemicals, AMSOIL, Afton Chemical, Ganesh Benzoplast, Ruhani Lubricants, Lubrizol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Dialkyldithiophosphates Additive Market Strategic Shifts & Innovations
The market's evolution reflects a shift from ZDDPs as a commodity to highly engineered components. This transformation resolves conflicting performance, environmental, and hardware compatibility demands in modern machinery, particularly within the automotive sector.
Secondary ZDDPs, characterized by specific alkyl group structures, provide enhanced thermal stability and hydrolysis resistance. Lubricant formulators for high-performance engines are increasingly adopting these tailored molecules to protect critical components. This development is unifying the historically separate objectives of robust wear protection and compatibility with sensitive emission control systems like gasoline particulate filters.
Regulatory frameworks, such as ECHA's REACH in Europe, impose stringent data and registration requirements on all chemical substances, including ZDDPs. This forces manufacturers to conduct extensive toxicological and environmental impact studies, increasing compliance costs and administrative burdens. The engine oil additive segment is most affected, compelling producers to rationalize product portfolios and invest in registering only the most commercially viable ZDDP structures.
End-users, particularly large automotive lubricant blenders, increasingly source complete, pre-certified additive packages rather than individual components. This model disrupts traditional component sales, favoring large suppliers offering warranted solutions that meet complex OEM specifications. The shift is most visible in North America and Europe, where meeting API and ACEA standards is a key procurement driver.
Zinc Dialkyldithiophosphates Additive Market Segmentation
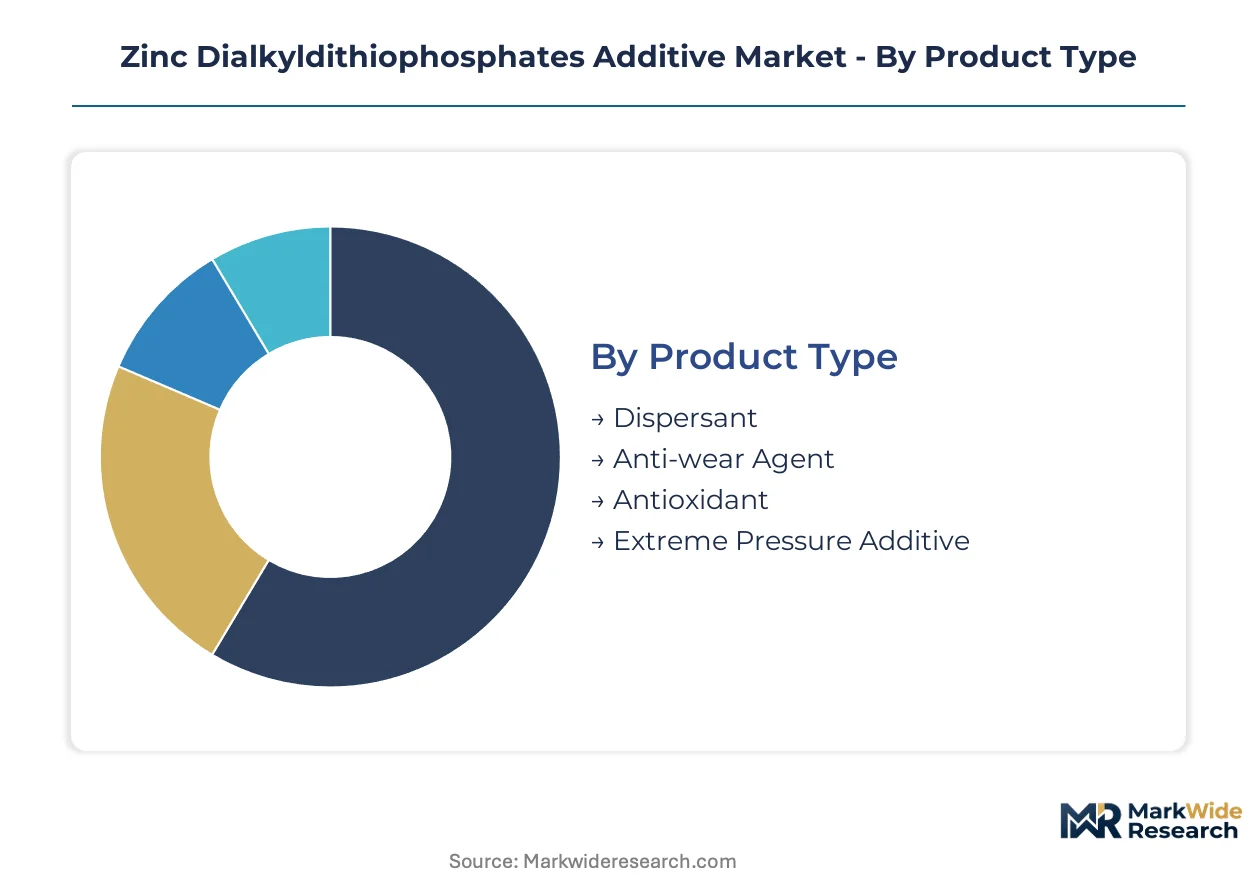
Understanding the distinct segments within the Zinc Dialkyldithiophosphates Additive market is crucial for producers to align product development with specific performance requirements. Each category reflects varying demands for anti-wear, antioxidant, and extreme pressure properties across diverse applications and end-user industries.
Product Type:
The market for ZDDPs differentiates based on their primary function, with some types acting as standalone performance enhancers and others integrated into complex additive packages.
- Dispersant:This ZDDP type suspends insoluble contaminants in lubricants, preventing their agglomeration and deposition on engine parts. It maintains engine cleanliness, especially in high-temperature operating conditions.
- Anti-wear Agent:These ZDDPs form a protective tribofilm on metal surfaces under boundary lubrication conditions, critically reducing friction and wear in engines and machinery. Demand for this core function remains high in modern automotive engine designs requiring robust protection.
- Antioxidant:These compounds inhibit the oxidation of base oils, extending lubricant life and preventing the formation of harmful sludge and varnish. Their use is essential in high-performance engine oils and industrial lubricants operating under thermal stress.
- Extreme Pressure Additive:These ZDDPs provide lubrication under severe load conditions, preventing metal-to-metal contact and scuffing, particularly in gear oils and metalworking fluids.
Volume placements concentrate in Anti-wear Agent; the faster expansion belongs to Antioxidant.
Application:
ZDDP applications span a broad spectrum of lubricant formulations, each requiring tailored additive packages to meet specific operational and regulatory demands.
- Engine Oils:This segment represents the largest application for ZDDPs, crucial for protecting automotive and industrial engines from wear, oxidation, and corrosion. Stricter emission standards in regions like the United States and Europe drive innovation in low-phosphorus formulations.
- Hydraulic Fluids:ZDDPs provide essential anti-wear and antioxidant properties in hydraulic systems, ensuring smooth operation and extended component life in heavy machinery. Significant demand originates from the construction equipment sector in countries like China.
- Gear Oils:These lubricants benefit from ZDDPs' extreme pressure and anti-wear capabilities, protecting gears in transmissions and differentials from high loads and sliding friction.
- Metalworking Fluids:ZDDPs enhance the performance of cutting and forming fluids by reducing tool wear and improving surface finish during manufacturing processes.
- Compressor Oils:ZDDPs contribute anti-wear and antioxidant properties to compressor lubricants, extending equipment life and maintaining efficiency in industrial air and gas compressors.
The largest revenue contribution comes from Engine Oils, while Hydraulic Fluids exhibits the steepest expansion trajectory.
End User Industry:
Different end-user industries possess distinct operational environments and machinery, influencing the specific performance requirements and consumption patterns of ZDDP additives.
- Manufacturing:This sector utilizes ZDDPs in lubricants for a wide array of machinery, including presses, CNC machines, and robotic systems, to ensure continuous operation and minimize downtime. Rapid industrialization across Asia, particularly China, drives substantial consumption.
- Agricultural Machinery:Tractors, harvesters, and other farm equipment rely on ZDDP-containing lubricants for their engines, transmissions, and hydraulic systems, operating under demanding conditions.
- Marine Operations:ZDDPs are incorporated into lubricants for marine engines and auxiliary equipment, providing critical protection against wear and corrosion in harsh saltwater environments.
- Construction Equipment:Heavy machinery like excavators, bulldozers, and cranes require robust ZDDP formulations in their engine and hydraulic oils to withstand extreme loads and abrasive conditions.
Demand intensity is highest in Manufacturing, with Construction Equipment showing significant growth potential.
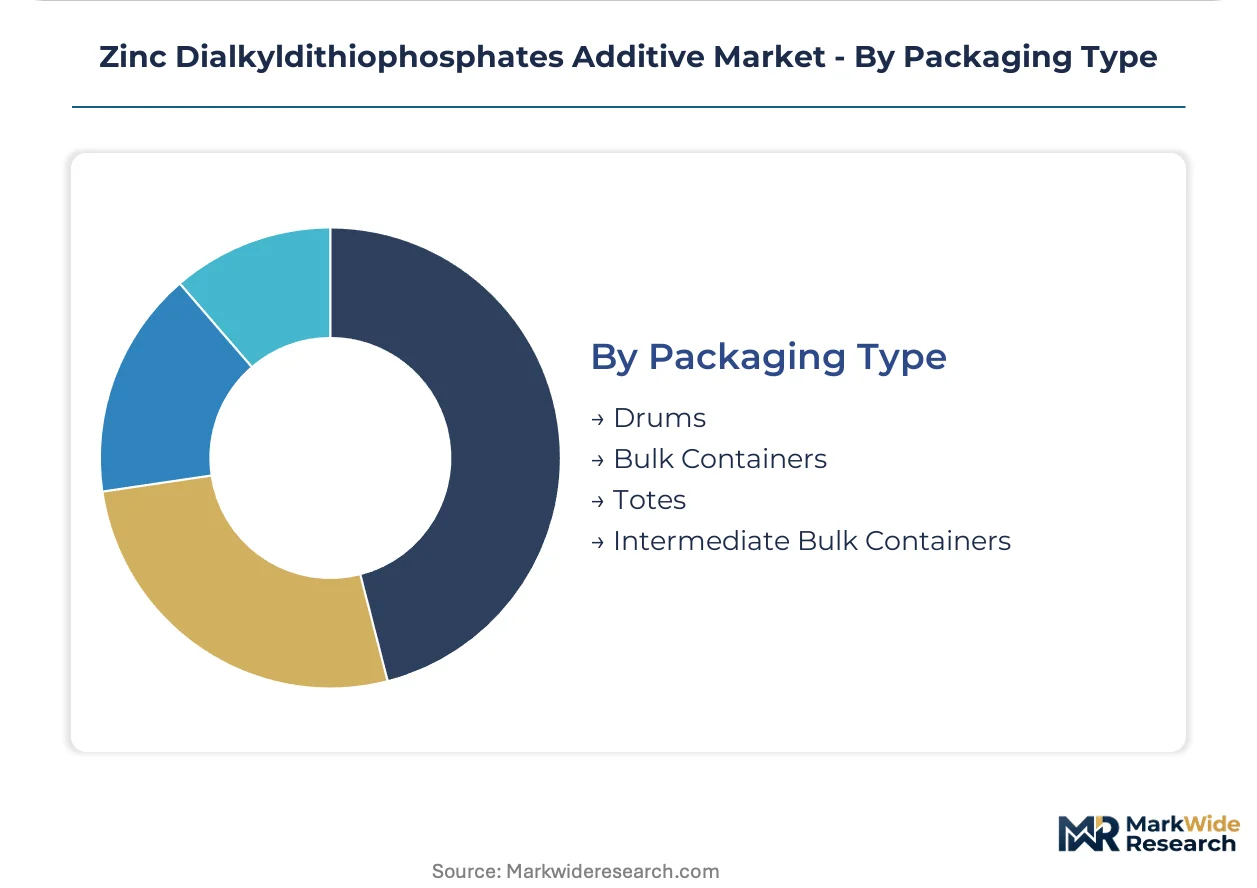
Packaging Type:
The choice of packaging for ZDDP additives often correlates with the volume requirements of lubricant blenders and the logistical considerations of distribution.
- Drums:These containers typically hold 200-220 liters of ZDDP additives, commonly used by medium-sized lubricant blenders and for distribution to smaller regional markets.
- Bulk Containers:Large-volume purchasers and major additive blenders procure ZDDPs in bulk containers, optimizing logistics and reducing per-unit costs.
- Totes:Intermediate bulk containers (IBCs) or totes offer a convenient solution for quantities between drums and bulk shipments, providing flexibility for various production scales.
- Intermediate Bulk Containers:These reusable containers, often larger than drums but smaller than bulk tanks, facilitate efficient handling and transportation for specific industrial clients.
High-volume purchasers favor Bulk Containers, whereas Drums serve more specialized or smaller-scale needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial and automotive manufacturing centers anchor significant demand for Zinc Dialkyldithiophosphates Additives, driving consumption across Asia. The need for advanced lubricant formulations to protect modern engines and heavy machinery shapes regional market dynamics. Regulatory frameworks across key economies influence ZDDP formulation and market access.
China
Rapid growth in China's manufacturing and automotive production sectors generates substantial demand for ZDDP-containing engine oils and hydraulic fluids. The country's dual carbon goals push for more efficient engines, requiring high-performance lubricants. Industrial clusters in the Yangtze River Delta and Pearl River Delta drive significant consumption for machinery and vehicle fleets.
United States
The United States market demands advanced ZDDP formulations for its large automotive and industrial machinery sectors. EPA mandates for emissions control influence lubricant development, necessitating lower phosphorus content. Major automotive manufacturing hubs in Michigan and the industrial Midwest require specialized anti-wear additives for high-performance engines.
Germany
Germany's premium automotive industry and advanced manufacturing sector create a strong market for high-performance ZDDPs. The EU Green Deal and ECHA's REACH framework impose strict environmental and chemical registration requirements. Bavarian automotive and machinery manufacturers prioritize lubricants that offer robust protection while complying with stringent European standards.
India
India's expanding automotive production and industrialization efforts fuel demand for ZDDPs in engine oils and hydraulic fluids. The country's vehicle emission standards are progressively tightening, influencing lubricant formulations. Manufacturing zones in Maharashtra and Tamil Nadu drive consumption for both passenger vehicles and industrial equipment.
Brazil
Brazil's agricultural machinery and automotive sectors are key consumers of ZDDPs, particularly for heavy-duty engine oils and hydraulic fluids. Environmental regulations, though evolving, impact lubricant specifications for local markets. Industrial centers around São Paulo and Minas Gerais require robust anti-wear additives for their diverse manufacturing and transport fleets.
Zinc Dialkyldithiophosphates Additive Market Key Industry Players
Global majors compete with regional champions across formulation expertise and market access in the Zinc Dialkyldithiophosphates Additive market. The market exhibits a tiered structure, with large integrated chemical companies at the top and specialized regional players serving niche applications. Strategic archetypes include innovation-driven formulators, cost-efficient producers, and regional specialists. Dominant competitive moves involve strategic partnerships to develop synergistic additive packages and capacity expansion to meet regional demand surges.
Innovation-driven formulators, such as Lubrizol and Afton Chemical, exemplify the focus on proprietary driveline and engine oil additive packages, leveraging extensive formulation expertise. Infineum also occupies a position among global suppliers, offering advanced solutions that meet complex OEM specifications. These companies anchor the premium segment, providing warranted solutions that address evolving performance and regulatory requirements across diverse end-user industries.
| Leading Market Players |
|---|
| Infineum |
| Yasho Industries |
| Chevron Oronite |
| Prasol Chemicals |
| AMSOIL |
| Afton Chemical |
| Ganesh Benzoplast |
| Ruhani Lubricants |
| Lubrizol |
| Others |
Cost & Logistics Intelligence
Vertical integration by major additive producers anchors both the supply position and the pricing power within the Zinc Dialkyldithiophosphates Additive market. This control over key precursors influences product availability and cost for downstream lubricant blenders.
Pricing Analysis
Warranted additive packages, often bundled with technical support, characterize the pricing structure for high-performance ZDDPs. The dominant pricing model involves long-term, contract-based offtake agreements for major lubricant blenders. Price differentiation stems from OEM certification levels, specific formulation complexity, and volume scale. Pricing pressure originates from the escalating costs associated with regulatory compliance, particularly for lower phosphorus content. Smaller, regional lubricant blenders exhibit higher price sensitivity compared to large automotive lubricant blenders that prioritize certified performance.
Supply Chain Analysis
Reverse logistics for ZDDPs primarily involves managing hazardous waste streams and ensuring proper disposal of spent lubricants containing these additives. Supply concentration for key precursors such as zinc oxide and specific alcohols resides in countries like China, India, and the United States. The supply chain for ZDDPs draws from these raw material dependencies, making it susceptible to commodity price volatility. Single-source vulnerability for specialized intermediates presents a structural risk. Distribution runs through direct sales from major additive producers to large lubricant blenders, complemented by regional distributors serving smaller-scale needs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a consolidation play, as stringent regulatory compliance and complex OEM certification processes force weaker players out. Only companies with robust R&D and strong technical support can sustain long-term growth.
For Market Incumbents: Lock in key OEM relationships through co-development of advanced ZDDP packages that meet future performance and emission standards. Invest significantly in R&D for thermally stable, low-phosphorus secondary ZDDPs to mitigate the threat from alternative ashless additives. Expand manufacturing capacity for these specialized molecules, particularly in high-demand regions like Asia, to maintain market share. Certification investment remains a crucial lever for defending market position against emerging technologies.
For New Entrants and Emerging Players: Capture niche industrial lubricant segments which often have less stringent phosphorus limits than passenger car engine oils. Target hydraulic fluids for construction equipment in Southeast Asia and gear oils in Latin America, where industrialization drives demand. A viable go-to-market angle involves offering cost-effective, regionally compliant ZDDP formulations that cater to specific equipment needs. Focus on applications where performance demands outweigh the immediate need for ultra-low phosphorus content.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized additive formulators with proprietary low-phosphorus technologies and strong intellectual property. The market remains viable long-term, driven by engine modernization and industrialization in developing economies, despite regulatory headwinds. Acquisition targets should include mid-sized players possessing strong regional distribution networks and specific application expertise in industrial lubricants. Practitioners should monitor increased M&A activity among major chemical companies for additive portfolios as an early signal of market shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Meeting rising demand for secondary ZDDPs in Asia-Pacific supports regional industrial growth. |
| Joint Venture | Co-developing advanced additive packages with major lubricant blenders accelerates market adoption. |
| Green Manufacturing Transition | Optimizing production processes to reduce environmental footprint enhances brand reputation and compliance. |
| Long-term Supply Agreement | Securing stable raw material supply for key precursors mitigates commodity price volatility risks. |
| Product Launch | Introducing new low-phosphorus ZDDPs for specific engine types addresses evolving regulatory requirements. |
Research Approach
Independent corroboration across industry association reports, regulatory body publications, and corporate financial disclosures underwrites the qualitative findings of this study. Primary interviews with R&D directors, procurement leads at lubricant blenders, automotive OEM engineers, and chemical plant managers provided critical insights. Secondary data from EPA emission reports, ECHA REACH registrations, API engine oil standards, and ACEA specifications further validated market dynamics. Both bottom-up and top-down triangulation approaches were employed to ensure data accuracy.
The forecast window was anchored to multiple historical reference periods, establishing a robust baseline for future projections across the analysis window. The analytical framework integrated both bottom-up and top-down approaches to model market segments comprehensively. Segmentation dimensions included product type, application, end-user industry, and regional markets like China, the US, and Germany. Compound annual growth rates were derived through regression analysis on historical data and projected market drivers, incorporating inputs such as vehicle production forecasts and industrial machinery output.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving emission regulations and the pace of alternative additive development. Forecasts reflect assumptions regarding technological advancements and market adoption rates. Unexpected shifts in raw material prices or accelerated adoption of ashless technologies represent specific risk factors that could revise projections. Practitioners should monitor new OEM lubricant specifications and major regulatory revisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Sorbitan Oleate Market
Additives
Sodium Benzoate Market
Additives
Disodium Guanylate Market
Additives
Sodium Caprylate Market
Additives
Tragacanth Market
Additives
Monocalcium Phosphate Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Lecithin and Phospholipids Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Alkyl Acetates Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
China Citric Acid Market
Additives
Global Zinc Stearate Market
Additives
Antiknock Agents Market
Additives
Plasticizers Market
Additives
Global Carboxylic Acids Based Esters Market