
 High-Heat Melamine Foam Market | 2026-2036
High-Heat Melamine Foam Market Size, Share, and Industry Trends Forecast 2026-2036
High-Heat Melamine Foam Market Analysis
Chinese petrochemical producers is rebalancing export volumes toward higher-margin specialty grades after capacity additions in Shandong and Jiangsu provinces. BASF SE leverages its Ludwigshafen integrated site to sustain captive melamine resin supply for foam extrusion. Huntsman Corporation anchors North American availability through its Port Neches polyurethanes complex. Evonik Industries AG differentiates via high-purity resin formulations serving aviation thermal barrier specifications.
High-heat melamine foam is a thermoset polymer foam synthesized from melamine-formaldehyde resin, capable of withstanding continuous service temperatures above 150°C while maintaining dimensional stability and low smoke toxicity. Its primary industrial purpose is to provide lightweight thermal insulation and fire protection in confined spaces where weight reduction and flame resistance are jointly critical. Rigid foam occupies the dominant margin pool in aerospace engine nacelle applications where compression strength at elevated temperature commands price premiums. Acoustic foam is expanding fastest in rail and mass transit interiors as operators retrofit rolling stock to meet stricter fire safety codes. Specialty foam variants incorporating intumescent coatings are maturing in offshore oil platform specifications where regulatory recertification cycles extend replacement intervals.
REACH registration requirements and the EU F-Gas Regulation are elevating compliance costs for imported foam products while creating preference for locally certified supply chains. FAA flame penetration standards and NHTSA interior burn rate rules in the United States are converging toward lower heat release metrics that favor melamine chemistry over competing polyurethane systems. Stakeholders must monitor how China's GB standards evolution and SAMR product certification timelines reshape competitive access for Western resin suppliers.
Market Dynamics
REACH chemical safety rules and the EU Green Deal are tightening permissible formaldehyde emissions in thermal insulation products, forcing resin suppliers to reformulate formulations or surrender market access. This regulatory compression is consolidating procurement around certified supply chains.
Growth Catalysts
- FAA flame penetration standards:Lower heat release metrics favor melamine chemistry over polyurethane systems in US aerospace applications. Aircraft OEMs are specifying melamine foam for engine nacelle insulation.
- Rail retrofit mandates:Mass transit operators across Germany and France are retrofitting rolling stock interiors to meet stricter fire safety codes, accelerating acoustic foam specification.
- Offshore platform recertification:Regulatory recertification cycles for North Sea and Gulf of Mexico platforms are extending replacement intervals for intumescent-coated specialty foam variants.
Market Restraints
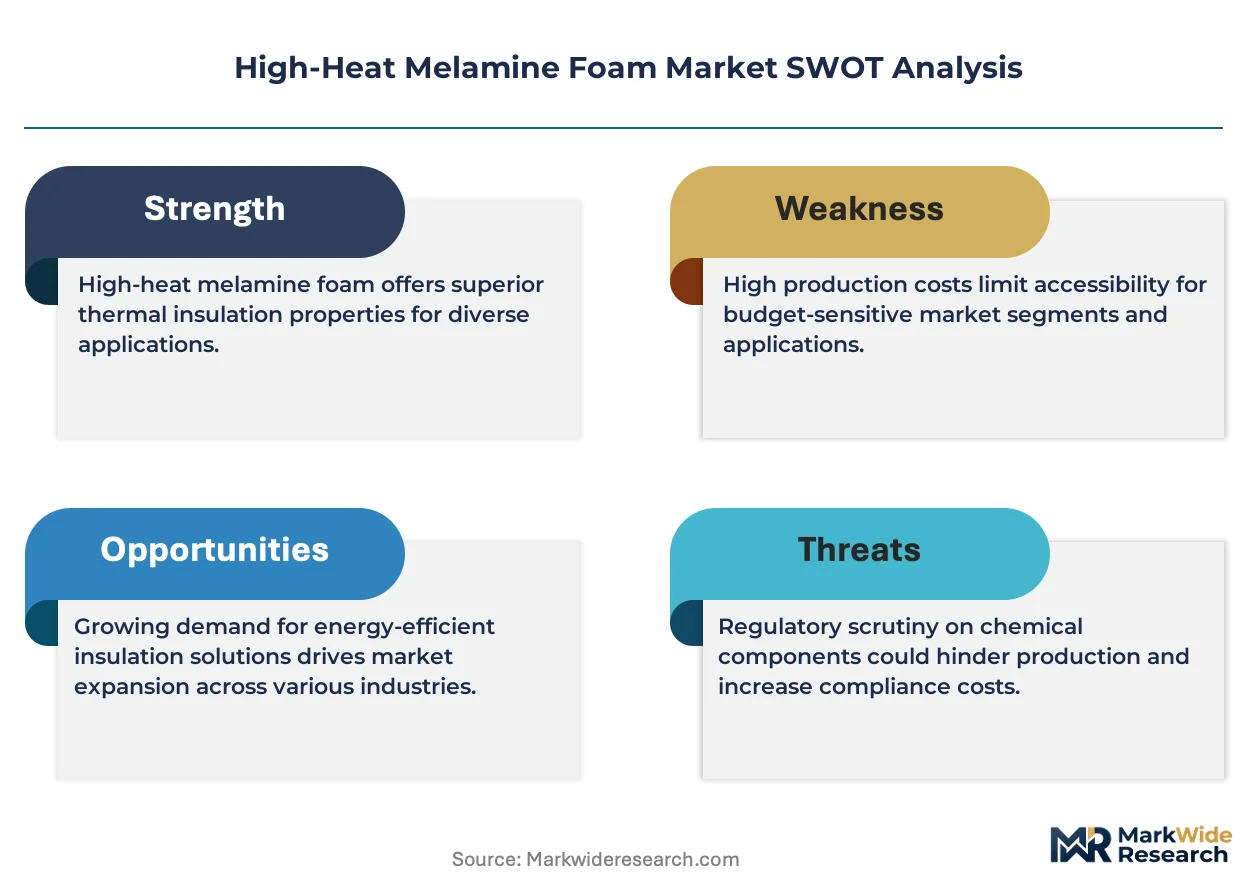
- Formaldehyde input volatility:Methanol-to-formaldehyde conversion costs fluctuate with natural gas pricing, squeezing resin producer margins.
- Captive supply concentration:BASF SE's Ludwigshafen integrated site controls substantial European resin supply, creating dependency risk for independent foam extruders.
- Mineral wool substitution:Basalt fiber insulation competes in petrochemical applications where compression strength requirements are less severe.
Strategic Opportunities
- Aviation thermal barrier specifications:High-purity resin formulations meeting aviation standards command substantial price premiums in US and European aerospace supply chains.
- EU F-Gas Regulation compliance:Elevated compliance costs for imported foam products create preference for locally certified supply chains within the European Union.
- China GB standards evolution:SAMR product certification timelines are reshaping competitive access for Western resin suppliers in Chinese industrial corridors.
Industry Challenges
- Resin formulation chemistry expertise:Formulators capable of balancing flame retardancy with low smoke toxicity remain scarce in industrial chemical labor markets.
- REACH registration timelines:Extended ECHA evaluation periods delay new product introductions by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Heat Melamine Foam Market |
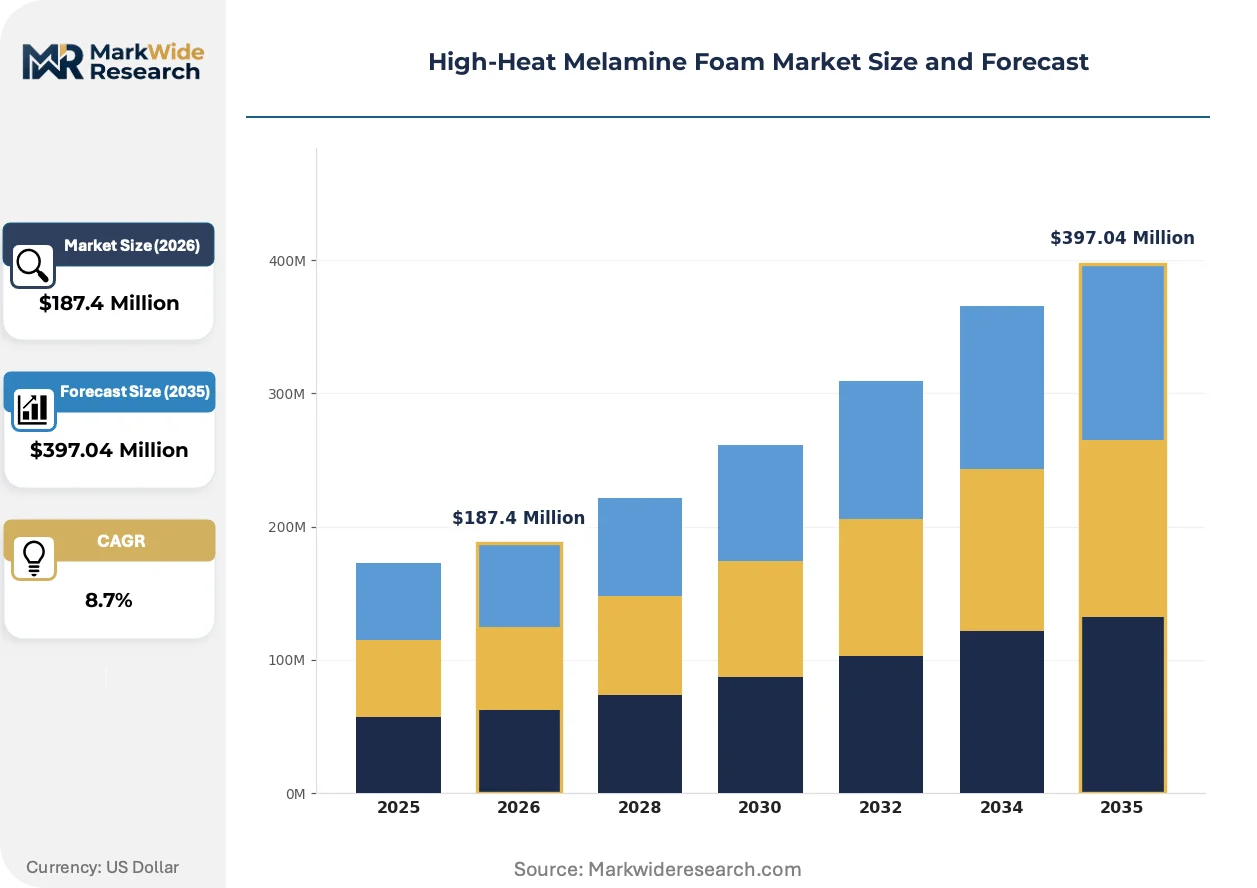
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Acoustic Foam, Specialty Foam Application: Insulation, Sound Absorption, Fire Protection, Automotive Interiors End User: Construction, Automotive, Consumer Electronics, Aerospace Delivery Mode: Direct Sales, Online Sales, Retail Sales, Distributors |
| Companies Covered | BASF SE, Huntsman Corporation, Evonik Industries AG, Saint-Gobain, Armacell International S.A., Recticel, SABIC, Nitto Denko Corporation, Rogers Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Heat Melamine Foam Market Emerging Trajectories
Reformulation pressures and certification complexity are driving material science investment across the value chain. Suppliers are racing to secure regulatory pre-approval while end-users demand performance guarantees.
Intumescent coating integration is consolidating as the dominant innovation pathway for offshore and high-hazard applications. Oil platform operators in the North Sea and Gulf of Mexico are specifying pre-coated foam panels to reduce field installation labor. This technology is consolidating specification power among coating-foam integrated suppliers.
REACH registration requirements are elevating compliance documentation burdens for imported foam products. ECHA substance evaluation dossiers now require extended toxicological data sets. European industrial buyers are responding by shortening approved vendor lists to pre-registered suppliers.
Specification-driven procurement is compressing traditional distribution channels in aerospace and rail sectors. Airlines and rolling stock OEMs are issuing long-term supply agreements directly to resin-integrated foam producers. This pattern is most visible in German aviation supply chains and French rail manufacturing clusters.
High-Heat Melamine Foam Market Segmentation
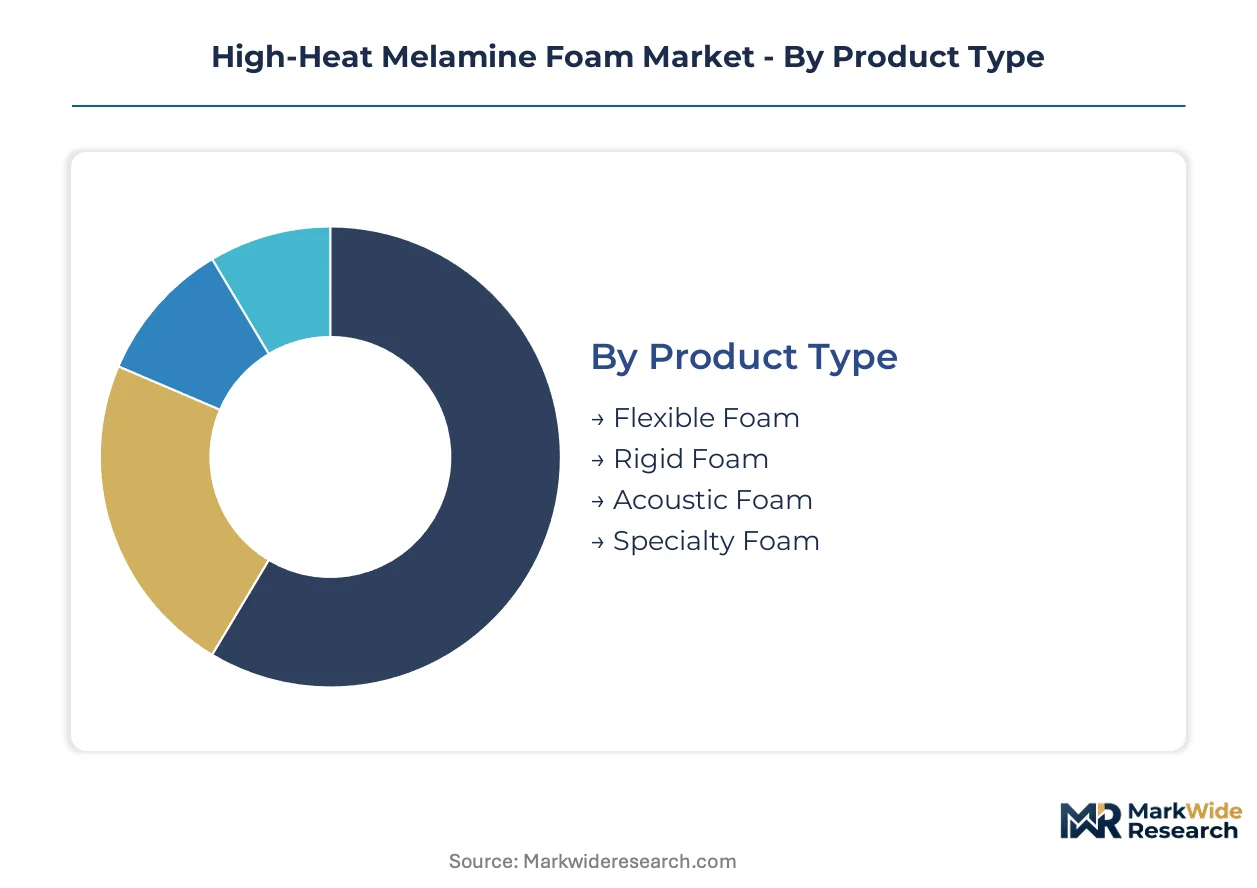
High-heat melamine foam exhibits pronounced specification divergence across product architectures and end-use environments. Each segment carries distinct thermal performance thresholds, regulatory certification burdens, and procurement channel preferences that reshape competitive positioning.
Product Type:
Thermal resistance and structural integrity define the specification hierarchy across foam architectures.
- Rigid Foam:Closed-cell thermoset structure delivers compression strength above 150°C continuous service temperature. Aerospace engine nacelle manufacturers in Germany and France specify rigid grades where dimensional stability under thermal load commands procurement priority.
- Acoustic Foam:Open-cell configuration optimized for sound absorption coefficients in rail and mass transit interiors. Operators across Bavaria and Rhone-Alpes corridors are retrofitting rolling stock to meet stricter fire safety codes, accelerating specification velocity.
- Flexible Foam:Lower-density formulation for conformable gasketing and sealing applications.
- Specialty Foam:Intumescent-coated variants engineered for offshore oil platform specifications where regulatory recertification cycles extend replacement intervals.
Rigid foam leads on scale; acoustic foam leads on momentum.
Application:
Functional performance requirements segment procurement around thermal, acoustic, or flame-barrier priorities.
- Insulation:Primary thermal barrier function in confined spaces where weight reduction and temperature maintenance are jointly critical. Petrochemical facilities along the US Gulf Coast specify melamine over mineral wool where compression strength requirements are severe.
- Fire Protection:Intumescent and char-forming behavior under flame exposure. FAA flame penetration standards favor melamine chemistry over polyurethane systems in US aerospace applications.
- Sound Absorption:Noise reduction coefficients in transportation and building envelopes.
- Automotive Interiors:Headliner and trim applications requiring low smoke toxicity under burn rate protocols.
Insulation dominates installed base; fire protection climbs the fastest.
End User:
Industry-specific certification regimes and performance guarantees drive vendor selection patterns.
- Aerospace:Thermal barrier specifications demand high-purity resin formulations meeting aviation standards. OEMs issue long-term supply agreements directly to resin-integrated foam producers, compressing traditional distribution channels.
- Automotive:NHTSA interior burn rate rules are converging toward lower heat release metrics that favor melamine chemistry.
- Construction:Building envelope and HVAC applications under REACH and EU Green Deal formaldehyde emission constraints.
- Consumer Electronics:Thermal management in compact electronic enclosures.
Aerospace leads on margin contribution; automotive leads on volume expansion.
Delivery Mode:
Channel structure reflects specification complexity and end-user procurement sophistication.
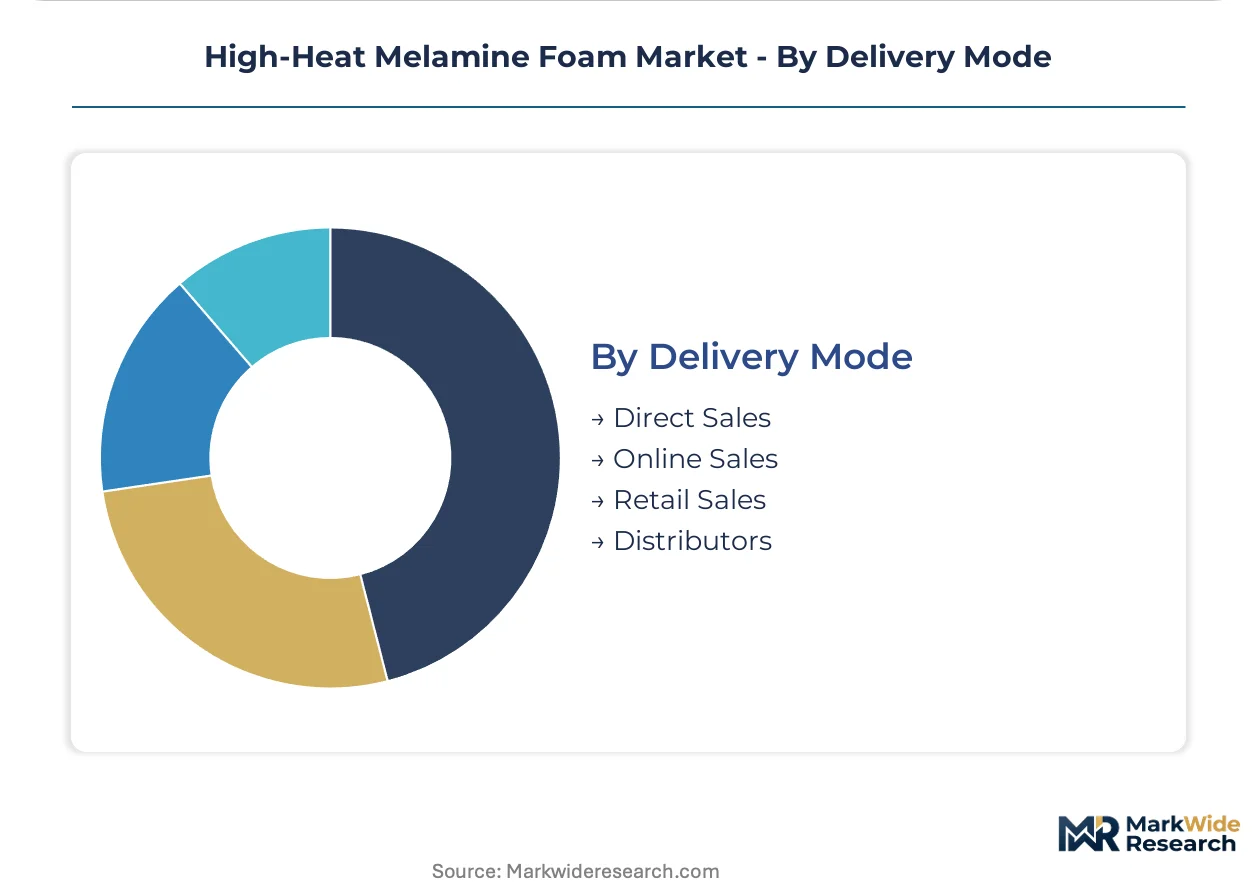
- Direct Sales:Long-term supply agreements between resin-integrated producers and OEMs in aviation and rail sectors. German aviation supply chains and French rail manufacturing clusters exhibit this pattern most visibly.
- Distributors:Stocking intermediaries serving construction and automotive aftermarket segments with shorter lead time requirements.
- Online Sales:Transactional procurement for standard grades and replacement volumes.
- Retail Sales:Limited presence in consumer-accessible thermal management products.
Direct sales commands premium tiers; distributors capture mid-market scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as compliance-cost differentials widen between jurisdictions. Resin suppliers are relocating formulation capacity toward zones with streamlined chemical registration pathways while maintaining sales presence in high-specification markets.
United States
FAA flame penetration standards and NHTSA interior burn rate rules favor melamine chemistry over polyurethane systems in aerospace and automotive applications. The US Gulf Coast petrochemical belt concentrates demand from offshore platform operators seeking intumescent-coated specialty foam for extended replacement intervals. Houston-area fabricators serve both domestic aviation OEMs and Gulf of Mexico energy infrastructure.
Germany
REACH chemical safety rules and the EU Green Deal tighten permissible formaldehyde emissions, forcing resin reformulation or market exit. BASF SE's Ludwigshafen integrated site anchors European captive supply for foam extrusion. Bavaria's aerospace manufacturing corridor generates concentrated procurement of rigid foam grades for engine nacelle insulation.
China
GB standards evolution and SAMR product certification timelines reshape competitive access for Western resin suppliers. Shandong and Jiangsu provinces host capacity additions driving export rebalancing toward higher-margin specialty grades. Yangtze River Delta industrial clusters absorb expanded domestic output for electronics thermal management.
France
EU F-Gas Regulation elevates compliance costs for imported foam products, creating preference for locally certified supply chains. Rhone-Alpes aerospace manufacturers expand procurement of fire-rated insulation materials. French rail manufacturing clusters specify acoustic foam for rolling stock retrofit mandates.
Japan
METI industrial standards and JIS certification requirements sustain premium-tier market segmentation. Automotive OEMs in the Kanto region specify low-smoke-toxicity grades for headliner applications. Precision electronics manufacturers in Osaka-Kobe corridors drive demand for conformable thermal management solutions.
High-Heat Melamine Foam Market Vendor Landscape
German chemical conglomerates anchor one tier; North American and Asian specialists hold differentiated positions in application-specific niches. Market structure reflects moderate consolidation around integrated resin-to-foam producers alongside fragmented specialty fabricators. Three archetypes dominate: captive resin-integrated multinationals, independent foam extruders sourcing merchant resin, and coating-foam integrators serving offshore platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure regulatory pre-approval.
Within the integrated-resin tier, BASF SE exemplifies backward control over melamine supply chains through its Ludwigshafen complex. Huntsman Corporation anchors North American availability through its Port Neches polyurethanes footprint. Evonik Industries AG occupies a position emphasizing high-purity resin formulations for aviation thermal barrier specifications.
| Leading Market Players |
|---|
| BASF SE |
| Huntsman Corporation |
| Evonik Industries AG |
| Saint-Gobain |
| Armacell International S.A. |
| Recticel |
| SABIC |
| Nitto Denko Corporation |
| Rogers Corporation |
| Others |
Supply Flow & Price Mechanics
Resin formulation chemistry expertise scarcity simultaneously elevates premium-grade production costs and consolidates supply control among captive-integrated producers in Germany and the United States. REACH registration timelines and ECHA substance evaluation dossiers extend new product introduction cycles, compressing margin recovery windows for independent foam extruders sourcing merchant resin.
Pricing Analysis
Distributor margins in construction and automotive aftermarket segments absorb 15-25 point markups over direct-to-OEM contract pricing. Three-tier pricing structure across aviation-certified, industrial-standard, and economy construction grades reflects certification burden differentials. Pricing pressure stems from methanol-to-formaldehyde conversion cost volatility tracking natural gas benchmarks. Construction sector buyers exhibit highest price sensitivity; aerospace OEMs prioritize thermal performance guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from FAA-certified aviation OEMs and EU rail operators mandate multi-supplier qualification across Germany, France, and the United States. Raw material dependencies center on melamine crystal, formaldehyde feedstock, and specialized blowing agents. Single-source vulnerability concentrates around BASF SE's Ludwigshafen captive resin supply. Distribution runs through specification-driven direct sales for aerospace and rail, with stocking intermediaries serving construction retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH chemical safety milestones and FAA flame penetration standard convergence mechanically expand addressable demand for certified melamine formulations.
For Market Incumbents: Cement backward integration into high-purity resin production to defend against Huntsman Corporation's Port Neches supply concentration and emerging Chinese specialty grade exports. Prioritize ECHA pre-registration completion to compress 18-36 month evaluation timelines before independent competitors achieve substance dossier compliance.
For New Entrants and Emerging Players: Launch via coating-foam integration partnerships serving North Sea and Gulf of Mexico offshore platform recertification cycles. Target acoustic foam specification in French and German rail retrofit mandates where incumbent certification burdens create penetrable white space. Pursue distributor relationships in construction aftermarket segments with shorter qualification pathways than aviation direct sales.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent foam extruders lacking captive resin supply but holding established SAMR product certification for Chinese industrial corridor access. Five-to-ten year viability hinges on GB standards evolution reshaping Western supplier competitive access. Monitor SAMR certification timeline acceleration as inflection signal for Chinese market entry feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | BASF SE's Ludwigshafen model demonstrates margin capture from captive melamine-formaldehyde supply control. |
| Intumescent Coating-Foam Integration | Pre-coated panel supply reduces North Sea platform field installation labor and extends replacement intervals. |
| ECHA Pre-Registration Acceleration | Early dossier submission compresses 18-36 month evaluation windows before competitor substance approvals. |
| Long-Term Supply Agreement with Aviation OEMs | German aviation supply chains exhibit direct procurement patterns that displace traditional distribution channels. |
| SAMR Certification Investment | GB standards evolution in Shandong and Jiangsu provinces reshapes Western resin supplier competitive access. |
Methodological Framework
Direct dialogue with resin formulation chemists, aerospace procurement directors, rail operator engineering leads, and offshore platform maintenance supervisors grounded qualitative findings in operational reality. Secondary validation drew from ECHA substance evaluation dossiers, FAA certification databases, customs trade flow records, and SEC filings from integrated chemical producers. Bottom-up volume modeling across foam product architectures triangulated against top-down end-use industry consumption estimates.
Bottom-up segment analysis projected rigid foam, acoustic foam, and specialty intumescent-coated grades across aviation, rail, automotive, and offshore energy applications. Top-down validation referenced petrochemical facility insulation specifications and REACH compliance cost burdens. CAGRs derived from weighted average of segment growth trajectories, with aviation thermal barrier specification velocity and rail retrofit mandate timing as primary sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SAMR certification timeline acceleration or ECHA registration backlog clearance. Deviation in formaldehyde emission regulatory stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High Purity Isobutylene (HPIB) Market
High-Value Chemicals
P-Hydroxybenzoates (PHB) Market
High-Value Chemicals
Hydroquinone Market
High-Value Chemicals
High Performance Fluoropolymers Market
High-Value Chemicals
Hydroxynitrile Lyase Market
High-Value Chemicals
High-Purity Boehmite Market
High-Value Chemicals
High Friction Films Market
High-Value Chemicals
Battery Grade High Purity Lithium Fluoride Market
High-Value Chemicals
High-K Dielectric Material Market
High-Value Chemicals
Global High Temperature Grease Market
High-Value Chemicals
Hydroxycarboxylic Acids Market
High-Value Chemicals
Hydroxyethyl Urea Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
High Methoxyl Pectin Market
High-Value Chemicals
High Purity Silica Market