
 Global Corrosion Inhibitor Market | 2026-2036
Global Corrosion Inhibitor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Corrosion Inhibitor Market Intelligence
The development of smart, self-healing, and bio-based inhibitor technologies is fragmenting the traditional product landscape. BASF SE leverages its extensive chemical synthesis capabilities to develop advanced organic inhibitors for specialized industrial uses. Ecolab dominates the water treatment application segment through its service-intensive model and on-site management solutions. Cortec Corporation specializes in Volatile Corrosion Inhibitors (VCIs) for protecting metal components during transport and storage.
A corrosion inhibitor is a chemical compound added in small concentrations to an environment to decrease the corrosion rate of a metal. It functions by adsorbing onto the metal surface, forming a thin protective film that physically isolates the material from corrosive elements like oxygen and water. Organic inhibitors lead the market due to their effectiveness across various pH levels, particularly in oil & gas applications. The water treatment segment also constitutes a primary demand center for both organic and inorganic types to maintain infrastructure integrity.
Regulatory frameworks, including the EPA's guidelines in the United States and ECHA's REACH regulation in Europe, are steering product development toward lower-toxicity and biodegradable formulations. In China, the Ministry of Ecology and Environment (MEE) imposes strict effluent standards, influencing inhibitor selection in industrial water circuits. Vendor success will increasingly depend on balancing high-performance corrosion protection with compliance to evolving environmental and health safety mandates.
Market Dynamics
The corrosion inhibitor market is defined by a structural tension between the demand for high-performance asset protection in harsh industrial environments and the escalating pressure from global environmental regulations to adopt less toxic, biodegradable formulations.
Growth Catalysts
- Infrastructure Investment:Major public and private investment in infrastructure, particularly within China's chemical processing and water utility sectors, directly stimulates consumption of inhibitors to protect new and aging assets from degradation.
- Stringent Water Regulations:Policies such as the European Union's Water Framework Directive and EPA guidelines in the United States mandate higher water quality, compelling industrial plants to use advanced inhibitors to prevent system corrosion and contaminant leaching.
- Deepwater Oil and Gas:The expansion of offshore exploration and production into deeper, higher-pressure environments necessitates sophisticated organic inhibitor packages to protect pipelines and equipment from extreme corrosive conditions, supporting premium product demand.
Market Restraints
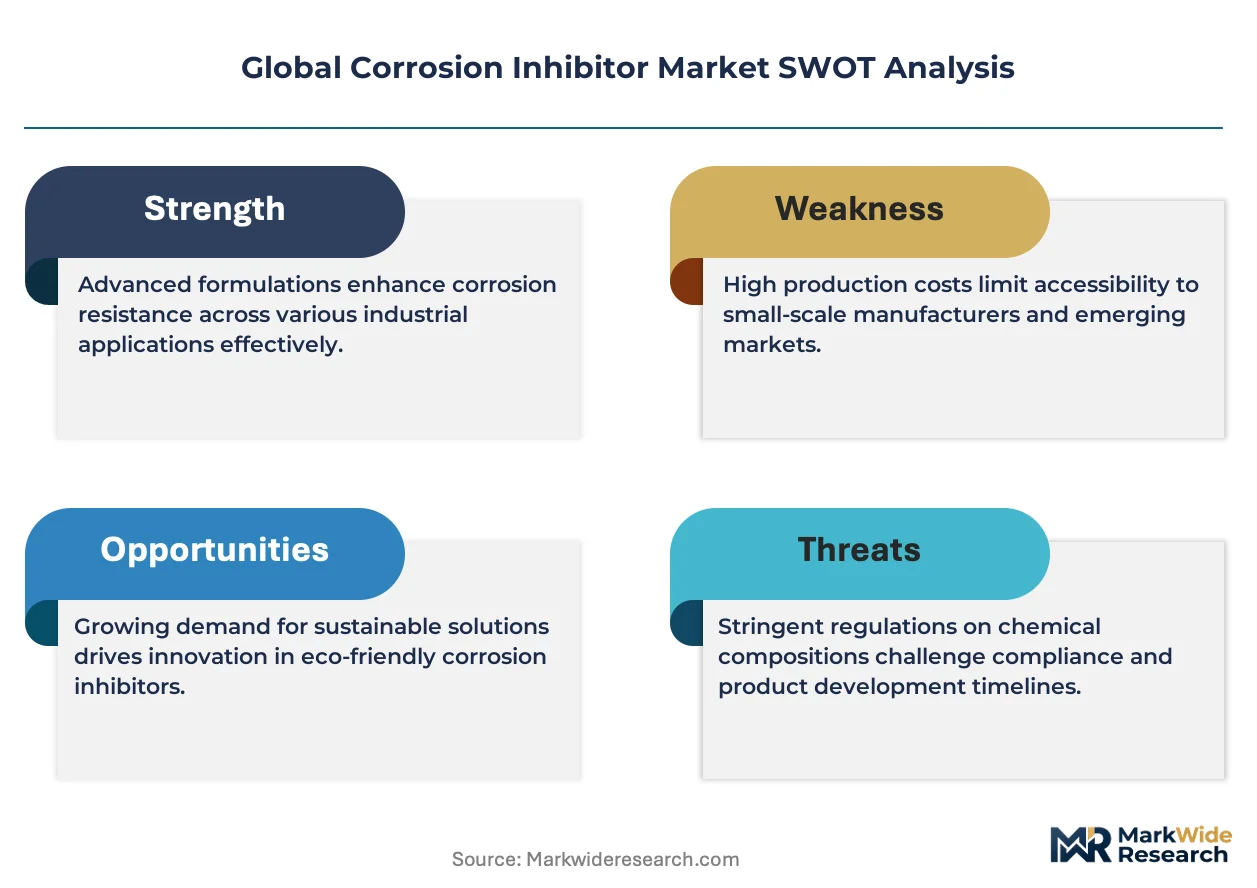
- Raw Material Price Volatility:The cost of key feedstocks for organic inhibitors, such as fatty amines and imidazolines derived from petrochemicals, is subject to market fluctuations, creating margin pressure and pricing instability for manufacturers.
- Performance Gaps in Bio-Based Formulations:While demand for green inhibitors is high, many current bio-based products offer lower thermal stability or reduced efficacy in extreme pH environments compared to traditional synthetic counterparts, limiting their adoption in critical applications.
- Complexities of REACH Compliance:The extensive testing and documentation required for chemical registration under the European Union's REACH framework creates significant cost and time-to-market barriers for new inhibitor formulations, slowing innovation.
Strategic Opportunities
- Renewable Energy Infrastructure:The construction of offshore wind farms and geothermal power plants presents a new application frontier, requiring specialized inhibitors to protect turbines, heat exchangers, and marine structures from atmospheric and saltwater corrosion.
- Smart and Self-Healing Coatings:Integrating nanocontainers filled with inhibitors into coatings creates "smart" systems that release protective agents upon detecting corrosion, offering a significant performance upgrade over passive-film technologies.
- Water Infrastructure in Southeast Asia:Rapid urbanization and industrialization in countries like Vietnam and Indonesia are creating significant, underpenetrated markets for water treatment inhibitors as these nations build out their municipal and industrial water systems.
Industry Challenges
- Specialized Formulation Expertise:A persistent shortage of chemical engineers and corrosion specialists with the skills to develop and test novel, eco-friendly inhibitor packages that meet diverse end-user specifications slows down product development cycles.
- Application-Specific Customization:The effectiveness of an inhibitor is highly dependent on the unique water chemistry, temperature, and flow rate of a specific industrial system, demanding extensive on-site analysis and custom blending from vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Corrosion Inhibitor Market |
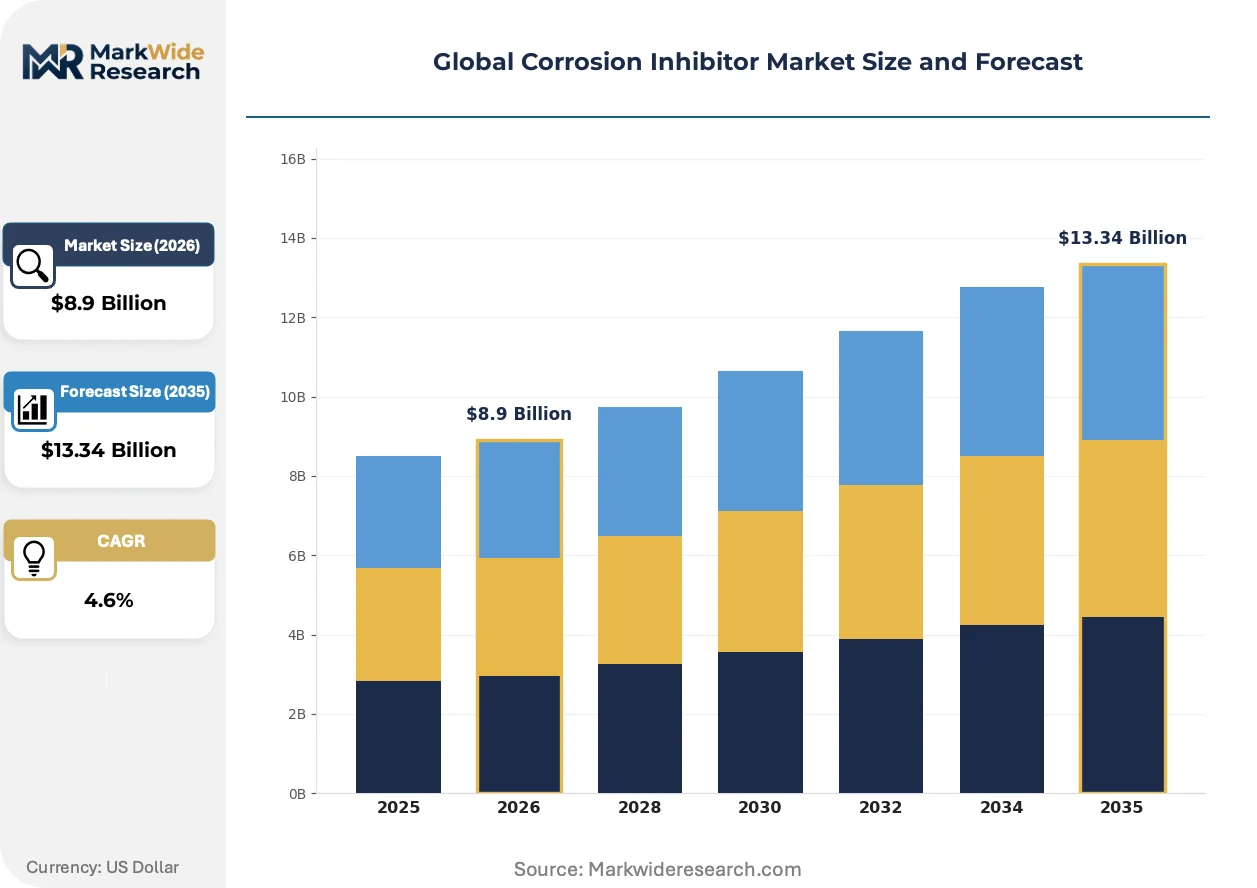
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $13.34 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Inhibitors, Inorganic Inhibitors, Volatile Corrosion Inhibitors, Mixed Inhibitors, Metallic Inhibitors Application: Oil & Gas, Water Treatment, Metal Fabrication, Construction, Marine, Power Generation End User Industry: Petrochemical Plants, Chemical Processing, Metal Works, Energy Producers, Infrastructure Maintenance Form: Liquid, Powder, Emulsion, Gel, Aerosol |
| Companies Covered | BASF SE, Ecolab, Ashland, Nouryon, Cortec Corporation, The Lubrizol Company, Dow, Henkel, DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Corrosion Inhibitor Market Strategic Shifts & Innovations
A fundamental re-evaluation of chemical efficacy and lifecycle impact is underway. This shift is driven by the twin forces of stricter environmental mandates and the commercial availability of digital monitoring technologies that enable more precise chemical management.
Smart inhibitor technology incorporates stimuli-responsive mechanisms, such as nano-capsules that rupture to release protective agents when a change in pH signals the onset of corrosion. The aerospace and high-value manufacturing sectors are adopting this technology for critical component protection. As a result, the market's approach to asset integrity is migrating from scheduled, preventative chemical dosing to a more efficient, responsive, and on-demand protection model.
Regulatory frameworks are a primary catalyst for product reformulation. China's Ministry of Ecology and Environment (MEE) has enforced strict effluent standards as part of its "dual carbon" initiative, directly impacting industrial water circuits. This policy pressures operators in power generation and chemical manufacturing to phase out older, more toxic chemistries like chromates. The water treatment segment in China is most affected, accelerating the switch to compliant organic and biodegradable inhibitor formulations.
End-user buying behavior is evolving from transactional product purchasing toward acquiring corrosion control as a managed service. This service-intensive model, which bundles chemical supply with on-site monitoring, automated dosing systems, and performance reporting, is displacing traditional sales through distributors. The trend is most advanced in the North American and European water treatment and energy sectors, where operational efficiency and regulatory compliance are paramount.
Global Corrosion Inhibitor Market Segmentation
Understanding the market through segmentation reveals how diverse chemical solutions address specific industrial challenges. This granular view highlights the varying performance requirements and regulatory pressures influencing product development across different applications and end-user industries.
Product Type:
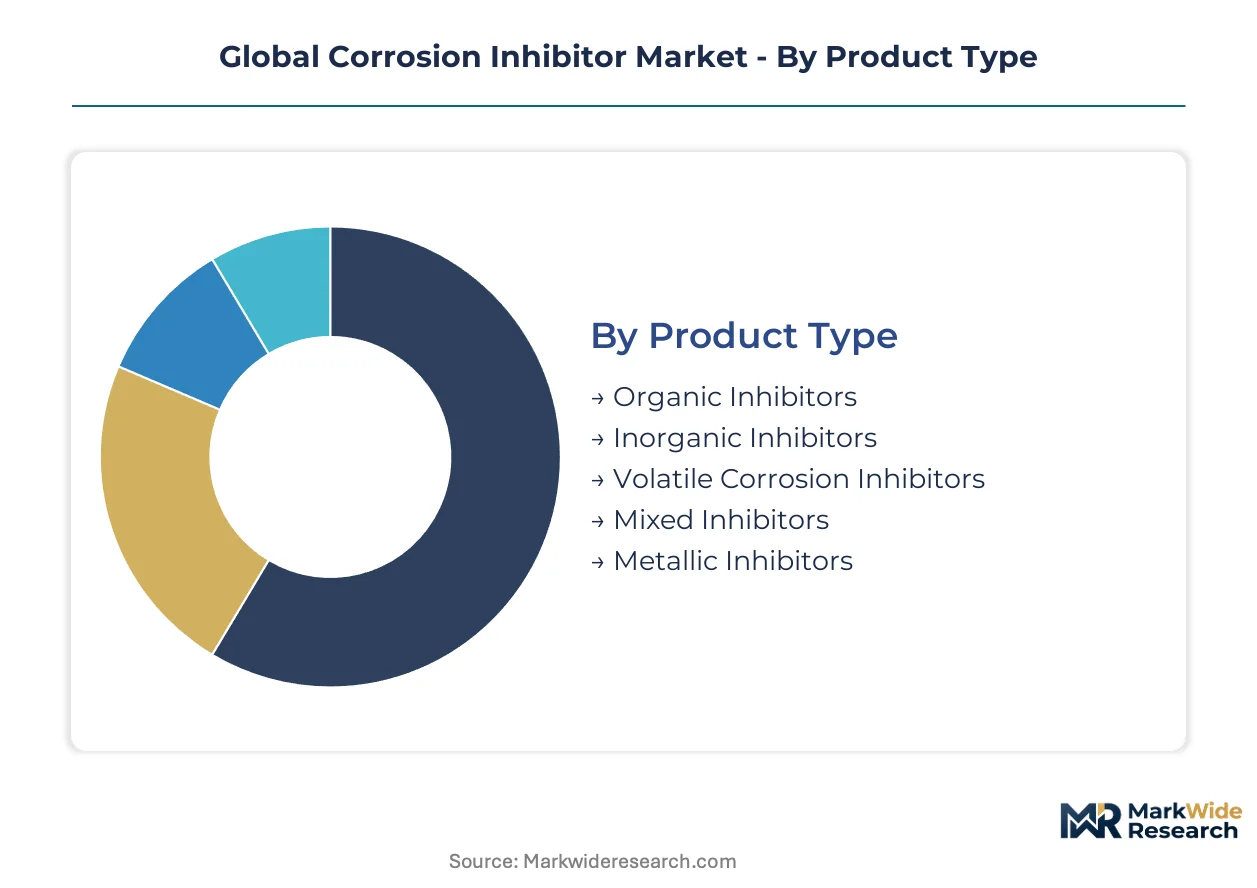
The product type segmentation highlights the diverse chemical compositions tailored for specific corrosive environments and material protection requirements.
- Organic Inhibitors:These compounds, often nitrogen or sulfur-containing, adsorb onto metal surfaces to form a protective film, offering broad effectiveness across various pH levels. Demand concentrates heavily in oil & gas applications and water treatment due to their versatility and performance in complex systems.
- Volatile Corrosion Inhibitors:VCIs are specialized compounds that vaporize and condense on metal surfaces, forming a molecular layer that prevents corrosion, particularly in enclosed spaces. Their primary demand stems from protecting metal components during transport, storage, and packaging to ensure product integrity.
- Inorganic Inhibitors:These traditional inhibitors, including phosphates and molybdates, primarily function by forming a passive layer on the metal surface. They find significant use in closed-loop cooling systems and some water treatment applications.
- Mixed Inhibitors:Combining both organic and inorganic compounds, mixed inhibitors leverage synergistic effects to achieve enhanced protection across a wider range of conditions. They are often deployed in systems with varied metallurgy or fluctuating operational parameters.
- Metallic Inhibitors:These inhibitors involve the use of sacrificial metals or metal ions to protect the primary metal, typically in highly specialized or niche applications. They offer targeted protection in specific electrochemical environments.
Established volume favors Organic Inhibitors; emerging adoption favors Volatile Corrosion Inhibitors.
Application:
The application segments delineate where corrosion inhibitors are critical for maintaining asset integrity across various industrial environments.
- Water Treatment:This segment includes preventing scale and corrosion in industrial cooling towers, boilers, and municipal water distribution systems. The demand is driven by the need to maintain infrastructure integrity, optimize operational efficiency, and comply with stringent water quality regulations in regions like the European Union.
- Oil & Gas:Inhibitors are essential for protecting pipelines, drilling equipment, and refining infrastructure from aggressive corrosive agents found in crude oil, natural gas, and produced water. Expansion into deeper, higher-pressure offshore environments necessitates sophisticated organic inhibitor packages for asset longevity.
- Metal Fabrication:Inhibitors are used during various stages of metal processing, including pickling, cleaning, and temporary storage, to prevent surface corrosion before further treatment or assembly. This ensures the quality and finish of manufactured metal components.
- Construction:Corrosion inhibitors protect steel reinforcement bars within concrete structures, extending the lifespan of bridges, buildings, and other infrastructure assets. They are incorporated into concrete admixtures or applied directly to rebar.
- Marine:This application involves protecting ships, offshore platforms, and port infrastructure from the highly corrosive effects of saltwater and marine atmospheres. Specialized coatings and inhibitors are crucial for long-term durability.
- Power Generation:Inhibitors safeguard critical equipment such as boilers, turbines, and cooling systems in thermal, nuclear, and renewable energy plants from corrosion. Operational reliability and efficiency depend on effective corrosion control in these facilities.
Water Treatment applications consistently drive inhibitor consumption, while Oil & Gas segments command premium product specifications.
End User Industry:
End user industries define the operational contexts where corrosion control is an essential component of asset management and process efficiency.
- Chemical Processing:This industry requires robust corrosion inhibitors to protect reactors, heat exchangers, and pipelines from aggressive chemicals and high-temperature processes. China's expanding chemical sector represents significant demand for these specialized formulations to prevent downtime and ensure product purity.
- Energy Producers:Inhibitors are vital for maintaining the integrity of power generation plants, including fossil fuel, nuclear, and renewable energy facilities. Operational reliability and safety standards in sectors such as offshore wind farms and geothermal power plants depend on effective corrosion protection for critical infrastructure.
- Petrochemical Plants:These facilities utilize inhibitors to combat corrosion caused by acidic components and high temperatures during the refining and processing of petroleum products. Preventing equipment failure is paramount for continuous operation.
- Metal Works:The metal works industry employs inhibitors for surface treatment, pickling operations, and temporary rust prevention on manufactured metal components. This ensures product quality and reduces material waste.
- Infrastructure Maintenance:Inhibitors are applied to protect public utilities, bridges, water pipelines, and other civil infrastructure from environmental degradation. Long-term asset preservation is a key driver in this segment.
Chemical Processing and Energy Producers represent significant high-value demand centers for specialized inhibitor formulations.
Form:
The form of corrosion inhibitors dictates their ease of application, dispersion characteristics, and suitability for various delivery systems.
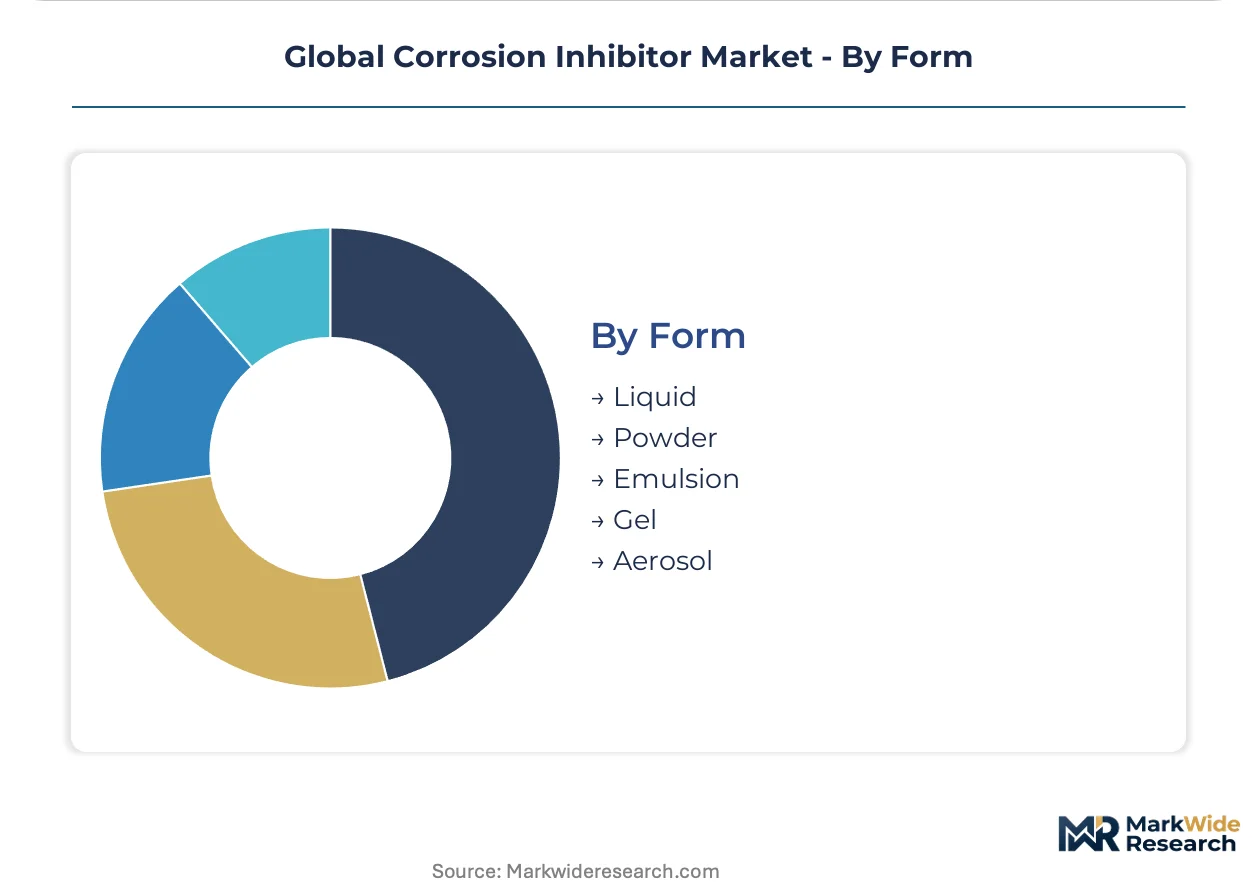
- Liquid:Liquid inhibitors, available as aqueous or oil-based solutions, are widely used due to their ease of handling, precise dosing capabilities, and uniform distribution in systems. They are a primary choice for continuous injection in water treatment systems and oil & gas pipelines.
- Powder:Powder inhibitors are solid formulations that are often dissolved in a solvent or dispersed directly into the system, offering advantages in transport efficiency and controlled release. They are particularly useful for batch treatments or dry storage applications where liquid forms are impractical.
- Emulsion:Emulsion forms consist of oil-in-water or water-in-oil dispersions, designed for specific delivery mechanisms or to achieve particular surface wetting properties. They are often used when a stable mixture of immiscible liquids is required.
- Gel:Gel inhibitors are viscous formulations that provide localized, long-lasting protection by adhering to specific surfaces. They are applied where targeted, slow-release corrosion control is necessary, such as in confined spaces or repair applications.
- Aerosol:Aerosol inhibitors are delivered via a spray, making them suitable for temporary protection of metal components or for application in hard-to-reach areas. They offer convenient, quick-drying corrosion prevention for small-scale or intermittent needs.
Liquid forms dominate bulk consumption, while specialized applications increasingly utilize Gel and Aerosol for targeted protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers of corrosion inhibitors concentrate in industrialized regions with extensive infrastructure and strict environmental mandates. These areas require advanced chemical solutions to protect critical assets from degradation. Infrastructure investment and stringent water regulations drive sustained demand across these markets.
China
Demand for corrosion inhibitors in China stems from its expanding chemical processing and infrastructure maintenance industries. The Ministry of Ecology and Environment (MEE) imposes strict effluent standards, influencing inhibitor selection for industrial water circuits. Major industrial zones like the Yangtze River Delta are seeing increased adoption of compliant organic and biodegradable formulations.
United States
The United States market requires corrosion inhibitors for its vast oil & gas infrastructure and municipal water treatment systems. EPA guidelines mandate higher water quality, compelling industrial plants to use advanced inhibitors. The Gulf Coast region, with its extensive petrochemical and offshore drilling operations, represents a significant demand center.
Germany
Germany's advanced manufacturing and power generation sectors drive demand for high-performance corrosion inhibitors. The European Union's REACH framework and Water Framework Directive steer product development towards lower-toxicity formulations. Industrial clusters in Bavaria focus on specialized organic inhibitors for complex industrial applications.
India
India's rapid urbanization and industrialization fuel the need for corrosion inhibitors in water infrastructure and chemical processing. The country's environmental regulations are evolving, pushing for more sustainable water treatment solutions. Major metropolitan areas like Mumbai and Delhi require significant investment in municipal water systems, boosting inhibitor consumption.
Vietnam
Vietnam's growing industrial base, particularly in manufacturing and infrastructure development, creates significant demand for corrosion inhibitors. Government initiatives to improve water quality and industrial wastewater treatment influence inhibitor selection. Industrial parks near Ho Chi Minh City are adopting advanced water treatment inhibitors for their expanding operations.
Global Corrosion Inhibitor Market Key Industry Players
Channel-controlling players compete with product-specialist players in the corrosion inhibitor market, creating a dynamic competitive environment. The market exhibits a moderately fragmented structure, with large chemical conglomerates offering broad portfolios alongside niche innovators focusing on specific technologies. Strategic archetypes include diversified chemical giants, application-focused service providers, and specialized product manufacturers. Portfolio diversification into bio-based formulations, geographic expansion, and strategic partnerships for technology co-development are dominant competitive moves among industry participants.
Specialists in advanced chemical synthesis, such as Germany-based BASF SE, occupy a position delivering broad-spectrum organic inhibitors for diverse industrial applications, leveraging extensive research and development capabilities. US-headquartered Ecolab exemplifies a service-intensive model, focusing on water treatment applications through comprehensive on-site management solutions and digital monitoring. Cortec Corporation represents a specialized product manufacturer, anchoring its offerings around Volatile Corrosion Inhibitors for metal component protection during storage and transport. These entities navigate the market by leveraging their distinct capabilities and market approaches, addressing various end-user requirements from high-volume industrial processes to niche protection needs with tailored solutions.
| Leading Market Players |
|---|
| BASF SE |
| Ecolab |
| Ashland |
| Nouryon |
| Cortec Corporation |
| The Lubrizol Company |
| Dow |
| Henkel |
| DuPont de Nemours |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock supply, particularly from Middle Eastern and Asian producers, concentrates margin pools at the upstream chemical synthesis stage. This structural dynamic directly impacts pricing power and profitability for downstream corrosion inhibitor formulators.
Pricing Analysis
Long-term supply agreements frequently operate on cost-plus contracts, often indexed to petrochemical commodity prices for key feedstocks like fatty amines. Price differentiation stems from performance efficacy in harsh industrial environments, regulatory compliance certifications such as REACH, and bundled on-site management services. Pricing softness reflects increasing competition from Asian manufacturers and the higher development costs for compliant bio-based alternatives. Water treatment and infrastructure maintenance segments exhibit high price sensitivity, whereas deepwater oil and gas applications prioritize inhibitor performance.
Supply Chain Analysis
Raw material sourcing for organic inhibitors heavily depends on a global network of chemical intermediate producers. Supply concentrates in regions like China and India, which provide key feedstocks such as fatty amines and imidazolines. The supply chain faces structural risk from single-source vulnerability for specialized performance additives. Distribution runs through a dual model, leveraging specialized chemical distributors for broader reach and direct sales channels for major industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corrosion inhibitor market presents a significant service-attach opportunity, with on-site monitoring and automated dosing systems expanding faster than chemical product sales. This shift allows vendors to capture recurring revenue streams and deepen customer relationships.
For Market Incumbents:Harden existing customer relationships by integrating advanced digital monitoring and automated dosing systems into service contracts. Invest heavily in R&D for next-generation bio-based and smart inhibitor technologies to counter the threat from specialized niche entrants. Expand channel control through strategic partnerships with regional service providers, especially in underserved markets. This strategy ensures long-term asset protection for critical infrastructure clients.
For New Entrants and Emerging Players:Establish a beachhead in underpenetrated segments like renewable energy infrastructure, particularly offshore wind farms, or the rapidly industrializing water treatment market in Vietnam. Focus on developing and certifying eco-friendly, REACH-compliant inhibitor formulations with demonstrable lifecycle cost advantages. A go-to-market angle emphasizing sustainability and regulatory adherence will resonate with increasingly environmentally conscious industrial buyers.
For Investors and Strategic Acquirers:Capital is best deployed toward acquiring niche innovators with proprietary bio-based or smart coating technologies, offering defensible intellectual property and high-performance solutions. These targets provide sustainable demand over the next decade as environmental regulations tighten globally. A key signal to watch is accelerated regulatory enforcement of effluent standards, particularly in China and India, which will drive rapid adoption of compliant inhibitor solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Investing in bio-based production reduces environmental impact and aligns with European Union REACH regulations. |
| Long-term Supply Agreement | Securing feedstock supply mitigates raw material price volatility for organic inhibitor manufacturers. |
| Joint Venture | Partnering for digital monitoring systems enhances service offerings for water treatment applications. |
| Capacity Expansion | Increasing production in China supports the expanding chemical processing and infrastructure maintenance industries. |
| Acquisition of Specialist Firm | Acquiring VCI technology bolsters portfolio for protecting metal components during transport and storage. |
Research Approach
A spread of perspectives from chemical R&D directors, plant managers, procurement leads, and environmental compliance officers converged on the working assumptions for this study. Primary interviews with these industry stakeholders were rigorously cross-referenced with extensive secondary research, including EPA guidelines, ECHA's REACH database, and China's MEE reports. This dual approach ensured bottom-up granularity and top-down market validation, providing a comprehensive data foundation.
The demand-supply balance for corrosion inhibitors was modeled through a robust analytical framework across the projection horizon. This framework segmented the market by product type, application, end-user industry, form, and regional regulatory frameworks to capture granular dynamics. Compound annual growth rates were derived from historical data analysis and projected future trends, considering inputs like infrastructure investment and evolving regulatory compliance costs.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or commodity price fluctuations would shift the trajectory. Forecasts reflect assumptions documented at publication, acknowledging potential impacts from geopolitical shifts. Cross-checking against World Bank industrial output data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Caprylhydroxamic Acid Market
Additives
Oxygen Scavengers Market
Additives
Chemical Silage Additives Market
Additives
Global Lubricating Oil Additives Market
Additives
Citric Acid Anhydrous Market
Additives
United Kingdom Sodium Reduction Ingredient Market
Additives
Ascorbyl Stearate Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Tris Nonylphenyl Phosphite Market
Additives
United States Betaine Market
Additives
India Feed Additives Market
Additives
Trioctyldodecyl Citrate Market
Additives
Piperonyl Butoxide (PBO) Market
Additives
Triazine UV Absorber Market
Additives
Germany Sodium Reduction Ingredient Market
Additives
Allura Red AC Market