
 Industrial Plastic Market | 2026-2036
Industrial Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Plastic Market Intelligence
Aftermarket service revenue for engineering-grade resin technical support is rewriting margin capture across the value chain. BASF leverages its global compounding network to anchor premium positioning in high-performance polymers. SABIC sustains cost leadership through backward integration into petrochemical feedstocks across Middle Eastern production hubs. Evonik Industries AG differentiates via R&D intensity in specialty polyamide formulations for medical and aerospace tiers.
Industrial plastics encompass thermoplastic and thermoset polymers engineered for load-bearing, chemical-resistant, or thermally stable performance in manufacturing environments, typically formulated with fillers, reinforcements, or stabilizers to meet tensile strength, flammability, or dielectric specifications for machinery, infrastructure, and transportation systems. Polyethylene and polypropylene together occupy the highest volume tiers, with polyethylene dominating commodity-grade packaging and pipe applications while polypropylene captures automotive interior and appliance segments where higher heat deflection temperatures justify modest premiums. Molding compounds represent the fastest-growing form category as injection and compression molding automation accelerates throughput for complex automotive parts and electronics housings.
The EPA regulates industrial plastic manufacturing emissions under Clean Air Act provisions, while OSHA sets workplace exposure limits for vinyl chloride monomer and other feedstock chemicals that shape plant location and capital expenditure decisions. REACH registration requirements in Europe restrict phthalate plasticizers and certain brominated flame retardants, redirecting formulation R&D toward bio-based plasticizers and phosphorus-based alternatives. China's MEE enforces wastewater and solid waste rules that compel domestic producers to adopt closed-loop recycling or face operating permit revocation. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance with multiple frameworks simultaneously will determine which producers retain market access versus face stranded capacity.
Market Dynamics
Automotive lightweighting mandates are compressing resin selection cycles across the value chain. OEMs now specify high-flow polyamides and long-fiber thermoplastics for structural components that previously used metal stampings, forcing compounders to compress qualification timelines from 18 months to under 9 months.
Growth Catalysts
- REACH chemical registration:European ECHA requirements for bio-based plasticizers are redirecting formulation R&D toward phosphorus-based flame retardants and non-phthalate alternatives, opening premium positioning for compliant suppliers.
- China's Yangtze River Delta:Integrated resin-to-part manufacturing clusters in Jiangsu and Zhejiang provinces concentrate procurement decisions, creating captive demand for locally compounded engineering grades.
- Injection molding automation:Automotive Tier-1 suppliers deploy collaborative robotics for complex electronics housings, accelerating throughput requirements for molding compounds with tighter dimensional tolerances.
Market Restraints
- Naphtha feedstock volatility:Middle Eastern petrochemical producers face margin compression when crude benchmarks spike, transmitting cost instability to polyethylene and polypropylene contract pricing.
- MEE wastewater enforcement:China's Ministry of Ecology and Environment mandates closed-loop recycling systems, threatening operating permit revocation for non-compliant domestic compounders lacking capital for retrofit.
- Metal substitution limits:High-temperature under-hood applications exceeding 200°C continuous service resist thermoplastic conversion, preserving cast aluminum dominance in powertrain structural components.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for automotive and electronics manufacturing are attracting resin compounders to Gujarat and Tamil Nadu industrial corridors ahead of localized supply chain buildout.
- Medical device sterilization:Gamma-stable polyamide formulations for surgical instrument trays represent underpenetrated demand as healthcare infrastructure expands across Southeast Asian markets.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive plastics create first-mover advantage for producers with verified bio-based content or renewable energy certificates.
Industry Challenges
- Compounding technician scarcity:Specialized expertise in twin-screw extrusion die design and filler dispersion rheology commands wage premiums that inflate fixed costs for mid-scale producers.
- Automotive PPAP timelines:Production part approval process documentation for new resin grades stretches 12-16 months, locking working capital in inventory before revenue recognition.
- Legacy ERP integration:Batch traceability systems for REACH-compliant formulations require middleware investment to connect with existing manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Plastic Market |
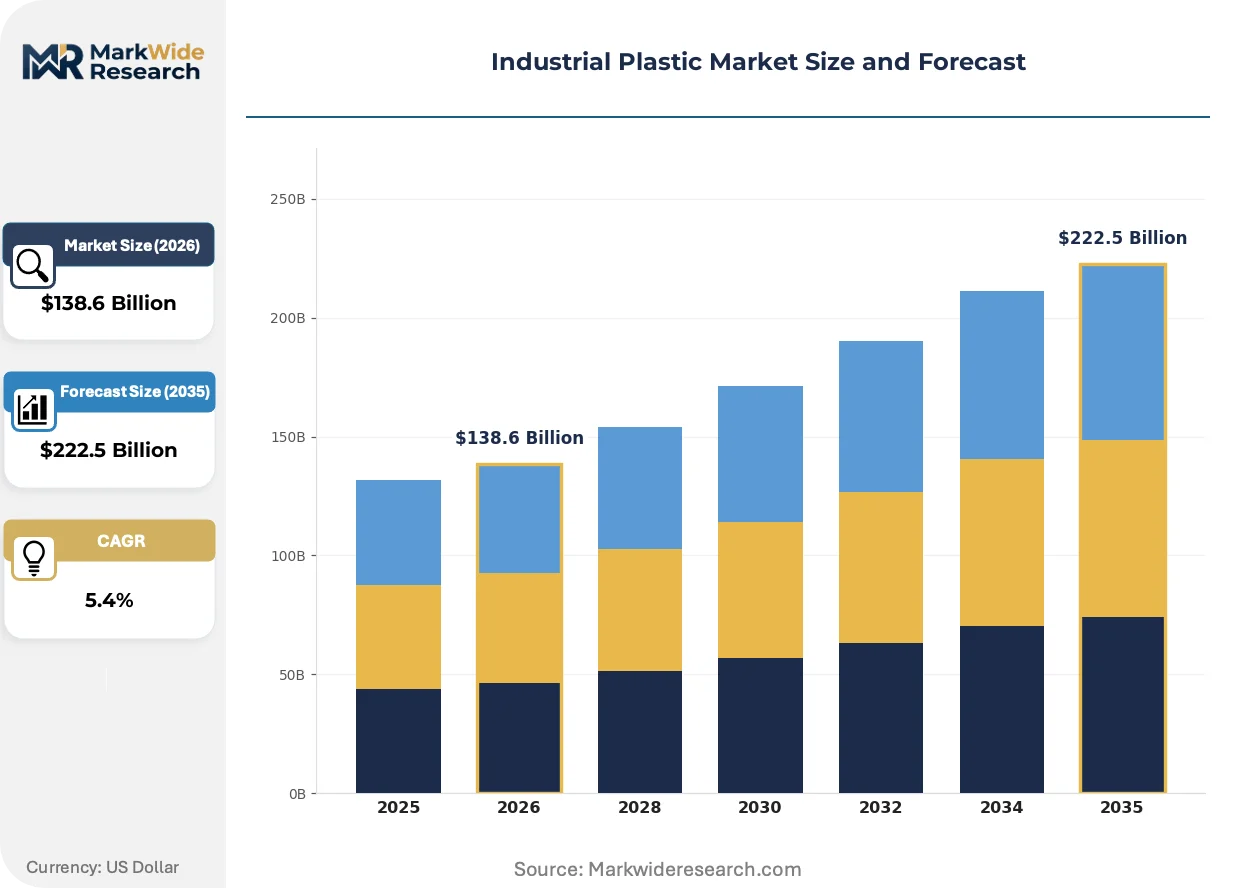
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $222.5 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, PVC End User: Automotive OEMs, Consumer Goods, Packaging Industry, Construction Form: Sheets, Films, Molding Compounds, Granules Application: Insulation, Containers, Automotive Parts, Electronics |
| Companies Covered | BASF, SABIC, Victrex plc, Ensinger, Evonik Industries AG, LyondellBasell Industries, Arkema Inc., Eastman Chemical Company, Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Plastic Market Strategic Shifts & Innovations
Material science breakthroughs are compressing the performance gap between commodity and engineering grades. Digital manufacturing tools now enable real-time viscosity adjustment during injection cycles, reducing scrap rates for thin-wall applications.
Continuous fiber-reinforced thermoplastic (CFRTP) tapes are rendering obsolete metal stampings in automotive seat structures and battery enclosures. BMW and Volkswagen Group chassis engineers specify unidirectional tape layups for crash-critical subframes. The shift eliminates welding operations and enables part consolidation that reduces assembly labor content by 30-40%.
REACH restrictions on brominated flame retardants are accelerating phosphorus-nitrogen synergist adoption in electrical housings. Compounders reformulate polybutylene terephthalate grades for connector applications to maintain UL 94 V-0 ratings without legacy halogen additives. Appliance manufacturers in Germany and France now specify halogen-free resins for dishwasher and washing machine control modules to preempt future regulatory expansion.
Automotive OEMs unbundle technical service contracts from resin supply agreements. Tier-1 molders now procure engineering support separately through specialized consultancies or compounder subscription programs. The decoupling is most advanced in Germany, where Bosch and Continental maintain independent material characterization laboratories that validate supplier data rather than relying on certificates of analysis.
Industrial Plastic Market Segmentation
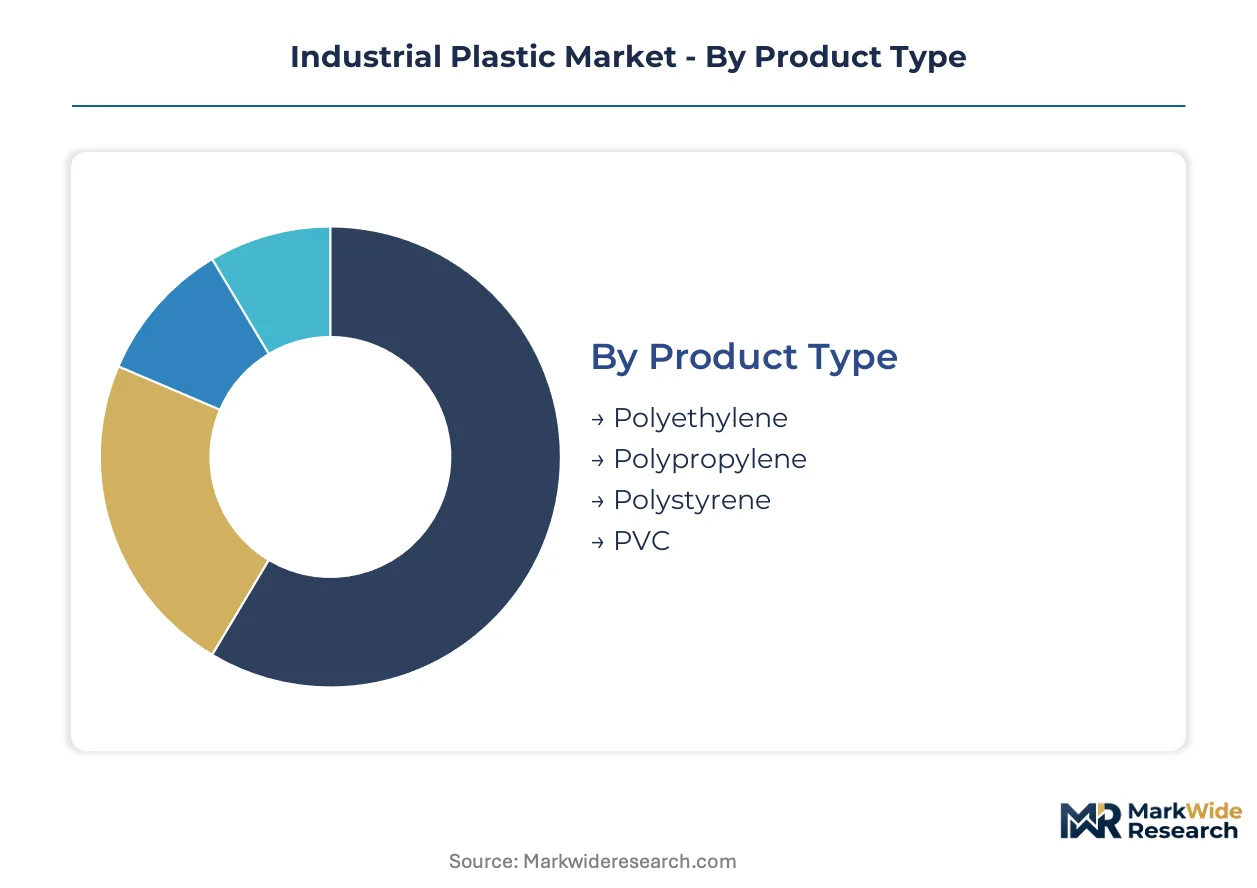
Industrial plastic procurement decisions cascade through multiple segmentation lenses simultaneously. Resin selection by product type determines baseline cost structures, while end-user specifications dictate performance tiers and compliance requirements.
Product Type:
Cost tier stratification separates commodity-grade volume leaders from specialty formulations commanding formulation premiums.
- Polyethylene:Linear low-density and high-density grades dominate pipe extrusion and flexible packaging applications. Yangtze River Delta converters source PE for water infrastructure projects where GB standard compliance mandates specific melt flow indices.
- Polypropylene:Homopolymer and copolymer variants capture automotive interior panels and appliance housings requiring heat deflection above 100°C. German OEMs specify PP compounds with long-glass reinforcement for under-hood air intake manifolds.
- Polystyrene:General-purpose and high-impact grades serve electronics packaging and disposable food service applications. India's expanding consumer goods manufacturing clusters in Gujarat drive expanded polystyrene demand for protective shipping.
- PVC:Rigid and plasticized formulations split between construction profiles and medical tubing segments. REACH phthalate restrictions redirect European flexible PVC compounding toward bio-based plasticizer alternatives.
Polyethylene holds installed capacity. Polypropylene is rotating up the share rankings.
End User:
Application intensity varies sharply across customer categories, with qualification timelines and technical service requirements defining supplier relationships.
- Automotive OEMs:Lightweighting mandates compress resin qualification cycles from 18 months to under 9 months. Volkswagen Group and BMW specify continuous fiber-reinforced thermoplastics for battery enclosure structures, eliminating metal stampings.
- Consumer Goods:Appliance manufacturers in France and Germany now mandate halogen-free resins for dishwasher control modules. Polypropylene captures washing machine drum assemblies where corrosion resistance outweighs metal alternatives.
- Packaging Industry:Food-grade polyethylene films face evolving EFSA migration limits for recycled content incorporation. Flexible packaging converters in China's Zhejiang province integrate closed-loop recycling to satisfy MEE wastewater enforcement.
- Construction:PVC profiles and PE pressure pipes dominate infrastructure specifications. India's PLI scheme for building materials attracts integrated resin-to-profile compounders to Tamil Nadu industrial corridors.
Automotive OEMs concentrate specification authority. Packaging Industry is climbing the fastest as sustainability mandates reshape material selection.
Form:
Processing technology alignment determines form factor demand, with automation readiness separating growth trajectories.
- Sheets:Extruded ABS and polycarbonate panels serve aircraft interior components and medical device housings. Thermoforming operations in Germany's Bavaria region specialize in aircraft-grade sheet calibration.
- Films:Biaxially oriented polypropylene and polyethylene terephthalate films capture flexible electronics and food barrier applications. Japan's METI efficiency standards accelerate thin-gauge film adoption for packaging minimization.
- Molding Compounds:Engineering-grade pellets with glass fiber or mineral fillers enable complex automotive electronics housings. Bosch and Continental subscription technical service programs validate molding compound performance independently of supply agreements.
- Granules:Virgin and compounded pellets feed downstream extrusion and injection operations. Compounders in Saudi Arabia leverage captive petrochemical feedstock for cost-advantaged polyethylene granule production.
Molding Compounds hold installed capacity. Granules is rotating up the share rankings.
Application:
Functional performance requirements segment demand by thermal, electrical, and mechanical specification intensity.
- Insulation:Cross-linked polyethylene and expanded polystyrene formulations serve electrical cable sheathing and building thermal barriers. EU Green Deal carbon border adjustments favor producers with renewable energy certificates for insulation-grade resins.
- Containers:HDPE and PP blow-molded vessels capture industrial chemical storage and consumer packaging. China's GB standards on plastic recyclability tighten material specifications for food-contact containers.
- Automotive Parts:Structural components previously metal-stamped now specify long-fiber thermoplastics and high-flow polyamides. Seat structures and crash-critical subframes adopt unidirectional CFRTP tape layups for part consolidation.
- Electronics:Flame-retardant polybutylene terephthalate grades maintain UL 94 V-0 ratings for connector applications. Phosphorus-nitrogen synergist formulations displace brominated retardants under REACH restrictions.
Automotive Parts hold installed capacity. Electronics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in commodity polyethylene segments exhibit acute price elasticity, while automotive OEMs purchasing long-fiber thermoplastics tolerate substantial formulation premiums for lightweighting compliance. This demand-elasticity contrast fragments procurement strategies across geographies.
China
Automotive battery enclosure demand and Yangtze River Delta manufacturing concentration anchor resin consumption. MEE wastewater enforcement compels Jiangsu and Zhejiang compounders to adopt closed-loop recycling or face permit revocation. Shanghai-based integrated resin-to-part ecosystems dominate procurement decisions for engineering-grade polyamides.
Germany
Volkswagen Group and BMW specifications for continuous fiber-reinforced thermoplastics drive high-performance polymer demand. REACH chemical registration requirements redirect formulation R&D toward phosphorus-based flame retardants and bio-based plasticizers. Bavaria's thermoforming specialists calibrate aircraft-grade polycarbonate sheets for aerospace interior contracts.
United States
EPA Clean Air Act provisions regulate manufacturing emissions while OSHA workplace exposure limits for vinyl chloride monomer shape plant location decisions. Gulf Coast petrochemical corridors leverage captive feedstock access for polyethylene granule cost advantages. Tier-1 automotive suppliers in Michigan deploy collaborative robotics for complex electronics housing production.
India
PLI scheme incentives for automotive and electronics manufacturing attract resin compounders to Gujarat and Tamil Nadu industrial corridors ahead of localized supply chain buildout. BIS standards compliance requirements tighten material specifications for domestic appliance manufacturers. Maharashtra's expanding consumer goods clusters drive expanded polystyrene demand for protective shipping applications.
Saudi Arabia
SABIC's backward integration into petrochemical feedstocks sustains cost leadership across polyethylene and polypropylene production. SFDA medical device regulations create compliance barriers for specialty formulation entrants. Eastern Province production hubs supply granule exports to South Asian and African conversion markets.
Industrial Plastic Market Key Industry Players
Capability concentration sits with specialty formulation developers; scale advantage sits with integrated petrochemical producers. The market structures around three tiers: global diversified chemical conglomerates with compounding networks, regional feedstock-integrated producers, and niche specialists in high-performance polymers. Consolidation pressure intensifies as automotive qualification timelines compress and regulatory compliance costs escalate. Dominant competitive moves include backward integration into monomer production and geographic expansion into PLI-subsidized manufacturing corridors.
Within the specialty formulation tier, Victrex plc and Ensinger exemplify high-performance polymer positioning, while Evonik Industries AG anchors the R&D-intensive segment for medical and aerospace applications. BASF represents the diversified chemical conglomerate archetype with global compounding network coverage. SABIC occupies the feedstock-integrated cost leadership position through Middle Eastern production scale. Arkema Inc. and Solvay SA sit within the European specialty chemicals cluster addressing REACH-compliant formulation demand.
| Leading Market Players |
|---|
| BASF |
| SABIC |
| Victrex plc |
| Ensinger |
| Evonik Industries AG |
| LyondellBasell Industries |
| Arkema Inc. |
| Eastman Chemical Company |
| Solvay SA |
| Others |
Cost & Logistics Intelligence
Naphtha feedstock volatility determines both margin compression at integrated petrochemical producers and the geographic clustering of compounding capacity near captive supply sources. Buyers in commodity polyethylene segments exhibit acute price elasticity, while automotive OEMs purchasing long-fiber thermoplastics tolerate substantial formulation premiums for lightweighting compliance.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between integrated petrochemical producers and large-volume converters, with spot markets filling residual demand swings. Price differentiation separates REACH-compliant specialty formulations from commodity grades, while volume scale and certification tier (UL 94 V-0, automotive PPAP) command additional premiums. Pricing pressure stems from naphtha cost transmission to polyethylene and polypropylene contract pricing when crude benchmarks spike. Packaging converters in China's Yangtze River Delta show highest price sensitivity; medical device and aerospace buyers show lowest.
Supply Chain Analysis
Export-control regimes on advanced compounding equipment and specialty additive formulations limit technology transfer to emerging production hubs. Supply concentrates in Saudi Arabia for captive feedstock-integrated polyethylene granules, in Germany for high-performance thermoplastic compounds, and in China's Jiangsu and Zhejiang provinces for integrated resin-to-part ecosystems. Raw material dependencies include naphtha-derived monomers, glass fiber reinforcements, and phosphorus-based flame retardant additives. Single-source vulnerability runs through Middle Eastern petrochemical corridors for base resin supply. Distribution runs through compounder technical service networks that bundle formulation support with material supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial plastic incumbents face sustained substitution pressure from continuous fiber-reinforced thermoplastic tapes displacing metal stampings in automotive structural applications. Defense of market position requires building durable competitive moats before qualification timelines compress further.
For Market Incumbents: Build regulatory compliance moats by accelerating REACH-aligned bio-based plasticizer and phosphorus-nitrogen flame retardant formulation portfolios ahead of phased halogen restrictions. Deepen backward integration into specialty additive production to capture margin currently leaked to third-party suppliers. Prioritize captive technical service capacity in Germany and China's Yangtze River Delta where OEMs unbundle engineering support from resin supply. For New Entrants and Emerging Players: Build out gamma-stable polyamide compounding capacity for surgical instrument trays across Southeast Asian healthcare infrastructure expansion corridors. Target India's PLI-subsidized automotive and electronics manufacturing clusters in Gujarat and Tamil Nadu ahead of localized supply chain maturation. Lead with subscription technical service programs that validate performance independently of material supply agreements, mirroring Bosch and Continental procurement patterns. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustment implementation reshapes the acquisition landscape toward producers with verified bio-based content or renewable energy certificates. Long-term viability favors specialty formulation developers with R&D intensity in medical and aerospace tiers over commodity volume players facing margin compression. Watch for MEE enforcement actions triggering distressed asset availability among non-compliant Chinese compounders lacking closed-loop recycling capital.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Additives | Captures margin from phosphorus-based flame retardant suppliers serving REACH-compliant electrical housing demand. |
| Long-term Supply Agreement with Yangtze River Delta Converters | Locks in procurement decisions for integrated resin-to-part ecosystems dominating engineering-grade polyamide demand. |
| Green Manufacturing Transition | Positions for EU Green Deal carbon border adjustment advantages through bio-based content verification and renewable energy certificates. |
| Joint Venture in India's PLI Corridors | Establishes localized compounding presence ahead of automotive and electronics supply chain buildout in Gujarat and Tamil Nadu. |
| Capacity Expansion for CFRTP Tape Production | Captures BMW and Volkswagen Group demand for unidirectional layups replacing metal stampings in battery enclosures. |
Research Approach
A standing panel of plant managers at integrated petrochemical facilities, procurement leads at automotive Tier-1 suppliers, distribution channel partners in Asian trading hubs, and technical R&D directors at specialty compounders provided ongoing calibration across the analysis window. Primary interview findings were cross-referenced with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration databases. Bottom-up resin consumption estimates by end-use application were reconciled with top-down petrochemical capacity and utilization data.
Scenario bracketing around naphtha price volatility, automotive lightweighting mandate acceleration, and regulatory enforcement intensity bounded the projection range. Segmentation modeling spanned product type tiers, end-use industry intensity, form factor automation readiness, and regional production hub regulatory clusters. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines. Key forecast inputs included automotive platform electrification rates and medical device sterilization infrastructure buildout across Southeast Asia.
Stress conditions across crude benchmark spikes, MEE permit revocation waves, and REACH restriction phase-in schedules were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding sustained automotive lightweighting compliance pressure and incremental bio-based formulation cost parity timelines. Material shifts in carbon border adjustment tariff schedules or abrupt feedstock supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Global Recycled Plastics Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
India Plastic Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
Global Post-Consumer Recycled Plastics Market
Recycled Plastics
North America BPA Free Plastic Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Circular Plastic Feedstock Traceability Market
Recycled Plastics
Plastic Waste Management Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
Fiber-Reinforced Plastic (FRP) Recycling Market
Recycled Plastics
United States Non-Ferrous Scrap Recycling Market
Recycled Plastics
Recycled Carbon Fiber Market
Recycled Plastics
Aluminum Recycling Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Polyvinyl Chloride (PVC) Market