
 Rubber Masterbatch Market | 2026-2036
Rubber Masterbatch Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Masterbatch Market Intelligence
Market Context
REACH regulation in Europe is rebalancing procurement priorities toward compliant, low-aromatic masterbatch formulations for tire and industrial rubber applications. Cabot Corporation leverages its integrated carbon black and masterbatch operations to sustain supply security across North American automotive plants. Lanxess anchors its position through specialized additive masterbatches that meet stringent heat-resistance specifications for under-the-hood components. BASF SE competes on polymer expertise, extending its color and additive portfolios into medical-grade rubber segments.
Technical Definition and Structural Segments
Rubber masterbatch denotes a concentrated dispersion of pigments, fillers, or functional additives predistributed in a rubber polymer carrier, typically containing 30-70% active ingredient by weight to ensure uniform incorporation during compounding. Black masterbatch dominates volume due to carbon black's irreplaceable reinforcement and UV-protection roles in tire treads, while additive masterbatch represents the fastest-expanding margin pool as antidegradant and curing-agent dispersions replace dusty powder handling. Tires anchor application demand, though seals and gaskets gain share from electric vehicle thermal-management requirements and healthcare device sterilization protocols.
Regulatory Frame and Outlook
EPA oversight of polycyclic aromatic hydrocarbon emissions and ECHA REACH restrictions on aromatic oils constrain formulation choices for suppliers serving transatlantic OEMs. China's MEE enforcement of dual carbon goals and evolving GB standards for rubber products reshape local production chemistry and import eligibility. FDA and EU MDR compliance for healthcare-grade masterbatches add certification layers that filter supplier bases. Stakeholders must monitor regulatory divergence between jurisdictions to align R&D pipelines and avoid stranded formulation investments.
Market Dynamics
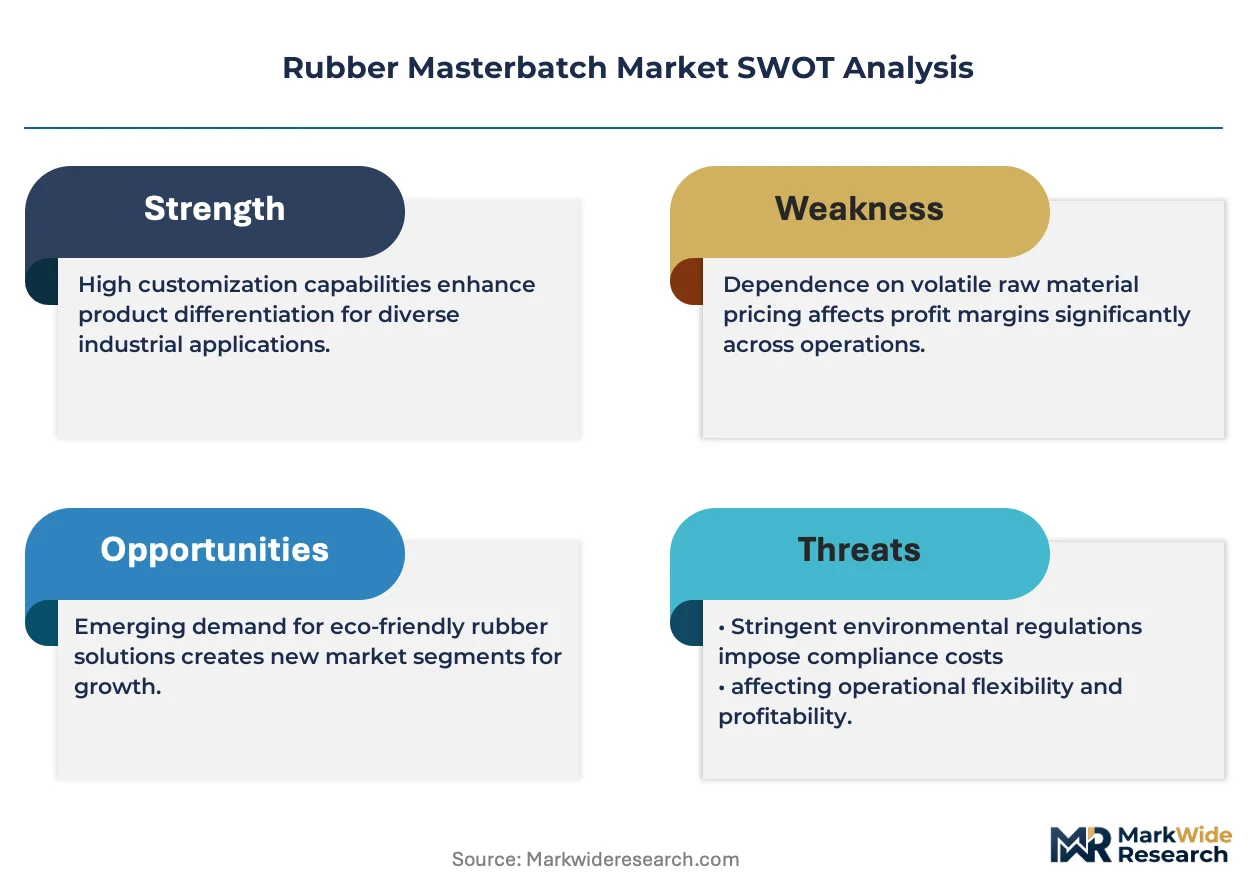
REACH restrictions on polycyclic aromatic hydrocarbons and EPA emissions standards are forcing tire manufacturers to reformulate carbon black masterbatches, compressing supplier margins while opening certification premiums for compliant producers.
Growth Catalysts
- EU Green Deal compliance mandates:Tire OEMs serving European automotive plants now specify low-PAH masterbatches to meet ECHA thresholds, redirecting procurement budgets toward certified suppliers.
- Electric vehicle thermal management:Seals and gaskets for battery cooling systems require heat-resistant additive masterbatches, expanding addressable demand beyond traditional tire applications.
- China's domestic tire scaling:MEE enforcement of dual carbon goals accelerates local masterbatch production capacity to serve continental rubber goods manufacturing.
Market Restraints
- Carbon black feedstock volatility:Crude oil and coal tar price swings compress formulation margins for black masterbatch producers serving price-locked automotive contracts.
- Specialty additive supply concentration:Antidegradant and curing-agent dispersion technologies cluster among a limited set of European and Japanese chemical suppliers, creating single-source vulnerability.
- Bio-based carbon black performance gaps:Renewable feedstock-derived blacks fail to match furnace black reinforcement indices in heavy-duty tire treads, limiting substitution rates.
Strategic Opportunities
- India PLI scheme for rubber goods:Domestic tire and conveyor belt manufacturing incentives create localized masterbatch demand requiring technical partnership entry.
- Medical-grade rubber certification:FDA and EU MDR compliance for healthcare device masterbatches filters competition to polymer specialists with cleanroom compounding capability.
- Digital formulation platforms:AI-driven dispersion optimization converges with laboratory automation to compress R&D cycle times for custom masterbatch development.
Industry Challenges
- Compounding technician scarcity:Specialized rubber polymer processing expertise concentrates among aging workforces in Germany and Japan, constraining capacity expansion.
- Multi-jurisdiction certification timelines:Simultaneous EPA, REACH, and GB standard compliance testing extends product launch windows by twelve to eighteen months.
- Legacy mixing equipment incompatibility:High-shear dispersion masterbatches require capital-intensive Banbury upgrades that mid-tier compounders defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Masterbatch Market |
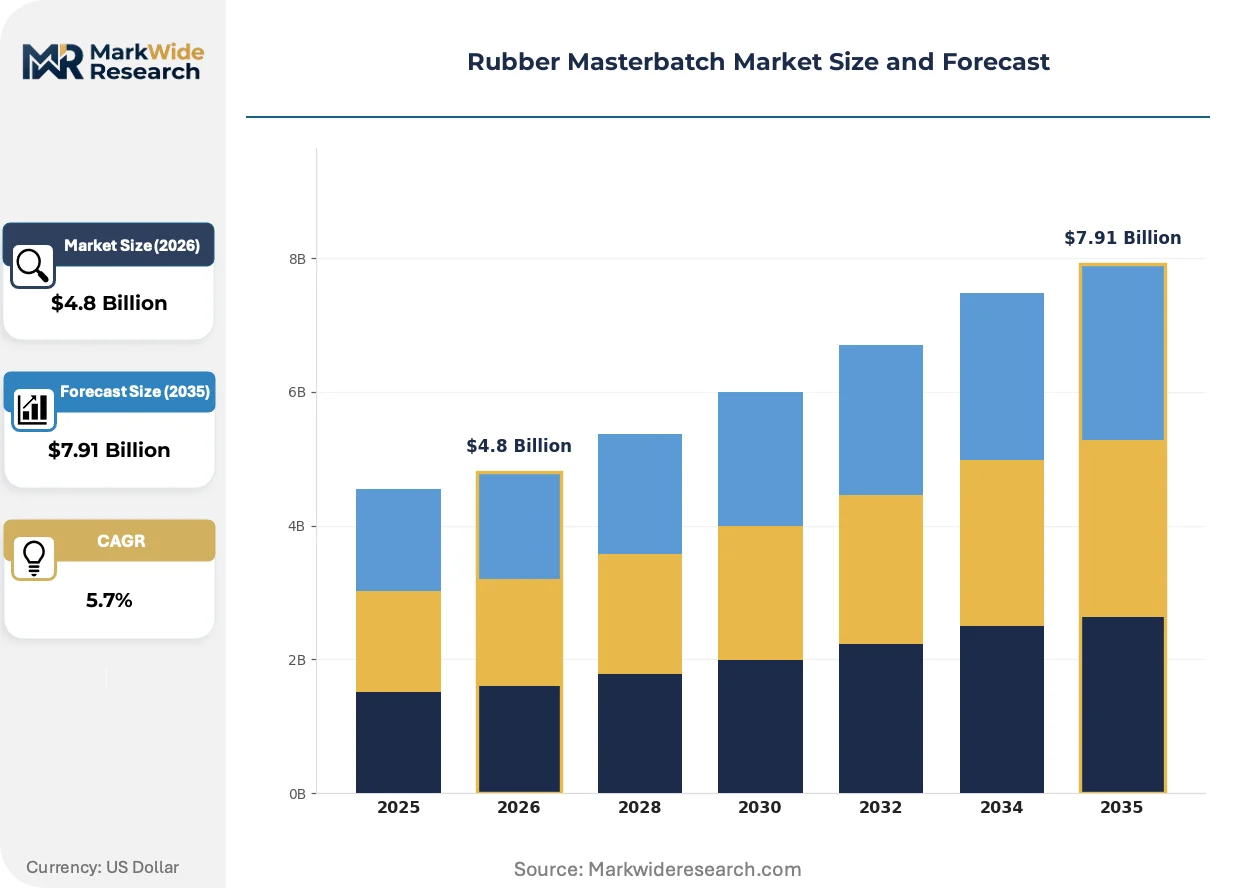
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Masterbatch, White Masterbatch, Color Masterbatch, Additive Masterbatch Application: Tires, Rubber Sheets, Seals, Gaskets End User: Automotive, Industrial, Consumer Goods, Healthcare Packaging Type: Bag, Bulk, Drum, Pallet |
| Companies Covered | Cabot Corporation, Avient Corporation, Lanxess, Clariant AG, Dow Inc., PolyOne, BASF SE, Ampacet Corporation, Versalis S.p.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Masterbatch Market Strategic Shifts & Innovations
Formulation intelligence platforms and regulatory chemistry convergence are compressing development cycles while fragmenting procurement authority between sustainability officers and traditional materials engineers.
Continuous liquid mixing technology is automating masterbatch dispersion consistency. Tier-one tire manufacturers in Germany and South Korea adopt these systems for high-volume tread compounds. The technology is automating batch-to-batch variance reduction that previously required manual laboratory adjustment.
REACH Annex XVII restrictions on aromatic extender oils are eliminating legacy processing aids from tire formulations. Compounders must validate alternative plasticizers without sacrificing Mooney viscosity targets. Passenger tire segments serving European OEMs face the steepest reformulation costs and timeline pressure.
Automotive procurement teams now mandate cradle-to-gate carbon disclosure for masterbatch suppliers. Tier-one tire makers in Japan and the United States unbundle sustainability certification from price negotiations. Battery electric vehicle platforms exhibit the strictest supplier qualification thresholds for Scope 3 emissions documentation.
Rubber Masterbatch Market Segmentation
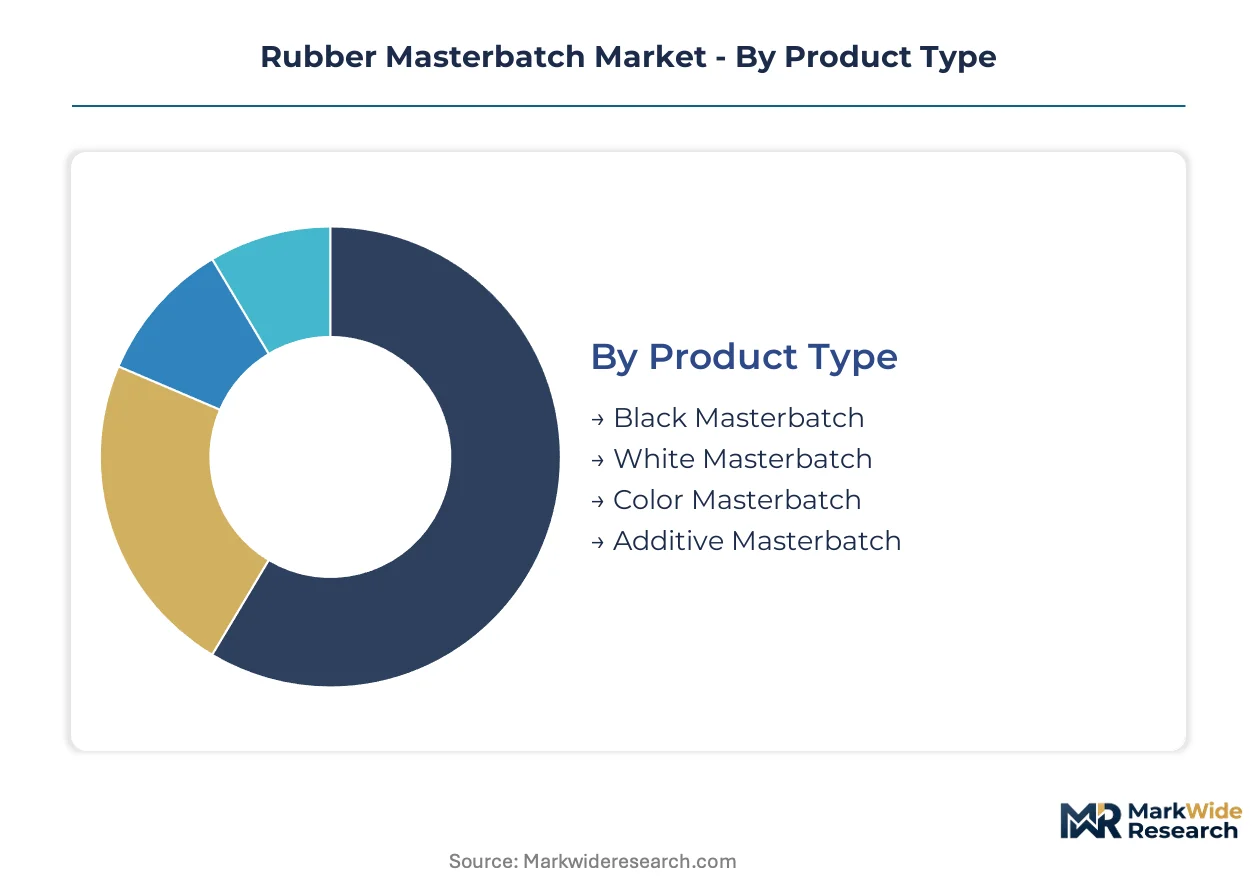
Rubber masterbatch segmentation reveals how formulation chemistry, end-use specifications, and supply chain logistics fragment procurement decisions across tire OEMs and industrial compounders. Each dimension carries distinct margin profiles and certification requirements that reshape supplier positioning.
Product Type:
Buyers differentiate by reinforcement performance versus regulatory compliance burden, with carbon black formulations facing stricter PAH thresholds than specialty additive dispersions.
- Black Masterbatch:Concentrated carbon black dispersions in rubber carriers deliver tensile strength and UV protection for tire treads. Demand concentrates in China and Germany where domestic tire production scales and REACH compliance mandates redirect procurement toward low-aromatic certified suppliers.
- Additive Masterbatch:Pre-dispersed antidegradants, curing agents, and processing aids replace dusty powder handling with cleanroom-compounded solutions. Electric vehicle battery sealing applications in Japan and South Korea drive the steepest volume expansion as thermal management specifications tighten.
- Color Masterbatch:Pigment concentrates for aesthetic and coding applications in consumer goods and industrial hoses.
- White Masterbatch:Titanium dioxide or mineral-based dispersions serving healthcare device manufacturers requiring sterilization-compatible formulations.
Black Masterbatch leads volumes today; Additive Masterbatch is gaining share fastest.
Application:
Volume scale and formulation complexity diverge sharply between commodity tire production and precision-engineered sealing systems for electrified powertrains.
- Tires:Tread, sidewall, and inner liner compounds consume the majority of carbon black masterbatch globally. Procurement from Germany, Japan, and the United States tilts toward suppliers with integrated carbon black operations and cradle-to-gate carbon disclosure capabilities mandated by automotive OEMs.
- Seals:Dynamic and static sealing systems for battery thermal management and fuel systems require heat-resistant additive packages. Chinese and South Korean electric vehicle manufacturing clusters are expanding specification-driven demand faster than traditional automotive segments.
- Gaskets:Compression-molded and cut-gasket applications for industrial and automotive fluid systems.
- Rubber Sheets:Conveyor belting, flooring, and roofing membranes serving mining and construction sectors with standardized formulation requirements.
Tires anchor absolute demand; Seals demonstrate the most rapid application expansion.
End User:
Certification intensity and pricing power vary from automotive's sustainability audits to healthcare's cleanroom compliance layers.
- Automotive:Tier-one tire and component manufacturers specify masterbatches with validated low-PAH content and documented Scope 3 emissions. European and Japanese OEMs unbundle sustainability certification from price negotiations, creating premium tiers for compliant suppliers.
- Healthcare:FDA and EU MDR compliance for medical-grade rubber devices filters competition to polymer specialists with validated cleanroom compounding and extractables testing protocols.
- Industrial:Conveyor belt, hose, and molded goods manufacturers prioritizing formulation cost and supply security over certification depth.
- Consumer Goods:Footwear, sporting equipment, and household product applications with color consistency and skin-contact safety requirements.
Automotive commands the largest procurement budgets; Healthcare exhibits the steepest margin expansion.
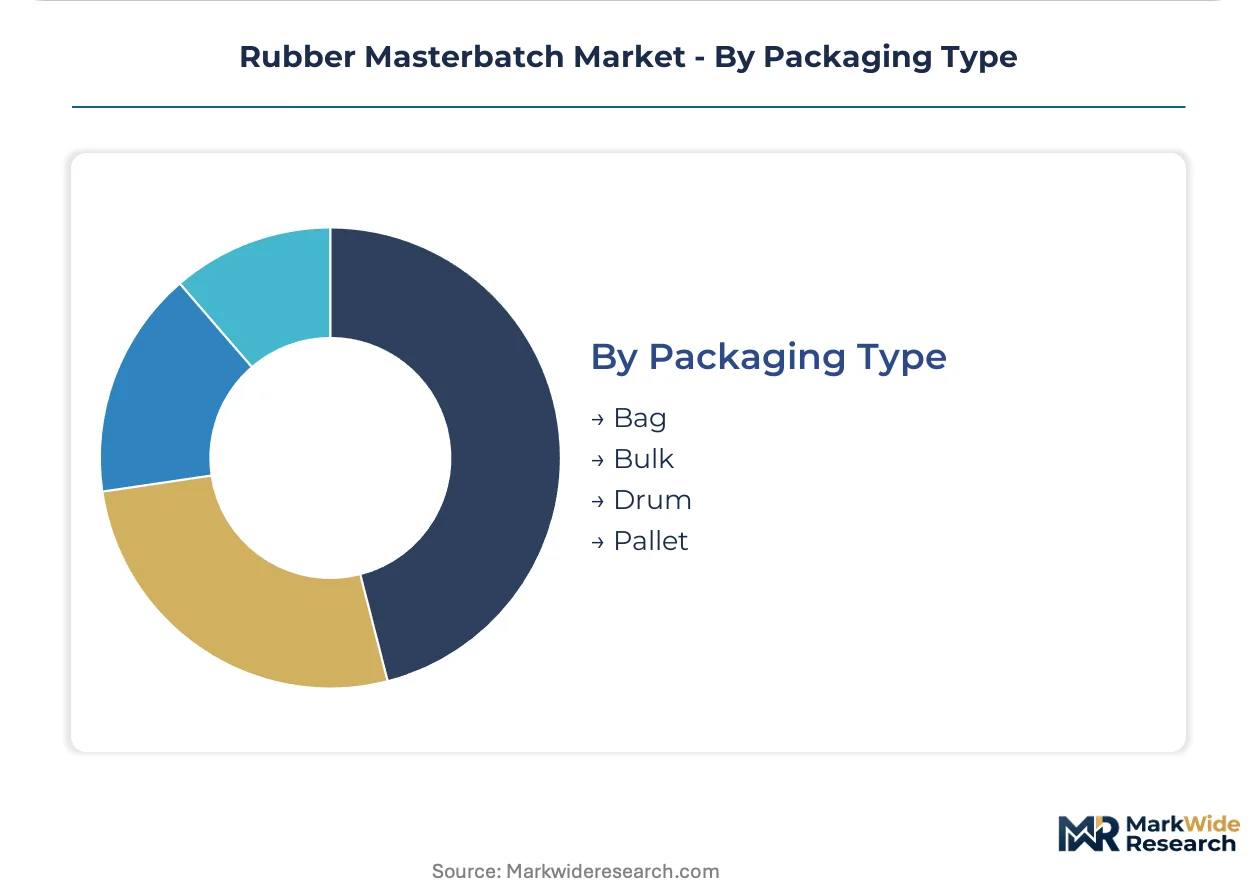
Packaging Type:
Logistics economics and contamination risk shape preferences between bulk integrated supply and packaged flexibility for smaller compounders.
- Bulk:Tanker and silo delivery systems serve high-volume tire plants in Germany, the United States, and China with direct pipeline integration, minimizing handling costs and dust exposure.
- Bag:25kg multi-layer paper or PE bags dominate mid-tier compounders in India and Southeast Asia requiring inventory flexibility and reduced capital commitment.
- Drum:Steel or fiber containers for liquid additive masterbatches and specialty formulations with shelf-life sensitivity.
- Pallet:Unitized loads for automated warehouse systems at large automotive component manufacturers.
Bulk shipments dominate tonnage; Bag packaging shows the most rapid adoption in emerging manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rubber masterbatch production originated in German industrial chemistry during the early twentieth century, with Bayer and BASF pioneering carbon black dispersion technologies for tire manufacturing. The industry subsequently dispersed across North American petrochemical corridors and East Asian manufacturing zones.
China
Domestic tire production in Shandong and Jiangsu provinces consumes the majority of Asia-Pacific masterbatch tonnage. MEE enforcement of dual carbon goals is accelerating local carbon black capacity upgrades to serve continental rubber goods manufacturing. Qingdao and Shanghai host the densest clusters of integrated masterbatch compounding operations.
Germany
Continental and Michelin tire plants in Lower Saxony and Baden-Württemberg specify low-PAH formulations to meet ECHA REACH Annex XVII thresholds. KBA vehicle certification requirements cascade into masterbatch procurement audits for automotive suppliers. The Cologne-Düsseldorf chemical corridor retains specialized additive dispersion expertise for under-the-hood applications.
United States
EPA emissions standards for carbon black production are reshaping formulation choices at tire plants in South Carolina and Ohio. NHTSA fuel economy regulations indirectly drive lightweight masterbatch demand through tire rolling-resistance specifications. The Gulf Coast petrochemical corridor supplies feedstock for domestic black masterbatch production.
Japan
Bridgestone and Sumitomo Rubber operations in Kansai and Chubu regions require heat-resistant additive packages for electric vehicle battery sealing applications. METI carbon neutrality roadmaps are pressuring suppliers to document Scope 3 emissions across masterbatch supply chains. Yokkaichi industrial complexes concentrate specialty rubber chemical production.
India
PLI scheme incentives for domestic tire and conveyor belt manufacturing are creating localized masterbatch demand in Maharashtra and Gujarat. BIS quality certification requirements are filtering import eligibility for foreign compounders. Chennai and Pune automotive clusters are expanding specification-driven procurement for passenger vehicle tires.
Rubber Masterbatch Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and formulation specialization. The vendor base organizes into three tiers: integrated carbon black producers with captive masterbatch operations, specialized additive compounders with cleanroom capability, and regional toll compounders serving price-sensitive industrial rubber segments. Dominant competitive moves include backward integration into carbon black production and geographic expansion through technical partnerships in emerging manufacturing clusters.
Among integrated chemical producers, Cabot Corporation and BASF SE exemplify the upstream-control archetype through captive carbon black and polymer expertise. Lanxess occupies a position within the specialty additive tier, representing the heat-resistance and antidegradant formulation specialists that serve automotive under-the-hood specifications. Clariant AG sits within the precision-compounding segment, anchoring the cleanroom-capable suppliers that filter into healthcare and medical-grade rubber applications.
| Leading Market Players |
|---|
| Cabot Corporation |
| Avient Corporation |
| Lanxess |
| Clariant AG |
| Dow Inc. |
| PolyOne |
| BASF SE |
| Ampacet Corporation |
| Versalis S.p.A |
| Others |
Cost & Logistics Intelligence
Carbon black feedstock volatility transmits directly through masterbatch pricing tiers, with furnace oil and coal tar cost swings compressing margins for commodity black formulations while low-PAH certified grades command automotive procurement premiums. This input-cost cascade separates integrated carbon black producers from toll compounders serving price-locked industrial rubber contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes procurement decisions by certification grade and volume scale. Premium tiers attach to REACH-compliant low-PAH formulations and FDA-validated medical grades, while economy tiers serve conveyor belt and construction rubber with basic carbon black dispersions. Pricing pressure stems from crude oil derivative volatility squeezing black masterbatch margins, with automotive OEMs least price-sensitive due to sustainability audit requirements and Indian industrial compounders most sensitive due to PLI scheme cost targets.
Supply Chain Analysis
Dual-sourcing requirements from German and Japanese automotive OEMs mandate qualified backup suppliers for critical additive masterbatches, fragmenting procurement authority between sustainability officers and materials engineers. Supply concentrates in China, Germany, and the United States, with carbon black feedstock drawing from Gulf Coast petrochemical corridors and coal tar distillation in Shandong province. Single-source vulnerability clusters around European and Japanese antidegradant dispersion technologies. Distribution runs through bulk tanker systems for high-volume tire plants and bagged formats for emerging manufacturing clusters in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in rubber masterbatch hinges on certification premium capture as automotive procurement unbundles sustainability compliance from price negotiations, compressing commodity tier returns while expanding cleanroom-compounded healthcare grades.
For Market Incumbents: Acquire captive carbon black production capacity to secure feedstock cost control against crude oil volatility threatening commodity tier margins. Defend automotive supply positions by accelerating REACH Annex XVII pre-certification for low-PAH formulations before ECHA enforcement tightens. Deepen technical partnership networks in Maharashtra and Gujarat to capture PLI-scheme driven localization demand before foreign compounders establish import eligibility. For New Entrants and Emerging Players: Capture medical-grade rubber masterbatch white space where FDA and EU MDR compliance filters competition to cleanroom-capable specialists. Target electric vehicle battery sealing applications in South Korean and Chinese manufacturing clusters where thermal management specifications outpace incumbent capacity. Enter through technical licensing arrangements with established additive dispersion specialists rather than greenfield Banbury mixing investments. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier compounders face twelve-to-eighteen-month multi-jurisdiction certification timelines that strand formulation investments. Long-term viability favors polymer specialists with integrated carbon black operations and validated healthcare cleanroom protocols over regional toll compounders. Watch for MEE enforcement intensity in Shandong province as the signal indicating whether Chinese domestic capacity expansion accelerates or import substitution stalls.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Black | Cabot Corporation's captive furnace operations insulate margin from feedstock volatility affecting toll compounders. |
| REACH Pre-Certification Investment | Early ECHA Annex XVII validation secures automotive procurement preference before compliance mandates harden. |
| Cleanroom Compounding Capacity | FDA-validated medical-grade production filters competition to polymer specialists with extractables testing protocols. |
| Technical Partnership in India | PLI scheme localization requirements create entry pathways without full capital commitment to greenfield plants. |
| Digital Formulation Platform | AI-driven dispersion optimization compresses R&D cycle times for custom masterbatch development serving EV sealing applications. |
Research Approach
Coverage spans China, Germany, the United States, Japan, and India, with primary inputs from each major production cluster combining interviews with tire plant procurement managers, rubber compounding technical directors, automotive OEM sustainability officers, and healthcare device regulatory affairs leads. Secondary validation draws from customs trade data, ECHA REACH registration databases, SEC carbon disclosure filings, and BIS quality certification records. Bottom-up segment sizing triangulates against top-down macroeconomic elasticity estimates.
Rate-of-change decomposition separates volume growth from value expansion across product type, application, end user, and packaging format dimensions throughout the forecast period. CAGRs derive from regression against automotive production indices, tire OEM capital expenditure patterns, and electric vehicle battery sealing content per vehicle trajectories. Modeled inputs include carbon black reinforcement index specifications, PAH threshold evolution under ECHA and EPA oversight, and dual carbon goal enforcement intensity from China's MEE.
Feedstock price volatility, regulatory threshold acceleration, and electric vehicle platform standardization are the dominant revision risks to modeled outputs. Deviation in MEE enforcement consistency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Polybutadiene Elastomers Market
Rubber
Polyisoprene Rubber Market
Rubber
Nitrile Butadiene Rubber (NBR) Latex Market
Rubber
Isoprene Rubber (IR) Latex Market
Rubber
Recycled Elastomers Market
Rubber
Rubber Color Masterbatch Market
Rubber
Europe Silicone Rubber Market
Rubber
Tire and Rubber Lubricants Market
Rubber
Isobutylene Market
Rubber
Synthetic Polyisoprene Rubber Market
Rubber
Fast Curing Nitrile Butadiene Rubber (NBR) Market
Rubber
Isoprene Rubber Market
Rubber
Gum Rosin Market
Rubber
Butyl Rubber Market
Rubber
Rubber Coatings Market
Rubber
Global Rubber Vulcanization Market