
 Ammonium Phosphatide Market | 2026-2036
Ammonium Phosphatide Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Phosphatide Market Outlook
The EU Green Deal is expanding requirements for sustainable food ingredient sourcing across European chocolate and confectionery supply chains. BASF leverages its integrated oleochemicals network to secure raw material streams for phosphatide production. Cargill anchors its position through backward integration into vegetable oil refining, while Palsgaard A/S specializes in application-specific emulsifier formulations for industrial chocolate processing.
Ammonium phosphatide is a phospholipid-based emulsifier synthesized from ammonia and phosphatidic acid derivatives, typically containing 30-40% phosphorous content and functioning as a viscosity reducer in chocolate mass at dosage levels of 0.3-0.5%. Its primary commercial purpose is to replace lecithin in chocolate manufacturing, enabling reduced cocoa butter content while maintaining flow properties and shelf stability. The liquid product type dominates current volume flows due to ease of incorporation into continuous chocolate processing lines. Pharmaceutical applications represent the fastest-expanding segment as tablet coating and lipid-based drug delivery systems advance. The food additive application remains the mature revenue core, with margin pools concentrated in certified halal and kosher grades serving premium confectionery brands.
EMA food contact guidelines and EFSA purity standards shape product specifications for pharmaceutical-grade ammonium phosphatide entering European markets. REACH registration requirements govern the chemical identity and impurity profiling of phospholipid derivatives used across food and drug applications. FDA GRAS status for ammonium phosphatide in chocolate manufacturing provides parallel market access in the United States. Stakeholders must monitor evolving clean-label certification schemes and regional regulatory divergence between EU and North American purity thresholds.
Market Dynamics
REACH compliance in the European Union is tightening purity thresholds for food-grade phosphatides, forcing manufacturers to reconfigure refining processes and recertify supply chains ahead of the 2025-2026 regulatory window.
Growth Catalysts
- Clean-label procurement acceleration:Chocolate manufacturers in Germany and Belgium are accelerating procurement of clean-label emulsifiers to meet retailer sustainability mandates and consumer transparency expectations.
- Pharmaceutical-grade expansion:EMA food contact guidelines and EFSA purity standards are creating certified pathways for ammonium phosphatide entry into tablet coating and lipid-based drug delivery systems.
- Halal and kosher certification premiums:Premium confectionery brands are concentrating demand in certified halal and kosher grades, expanding margin pools for compliant producers.
Market Restraints
- Vegetable oil feedstock volatility:Rapeseed and sunflower oil price swings in Black Sea sourcing regions transmit directly into phosphatide production costs.
- Regulatory divergence friction:Divergence between EU REACH purity thresholds and FDA GRAS status requirements creates dual-compliance burdens for cross-Atlantic suppliers.
- Lecithin substitution economics:Soy and sunflower lecithin maintain cost advantages in commodity chocolate segments, capping ammonium phosphatide penetration in price-sensitive applications.
Strategic Opportunities
- Pharmaceutical application white space:Lipid-based drug delivery systems in North American and European markets represent underpenetrated demand for high-purity phosphatide grades.
- EU Green Deal sourcing mandates:Sustainable food ingredient sourcing requirements across European chocolate supply chains create preference tailwinds for certified-sustainable emulsifier producers.
- Liquid-to-powder format innovation:Spray-dried and agglomerated powder formats are opening distribution channels into artisanal and small-batch chocolate processing equipment.
Industry Challenges
- Specialized process engineering talent scarcity:Phospholipid extraction and ammonia reaction optimization require chemists with oleochemical synthesis experience that concentrates in legacy European and North American refining hubs.
- Multi-jurisdiction certification timelines:Parallel halal, kosher, and pharmaceutical-grade audits extend product launch cycles by 12-18 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Phosphatide Market |
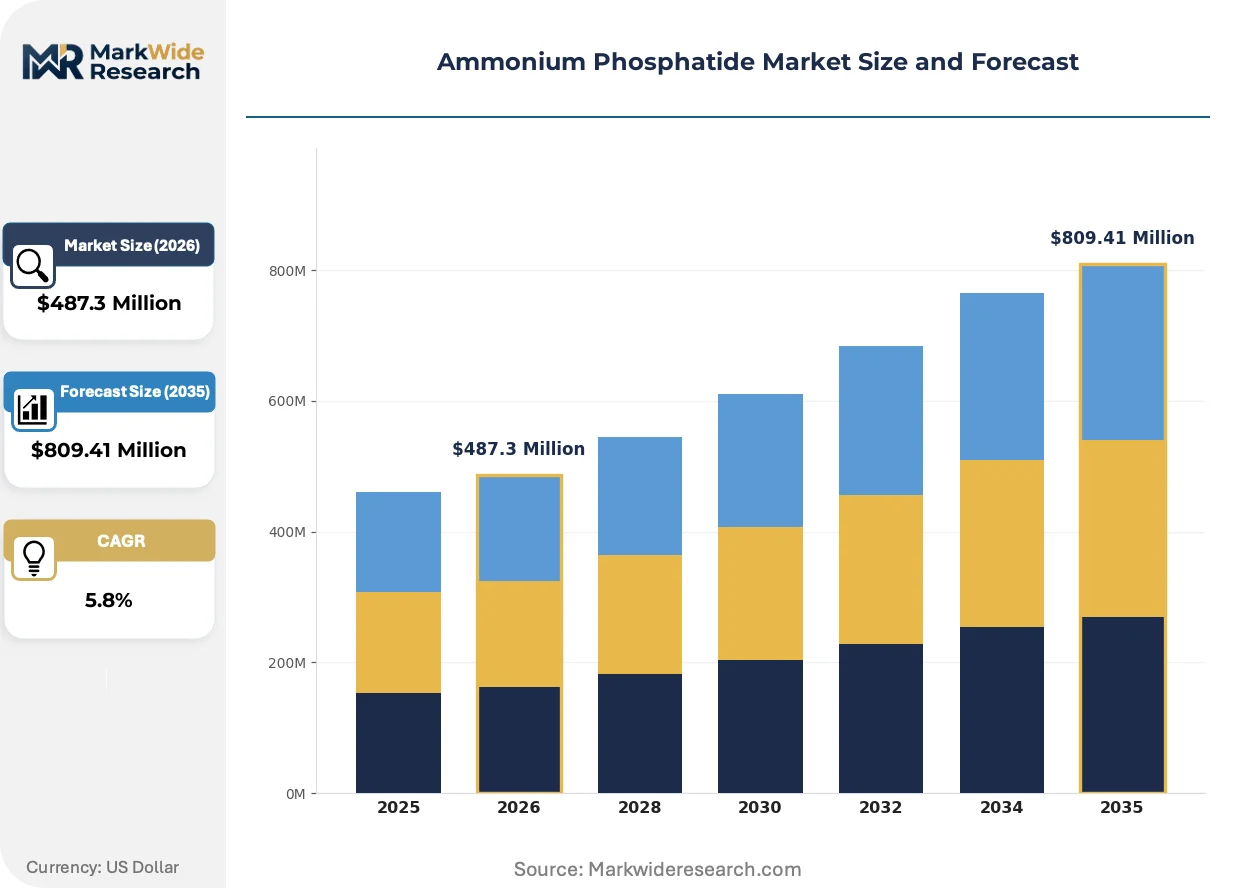
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Paste Application: Food Additive, Nutraceuticals, Coatings, Pharmaceuticals End User: Food Industry, Cosmetic Manufacturers, Dietary Supplement Producers, Pharmaceutical Companies Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | BASF, Puratos, Cargill, Oleon, Ingredion Incorporated, Kerry Group, Lonza Group, Stephan Company, Palsgaard A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Phosphatide Market Strategic Shifts
Continuous processing automation and enzymatic modification techniques are reshaping how ammonium phosphatide is synthesized, tested, and incorporated into downstream formulations.
Enzymatic interesterification is converging with traditional chemical synthesis routes in phosphatide production. Industrial chocolate processors in Belgium and Switzerland are adopting enzymatically modified grades at pilot scale. This convergence is compressing the performance gap between natural and modified emulsifiers while reducing processing temperatures.
REACH registration requirements are expanding impurity profiling obligations for phospholipid derivatives entering European food and drug applications. Manufacturers must now document full chemical identity spectra and residual solvent thresholds. Pharmaceutical-grade ammonium phosphatide faces the steepest compliance burden, with EMA audits intensifying for tablet coating applications.
Confectionery procurement teams are consolidating supplier relationships around vertically integrated oleochemical producers with captive vegetable oil refining. German and Dutch chocolate manufacturers are reducing their emulsifier vendor counts from six to two qualified sources. This concentration is most visible in premium brand supply chains where traceability documentation requirements have multiplied.
Ammonium Phosphatide Market Segmentation
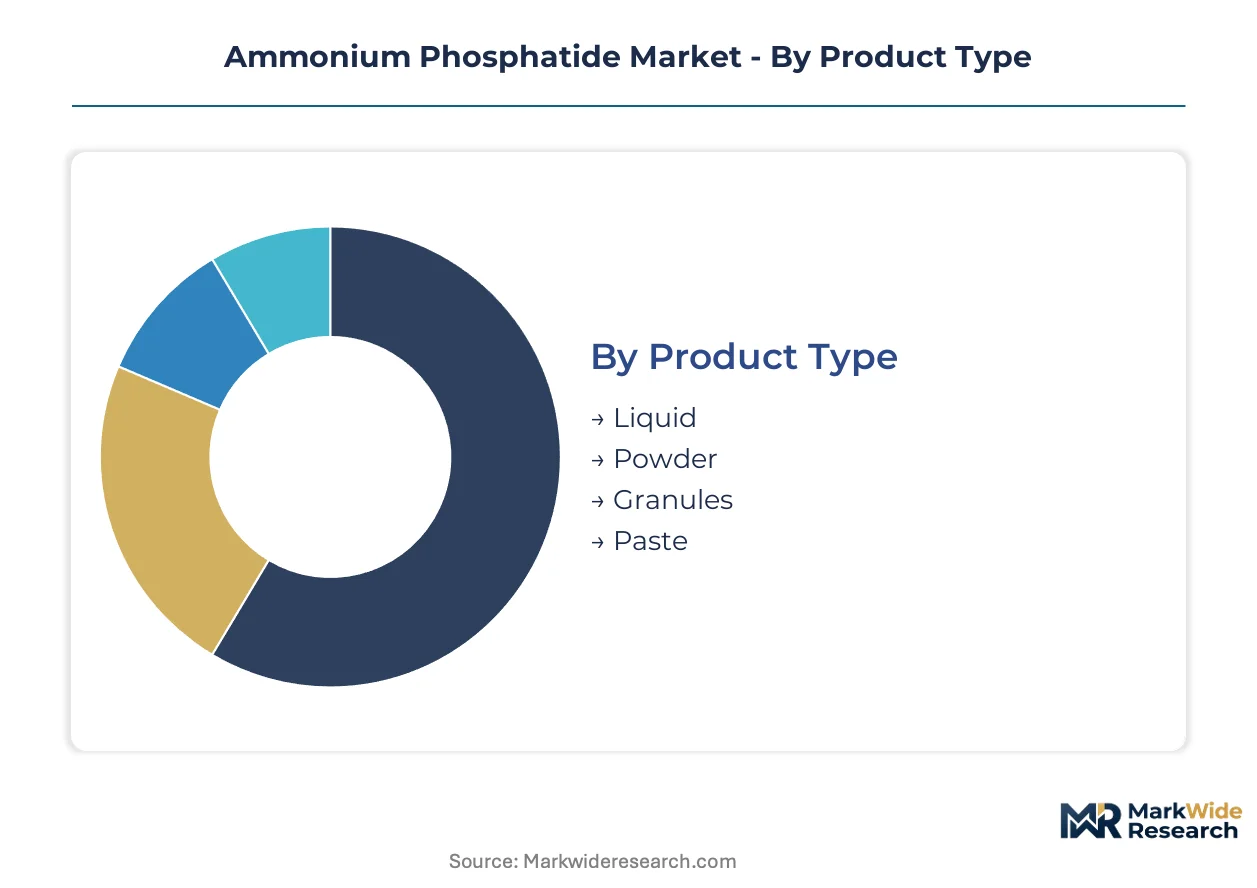
Segmentation in ammonium phosphatide markets reveals how physical form, application intensity, and procurement channel determine margin capture. Manufacturers configure production assets around these divides to defend position against lecithin substitutes.
Product Type:
Supply concentration in liquid formats shapes competitive dynamics across all four physical presentations.
- Liquid:Contains 30-40% phosphorous content in fluid suspension, enabling direct injection into continuous chocolate processing lines without pre-dispersion. Demand concentrates in Belgium and Germany where industrial confectionery clusters operate continuous tempering equipment, constrained by refrigerated storage requirements and shorter shelf stability versus dry alternatives.
- Powder:Spray-dried or agglomerated formats reduce transportation costs and extend ambient stability for artisanal chocolate processors lacking liquid handling infrastructure. Powder grades are gaining share fastest in small-batch European confectionery and North American craft chocolate segments where equipment retrofit costs block liquid adoption.
- Granules:Free-flowing particulate form minimizes dust generation during handling, serving pharmaceutical tablet coating operations where contamination control protocols demand clean-room compatibility.
- Paste:Semi-solid consistency bridges liquid flow properties with powder stability, finding niche use in manual chocolate tempering applications and specialty coating formulations where precise viscosity control outweighs handling convenience.
Today's leader: Liquid. Tomorrow's challenger: Powder.
Application:
Cost tier differentiation separates commodity food additive volumes from certified pharmaceutical premiums.
- Food Additive:Primary commercial purpose centers on cocoa butter reduction in chocolate mass at 0.3-0.5% dosage levels, maintaining flow properties and shelf stability. Revenue concentrates in halal and kosher certified grades serving premium European confectionery brands, constrained by soy and sunflower lecithin cost advantages in commodity chocolate segments.
- Pharmaceuticals:High-purity grades for tablet coating and lipid-based drug delivery systems command certification premiums under EMA food contact guidelines and EFSA purity standards. This segment climbs the fastest as North American and European drug developers advance oral bioavailability formulations.
- Nutraceuticals:Encapsulation applications in dietary supplements leverage phosphatide emulsification properties for fat-soluble vitamin dispersion, primarily serving soft-gel and liquid supplement manufacturers in Germany and the United States.
- Coatings:Functional barrier layers in pharmaceutical and food packaging applications exploit phospholipid film-forming characteristics, with demand tied to controlled-release tablet formulations and moisture-sensitive confectionery protection.
Food additive anchors current revenue. Pharmaceutical applications show steepest expansion trajectory.
End User:
Customer type determines specification stringency and certification burden across procurement relationships.
- Food Industry:Industrial chocolate manufacturers in Germany, Belgium, and Switzerland consolidate supplier relationships around vertically integrated oleochemical producers with captive vegetable oil refining and full traceability documentation.
- Pharmaceutical Companies:EMA audits and REACH registration requirements impose the steepest impurity profiling obligations, with full chemical identity spectra and residual solvent thresholds mandatory for tablet coating applications.
- Dietary Supplement Producers:Encapsulation-grade phosphatides for soft-gel manufacturing require kosher and halal certification alignment with premium brand positioning in North American and European markets.
- Cosmetic Manufacturers:Liposome formulation applications in skincare emulsions demand cosmetic-grade purity with enhanced oxidative stability, serving formulators in France, Germany, and Switzerland.
Food industry commands volume scale. Pharmaceutical companies extract specification premiums.
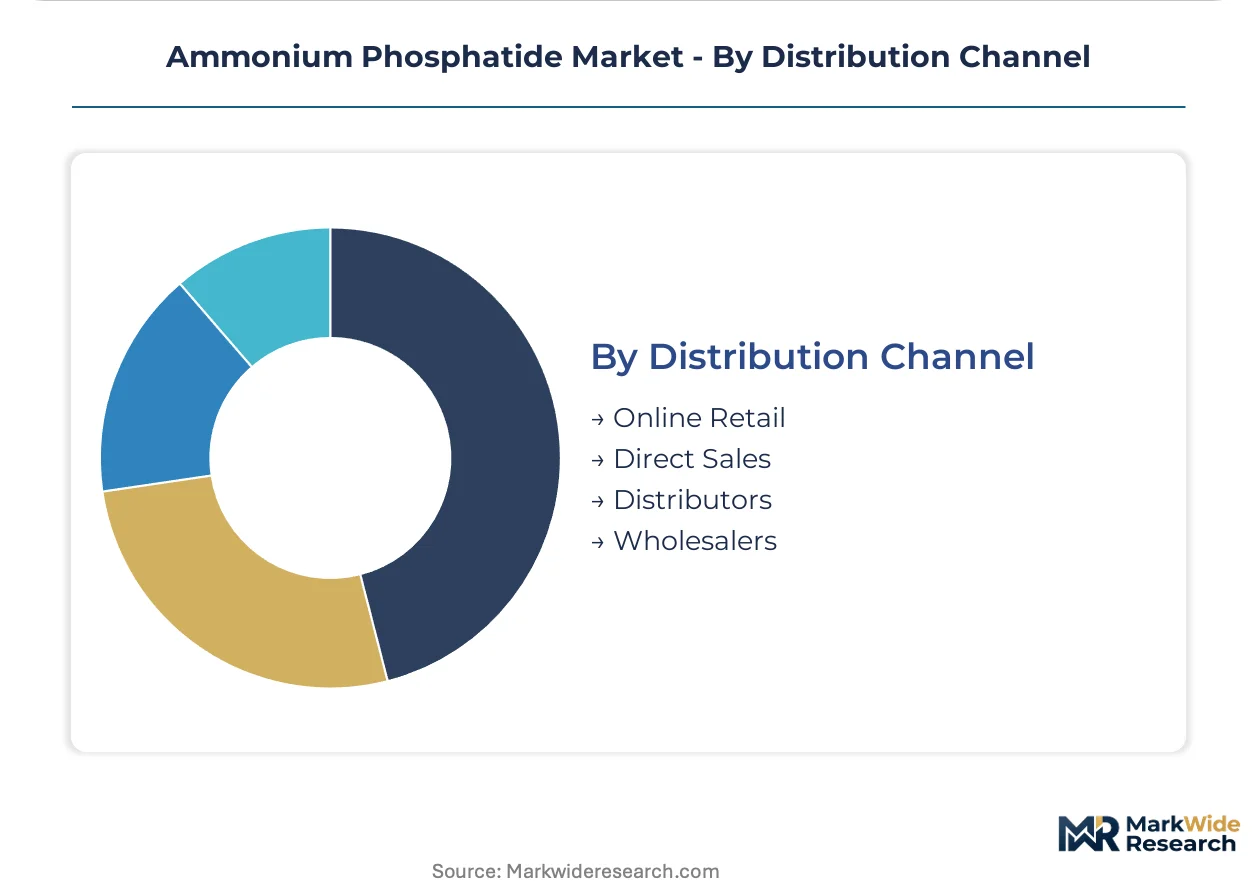
Distribution Channel:
Volume scale and margin structure diverge sharply between direct technical sales and arms-length wholesale.
- Direct Sales:Technical service relationships dominate pharmaceutical and large-scale food additive procurement, with BASF and Cargill fielding application specialists for chocolate processing optimization and regulatory documentation support.
- Distributors:Regional chemical distributors aggregate fragmented demand from mid-tier confectionery and nutraceutical processors, carrying inventory risk for standard-grade liquid and powder formats.
- Online Retail:E-commerce platforms serve artisanal chocolate makers and small-batch cosmetic formulators with packaged kilogram-scale quantities, though refrigerated liquid shipments constrain geographic reach.
- Wholesalers:Bulk commodity traders handle spot market volumes for non-certified grades, primarily in Black Sea sunflower oil sourcing corridors where feedstock price volatility transmits directly into phosphatide production economics.
Direct sales capture margin depth. Distributors extend geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemists with oleochemical synthesis experience concentrate in legacy European and North American refining hubs, anchoring regional production capabilities and shaping procurement patterns across chocolate and pharmaceutical supply chains.
Germany
Industrial chocolate manufacturers in Cologne and Hamburg accelerate clean-label emulsifier procurement to meet retailer sustainability mandates. ECHA REACH registration requirements tighten impurity profiling obligations for phospholipid derivatives entering food applications. The North Rhine-Westphalia cluster hosts major confectionery operations where supplier consolidation from six to two qualified sources is most visible.
Belgium
Continuous tempering equipment operators in Brussels and Antwerp drive liquid format demand for direct injection into processing lines. EU Green Deal sourcing mandates expand sustainable food ingredient requirements across chocolate supply chains. The Flanders confectionery belt represents Europe's densest industrial chocolate processing concentration.
Switzerland
Premium brand chocolate manufacturers in Zurich and Geneva extract specification premiums for halal and kosher certified grades. Swissmedic pharmaceutical audits intensify for tablet coating applications using high-purity phosphatide grades. The Basel pharmaceutical corridor advances lipid-based drug delivery system development.
United States
FDA GRAS status provides parallel market access for ammonium phosphatide in chocolate manufacturing, enabling cross-Atlantic supplier operations. Dietary supplement producers in New Jersey and California require kosher and halal certification alignment for soft-gel manufacturing. The New Jersey pharmaceutical belt drives North American demand for encapsulation-grade phosphatides.
Netherlands
Vegetable oil refiners in Rotterdam leverage captive supply networks to secure raw material streams for phosphatide production. EFSA purity standards shape product specifications for pharmaceutical-grade material entering European markets. The Rotterdam-Antwerp port complex anchors Black Sea sunflower oil sourcing corridors.
Ammonium Phosphatide Market Competitive Environment
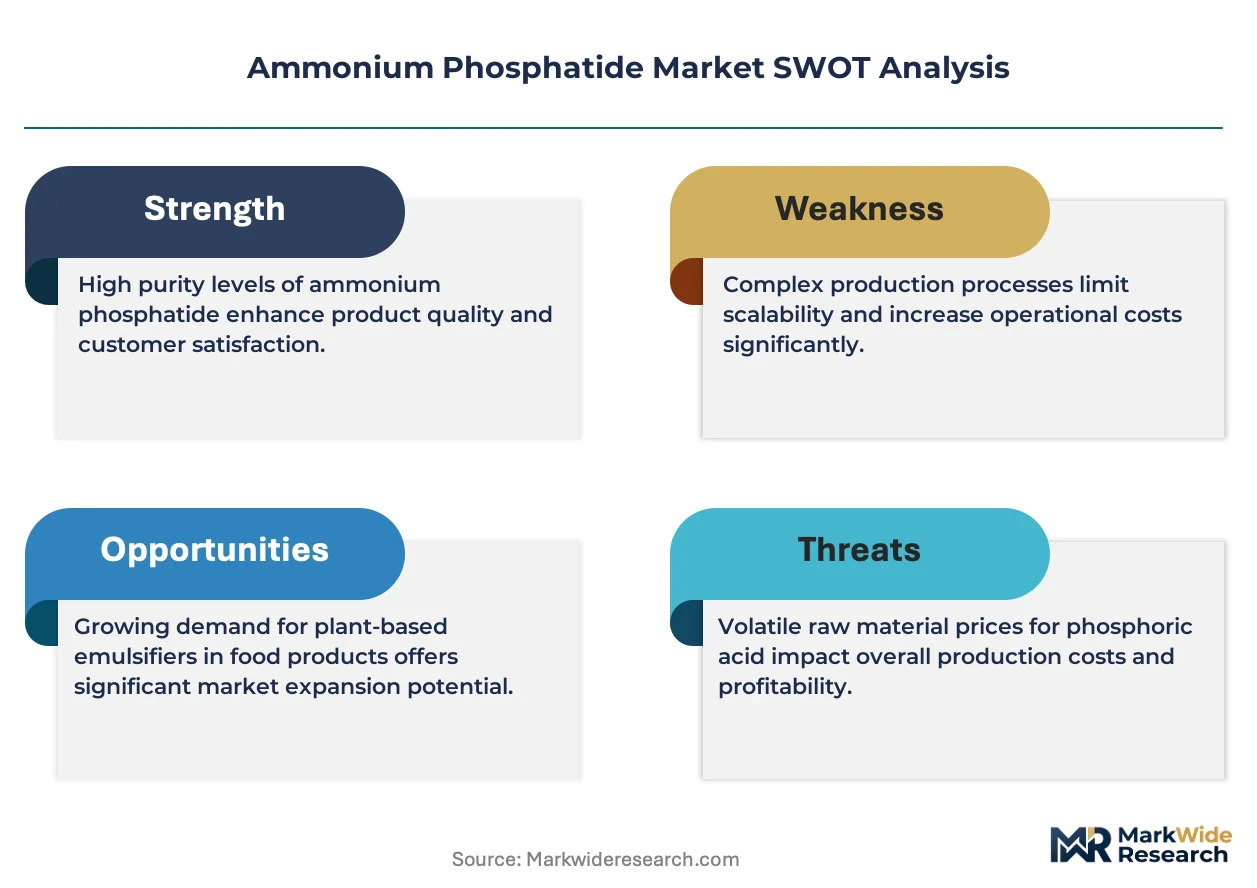
Capital-heavy producers compete with asset-light designers across the ammonium phosphatide landscape, creating a tiered structure where integrated oleochemical networks face specialized emulsifier formulators. The vendor base splits between backward-integrated agricultural processors and application-specific technology developers. Three archetypes dominate: integrated oleochemical majors with captive vegetable oil refining, specialized emulsifier houses with chocolate processing expertise, and pharmaceutical-grade purity specialists. Competitive moves center on supplier consolidation by confectionery procurement teams and enzymatic modification technology licensing.
Among integrated oleochemical producers, BASF SE and Cargill Incorporated exemplify the backward-integrated archetype with upstream control over vegetable oil supply chains. Palsgaard A/S occupies a position within the specialized emulsifier tier, representing application-specific formulation capabilities for industrial chocolate processing. These three companies anchor the competitive structure, with integrated players leveraging raw material security and specialists capturing premium positioning through technical service relationships.
| Leading Market Players |
|---|
| BASF |
| Puratos |
| Cargill |
| Oleon |
| Ingredion Incorporated |
| Kerry Group |
| Lonza Group |
| Stephan Company |
| Palsgaard A/S |
| Others |
Value Chain & Pricing Dynamics
Black Sea sunflower oil futures transmit volatility directly into ammonium phosphatide production economics, cascading through three distinct pricing tiers that separate pharmaceutical-grade premiums from commodity food additive benchmarks. Feedstock swings in Ukrainian and Russian sourcing corridors compress margins at the standard grade while reinforcing certification premiums for halal and kosher certified volumes.
Pricing Analysis
Technical service bundling versus unbundled commodity supply splits the market into divergent pricing models. Pharmaceutical and large-scale chocolate processors contract through direct sales relationships that embed application support and regulatory documentation, commanding premium-mid-economy pricing differentiation based on certification grade and after-sales service intensity. Cost compression in standard food additive tiers is intensifying because soy and sunflower lecithin substitutes maintain persistent cost advantages. Commodity chocolate manufacturers exhibit the highest price sensitivity, while premium confectionery brands and pharmaceutical companies absorb specification premiums with minimal volume elasticity.
Supply Chain Analysis
Vegetable oil feedstock supply rests on Black Sea sourcing corridors through Ukraine and Russia, with downstream refining concentrated in Germany, Belgium, and the Netherlands. Rapeseed oil from European domestic production and sunflower oil from Eastern European crushing operations constitute the primary phospholipid inputs, supplemented by soy oil streams from South American origins. Single-source vulnerability in Black Sea sunflower oil exposes producers to geopolitical disruption and harvest volatility. Distribution runs through vertically integrated oleochemical majors with captive refining assets, bypassing traditional chemical distributor networks for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ammonium phosphatide functions as a stable compounder anchored by irreversible clean-label substitution trends in European chocolate manufacturing that sustain emulsifier demand through regulatory and consumer preference cycles.
For Market Incumbents: Anchor defensive positioning through backward integration into vegetable oil refining and enzymatic modification technology licensing. Consolidate supplier relationships with major confectionery procurement teams in Germany and Belgium before emerging biotech-emulsifier developers capture pilot-scale traction. Prioritize REACH registration recertification investments ahead of tightening ECHA purity thresholds. For New Entrants and Emerging Players: Enter via pharmaceutical-grade tablet coating applications where EMA audit requirements and impurity profiling obligations create certification barriers that favor specialized purity specialists over commodity producers. Target North American lipid-based drug delivery system developers with encapsulation-grade phosphatides, leveraging FDA GRAS status for parallel market access without EU regulatory duplication. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap oleochemical processors possessing captive vegetable oil supply and existing halal or kosher certification infrastructure. Long-term viability extends through the projection horizon for producers capable of serving both food additive volume and pharmaceutical premium tiers. Monitor enzymatic modification patent filings as an inflection indicator for technology displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vegetable Oil Refining | Captive supply of rapeseed and sunflower oil feedstock secures margin control against Black Sea price volatility. |
| Pharmaceutical-Grade Certification Investment | EMA and EFSA compliance opens tablet coating and drug delivery system revenue streams with premium capture. |
| Enzymatic Modification Technology Licensing | Pilot-scale adoption by Belgian and Swiss chocolate processors reduces processing temperatures and energy intensity. |
| Halal and Kosher Certification Expansion | Premium confectionery brand procurement concentrates in certified grades, expanding addressable margin pools. |
| Direct Technical Service Relationships | Application specialists for chocolate processing optimization defend incumbent positions against distributor-based competitors. |
Study Parameters
Coverage spans Europe and North America, with primary inputs from each region combined with secondary validation across trade and regulatory databases. Primary interviews engaged plant managers at oleochemical refineries, procurement leads at industrial chocolate manufacturers, regulatory affairs specialists navigating REACH and FDA frameworks, and distribution channel partners handling phospholipid derivatives. Secondary sources incorporated ECHA registration databases, EFSA scientific opinions, FDA GRAS notifications, customs and trade flow data from Eurostat and the US Census Bureau, and SEC filings from listed chemical producers. Bottom-up volume estimates triangulated against top-down market sizing derived from vegetable oil processing capacity and emulsifier substitution rates.
Rate-of-change decomposition across the projection horizon segmented growth drivers by product form, application intensity, certification tier, and regional regulatory cluster. The analytical framework modeled liquid, powder, granule, and paste formats separately against food additive, pharmaceutical, nutraceutical, and coating end-uses. CAGRs were derived from feedstock cost trajectory assumptions, substitution elasticity estimates for lecithin displacement, and certification premium persistence in premium confectionery supply chains. Forecast inputs incorporated REACH compliance cost burdens, EU Green Deal sourcing mandate adoption curves, and pharmaceutical lipid delivery system pipeline advancement.
Inputs from ECHA registration databases and FDA GRAS filings were available through the study window; gaps in private-label confectionery procurement contract terms introduce uncertainty bands around volume share estimates. Forecasts reflect documented assumptions regarding enzymatic modification adoption rates and Black Sea sunflower oil supply stability. Regulatory divergence between EU and North American purity thresholds, feedstock price volatility, and biotech-emulsifier technology maturation warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Phenolic Antioxidant Market
Additives
China Feed Additives Market
Additives
Engine Oil Additive Market
Additives
Adjustive Agents Market
Additives
1,4 Butanediol Derivatives Market
Additives
Refining Additives Market
Additives
Global PVC Stabilizer Market
Additives
Biosaccharide Gum Market
Additives
Surface Modifiers Market
Additives
Global Butyric Acid Derivatives Market
Additives
Gelatin Peptones Market
Additives
Europe Citric Acid Market
Additives
Europe Choline Chloride Market
Additives
Binding Agents Market
Additives
Powder Induction and Dispersion Systems Market
Additives
Global Anti-Fog Additives Market