
 Asia-Pacific Fuel Additives Market | 2026-2036
Asia-Pacific Fuel Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fuel Additives Market Outlook
Ultra-low sulfur diesel (ULSD) specification upgrades across Asian refining hubs is reorganizing procurement priorities for fuel additive suppliers. BASF SE leverages its Ludwigshafen technical center to transfer European ULSD formulation expertise into Chinese and Indian refinery trials. Dorf Ketal Chemicals India Pvt. Ltd. anchors its position through captive manufacturing at Tarapur and direct supply relationships with Indian Oil and HPCL. Innospec Inc. competes in the octane booster segment with detergent packages tailored to emerging Asian gasoline sulfur regulations.
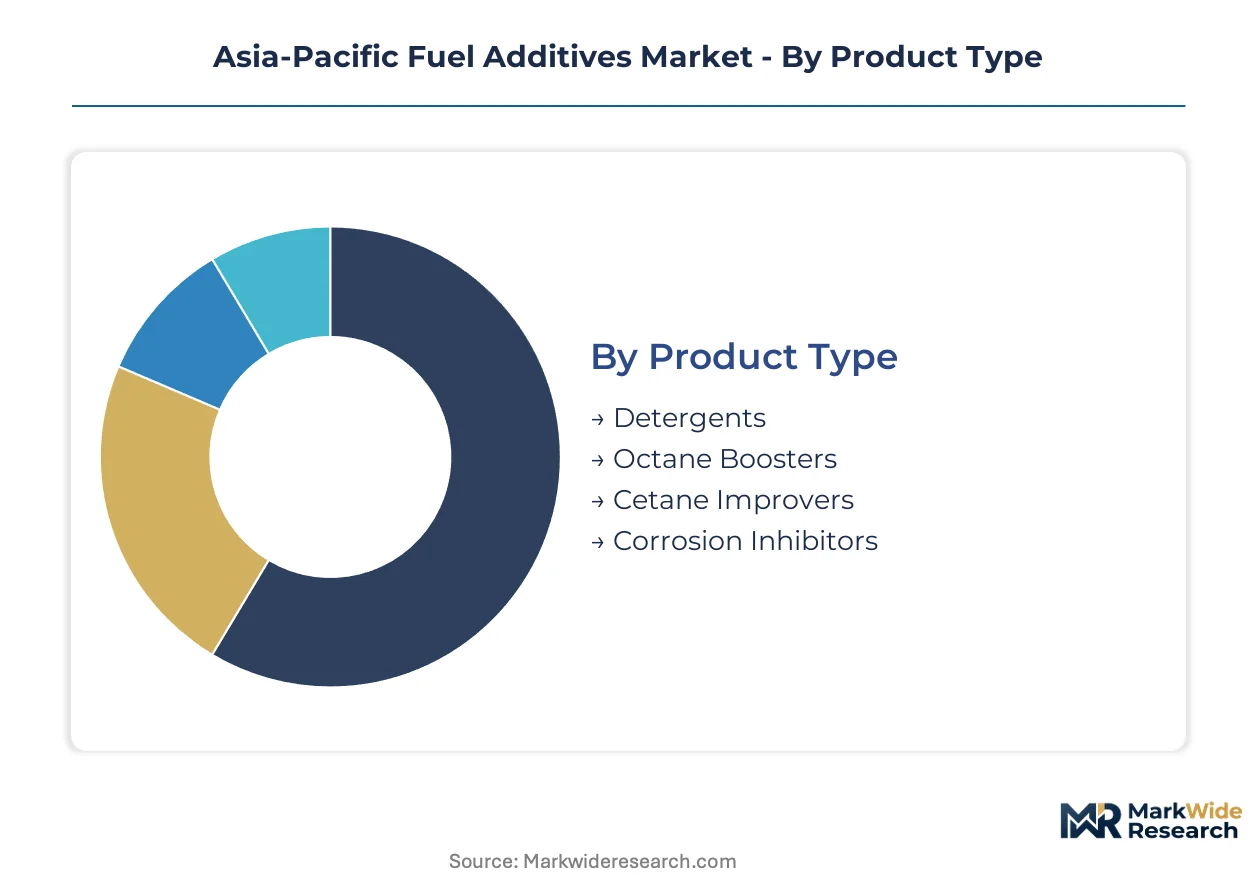
Asia-Pacific fuel additives are chemical formulations—typically comprising detergents, dispersants, antioxidants, and corrosion inhibitors at parts-per-million treat rates—blended into transportation and industrial fuels to enhance combustion efficiency, reduce engine deposits, and meet emissions standards. Detergents dominate value contribution as gasoline direct-injection (GDI) engine penetration rises and deposit control becomes critical for injector cleanliness. Cetane improvers represent the fastest-growing product category, driven by India's Bharat Stage VI diesel standards and China's CN VI-B implementation, where ignition quality premiums command stronger pricing.
China's MIIT enforces GB 17930 and GB 19147 fuel quality standards that mandate specific additive performance for sulfur, olefin, and aromatic content, while India's BIS certifies additive packages under Automotive Research Association of India test protocols. Japan's METI maintains JIS K 2202 and K 2205 specifications that exceed regional baselines, creating a technical barrier for non-specialized suppliers. Stakeholders must monitor how ASEAN harmonization of fuel standards under the AEC Blueprint affects formulation registration requirements and cross-border additive trade.
Market Dynamics
IMO sulfur caps and China's GB fuel quality standards are compressing formulation cycles for additive suppliers, forcing rapid recertification of detergent and cetane improver packages across Singapore, South Korea, and Japan's marine bunkering terminals.
Growth Catalysts
- Marine bunker fuel treatment programs:Singapore, South Korea, and Japan are expanding additive dosing infrastructure ahead of stricter IMO sulfur regulations, creating dedicated demand for corrosion inhibitors and combustion catalysts in coastal refining corridors.
- GB 17930 and GB 19147 enforcement:China's MIIT mandates specific additive performance thresholds for sulfur, olefin, and aromatic content, compelling domestic refiners to upgrade gasoline and diesel treatment packages.
- Bharat Stage VI diesel standards:India's ignition quality premiums for high-cetane fuel are accelerating cetane improver consumption across the Gujarat-Maharashtra refining belt.
Market Restraints
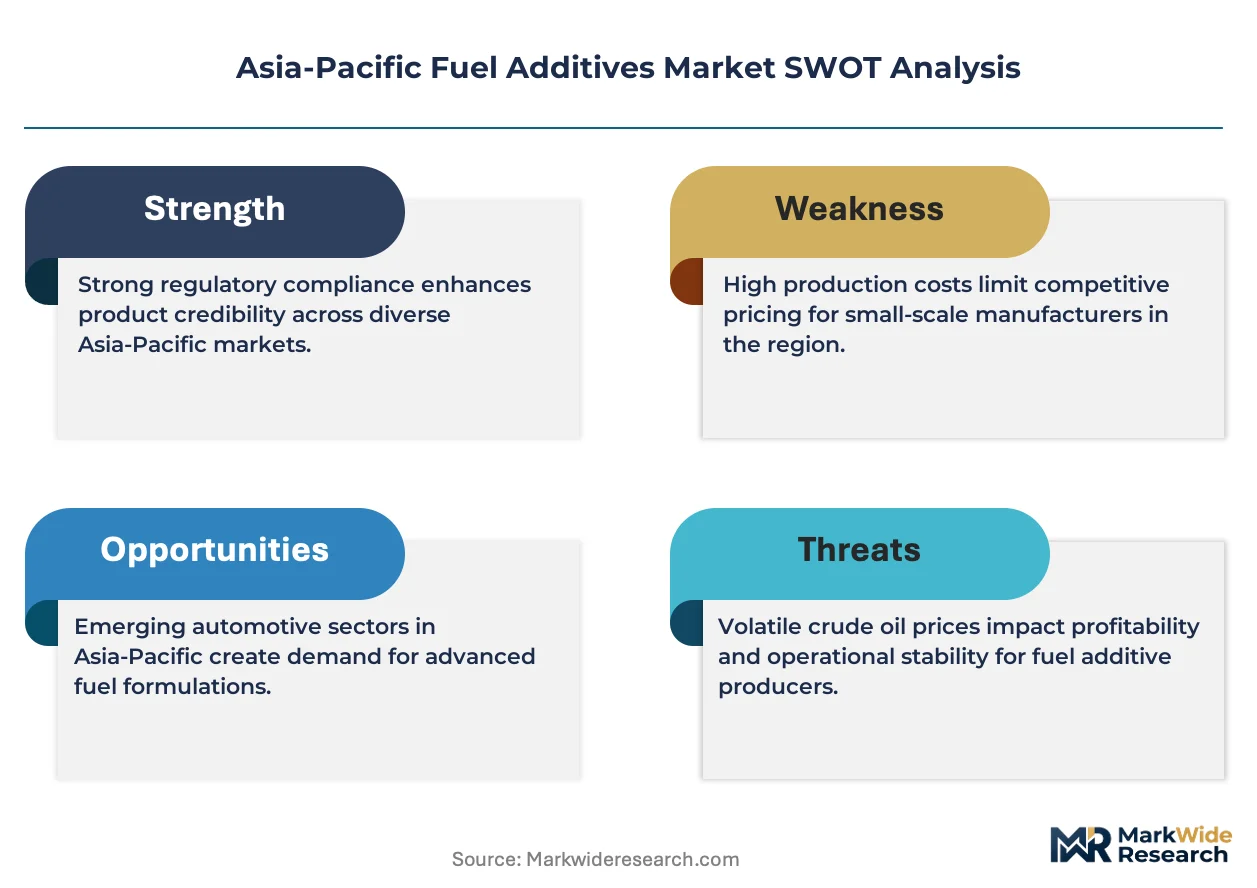
- Specialty chemical feedstock volatility:Naphtha-derived detergent precursors and 2-ethylhexyl nitrate for cetane improvers face price swings tied to regional cracking margins.
- Supplier concentration in Northeast Asia:Base additive manufacturing clusters in Japan and South Korea create geographic single-source exposure for Southeast Asian blenders.
- JIS K 2202 technical barriers:Japan's METI specifications exceed regional baselines, requiring separate formulation development that fragments R&D economies of scale.
Strategic Opportunities
- ASEAN AEC Blueprint harmonization:Emerging fuel standard convergence across Thailand, Vietnam, and Indonesia will streamline cross-border additive registration and reduce formulation fragmentation.
- Gasoline direct-injection engine penetration:Deposit control additives for GDI systems represent underpenetrated demand as vehicle fleets upgrade across India and Southeast Asia.
- Dual carbon goals in China:The MEE's emissions intensity targets are creating procurement incentives for combustion efficiency additives that reduce CO2 per unit fuel consumed.
Industry Challenges
- ARAI certification timelines:India's Automotive Research Association of India test protocols for additive packages extend market entry cycles by 12-18 months for new detergent formulations.
- FCC gasoline hydrotreater integration:Refiners upgrading fluid catalytic cracking output face complex compatibility testing between new process streams and existing additive treat rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fuel Additives Market |
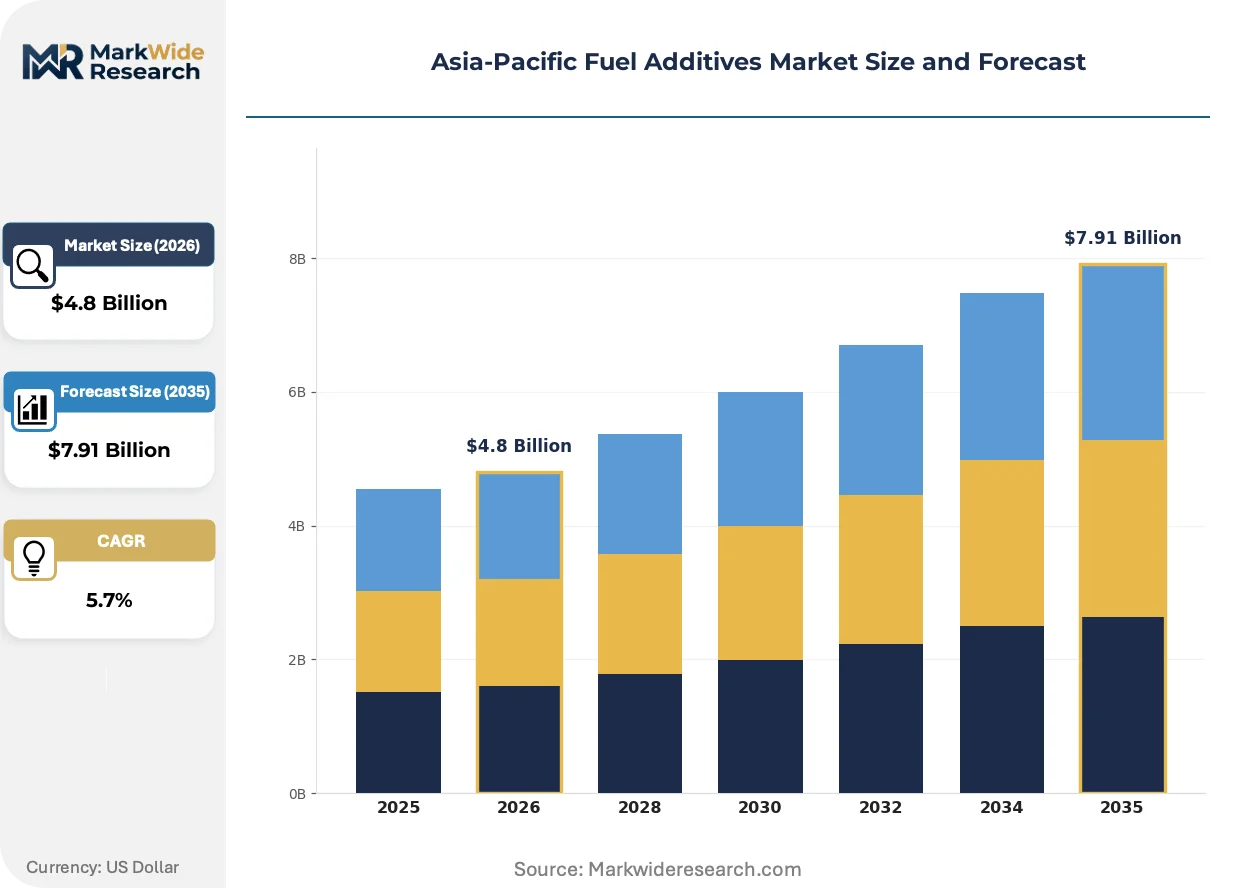
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detergents, Octane Boosters, Cetane Improvers, Corrosion Inhibitors Application: Automotive Fuels, Aviation Fuels, Marine Fuels, Industrial Fuels End User: Refineries, Fuel Distributors, OEMs, Repair Shops Storage Mode: Bulk Storage, Drumming, Canning, Bagging |
| Companies Covered | Afton Chemical, The Lubrizol Corporation, Innospec Inc., BASF SE, Chevron Oronite Company LLC, Infineum International Ltd., Dorf Ketal Chemicals India Pvt. Ltd., LANXESS, Baker Hughes Co., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fuel Additives Market Strategic Shifts
Formulation science is pivoting from universal additive packages toward segment-specific designs, driven by diverging sulfur regulations and engine technology roadmaps across marine, automotive, and industrial fuel applications.
Polyetheramine detergent chemistry is fragmenting the deposit control segment. BASF and regional suppliers are deploying differentiated molecular weights for gasoline direct-injection versus port-fuel-injection engines. Japanese OEMs specify low-temperature deposit control that diverges from Chinese and Indian treat rate conventions, forcing suppliers to maintain parallel formulation libraries rather than scaled single products.
China's MIIT is tightening GB 19147 diesel sulfur limits ahead of the original schedule, compressing the window for refiners to validate new hydrotreating catalysts and matching additive packages. Indian refiners along the Gujarat coast are responding by front-loading cetane improver procurement to avoid certification bottlenecks when BIS aligns with Bharat Stage VI Phase II norms.
Refiner procurement of additive packages is consolidating toward direct technical partnerships with formulators, displacing traditional distributor intermediaries. Reliance Industries and Indian Oil are negotiating captive supply agreements with Dorf Ketal for Tarapur-manufactured detergents. This channel compression is most visible in India's public-sector refining units, where long-term offtake contracts now specify joint formulation development rather than spot purchasing.
Asia-Pacific Fuel Additives Market Segmentation
Asia-Pacific fuel additive procurement splits across technical specifications, logistics constraints, and end-user integration depth. Regulatory divergence between China's GB standards, India's BIS protocols, and Japan's JIS specifications fragments formulation requirements across every segment axis.
Product Type:
China's MIIT enforces distinct additive performance thresholds for sulfur, olefin, and aromatic content under GB 17930 and GB 19147, forcing suppliers to maintain parallel formulation libraries across jurisdictions.
- Detergents:Polyetheramine-based formulations at differentiated molecular weights control deposits in gasoline direct-injection engines. Demand concentrates in China's coastal refining clusters where GDI vehicle penetration outpaces port-fuel-injection legacy fleets, though Japan's METI specifies low-temperature deposit control that diverges from Chinese treat rate conventions.
- Cetane Improvers:2-ethylhexyl nitrate and alternative chemistries elevate diesel ignition quality. India's Bharat Stage VI standards along the Gujarat-Maharashtra corridor command premium pricing for high-cetane fuel, compressing procurement cycles as refiners front-load additive purchases ahead of BIS Phase II alignment.
- Octane Boosters:MMT and oxygenate packages address gasoline sulfur regulations across emerging Asian markets.
- Corrosion Inhibitors:Amine-based and carboxylate chemistries protect storage and distribution infrastructure.
Detergents handle the majority of throughput; cetane improvers are expanding most quickly on share.
Application:
Marine bunker fuel treatment programs in Singapore, South Korea, and Japan are expanding additive dosing infrastructure ahead of stricter IMO sulfur caps, reshaping volume allocation across application segments.
- Automotive Fuels:Gasoline and diesel treatment packages for passenger and commercial vehicles. China's MIIT GB standard enforcement drives detergent and cetane improver consumption in domestic refineries, while India's BIS certification protocols extend market entry timelines for new formulations.
- Marine Fuels:Corrosion inhibitors and combustion catalysts for residual fuel oil and distillate bunkers. Singapore's coastal refining corridor anchors regional demand as operators upgrade dosing systems ahead of IMO regulatory tightening.
- Aviation Fuels:Antioxidant and anti-icing additives for jet fuel specifications.
- Industrial Fuels:Combustion efficiency packages for power generation and heating applications.
Automotive fuels dominate current volume; marine fuels are gaining share fastest.
End User:
Refiner procurement is consolidating toward direct technical partnerships, displacing traditional distributor intermediaries across Asia-Pacific's public-sector refining units.
- Refineries:Integrated additive package procurement for in-house fuel blending. Reliance Industries and Indian Oil negotiate captive supply agreements specifying joint formulation development rather than spot purchasing, compressing channel margins for independent distributors.
- Fuel Distributors:Terminal blending and additive injection services. Geographic concentration in Japan and South Korea base manufacturing creates single-source exposure for Southeast Asian blenders seeking supply security.
- OEMs:Factory-fill specifications and warranty-compliant treatment packages.
- Repair Shops:Aftermarket additive retail for consumer vehicle maintenance.
Refineries command the largest procurement volumes; fuel distributors are climbing fastest on share.
Storage Mode:
Feedstock volatility in naphtha-derived detergent precursors and specialty chemical inputs shapes logistics economics across storage configurations.
- Bulk Storage:Large-volume additive receipt at coastal refining terminals. Dorf Ketal's Tarapur manufacturing facility supplies Indian Oil and HPCL through direct bulk transfer, eliminating intermediate handling costs.
- Drumming:Intermediate packaging for regional distribution and smaller blender access.
- Canning:Consumer retail formats for aftermarket applications.
- Bagging:Powder additive formats for specific industrial fuel treatments.
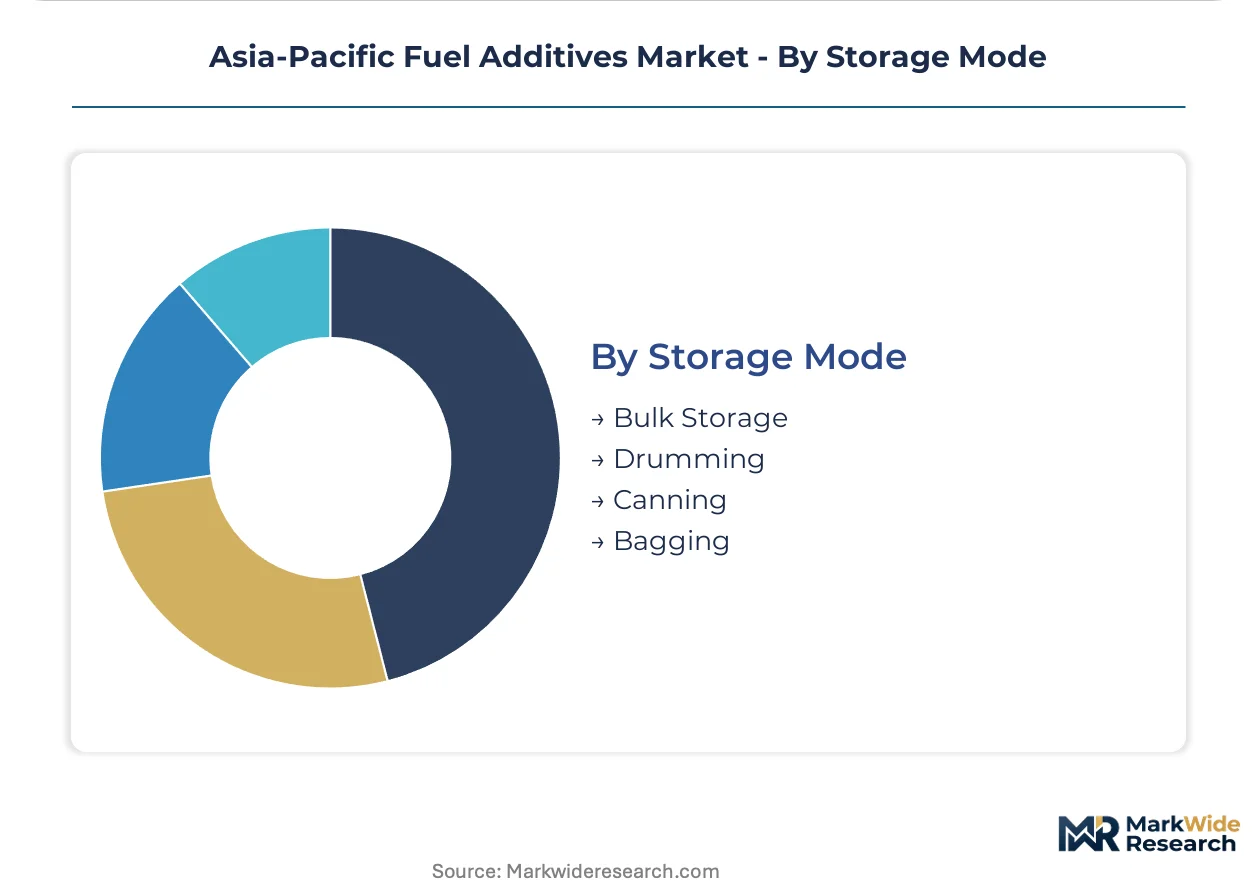
Bulk storage handles the majority of throughput; drumming is expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore exports marine fuel additives to Southeast Asian bunkering terminals, while Japan and South Korea supply detergent precursors to Indian refineries along the Gujarat-Maharashtra corridor. This trade-flow pattern concentrates procurement leverage in coastal refining clusters.
China
MIIT enforcement of GB 17930 and GB 19147 standards compels refiners to upgrade gasoline and diesel additive packages for sulfur, olefin, and aromatic compliance. The Yangtze River Delta refining cluster near Shanghai validates new hydrotreating catalysts under compressed timelines. Coastal provinces import European ULSD formulation expertise through technical center partnerships.
India
Bharat Stage VI diesel standards command premium pricing for high-cetane fuel across the Gujarat-Maharashtra belt. BIS certification protocols extend market entry cycles for new detergent formulations by 12-18 months. Reliance Industries and Indian Oil negotiate captive supply agreements specifying joint formulation development at Tarapur manufacturing facilities.
Japan
METI maintains JIS K 2202 and K 2205 specifications that exceed regional baselines, creating technical barriers for non-specialized suppliers. Japanese OEMs specify low-temperature deposit control diverging from Chinese treat rate conventions. Kanto region refiners maintain parallel formulation libraries for domestic and export specifications.
South Korea
Marine bunker fuel treatment programs expand additive dosing infrastructure ahead of stricter IMO sulfur regulations. Base additive manufacturing clusters create geographic single-source exposure for Southeast Asian blenders. Ulsan coastal refining terminals anchor regional demand for corrosion inhibitors and combustion catalysts.
Singapore
Marine shipping operators upgrade bunker fuel treatment programs ahead of IMO regulatory tightening. The coastal refining corridor anchors regional demand for residual fuel oil and distillate bunker additives. Terminal blending infrastructure concentrates procurement toward direct technical partnerships with formulators.
Asia-Pacific Fuel Additives Market Competitive Environment
Listed leaders compete with private specialists across formulation development and captive supply relationships. The vendor base fragments between multinational chemical conglomerates with integrated R&D platforms and regional manufacturers with direct refinery partnerships. Three archetypes dominate: European technology licensors transferring ULSD expertise, Indian captive suppliers with Tarapur-based manufacturing, and marine-focused corrosion inhibitor specialists. Competitive moves concentrate on backward integration into detergent precursor production and long-term offtake contracts specifying joint formulation development.
Among European technology licensors, BASF SE exemplifies the formulation transfer archetype through its Ludwigshafen technical center operations. Dorf Ketal Chemicals India Pvt. Ltd. occupies the captive supplier position with direct supply relationships to Indian Oil and HPCL. Innospec Inc. sits within the gasoline additive specialization tier, competing in octane booster segments. These three anchors represent distinct competitive vectors: technology licensing, geographic captive supply, and segment-specific formulation focus.
| Leading Market Players |
|---|
| Afton Chemical |
| The Lubrizol Corporation |
| Innospec Inc. |
| BASF SE |
| Chevron Oronite Company LLC |
| Infineum International Ltd. |
| Dorf Ketal Chemicals India Pvt. Ltd. |
| LANXESS |
| Baker Hughes Co. |
| Others |
Value Chain & Pricing Dynamics
Tarapur manufacturing scale economies anchor price floors for Indian detergent supply, compressing margins for smaller blenders while elevating procurement leverage for Reliance Industries and Indian Oil. This concentration dynamic propagates across the Asia-Pacific basin as coastal refining clusters consolidate additive purchasing around direct technical partnerships.
Pricing Analysis
ULSD formulation expertise commands premium positioning against legacy sulfur-tolerant packages, while next-generation polyetheramine detergents for gasoline direct-injection engines stratify above both. Three-tier pricing structure across premium cetane improvers, standard detergent packages, and economy corrosion inhibitors reflects certification grade and volume scale differentiation. Pricing pressure stems from naphtha-derived feedstock volatility tied to regional cracking margins. Small fuel distributors exhibit highest price sensitivity; integrated refiners absorb cost swings through captive supply agreements.
Supply Chain Analysis
Port congestion at Singapore bunkering terminals and container tightness on Northeast Asia-Southeast Asia lanes elevate inbound logistics costs for detergent precursors. Manufacturing concentrates in Japan, South Korea, and India; specialty chemical inputs draw from naphtha crackers, 2-ethylhexyl nitrate producers, and polyetheramine specialists. Single-source vulnerability runs through Japan and South Korea base additive clusters. Distribution runs through direct technical partnerships with formulators, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification of commercial fleets and hydrogen combustion pilots constitute substitution threats that additive suppliers must navigate through combustion efficiency positioning. Incumbents face defense imperatives around formulation differentiation and supply security.
For Market Incumbents: Compound technical partnership depth with Indian and Chinese refiners to lock in long-term offtake agreements specifying joint formulation development. Backward integration into detergent precursor production at Tarapur-scale facilities mitigates feedstock volatility exposure from naphtha cracking margins. Prioritize ARAI and BIS certification pipeline acceleration to compress 12-18 month market entry cycles for new entrants.
For New Entrants and Emerging Players: Differentiate on marine corrosion inhibitor specialization for Singapore bunkering terminals, where IMO sulfur cap expansion outpaces incumbent capacity allocation. Target Indonesia and Vietnam fuel standard harmonization under ASEAN AEC Blueprint convergence as the most penetrable geographic window. Pursue direct terminal blending partnerships with Southeast Asian distributors bypassing Northeast Asian manufacturing clusters.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors captive suppliers with integrated manufacturing and direct refinery relationships over technology licensors without asset-backed supply security. Five-to-ten year viability hinges on dual carbon goal alignment in China and Bharat Stage VI Phase II implementation depth in India. Monitor GB 19147 sulfur limit acceleration timelines as inflection indicator for hydrotreating catalyst and matching additive package demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detergent Precursors | Tarapur-scale captive production secures margin control against naphtha volatility for Indian supply. |
| Long-term Supply Agreement with Refiners | Reliance Industries and Indian Oil joint formulation contracts displace spot purchasing channel intermediaries. |
| Green Manufacturing Transition | Dual carbon goal alignment in China creates procurement preference for combustion efficiency additives. |
| Joint Venture for Regional Manufacturing | Southeast Asian production footprint reduces single-source exposure to Japan and South Korea clusters. |
| Technology Licensing Partnership | BASF Ludwigshafen ULSD expertise transfer accelerates Chinese refinery validation cycles. |
Study Parameters
The analysis maps detergent, cetane improver, octane booster, and corrosion inhibitor sub-sectors, each validated through refinery procurement managers, additive formulator technical directors, marine bunkering operators, and BIS certification specialists. Primary fieldwork combined with secondary validation from customs trade data, MIIT GB standard filings, SEC chemical company disclosures, and ARAI test protocol documentation. Bottom-up volume builds triangulated against top-down regional fuel consumption projections.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product chemistry tier, application end-use, refinery integration depth, and regional regulatory cluster. CAGRs derived from additive treat rate evolution tied to sulfur specification tightening and engine technology penetration curves. Forecast inputs incorporated GDI vehicle fleet upgrade timelines and IMO marine fuel regulation implementation phasing.
Decision-makers should treat outputs as directional under base assumptions of continued GB and BIS standard enforcement; material deviation in regulatory timelines or electrification acceleration would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Lubricant Additives Market
Additives
Global Isosorbide Market
Additives
Metal Deactivators Market
Additives
Cold Flow Improvers Market
Additives
Polymeric Plasticizer Market
Additives
Engine Oil Additive Market
Additives
Humectants Market
Additives
Nucleating Agents Market
Additives
Foundry Additives Market
Additives
Japan Sodium Reduction Ingredient Market
Additives
Bromine Derivatives Market
Additives
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market
Additives
Nucleating and Clarifying Agents Market
Additives
Binding Agents Market
Additives
Dispersing Agents Market
Additives
United Kingdom Sodium Reduction Ingredient Market