
 Netherlands Transportation Infrastructure Construction Market | 2026-2036
Netherlands Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Transportation Infrastructure Construction Market Foresight
Multi-source procurement for specialized marine and tunnel works is decoupling from traditional single-contractor frameworks in Dutch infrastructure. Heijmans leverages its integrated design-build capability to secure complex water management projects. Royal BAM Group anchors large-scale rail extensions through its civil engineering division. VolkerWessels competes aggressively in modular construction methods for urban roadworks.
Netherlands transportation infrastructure construction encompasses the engineering, fabrication, and assembly of roadways, bridges, tunnels, and rail systems designed to withstand North Sea maritime climates and dense delta soil conditions, typically requiring pile depths exceeding twenty meters and corrosion-resistant steel reinforcement. Its primary purpose is sustaining freight flow through Rotterdam-Europoort and passenger mobility across the Randstad urban corridor. Road works and rail extensions command the largest share of public capital allocation, while tunnel development captures premium margins due to geological complexity beneath Amsterdam and Rotterdam waterways. Prefabricated construction methods are gaining share as contractors seek to compress project timelines and limit disruption to existing traffic networks.
Rijkswaterstaat enforces environmental impact standards for all national infrastructure, while the EU Green Deal mandates carbon intensity reductions in construction materials and transport planning. Dutch building codes administered by the Ministry of Infrastructure and Water Management require climate-adaptive designs for flood-prone zones. Stakeholders must monitor evolving EU taxonomy criteria for sustainable infrastructure finance and align procurement strategies with circular material certification requirements.
Market Dynamics
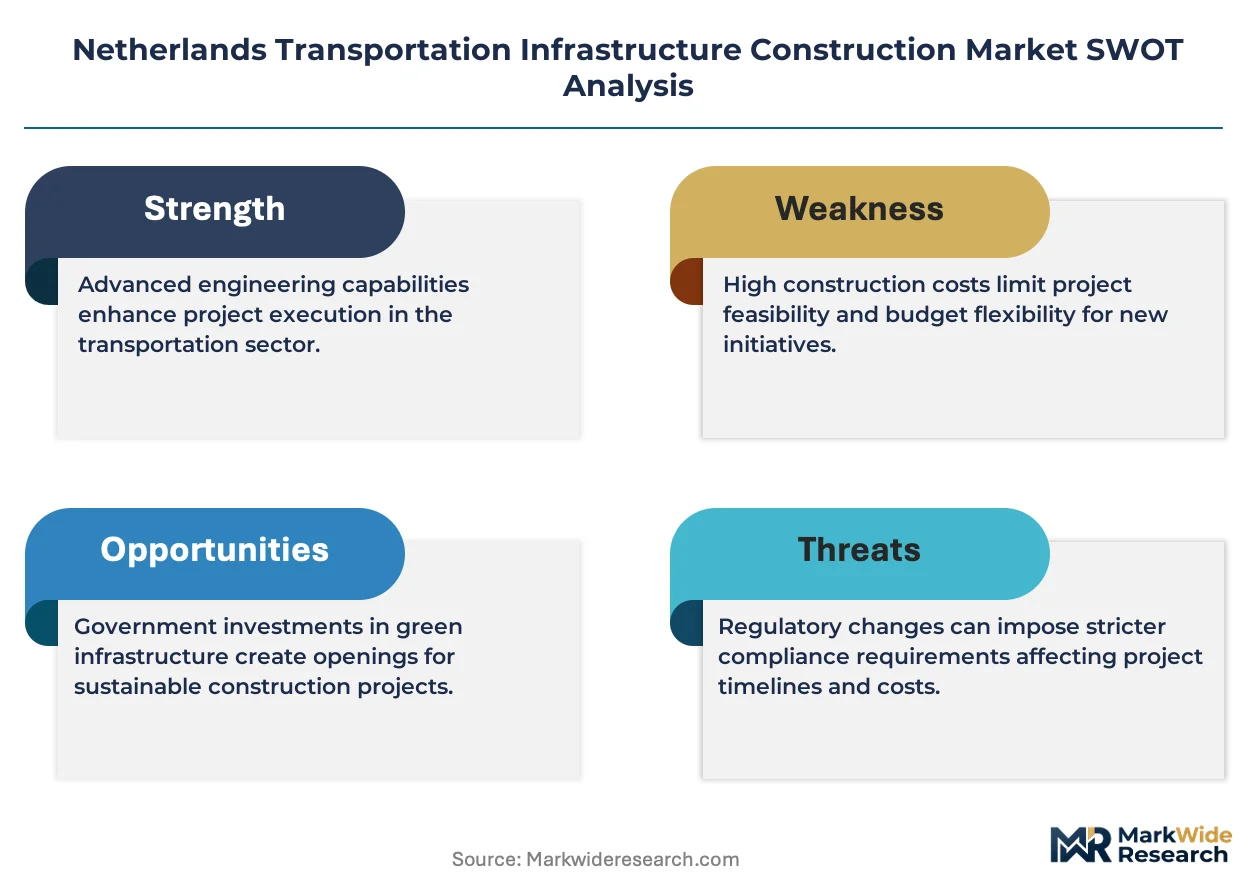
EU Green Deal carbon intensity mandates are forcing Dutch contractors to decarbonize material procurement and construction methods across the Randstad corridor. Rijkswaterstaat now embeds lifecycle emissions criteria into every national tender, reshaping competitive positioning for firms unable to source low-carbon concrete or steel.
Growth Catalysts
- EU Green Deal modal shift mandates:Binding targets for freight diversion from road to rail and inland waterways are accelerating corridor upgrades through Rotterdam-Europoort and Amsterdam port hinterlands.
- Delta soil specialization:Deep pile engineering expertise developed for North Sea maritime climates creates exportable capability for similar geotechnical conditions in Belgian and German border regions.
- Randstad urban densification:Population concentration in the Amsterdam-Rotterdam-Utrecht-The Hague corridor generates sustained demand for tunnel and bridge capacity expansion.
Market Restraints
- Steel and cement input cost volatility:Energy-intensive material production exposed to EU carbon border adjustment mechanisms compresses fixed-price contract margins.
- Specialized marine contractor concentration:Limited Dutch firms qualified for immersed tube tunnel construction in soft delta soils creates bottleneck risk for large-scale waterway crossings.
- Archaeological clearance delays:Mandatory pre-construction surveys by Rijkswaterstaat for UNESCO-protected polder landscapes extend project timelines unpredictably.
Strategic Opportunities
- Modular prefabrication methods:Factory-based bridge component manufacturing reduces on-site labor hours and traffic disruption in dense urban cores.
- North Sea offshore wind logistics hubs:Port of Rotterdam expansion for turbine component handling requires dedicated heavy-load quay walls and transport corridors.
- Circular material certification premiums:Early alignment with evolving EU taxonomy criteria for recycled aggregate use unlocks green finance access.
Industry Challenges
- Geotechnical engineer scarcity:Specialized expertise in delta soil mechanics and groundwater management faces retirement-driven attrition without adequate pipeline replacement.
- Heritage infrastructure integration:19th-century canal and rail alignments constrain modern clearance standards and electrification geometry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Transportation Infrastructure Construction Market |
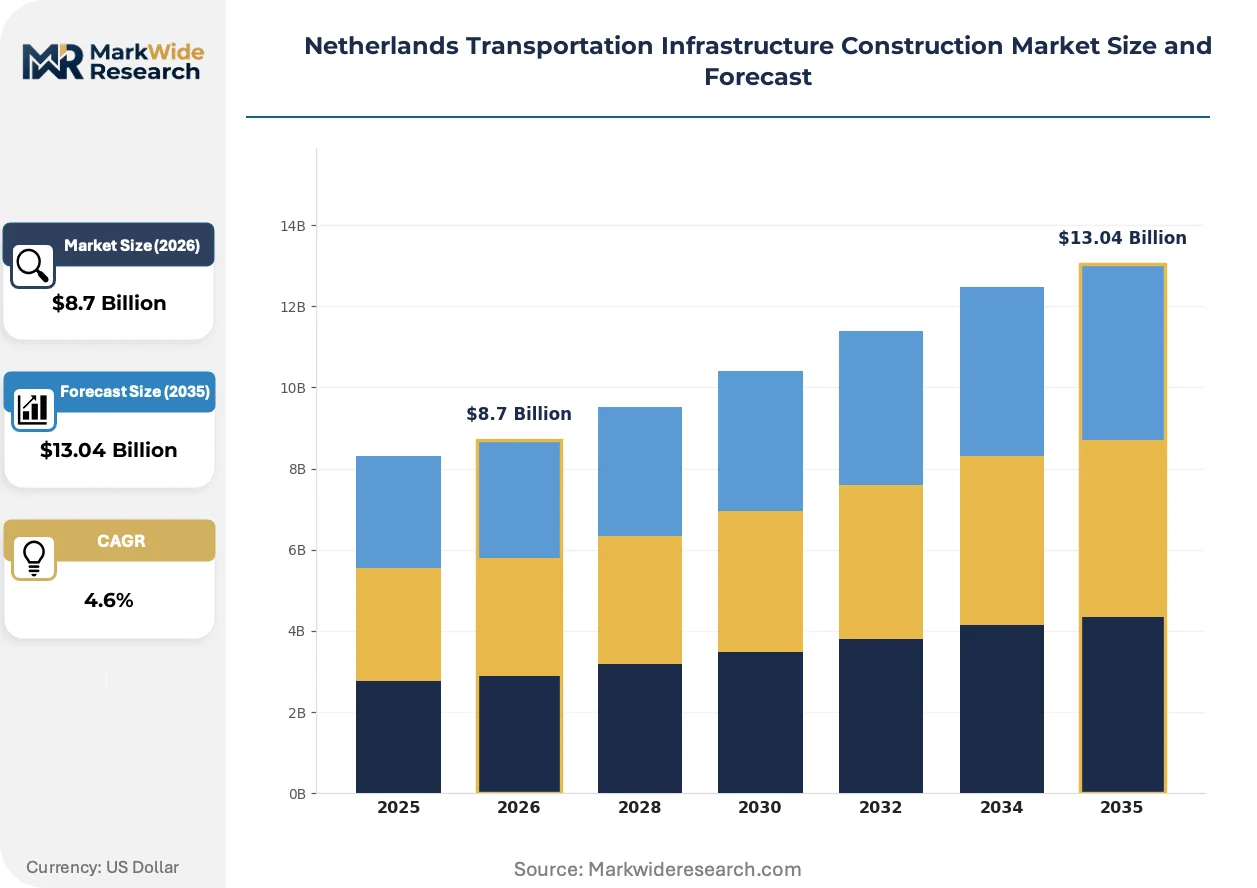
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Road Works, Bridge Construction, Tunnel Development, Rail Extensions Material: Concrete, Asphalt, Steel, Composite Materials Construction Method: Traditional, Modular, Prefabricated, In-situ End User: Government Agencies, Private Companies, Public-Private Partnerships, Transportation Authorities |
| Companies Covered | Heijmans, Van Oord, Royal BAM Group, Strukton, Ballast Nedam, VolkerWessels, BESIX, Mobilis, Dura Vermeer, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Transportation Infrastructure Construction Market Shifts & Advancements
Digital twin technology is compressing design-validation cycles for complex Dutch infrastructure, while circular material mandates and procurement model evolution are restructuring how public agencies contract for long-life assets.
Building information modeling paired with real-time sensor networks is integrating geotechnical monitoring with construction sequencing for deep foundation works beneath Amsterdam's canal belt. Rijkswaterstaat pilot projects demonstrate 15-20% schedule compression through predictive settlement modeling. Contractors adopting this capability are securing design-build contracts that transfer geological risk from public clients.
EU Green Deal carbon intensity reporting requirements administered by the Ministry of Infrastructure and Water Management now mandate embodied emissions disclosure for steel, cement, and asphalt in national infrastructure tenders. Contractors must document supply chain provenance or face disqualification. The Rotterdam port rail extension program exemplifies this shift, with low-carbon concrete specifications written into technical requirements.
Public clients are consolidating maintenance and construction spend into decade-long performance contracts that bundle asset availability guarantees with initial capital delivery. Rijkswaterstaat's A16 Rotterdam and A15 Maasvlakte-Vaanplein projects demonstrate this model. Tier-one contractors must now underwrite operational risk for thirty-year design lives, favoring firms with in-house maintenance capability and balance sheet depth.
Netherlands Transportation Infrastructure Construction Market Segmentation
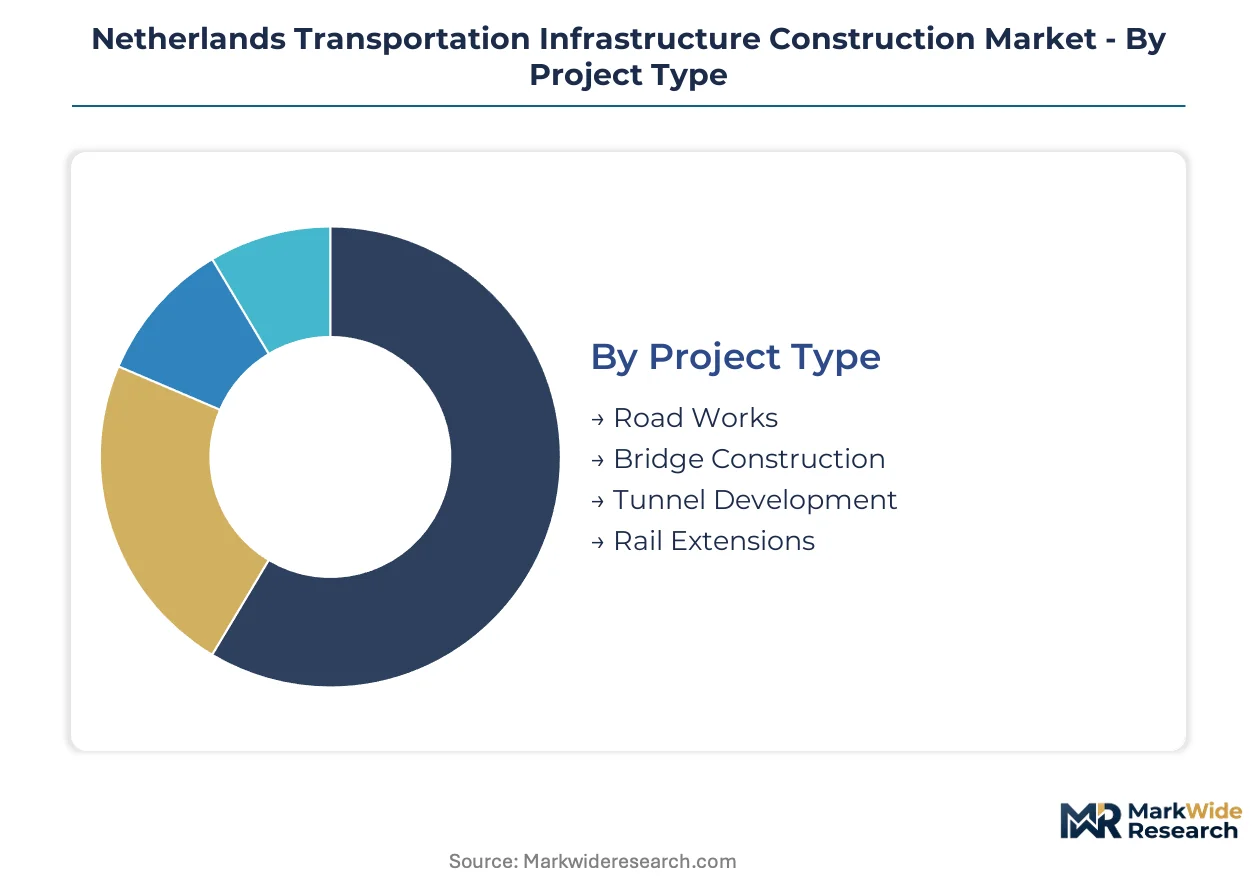
Dutch infrastructure procurement channels capital through distinct technical and contractual pathways. Project type determines geotechnical complexity and regulatory oversight intensity. Material selection and construction method choices increasingly hinge on carbon intensity thresholds embedded in Rijkswaterstaat tenders.
Project Type:
Buyer differentiation centers on soil mechanics expertise requirements and waterway disruption tolerance.
- Road Works:Surface and sub-surface pavement engineering for highways and urban arterials dominates public capital allocation. Randstad congestion relief drives demand for lane expansion and interchange upgrades, though archaeological clearance beneath polder landscapes extends timelines unpredictably.
- Rail Extensions:Electrified corridor development for freight diversion from road networks commands premium engineering margins. Rotterdam-Europoort connectivity and European freight corridor integration concentrate investment in double-tracking and gauge standardization projects.
- Bridge Construction:Span structures over canals and rivers require corrosion-resistant design for North Sea maritime climates. Delta soil conditions necessitate pile depths exceeding twenty meters for foundation stability.
- Tunnel Development:Immersed tube and bored tunnel methods beneath Amsterdam and Rotterdam waterways capture the highest margins due to specialized marine contractor scarcity.
Volume sits with Road Works; growth tilts toward Rail Extensions.
Material:
Specification choices separate projects by embodied carbon disclosure requirements and design life expectations.
- Concrete:Low-carbon formulations with recycled aggregate content now mandated for national infrastructure tenders. Rijkswaterstaat lifecycle emissions criteria disqualify conventional Portland cement blends lacking supply chain provenance documentation.
- Steel:Corrosion-resistant reinforcement grades essential for marine exposure zones in Rotterdam port hinterlands. EU carbon border adjustment exposure compresses margins on imported structural sections.
- Asphalt:Surface course mixtures for highways and urban roadways incorporating reclaimed pavement material. Warm-mix technologies reduce production energy intensity for Green Deal compliance.
- Composite Materials:Fiber-reinforced polymers for bridge decks and corrosion barriers in aggressive chloride environments. Limited domestic supply chains constrain adoption outside demonstration projects.
Concrete commands current procurement volumes; steel faces the steepest cost pressure from decarbonization mandates.
Construction Method:
Schedule compression needs and traffic disruption limits drive method selection divergence between urban cores and greenfield corridors.
- Traditional:Cast-in-place concrete and on-site steel erection for remote or low-traffic locations. Labor intensity and weather exposure extend project durations beyond compressed urban timelines.
- Modular:Factory-produced bridge components and tunnel segments assembled on-site with minimal traffic closure. Randstad urban densification favors this approach for A16 Rotterdam and A15 Maasvlakte-Vaanplein corridors.
- Prefabricated:Complete superstructure elements manufactured off-site and transported to foundation locations. Heijmans and VolkerWessels compete aggressively for these contracts to limit on-site labor hours.
- In-situ:Continuous pour and cast methods for complex geometries unsuited to prefabrication. Deep foundation works beneath Amsterdam's canal belt rely on real-time geotechnical monitoring during placement.
Traditional methods retain volume in peripheral provinces; modular approaches are expanding most quickly in Randstad corridors.
End User:
Risk allocation preferences and balance sheet capacity separate procurement channels.
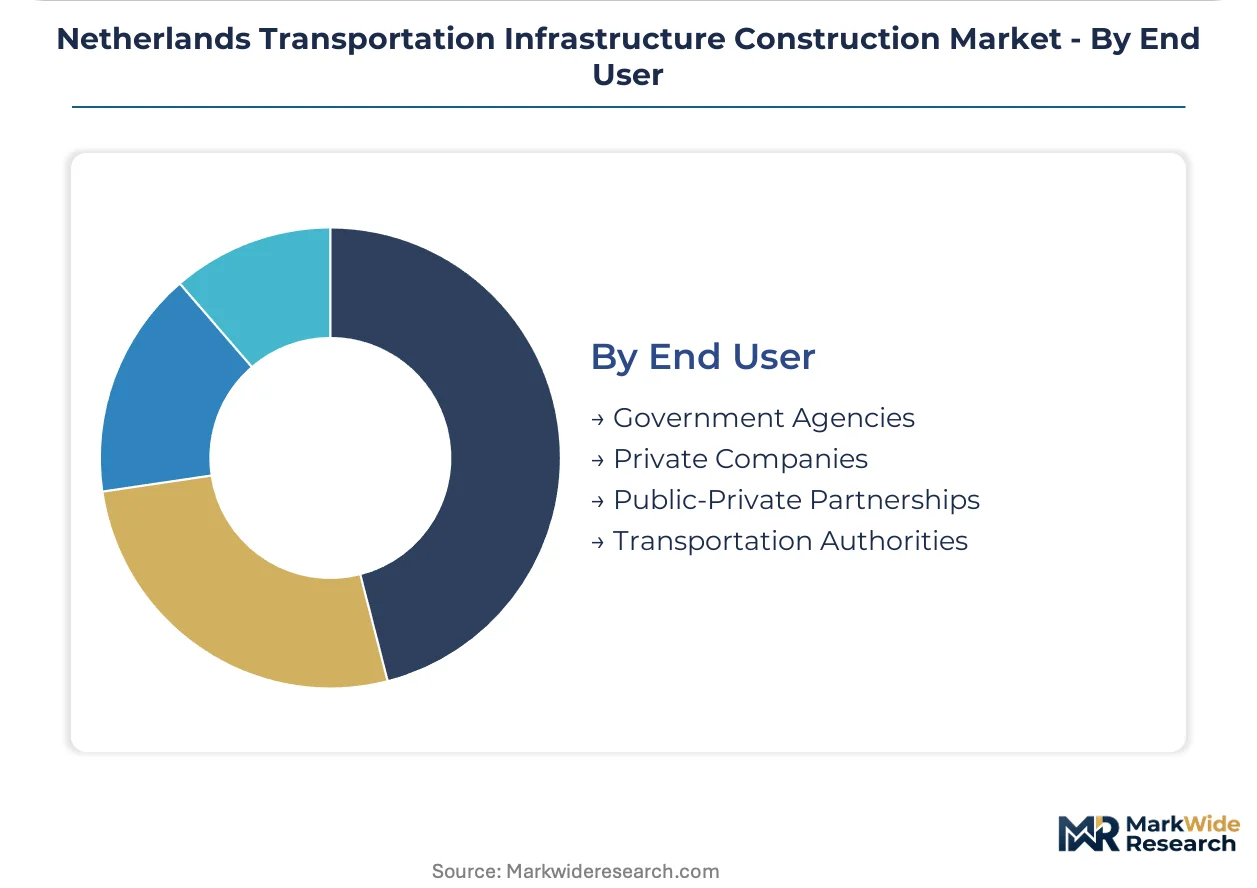
- Government Agencies:Rijkswaterstaat and Ministry of Infrastructure and Water Management administer national trunk road and waterway programs. Direct procurement maintains design control for heritage-sensitive alignments.
- Private Companies:Industrial facility access roads and port terminal infrastructure commissioned by Rotterdam-Europoort operators. Specifications prioritize heavy-load capacity and maintenance cost minimization.
- Public-Private Partnerships:Decade-long performance contracts bundling construction and maintenance risk transfer to contractors. Royal BAM Group anchors these through civil engineering division balance sheet depth.
- Transportation Authorities:Provincial and municipal entities managing urban transit and regional rail. Amsterdam and Rotterdam metropolitan agencies drive tunnel and bridge capacity expansion.
Direct government procurement holds current volume; public-private partnerships are gaining share fastest through availability-guarantee models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Dutch transportation infrastructure concentrates in the Randstad corridor, where Rotterdam-Europoort freight volumes and Amsterdam urban densification drive tunnel, bridge, and rail investment. Provincial sub-regions exhibit divergent project pipelines shaped by soil conditions, port proximity, and heritage protection intensity.
Randstad Conurbation
Amsterdam-Rotterdam-Utrecht-The Hague corridor commands the dominant share of national infrastructure capital. Rijkswaterstaat administers the A16 Rotterdam and A15 Maasvlakte-Vaanplein corridor upgrades under performance-contract frameworks. Rotterdam port expansion for offshore wind logistics drives heavy-load quay wall construction along the Nieuwe Waterweg.
North Brabant
Eindhoven-Tilburg-Breda triangle generates sustained road and rail demand from logistics distribution clustering. The Ministry of Infrastructure and Water Management prioritizes freight corridor electrification through this southern province. Modular bridge component manufacturing concentrates near Tilburg industrial zones to supply Randstad projects.
Northern Netherlands
Groningen-Friesland-Drenthe provinces face slower project velocity due to lower population density and peat soil geotechnical complexity. EU Green Deal modal shift mandates nonetheless require rail upgrades to Groningen Seaport. Archaeological clearance for UNESCO-protected Wadden Sea adjacency extends environmental review timelines unpredictably.
Zeeland
Scheldt-Rhine corridor and Western Scheldt tunnel access dominate infrastructure priorities in this southwestern delta region. Specialized marine contractors concentrate here for immersed tube tunnel expertise serving cross-waterway connections. Port of Vlissingen expansion for container throughput drives quay reinforcement and access road upgrades.
Netherlands Transportation Infrastructure Construction Market Competitive Landscape
Consolidation through design-build capability integration dominates the current landscape as contractors seek geological risk transfer from public clients. The market structures around three tiers: integrated national champions with balance sheet depth for thirty-year performance contracts; specialized marine and tunnel contractors with delta soil expertise; and regional modular construction specialists. Strategic archetypes separate firms by risk underwriting capacity, with in-house maintenance divisions anchoring availability-guarantee models. M&A activity targets geotechnical engineering boutiques, while strategic partnerships with circular material suppliers address EU Green Deal carbon disclosure mandates.
Within the integrated national champion tier, Royal BAM Group and Heijmans occupy positions defined by design-build scale and water management specialization. Van Oord anchors the specialized marine contractor segment, exemplifying the scarce expertise pool for immersed tube tunnel construction in soft delta soils. VolkerWessels sits within the modular construction specialist category, representing competitive positioning through prefabricated methods for urban roadworks compression.
| Leading Market Players |
|---|
| Heijmans |
| Van Oord |
| Royal BAM Group |
| Strukton |
| Ballast Nedam |
| VolkerWessels |
| BESIX |
| Mobilis |
| Dura Vermeer |
| Others |
Supply & Pricing Matrix
Steel futures on the London Metal Exchange cascade through Dutch contractor bid pricing, compressing margins on fixed-price tunnel contracts while amplifying premiums for low-carbon cement blends that satisfy Rijkswaterstaat tender requirements. This commodity volatility stratifies procurement power between integrated national champions with captive supply agreements and smaller regional players exposed to spot market fluctuations.
Pricing Analysis
Volume concentrates in road works and standard bridge construction where thin margins reflect commodity competition, while tunnel development and rail electrification capture premium pricing through specialized marine contractor scarcity and geotechnical risk transfer. Price differentiation hinges on EU Green Deal carbon certification tiers and design-build capability depth, with Rijkswaterstaat's lifecycle emissions criteria disqualifying uncertified bidders. Cost compression in standard concrete and asphalt segments is intensifying because of EU carbon border adjustment exposure on imported structural steel. Provincial municipalities exhibit highest price sensitivity due to constrained capital budgets, whereas Rotterdam-Europoort operators prioritize heavy-load capacity over unit cost.
Supply Chain Analysis
Freight costs from German and Belgian steel mills to Randstad construction sites amplify input price volatility for corrosion-resistant reinforcement grades required in marine exposure zones. Raw material sourcing draws from domestic limestone quarries for cement production, recycled aggregate processors in North Brabant, and specialized tunnel segment manufacturers concentrated in Zeeland's immersed tube fabrication yards. Single-source vulnerability pervades the low-carbon concrete admixture segment, where limited domestic suppliers of alternative binder materials create bottleneck risk. Distribution runs through Rijkswaterstaat-administered national tender platforms for public works, with direct procurement from Rotterdam port operators for private terminal infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of qualified immersed tube tunnel contractors in soft delta soils props pricing power for specialized marine firms, constraining capacity expansion for Amsterdam and Rotterdam waterway crossings. This supply bottleneck sustains margin premiums unavailable in commoditized road construction segments.
For Market Incumbents: Cement design-build capability integration to capture geological risk transfer from Rijkswaterstaat, while securing backward integration into recycled aggregate processing to meet EU Green Deal circular material mandates. Royal BAM Group and Heijmans must defend against modular construction specialists encroaching on urban roadworks through prefabrication efficiency advantages. Capacity addition in Zeeland marine fabrication yards represents the priority lever for tunnel segment supply security. For New Entrants and Emerging Players: Digital-twin-enabled geotechnical monitoring services offer a low-capital entry path into design-build contracts without heavy fabrication assets. Northern Netherlands peat soil rail upgrades present the most penetrable geography given limited incumbent presence and EU Green Deal modal shift funding availability. Partnering with established contractors as predictive modeling subcontractors provides initial revenue traction before direct bidding qualification. For Investors and Strategic Acquirers: Distressed-cycle entries favor geotechnical engineering boutiques in the Randstad corridor, where retirement-driven expertise attrition creates acquisition targets with irreplaceable delta soil mechanics knowledge. Long-term viability centers on firms with in-house maintenance divisions capable of underwriting thirty-year availability guarantees. Watch Rijkswaterstaat pilot project awards for digital twin adoption as the inflection signal for technology-enabled competitive displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build Capability Integration | Captures geological risk transfer from Rijkswaterstaat tenders through single-point accountability. |
| Recycled Aggregate Processing Investment | Secures EU Green Deal compliance for circular material certification in national infrastructure bids. |
| Digital Twin Technology Adoption | Compresses project schedules by 15-20% through predictive settlement modeling for Amsterdam canal belt works. |
| Marine Fabrication Yard Expansion | Addresses bottleneck risk for immersed tube tunnel construction in Rotterdam-Europoport corridor upgrades. |
| Performance Contract Underwriting | Locks in thirty-year maintenance revenue streams through Rijkswaterstaat availability-guarantee frameworks. |
Research Methodology
Independent corroboration across Rijkswaterstaat tender documentation, EU Green Deal implementation guidelines, and Dutch construction industry association filings underwrites the qualitative findings in this study. Primary interviews with project directors at national infrastructure contractors, procurement officers at Rotterdam port authorities, geotechnical engineering consultants, and circular material suppliers were combined with secondary validation from customs trade data, Ministry of Infrastructure and Water Management policy releases, and European Construction Industry Federation reports. Bottom-up project pipeline aggregation and top-down macroeconomic driver assessment were triangulated to establish market sizing boundaries.
Rate-of-change decomposition across project type, material specification, construction method, and end-user risk allocation dimensions anchors the analytical framework over the projection horizon. CAGRs were derived from weighted average growth across segmentation layers, with rail extension investment intensity and tunnel development margin expansion serving as primary forecast inputs. The modeling period incorporates EU Green Deal binding target implementation schedules and Rijkswaterstaat decade-long performance contract rollout patterns without specifying discrete years.
The model holds under sustained EU Green Deal enforcement and stable Rijkswaterstaat capital allocation; deviation in carbon border adjustment tariff levels or archaeological clearance timeline extensions would shift project velocity assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
Taiwan Data Center Construction Market
Infrastructure Construction
Qatar Infrastructure Sector Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Canada Commercial Construction Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
United States Transportation Infrastructure Construction Market
Infrastructure Construction
South Korea Transportation Infrastructure Construction Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
Poland Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Switzerland Transportation Infrastructure Construction Market
Infrastructure Construction
Philippines Data Center Construction Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
China Infrastructure Market