
 Asia-Pacific Transportation Infrastructure Construction Market | 2026-2036
Asia-Pacific Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Transportation Infrastructure Construction Market Outlook
Modular bridge fabrication and precast segment assembly is broadening buyer choice across Asia-Pacific procurement offices. China State Construction Engineering Corporation leverages captive concrete batching capacity to anchor margins on megaprojects. Obayashi Corporation specializes in seismic-resistant joint systems for Japan's expressway renewal cycles. Hyundai Engineering & Construction extends its order book through design-build rail contracts in Southeast Asia.
Asia-Pacific transportation infrastructure construction encompasses the planning, engineering, and physical assembly of corridors and nodes that move freight and passengers across land and air, typically requiring compressive strengths of 30-60 MPa for concrete superstructures and fatigue-rated steel grades for long-span bridges. Its primary purpose is to reduce logistics costs and intercity travel times while supporting population density shifts from rural hinterlands to coastal megacities. Roadways and railways absorb the bulk of public capital allocation, with railways offering higher lifecycle returns where land acquisition permits straight-line geometry. Prefabrication is displacing cast-in-place methods on congested urban sites, compressing construction windows and reducing labor exposure. Government end users dominate tender issuance, though private sector participation through availability-payment concessions is deepening in Australia and India.
Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces PMDA-aligned material certifications for earthquake-resistant infrastructure, while India's BIS mandates IS 456 compliance for reinforced concrete in National Highway Authority projects. China's MEE embeds carbon intensity ceilings into provincial transport procurement, filtering contractor eligibility. Australia's Infrastructure Australia maintains independent project ratings that shape federal funding priority queues. Stakeholders must track how Indonesia's new capital relocation and Vietnam's North-South expressway phases redistribute contractor capacity across the region.
Market Dynamics
China's dual carbon goals are compressing contractor margins through carbon intensity ceilings embedded in provincial transport procurement, forcing material sourcing shifts across cement and steel supply chains.
Growth Catalysts
- Urban rail expansion mandates:India's National Highways Authority is accelerating turnkey construction packages for metro corridors in Delhi, Mumbai, and Bangalore, concentrating demand around design-build delivery models.
- Seismic resilience standards:Japan's PMDA-aligned material certifications for earthquake-resistant infrastructure are mandating advanced joint systems and fatigue-rated steel grades on expressway renewal cycles.
- High-speed rail corridors:Indonesia's new capital relocation and Vietnam's North-South expressway phases are redistributing contractor capacity toward design-build rail contracts across Southeast Asia.
Market Restraints
- Steel and cement input volatility:China's MEE carbon intensity ceilings are tightening material standards and filtering contractor eligibility through embedded emissions tracking.
- Land acquisition geometry constraints:Straight-line railway corridors face acquisition bottlenecks in densely populated Indian states, elevating project timelines and right-of-way costs.
- Prefabrication capability gaps:Cast-in-place methods persist in secondary Southeast Asian markets where modular fabrication yards remain underdeveloped.
Strategic Opportunities
- Availability-payment concessions:Australia's Infrastructure Australia independent project ratings are deepening private sector participation through federal funding priority queues.
- Modular bridge fabrication:Precast segment assembly is broadening buyer choice across procurement offices in congested urban sites throughout the region.
- Carbon-capture concrete integration:China's dual carbon goals are creating procurement preference for low-clinker cement blends in provincial transport bureau tenders.
Industry Challenges
- Seismic engineering talent scarcity:Japan's expressway renewal cycles require specialized expertise in seismic-resistant joint systems that outpaces regional training pipeline output.
- IS 456 compliance timelines:India's BIS mandates for reinforced concrete in National Highway Authority projects extend certification windows for imported admixtures and specialty steel.
- Legacy corridor integration:Indonesia's new capital relocation must interface with existing port and intermodal infrastructure, complicating design-build handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Transportation Infrastructure Construction Market |
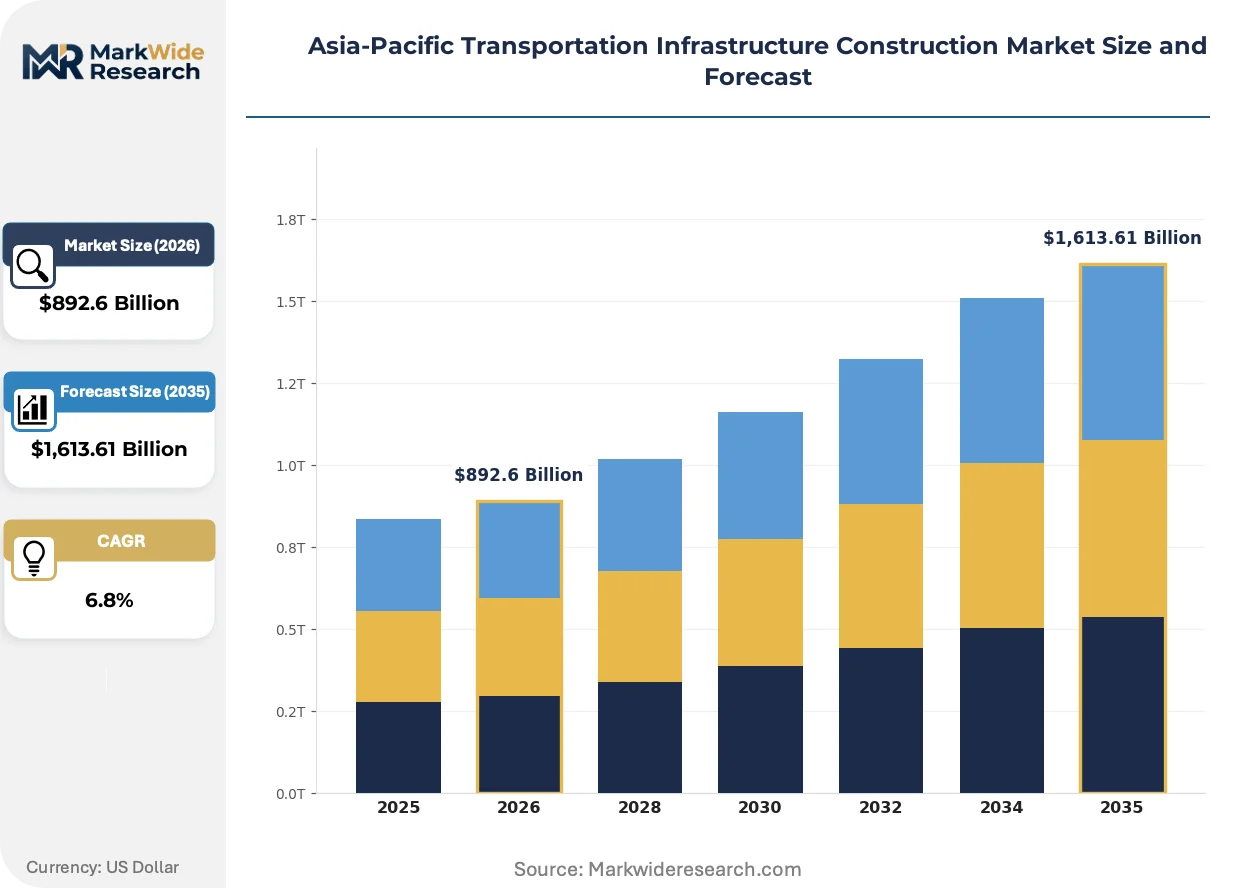
| Market Size in 2026 | $892.6 Billion |
| Market Size in 2035 | $1,613.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roadways, Railways, Airports, Bridges Construction Method: Traditional, Prefabrication, Design-Build, Open Book End User: Government, Contractors, Private Sector, Investors Material Used: Concrete, Steel, Asphalt, Composites |
| Companies Covered | Larsen & Toubro Ltd, Obayashi Corporation, China State Construction Engineering Corporation, Dilip Buildcon Ltd, Reliance Infrastructure Limited, China Railway Construction Corporation, Hyundai Engineering & Construction, CPB Contractors, China Communications Construction Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Transportation Infrastructure Construction Market Strategic Shifts
Prefabrication methods are compressing construction windows and reducing labor exposure on congested urban sites, while digital design tools reshape how transport corridors interface with existing infrastructure networks.
Ultra-high-performance concrete (UHPC) delivers compressive strengths exceeding 150 MPa for thin bridge deck overlays and precast segment joints. Japan's Ministry of Land, Infrastructure, Transport and Tourism is specifying UHPC for seismic retrofit applications on aging expressway structures. This material specification is converging with fatigue-rated steel grades to enable longer bridge spans with reduced superstructure depth.
China's MEE has embedded carbon intensity ceilings into provincial transport procurement frameworks, filtering contractor eligibility based on embedded emissions in cement and steel. Contractors must now document lifecycle carbon footprints for concrete batching and structural steel sourcing. Megaproject tenders in coastal provinces are most affected, with bidders restructuring supply chains to qualify.
Design-build delivery models are displacing traditional design-bid-build sequences on high-speed rail and urban metro projects. Southeast Asian transport authorities in Indonesia and Vietnam are consolidating engineering and construction risk under single-contractor arrangements. This consolidation is most visible in Vietnam's North-South expressway phases, where availability-payment structures now dominate procurement.
Asia-Pacific Transportation Infrastructure Construction Market Segmentation
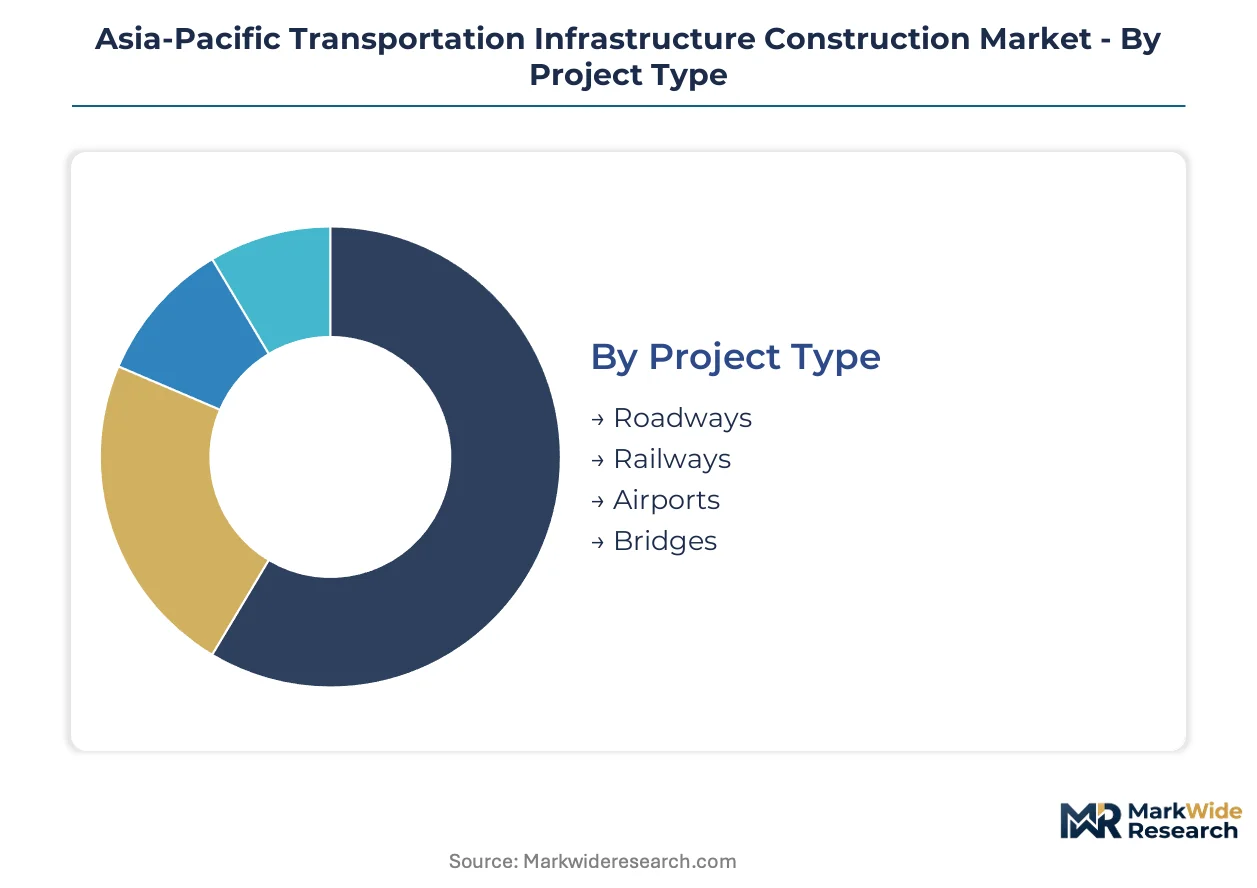
Segmentation in Asia-Pacific transportation infrastructure construction reveals how capital allocation, procurement methods, and material specifications concentrate contractor capability and government spending. Each dimension shapes risk distribution, timeline compression, and compliance burdens across megaprojects and corridor renewals.
Project Type:
Roadways and railways absorb the heaviest upfront capital deployment, with land acquisition and earthworks consuming 40-60% of total project budgets before superstructure assembly begins.
- Roadways:Expressways and arterial corridors dominate procurement volume across India's National Highways Authority and Vietnam's North-South phases. Right-of-way bottlenecks in densely populated states inflate timeline risk and elevate design-build contractor selection criteria.
- Railways:High-speed and urban metro corridors concentrate the region's largest single-project capital outlays. Indonesia's new capital relocation and India's metro expansion in Delhi, Mumbai, and Bangalore are redistributing contractor capacity toward turnkey delivery models.
- Airports:Greenfield terminals and runway extensions in Southeast Asia require specialized pavement engineering and airside logistics integration.
- Bridges:Long-span crossings over major river systems and coastal inlets demand fatigue-rated steel grades and seismic-resistant joint systems.
Most installed capacity flows through Roadways. Expansion is steepest in Railways.
Construction Method:
Method selection determines how engineering risk, cost certainty, and schedule accountability distribute between public agencies and private contractors.
- Design-Build:Single-contractor consolidation of engineering and construction risk is displacing traditional sequences on high-speed rail and urban metro projects. Southeast Asian transport authorities in Indonesia and Vietnam now mandate this approach for corridor megaprojects.
- Prefabrication:Modular bridge fabrication and precast segment assembly compress construction windows on congested urban sites. Japan's expressway renewal cycles and Australia's availability-payment concessions are accelerating yard infrastructure investment.
- Traditional:Cast-in-place methods persist where modular fabrication capacity remains underdeveloped, particularly in secondary Southeast Asian markets.
- Open Book:Transparent cost-plus arrangements with shared risk pools are deepening private sector participation in Australian federal funding queues.
Design-Build captures the dominant share of new tender issuance. Prefabrication is gaining share fastest where labor constraints and urban congestion intensify.
End User:
User type dictates procurement authority, funding mechanisms, and contractor qualification thresholds across the project lifecycle.
- Government:National transport ministries and provincial bureaus issue the majority of tenders, embedding carbon intensity ceilings and material certification requirements into eligibility filters. China's MEE and India's BIS mandates shape contractor compliance burdens.
- Contractors:Large integrated construction groups anchor demand for captive concrete batching capacity and in-house seismic engineering expertise.
- Private Sector:Availability-payment concessions and operational maintenance contracts are expanding in Australia and India, transferring revenue risk to private operators.
- Investors:Infrastructure funds and multilateral lenders shape project finance structures and environmental, social, and governance screening protocols.
Government end users command the largest committed project pipeline. Private Sector participation is expanding most quickly through federal priority queues.
Material Used:
Material specification determines structural performance, lifecycle maintenance burden, and compliance with tightening environmental procurement standards.
- Concrete:Compressive strengths of 30-60 MPa for superstructures and ultra-high-performance formulations exceeding 150 MPa for seismic retrofit applications. China's dual carbon goals are tightening clinker content restrictions in provincial transport bureau tenders.
- Steel:Fatigue-rated grades for long-span bridges and earthquake-resistant joint systems. Japan's PMDA-aligned certifications mandate traceable sourcing for expressway renewal cycles.
- Asphalt:Flexible pavement layers for roadways and airport runways, with polymer-modified binders specified for heavy freight corridors.
- Composites:Fiber-reinforced polymers for bridge deck overlays and corrosion-resistant reinforcement in coastal exposure zones.
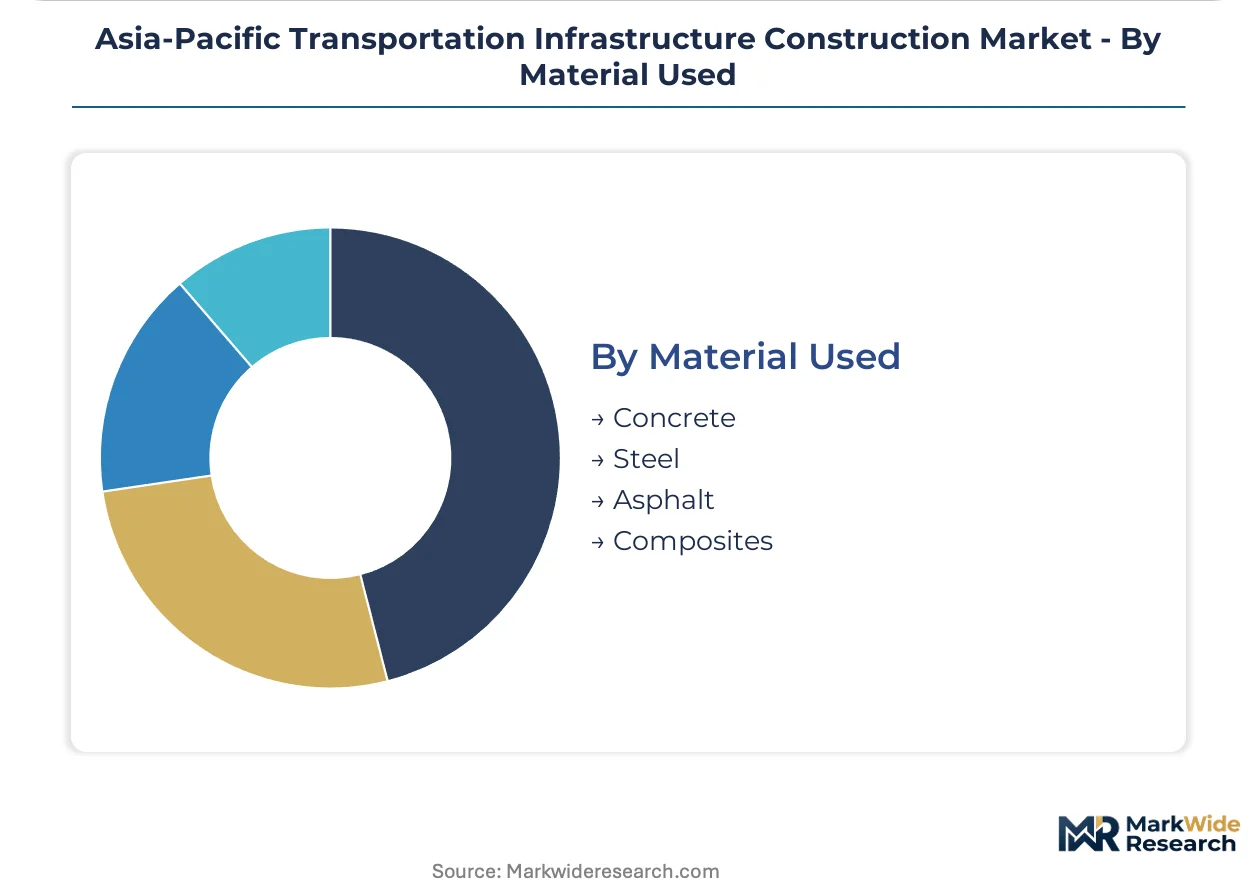
Concrete and Steel together constitute the bulk of material procurement by value. Composites are climbing the fastest as durability specifications tighten in coastal and seismic zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific transportation infrastructure construction traces its modern lineage to Japan's expressway buildout of the 1960s, which established seismic engineering standards later adopted across the region. China's coastal corridor development from the 1990s scaled turnkey delivery models now standard in megaproject procurement.
China
Provincial transport bureaus in Guangdong and Jiangsu are embedding MEE carbon intensity ceilings into tender eligibility, filtering contractor access based on documented cement and steel emissions. The Yangtze River Delta concentrates design-build rail contracts where captive concrete batching anchors bidder margins. Shanghai's megaproject pipeline is restructuring supply chains to qualify for coastal province tenders.
India
National Highways Authority turnkey packages for Delhi, Mumbai, and Bangalore metro corridors are accelerating design-build adoption. BIS IS 456 compliance mandates for reinforced concrete extend certification timelines for imported admixtures. Maharashtra and Karnataka are absorbing the bulk of contractor capacity as land acquisition geometry constraints elevate right-of-way costs in densely populated states.
Japan
MLIT PMDA-aligned material certifications for earthquake-resistant infrastructure are mandating fatigue-rated steel grades on expressway renewal cycles. Kanto and Kansai industrial corridors anchor demand for seismic-resistant joint systems as aging structures require retrofit. Tokyo's procurement offices are specifying ultra-high-performance concrete exceeding 150 MPa for thin deck overlays.
Australia
Infrastructure Australia independent project ratings are deepening private sector participation through availability-payment concessions in federal funding queues. New South Wales and Victoria are concentrating design-build contractor selection where open-book cost-plus arrangements transfer revenue risk. Sydney and Melbourne procurement offices are accelerating prefabrication yard investment to compress urban construction windows.
Vietnam
North-South expressway phases are redistributing contractor capacity toward design-build delivery with consolidated engineering and construction risk. Ho Chi Minh City and Hanoi corridors are absorbing prefabrication methods where modular fabrication yards remain underdeveloped in secondary markets. Provincial transport authorities are mandating single-contractor arrangements for corridor megaprojects.
Asia-Pacific Transportation Infrastructure Construction Market Competitive Environment
The competitive structure tilts toward state-linked construction groups with captive material supply chains. Engineering-led conglomerates and specialized seismic contractors occupy distinct tier positions. Market consolidation centers on design-build capability and in-house concrete batching capacity. Dominant competitive moves include backward integration into cement supply and strategic partnerships for modular fabrication technology licensing.
Among India-based integrated construction groups, Larsen & Toubro Ltd and Dilip Buildcon Ltd exemplify the turnkey delivery archetype with established National Highways Authority relationships. China State Construction Engineering Corporation anchors the state-linked tier with provincial transport bureau positioning. These three entities represent how geographic origin and company structure shape competitive positioning across procurement eligibility filters.
| Leading Market Players |
|---|
| Larsen & Toubro Ltd |
| Obayashi Corporation |
| China State Construction Engineering Corporation |
| Dilip Buildcon Ltd |
| Reliance Infrastructure Limited |
| China Railway Construction Corporation |
| Hyundai Engineering & Construction |
| CPB Contractors |
| China Communications Construction Company |
| Others |
Value Chain & Pricing Dynamics
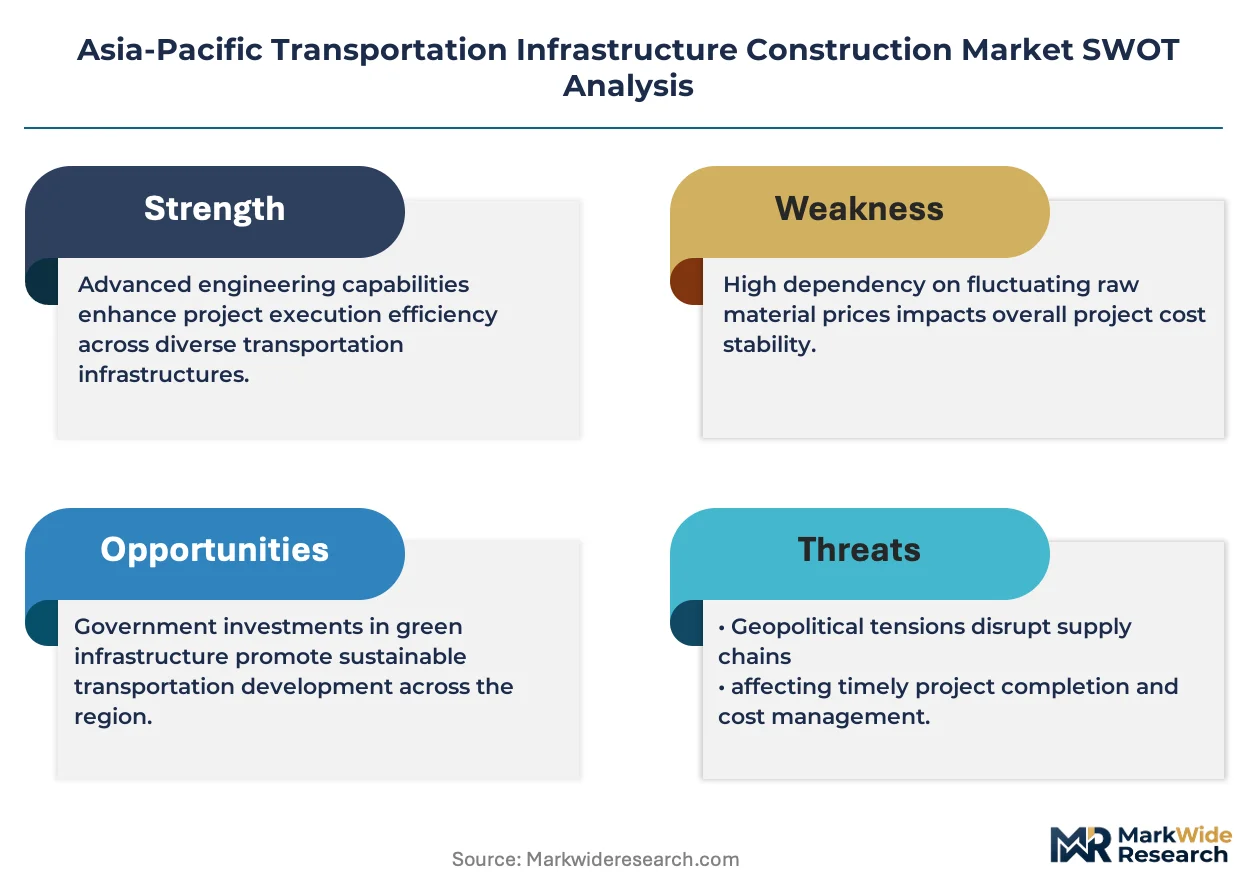
Sovereign-backed construction groups with captive concrete batching capacity anchor supply-side discipline across Asia-Pacific procurement offices, translating upstream material control into bid pricing flexibility on megaproject tenders. China's MEE carbon intensity ceilings and India's BIS IS 456 compliance mandates filter contractor eligibility, concentrating pricing power among integrated players who internalize certification costs.
Pricing Analysis
Project-based lump-sum contracting with escalation clauses dominates transport infrastructure procurement across the region. Price differentiation rests on design-build capability tier and MEE-aligned carbon certification status, with turnkey contractors commanding premiums over traditional sequence bidders. Cost compression in secondary Southeast Asian markets intensifies as Indonesian and Vietnamese authorities consolidate engineering and construction risk under single-contractor arrangements. Government end users exhibit highest price sensitivity on availability-payment concessions, while private operators in Australian federal funding queues prioritize lifecycle cost certainty over upfront capital outlays.
Supply Chain Analysis
MEE-aligned carbon certification and BIS IS 456 compliance function as procurement gates that filter supplier access to provincial transport bureau tenders. Cement and steel supply concentrates in China, India, and Japan, with fatigue-rated steel grades and low-clinker cement blends drawing from integrated domestic mills. Single-source vulnerability runs through coastal province concrete batching capacity where MEE emissions tracking has consolidated supplier tiers. Distribution feeds from captive fabrication yards through design-build contractor networks to government procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific transportation infrastructure construction market functions as a stable compounder anchored by irreversible urbanization and government-mandated rail corridor expansion across India and Southeast Asia.
For Market Incumbents: Acquire modular fabrication yard capacity in Indonesia and Vietnam to preempt design-build tender consolidation. Backward integration into low-clinker cement supply secures MEE compliance margins as carbon intensity ceilings tighten. Threat substitution from cast-in-place persistence in secondary markets demands accelerated prefabrication technology licensing to defend turnkey positioning. For New Entrants and Emerging Players: Capture seismic engineering talent scarcity in Japan's expressway renewal cycles through specialized joint system partnerships. Indonesia's new capital relocation presents the most penetrable white-space corridor, with design-build rail contracts redistributing contractor capacity. Lead with UHPC overlay specialization certified to MLIT PMDA standards as the go-to-market wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap Indian contractors with National Highways Authority relationships but limited captive batching capacity. Long-term viability frames around decade-long government capital commitment cycles rather than project-specific cash flows. Watch Indonesia's provincial transport authority procurement volume as the inflection signal for Southeast Asian contractor capacity utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Clinker Cement | Secures MEE carbon ceiling compliance for coastal province tender eligibility. |
| Modular Fabrication Yard Expansion | Compresses construction windows for congested urban metro sites in Delhi and Bangalore. |
| Seismic Joint System Technology Licensing | Captures MLIT PMDA-certified demand from Japan's expressway renewal cycles. |
| Design-Build Capability Acquisition | Consolidates engineering and construction risk for Vietnam North-South expressway phases. |
| Availability-Payment Concession Structuring | Transfers revenue risk to private operators in Australian federal funding queues. |
Study Parameters
Bottom-up project pipeline modeling reconciled against top-down contractor capacity tracking forms the analytical core of this study. Primary interviews with procurement officers at India's National Highways Authority, project directors at Chinese provincial transport bureaus, and seismic engineering leads at Japan's MLIT inform demand-side calibration. Secondary validation draws from Infrastructure Australia project ratings databases, BIS certification registries, MEE emissions disclosure filings, and customs records for steel and cement trade flows.
Input-output matrices map construction method adoption rates against material specification trends across the projection horizon. Segmentation dimensions include project type, delivery model, end-user procurement authority, and material compliance tier. CAGRs derive from corridor investment schedules and contractor order book trajectories, with carbon intensity ceiling implementation timelines and land acquisition geometry constraints as industry-specific forecast modifiers.
Underlying measurement precision varies by segment; design-build rail contracts and government end-user pipelines carry tighter precision than private availability-payment concessions. Forecasts reflect documented assumptions regarding MEE enforcement consistency and BIS certification timeline stability. A model refresh is warranted upon material change in Indonesia's new capital relocation procurement volume or India's state-level land acquisition policy shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
Poland Transportation Infrastructure Construction Market
Infrastructure Construction
Canada Commercial Construction Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
Finland Transportation Infrastructure Construction Market
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Israel Data Center Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Singapore Transportation Infrastructure Construction Market
Infrastructure Construction
Brazil Infrastructure Sector Market