
 North America Pipeline Maintenance Market | 2026-2036
North America Pipeline Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pipeline Maintenance Market Analytics
Outsourced integrity management is decoupling from traditional in-house pipeline operations across North America. Baker Hughes A GE Co leverages its inspection technology portfolio to anchor long-term service contracts with major midstream operators. T. D. Williamson Inc specializes in inline inspection tools and hot-tapping systems that sustain revenue through recurring hardware refresh cycles. MISTRAS Group competes on advanced ultrasonic testing capabilities, positioning its asset protection solutions across both upstream and downstream infrastructure.
North America pipeline maintenance encompasses the systematic inspection, repair, and rehabilitation of hydrocarbon and water conveyance systems using technologies operating at pressures up to 1,440 psi and temperatures ranging from cryogenic to 350°F, with primary purpose being leak prevention, flow assurance, and regulatory compliance extension of asset life. Inspection services dominate current revenue pools as operators face mandatory cycle reductions under federal rules, while predictive maintenance categories are expanding fastest as sensor deployment and data analytics enable shift from time-based to condition-based intervention. Ultrasonic and magnetic flux leakage technologies capture the majority of inline inspection contracts, though CCTV methods retain strong share in water utility and municipal distribution networks where access constraints favor simpler deployment.
PHMSA governs hazardous liquid and natural gas pipeline safety standards across the United States, mandating integrity management programs that directly determine inspection frequency and method selection for operators. Canada's CER and provincial regulators including the AER enforce comparable requirements that shape cross-border maintenance protocols and technology qualification processes. Mexico's CRE and ASEA are tightening downstream pipeline oversight as energy reform expands private participation in hydrocarbon transport. Stakeholders must monitor regulatory harmonization progress across all three countries while evaluating which inspection technologies qualify under evolving mutual recognition frameworks.
Market Dynamics
PHMSA's integrity management cycle compression is forcing midstream operators to accelerate inspection frequency across aging gas transmission networks, fundamentally restructuring how maintenance capacity is procured and scheduled.
Growth Catalysts
- Inline inspection tool advancement:Magnetic flux leakage and ultrasonic testing platforms now detect corrosion defects at sub-millimeter resolution, enabling predictive replacement of pipe segments before failure.
- Texas Permian Basin density:Concentrated pipeline infrastructure in West Texas generates recurring maintenance demand as crude gathering systems require continuous integrity verification under high-cycle production stress.
- PHMSA rule tightening:Updated federal safety standards mandate shortened reassessment intervals for high-consequence areas, directly expanding contracted inspection service volume.
Market Restraints
- Specialized technician scarcity:Certified inline inspection analysts and pipeline welding inspectors command premium labor rates, compressing contractor margins across the US and Canada.
- Equipment import concentration:Advanced sensor arrays and robotic crawler systems rely heavily on European and East Asian component suppliers, exposing maintenance fleets to extended lead times.
- Permitting friction for excavation:Environmental review requirements for pipeline digs in federally managed lands create scheduling uncertainty that delays repair execution.
Strategic Opportunities
- Mexico energy reform pipeline buildout:CRE and ASEA oversight expansion across newly privatized hydrocarbon transport routes creates first-mover positioning for integrity management providers entering Mexican operations.
- Drone-mounted sensor deployment:Aerial thermography and methane detection systems are converging with ground-based inspection protocols to enable continuous right-of-way monitoring without pipeline shutdown.
- Digital twin integration:Physics-based modeling of pressure and corrosion progression allows operators to extend asset life through targeted intervention rather than blanket replacement.
Industry Challenges
- Data interoperability gaps:Legacy SCADA systems in decades-old pipeline networks resist integration with modern analytics platforms, fragmenting operational visibility.
- Certification timeline compression:Rapidly evolving PHMSA qualification requirements for new inspection technologies force service providers to recertify platforms before full depreciation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pipeline Maintenance Market |
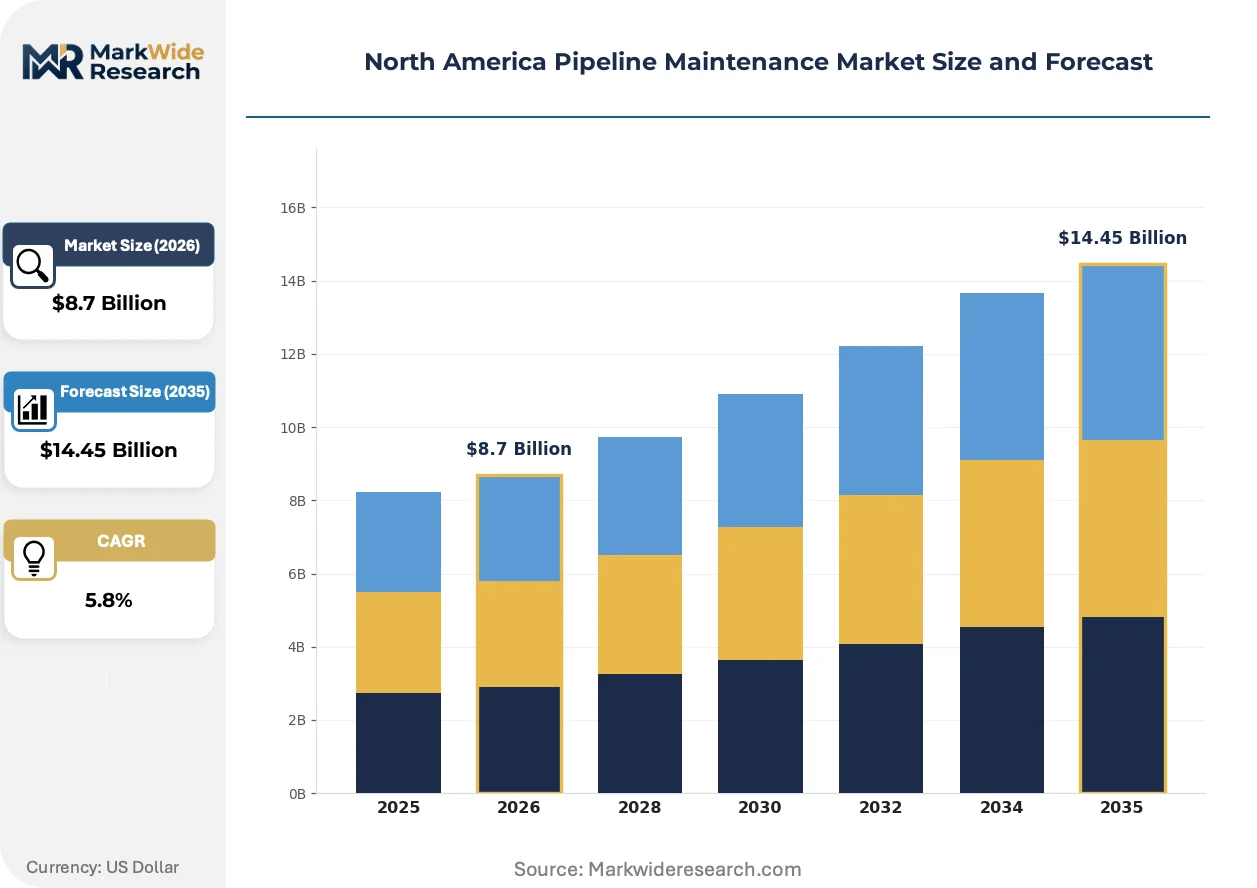
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Cleaning, Rehabilitation, Emergency Repair Technology: Ultrasonic, Magnetic Flux Leakage, Laser, CCTV End User: Oil & Gas, Water Utilities, Chemicals, Telecommunications Maintenance Type: Preventive, Predictive, Corrective, Condition-Based |
| Companies Covered | Baker Hughes A GE Co, T. D. Williamson Inc, Oil States Industries Inc., EnerMech Ltd, STATS Group, Intertek Group PLC, MISTRAS Group, Aegion Corporation, NiGen International L L C, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pipeline Maintenance Market Evolving Landscape
Sensor miniaturization and edge computing are collapsing the latency between defect detection and maintenance dispatch, compressing the traditional inspection-to-intervention cycle from months to days across North American pipeline networks.
Robotic inline inspection platforms equipped with electromagnetic acoustic transducers are converging with cloud-based defect classification algorithms, enabling real-time crack sizing without pipeline depressurization. Midstream operators in the Permian Basin and Alberta oil sands are deploying these systems on quarterly rather than annual cycles. The structural result is a shift from calendar-based maintenance budgets to condition-triggered capital allocation.
PHMSA's 2024 guidance on advanced leak detection performance targets is mandating continuous monitoring systems for gas transmission lines in high-consequence areas. Operators must now demonstrate detection sensitivity below one percent of flow volume within five minutes. This regulatory compression is driving fastest adoption among interstate transmission systems crossing densely populated corridors in the Northeast and California.
Service contracting is fragmenting from multi-year bundled agreements toward discrete scope purchases for specific inspection technologies. Large midstream companies now procure magnetic flux leakage, ultrasonic, and direct assessment services through separate vendor relationships rather than single-source integrity management contracts. This unbundling is most pronounced among Permian Basin operators managing diverse gathering system ages and metallurgies.
North America Pipeline Maintenance Market Segmentation
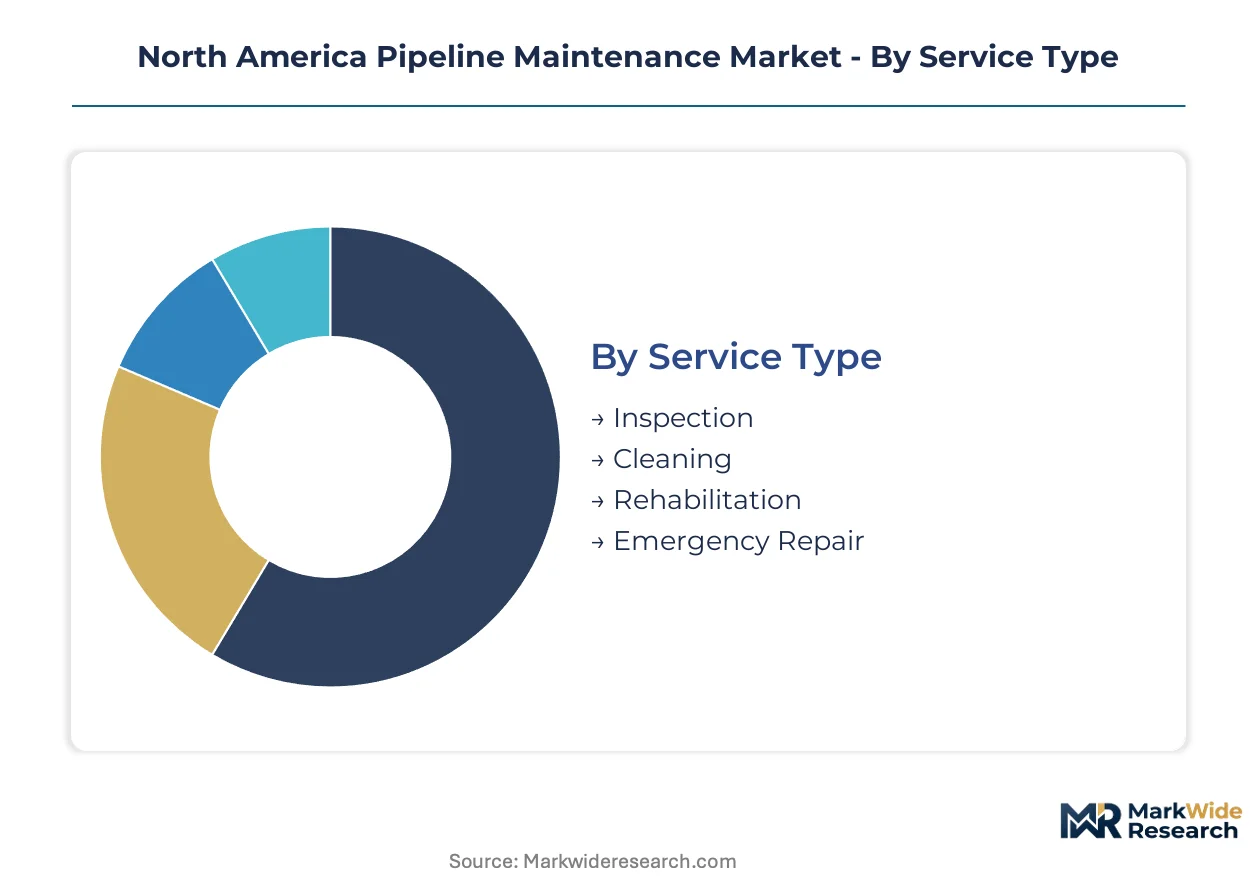
Pipeline maintenance procurement patterns diverge sharply between integrated integrity programs and discrete service purchases. Understanding where operators embed capabilities versus outsource standalone functions determines vendor positioning and contract structure across North American midstream networks.
Service Type:
Inspection services anchor standalone procurement with dedicated budgets and specialized contractor relationships, while cleaning and rehabilitation often embed within broader integrity management frameworks.
- Inspection:Magnetic flux leakage and ultrasonic platforms operate at pressures up to 1,440 psi across crude oil and natural gas transmission lines. PHMSA's compressed reassessment intervals for high-consequence areas are expanding contracted inline inspection volume in Texas and California corridors.
- Cleaning:Pigging operations remove wax, scale, and debris to restore flow efficiency in gathering systems. Permian Basin operators schedule quarterly cleaning cycles under high-cycle production stress, generating recurring demand independent of integrity findings.
- Rehabilitation:Sleeve installation and composite wrap repairs extend asset life without line replacement.
- Emergency Repair:Hot-tap and clamp deployment addresses unplanned failures under pressure.
Volume placements concentrate in Inspection; the faster expansion belongs to Emergency Repair as climate stress and aging metallurgy elevate rupture frequency.
Technology:
Cost tier differentiation separates premium sensor platforms from standardized visual methods, with procurement patterns reflecting defect sensitivity requirements and access constraints.
- Ultrasonic:Electromagnetic acoustic transducers detect crack geometries at sub-millimeter resolution without pipeline depressurization. Midstream operators in Alberta oil sands deploy these systems on quarterly cycles, shifting from calendar-based to condition-triggered capital allocation.
- Magnetic Flux Leakage:High-field magnetization identifies corrosion metal loss across long-haul transmission segments. The technology captures majority share in interstate gas networks where PHMSA mandates continuous wall thickness verification.
- Laser:Structured light profiling maps dent and deformation geometry for fitness-for-service assessments.
- CCTV:Closed-circuit video inspection dominates municipal water distribution networks where access constraints and lower pressure ratings favor simpler deployment.
Magnetic Flux Leakage holds the largest installed base; Ultrasonic platforms are climbing the fastest as real-time crack sizing enables predictive replacement.
End User:
Application severity splits the market between hydrocarbon transport with catastrophic failure consequences and utility infrastructure with service continuity priorities.
- Oil & Gas:Crude gathering and gas transmission systems operate under PHMSA integrity management rules with mandatory inspection cycles. Texas Permian Basin density generates concentrated maintenance spend as operators verify continuous integrity under high-stress production conditions.
- Water Utilities:Potable and wastewater conveyance systems prioritize leak detection and structural rehabilitation. Municipal procurement favors CCTV and acoustic methods over inline sensor platforms due to smaller diameter pipelines and lower operating pressures.
- Chemicals:Corrosive product pipelines require specialized metallurgy and accelerated inspection protocols.
- Telecommunications:Fiber optic conduit maintenance represents emerging demand as broadband infrastructure expands.
Oil & Gas commands the dominant revenue share; Water Utilities are gaining share fastest as lead pipe replacement programs accelerate across US municipal systems.
Maintenance Type:
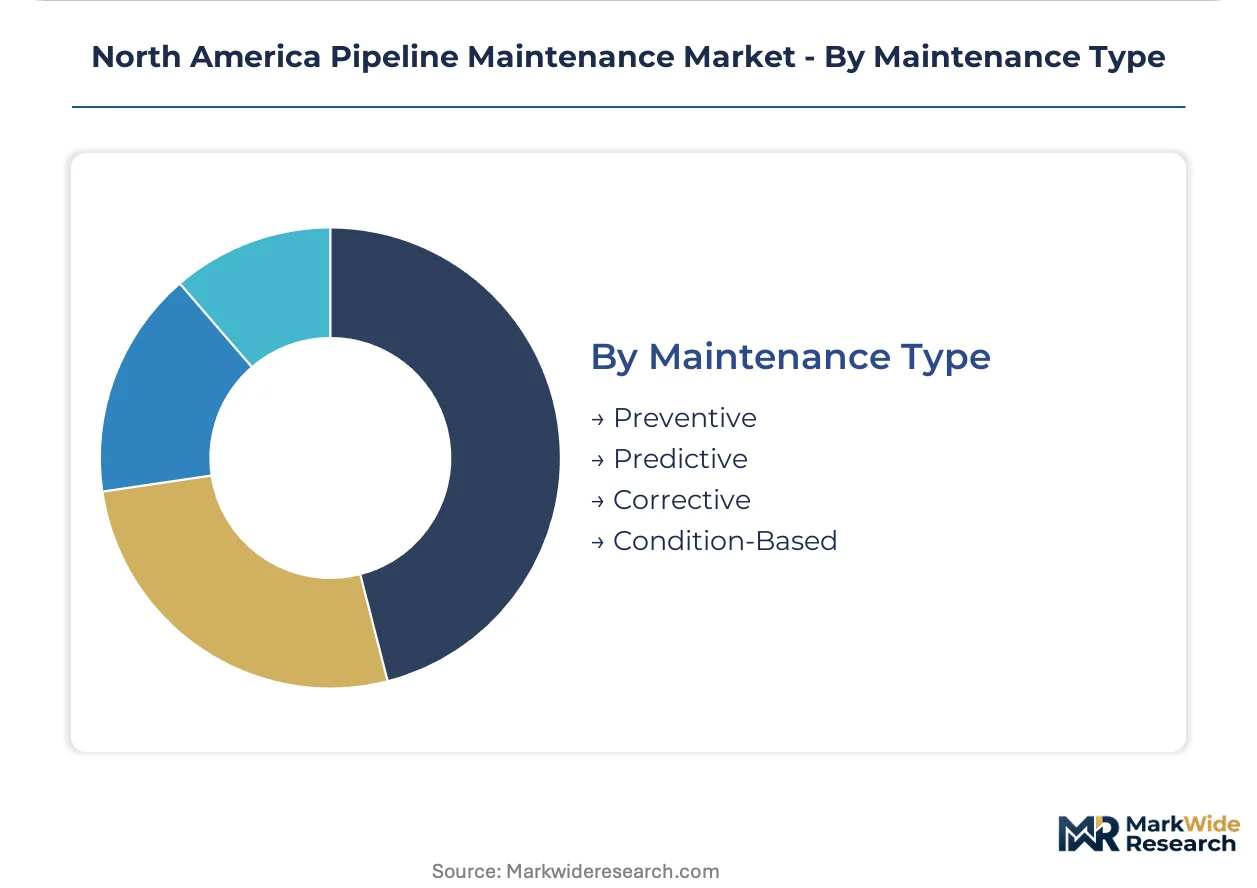
Maturity stage differentiation positions legacy time-based programs against emerging condition-monitoring frameworks with divergent technology requirements and vendor relationships.
- Predictive:Sensor deployment and data analytics enable defect progression modeling before failure manifestation. PHMSA's 2024 leak detection performance targets mandate continuous monitoring systems with sub-one-percent sensitivity, driving fastest adoption among Northeast and California interstate corridors.
- Preventive:Scheduled inspection and replacement intervals based on historical failure rates and regulatory minimums. This category retains strong share among smaller operators lacking capital for sensor infrastructure and analytics platforms.
- Corrective:Reactive response to identified defects or reported failures.
- Condition-Based:Intervention triggered by real-time monitoring thresholds rather than calendar schedules.
Preventive programs retain the largest operational footprint; Predictive categories show the steepest expansion trajectory as digital twin integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin crude deposits anchor North American pipeline maintenance demand, with West Texas infrastructure density generating concentrated inspection and repair activity across gathering systems operating under sustained production stress.
United States
PHMSA's compressed integrity management cycles mandate shortened reassessment intervals for high-consequence areas, particularly across interstate gas transmission corridors in the Northeast and California. The Permian Basin in West Texas concentrates maintenance spend as operators verify continuous pipeline integrity under high-cycle crude production conditions. Baker Hughes A GE Co and T. D. Williamson Inc anchor service contracting relationships with major midstream operators in this region.
Canada
The Canada Energy Regulator and provincial authorities including the Alberta Energy Regulator enforce integrity management requirements comparable to US standards, shaping cross-border maintenance protocols for transnational pipeline systems. Alberta's oil sands operations generate recurring ultrasonic inspection demand as electromagnetic acoustic transducer deployments shift toward quarterly cycles. MISTRAS Group positions its asset protection solutions across both upstream extraction and downstream refining infrastructure in this jurisdiction.
Mexico
The Comisión Reguladora de Energía and Agencia de Seguridad, Energía y Ambiente are tightening downstream pipeline oversight as energy reform expands private participation in hydrocarbon transport routes. Newly privatized transport infrastructure creates positioning opportunities for integrity management providers entering Mexican operations. Gulf Coast corridor development connects this market to US and Canadian maintenance service ecosystems.
North America Pipeline Maintenance Market Competitive Landscape
Technology licensing dominates the current landscape as service providers seek qualification under rapidly evolving PHMSA certification requirements. The vendor base clusters around three strategic archetypes: diversified energy technology conglomerates with inspection hardware portfolios, specialized inline tool manufacturers with recurring hardware refresh revenue models, and asset protection specialists competing on advanced non-destructive testing capabilities. M&A activity concentrates among mid-cap regional contractors seeking geographic coverage expansion, while strategic partnerships between sensor technology developers and analytics platforms accelerate predictive maintenance solution deployment.
Within the diversified technology tier, Baker Hughes A GE Co exemplifies the integrated service provider archetype through its long-term contracting relationships with major midstream operators. T. D. Williamson Inc occupies a specialized position among inline inspection tool manufacturers, with its corporate structure indicating sustained revenue through hardware refresh cycles. MISTRAS Group represents the asset protection specialist archetype, competing across upstream and downstream infrastructure segments with advanced testing capabilities. These three companies collectively illustrate the competitive positioning strategies visible across the North American pipeline maintenance vendor landscape.
| Leading Market Players |
|---|
| Baker Hughes A GE Co |
| T. D. Williamson Inc |
| Oil States Industries Inc. |
| EnerMech Ltd |
| STATS Group |
| Intertek Group PLC |
| MISTRAS Group |
| Aegion Corporation |
| NiGen International L L C |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up inspection specialists now dominate North American pipeline maintenance contracting, concentrating supply-side ownership among fewer entities and hardening pricing discipline across multi-year service agreements. This ownership compression tightens margin negotiation leverage for midstream operators while embedding equipment financing costs into quoted rates.
Pricing Analysis
Warranty and service-bundling configurations separate premium from economy tiers, with comprehensive coverage including sensor recalibration and emergency response commanding substantial premiums over bare equipment leases. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under PHMSA qualification requirements. Price differentiation hinges on ultrasonic platform resolution capabilities and magnetic flux leakage field strength specifications. Cost compression in economy-tier pigging services is intensifying because certified analyst scarcity drives labor premiums. Smaller municipal water utilities exhibit highest price sensitivity due to fixed-rate revenue constraints, while Permian Basin crude operators prioritize detection sensitivity over unit cost.
Supply Chain Analysis
Workforce availability constraints in German sensor manufacturing and Japanese precision electronics hubs extend lead times for electromagnetic acoustic transducer arrays and robotic crawler components. Advanced inline inspection platforms draw from specialized magnet suppliers in Germany, semiconductor fabs in Japan, and composite housing producers in South Korea. Raw material dependencies center on rare-earth magnets, high-temperature alloys, and fiber-optic sensing cables. Single-source vulnerability concentrates in electromagnetic acoustic transducer production where qualified vendors number below five globally. Distribution runs through authorized service centers co-located with Permian Basin and Alberta oil sands production clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American pipeline maintenance sits in a technology-transition phase as real-time crack-sizing ultrasonic platforms displace calendar-based magnetic flux leakage programs. This shift restructures vendor relationships and capital allocation patterns across midstream networks.
For Market Incumbents: Deploy backward integration into sensor manufacturing to secure component supply against extended lead times from German and Japanese suppliers. Lock in multi-year exclusive service agreements with Permian Basin operators before unbundling trends fragment contracting relationships. Certification investment under PHMSA's evolving qualification timelines anchors competitive positioning against emerging technology entrants. For New Entrants and Emerging Players: The premium-to-economy price gap in inline inspection services opens positioning room for mid-tier providers offering PHMSA-compliant magnetic flux leakage without full ultrasonic resolution. Mexico's newly privatized hydrocarbon transport routes represent the most penetrable geography as CRE and ASEA oversight expansion creates first-mover windows. Direct sales to regional midstream operators bypassing established distributor networks accelerates initial contract capture. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized inline tool manufacturers with recurring hardware refresh revenue models in Texas and Alberta corridors. Five-to-ten year viability hinges on predictive maintenance platform integration capabilities rather than standalone inspection hardware. The signal to watch is PHMSA guidance on advanced leak detection performance thresholds accelerating continuous monitoring mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Manufacturing Backward Integration | Captive magnet and transducer supply secures production continuity against German and Japanese export constraints. |
| Mexico Energy Reform Market Entry | CRE and ASEA oversight expansion across privatized routes creates first-mover positioning for integrity providers. |
| Digital Twin Platform Integration | Physics-based corrosion modeling extends asset life and shifts capital allocation from replacement to targeted intervention. |
| Drone-Mounted Sensor Deployment | Aerial thermography converges with ground protocols enabling continuous right-of-way monitoring without pipeline shutdown. |
| PHMSA Certification Pre-Investment | Early qualification under evolving performance targets locks in approved vendor status before competitor platform recertification. |
Research Methodology
PHMSA regulatory filings, CER enforcement records, and midstream operator integrity management disclosures formed the secondary backbone for demand quantification and cycle compression analysis. Primary interviews with pipeline integrity managers, inline inspection tool engineers, and midstream procurement directors combined with bottom-up service contract aggregation and top-down regional infrastructure mapping. Triangulation across these sources validated segmentation splits between predictive and preventive maintenance categories.
Historical trendline analysis of inspection service volumes tracked against PHMSA reassessment interval compressions established baseline growth trajectories across the projection horizon. The analytical framework modeled service type, technology platform, end-user sector, and maintenance program maturity as core segmentation dimensions. CAGRs derived from correlated infrastructure age profiles and regulatory mandate timelines, with Permian Basin production stress indices and Alberta oil sands extraction rates serving as industry-specific volume drivers.
Inputs from federal regulatory databases and provincial energy regulators were available through the study window; gaps in proprietary operator maintenance spend data introduce uncertainty bands around segment-level forecasts. Forecasts reflect documented assumptions regarding PHMSA rule implementation pace and Mexico energy reform participation rates. Material deviation in pipeline rupture frequency or cross-border regulatory harmonization progress warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
South Korea Transportation Infrastructure Construction Market
Infrastructure Construction
Qatar Infrastructure Sector Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Overhead Conductor Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Bahrain Construction Market
Infrastructure Construction
Global Rail Infrastructure Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
Canada Commercial Construction Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
Transportation Infrastructure Construction Market
Infrastructure Construction
Israel Data Center Construction Market