
 Building Modules Market | 2026-2036
Building Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Building Modules Market Analytics
ISO 3834 welding quality certification is collapsing the supplier base for steel module fabricators, eliminating smaller metalworkers who cannot sustain audit cycles. Skanska leverages its captive design-build capability to control module specification from engineering through site handover. Bouygues Construction anchors its position through integrated concrete precasting across French and Belgian plants. VINCI dominates transport logistics, using proprietary heavy-lift sequencing to reduce crane time on constrained urban sites.
Building modules are volumetric structural units, typically 90-95% complete at factory exit, incorporating MEP rough-ins, insulation, and interior finishes before flatbed delivery to foundation anchors. Their primary purpose is compressing construction schedules by parallelizing site preparation with factory production. Steel modules lead in commercial office applications where column-free spans and fire ratings drive specification, while wood modules capture residential unit growth as mass timber engineering codes mature across Nordic and North American jurisdictions. Hybrid modules concentrate margin pools where concrete cores provide acoustic separation and steel frames enable long-span upper floors.
F-Gas Regulation in Europe restricts refrigerant-intensive HVAC pre-installation in modules, forcing manufacturers toward CO2 heat pump integration or site-based mechanical commissioning. The EPA's lead-safe renovation rules in the US extend to module finish work, adding compliance layers for residential suppliers targeting multifamily developers. OSHA's fall-protection mandates for module stacking operations shape crane-protocol design and crew certification requirements. Stakeholders must decide whether to internalize certification costs or cede steel-module share to concrete and timber alternatives as qualification barriers stiffen.
Market Dynamics
ISO 3834 welding certification is compressing the steel module supplier base, eliminating smaller fabricators unable to sustain audit cycles while concentrating production among qualified producers. This structural filter is reshaping competitive access across commercial and healthcare verticals.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Procurement teams in Germany and France now specify low-carbon steel and mass timber systems, redirecting capital toward certified fabricators.
- Healthcare facility expansion timelines:Hospital operators in the UK and Netherlands compress construction schedules by 40-60% through volumetric patient room modules with pre-installed MEP.
- Labor shortage intensity in Nordic residential construction:Denmark and Sweden face skilled trades deficits exceeding 15,000 workers, pushing developers toward factory-completed housing units.
Market Restraints
- Steel input cost volatility:Hot-rolled coil price swings of 30-40% annually destabilize module fabricator margins and contract bidding confidence.
- F-Gas Regulation refrigerant restrictions:Europe's HVAC pre-installation limitations force manufacturers toward CO2 heat pump integration, adding engineering complexity and cost.
- Transport dimensional constraints:Road clearance limits below 4.5 meters in urban UK and German corridors restrict module height and interior volume specification.
Strategic Opportunities
- US multifamily residential underpenetration:Modular construction captures under 5% of annual housing starts, leaving white space for timber-framed unit producers to scale.
- Hybrid module technology convergence:Concrete core-steel frame combinations enable acoustic separation in lower floors with long-span upper levels for commercial flex space.
- India PLI scheme for affordable housing:Production-linked incentives for prefabricated construction create entry pathways for European and Asian module exporters.
Industry Challenges
- ISO 3834 certification timeline compression:Smaller metalworkers face 18-24 month qualification cycles, ceding steel module share to concrete and timber alternatives.
- Site-factory coordination complexity:Foundation anchor precision requirements within 3mm tolerance demand laser surveying and real-time logistics synchronization.
- OSHA fall-protection mandate compliance:Module stacking operations require certified rigging crews and engineered lift sequences, constraining crane availability and crew scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Modules Market |
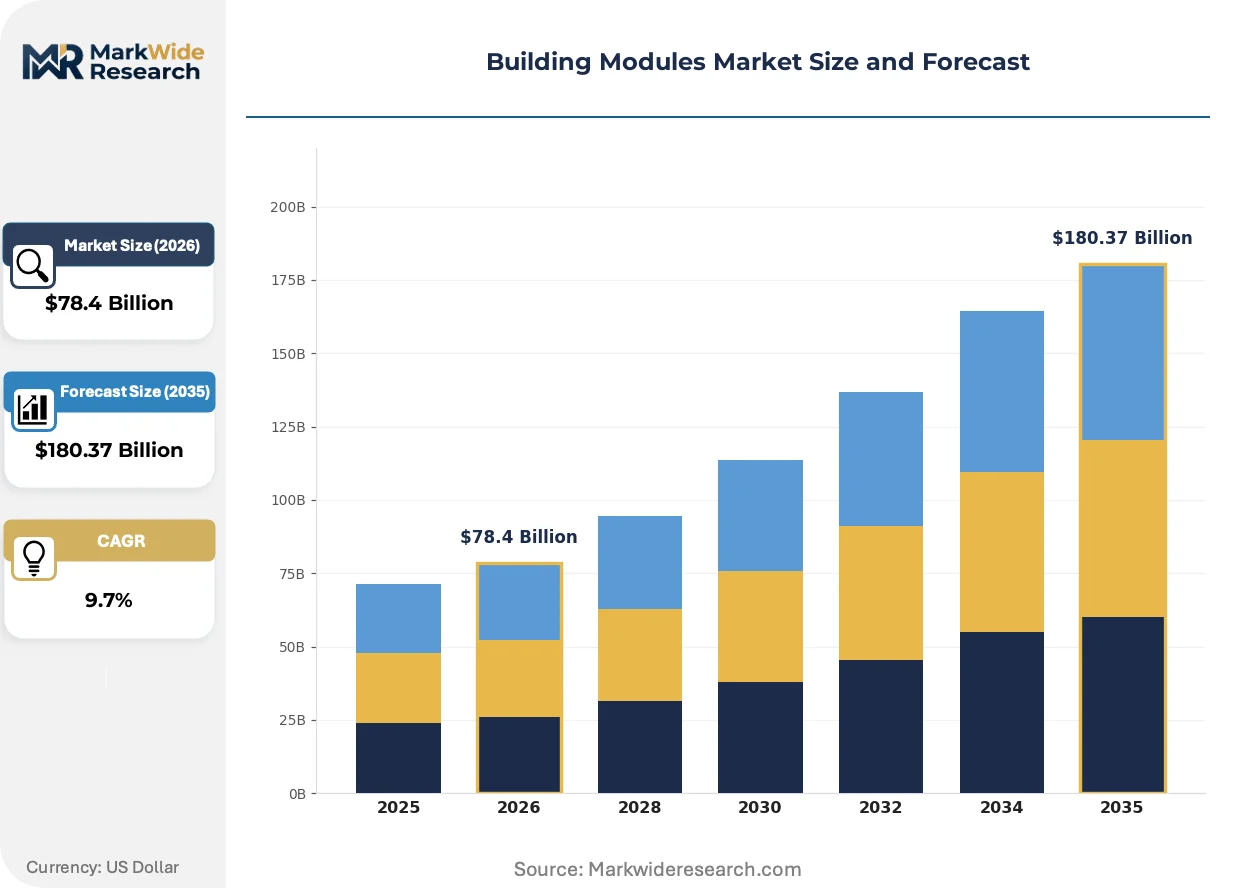
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $180.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Modules, Steel Modules, Concrete Modules, Hybrid Modules Application: Residential Units, Commercial Offices, Educational Institutions, Healthcare Facilities Installation Type: On-site Assembly, Off-site Prefabrication, Modular Renovation, Temporary Structures End User: Contractors, Developers, Architects, Government Agencies |
| Companies Covered | Laing O'Rourke, Skanska, ATCO Ltd., Modulaire Group, Bouygues Construction, Red Sea International, VINCI, Lendlease Corporation, Bechtel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Modules Market Evolving Landscape
Mass timber engineering codes are maturing across Nordic and North American jurisdictions, enabling wood modules to capture residential unit growth while steel retains commercial office dominance. Three converging developments are restructuring product specification and procurement patterns.
Cross-laminated timber (CLT) and glue-laminated beam systems are supplanting light-frame wood in mid-rise residential modules, delivering fire ratings and span capabilities previously requiring steel. Scandinavian developers specify CLT volumetric units for 6-12 story buildings. This material shift compresses embodied carbon footprints by 30-50% versus conventional steel-concrete hybrids.
Europe's F-Gas Regulation restricts refrigerant-intensive HVAC pre-installation in modules, forcing manufacturers toward CO2 heat pump integration or site-based mechanical commissioning. Fabricators in Germany and Belgium now engineer split-system designs that complete refrigerant connections post-delivery. Residential and hospitality segments absorb the added coordination cost to maintain factory completion rates near 90%.
Hospital operators and student housing developers now contract directly with module fabricators, bypassing general contractor markups and compressing procurement cycles. Design-build entities like Skanska and VINCI respond by internalizing module specification control from engineering through site handover. This channel disintermediation concentrates most visibly in UK healthcare and French social housing programs where public procurement rules favor direct manufacturer engagement.
Building Modules Market Segmentation
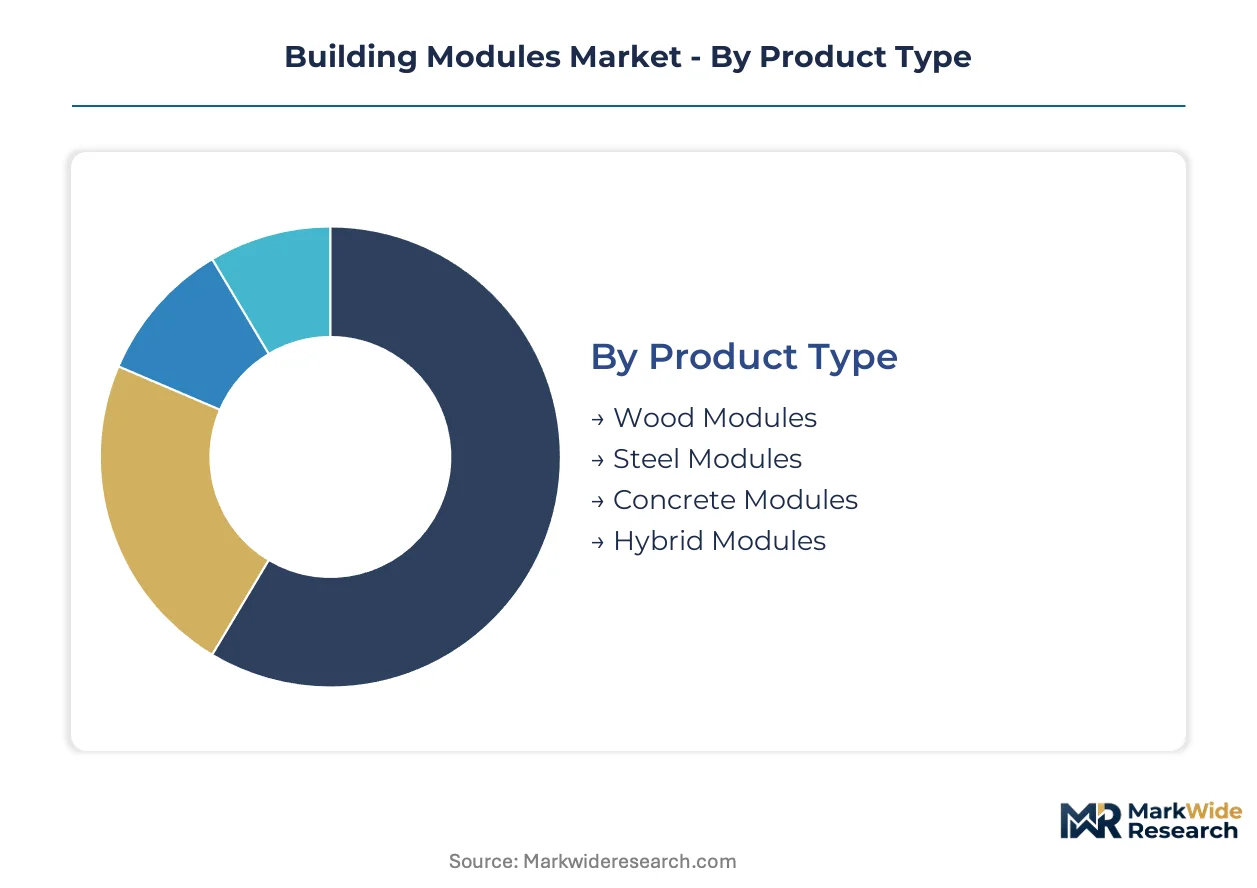
Building modules segment across material systems, project types, and delivery models that determine factory investment, transport logistics, and site coordination requirements. Specification choices cascade through supply chains, welding certification demands, and carbon accounting methodologies.
Product Type:
Wood modules face the most intense substitution pressure as mass timber codes mature and developers seek embodied carbon reductions.
- Steel Modules:Hot-rolled and cold-formed steel framing delivers column-free spans and fire ratings required in commercial office towers. Germany and France specify low-carbon steel grades under EU Green Deal thresholds, concentrating procurement among ISO 3834-certified fabricators.
- Wood Modules:Cross-laminated timber and glue-laminated systems enable 6-12 story residential construction with 30-50% lower embodied carbon than steel-concrete alternatives. Denmark and Sweden deploy CLT volumetric units to offset skilled trades deficits exceeding 15,000 workers.
- Concrete Modules:Precast concrete delivers acoustic separation and thermal mass in healthcare and educational buildings. Bouygues Construction anchors European supply through integrated precasting across French and Belgian plants.
- Hybrid Modules:Concrete core-steel frame combinations pair acoustic performance at lower levels with long-span upper floors for commercial flex space. UK hospital operators specify hybrid systems for patient room modules with pre-installed MEP.
Steel modules anchor the volume base in commercial applications while wood modules gain share at the steepest rate in Nordic residential construction.
Application:
Cost tier differentiation separates turnkey healthcare contracts from speculative residential development.
- Residential Units:Multifamily housing drives timber module adoption as factory completion rates near 90% compress construction schedules. US underpenetration below 5% of annual housing starts leaves expansion white space for timber-framed producers.
- Healthcare Facilities:Hospital operators in the UK and Netherlands compress timelines by 40-60% through volumetric patient rooms with pre-installed mechanical, electrical, and plumbing systems. Direct fabricator contracting bypasses general contractor markups.
- Commercial Offices:Steel modules dominate where fire ratings and open floor plates drive specification. Skanska leverages captive design-build capability to control module engineering through site handover.
- Educational Institutions:School construction favors concrete modules for durability and acoustic separation in classroom clusters. French social housing programs channel procurement toward direct manufacturer engagement.
Healthcare facilities command premium pricing while residential units expand most quickly across European and North American markets.
Installation Type:
Supply concentration favors off-site prefabrication as transport logistics and crane protocols mature.
- Off-site Prefabrication:Factory completion rates of 90-95% compress site schedules by parallelizing foundation work with production. VINCI dominates transport sequencing through proprietary heavy-lift protocols that reduce crane time on constrained urban sites.
- On-site Assembly:Foundation anchor precision within 3mm tolerance demands laser surveying and real-time logistics synchronization. OSHA fall-protection mandates shape rigging crew certification and crane availability.
- Modular Renovation:EPA lead-safe renovation rules in the US extend to module finish work, adding compliance layers for residential suppliers. Site-factory coordination complexity limits adoption in historic building retrofits.
- Temporary Structures:Rapid-deployment modules serve emergency housing and event infrastructure with reduced foundation requirements. Transport dimensional constraints below 4.5 meters in UK and German urban corridors restrict interior volume specification.
Off-site prefabrication anchors production scale while modular renovation climbs the fastest as retrofit markets mature.
End User:
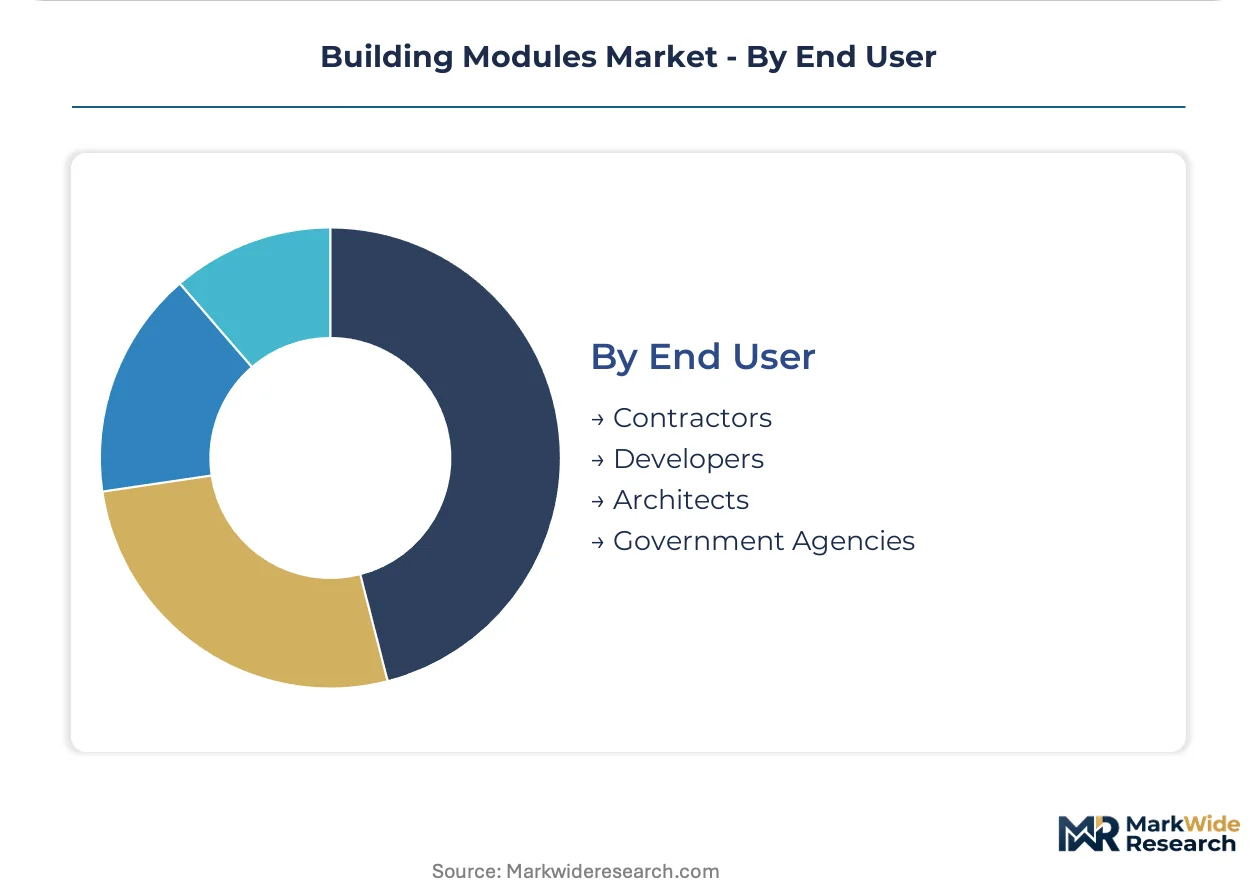
Customer type determines specification control, with developers and government agencies driving standardization.
- Developers:Speculative residential and commercial projects prioritize schedule compression and cost predictability. Labor shortage intensity in Nordic markets pushes developers toward factory-completed housing units.
- Government Agencies:Public procurement rules in UK healthcare and French social housing favor direct manufacturer engagement. India's PLI scheme for affordable housing creates entry pathways for European and Asian module exporters.
- Contractors:General contractors face margin compression as hospital operators and student housing developers bypass traditional procurement channels. Design-build entities respond by internalizing module specification control.
- Architects:Early-stage design influence shapes material selection and module dimensioning. Mass timber engineering code maturation across Nordic and North American jurisdictions redirects architect specification toward wood systems.
Developers anchor current demand volume while government agencies gain procurement influence fastest through public housing and healthcare programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital operators and affordable housing developers concentrate procurement power in Germany, the UK, and the Netherlands, while Nordic residential markets absorb timber modules to offset skilled trades shortages exceeding 15,000 workers.
Germany
Labor shortages and housing deficits push developers toward off-site prefabrication as factory completion compresses schedules. EU Green Deal embodied carbon thresholds redirect procurement toward low-carbon steel and mass timber systems. The Rhine-Ruhr corridor anchors steel module fabrication where ISO 3834-certified producers concentrate production.
United Kingdom
Hospital operators compress construction timelines by 40-60% through volumetric patient room modules with pre-installed MEP systems. Public procurement rules in NHS expansion programs favor direct manufacturer engagement over general contractor channels. The Midlands manufacturing belt hosts timber and steel module plants serving London healthcare and student housing clusters.
Netherlands
Healthcare facility expansion drives demand for hybrid concrete-steel patient room units with acoustic separation. F-Gas Regulation restrictions force manufacturers toward CO2 heat pump integration or site-based mechanical commissioning. The Randstad urban corridor concentrates module logistics where VINCI deploys proprietary heavy-lift sequencing to reduce crane time.
Sweden
Residential construction faces skilled trades deficits that factory-completed housing units address through 90-95% completion rates at plant exit. Mass timber engineering codes mature across Nordic jurisdictions, enabling CLT volumetric units for 6-12 story buildings. Stockholm and Gothenburg anchor CLT module fabrication serving densification targets in Malmö and Uppsala.
France
Social housing programs channel procurement toward direct manufacturer engagement under public procurement rules favoring design-build entities. Bouygues Construction anchors European supply through integrated concrete precasting across French and Belgian plants. The Île-de-France region concentrates hospital and educational module demand where acoustic separation specifications favor concrete core systems.
Building Modules Market Competitive Landscape
Player mix skews toward integrated construction conglomerates with captive design-build capability, compressing access for standalone module fabricators. Tiered concentration separates ISO 3834-certified steel specialists from mass timber entrants and concrete precasters with plant networks. Dominant competitive moves include backward integration into MEP engineering and transport logistics control, plus strategic partnerships with hospital operators to bypass general contractor markups.
Among European-based integrated contractors, Skanska, Bouygues Construction, and VINCI occupy positions spanning engineering through site handover. Skanska exemplifies the design-build archetype controlling module specification from initial engineering. Bouygues Construction anchors concrete module supply through captive precasting infrastructure. VINCI represents logistics-dominated positioning where proprietary heavy-lift sequencing reduces urban site constraints.
| Leading Market Players |
|---|
| Laing O'Rourke |
| Skanska |
| ATCO Ltd. |
| Modulaire Group |
| Bouygues Construction |
| Red Sea International |
| VINCI |
| Lendlease Corporation |
| Bechtel Corporation |
| Others |
Value Network & Pricing Analysis
ISO 3834 welding quality certification gates both supplier qualification and price differentiation simultaneously, concentrating steel module production among audited fabricators while relegating uncertified metalworkers to commodity tiers. Hospital operators in the UK and Netherlands absorb 15-25% premiums for certified volumetric units with pre-installed MEP, whereas speculative residential developers in Germany and France prioritize cost predictability over certification grade.
Pricing Analysis
Cost-plus contracts with hot-rolled coil indexation dominate steel module procurement, transferring input volatility to hospital operators and government agencies with budget certainty requirements. Three-tier pricing structure across premium, standard, and economy levels separates ISO 3834-certified fabricators from timber entrants and uncertified steel producers. Pricing pressure stems from steel input cost swings of 30-40% annually, compressing fabricator margins and destabilizing bidding confidence. Government agencies exhibit lowest price sensitivity due to public procurement rules favoring direct manufacturer engagement, while speculative residential developers in the US multifamily segment demand maximum cost compression.
Supply Chain Analysis
Germany and France anchor steel module fabrication where ISO 3834-certified producers concentrate production, while Sweden and Denmark host mass timber CLT plants serving Nordic residential densification targets. Hot-rolled coil, cross-laminated timber panels, and CO2 heat pump systems constitute critical input dependencies. Single-source vulnerability concentrates in German steel suppliers serving Rhine-Ruhr corridor fabricators. Distribution runs through flatbed trucking networks with crane-equipped delivery to foundation anchors, where VINCI deploys proprietary heavy-lift sequencing to reduce urban site constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The building modules market represents high-growth construction disruption as EU Green Deal embodied carbon thresholds redirect procurement toward low-carbon steel and mass timber systems. This regulatory inflection compresses qualification timelines and concentrates production among certified fabricators.
For Market Incumbents: Compound captive design-build capability to control module specification from engineering through site handover, internalizing margin pools threatened by direct manufacturer contracting. Skanska and VINCI demonstrate this archetype. Accelerate backward integration into MEP engineering and transport logistics to defend against channel disintermediation by hospital operators bypassing general contractor markups. For New Entrants and Emerging Players: Lead with timber-framed residential units in US multifamily housing where modular construction captures under 5% of annual starts. Target direct engagement with student housing developers and affordable housing agencies in France and the UK where public procurement rules favor manufacturer bypass of traditional channels. Position through CO2 heat pump integration expertise to address F-Gas Regulation compliance gaps. For Investors and Strategic Acquirers: EU Green Deal implementation reshapes the acquisition landscape by privileging fabricators with certified low-carbon steel supply chains and mass timber engineering capabilities. Long-term viability centers on 5-10 year carbon accounting maturation across European jurisdictions. Target ISO 3834-certified steel specialists with underutilized capacity in Germany and hybrid module technology holders bridging concrete and timber systems. Monitor F-Gas Regulation enforcement intensity as signal for HVAC pre-installation capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 3834 Certification Investment | Qualifies fabricators for EU Green Deal procurement in Germany and France hospital programs. |
| CO2 Heat Pump Integration | Addresses F-Gas Regulation restrictions on refrigerant-intensive HVAC pre-installation in European modules. |
| Direct Manufacturer Contracting | Bypasses general contractor markups in UK NHS expansion and French social housing procurement. |
| Hybrid Module Technology Development | Combines concrete core acoustic separation with steel frame long-span capability for UK patient rooms. |
| Proprietary Heavy-Lift Logistics | Reduces crane time on constrained urban sites in Randstad and London healthcare clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with hospital procurement directors, modular fabricator plant managers, steel distributor account executives, and crane logistics coordinators. Secondary validation drew from EU Green Deal implementation documents, F-Gas Regulation compliance filings, NHS procurement databases, and Swedish mass timber engineering code revisions. Bottom-up module shipment tallies triangulated against top-down construction spend allocations across residential, healthcare, and commercial verticals.
Across the analysis window, volume and value outputs reflect modeling across material system, application type, installation method, and end-user archetype dimensions. CAGRs were derived from segmented growth rate reconciliation against macro construction indicators. Forecast inputs incorporated labor shortage intensity metrics in Nordic markets, embodied carbon threshold enforcement timelines, and steel input cost volatility bands.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement, stable steel pricing regimes, or continued NHS direct procurement authorization would require recalibration. Forecasts reflect documented assumptions regarding certification timeline compression and transport dimensional constraint stability. Recalibration cycles align with material shifts in carbon accounting methodologies and healthcare procurement rule amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Plumbing Fixtures Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Fire-Retardant Treated Wood Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Drywall and Gypsum Board Market
Building & Construction Materials
Architectural Window Films Market
Building & Construction Materials
Quarry Tiles Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
Hydraulic Binder Market
Building & Construction Materials
Elastomeric Expansion Joint Market
Building & Construction Materials
Cleanroom Flooring Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
Global Metal-Faced Insulated Panels Market
Building & Construction Materials
External Wall Insulation Board Market
Building & Construction Materials
Construction Sealants Market