
 APAC Data Center Construction Market | 2026-2036
APAC Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Data Center Construction Market Insights
Project finance through sale-leaseback structures is fragmenting competitive access across the APAC data center construction landscape. DPR Construction leverages its hyperscale specialization to dominate U.S.-originated projects expanding into Singapore and Tokyo. Larsen & Toubro anchors large-scale civil and mechanical builds across India with integrated EPC capabilities. Aurecon Group differentiates through digital engineering and sustainability advisory on Australian and Southeast Asian developments.
Data center construction encompasses the design, engineering, and physical build-out of facilities housing IT infrastructure, with specifications typically requiring power densities exceeding 15 kW per rack and tier III or IV redundancy for mission-critical uptime. Colocation and hyperscale deployment models absorb the majority of new capacity investment, as cloud operators prioritize scalable shell-and-core builds with direct liquid cooling integration over legacy air-cooled enterprise facilities. Modular construction techniques gain traction for edge deployments requiring rapid site activation across dispersed geographies.
Japan's METI enforces stringent energy efficiency standards under its data center policy framework, while Australia's NBN and state-level planning regulations shape facility location and connectivity requirements across New South Wales and Victoria. India's CEA mandates and state electricity board coordination determine power allocation timelines for Mumbai and Chennai projects. Stakeholders must monitor evolving carbon disclosure rules and grid interconnection queues as primary determinants of project feasibility and delivery schedules.
Market Dynamics
Hyperscale cloud operators in Singapore and Sydney are compressing delivery timelines for tier III and tier IV facilities, forcing construction firms to prefabricate electrical and mechanical modules offsite while coordinating with strained grid interconnection queues across metropolitan load centers.
Growth Catalysts
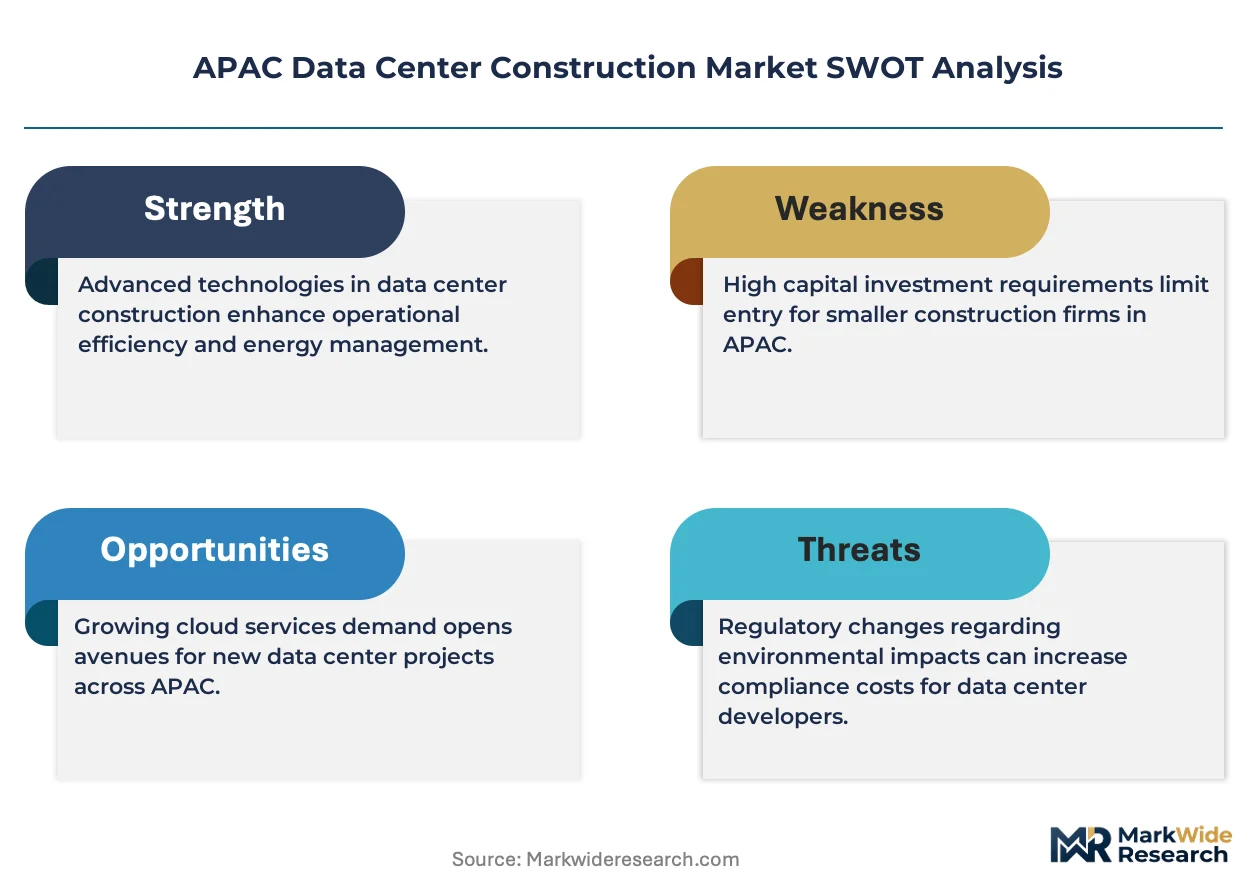
- Japan's METI efficiency mandates:Stringent power usage effectiveness targets under the national data center policy framework accelerate retrofit and greenfield builds compliant with liquid cooling integration requirements.
- Hyperscale deployment models:Cloud operators prioritize scalable shell-and-core construction with direct liquid cooling over legacy air-cooled enterprise facilities, absorbing majority capacity investment.
- India's CEA grid coordination:Central Electricity Authority mandates streamline power allocation timelines for Mumbai-Pune corridor projects, reducing regulatory friction for mission-critical uptime certification.
Market Restraints
- Copper and electrical steel volatility:Transformer and busway material costs fluctuate with commodity markets, compressing EPC margin buffers on fixed-price hyperscale contracts.
- Specialized contractor concentration:Liquid cooling integration expertise concentrates among Singapore and Tokyo-based mechanical firms, creating bottleneck risk for regional expansion timelines.
- Grid interconnection queues:State electricity boards in Maharashtra and Tamil Nadu delay power delivery schedules, extending project feasibility windows beyond sponsor return thresholds.
Strategic Opportunities
- Indonesia's Batam-Jakarta axis:Submarine cable landing stations and tax incentive zones attract hyperscale investment requiring rapid modular deployment across dispersed island geographies.
- Edge computing convergence with 5G:Telecom infrastructure rollouts in Australia and South Korea generate demand for micro data centers with sub-500 kW capacity and sub-12-month activation cycles.
- Australia's NBN infrastructure requirements:National Broadband Network mandates for distributed connectivity nodes create compliance-driven facility specifications favoring design-build contractors with integrated network engineering capabilities.
Industry Challenges
- Liquid cooling technician scarcity:Refrigeration and thermal engineering skill gaps in India and Southeast Asia extend commissioning timelines for high-density rack configurations exceeding 30 kW.
- Tier IV certification complexity:Uptime Institute and TIA-942 concurrent compliance requirements demand redundant documentation streams, inflating project management overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Data Center Construction Market |
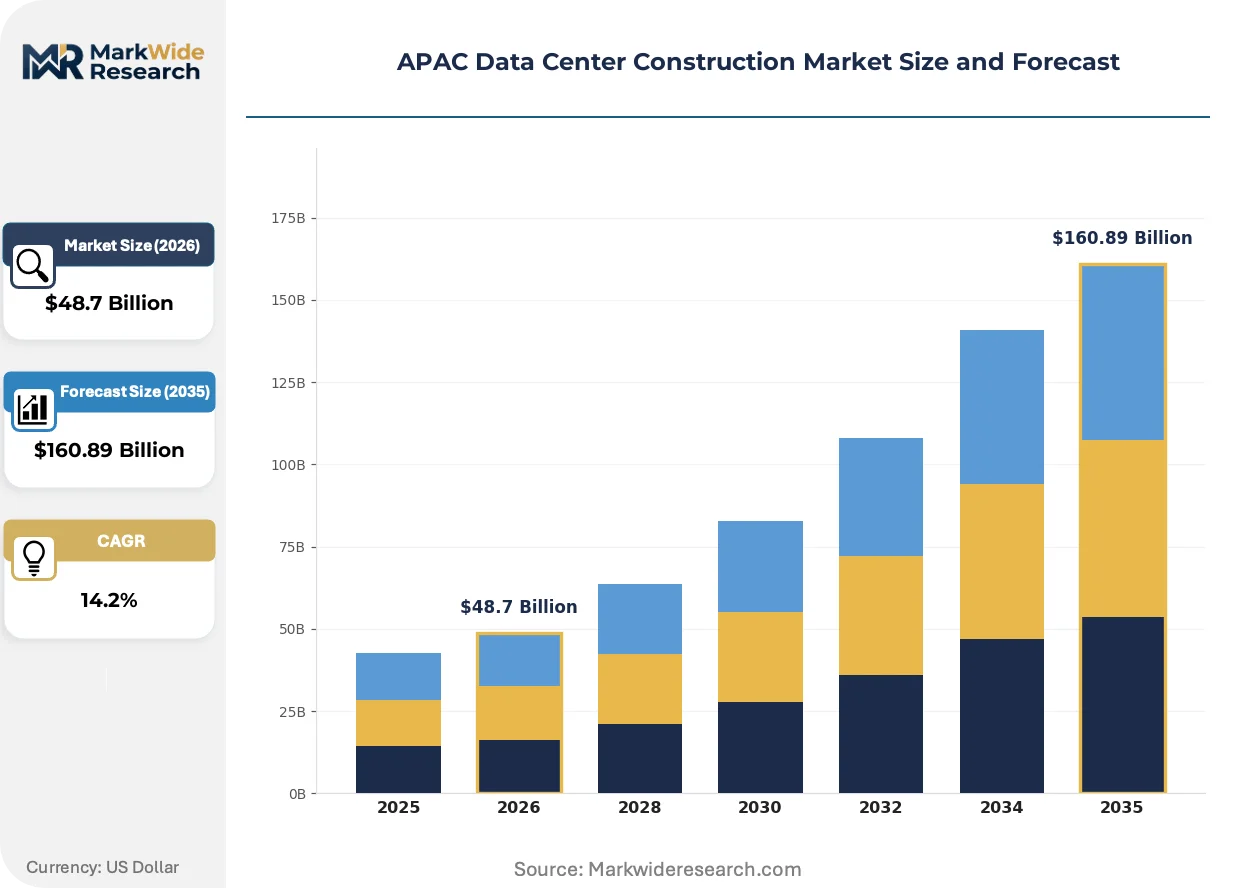
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: New Build, Renovation, Modular, Retrofit Deployment Model: Colocation, Enterprise, Hyperscale, Edge Cooling Technology: AIR, Liquid Cooling, Free Cooling, Immersion Cooling Power Source: Renewable, Grid, Diesel Generator, UPS |
| Companies Covered | DPR Construction Inc., Turner Construction Company, AECOM, Exyte GmbH, Larsen & Toubro, Leighton Asia, Aurecon Group, Gammon Construction, PM Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Data Center Construction Market Trends and Innovations
Digital twin platforms and modular prefabrication are compressing traditional design-build cycles across the APAC data center construction landscape, enabling faster site activation for cloud operators facing capacity constraints.
Software-defined power distribution is virtualizing electrical infrastructure management, allowing hyperscale operators to reconfigure rack-level redundancy without physical rewiring. Singapore and Sydney facilities lead adoption, deploying intelligent busway systems with embedded metering. This capability is virtualizing the traditional electrical contractor role, compressing commissioning timelines from months to weeks.
Japan's METI enforces data center energy efficiency standards requiring annual power usage effectiveness reporting and liquid cooling readiness for facilities exceeding 10 MW capacity. Industrial consequence includes mandatory thermal design reviews before grid connection approval. Hyperscale builds in Tokyo and Osaka face the strictest compliance timelines, accelerating partnerships with local MEP engineering specialists.
Buyers are consolidating procurement under design-build-operate contracts that transfer long-term facility performance risk to EPC firms. Traditional general contracting with separate O&M handoff is losing share to integrated 15-20 year service agreements. This shift is most visible in Australia's New South Wales and Victoria markets, where superannuation fund infrastructure investment mandates favor operational certainty over upfront capex minimization.
APAC Data Center Construction Market Segmentation
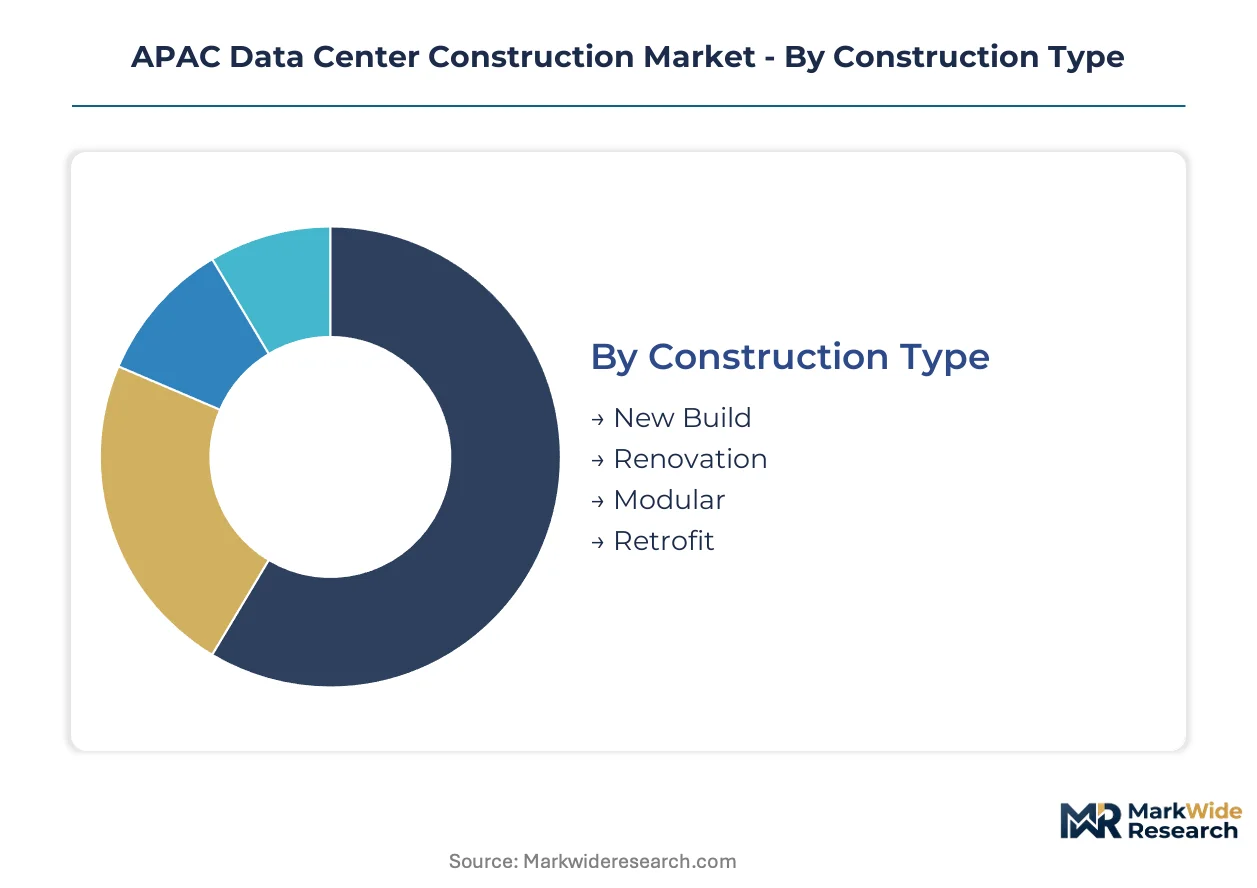
Segmentation reveals how construction specifications diverge across facility types and operational requirements in the APAC data center market. Construction type determines capital deployment patterns, while cooling technology selection increasingly dictates contractor specialization and regional labor availability.
Construction Type:
After-sales service intensity varies dramatically across construction types, with modular deployments demanding rapid field activation support versus multi-year maintenance partnerships for new builds.
- New Build:Ground-up facility development encompasses civil works, shell construction, and integrated MEP installation for greenfield sites exceeding 10 MW capacity. Demand concentrates in Singapore's Tuas and Sydney's Western Parkland City where hyperscale operators secure long-term land leases. Grid interconnection timelines and local planning authority approvals represent the primary delivery constraints.
- Modular:Prefabricated data center modules enable rapid deployment through factory-built mechanical and electrical components shipped to prepared pad sites. Indonesia's Batam-Jakarta corridor and India's secondary cities absorb this format where land scarcity and compressed delivery windows dominate sponsor requirements. Standardized module designs reduce on-site skilled labor dependence.
- Renovation:Existing facility upgrades address power density limitations and cooling inefficiencies in legacy enterprise data centers across Japan and Australia.
- Retrofit:Structural adaptations convert industrial warehouses or commercial buildings into data center-ready infrastructure, prevalent in Mumbai's repurposed textile mills.
New Build holds the largest share; momentum sits with Modular.
Deployment Model:
Cost tier stratification separates capex-heavy hyperscale builds from operational expenditure models favored by enterprise and colocation operators.
- Hyperscale:Single-tenant facilities designed for cloud operators requiring 50+ MW scalable capacity with tier IV redundancy and direct liquid cooling integration. Singapore and Sydney host the densest concentration where DPR Construction and local EPC firms compete for multi-year program awards. Power purchase agreement structures and renewable energy certificates determine site selection feasibility.
- Colocation:Multi-tenant facilities offering wholesale and retail space with standardized power and cooling SLAs to enterprise customers. India's Mumbai-Pune corridor and Melbourne's southeastern suburbs generate sustained demand as financial services and media companies outsource infrastructure ownership. Lease structures emphasize operational uptime guarantees over construction speed.
- Enterprise:Dedicated facilities built for single corporate operators, declining share as cloud migration accelerates across Australian and Japanese enterprises.
- Edge:Sub-1 MW distributed facilities positioned for latency-sensitive applications, expanding most quickly across South Korea's 5G corridor and Australia's NBN node requirements.
Hyperscale commands the largest share; Edge represents the fastest-growing trajectory.
Cooling Technology:
Application requirements dictate thermal management selection, with artificial intelligence training loads forcing adoption of advanced liquid systems.
- Liquid Cooling:Direct-to-chip and rear-door heat exchanger systems handle rack densities exceeding 30 kW for GPU-intensive workloads. Japan's METI mandates accelerate adoption in Tokyo and Osaka facilities where power usage effectiveness targets require sub-1.2 PUE operation. Specialized refrigeration technician scarcity in Southeast Asia extends commissioning timelines.
- Air Cooling:Traditional computer room air handler and hot aisle containment configurations serve legacy enterprise and lower-density colocation facilities. Australia's temperate coastal markets and India's Bangalore plateau leverage this mature technology where ambient conditions permit efficient operation. Capital cost advantages persist for sub-15 kW rack deployments.
- Free Cooling:Economizer systems utilizing ambient air or water sources reduce mechanical refrigeration load, prevalent in New Zealand and southern Australian facilities.
- Immersion Cooling:Dielectric fluid submersion of entire server assemblies addresses extreme density requirements, emerging in Singapore's research and blockchain computing facilities.
Air Cooling retains the largest share; Liquid Cooling gains share fastest.
Power Source:
Customer type differentiation separates sustainability-focused hyperscale procurement from reliability-prioritized enterprise and financial services requirements.
- Renewable:Solar, wind, and geothermal power purchase agreements coupled with battery energy storage systems satisfy corporate sustainability mandates and regulatory disclosure requirements. Australia's Renewable Energy Target and Singapore's Green Plan drive procurement in New South Wales and Jurong Island developments. Grid-scale solar plus storage hybrids reduce reliance on diesel backup.
- Grid:Utility power serves as primary supply with UPS and generator backup for tier III and IV certification compliance. India's CEA coordination with state electricity boards in Maharashtra and Tamil Nadu determines allocation timelines for Mumbai and Chennai projects. Distribution network capacity constraints increasingly limit site feasibility.
- Diesel Generator:Emergency backup systems remain mandatory for tier certification despite sustainability pressures, with fuel storage regulations tightening across Japanese prefectures.
- UPS:Uninterruptible power supply systems provide ride-through capability during grid transitions, with flywheel and lithium-ion technologies displacing lead-acid in premium facilities.
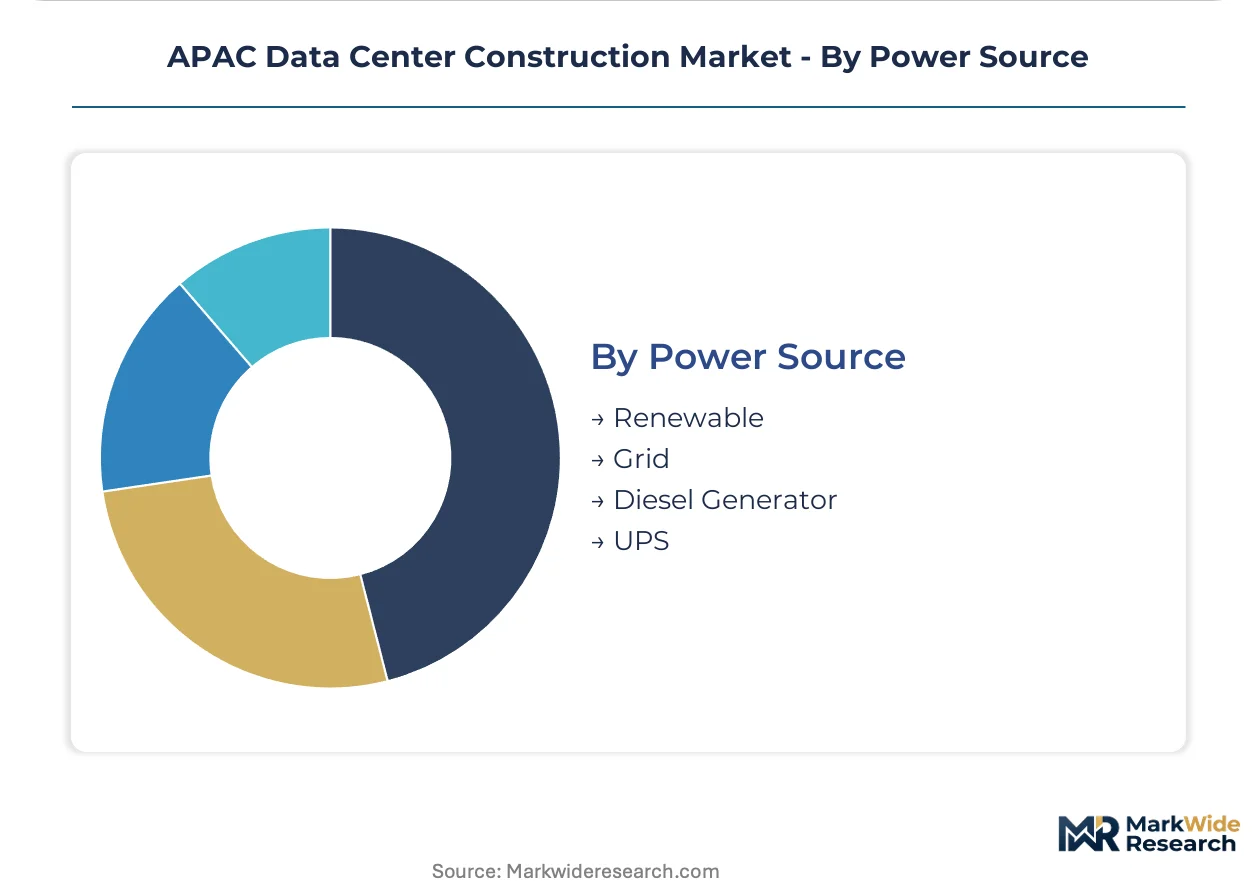
Grid dominates current share; Renewable climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Green Plan 2030 and Australia's National Broadband Network requirements are reshaping facility specifications across the region. National regulators in Japan and India enforce efficiency mandates and grid coordination protocols that determine project feasibility. Construction demand concentrates in metropolitan clusters where hyperscale operators secure land and power allocation.
Singapore
Hyperscale cloud operators compress delivery timelines for tier IV facilities in Tuas and Jurong Island. The country's Green Plan mandates renewable energy procurement and carbon disclosure for facilities exceeding 10 MW capacity. DPR Construction and regional EPC firms compete for multi-year program awards where power purchase agreement structures determine site selection feasibility.
Japan
METI enforces stringent power usage effectiveness targets under the national data center policy framework. Annual PUE reporting and liquid cooling readiness requirements accelerate retrofit and greenfield builds in Tokyo and Osaka. Industrial consequence includes mandatory thermal design reviews before grid connection approval, accelerating partnerships with local MEP engineering specialists.
India
The Mumbai-Pune corridor generates sustained demand as financial services and media companies outsource infrastructure ownership. CEA mandates streamline power allocation timelines, though state electricity boards in Maharashtra and Tamil Nadu delay power delivery schedules. Larsen & Toubro anchors large-scale civil and mechanical builds with integrated EPC capabilities across the region.
Australia
NBN infrastructure requirements and state-level planning regulations shape facility location across New South Wales and Victoria. Design-build contractors with integrated network engineering capabilities capture compliance-driven facility specifications. Superannuation fund infrastructure investment mandates favor operational certainty over upfront capex minimization in Sydney's Western Parkland City.
Indonesia
Submarine cable landing stations and tax incentive zones attract hyperscale investment across the Batam-Jakarta axis. Rapid modular deployment addresses dispersed island geographies where land scarcity and compressed delivery windows dominate sponsor requirements. Standardized module designs reduce on-site skilled labor dependence for edge computing convergence with 5G infrastructure.
APAC Data Center Construction Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement channels. The vendor base organizes around three tiers: integrated EPC firms with civil-mechanical-electrical capabilities, hyperscale-specialized contractors with modular fabrication expertise, and regional design-build operators with local regulatory relationships. Dominant competitive moves include strategic partnerships for liquid cooling integration and geographic expansion through sale-leaseback project finance structures.
Within the integrated EPC tier, Larsen & Toubro represents the archetype of civil and mechanical build anchoring across India. DPR Construction exemplifies hyperscale specialization expanding from U.S. origins into Singapore and Tokyo. Aurecon Group occupies a position in digital engineering and sustainability advisory for Australian and Southeast Asian developments. These three firms illustrate how contractor concentration in liquid cooling integration expertise creates bottleneck risk for regional expansion timelines.
| Leading Market Players |
|---|
| DPR Construction Inc. |
| Turner Construction Company |
| AECOM |
| Exyte GmbH |
| Larsen & Toubro |
| Leighton Asia |
| Aurecon Group |
| Gammon Construction |
| PM Group |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in liquid cooling technician pools across India and Southeast Asia compresses EPC margin buffers while inflating tier IV certification premiums. Singapore and Tokyo-based mechanical firms exploit this scarcity to command pricing power on hyperscale contracts, forcing buyers into longer-term service attachments.
Pricing Analysis
Certification level (Uptime Institute tier III/IV) creates the primary spread between commodity EPC bids and mission-critical premiums. Project-based fixed-price contracts dominate hyperscale procurement, with tier IV redundancy requirements and liquid cooling integration driving differentiation. Cost compression in air-cooled legacy segments is intensifying because cloud operators prioritize scalable shell-and-core builds. Enterprise data center operators exhibit the highest price sensitivity, while hyperscale cloud operators prioritize uptime guarantees over upfront capex minimization.
Supply Chain Analysis
Electrical steel and copper busway fabrication concentrates in China, South Korea, and Japan. Transformer windings and switchgear assemblies draw from these hubs, with refrigeration compressors for liquid cooling systems anchored in Japanese and German manufacturing bases. Single-source vulnerability in specialized MEP engineering creates bottleneck risk for regional expansion timelines. Distribution runs through design-build-operate contracts that transfer long-term facility performance risk to integrated EPC firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Design-build-operate contracts represent a service-attach opportunity expanding faster than standalone construction awards, as superannuation fund infrastructure mandates favor operational certainty over upfront capex minimization.
For Market Incumbents: Harden liquid cooling integration capabilities through partnerships with Tokyo-based MEP specialists before regional expansion timelines compress further. Anchor capacity in Singapore's Tuas and Sydney's Western Parkland City where hyperscale operators secure multi-year program awards. Certification investment in Uptime Institute concurrent compliance documentation streams protects margin buffers against fixed-price contract volatility. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's Batam-Jakarta corridor where tax incentive zones and submarine cable landing stations attract hyperscale investment requiring rapid modular deployment. Edge computing convergence with 5G infrastructure across South Korea and Australia generates white-space demand for micro data centers with sub-12-month activation cycles. Pursue design-build contracts with integrated network engineering capabilities to capture NBN compliance-driven specifications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among EPC firms with captive O&M service arms spanning 15-20 year agreements. Long-term viability over a multi-year horizon rests on operational performance guarantees rather than construction volume exposure. Acquisition targets should display integrated civil-mechanical-electrical capabilities with established state electricity board relationships in Maharashtra and Tamil Nadu. Monitor grid interconnection queue clearance rates as the primary inflection indicator for project feasibility windows.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Partnership | Tokyo-based MEP specialists accelerate METI-compliant thermal design reviews before grid connection approval. |
| Modular Fabrication Scale-Up | Standardized module designs reduce on-site skilled labor dependence across Indonesia's dispersed island geographies. |
| Design-Build-Operate Contract Conversion | Integrated 15-20 year service agreements transfer long-term facility performance risk from hyperscale operators. |
| Renewable Energy Procurement Integration | Solar plus storage hybrids satisfy Singapore Green Plan mandates and reduce diesel backup reliance. |
| Digital Twin Platform Deployment | Virtual commissioning compresses traditional design-build cycles from months to weeks for cloud operators. |
Research Methodology
A standing panel of EPC project directors, hyperscale cloud infrastructure planners, state electricity board engineers, and MEP commissioning specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from CEA mandate documentation, METI policy filings, Uptime Institute certification records, and NBN infrastructure specifications. Bottom-up project pipeline analysis triangulated against top-down capex disclosure tracking from major cloud operators.
Scenario-bracketing around grid interconnection queue clearance rates, copper and electrical steel commodity volatility, and liquid cooling technician availability shaped projection boundaries. Segmentation dimensions modeled include construction type, deployment model, cooling technology, and power source across the analysis window. CAGRs derived from facility completion timelines, power allocation schedules, and sponsor return threshold sensitivity. Industry-specific inputs incorporated METI PUE reporting mandates and CEA coordination protocols.
Stress conditions across transformer lead times, refrigeration compressor allocation, and tier IV certification documentation throughput were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hyperscale operator land lease commitments and state-level planning authority approval timelines. Quarterly review of grid interconnection queue clearance rates and carbon disclosure rule evolution is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
Taiwan Data Center Construction Market
Infrastructure Construction
Poland Transportation Infrastructure Construction Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
China Transportation Infrastructure Construction Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
Qatar Infrastructure Sector Market
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
Norway Transportation Infrastructure Construction Market
Infrastructure Construction
United States Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Overhead Conductor Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
Philippines Data Center Construction Market