
 Sweden Transportation Infrastructure Construction Market | 2026-2036
Sweden Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Transportation Infrastructure Construction Market Analytics
Market Context
Multi-source procurement for specialized civil engineering is expanding across Sweden's public infrastructure agencies. Skanska leverages its integrated design-build capabilities to secure complex tunnel and rail packages in the Stockholm region. NCC anchors heavy civil operations through established quarries and asphalt production networks. Veidekke competes aggressively on sustainable construction credentials aligned with public tender requirements.
Technical Definition and Segment Structure
Sweden transportation infrastructure construction encompasses the engineering, materials supply, and assembly of railways, highways, bridges, and tunnels designed to withstand subarctic freeze-thaw cycles and bearing loads exceeding 25 tonnes per axle. Railway project types command the deepest capital pools as the state prioritizes electrified trunk line upgrades and urban commuter expansion. Concrete material types dominate structural applications, though steel reinforcement grades are tightening under new durability standards for coastal exposure zones. Sustainable construction methods represent the fastest-expanding category, driven by tender scoring that rewards lower embodied carbon and circular material sourcing.
Regulatory Framework and Outlook
The Swedish Transport Administration (Trafikverket) embeds climate performance requirements directly into design-build contracts, while the Swedish Environmental Protection Agency (Naturvårdsverket) enforces habitat corridor mandates that reshape route planning and seasonal construction windows. Boverket's building regulations extend to temporary works standards, forcing contractors to certify formwork and scaffolding under national structural codes. Stakeholders must monitor how the EU Green Deal's evolving embodied carbon benchmarking will recalibrate material procurement and subcontractor qualification thresholds.
Market Dynamics
Trafikverket's embodied carbon scoring system now dictates contractor qualification, compressing margins for firms unable to certify low-carbon concrete mixes and circular steel sourcing.
Growth Catalysts
- Electrified Rail Mandates:Sweden's national climate action framework requires all new trunk line investments to support 25 kV AC electrification, pulling capital toward overhead catenary and substation construction.
- Stockholm Bypass Tunneling:The Förbifart Stockholm project concentrates demand for tunnel boring machine deployment and segmental lining production in the Mälardalen corridor.
- Embodied Carbon Thresholds:Public works contracts now weight environmental product declarations at 20% of technical scoring, rewarding contractors with verified low-carbon supply chains.
Market Restraints
- Steel Reinforcement Cost Volatility:Coastal durability standards mandate stainless and micro-alloyed rebar grades exposed to Baltic Sea salt spray, exposing projects to nickel and molybdenum price swings.
- Specialized Labor Concentration:Tunnel boring machine operators and sprayed concrete technicians cluster in Stockholm and Gothenburg, constraining project ramp rates in Norrland.
- Seasonal Construction Windows:Naturvårdsverket's habitat corridor mandates restrict blasting and heavy earthwork to July through February in reindeer herding districts.
Strategic Opportunities
- Gothenburg Commuter Rail Expansion:Västra Götaland's regional transport authority plans three new underground stations, creating first-mover advantage for design-build consortia with urban tunneling experience.
- Battery-Electric Construction Equipment:Trafikverket's zero-emission site pilots create demand for electric excavators and haul trucks in rail maintenance depots.
- Cross-Laminated Timber Integration:Boverket's revised structural codes permit timber in temporary works and pedestrian bridges, opening substitution plays against concrete in non-critical applications.
Industry Challenges
- Geotechnical Risk Allocation:Design-build contracts force contractors to assume liability for unforeseen bedrock conditions in fractured gneiss formations common to Stockholm's tunnel alignments.
- EPD Verification Bottlenecks:Third-party certification of environmental product declarations for concrete and asphalt faces 14-week backlogs at accredited bodies, delaying bid submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Transportation Infrastructure Construction Market |
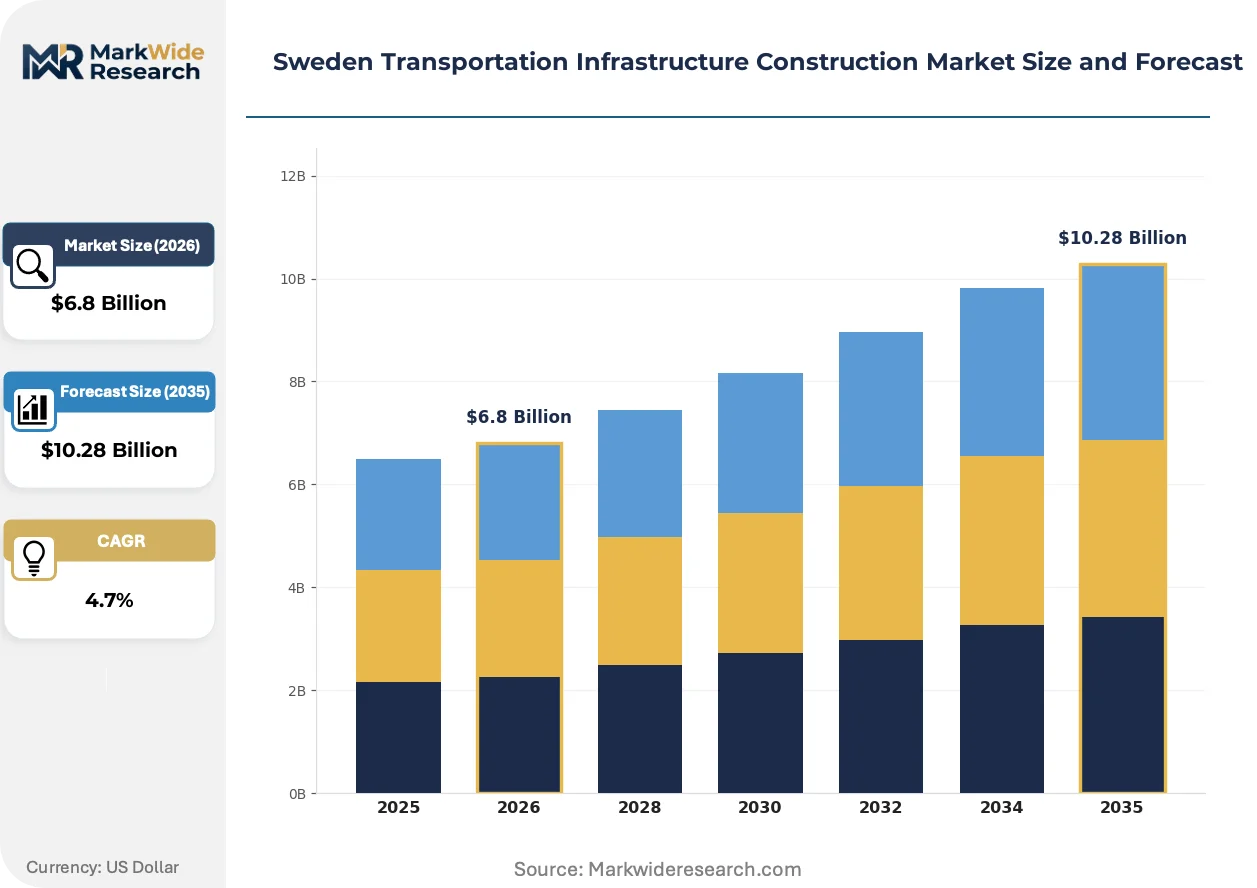
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Railway, Highway, Bridge, Tunnel Material Type: Concrete, Steel, Asphalt, Aggregate Construction Method: Traditional, Modular, Prefabricated, Sustainable End User: Government, Contractors, Private Sector, Infrastructure Funders |
| Companies Covered | Sweco AB, AF Gruppen, Skanska, Tyrens, Atkins, NCC, Ramboll Group, AECOM, Veidekke, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Transportation Infrastructure Construction Market Evolving Landscape
Digital fabrication and low-carbon material science are compressing project timelines while rewriting contractor qualification requirements across Swedish transport agencies.
Autonomous drilling jumbos are automating blasthole pattern execution in hard rock tunnels, cutting cycle times from eight to five hours per round. Skanska and NCC have deployed these systems on Stockholm metro extensions since 2023. The technology is automating shotcrete application quality control, reducing rebound waste and labor exposure in confined headings.
The EU Green Deal's evolving embodied carbon benchmarking is tightening material procurement rules for publicly funded infrastructure. Trafikverket now requires whole-life carbon assessments for steel and concrete exceeding 500 tonnes on major projects. Railway and bridge segments face the steepest compliance curves as suppliers scramble to secure EPD coverage for imported rebar and cement.
Municipal transit authorities are consolidating design-build packages into larger, multi-year frameworks that bundle maintenance obligations with initial construction. Stockholm's SL and Gothenburg's Västtrafik have shifted procurement toward 15-year performance contracts. This restructuring favors contractors with in-house asphalt production and rail maintenance divisions over pure construction specialists.
Sweden Transportation Infrastructure Construction Market Segmentation
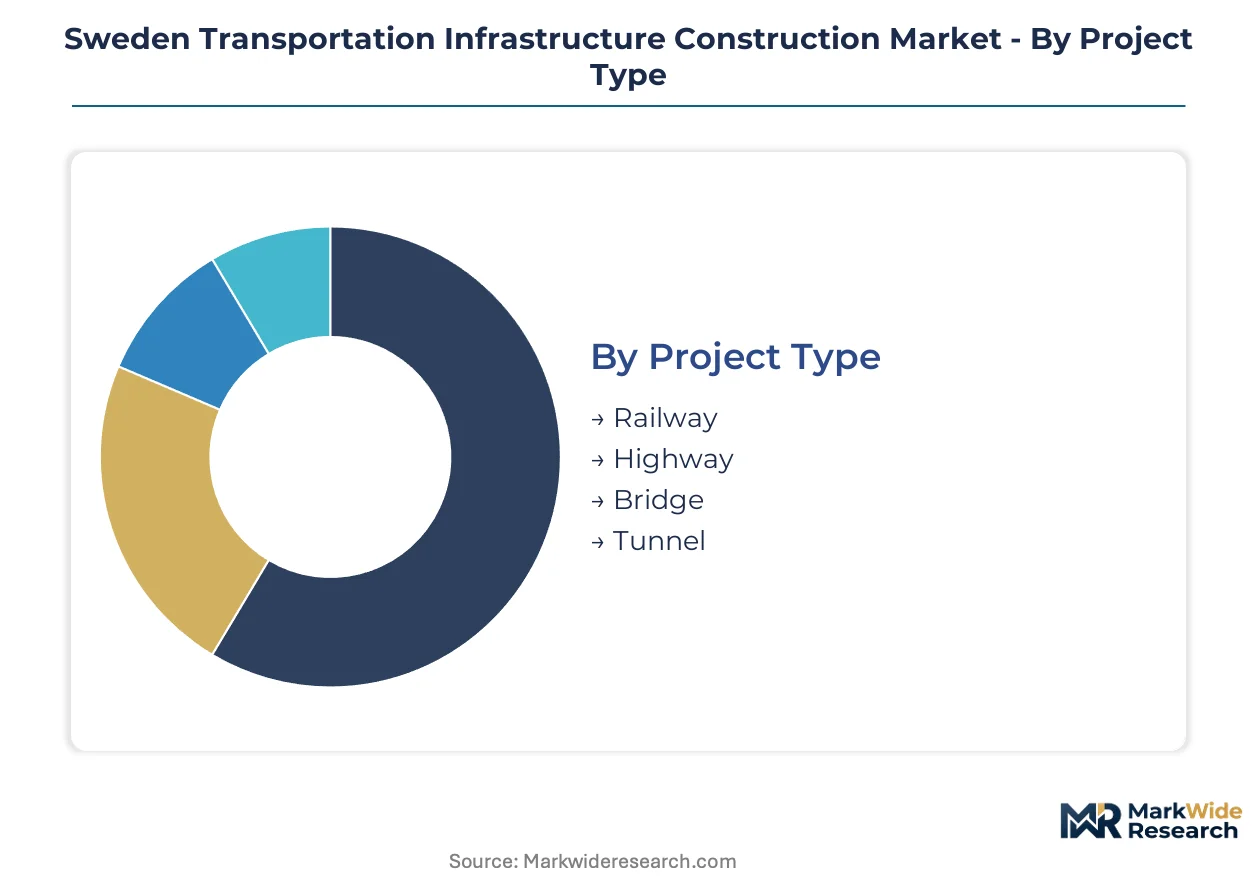
Segmentation in Sweden's transportation infrastructure construction reveals how procurement specialization, material science advances, and contracting models intersect. Each dimension shapes contractor qualification requirements and capital allocation patterns across Trafikverket's project pipeline.
Project Type:
Railway and tunnel segments operate as integrated systems demanding design-build continuity, while highways and bridges permit more fragmented procurement.
- Railway:Electrified trunk lines and urban commuter corridors absorb the deepest capital pools. Stockholm's metro extensions and Mälardalen commuter upgrades concentrate demand for 25 kV AC overhead systems and substation infrastructure. Trafikverket's climate mandates pull investment toward catenary modernization and regenerative braking infrastructure.
- Tunnel:Hard rock boring through Stockholm's fractured gneiss demands specialized TBM deployment and segmental lining production. The Förbifart Stockholm bypass anchors current demand, with Gothenburg's Västlänken extension following. Contractors assume full geotechnical risk under design-build terms.
- Highway:Road widening and intersection upgrades dominate maintenance-heavy portfolios. Regional county councils bundle resurfacing with bridge deck rehabilitation.
- Bridge:Coastal exposure zones drive stainless steel reinforcement specifications. Baltic Sea crossings face the strictest durability codes under Boverket's revised standards.
Volume placements concentrate in railway; the faster expansion belongs to tunnel.
Material Type:
Cost tier differentiation separates commodity bulk materials from performance-grade engineered products with certified low-carbon credentials.
- Concrete:Structural grades dominate foundation and tunnel lining applications. Low-carbon mix designs with slag and fly ash substitution now qualify for Trafikverket's 20% environmental scoring weight. EPD verification bottlenecks at 14 weeks constrain rapid procurement.
- Steel:Micro-alloyed and stainless rebar grades withstand coastal salt exposure under tightening durability mandates. Nickel and molybdenum price volatility compress margins on Baltic Sea bridge projects.
- Asphalt:Surface and binder courses flow through NCC's captive quarry networks. Warm-mix technologies reduce production emissions for public agency scoring.
- Aggregate:Crushed rock and sand supply clusters around established extraction permits in Mälardalen and Skåne. Transport radius economics favor local sourcing for road base and rail ballast.
Concrete commands absolute volume; steel is climbing the fastest on specification upgrades.
Construction Method:
Application context determines whether methods deploy as standalone project delivery models or embed within hybrid contracting frameworks.
- Sustainable:Whole-life carbon assessment and circular material sourcing now anchor Trafikverket's technical scoring. Battery-electric equipment pilots and timber substitution in temporary works expand qualifying project types.
- Prefabricated:Off-site bridge segment casting and modular station platforms compress on-site schedules. Factory quality control reduces weather exposure in subarctic construction windows.
- Modular:Standardized tunnel lining segments and precast culvert systems suit repetitive rural highway crossings. Design standardization limits customization for complex urban alignments.
- Traditional:Cast-in-place concrete and stick-built steel retain dominance in bespoke geometries and geotechnically uncertain conditions. Labor concentration in Stockholm and Gothenburg constrains scaling.
Traditional methods retain volume dominance; sustainable construction is gaining share fastest on tender scoring reforms.
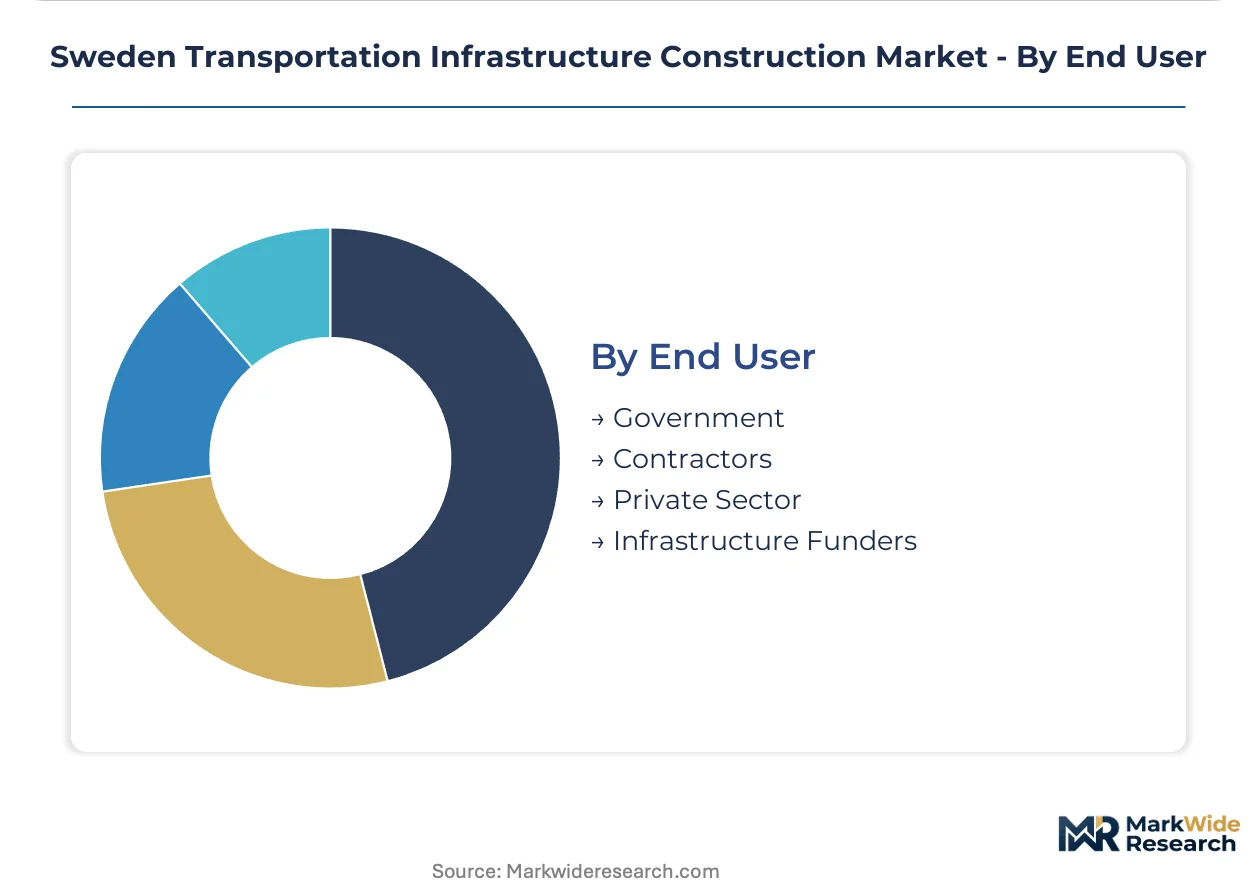
End User:
Customer type segmentation maps how risk allocation and financing structures reshape contractor relationships across public and private capital sources.
- Government:Trafikverket and municipal transit authorities anchor procurement through 15-year performance contracts. SL and Västtrafik bundle construction with maintenance obligations, favoring contractors with in-house asphalt and rail divisions.
- Contractors:Tier-one design-build consortia self-perform specialized civil work while subcontracting commodity trades. Skanska and NCC leverage integrated capabilities for complex tunnel and rail packages.
- Private Sector:Industrial logistics terminals and private port expansions operate outside Trafikverket's carbon scoring mandates. Project financing concentrates in Stockholm's port modernization.
- Infrastructure Funders:Pension capital and infrastructure debt funds back availability-payment highway concessions. Long-dated revenue streams suit institutional liability matching.
Government placements concentrate absolute volume; infrastructure funders are expanding most quickly on concession model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fractured gneiss bedrock in Stockholm's Mälardalen corridor anchors Sweden's tunneling specialization and shapes contractor qualification requirements across the national market.
Stockholm Metropolitan Region
The Förbifart Stockholm bypass and metro extensions concentrate demand for tunnel boring machines and segmental lining production. Trafikverket's embodied carbon scoring mandates 20% environmental weighting in technical tenders. SL bundles 15-year performance contracts that favor contractors with captive asphalt and rail maintenance divisions.
Gothenburg-Västra Götaland
Västlänken commuter rail and three planned underground stations pull capital toward urban tunneling expertise. The Swedish Transport Administration requires 25 kV AC electrification compatibility on all trunk line investments. Västtrafik's procurement consolidation mirrors Stockholm's shift toward multi-year design-build frameworks with maintenance obligations.
Malmö-Skåne Southern Corridor
The Öresund Bridge maintenance cycles and Fehmarn Belt fixed link preparations sustain bridge engineering demand. Boverket's coastal durability standards mandate stainless steel reinforcement for Baltic Sea exposure zones. Specialized rebar procurement faces nickel and molybdenum price volatility from concentrated supplier bases.
Norrland Northern Districts
Arctic rail upgrades and mining logistics corridors encounter Naturvårdsverket's habitat corridor restrictions. Reindeer herding districts limit blasting and heavy earthwork to July through February windows. Labor scarcity for tunnel boring machine operators constrains project ramp rates outside Stockholm and Gothenburg clusters.
Linköping-Östergötland Logistics Belt
East Coast rail freight upgrades and port modernization at Norrköping sustain civil engineering demand outside metropolitan cores. County council procurement maintains traditional maintenance-heavy portfolios for highway resurfacing and intersection upgrades. Regional asphalt supply networks favor contractors with established quarry positions in Mälardalen extraction zones.
Sweden Transportation Infrastructure Construction Market Competitive Landscape
Design-build consolidation dominates the current landscape as public agencies bundle construction with long-dated maintenance obligations. The market structures around three tiers: integrated Nordic contractors with captive material supply, international engineering consultancies anchoring technical design, and specialized tunneling consortia assembling for major hard-rock projects. Strategic archetypes include quarry-anchored heavy civil operators, carbon-credentialed sustainability leaders, and metro-specialized urban tunneling firms. Competitive moves center on 15-year performance contract pursuit and low-carbon supply chain certification.
Among Stockholm-anchored integrated contractors, Skanska, NCC, and Veidekke occupy positions shaped by Trafikverket's technical scoring reforms. Skanska exemplifies the design-build continuity archetype through tunnel and rail package integration. NCC represents quarry-anchored heavy civil operations with captive asphalt production networks. Veidekke sits within the sustainability-credentialed tier, competing on environmental product declaration coverage and circular material sourcing aligned with public tender requirements.
| Leading Market Players |
|---|
| Sweco AB |
| AF Gruppen |
| Skanska |
| Tyrens |
| Atkins |
| NCC |
| Ramboll Group |
| AECOM |
| Veidekke |
| Others |
Value Network & Pricing Analysis
Tunnel boring machine operators concentrated in Stockholm and Gothenburg command wage premiums that compress pricing spreads between premium design-build consortia and regional maintenance contractors bidding on county council highway packages.
Pricing Analysis
15-year performance contract bundling separates pricing tiers in Swedish transport infrastructure, with Trafikverket's 20% environmental scoring weight creating premium brackets for contractors certifying low-carbon concrete mixes and circular steel sourcing. Price differentiation hinges on embodied carbon verification coverage and captive asphalt production networks. Cost compression in standard highway maintenance tiers intensifies as NCC's quarry-anchored operations squeeze regional resurfacing margins. Municipal transit authorities show lowest price sensitivity on metro tunnel packages where geotechnical risk transfer dominates award criteria.
Supply Chain Analysis
Stainless steel rebar supply rests on Finnish and German specialty mills serving Baltic Sea bridge projects under Boverket's coastal durability mandates. Cement and slag feedstock draw from domestic Mälardalen kilns and Norwegian import corridors. Single-source vulnerability concentrates in micro-alloyed reinforcement grades exposed to nickel and molybdenum price swings. Distribution runs through Trafikverket's consolidated design-build frameworks that bundle segmental lining production with long-dated maintenance obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swedish transportation infrastructure construction has become a vertical-integration race where captive quarry networks and in-house rail maintenance divisions determine qualification for 15-year performance contracts.
For Market Incumbents: Lock in geotechnical risk management capabilities through specialized TBM operator training pipelines and fractured gneiss bedrock assessment protocols. Deepen backward integration into low-carbon cement sourcing to defend margin position as Trafikverket's embodied carbon thresholds tighten technical scoring weights. Carbon-credentialed competitors threaten incumbents lacking verified environmental product declaration coverage. For New Entrants and Emerging Players: Digital fabrication partnerships with autonomous drilling jumbo suppliers offer entry routes into Stockholm's metro extension pipeline. Battery-electric construction equipment pilots present the most penetrable white-space as Trafikverket's zero-emission site mandates expand beyond rail maintenance depots. Target Gothenburg's Västlänken underground station packages through urban tunneling consortium formation. For Investors and Strategic Acquirers: Re-rating potential sits with quarry-anchored mid-cap contractors given Trafikverket's procurement consolidation toward multi-year frameworks. Long-term viability over a 5-10 year horizon favors assets with captive aggregate extraction permits in Mälardalen and Skåne. Watch Naturvårdsverket's habitat corridor mandate enforcement as an inflection signal for seasonal construction window restrictions in Norrland.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Cement | Captive slag and fly ash sourcing secures Trafikverket's 20% environmental scoring advantage on major rail tenders. |
| TBM Operator Training Pipeline | Specialized labor scarcity in Stockholm and Gothenburg constrains project ramp rates for hard rock tunneling. |
| Battery-Electric Equipment Fleet Conversion | Trafikverket's zero-emission site pilots create first-mover qualification for rail maintenance depot contracts. |
| Cross-Laminated Timber Certification | Boverket's revised structural codes permit timber substitution in temporary works and pedestrian bridge applications. |
| 15-Year Performance Contract Pursuit | SL and Västtrafik bundling favors contractors with integrated asphalt production and rail maintenance divisions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with Trafikverket procurement officers, tunnel project managers at Skanska and NCC, municipal transit authority planning directors, and environmental product declaration certification bodies combined with secondary validation from Swedish Transport Administration project databases, Boverket building regulation updates, and Naturvårdsverket habitat corridor enforcement records. Bottom-up project pipeline aggregation and top-down construction sector value triangulation cross-checked volume estimates.
Segment-level modeling tracked project type, material grade, construction method, and end-user procurement structure across the projection horizon. Railway electrification mandates, tunnel boring machine deployment cycles, and embodied carbon scoring adoption curves fed analytical frameworks. CAGRs derived from weighted project commissioning schedules and maintenance obligation bundling trends.
Inputs from Trafikverket's published tender awards and municipal transit authority capital plans were available through the study window; gaps in proprietary contractor margin data and real-time steel alloy pricing introduce uncertainty bands. Forecasts reflect documented assumptions on climate mandate enforcement pacing and labor mobility constraints. A small set of triggers—Naturvårdsverket seasonal window expansions, EU Green Deal embodied carbon benchmarking revisions, and nickel-molybdenum alloy supply disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Israel Data Center Construction Market
Infrastructure Construction
Ship Port Infrastructure Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
United States Transportation Infrastructure Construction Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
Latin America Data Center Construction Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
Global Transportation Infrastructure Market