
 Qatar Infrastructure Sector Market | 2026-2036
Qatar Infrastructure Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Infrastructure Sector Market Analytics
The Qatar infrastructure sector is pivoting between premium design-build consortiums executing mega-projects and commodity-tier contractors competing on basic civil works volume. Lusail Development Company leverages its master-developer mandate to control integrated city-scale delivery. HBK Contracting Company anchors traditional road and utility segments with established local labor networks. China State Construction Engineering Corp. (CSCEC) competes on cost-engineered concrete and steel packages for stadium and transit assets.
Qatar infrastructure encompasses engineered fixed assets—transport corridors, utility networks, built structures, and energy facilities—delivered through reinforced concrete, structural steel, and asphalt composite systems designed to withstand Gulf arid-zone thermal cycling and seismic loads. The sector serves sovereign development planning, population accommodation, and hydrocarbon logistics. Transportation and Energy project types command the dominant capital allocation given North Field gas expansion and rail-metro completion timelines. Design-Build contracting is displacing traditional Design-Bid-Build for speed-to-completion on priority assets. Government funding sources retain primacy, though PPP structures are penetrating social infrastructure where operational revenue streams exist.
Ashghal, the Qatar Free Zones Authority, and Ministry of Municipality enforce building codes, environmental clearance, and contractor classification tiers that determine bid eligibility on state projects. International contractors must navigate joint-venture mandates and local content thresholds to secure licenses. Stakeholders must monitor how sovereign budget rebalancing between hydrocarbon infrastructure and diversification assets reshapes project prioritization and payment security structures.
Market Dynamics
Sovereign wealth deployment through Qatar Investment Authority is compressing project timelines and consolidating contractor tiers around design-build consortia capable of delivering integrated city-scale assets under single-point accountability.
Growth Catalysts
- North Field Expansion:Hydrocarbon logistics infrastructure is pulling capital into marine terminals, pipeline corridors, and power generation facilities. QatarEnergy's phased development creates sequential project windows.
- Ashghal Sustainable Building Codes:Green building mandates are forcing technology upgrades across concrete batching, steel fabrication, and MEP systems. Contractor requalification is filtering the supply base.
- Lusail City Master Development:Integrated district delivery is concentrating demand for smart city infrastructure, district cooling networks, and transit-oriented construction clusters.
Market Restraints
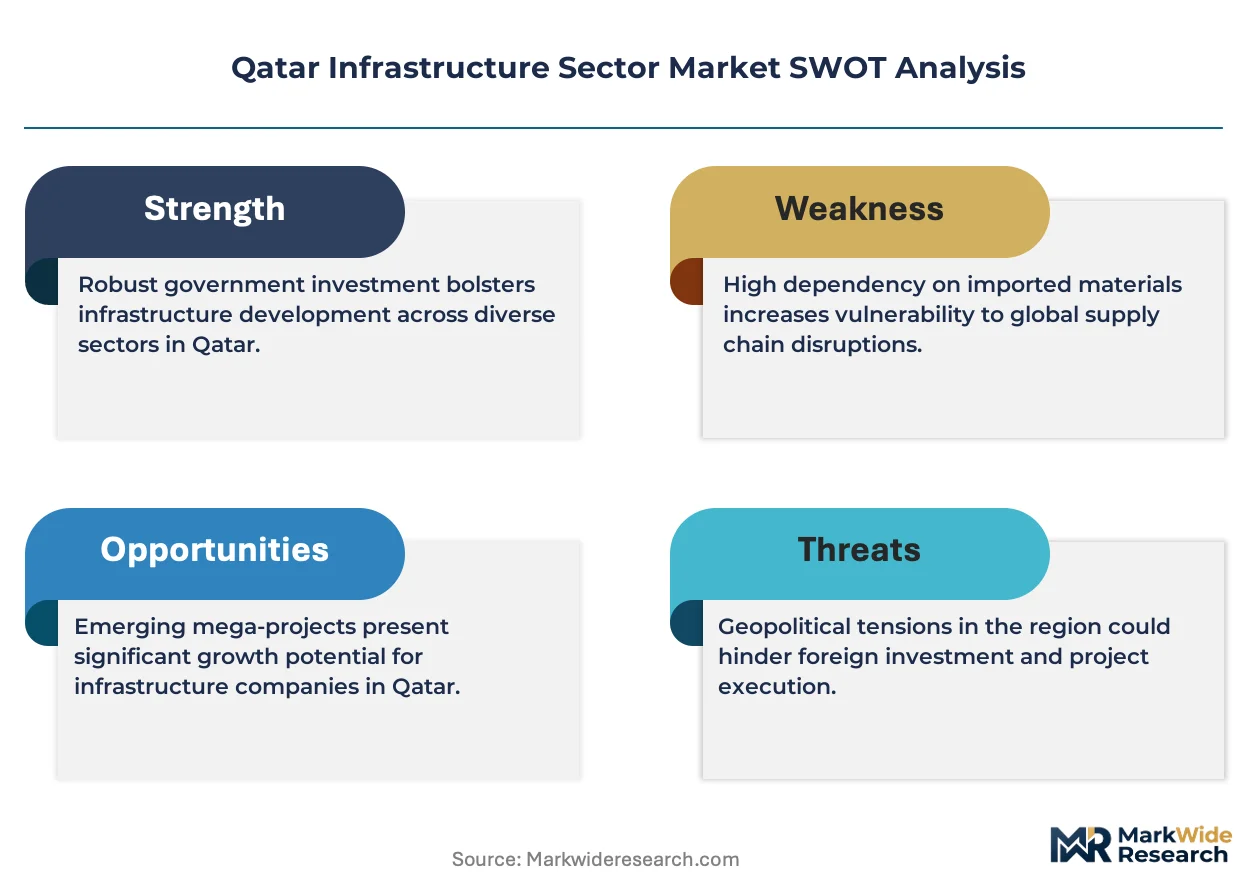
- Specialized Labor Scarcity:Qatar's kafala system reforms and nationalization targets are constraining access to experienced civil engineering and project management talent pools.
- Steel and Cement Input Volatility:Regional supply disruptions from Saudi Arabia and UAE producers are injecting cost uncertainty into fixed-price contract structures.
- Joint-Venture Mandates:Local content thresholds requiring Qatari equity participation are extending procurement cycles and complicating foreign contractor market entry.
Strategic Opportunities
- PPP Social Infrastructure:Healthcare and education assets with operational revenue streams are opening to private capital under Ministry of Finance frameworks.
- Doha Metro Corridor Extensions:Transit-oriented development zones around Gold and Green Line stations present mixed-use construction packages.
- Building Information Modeling Convergence:Digital twin integration with GIS and IoT sensor networks is enabling predictive maintenance contracts for Ashghal-managed assets.
Industry Challenges
- Gulf Standardization Delays:Divergent technical specifications between Qatar Construction Standards and GCC harmonization initiatives are forcing redundant engineering reviews.
- Payment Security Reconfiguration:Sovereign budget rebalancing between hydrocarbon and diversification projects is stretching contractor receivable cycles and bonding requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Infrastructure Sector Market |
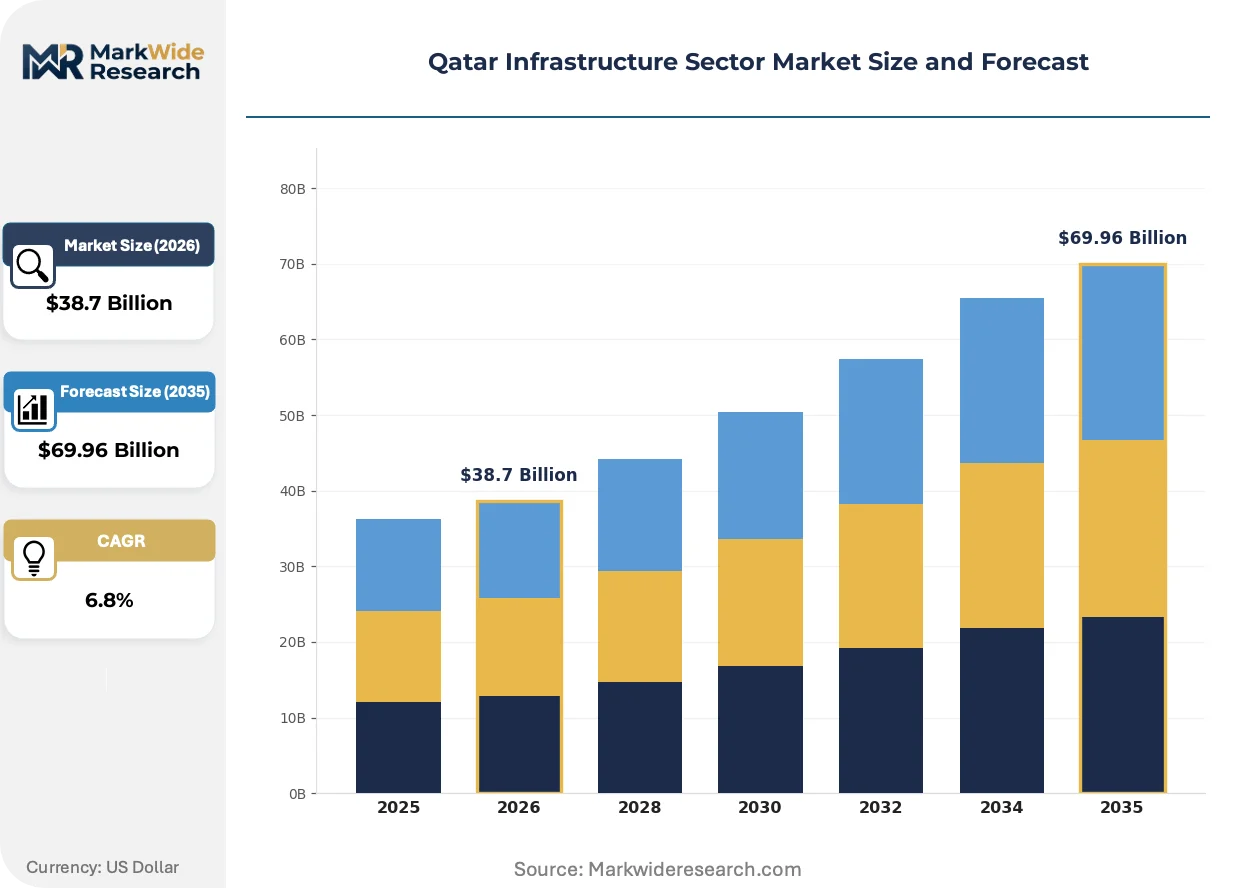
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Transportation, Energy Contracting Method: Design-Bid-Build, Design-Build, Construction Management, Joint Venture Funding Source: Government, Private Investment, PPP, International Aid Material Type: Steel, Concrete, Asphalt, Aggregates |
| Companies Covered | Lusail Development Company, Al Jaber Engineering Co., HBK Contracting Company, China State Construction Engineering Corp. (CSCEC), Consolidated Contractors Company (CCC), Qatari Diar Vinci Construction (QDVC) QSC, Arabian Construction Engineering Company, Vinci SA, Gulf Housing & Construction Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Infrastructure Sector Market Evolving Landscape
Digital delivery methods and modular construction systems are compressing traditional project timelines while Ashghal's evolving technical specifications are raising performance benchmarks across structural and MEP disciplines.
Advanced composite reinforcement systems incorporating carbon-fiber polymer matrices are replacing conventional steel rebar in marine and corrosive environments. Qatar Rail and Lusail Development Company are specifying these materials for underground and coastal assets. This substitution is unifying durability performance with accelerated construction schedules in high-chloride exposure zones.
Ashghal's updated Green Building Guidelines are mandating energy modeling and lifecycle carbon accounting for state-funded projects above specified thresholds. Contractors must now submit embodied carbon calculations alongside traditional cost proposals. Heavy civil and building segments are responding by pre-qualifying suppliers with verified Environmental Product Declarations.
Consolidated procurement through framework agreements is displacing project-by-project bidding for recurring infrastructure categories. Ashghal and Kahramaa are bundling multi-year maintenance and upgrade contracts into single-source arrangements. This concentration is most visible in road rehabilitation and substation expansion programs where repeatability favors incumbent performers.
Qatar Infrastructure Sector Market Segmentation
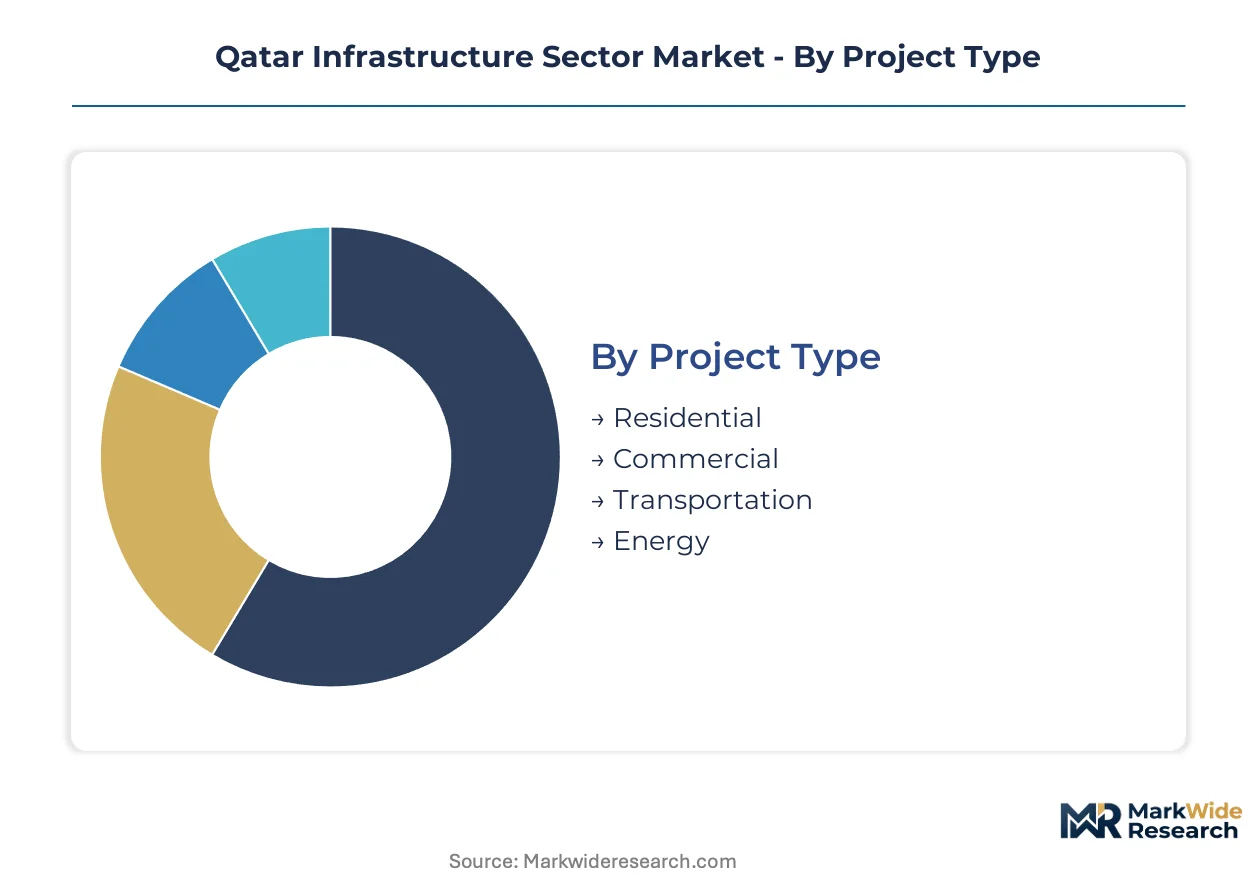
Qatar's infrastructure segmentation reflects sovereign capital deployment patterns and Ashghal's procurement centralization. Project type and contracting method classifications determine contractor qualification tiers and bid eligibility thresholds.
Project Type:
Supply concentration clusters around hydrocarbon-linked assets and transit corridors where QatarEnergy and Qatar Rail consolidate procurement authority.
- Transportation:Rail-metro systems, road networks, and marine terminals form the capital-intensive core. Doha Metro corridor extensions and Lusail City transit links concentrate demand for integrated civil-electrical-mechanical packages under single-source accountability.
- Energy:North Field expansion drives pipeline corridors, LNG terminals, and power generation facilities. QatarEnergy's phased development creates sequential project windows with specialized contractor pre-qualification requirements.
- Commercial:Mixed-use towers and retail districts in Lusail and West Bay.
- Residential:Worker accommodation and expatriate housing clusters.
Today's leader: Energy. Tomorrow's challenger: Transportation.
Contracting Method:
Cost tier differentiation separates premium design-build consortia from commodity-tier procurement for basic civil works.
- Design-Build:Single-point accountability compresses timelines for priority assets. Lusail Development Company and Ashghal mandate this method for city-scale integrated delivery where speed-to-completion outweighs initial cost optimization.
- Design-Bid-Build:Traditional sequential procurement persists for standardized road and utility maintenance where repeatability favors incumbent performers.
- Construction Management:Owner-represented oversight for complex multi-contractor coordination.
- Joint Venture:Local content compliance vehicle for foreign contractor market entry.
Design-Build captures sovereign priority projects; Joint Venture serves as the mandatory entry mechanism for international firms.
Funding Source:
Volume concentration tracks Qatar Investment Authority deployment cycles and Ministry of Finance diversification mandates.
- Government:Direct sovereign funding dominates hydrocarbon logistics and core transport networks. Ashghal and Kahramaa retain procurement control with consolidated framework agreements displacing project-by-project bidding.
- PPP:Healthcare and education assets with operational revenue streams attract private capital under Ministry of Finance structures.
- Private Investment:Lusail City commercial and residential components.
- International Aid:Limited presence in specialized technical assistance programs.
Government funding anchors current pipelines; PPP structures represent the expanding frontier for social infrastructure.
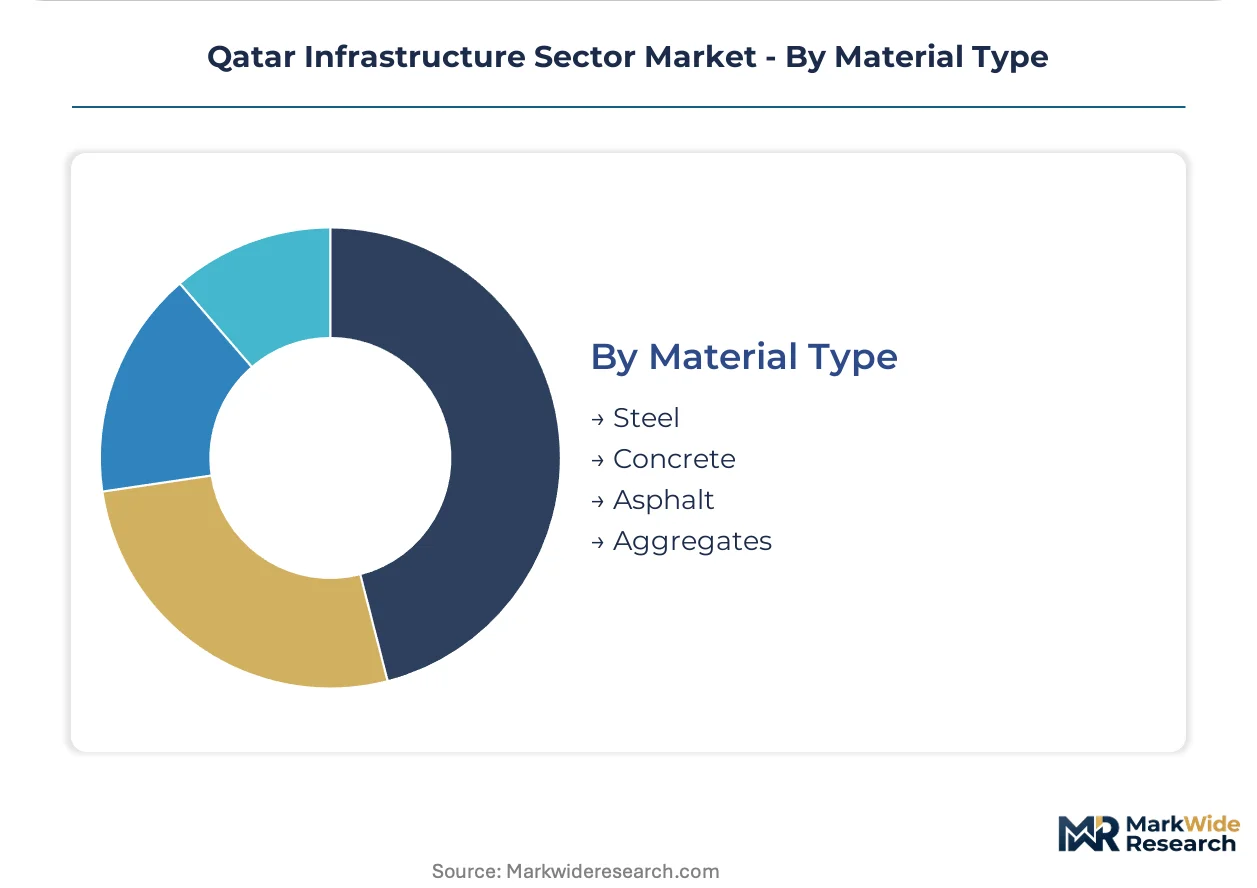
Material Type:
Application-specific specifications drive procurement bundling for reinforced concrete and structural steel in corrosive coastal environments.
- Concrete:High-performance mixes with corrosion inhibitors dominate marine and underground assets. Ashghal's Green Building Guidelines now mandate embodied carbon calculations alongside traditional cost proposals.
- Steel:Structural sections and rebar face regional supply volatility from Saudi and UAE producers. Carbon-fiber polymer matrices substitute for conventional rebar in high-chloride exposure zones specified by Qatar Rail.
- Asphalt:Road surface composites for highway and arterial networks.
- Aggregates:Crushed stone and sand for base course and concrete batching.
Concrete commands volume leadership; advanced composite reinforcement gains specification share in premium durability applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized construction labor pools concentrate in Doha and Al Wakrah, anchoring project execution capacity for hydrocarbon-linked infrastructure. These workforce clusters enable rapid mobilization for North Field expansion and Lusail City delivery timelines. Ashghal's contractor classification system filters market entry based on demonstrated local project completion.
Doha Metropolitan Area
The capital region concentrates QatarEnergy headquarters procurement and Qatar Rail corridor extensions. Ashghal's consolidated framework agreements for road rehabilitation bundle multi-year contracts here. Lusail City and West Bay districts drive mixed-use tower construction with integrated district cooling networks.
Al Wakrah Industrial Corridor
Marine terminal construction for North Field LNG expansion anchors demand in this southern zone. Kahramaa substation expansion programs concentrate procurement authority for power generation facilities. The area hosts specialized concrete batching plants serving coastal corrosion-resistant specifications.
Al Khor Northern Zone
Worker accommodation clusters and residential housing construction concentrate near North Field onshore facilities. The Ministry of Municipality enforces building codes for expatriate housing density in this sub-region. Pipeline corridor construction links hydrocarbon logistics to marine export terminals.
Umm Salal Central Belt
Utility network extensions and arterial road upgrades dominate Ashghal procurement in this intermediate zone. The area serves as a logistics bridge between Doha and northern industrial assets. Framework agreements for repeat maintenance contracts favor incumbent performers with established local labor networks.
Al Shamal Northwestern Reach
Strategic reserve infrastructure and limited coastal development characterize this frontier sub-region. Qatar Investment Authority diversification mandates are gradually extending project pipelines northward. The zone remains secondary to core hydrocarbon and metropolitan construction volumes.
Qatar Infrastructure Sector Market Competitive Landscape
Top-tier vendors anchor design-build consortia for mega-project delivery, while commodity-tier contractors compete on basic civil works volume. The market structure concentrates around sovereign-mandated master developers and state-linked construction groups with established Ashghal qualification tiers. Two strategic archetypes dominate: integrated city-scale delivery specialists and hydrocarbon logistics infrastructure fabricators. Competitive moves center on joint-venture formation for local content compliance and framework agreement capture for recurring maintenance contracts.
Within the sovereign-linked master developer tier, Lusail Development Company and Qatari Diar Vinci Construction occupy positions controlling integrated district delivery. Among established local contractors, HBK Contracting Company and Al Jaber Engineering Co. exemplify traditional road and utility segments with qualified labor networks. China State Construction Engineering Corp. represents the cost-engineered international entrant competing on concrete and steel packages for stadium and transit assets.
| Leading Market Players |
|---|
| Lusail Development Company |
| Al Jaber Engineering Co. |
| HBK Contracting Company |
| China State Construction Engineering Corp. (CSCEC) |
| Consolidated Contractors Company (CCC) |
| Qatari Diar Vinci Construction (QDVC) QSC |
| Arabian Construction Engineering Company |
| Vinci SA |
| Gulf Housing & Construction Co. |
| Others |
Value Network & Pricing Analysis
Design-build consortium premiums diverge sharply from commodity civil works bids across Qatar's infrastructure sector, compressing margins for asphalt and basic concrete contractors while reinforcing pricing power for integrated delivery specialists holding Ashghal framework agreements. This bifurcation reshapes procurement patterns as sovereign fund deployment accelerates toward single-point accountability models.
Pricing Analysis
Bundled design-build contracts command substantial premiums over unbundled design-bid-build procurement across Lusail City and North Field expansion projects. Price differentiation separates carbon-certified concrete suppliers with Environmental Product Declarations from conventional batching operations, while geographic delivery costs to Al Wakrah marine terminals add transport premiums. Pricing pressure intensifies in commodity road rehabilitation segments where Ashghal's multi-year framework agreements favor incumbent performers with established labor networks. State-linked master developers show lowest price sensitivity; tier-two contractors competing for basic utility maintenance face acute margin compression.
Supply Chain Analysis
Workforce availability constraints in Saudi Arabia and UAE steel fabrication centers are extending lead times for structural sections specified in Qatar Rail corridor projects. Raw material dependencies center on Saudi cement clinker, UAE rebar shipments, and specialized corrosion inhibitors from European chemical suppliers. Single-source vulnerability concentrates in carbon-fiber polymer matrix imports for marine environment specifications. Distribution runs through Ashghal-consolidated procurement portals for state-funded assets, with private developers maintaining direct supplier relationships for Lusail commercial components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's infrastructure sector represents a late-cycle quality story as Ashghal's Green Building Guidelines force embodied carbon accounting and advanced composite specifications, shifting procurement preference toward certified suppliers with verified Environmental Product Declarations.
For Market Incumbents: Anchor market position through captive control over high-performance concrete batching capacity in Al Wakrah and Doha metropolitan zones. Deepen backward integration into corrosion inhibitor supply chains to offset regional steel price volatility. Secure multi-year Ashghal framework renewals before qualification tiers tighten further.
For New Entrants and Emerging Players: Digital-channel pre-qualification platforms offer the most penetrable entry vector for specialized MEP and smart city technology providers lacking established Qatari joint-venture partnerships. Target Qatar Rail's Building Information Modeling convergence initiatives for predictive maintenance contracts. Pursue Ministry of Finance PPP healthcare frameworks where operational revenue streams reduce sovereign payment dependency.
For Investors and Strategic Acquirers: Consolidation pressure builds where contractor classification tiers strand mid-size civil works firms below Ashghal bid eligibility thresholds. Five-to-ten year viability favors design-build specialists with integrated city-scale delivery credentials and framework agreement capture history. Monitor Qatar Investment Authority capital rebalancing between hydrocarbon logistics and diversification assets as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Framework Agreement Capture | Ashghal's consolidated procurement bundles multi-year road rehabilitation contracts favoring incumbent performers. |
| Green Certification Investment | Environmental Product Declaration pre-qualification opens bidding on state-funded projects above carbon thresholds. |
| Joint Venture Formation | Local content compliance enables foreign contractor market entry for QatarEnergy North Field expansion packages. |
| Digital Twin Integration | Building Information Modeling convergence with GIS networks secures predictive maintenance contracts for rail assets. |
| Specialized Labor Network Development | Established kafala-compliant engineering pools accelerate mobilization for compressed sovereign project timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Ashghal procurement officers, QatarEnergy project development leads, EPC contractor bid managers, and concrete batching plant operations heads with secondary validation against Qatar Central Bank infrastructure spending disclosures, Ashghal annual reports, QatarEnergy phased development announcements, and GCC customs trade data for steel and cement flows. Bottom-up project pipeline aggregation and top-down sovereign capital deployment analysis triangulated market sizing.
Segment-weighting approaches distributed value across transportation, energy, commercial, and residential project types, with further granularity by design-build versus design-bid-build contracting methods and government versus PPP funding sources. CAGRs derived from year-over-year capital commitment trajectories and completion timeline compressions. Forecast inputs incorporated Qatar Investment Authority diversification mandate intensity and Ashghal sustainable building code implementation pace across the modeling period.
The model assumes a particular technology adoption path; alternative pathways for carbon-fiber polymer reinforcement substitution would alter the outlook for conventional steel rebar demand. Forecasts reflect documented assumptions regarding sovereign budget stability and regional material supply continuity. Practitioners should monitor QatarEnergy project window announcements and Ashghal contractor requalification bulletins for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
Steel Utility Poles Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
Concrete Canvas Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
Global Rail Infrastructure Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
Norway Transportation Infrastructure Construction Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
Taiwan Data Center Construction Market