
 Overhead Conductor Market | 2026-2036
Overhead Conductor Market Size, Share, and Industry Trends Forecast 2026-2036
Overhead Conductor Market Analysis
Utility-led procurement is unwinding toward renewable energy providers and large industrial offtakers as the fastest-growing buyer archetype. Prysmian Group leverages its European manufacturing footprint to anchor supply contracts for submarine and overhead interconnectors. Hengtong Group dominates domestic tender flows through backward integration into aluminum rod and rare-earth processing. Nexans differentiates via high-temperature low-sag conductor technology leadership in Mediterranean and North African project pipelines.
Overhead conductors are stranded aluminum or aluminum-alloy wires, often steel-reinforced, engineered to carry electrical current across open spans with specified tensile strength and thermal expansion coefficients. ACSR and AAAC variants command the largest volume positions due to their strength-to-weight ratios and corrosion resistance in long-span transmission. Copper conductors occupy premium niche positions in urban installations where space constraints and ampacity requirements justify higher material costs. The application split shows transmission lines capturing the deepest margin pools, while rural electrification programs drive volume expansion across emerging economies.
FERC and EPA standards in the United States, combined with EU Green Deal directives and REACH material compliance, shape conductor specifications and market access conditions across major economies. BIS certification and CEA technical standards govern Indian procurement, enforcing stringent testing protocols for thermal cycling and mechanical load. Stakeholders must monitor evolving national content requirements and carbon-border adjustment mechanisms as these determine competitive positioning in upcoming transmission infrastructure tenders.
Market Dynamics
Renewable energy integration is forcing transmission operators to upgrade corridor capacity faster than legacy conductor replacement cycles permit, compressing procurement timelines and elevating thermal performance specifications across tender documents.
Growth Catalysts
- EU Green Deal grid mandates:National transmission system operators must accelerate interconnector deployment to meet 2030 renewable targets, directly lifting high-temperature conductor volumes.
- Aluminum-lithium alloy adoption:Advanced metallurgy delivers 30% higher ampacity with equivalent sag characteristics, enabling reconductoring without tower replacement.
- Rural electrification corridors:India's CEA technical standards enforcement drives AAAC procurement for last-mile distribution networks spanning 400,000 villages.
Market Restraints
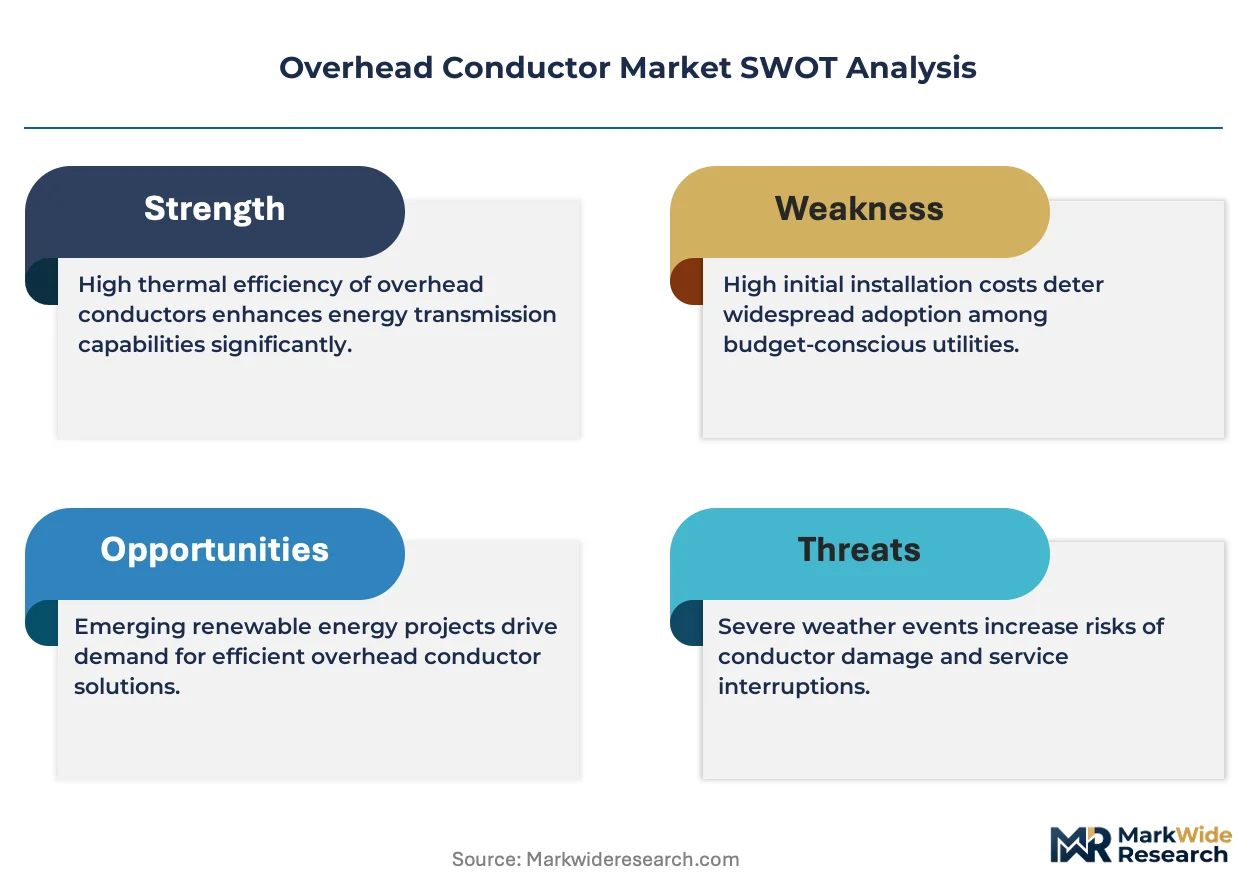
- Aluminum ingot price volatility:LME benchmark swings above 15% annually compress margin visibility for stranded wire producers locked into fixed-price transmission tenders.
- Rare-earth processing concentration:Dysprosium and terbium supply for high-performance alloys clusters in China's Jiangxi and Inner Mongolia refining complexes, creating single-source vulnerability.
- ACSR thermal ceiling:Steel-core designs face hard ampacity limits below 150°C, disqualifying them from high-density renewable export corridors without complete reconductoring.
Strategic Opportunities
- Brazil's Amazon transmission spine:Belo Monte and Madeira river hydro complexes require 800kV UHV corridors through humid rainforest, demanding corrosion-resistant aluminum-zirconium alloys.
- Carbon border adjustment mechanisms:EU CBAM phase-in from 2026 incentivizes low-carbon aluminum smelter partnerships for European conductor manufacturers.
- Drone-assisted line inspection:UAV thermal imaging integration with predictive maintenance platforms creates aftermarket service revenue streams beyond hardware supply.
Industry Challenges
- High-temperature installation protocols:ACCR and GZTACSR conductor stringing requires specialized tensioning equipment and certified crews scarce outside OECD transmission markets.
- Multi-standard certification overlap:Simultaneous IEC, ASTM, and BIS testing protocols extend product qualification timelines by 8-14 months for pan-regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Overhead Conductor Market |
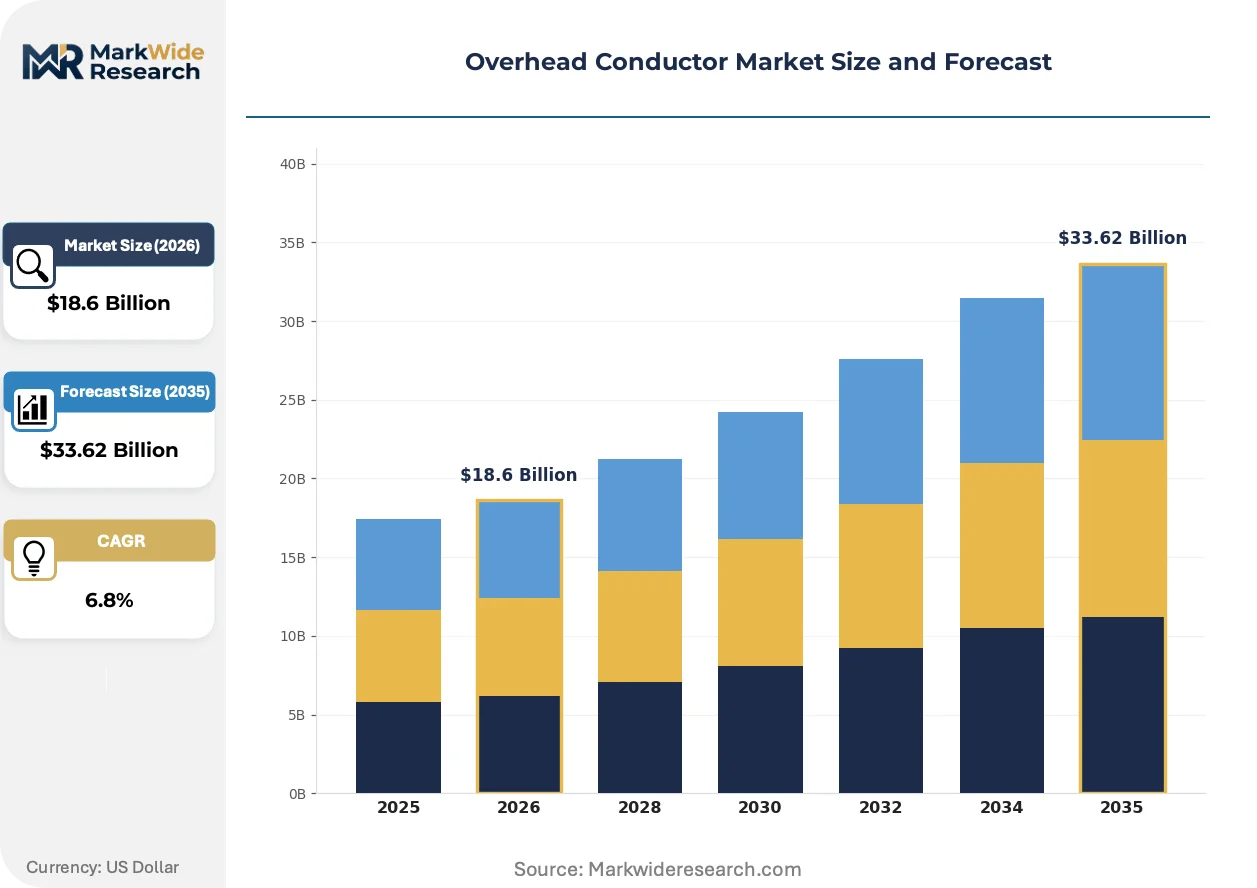
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ACSR, AAC, AAAC, Copper Application: Transmission, Distribution, Urban Installations, Rural Electrification End User: Utilities, Contractors, Industrial Plants, Renewable Energy Providers Installation Type: Overhead, Underground, Hybrid, Temporary |
| Companies Covered | Sumitomo Electric Industries, Hengtong Group, Prysmian Group, LS Cable & System, Tratos, Nexans, Midal Cables, KEI Industries, Southwire Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Overhead Conductor Market Emerging Trajectories
Material science breakthroughs and digital grid integration are redefining conductor value propositions beyond ampacity, embedding sensing capabilities and lifecycle analytics into transmission hardware specifications.
Composite core technology is decomposing the traditional steel-reinforced design paradigm. Carbon fiber and glass-fiber reinforced polymer cores from manufacturers like CTC Global deliver double the strength-to-weight ratio of galvanized steel. Transmission developers in Texas and California are specifying ACCR for 345kV renewable export lines where tower loading constraints prohibit heavier conventional conductors. This substitution is compressing total installed cost differentials between reconductoring and new-build corridors.
EU F-Gas Regulation phase-down is accelerating sulfur hexafluoride elimination from switchgear and substations adjacent to overhead lines. Grid operators must now specify conductor systems compatible with vacuum-interrupter and clean-air insulation technologies. Mediterranean interconnectors under the PCI framework are prioritizing SF6-free substation designs, affecting conductor termination and hardware selection criteria.
Asset owner procurement patterns are fragmenting toward engineering-procurement-construction consortia. Vertically integrated renewable developers like Iberdrola and Enel now bundle conductor supply into turnkey transmission packages, displacing traditional utility direct purchasing. This consolidation is most visible in offshore wind connection projects across the North Sea and Baltic Sea, where single-contractor accountability reduces interface risk.
Overhead Conductor Market Segmentation
Conductor selection dictates transmission economics across voltage classes and terrain constraints. Procurement patterns diverge sharply between legacy grid reinforcement and greenfield renewable export corridors, forcing suppliers to maintain parallel product portfolios with incompatible metallurgical specifications.
Product Type:
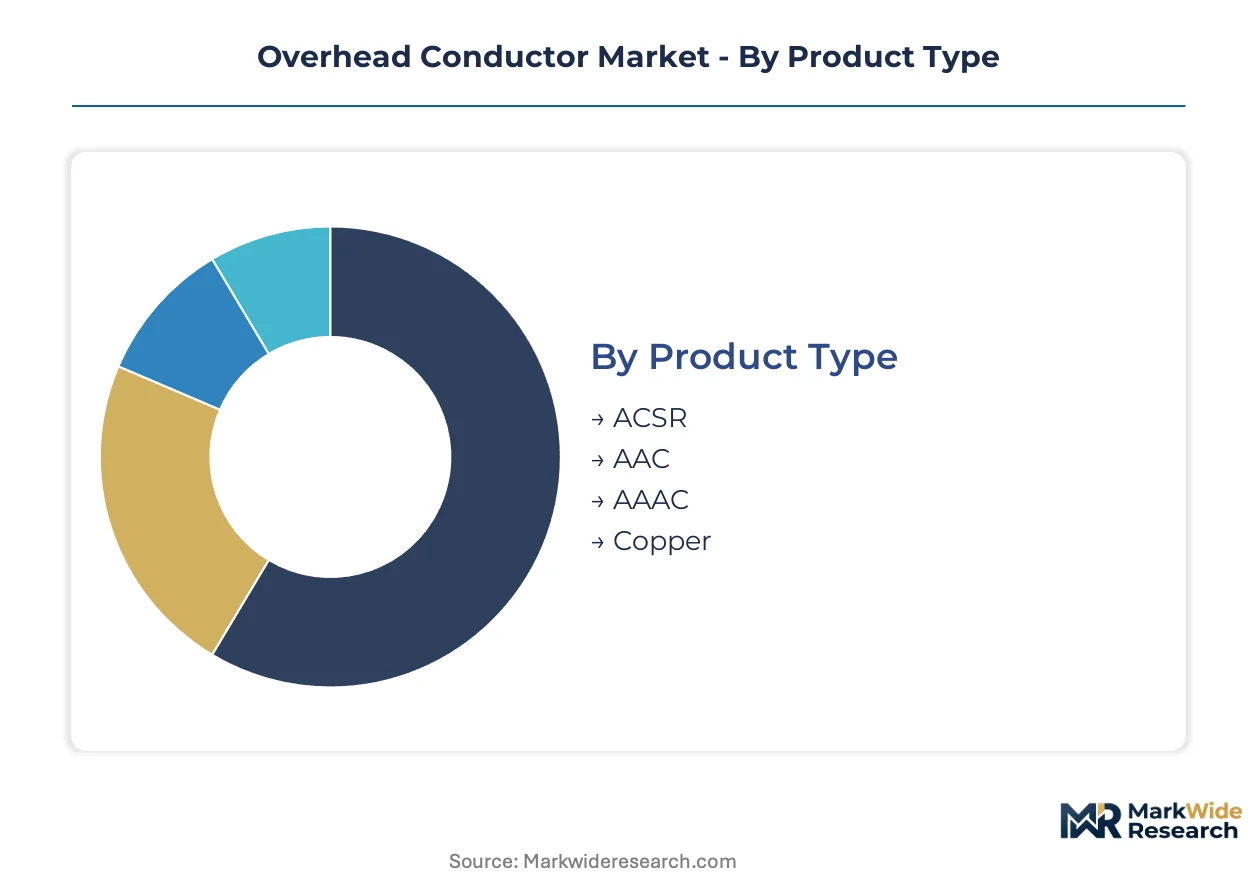
Substitution pressure concentrates in steel-reinforced designs facing displacement by composite-core alternatives with superior thermal ceilings.
- ACSR:Aluminum conductor steel-reinforced construction combines stranded aluminum outer layers with galvanized steel core wires for mechanical strength. India's CEA technical standards enforcement drives procurement for 132kV and below corridors where cost optimization outweighs ampacity gains.
- AAAC:All-aluminum alloy conductor eliminates steel cores through heat-treatable aluminum-magnesium-silicon alloys delivering equivalent sag performance at lighter weights. Brazil's Amazon transmission spine specifications favor these alloys for 800kV humid rainforest corridors where corrosion resistance outweighs first-cost premiums.
- AAC:All-aluminum conductor serves short-span distribution networks with moderate mechanical loading requirements.
- Copper:High-conductivity material occupies premium niche positions in dense urban installations with severe right-of-way constraints.
ACSR retains volume leadership; AAAC holds the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive interconnector projects from volume-driven rural electrification programs with divergent margin structures.
- Transmission:High-voltage corridor construction spanning 220kV to 800kV classes demands conductors with thermal ratings above 150°C for renewable export density. EU Green Deal grid mandates accelerate procurement timelines across North Sea and Mediterranean interconnectors.
- Rural Electrification:India's 400,000-village electrification mandate generates sustained demand for AAAC and AAC conductors in 33kV and 11kV distribution classes. CEA technical standards enforcement tightens mechanical load testing protocols for last-mile networks.
- Distribution:Medium-voltage urban and peri-urban networks balance ampacity requirements against right-of-way availability.
- Urban Installations:Space-constrained environments specify compact conductor bundles with enhanced clearances.
Transmission commands the deepest margin pools; rural electrification generates the largest unit volumes.
End User:
Customer type fragmentation is accelerating as vertically integrated renewable developers displace traditional utility procurement channels.
- Utilities:Established transmission system operators in Germany, Spain, and the United States maintain direct conductor purchasing for regulated asset base expansion. FERC standards and EU Green Deal directives shape technical specifications across their procurement documents.
- Renewable Energy Providers:Wind and solar developers in Texas, California, and offshore North Sea markets now bundle conductor supply into engineering-procurement-construction contracts. Iberdrola and Enel procurement patterns demonstrate this consolidation most visibly in submarine and overhead interconnector projects.
- Contractors:EPC consortia intermediate supply for turnkey infrastructure delivery.
- Industrial Plants:Captive generation and private wire networks specify conductors for direct grid connection.
Utilities retain the largest installed base; renewable energy providers are climbing the fastest as a procurement channel.
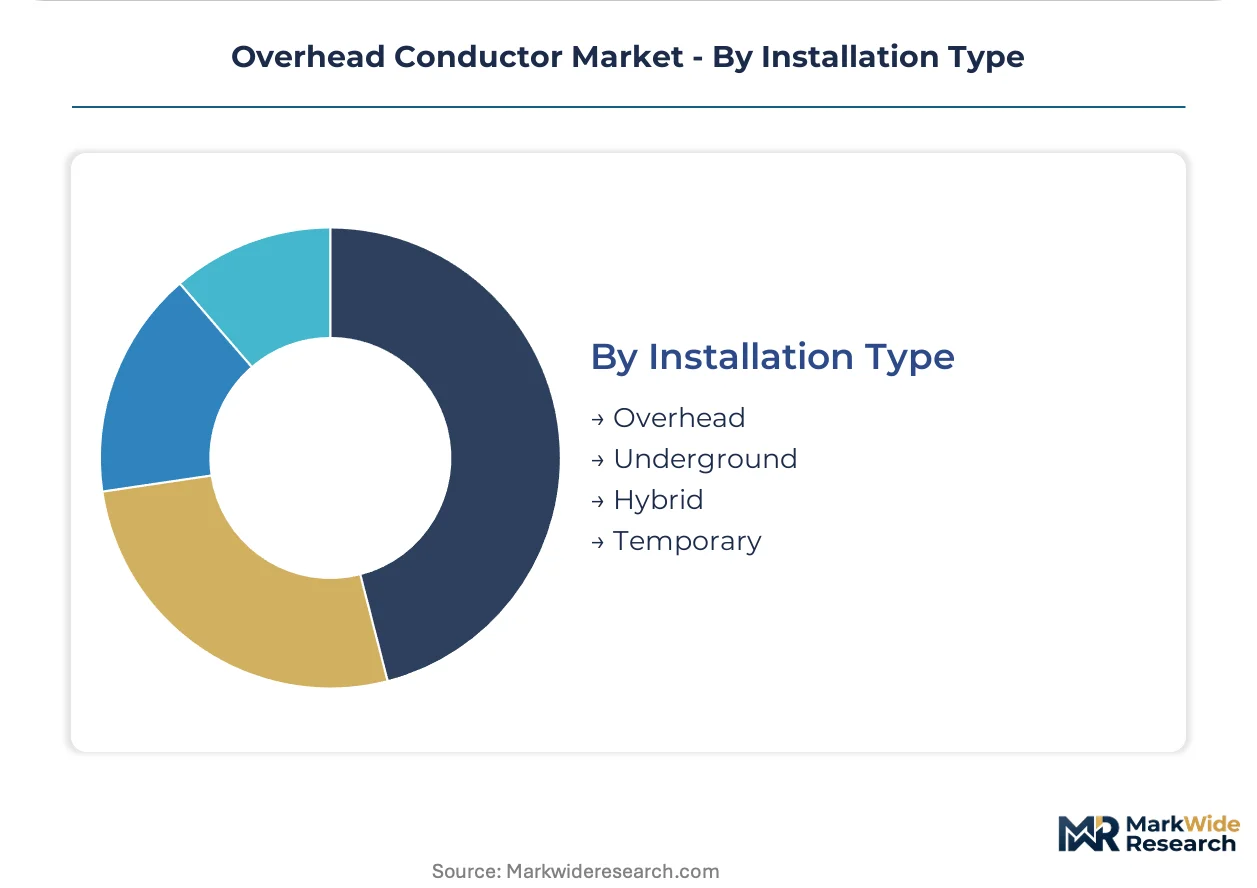
Installation Type:
Volume concentration in overhead construction masks supply chain vulnerability where specialized stringing equipment and certified crews face geographic scarcity.
- Overhead:Open-span conductor deployment dominates transmission economics across all voltage classes and terrain types. ACCR and GZTACSR conductor stringing requires specialized tensioning equipment scarce outside OECD transmission markets, compressing contractor availability for high-temperature installations.
- Underground:XLPE-insulated cable systems substitute for overhead lines in dense urban corridors and environmentally sensitive zones. EU F-Gas Regulation phase-down affects adjacent substation equipment specifications.
- Hybrid:Mixed overhead-underground routing optimizes cost and reliability for specific corridor constraints.
- Temporary:Mobile conductor systems serve construction power and emergency restoration applications.
Overhead methods retain absolute volume dominance; underground installations are gaining share fastest in urban constraint environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement concentrates in China, India, and the United States as these markets expand inter-regional transmission corridors to accommodate renewable generation zones. Renewable energy providers are accelerating procurement of high-capacity transmission conductors across all three markets. Grid modernization mandates under the EU Green Deal and similar national frameworks are tightening material standards and thermal performance requirements.
China
State Grid Corporation drives demand for 800kV UHV corridors connecting western renewable bases to eastern load centers. MIIT and GB standards enforce stringent thermal cycling protocols for conductor qualification. Jiangxi and Inner Mongolia refining complexes control rare-earth processing for high-performance alloys.
India
Power Grid Corporation and state utilities execute CEA-mandated rural electrification across 400,000 villages requiring AAAC and AAC conductors. BIS certification and CEA technical standards govern procurement with strict mechanical load testing. Gujarat and Maharashtra industrial clusters host domestic aluminum rod and conductor manufacturing capacity.
United States
ERCOT and CAISO transmission operators specify ACCR conductors for 345kV renewable export lines in Texas and California. FERC standards and EPA environmental compliance shape technical specifications and market access. Southeast manufacturing corridors supply stranded wire for utility direct purchasing programs.
Germany
TenneT and 50Hertz accelerate North Sea offshore wind interconnectors under EU Green Deal 2030 renewable targets. REACH material compliance and EU F-Gas Regulation phase-down affect conductor termination specifications. Bavaria and North Rhine-Westphalia host Prysmian and Nexans European manufacturing footprints.
Brazil
Eletrobras and private transmission concessionaires deploy corrosion-resistant aluminum-zirconium alloys for Amazon basin 800kV corridors. ANVISA and national grid codes enforce environmental and technical standards for humid rainforest installations. Belo Monte and Madeira river hydro complexes anchor demand in the northern transmission spine.
Overhead Conductor Market Vendor Landscape
Player mix skews toward integrated cable-conductor conglomerates with metallurgical backward integration and regional specialists with certification depth. The vendor base concentrates around three strategic archetypes: European engineering-procurement-construction bundlers, Chinese state-linked aluminum-smelter hybrids, and Japanese-Korean precision metallurgy houses. Consolidation pressure intensifies through capacity expansion in high-temperature composite core segments and strategic partnerships for rare-earth alloy supply security.
Within the integrated conglomerate tier, Prysmian Group and Nexans occupy positions exemplifying European high-temperature low-sag technology leadership. Hengtong Group represents the Chinese state-linked archetype with captive aluminum rod and rare-earth processing capabilities. These three anchors illustrate the competitive divergence between engineering-procurement-construction bundling and upstream metallurgical control.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| Hengtong Group |
| Prysmian Group |
| LS Cable & System |
| Tratos |
| Nexans |
| Midal Cables |
| KEI Industries |
| Southwire Company |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with aluminum ingot indexation lock in supply access and margin visibility for stranded wire producers serving transmission tenders under FERC and EU Green Deal mandates. These structures transfer LME volatility risk to buyers while securing smelter partnerships for high-temperature alloy feedstock.
Pricing Analysis
Cost-plus contracts with LME aluminum indexation dominate procurement for ACSR and AAAC volumes, with price differentiation separating IEC-certified high-temperature conductors from standard CEA-compliant distribution grades. Premium-mid-economy pricing differentiation rests on thermal ceiling ratings and composite core technology tiers. Pricing pressure stems from fixed-price tender exposure to ingot volatility, with rural electrification programs in India showing highest price sensitivity and North Sea interconnector projects demonstrating lowest.
Supply Chain Analysis
Strategic stockpiling of aluminum rod and rare-earth alloys prevails over just-in-time approaches given Jiangxi and Inner Mongolia processing concentration for dysprosium and terbium feedstocks. China, India, and Germany anchor manufacturing capacity, drawing from bauxite refining and aluminum smelting inputs. Single-source vulnerability in rare-earth processing creates structural risk. Distribution runs through utility direct purchasing and EPC consortium bundling channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite core substitution threatens steel-reinforced incumbents, forcing defensive repositioning around thermal performance certification and metallurgical backward integration.
For Market Incumbents: Shield core product lines by deepening captive aluminum alloy production in India and Brazil to offset rare-earth supply concentration. Secure IEC and BIS certification for ACCR stringing protocols before composite core competitors establish crew training networks. The threat of carbon fiber core displacement demands preemptive high-temperature low-sag technology investment.
For New Entrants and Emerging Players: Lead with drone-assisted thermal inspection services bundled with conductor supply to penetrate the aftermarket maintenance gap in North American utility markets. Target Texas and California renewable export corridors where ACCR installation crew scarcity creates white-space for certified EPC partnerships. The most penetrable segment lies in predictive maintenance platform integration.
For Investors and Strategic Acquirers: Regional specialists with CEA and BIS certification depth present acquisition targets given their irreplaceable position in Indian rural electrification procurement. Long-term viability hinges on exposure to EU Green Deal interconnector pipelines versus commodity-tied distribution volumes. Watch for aluminum-lithium alloy qualification timelines as inflection signals for technology leadership shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rod | Captive smelter partnerships in Gujarat and Inner Mongolia secure feedstock against LME volatility. |
| High-Temperature Conductor Certification | IEC and BIS qualification for ACCR stringing opens EU Green Deal and Indian transmission tenders. |
| Drone-Assisted Line Inspection | UAV thermal imaging integration with predictive platforms creates recurring service revenue beyond hardware. |
| Rare-Earth Alloy Supply Partnership | Long-term offtake with Jiangxi processors mitigates single-source vulnerability for dysprosium-dependent alloys. |
| Carbon Border Adjustment Compliance | Low-carbon aluminum sourcing positions European manufacturers for EU CBAM phase-in from 2026. |
Methodological Framework
A spread of perspectives from transmission planning officers at State Grid and Power Grid Corporation, procurement leads at Iberdrola and Enel, EPC contractors in Texas and North Sea markets, and metallurgical R&D directors at Prysmian and Hengtong converged on the working assumptions. These primary insights combined with secondary validation from FERC filings, CEA technical standards documentation, EU Green Deal directive texts, and aluminum trade flow data. Bottom-up project pipeline assessment and top-down regulatory mandate analysis triangulated volume estimates.
Product type, application voltage class, end-user archetype, and installation method dimensions structured the analytical framework across the projection horizon. CAGRs derived from regression against renewable capacity deployment trajectories and grid modernization spend patterns. Forecast inputs incorporated aluminum ingot price scenarios and rare-earth supply disruption probabilities.
Underlying assumptions cover sustained EU Green Deal implementation, CEA rural electrification enforcement, and LME aluminum price bands, with deviation risk concentrated in rare-earth export restrictions and composite core technology adoption curves. Revision becomes warranted when carbon fiber core cost parity crosses thresholds or when national content requirements shift procurement eligibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Qatar Infrastructure Sector Market
Infrastructure Construction
Ship Port Infrastructure Market
Infrastructure Construction
France Transportation Infrastructure Construction Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
Steel Utility Poles Market
Infrastructure Construction
Singapore Transportation Infrastructure Construction Market
Infrastructure Construction
Poland Transportation Infrastructure Construction Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
Finland Transportation Infrastructure Construction Market
Infrastructure Construction
Gas Pipeline Infrastructure Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market