
 Africa Pipeline Construction Market | 2026-2036
Africa Pipeline Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Pipeline Construction Market Analytics
Nigeria's Escravos-Lagos pipeline expansion is rewriting regional gas distribution economics. China Communications Construction Group Ltd. leverages its port and marine engineering expertise to dominate coastal pipeline landings. Dangote Group anchors downstream connectivity through its integrated refinery-pipeline complex near Lagos. Republic of Mozambique Pipeline Investments Company specializes in cross-border gas transmission, sustaining its position along the Maputo corridor.
Africa pipeline construction encompasses the engineering, fabrication, and installation of tubular conduit systems for hydrocarbon and utility transport, typically employing API 5L-grade steel with diameters ranging from 4 to 48 inches and operating pressures up to 1440 psi. These networks serve primary industrial functions including crude oil gathering, natural gas transmission, refined product distribution, and water conveyance across vast sub-Saharan distances. Steel pipelines occupy the dominant material position due to structural integrity requirements for high-pressure hydrocarbon service, while horizontal directional drilling is gaining share in environmentally sensitive terrain and densely populated urban crossings. Distribution projects linked to city gas networks represent the fastest-growing project type as municipal utilities expand access.
Nigeria's Department of Petroleum Resources, South Africa's Petroleum Agency SA, and Mozambique's National Petroleum Institute each enforce welding qualification standards, environmental impact assessments, and right-of-way compensation frameworks that directly shape project timelines and contractor eligibility. The African Petroleum Producers Organization coordinates regional pipeline safety protocols, though implementation remains uneven across member states. Stakeholders must monitor how divergent national content requirements and local procurement thresholds affect cross-border project economics and contractor selection.
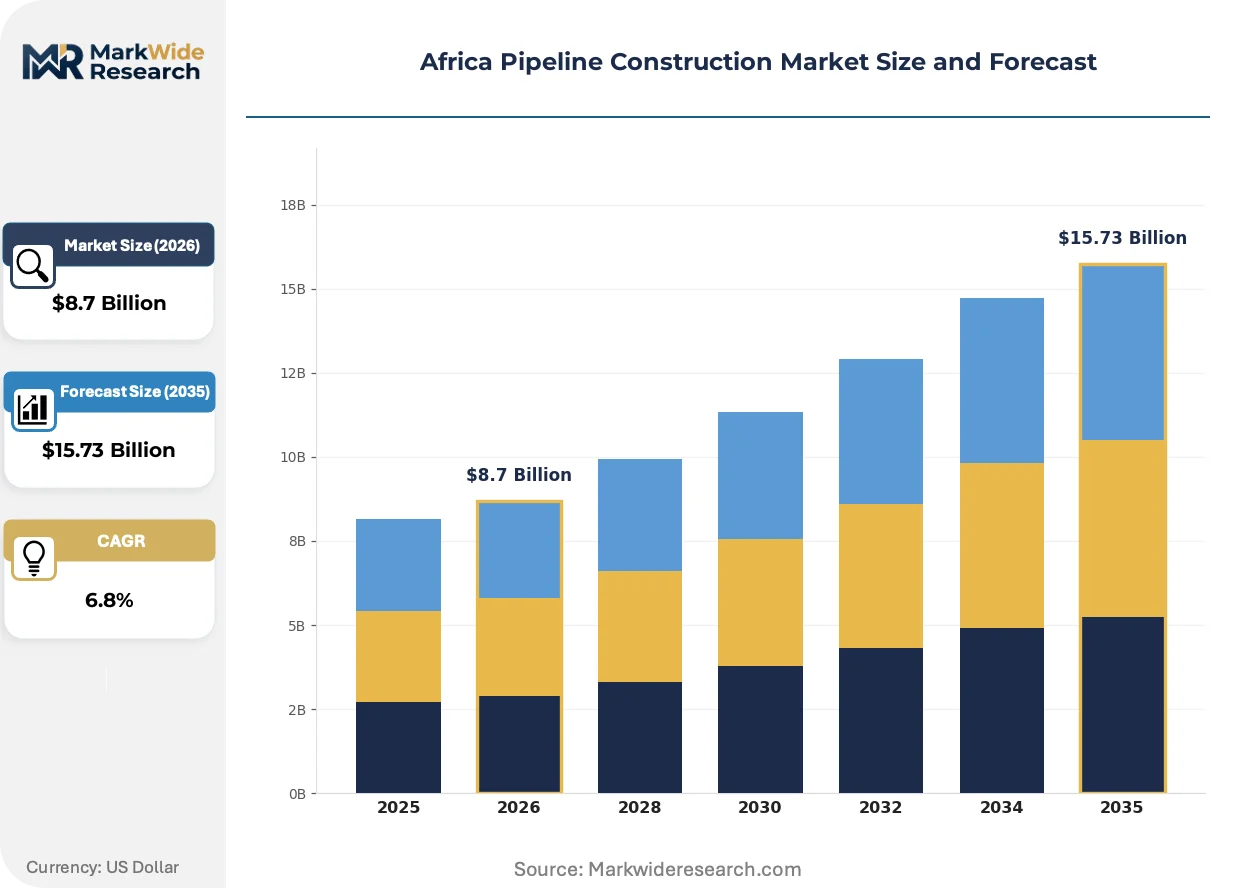
Market Dynamics
Horizontal directional drilling is compressing project timelines for environmentally sensitive crossings, while national regulators in Nigeria, South Africa, and Mozambique impose divergent welding qualification standards that fragment contractor eligibility across borders.
Growth Catalysts
- East African LNG corridors:Tanzania and Mozambique are developing pipeline networks to monetize offshore gas discoveries, pulling investment into midstream infrastructure.
- Nigeria's DPR welding protocols:Tighter qualification standards are professionalizing contractor pools and reducing failure rates on high-pressure lines.
- City gas distribution mandates:Municipal utilities across sub-Saharan capitals are expanding access networks, creating demand for smaller-diameter distribution pipelines.
Market Restraints
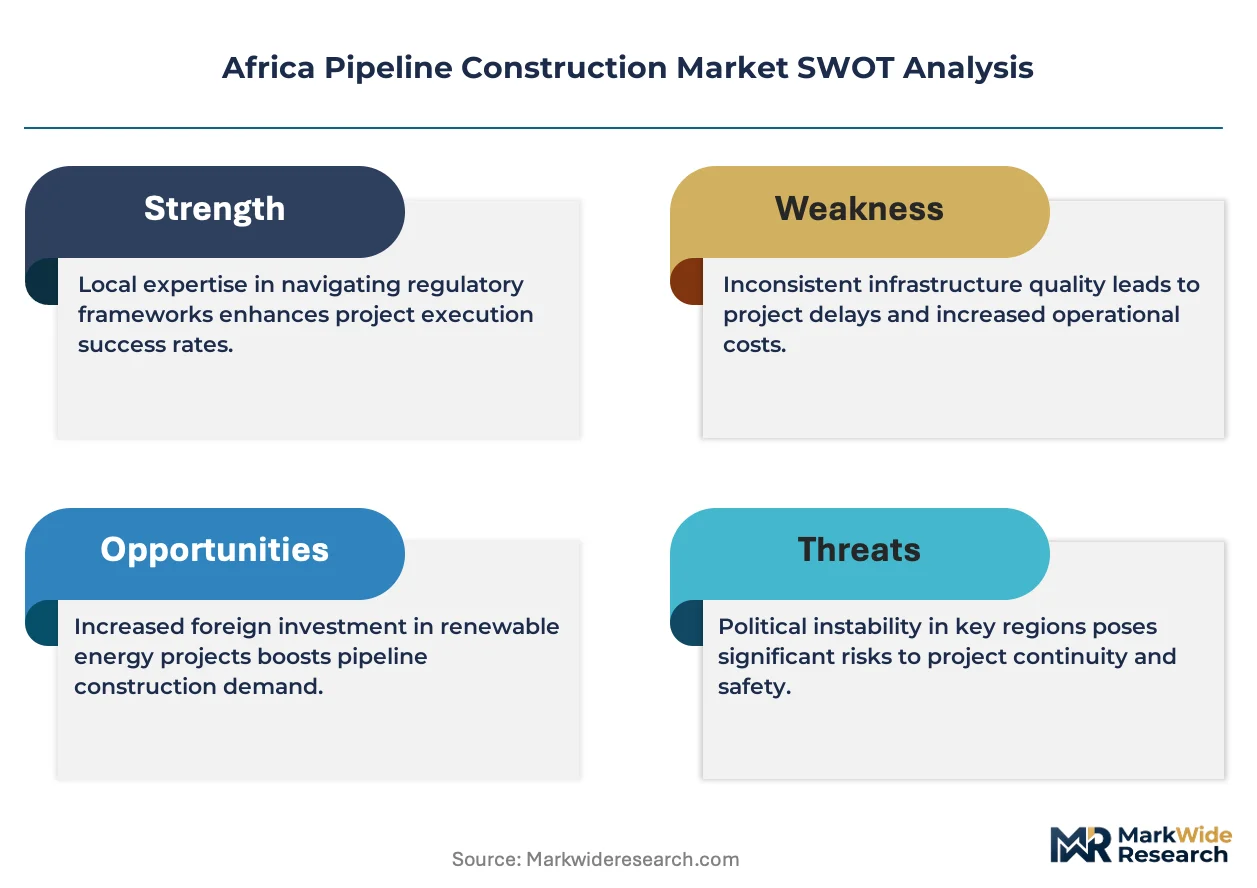
- API 5L steel price volatility:Fluctuations in alloy inputs compress margins for EPC contractors locked into fixed-price contracts.
- Specialized welding labor concentration:Certified technicians cluster in South Africa and Nigeria, creating bottlenecks for projects in landlocked jurisdictions.
- Right-of-way compensation disputes:Mozambique's INP framework for land acquisition triggers delays on cross-border corridors.
Strategic Opportunities
- Ethiopia's underpenetrated transmission grid:The absence of legacy infrastructure creates first-mover advantages for integrated pipeline-power projects.
- Water-energy nexus applications:Desalination-linked pipelines for mining operations in Namibia and Botswana open non-hydrocarbon revenue streams.
- APP regional safety coordination:The African Petroleum Producers Organization's harmonized protocols reduce compliance duplication for multi-country operators.
Industry Challenges
- ASME Section IX certification timelines:Qualification bottlenecks for exotic material welding delay mobilization on sour gas projects.
- Legacy gathering system integration:New high-pressure lines must interface with decades-old infrastructure lacking digital monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Pipeline Construction Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Transmission, Distribution, Gathering, Others Material: Steel, Plastic, Composite, Ductile Iron End User: Oil & Gas Companies, Government Agencies, Industrial Sectors, Utility Providers Installation Method: Trenching, Horizontal Directional Drilling, Open Cut, Others |
| Companies Covered | China Communications Construction Group Ltd., China Railway Construction Corporation Ltd., Vinci SA, Dangote Group, Bouygues SA, Republic of Mozambique Pipeline Investments Company, West African Gas Pipeline Company, TotalEnergies, Sinopec, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Pipeline Construction Market Evolving Landscape
Automation is penetrating fabrication yards and welding stations, while composite material trials and digital twin deployment are reshaping how operators manage integrity across vast sub-Saharan distances.
Composite reinforced thermoplastic pipe is hybridizing with conventional steel for low-pressure gathering lines in corrosive environments. IOCs operating in Nigeria's Niger Delta are piloting spoolable systems for marginal field tie-ins. This technology is hybridizing project economics by cutting installation crews and eliminating coating yards.
Nigeria's Department of Petroleum Resources has mandated inline inspection verification for all new transmission lines above 24-inch diameter. The rule forces contractors to pre-negotiate pigging agreements before construction commences. Offshore gathering systems face the steepest compliance cost escalation.
Asset operators are unbundling integrity management from EPC contracts, creating standalone decade-long service agreements. This procurement split favors specialized inspection firms over traditional construction houses. Angola's offshore developments exhibit the most advanced contracting sophistication.
Africa Pipeline Construction Market Segmentation
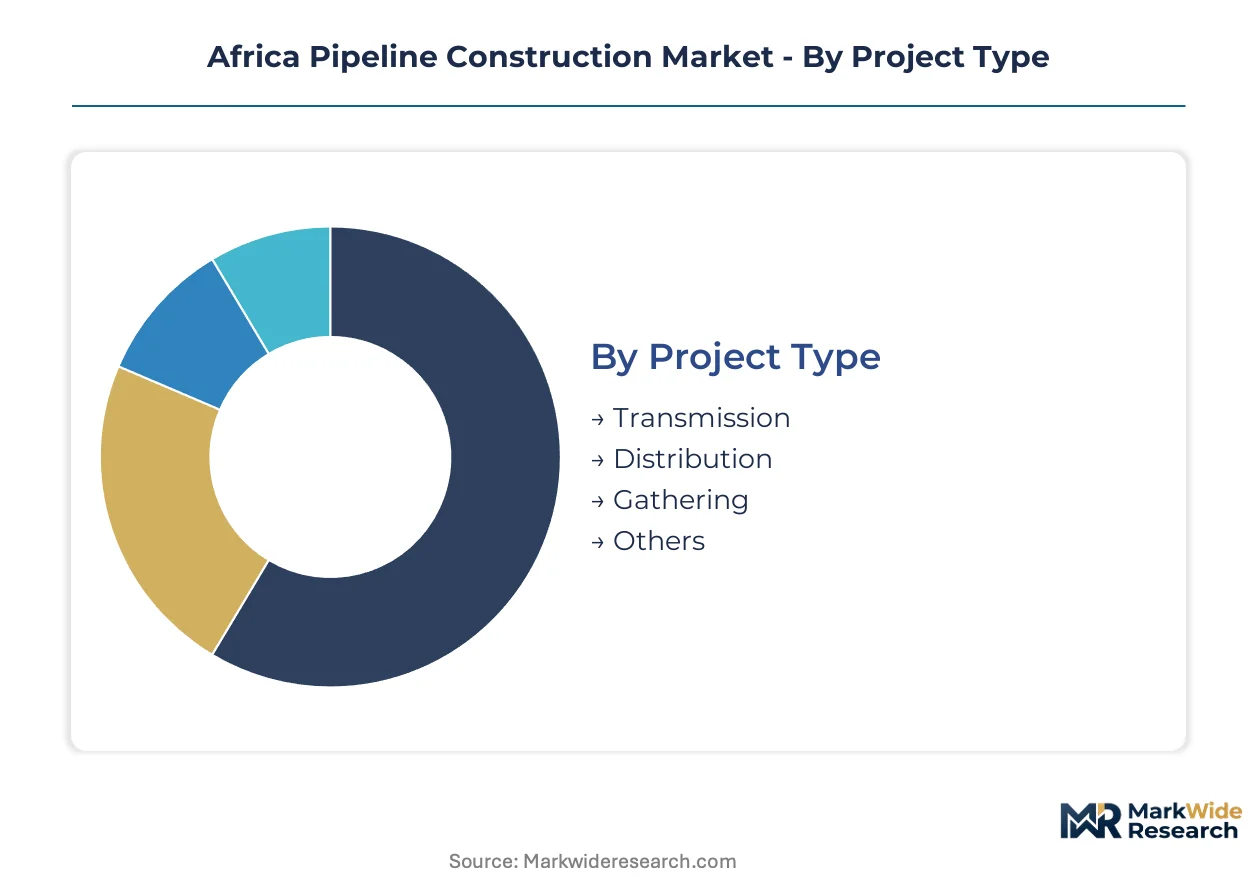
Pipeline construction across Africa demands granular segmentation to capture divergent technical specifications, regulatory environments, and investment cycles that distinguish high-pressure transmission corridors from municipal distribution networks. Each dimension—project scale, material selection, end-use application, and installation methodology—carries distinct procurement patterns and contractor qualification thresholds that reshape competitive positioning.
Project Type:
Project scale spans from continent-spanning trunk lines to localized gathering systems, with each tier commanding different welding protocols, environmental scrutiny, and financing structures.
- Transmission:High-pressure steel arteries typically exceeding 24-inch diameter connect production basins to coastal export terminals or cross-border interconnections. Nigeria's Escravos-Lagos expansion and Mozambique's Maputo corridor anchor regional demand, though right-of-way compensation disputes and multi-jurisdictional permitting compress contractor margins.
- Distribution:Medium-pressure networks branch from transmission hubs to industrial offtakers and city gate stations, with sub-Saharan capitals expanding municipal access programs. Tanzania's Dar es Salaam distribution ring and Angola's Luanda network drive procurement of smaller-diameter API 5L grades, while national content requirements fragment contractor eligibility.
- Gathering:Low-pressure collection systems aggregate flow from marginal fields and well pads, often employing flexible composite solutions in Nigeria's Niger Delta swamp terrain.
- Others:Specialized categories include refinery feedstock lines, LNG plant interconnects, and water-energy nexus infrastructure for mining operations.
Established volume favors Transmission; emerging adoption favors Distribution.
Material:
Material selection pivots on pressure rating, corrosivity, and installation constraints, with cost tier and performance requirements dicting procurement splits across project portfolios.
- Steel:API 5L-grade carbon and alloy steels dominate high-pressure hydrocarbon service, offering structural integrity for pressures up to 1440 psi across vast sub-Saharan distances. Nigerian Department of Petroleum Resources mandates inline inspection compatibility for all steel transmission lines above 24-inch diameter, forcing pre-negotiated pigging agreements.
- Composite:Reinforced thermoplastic pipe is hybridizing with conventional steel for low-pressure gathering in corrosive Niger Delta environments, cutting installation crews and eliminating coating yards through spoolable deployment.
- Plastic:Polyethylene and PVC variants serve low-pressure water conveyance and rural gas distribution where flexibility and corrosion immunity outweigh pressure requirements.
- Ductile Iron:Municipal water transmission in South Africa and North African jurisdictions employs centrifugally cast iron for buried pressure mains.
Steel commands procurement value; composite materials are climbing the fastest in marginal field applications.
End User:
Customer type determines risk allocation, contract duration, and technical specification stringency, with international oil companies imposing distinct qualification regimes from state utilities.
- Oil & Gas Companies:Integrated majors and independents drive frontier developments in Mozambique's Rovuma Basin and Angola's offshore blocks, bundling pipeline construction with production sharing contract obligations. These operators unbundle integrity management from EPC contracts, favoring decade-long service agreements with specialized inspection firms.
- Government Agencies:State petroleum corporations and infrastructure ministries anchor cross-border corridors, though procurement delays and local content thresholds extend project timelines.
- Industrial Sectors:Mining conglomerates in Namibia and Botswana procure desalination-linked pipelines, creating non-hydrocarbon revenue streams for contractors.
- Utility Providers:Municipal gas distribution companies in sub-Saharan capitals expand residential access networks, generating demand for standardized, repeatable installation methodologies.
International oil companies concentrate project value; utility providers are expanding most quickly across city gas mandates.
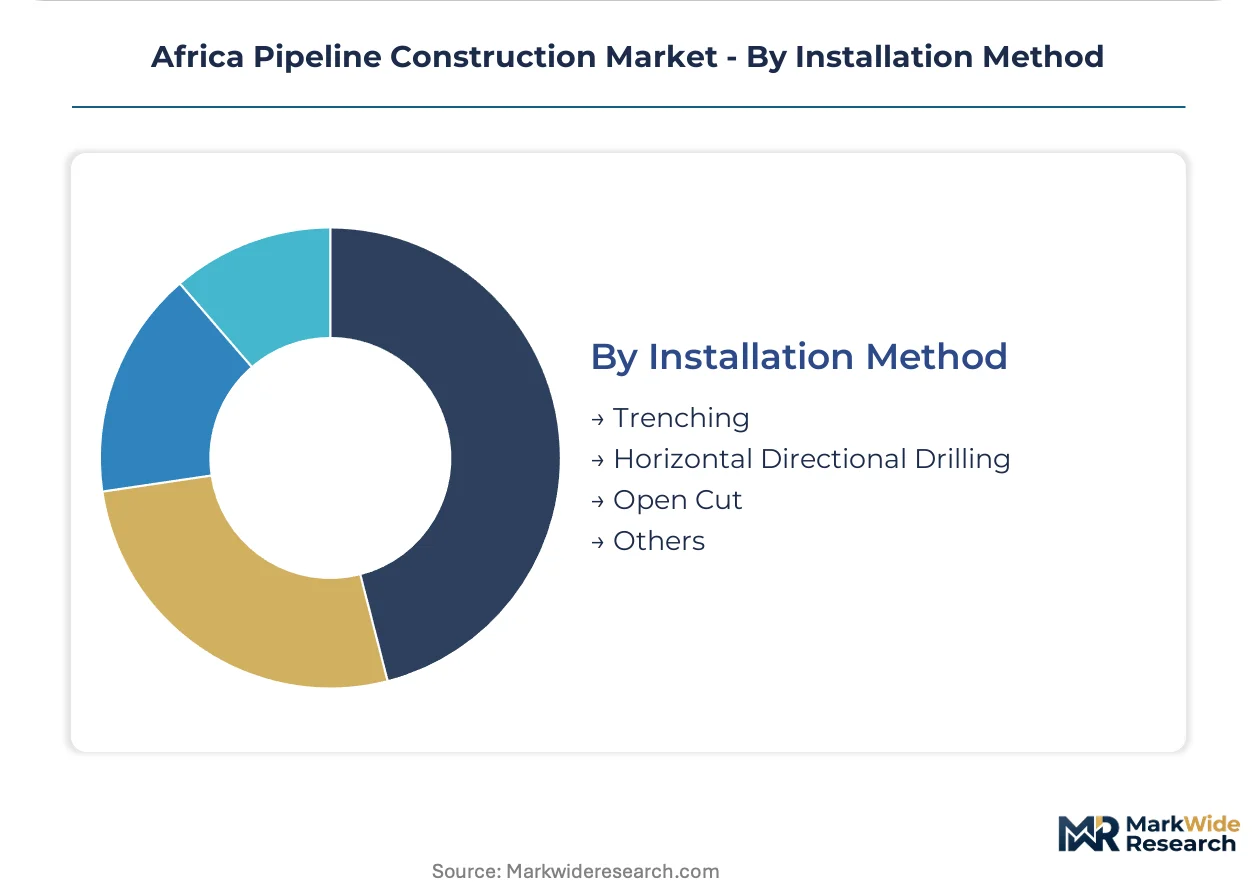
Installation Method:
Construction technique selection balances terrain sensitivity, population density, and schedule pressure, with environmental compliance costs reshaping method economics.
- Horizontal Directional Drilling:Trenchless technology compresses timelines for environmentally sensitive river crossings and densely populated urban corridors, though specialized equipment mobilization concentrates capable contractors in Nigeria and South Africa.
- Trenching:Conventional open excavation remains cost-dominant for rural transmission corridors with favorable geotechnical conditions and minimal surface constraints.
- Open Cut:Surface excavation for road crossings and facility interconnects persists in industrial zones where shutdown windows permit disruptive construction.
- Others:Micro-tunneling and pipe bursting address rehabilitation of legacy networks in South Africa's established industrial corridors.
Trenching retains volume leadership; horizontal directional drilling is gaining share fastest in environmentally regulated terrain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractor capacity clusters in Nigeria and South Africa, leaving East African projects dependent on imported welding crews and specialized equipment. Pipeline investment flows concentrate along four national corridors where regulatory frameworks and resource endowments align.
Nigeria
Escravos-Lagos expansion and Dangote refinery interconnects drive transmission demand. The Department of Petroleum Resources enforces inline inspection mandates for lines above 24-inch diameter. Lagos anchors fabrication yard activity while the Niger Delta hosts composite pipe trials for marginal field gathering.
Mozambique
Rovuma Basin LNG developments pull cross-border corridor investment toward the Maputo corridor. The National Petroleum Institute administers right-of-way compensation frameworks that extend permitting timelines. Northern Cabo Delgado province concentrates offshore-to-onshore landing infrastructure.
Tanzania
Offshore gas discoveries at Mtwara and Lindi feed pipeline planning for Dar es Salaam distribution expansion. The national petroleum regulator coordinates environmental assessments with marine authorities. The coastal corridor between Mtwara and Dar es Salaam hosts preliminary route surveys.
Angola
Offshore block developments sustain subsea-to-beach gathering system demand. Sonangol unbundles integrity management from EPC contracts, favoring decade-long service structures. Luanda concentrates procurement decision-making for Cabinda and Kwanza Basin projects.
South Africa
Specialized welding labor pools support regional contractor mobility. Petroleum Agency SA enforces qualification standards that shape cross-border eligibility. Durban-Richards Bay industrial corridor hosts the continent's deepest stock of certified ASME Section IX technicians.
Africa Pipeline Construction Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fabrication and inspection niches. The market structures around three tiers: Chinese state-owned engineering conglomerates, European infrastructure multinationals, and African national champions with downstream integration. Strategic moves concentrate on welding qualification pre-positioning and cross-border regulatory navigation rather than capacity expansion.
Among Chinese state-owned contractors, China Communications Construction Group Ltd. and China Railway Construction Corporation Ltd. occupy positions shaped by port and marine engineering heritage. European-listed infrastructure groups including Vinci SA and Bouygues SA exemplify the premium-tier EPC model. African national champions such as Dangote Group and Republic of Mozambique Pipeline Investments Company anchor downstream-integrated and cross-border transmission archetypes respectively.
| Leading Market Players |
|---|
| China Communications Construction Group Ltd. |
| China Railway Construction Corporation Ltd. |
| Vinci SA |
| Dangote Group |
| Bouygues SA |
| Republic of Mozambique Pipeline Investments Company |
| West African Gas Pipeline Company |
| TotalEnergies |
| Sinopec |
| Others |
Value Network & Pricing Analysis
Lagos fabrication yards anchor Africa's pipeline steel procurement, with capacity utilization swings directly transmitting into EPC contractor pricing power across Nigerian transmission projects. API 5L-grade steel availability from these coastal clusters determines whether fixed-price contracts retain margin or bleed into cost escalation clauses.
Pricing Analysis
Nigeria's Department of Petroleum Resources welding qualification mandates dictate the pricing tier structure across contractor bids, separating ASME Section IX-certified houses from uncertified competitors. Three-tier pricing stratifies across premium certified, standard compliant, and economy provisional tiers based on welder certification density and inline inspection pre-negotiation status. Cost compression in economy-tier gathering systems is intensifying because composite spoolable alternatives are eliminating coating yard overhead. Municipal utilities in Dar es Salaam and Luanda exhibit highest price sensitivity, while integrated majors in Mozambique's Rovuma Basin absorb premium tiering for decade-long integrity service unbundling.
Supply Chain Analysis
Chinese state-owned engineering conglomerates and European infrastructure multinationals hold dominant EPC contract manufacturing capacity, with fabrication yards concentrated in Nigeria, South Africa, and Angola's Luanda corridor. Raw material flows draw from Chinese API 5L steel mills, South African alloy suppliers, and Korean coating material specialists. Single-source vulnerability concentrates in specialized horizontal directional drilling equipment, where Nigerian and South African contractors monopolize regional mobilization. Distribution runs through coastal port terminals at Lagos, Maputo, and Luanda, with inland logistics to landlocked Tanzania and Ethiopia adding cost layering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified welding labor scarcity constrains project mobilization timelines, with ASME Section IX technician density determining which contractors capture high-pressure transmission awards. The gap between South Africa's qualification depth and East Africa's project demand creates arbitrage opportunities for workforce mobility plays.
For Market Incumbents: Harden welding qualification pre-positioning in Mozambique and Tanzania before National Petroleum Institute and national regulator mandates tighten eligibility thresholds. Defend margin position by unbundling integrity management from EPC contracts into standalone decade-long service agreements, following Sonangol's contracting sophistication in Angola. Backward integration into coating yard ownership insulates against API 5L steel price volatility transmitted through fixed-price structures. For New Entrants and Emerging Players: Establish a beachhead in Ethiopia's underpenetrated transmission grid, where first-mover advantages await integrated pipeline-power project developers. Target water-energy nexus applications for Namibian and Botswanan mining desalination corridors, where non-hydrocarbon revenue streams escape oil and gas incumbent dominance. Lead with composite reinforced thermoplastic pipe installation capability to bypass steel-centric welding qualification bottlenecks entirely. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized inspection firms over traditional construction houses as asset operators unbundle integrity management. Long-term viability across the projection horizon rests on decade-long service agreement annuity streams rather than lumpy EPC project exposure. Acquisition targets should demonstrate pre-negotiated pigging agreements with Nigerian Department of Petroleum Resources compliance track records. Monitor ASME Section IX certification queue lengths as the inflection signal for contractor pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Welding Qualification Pre-Positioning | ASME Section IX certification density determines eligibility for Nigerian DPR-mandated high-pressure lines. |
| Composite Material Capability Buildout | Reinforced thermoplastic pipe installation bypasses steel-centric labor bottlenecks in Niger Delta swamp terrain. |
| Integrity Management Unbundling | Standalone decade-long service agreements capture recurring revenue from Angola's offshore contracting sophistication. |
| Cross-Border Regulatory Navigation | Multi-jurisdictional permitting expertise compresses Mozambique INP right-of-way compensation timelines. |
| Horizontal Directional Drilling Equipment Access | Specialized trenchless capability commands premium pricing for environmentally sensitive river crossings. |
Research Methodology
Initial hypotheses were tested against primary input from EPC contract managers, welding qualification auditors, national petroleum regulator officials, and municipal utility procurement directors, then refined against secondary validation from Nigerian Department of Petroleum Resources filings, Mozambique National Petroleum Institute environmental assessments, Angola Sonangol contracting disclosures, and African Petroleum Producers Organization safety protocols. Bottom-up project pipeline tracking across Tanzania, Mozambique, Nigeria, and Angola triangulated with top-down steel demand modeling from API 5L-grade consumption patterns.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning project type, material selection, end user archetype, and installation methodology. CAGRs derived from project-level capital expenditure aggregation and contractor backlog analysis, incorporating horizontal directional drilling adoption curves and composite pipe penetration rates in marginal field gathering systems.
Sensitivities concentrate around API 5L steel alloy input volatility, ASME Section IX certification queue bottlenecks, and right-of-way compensation dispute resolution timelines in cross-border corridors. Forecasts reflect documented assumptions on welding labor mobility constraints and national content threshold enforcement intensity. Quarterly review of certification wait times, steel futures positioning, and regulator mandate implementation cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
Philippines Data Center Construction Market
Infrastructure Construction
Taiwan Data Center Construction Market
Infrastructure Construction
South Korea Infrastructure Market
Infrastructure Construction
Global Port Infrastructure Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
Israel Data Center Construction Market
Infrastructure Construction
South Korea Transportation Infrastructure Construction Market
Infrastructure Construction
Global Rail Infrastructure Market
Infrastructure Construction
Qatar Transportation Infrastructure Construction Market
Infrastructure Construction
New Zealand Data Center Construction Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
Steel Utility Poles Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Ship Port Infrastructure Market