
 Construction Nails Market | 2026-2036
Construction Nails Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Nails Market Analytics
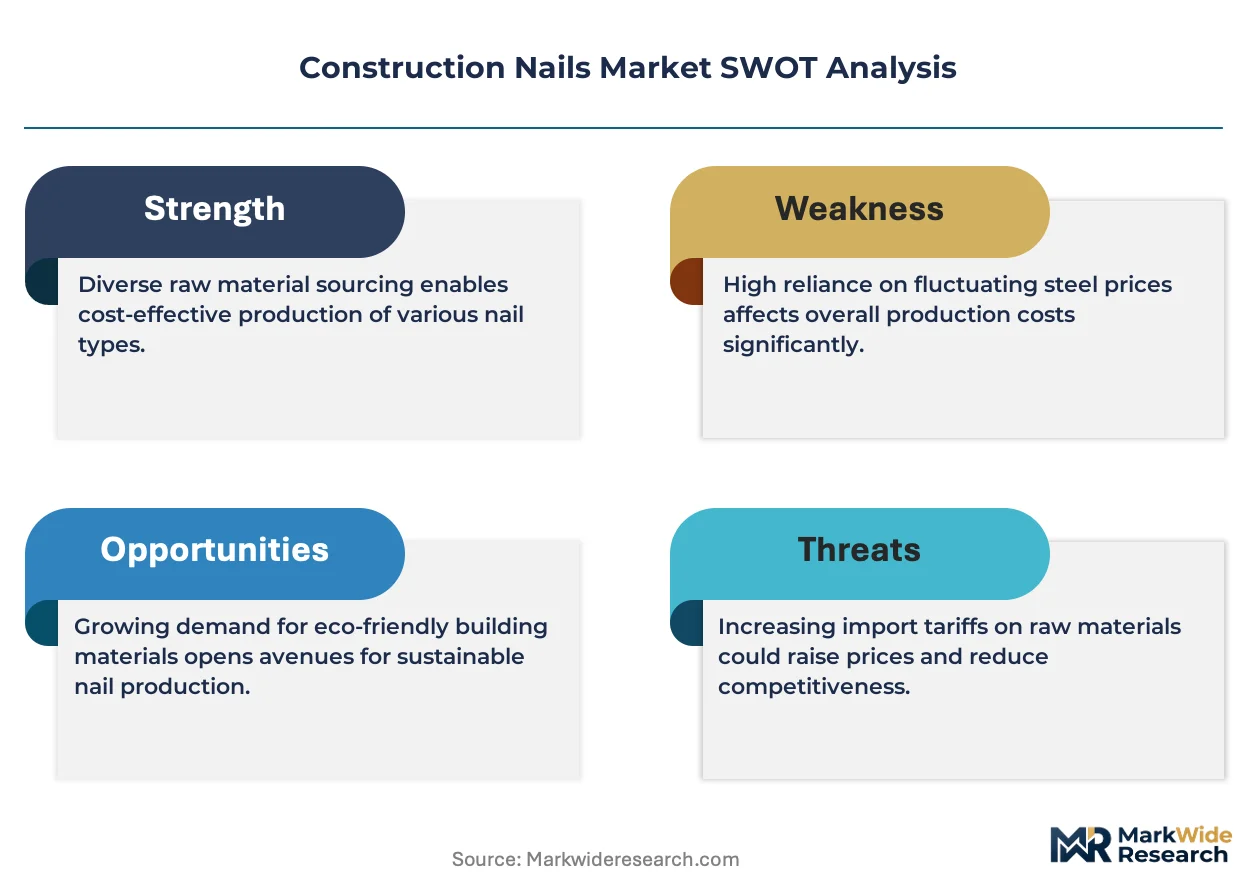
The construction nails sector is restructuring around a sharp split between premium corrosion-resistant fasteners and undifferentiated commodity bulk nails. Simpson Strong-Tie leverages engineered fastening systems for structural applications to command premium positioning. Grip-Rite sustains volume dominance through distribution depth in residential building channels. Maze Nails differentiates via specialty copper and stainless steel offerings for heritage restoration and marine environments.
Construction nails are hardened steel or non-ferrous metal fasteners, typically 1 to 6 inches in length, manufactured through wire drawing, cold heading, and point-forming processes, designed to join structural lumber, sheathing, and roofing substrates under shear and withdrawal loads. Framing nails dominate volume demand in wood-frame residential construction, while roofing nails command tighter margin pools due to galvanized and epoxy-coated specifications. Stainless steel material grades capture expanding share in coastal and chemically exposed applications where zinc-plated alternatives fail prematurely.
EPA lead-safe renovation rules and REACH substance restrictions on hexavalent chromium coatings compel manufacturers to reformulate plating chemistries and certify compliance for market access. OSHA nail gun safety standards shape product design and trigger mechanism specifications across commercial jobsites. Stakeholders must monitor evolving building code adoptions of ring-shank and screw-shank geometries that promise superior pull-out resistance.
Market Dynamics
Anti-corrosion coating mandates from EPA and REACH are forcing manufacturers to abandon hexavalent chromium plating and retool production lines for compliant chemistries. This regulatory compression is reshaping cost structures and supplier qualification requirements across the construction nails value chain.
Growth Catalysts
- REACH substance restrictions:European mandates on hexavalent chromium drive material upgrades toward epoxy and ceramic coatings, expanding premium product margins.
- Residential housing construction:Wood-frame building activity in the United States and Germany sustains volume demand for framing and sheathing fasteners.
- Stainless steel material grades:Coastal infrastructure renewal and marine environment exposure accelerate adoption of corrosion-resistant alloys over zinc-plated alternatives.
Market Restraints
- Wire rod input volatility:Cold-heading quality steel pricing fluctuations compress margin predictability for commodity nail producers.
- Supply concentration in China:Bulk nail manufacturing gravity creates dependency risk for distributors serving North American and European building channels.
- Mechanical fastener substitution:Structural screws with superior pull-out resistance capture share in engineered wood and mass timber applications.
Strategic Opportunities
- Heritage restoration segment:Specialty copper and silicon bronze nails for historic building preservation command premium pricing with limited competition.
- OSHA nail gun safety standards:Sequential trigger mechanism mandates create aftermarket upgrade demand and certified tool bundling potential.
- Building code adoption of ring-shank geometries:Enhanced withdrawal resistance specifications in hurricane-prone US states favor engineered shank designs.
Industry Challenges
- Plating chemistry reformulation:EPA lead-safe renovation rules and REACH compliance timelines require capital-intensive process validation and third-party certification.
- Fastener-grade steel sourcing:Cold-heading quality wire rod availability constraints from integrated mills limit production flexibility for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Nails Market |
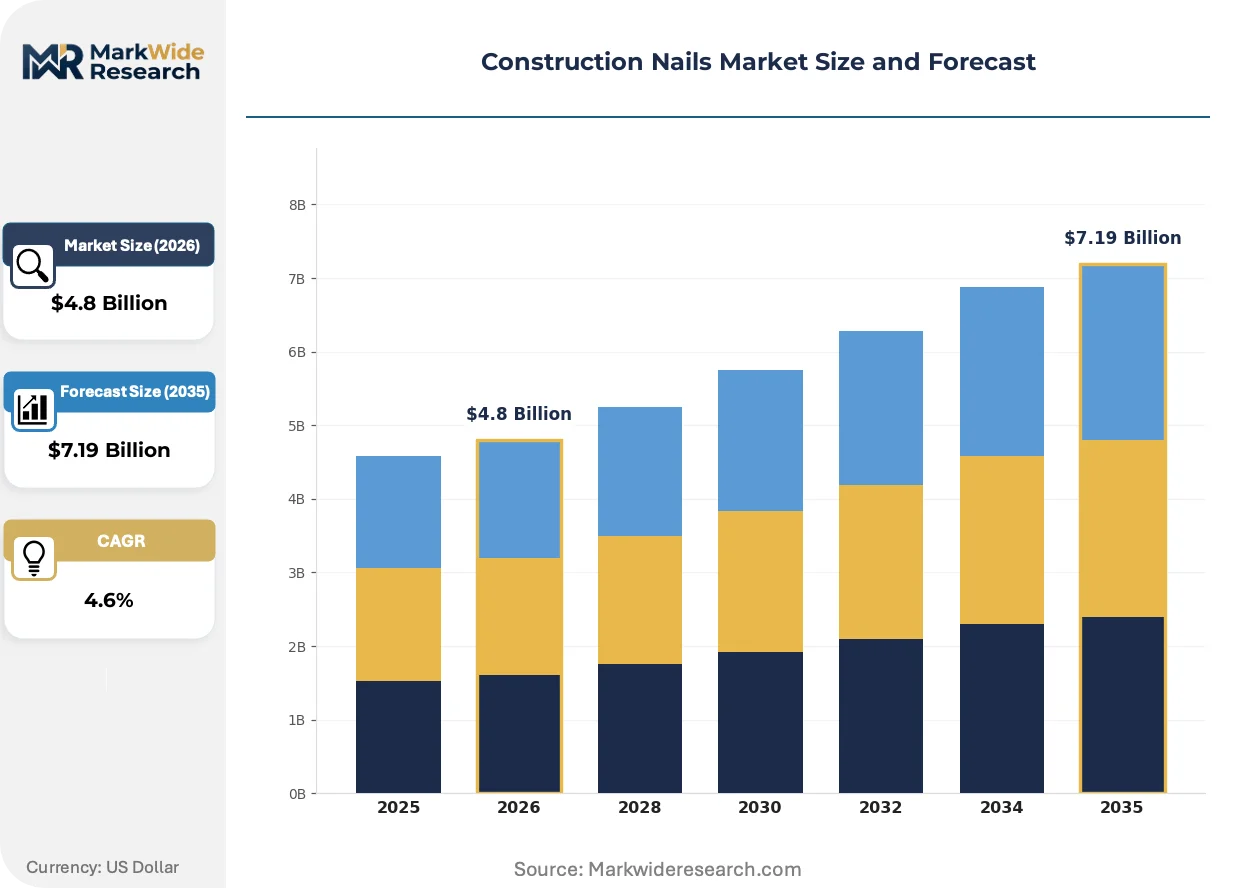
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Common Nails, Finishing Nails, Framing Nails, Roofing Nails Material: Steel, Stainless Steel, Copper, Aluminum Coating: Zinc Plated, Galvanized, Epoxy Coated, Black Oxide Head Style: Flat Head, Round Head, Clipped Head, Sinkers |
| Companies Covered | Simpson Strong-Tie, Grip-Rite, Maze Nails, TITIBI, Bostitch, Mid Continent Steel & Wire, Duchesne, BECK Fastener Group, DEACERO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Nails Market Evolving Landscape
Coating technology advancement and shank geometry engineering are compressing the performance gap between commodity bulk nails and structural fastening systems. Manufacturers are repositioning around certified compliance and application-specific performance rather than pure volume scale.
Mechanically deposited aluminum-zinc alloy coatings are consolidating market share in coastal and chemically exposed construction environments. Marine contractors and infrastructure engineers specify these finishes for salt-air resistance that exceeds conventional hot-dip galvanizing. The technology is consolidating specification authority away from commodity zinc-plated products in high-corrosion-risk applications.
EPA enforcement of lead-safe renovation certification for contractors handling pre-1978 housing stock is tightening fastener traceability requirements. Distributors must now document plating chemistry compliance for products entering regulated renovation channels. Roofing and siding nail categories face the steepest compliance burden as they penetrate existing residential structures most frequently.
Building material distributors are unbundling fastener procurement from lumber and sheathing bundles to standalone specification-driven purchasing. Large residential builders and commercial general contractors now source corrosion-resistant fasteners through direct manufacturer relationships rather than traditional two-step distribution. This pattern is most pronounced in the United States where national homebuilders consolidate purchasing across multi-regional construction portfolios.
Construction Nails Market Segmentation
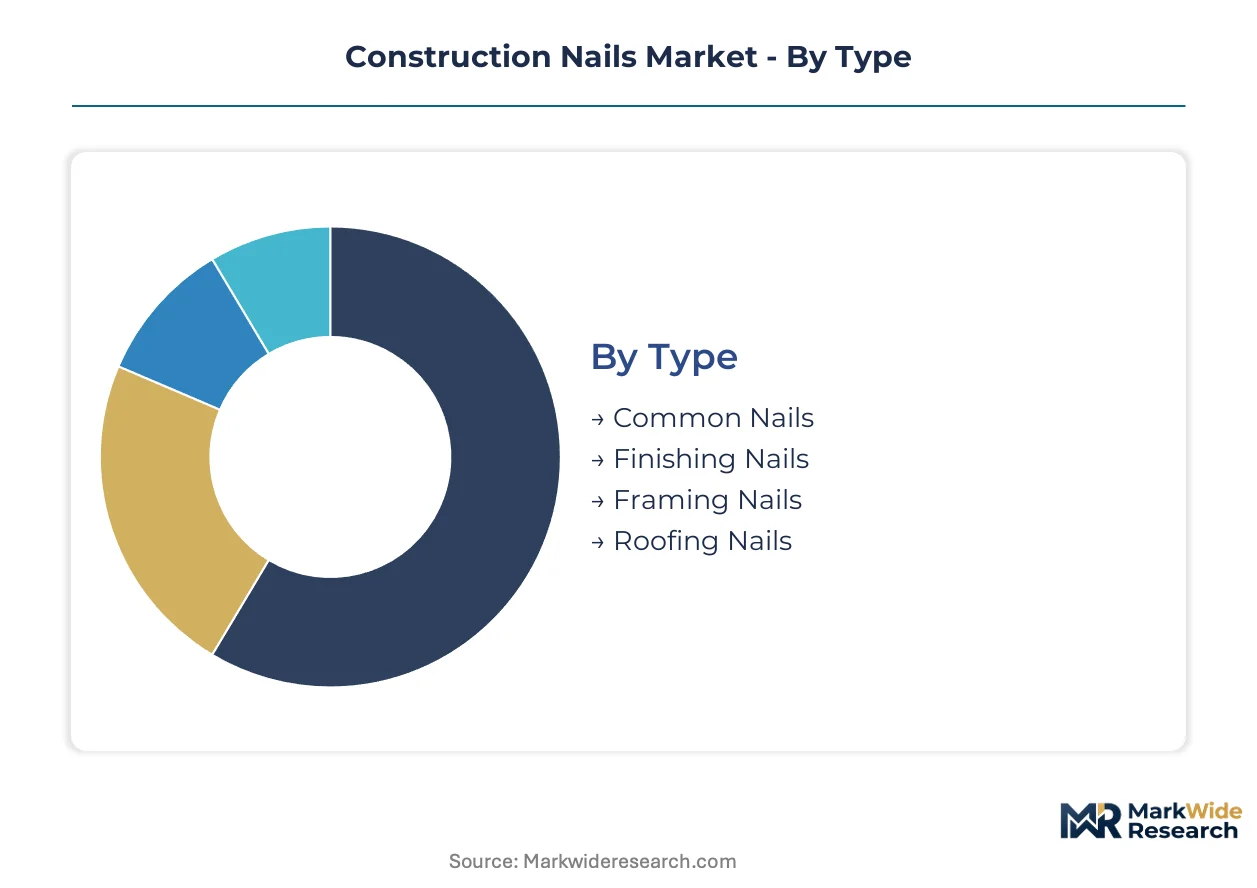
Construction nail procurement now pivots on specification-grade differentiation rather than commodity volume. Buyers segment demand across corrosion resistance, structural load requirements, and substrate compatibility, forcing manufacturers to align production with application-specific performance tiers.
Type:
Specification intensity varies sharply across construction phases, with structural fastening commanding premium validation while finish carpentry tolerates broader interchangeability.
- Framing Nails:Hardened steel fasteners with ring-shank or screw-shank geometries engineered for shear and withdrawal resistance in dimensional lumber assemblies. Residential wood-frame construction in the United States and Germany absorbs the majority of volume, driven by single-family housing starts and multi-family podium structures.
- Roofing Nails:Short-shank fasteners with broad heads and elastomeric washers designed for asphalt shingle and underlayment attachment. Coastal infrastructure renewal across Florida, California, and North Carolina accelerates specification of enhanced corrosion-resistant grades over standard zinc-plated alternatives.
- Common Nails:General-purpose smooth-shank fasteners for rough carpentry and temporary formwork applications.
- Finishing Nails:Small-diameter fasteners with minimal head profiles for trim, molding, and visible woodwork installations.
Mature deployment sits with framing nails in standard wood-frame construction. Newer deployment is concentrated in roofing nails with specialized coastal-grade coatings.
Material:
Cost-to-performance ratios determine specification authority, with premium alloys capturing share in chemically aggressive environments where coating failures prove catastrophic.
- Steel:Cold-heading quality carbon steel dominates volume production through wire drawing and point-forming processes, delivering cost-efficient shear strength for interior and protected exterior applications. Bulk residential construction in the United States sustains demand despite corrosion limitations in exposed conditions.
- Stainless Steel:Austenitic and martensitic grades specified for salt-air, chemical, and marine environments where galvanic protection fails. Infrastructure renewal along the US Gulf Coast and Mediterranean coastal zones in Spain and Italy drives specification of 304 and 316 grades.
- Copper:Non-ferrous fasteners for heritage restoration and architectural applications requiring material compatibility with historic substrates.
- Aluminum:Lightweight fasteners for specialized applications demanding galvanic isolation from dissimilar metals.
Steel anchors volume across standard construction phases. Stainless steel is climbing the fastest in coastal and chemically exposed specifications.
Coating:
Regulatory chemistry mandates are restructuring supplier qualification, with REACH and EPA restrictions disqualifying legacy hexavalent chromium processes.
- Galvanized:Hot-dip zinc coating delivering sacrificial corrosion protection through metallurgical bonding, specified for pressure-treated lumber contact and exterior framing. Building code adoption across hurricane-prone US states favors heavier coating weights for enhanced durability cycles.
- Epoxy Coated:Thermoset polymer barriers applied over zinc substrates for chemical and salt-air resistance in aggressive environments. Marine contractors in the Netherlands and coastal Germany specify these finishes for infrastructure with design lives exceeding fifty years.
- Zinc Plated:Electrodeposited thin-film coatings for interior and temporary applications with minimal exposure risk.
- Black Oxide:Conversion coating for aesthetic consistency and minimal corrosion protection in dry interior environments.
Galvanized coatings retain specification authority in standard exterior construction. Epoxy coated deployment is expanding most quickly in infrastructure and marine applications.
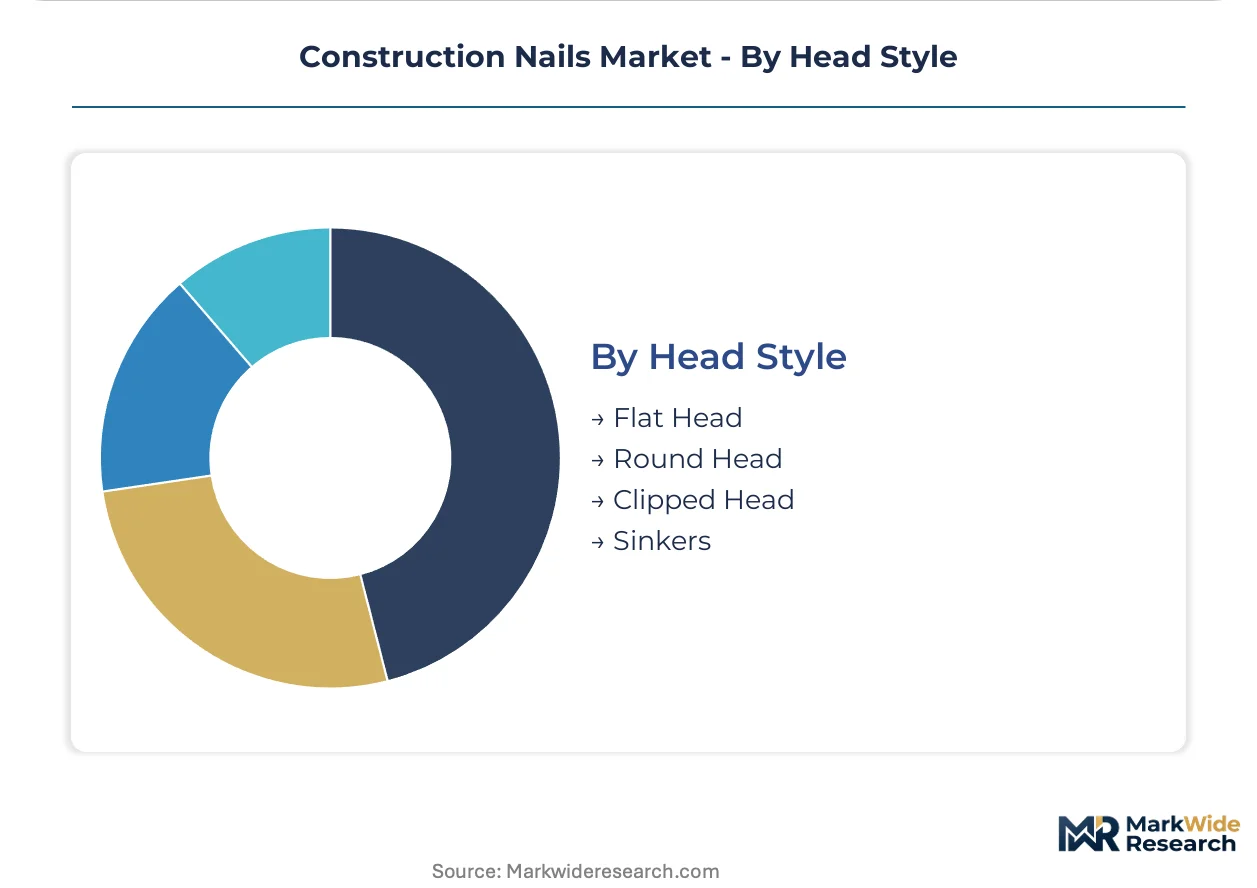
Head Style:
Tool compatibility and substrate concealment requirements drive differentiation, with pneumatic fastening systems dictating collation and head geometry standards.
- Clipped Head:Offset head profiles enabling tighter collation angles for high-capacity magazine tools, maximizing fasteners per strip in production framing. US residential contractors specify clipped head configurations for volume efficiency in platform framing systems.
- Flat Head:Flush-seating profiles for finished carpentry and visible surface applications requiring minimal protrusion.
- Round Head:Traditional full-head geometry for manual driving and code-specified structural connections requiring maximum bearing surface.
- Sinkers:Cement-coated shanks with textured heads for reduced splitting and improved drivability in dense lumber.
Round head configurations dominate manual and structural code-specified applications. Clipped head tooling is gaining share fastest in production residential framing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston-Galveston corridor anchors North American fastener demand through petrochemical infrastructure renewal and Gulf Coast residential expansion. Construction nail consumption concentrates in industrial clusters where building code enforcement and coastal exposure create specification pressure for corrosion-resistant grades.
United States
Single-family housing starts in Texas and Florida drive framing nail volume, while EPA lead-safe renovation rules tighten plating chemistry documentation for roofing fasteners. Miami-Dade County building codes mandate ring-shank geometries for hurricane wind resistance, elevating engineered shank specifications across the Southeast.
Germany
Multi-family podium construction in Berlin and Hamburg sustains demand for structural fastening systems, with timber-frame building codes expanding in Bavaria. REACH substance restrictions on hexavalent chromium force coating reformulation across Ruhr Valley manufacturing clusters, pushing epoxy and ceramic finishes.
China
Yangtze River Delta infrastructure renewal absorbs bulk nail volume for bridge and highway construction, though cold-heading quality wire rod sourcing constraints limit mid-tier producer flexibility. Shanghai port logistics handle re-export flows to Southeast Asian building markets.
India
Affordable housing programs in Maharashtra and Gujarat generate commodity nail demand for concrete formwork and temporary structures. Bureau of Indian Standards certification requirements for structural fasteners create qualification barriers for imported products entering Delhi-NCR distribution channels.
Netherlands
Marine infrastructure contractors in Rotterdam specify mechanically deposited aluminum-zinc coatings for salt-air resistance exceeding conventional galvanizing. Delta Works flood defense maintenance drives specialty fastener procurement through direct manufacturer relationships rather than traditional distribution.
Construction Nails Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating technology and specification-grade certification, creating a tiered structure where corrosion resistance and code compliance separate pricing power. The vendor base spans integrated steel-to-fastener manufacturers, specialized coating applicators, and regional distributors with private-label programs. Two strategic archetypes dominate: engineered fastening system providers bundling tools and consumables, and volume-scale commodity producers optimizing wire rod throughput. Consolidation pressure is mounting through backward integration into cold-heading quality steel sourcing and geographic expansion into coastal specification markets.
Among North American specialists, Simpson Strong-Tie and Grip-Rite exemplify divergent archetypes within the same regional market. Simpson Strong-Tie occupies a position as an engineered system provider, while Grip-Rite represents volume-scale distribution depth. Maze Nails anchors the specialty materials tier with heritage restoration focus. TITIBI and BECK Fastener Group represent European coating technology and precision manufacturing positions respectively.
| Leading Market Players |
|---|
| Simpson Strong-Tie |
| Grip-Rite |
| Maze Nails |
| TITIBI |
| Bostitch |
| Mid Continent Steel & Wire |
| Duchesne |
| BECK Fastener Group |
| DEACERO |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap wire rod processors anchor supply discipline across the construction nails value chain, converting cold-heading quality steel into specification-grade fasteners while resisting margin erosion through captive coating operations and direct-to-builder channel control.
Pricing Analysis
Performance-outcome pricing anchors specification-grade segments, with corrosion resistance warranties and code compliance certifications commanding premiums over commodity zinc-plated alternatives. Three-tier pricing structure across premium, standard, and economy levels separates epoxy-coated structural fasteners from hot-dip galvanized framing nails and uncoated bulk common nails. Cost compression in economy tiers is intensifying because Chinese wire rod export pricing volatility feeds through to North American commodity producers. Volume-scale homebuilders exhibit highest price sensitivity, while marine contractors and heritage restoration specialists demonstrate lowest sensitivity due to failure-cost exposure.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cold-heading quality wire rod production, which feeds re-export flows to Southeast Asian fabricators and North American distributors. Raw material dependencies rest on scrap steel pricing, zinc ingot availability, and epoxy resin chemistries. Tariff exposure on steel mill products creates margin unpredictability for mid-tier manufacturers lacking captive melt shop access. Distribution runs through building material wholesalers unbundling fastener procurement from lumber bundles, with large residential builders shifting toward direct manufacturer relationships for specification-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into cold-heading quality steel sourcing and captive coating chemistry production defines competitive positioning, as REACH and EPA mandates disqualify third-party plating suppliers lacking certification depth.
For Market Incumbents: Lock in specification authority through certified epoxy and ceramic coating investments that satisfy REACH substance restrictions and EPA lead-safe renovation documentation requirements. Secure multi-year offtake agreements with Ruhr Valley and Yangtze River Delta wire rod producers to buffer input volatility. Defend against structural screw substitution in mass timber by bundling ring-shank nail systems with pneumatic tool platforms and jobsite training programs. For New Entrants and Emerging Players: REACH substance restrictions in Europe open a window for specialty copper and silicon bronze fastener production serving heritage restoration contractors in Bavaria and Mediterranean coastal zones. Target marine infrastructure segments in the Netherlands and Florida where mechanically deposited aluminum-zinc coatings command premium positioning against conventional galvanizing. Pursue direct specification relationships with Rotterdam Delta Works maintenance contractors and Miami-Dade County roofing specialists bypassing traditional two-step distribution. For Investors and Strategic Acquirers: Building code adoption of ring-shank geometries in hurricane-prone US states is the leading indicator that engineered shank design capabilities will consolidate premium positioning. Frame long-term viability around coating technology IP and certification infrastructure rather than volume scale. Monitor OSHA sequential trigger mechanism mandates as aftermarket upgrade demand signals. Acquisition targets should demonstrate validated plating chemistry reformulation and direct relationships with national homebuilder procurement teams.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Rod Sourcing | Captive cold-heading quality steel supply buffers margin volatility from Chinese export pricing swings. |
| Coating Chemistry Certification Investment | EPA and REACH compliant plating processes unlock specification-grade market access against non-compliant competitors. |
| Direct Homebuilder Relationship Development | Bypassing traditional distribution captures specification-driven procurement shifting toward manufacturer-direct models. |
| Engineered Shank Geometry R&D | Ring-shank and screw-shank designs satisfy Miami-Dade hurricane codes and mass timber withdrawal resistance requirements. |
| Heritage Restoration Segment Expansion | Copper and silicon bronze fasteners for historic building preservation command premium pricing with limited competition. |
Research Methodology
Trade publications, customs filings, and building code adoption records formed the secondary backbone, cross-referenced against primary interviews with fastener procurement managers at national homebuilders, coating chemistry technical directors at Ruhr Valley manufacturers, and marine infrastructure contractors in Rotterdam and Miami. Plant managers at Yangtze River Delta wire rod mills and distribution channel partners in Texas and Florida provided operational validation. Bottom-up volume modeling triangulated against top-down construction spending correlation analysis.
Historical trendline analysis of single-family housing starts, multi-family podium construction permits, and coastal infrastructure renewal appropriations informed demand elasticity parameters across the projection horizon. Segmentation dimensions modeled include fastener type, material grade, coating chemistry, head style, and regional building code enforcement intensity. CAGRs derived from regression-weighted scenario analysis incorporating wire rod pricing volatility and regulatory compliance timeline assumptions. Industry-specific inputs encompassed EPA lead-safe renovation certification penetration rates and REACH substance restriction implementation phases.
The model assumes a particular technology adoption path; alternative pathways for mechanically deposited aluminum-zinc coatings displacing conventional hot-dip galvanizing would alter the outlook. Forecasts reflect assumptions regarding building code harmonization across hurricane-prone states and REACH enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Rotary Tools Market
Tools
Water Pump Pliers Market
Tools
CNC Leather Cutting Machine Market
Tools
Global Sandblasting Media Market
Tools
Ripper Market
Tools
Indexable Tool Inserts Market
Tools
Masonry Cleaners Market
Tools
Dumpy Level Market
Tools
Pneumatic Tools Market
Tools
Assembly Fastening Tool Market
Tools
Global Flange Fasteners Market
Tools
Foam Cutting Machine Market
Tools
Global Staple Gun Market
Tools
Engraver Machine Market
Tools
Fastening Power Tools Market
Tools
Thread Milling Machine Market