
 Bahrain Transportation Infrastructure Construction Market | 2026-2036
Bahrain Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Bahrain Transportation Infrastructure Construction Market Outlook
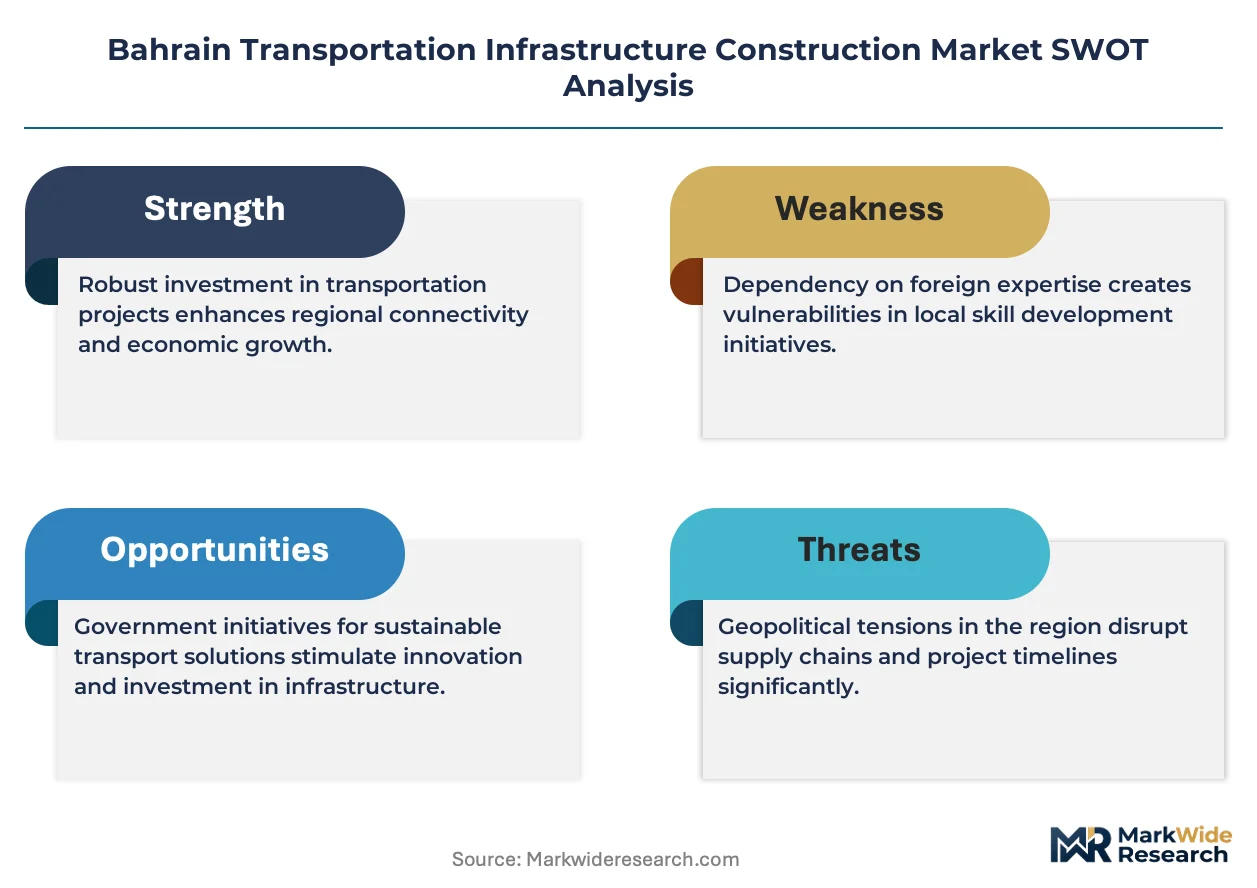
Digital twin modeling is fragmenting traditional design-bid-build workflows across Bahrain's transport project pipeline. Projects Holding Company WLL leverages in-house engineering capabilities to secure multi-year road contracts. Delta Construction Co. anchors its position through captive asphalt production at its Sitra facility. Al Hassanain Company WLL specializes in marine bridge foundations spanning the archipelago's tidal channels.
Bahrain transportation infrastructure construction encompasses the civil engineering, materials fabrication, and site assembly required to create road networks, bridges, tunnels, and airport facilities capable of sustaining design loads from 80-kN axle configurations to 1,200-MPa tensile steel cable ratings. Its primary purpose is reducing inter-island transit friction and expanding airside cargo throughput capacity. Road construction commands the largest share of public tender value given the ongoing Northern Causeway expansion and East Sitra connector programs. Bridge building generates premium margin pools due to marine piling complexity and corrosion-protection specifications in Gulf waters. Airport expansion remains nascent but structurally significant as Bahrain International Airport's cargo zone requires reinforced concrete aprons rated for 575,000-kg freighter wheel loads.
Bahrain's Ministry of Works and Urban Planning sets geometric design standards and pavement performance criteria that contractors must satisfy for prequalification. The country's national environmental regulator enforces coastal construction permits and marine impact assessments for bridge projects crossing sensitive habitats. The Central Bank of Bahrain's infrastructure bond framework shapes how joint ventures and private investment structures access riyal-denominated project finance. Stakeholders must monitor how evolving concrete durability codes and green procurement criteria will reshape supplier qualification thresholds before the next planning cycle.
Market Dynamics
Digital twin modeling is fragmenting traditional design-bid-build workflows across Bahrain's transport project pipeline, forcing contractors to restructure prequalification capabilities around real-time simulation competencies.
Growth Catalysts
- Bahrain's Ministry of Works durability mandates:Stricter concrete mix standards on arterial routes are accelerating adoption of high-performance admixtures and automated batching systems.
- Marine bridge complexity:Foundation works spanning tidal channels between Manama and Muharraq corridors command premium engineering fees and extended contract tenures.
- Airside cargo expansion:Reinforced concrete apron specifications for 575,000-kg freighter loads at Bahrain International Airport are generating specialized pavement construction demand.
Market Restraints
- Captive asphalt supply concentration:Single-facility production at Sitra creates vulnerability to feedstock price volatility and logistics bottlenecks.
- Marine piling corrosion protection costs:Gulf water salinity and tidal abrasion necessitate expensive cathodic systems and high-grade steel alloys.
- Central Bank bond framework limitations:Riyal-denominated project finance structures restrict foreign joint venture capital access and extend procurement cycles.
Strategic Opportunities
- East Sitra connector corridor:Unawarded segments of this arterial program offer entry points for contractors with in-house marine engineering capabilities.
- Green procurement criteria evolution:Anticipated Ministry of Works revisions will reshape supplier qualification thresholds for low-carbon concrete and recycled aggregates.
- Digital twin integration:Convergence of BIM platforms with IoT sensor networks enables predictive maintenance contracting models for completed assets.
Industry Challenges
- Marine geotechnical specialist scarcity:Limited local pool of engineers qualified for tidal channel foundation design compresses project staffing timelines.
- Multi-stakeholder coordination complexity:Joint ventures must align Ministry of Works standards with Central Bank financing covenants and environmental regulator permit conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bahrain Transportation Infrastructure Construction Market |
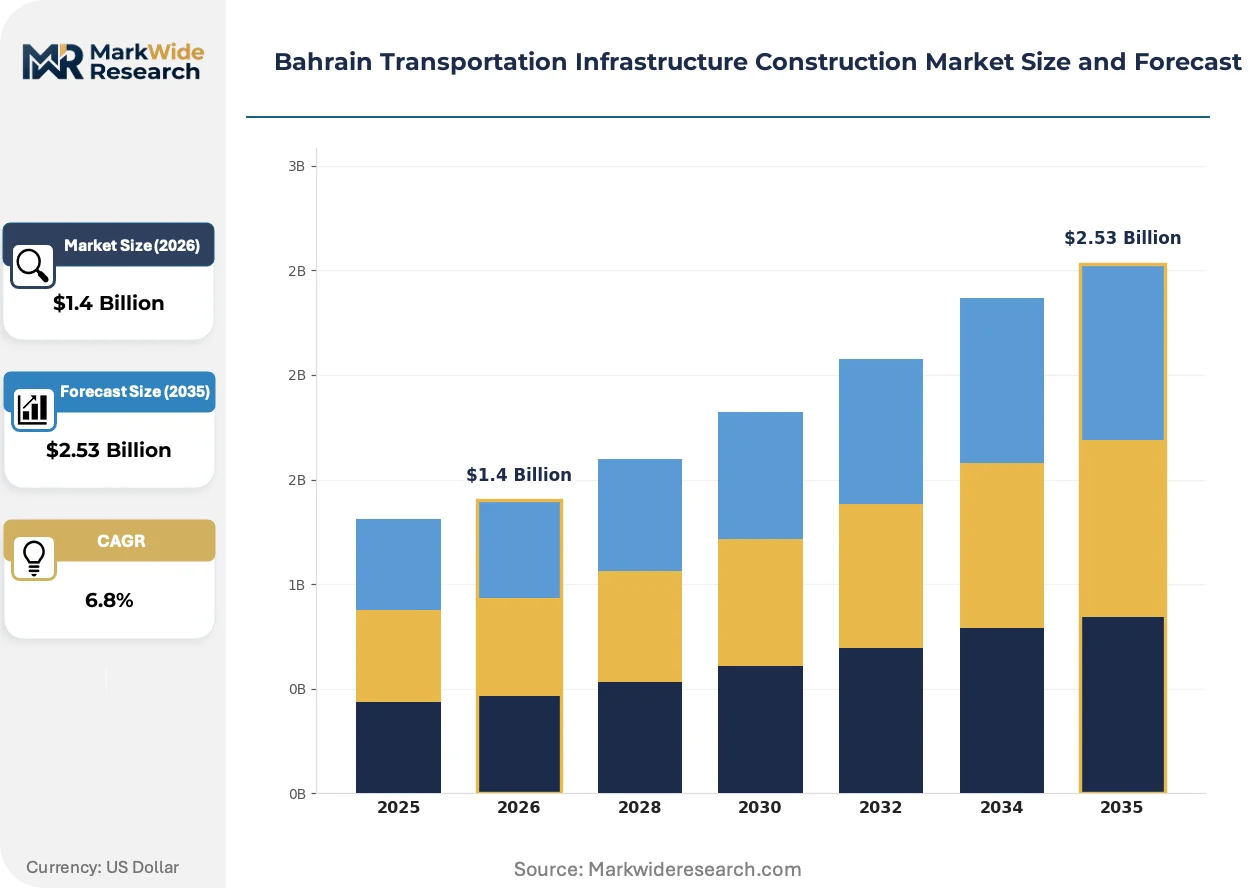
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Road Construction, Bridge Building, Tunnel Development, Airport Expansion Materials Used: Concrete, Asphalt, Steel, Composites Funding Source: Public Financing, Private Investment, Joint Ventures, International Aid End User: Government Agencies, Construction Firms, Transport Authorities, Stakeholders |
| Companies Covered | Projects Holding Company WLL, Delta Construction Co., Bahrain Motors Company WLL, Al Hassanain Company WLL, Kooheji Contractors WLL, Eastern Asphalt and Mixed Concrete Co., Bahrain Foundation Construction Co. WLL, Ramsis Engineering, Bokhowa Group WLL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bahrain Transportation Infrastructure Construction Market Strategic Shifts
Construction workflows across Bahrain's transportation sector are restructuring around predictive simulation and automated compliance verification, compressing traditional design-review cycles.
Building information modeling is migrating from static documentation to live digital twin environments that synchronize design iterations with real-time geotechnical feedback. Bahrain's Ministry of Works now requires BIM-native submissions for bridge tenders above defined complexity thresholds. This shift is compressing pre-construction risk assessment timelines while elevating software competency requirements for contractor prequalification.
Bahrain's national environmental regulator has tightened coastal construction permit requirements for bridge projects crossing sensitive marine habitats. Contractors must now submit real-time sediment monitoring protocols and adaptive pile-driving schedules before breaking ground. Marine foundation specialists face extended approval timelines but gain competitive differentiation through demonstrated compliance automation.
Public procurement patterns are fragmenting as Projects Holding Company WLL and similar entities move toward multi-year program contracts rather than discrete project tenders. This consolidation favors contractors with captive engineering and materials production capabilities. The shift is most visible in Manama-Muharraq corridor road programs, where single-source responsibility models are displacing fragmented subcontractor networks.
Bahrain Transportation Infrastructure Construction Market Segmentation
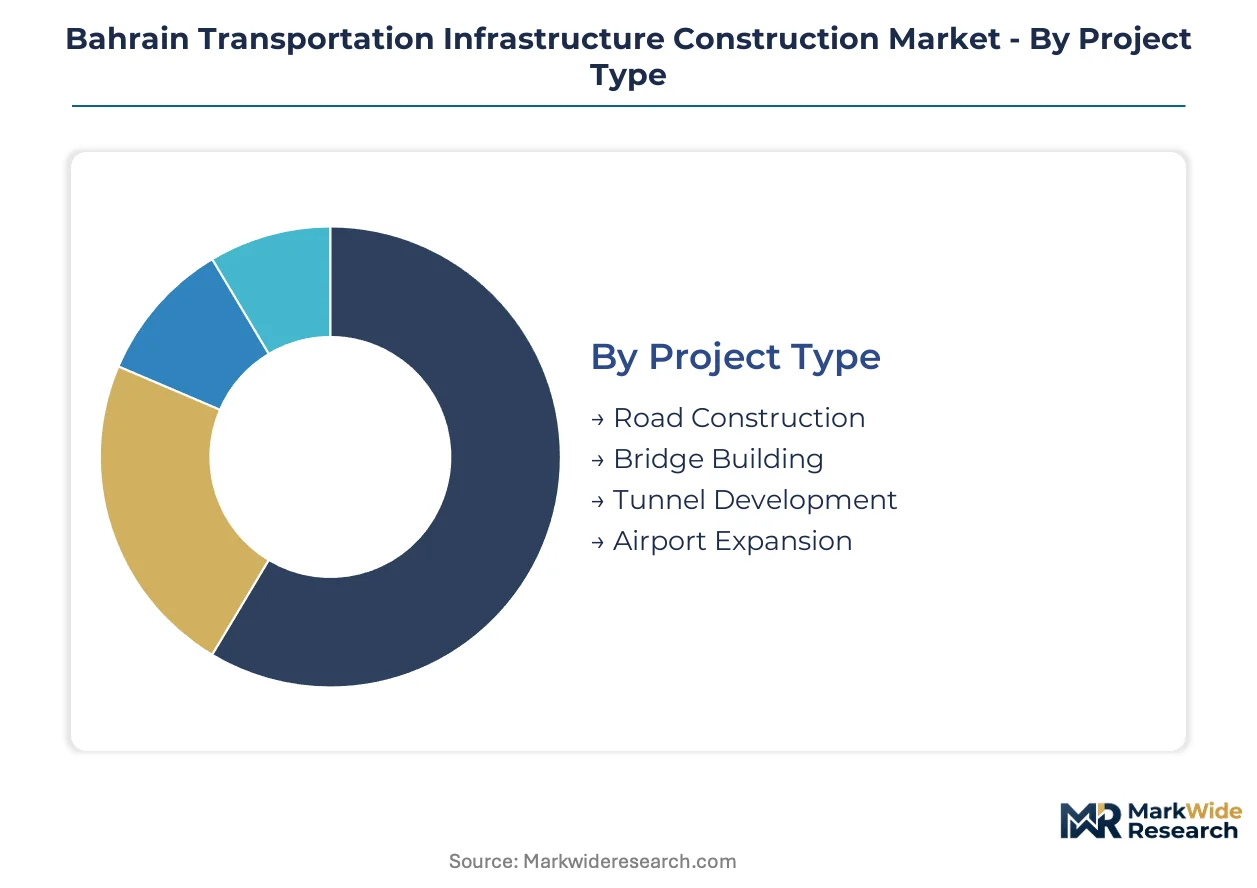
Segmentation in Bahrain's transportation infrastructure market reveals how procurement concentration, material specifications, and funding structures allocate contract value across discrete project categories. Contractors must align capabilities with the specific technical and financing requirements of each segment to secure prequalification.
Project Type:
Application focus determines engineering specialization requirements and margin profiles across Bahrain's transport construction pipeline.
- Road Construction:Arterial route development and urban corridor upgrades consume the largest share of public tender value. Northern Causeway expansion and East Sitra connector programs concentrate demand in Manama and Muharraq, where Ministry of Works durability mandates for concrete mixes are accelerating adoption of high-performance admixtures.
- Bridge Building:Marine foundation works spanning tidal channels between islands command premium engineering fees due to corrosion-protection specifications and cathodic system requirements in Gulf waters. Foundation complexity extends contract tenures and elevates specialist qualification thresholds.
- Tunnel Development:Limited subterranean projects focus on utility corridors and pedestrian underpasses in dense urban districts.
- Airport Expansion:Reinforced concrete apron construction for cargo zone expansion at Bahrain International Airport requires specialized pavement rated for 575,000-kg freighter wheel loads.
Road Construction holds installed capacity. Bridge Building is rotating up the share rankings.
Materials Used:
Cost tier positioning of raw inputs shapes contractor margin structures and supply chain vulnerability profiles.
- Concrete:High-performance mixes with automated batching systems dominate arterial route specifications. Stricter durability codes from the Ministry of Works are reshaping supplier qualification thresholds for low-carbon formulations and recycled aggregates.
- Asphalt:Captive production at single-facility operations creates feedstock price volatility exposure. Road surfacing demand concentrates in government-funded corridor programs with multi-year supply agreements.
- Steel:Marine piling applications require high-grade alloys resistant to Gulf water salinity and tidal abrasion. Corrosion-protection coatings add material cost premiums.
- Composites:Specialized bridge decking and non-structural applications remain niche due to qualification barriers and limited local fabrication capacity.
Concrete holds installed capacity. Steel is rotating up the share rankings.
Funding Source:
Capital structure determines procurement cycle length, stakeholder coordination complexity, and foreign joint venture access constraints.
- Public Financing:Ministry of Works tenders dominate volume through multi-year program contracts favoring contractors with in-house engineering capabilities. Riyal-denominated disbursements align with Central Bank infrastructure bond frameworks.
- Private Investment:Limited transport asset privatization creates constrained opportunity pools outside airport and port adjacent development zones.
- Joint Ventures:Foreign capital participation faces extended procurement cycles due to currency denomination restrictions and prequalification alignment requirements.
- International Aid:Development finance for regional connectivity projects remains marginal to overall market value.
Public Financing holds installed capacity. Joint Ventures is rotating up the share rankings.
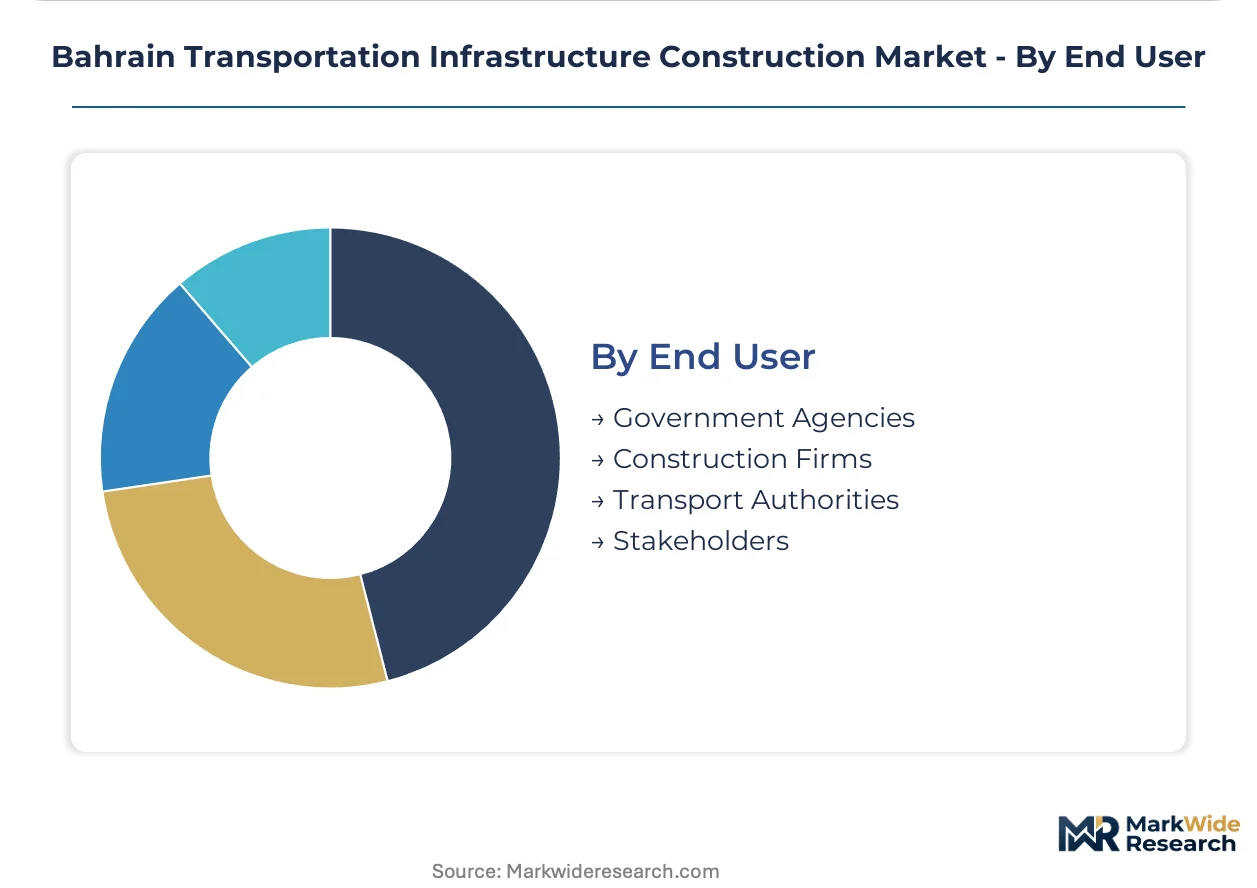
End User:
Customer type dictates technical specification authority, contract tenure preferences, and maintenance responsibility allocation.
- Government Agencies:Ministry of Works and Urban Planning sets geometric design standards and pavement performance criteria that contractors must satisfy for prequalification. Procurement volumes are rising as multi-year program contracts displace fragmented subcontractor networks.
- Construction Firms:Prime contractors with captive materials production and engineering capabilities secure preferred bidder status on complex marine and airside projects.
- Transport Authorities:Bahrain International Airport and port operators generate specialized demand for heavy-load pavement and marine structure specifications.
- Stakeholders:Environmental regulators and coastal zone managers enforce permit conditions that extend approval timelines for sensitive habitat crossings.
Government Agencies hold installed capacity. Transport Authorities is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bahrain's transportation infrastructure construction sector serves as a critical trade-flow corridor connecting Saudi Arabia's Eastern Province industrial zones to export terminals along the Gulf coastline. The kingdom's island geography concentrates marine bridge demand across tidal channels while arterial road programs link port facilities to industrial hinterlands.
Manama Capital Governorate
The Northern Causeway expansion and central business district road upgrades drive concrete demand exceeding standard durability specifications. Bahrain's Ministry of Works enforces stricter mix standards on arterial routes passing through the capital. Marine bridge foundations spanning the Manama-Muharraq corridor command premium engineering fees due to tidal channel complexity.
Muharraq Governorate
Airside cargo expansion at Bahrain International Airport generates specialized pavement construction for 575,000-kg freighter wheel loads. The Central Bank's infrastructure bond framework channels riyal-denominated finance toward airport-adjacent development zones. Sitra industrial facilities anchor captive asphalt production serving corridor programs linking the airport to port terminals.
Northern Governorate
The East Sitra connector program concentrates unawarded arterial segments requiring contractors with marine engineering capabilities. Coastal construction permits from the national environmental regulator mandate real-time sediment monitoring for bridge projects crossing sensitive habitats. Unawarded road segments offer entry points for firms qualifying under evolving green procurement criteria.
Southern Governorate
Industrial zone connectivity roads support petrochemical facility expansion along the peninsula's southern reaches. Durability mandates for heavy-haul routes accelerate adoption of high-performance concrete admixtures. Limited bridge demand contrasts with concentrated road surfacing requirements for logistics corridors.
Bahrain Transportation Infrastructure Construction Market Competitive Environment
On the supply side, the industry is consolidating around contractors with captive materials production and in-house engineering capabilities. Multi-year program contracts from government agencies favor integrated players over fragmented subcontractor networks. Two strategic archetypes dominate: vertically integrated construction groups controlling asphalt and concrete supply, and marine engineering specialists commanding premium positioning on tidal foundation projects. Competitive moves concentrate on securing multi-year road contracts and deepening upstream control over batching and mixing operations.
Within the integrated construction tier, Projects Holding Company WLL and Delta Construction Co. exemplify the captive production model, with the latter anchoring supply position through in-house asphalt facilities. Al Hassanain Company WLL occupies a specialist position in marine bridge foundations, representing the engineering-intensive archetype required for complex tidal channel crossings across the archipelago.
| Leading Market Players |
|---|
| Projects Holding Company WLL |
| Delta Construction Co. |
| Bahrain Motors Company WLL |
| Al Hassanain Company WLL |
| Kooheji Contractors WLL |
| Eastern Asphalt and Mixed Concrete Co. |
| Bahrain Foundation Construction Co. WLL |
| Ramsis Engineering |
| Bokhowa Group WLL |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in high-performance concrete batching across the Northern Governorate is compressing contractor margins while elevating pricing power for automated mixing operations serving arterial route programs. This utilization squeeze feeds directly into procurement posture, as Ministry of Works durability mandates force buyers toward premium admixture formulations with limited qualified supply.
Pricing Analysis
Current-generation digital twin-enabled project delivery commands fee premiums against prior-generation design-bid-build workflows, while next-generation predictive maintenance contracting remains nascent and unpriced. Project-based pricing dominates public tenders, with differentiation driven by marine engineering certification tier and captive materials integration depth. Cost compression in standard road surfacing is intensifying because of single-facility asphalt concentration at Sitra. Government agencies show lowest price sensitivity given multi-year program mandates, while emerging joint venture entrants face acute margin pressure on prequalification compliance.
Supply Chain Analysis
Captive production concentration at Delta Construction Co.'s Sitra facility and Projects Holding Company WLL's integrated batching operations controls regional asphalt and concrete supply. Raw material flows draw from Saudi Arabian petrochemical feedstocks, UAE steel rebar shipments, and specialty admixture imports from European chemical suppliers. Single-source vulnerability at the Sitra asphalt plant creates logistics chokepoint exposure for corridor programs. Distribution runs through Ministry of Works multi-year program contracts with discrete subcontractor tiering for marine foundation specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bahrain's transportation infrastructure construction market functions as a defensive-moat arena where regulatory entrenchment through Ministry of Works prequalification standards creates durable incumbent advantages. Switching costs for public agencies escalate with each completed program contract, cementing supplier relationships.
For Market Incumbents: Harden captive materials positions through backward integration into automated concrete batching and corrosion-protection coating application. Deepen engineering staff pools for marine geotechnical design to counter specialist scarcity threats. Secure multi-year program extensions before green procurement criteria revisions reshape qualification thresholds.
For New Entrants and Emerging Players: Pursue unawarded East Sitra connector segments where marine engineering capabilities create differentiation against standard road contractors. Target airport cargo apron expansion as the most penetrable specialized segment given freighter-load pavement specifications. Lead with digital twin simulation competencies to bypass traditional prequalification barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated construction groups with captive asphalt production and in-house marine foundation engineering. Long-term viability over the coming decade rests on regulatory alignment with evolving durability codes and environmental permit automation. Monitor Ministry of Works green procurement revision timing as the critical inflection signal for supplier qualification disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Materials Expansion | Backward integration into automated batching secures margin control against feedstock volatility. |
| Marine Engineering Certification | Specialist qualification for tidal channel foundations unlocks premium corridor contract access. |
| Digital Twin Capability Buildout | BIM-native submission competency satisfies evolving Ministry of Works tender requirements. |
| Green Procurement Alignment | Low-carbon concrete formulation investment anticipates supplier threshold revisions. |
| Multi-Year Program Consolidation | Single-source responsibility models displace fragmented subcontractor networks in Manama-Muharraq corridors. |
Study Parameters
A standing panel of Ministry of Works procurement officers, marine foundation engineering directors, asphalt plant operations managers, and Central Bank infrastructure finance specialists provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against customs trade records, Ministry of Works tender disclosures, Central Bank bond framework documentation, and contractor prequalification filings. Bottom-up project pipeline enumeration triangulated against top-down public expenditure tracking.
Scenario-bracketing around public financing continuity, green procurement adoption velocity, and marine specialist labor pool expansion shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include project type, materials specification tier, funding source structure, and end-user procurement authority. CAGRs were derived from expenditure trajectory analysis and capacity utilization signals. Forecast inputs incorporated concrete durability code revision schedules and environmental permit approval timeline trends.
Sensitivities concentrate around Ministry of Works mandate timing, Central Bank riyal-denominated finance access, and marine geotechnical specialist availability. Forecasts reflect documented assumptions on public expenditure continuity and regulatory implementation cadence. Quarterly review of tender award patterns, prequalification threshold revisions, and captive production capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Finland Transportation Infrastructure Construction Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
Israel Data Center Construction Market
Infrastructure Construction
Singapore Transportation Infrastructure Construction Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
New Zealand Infrastructure Market