
 North America Transportation Infrastructure Construction Market | 2026-2036
North America Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
North America Transportation Infrastructure Construction Market Analytics
State transportation departments is rotating procurement priority from greenfield highway expansion toward bridge rehabilitation and multimodal corridor upgrades. Bechtel Corporation leverages its integrated engineering-procurement-construction model to anchor large-scale rail and tunnel programs across the United States. Kiewit Corporation sustains dominant market presence in heavy civil infrastructure through self-perform capabilities and equipment ownership. Granite Construction Inc. competes aggressively in the western states by controlling regional aggregates supply and asphalt production assets.
North America transportation infrastructure construction encompasses the planning, engineering, and physical assembly of roads, bridges, tunnels, and railways using concrete, asphalt, steel, or composite materials, typically requiring load-bearing specifications of 80,000-pound truck equivalents for interstate highway design and seismic resilience ratings for major bridge structures. Its primary purpose is to enable safe, efficient freight and passenger movement across metropolitan, intercity, and international corridors while supporting economic connectivity and supply chain reliability. Roads and bridges command the largest share of public capital allocation, though railway and tunnel segments attract accelerating private investment as Class I railroads expand intermodal capacity and urban agencies pursue underground transit relief. Concrete and asphalt remain the dominant material categories by tonnage deployed, yet steel and composite alternatives gain traction in bridge superstructure applications where extended service life and reduced maintenance downtime justify premium first-cost outlays.
The Federal Highway Administration enforces National Bridge Inspection Standards that mandate biennial structural evaluations, directly sustaining demand for specialized rehabilitation contractors and accelerated bridge construction techniques. EPA stormwater regulations under the Clean Water Act shape erosion control and permeable pavement specifications, while OSHA trenching and excavation standards govern underground construction safety protocols across all project types. Stakeholders must monitor how IIJA formula funding transitions toward competitive discretionary grants and how Buy America domestic content requirements evolve for steel and manufactured products.
Market Dynamics
The Infrastructure Investment and Jobs Act is redirecting state transportation departments toward climate-adaptive bridge rehabilitation and multimodal corridor upgrades, compressing traditional greenfield highway expansion timelines. Federal formula funding transitions are concentrating procurement authority among agencies with demonstrated accelerated construction capabilities.
Growth Catalysts
- IIJA Discretionary Grants:Federal competitive funding pools reward applicants integrating resilient design standards and domestic content compliance, favoring contractors with established Buy America supply chain documentation.
- Biennial Bridge Inspection Mandates:The Federal Highway Administration's National Bridge Inspection Standards sustain continuous demand for specialized rehabilitation contractors and accelerated bridge construction techniques across structurally deficient inventory.
- Class I Railroad Intermodal Expansion:Union Pacific and BNSF Railway are channeling private capital into terminal capacity and tunnel clearances, creating parallel demand streams alongside public highway investment.
Market Restraints
- Steel Price Volatility:Domestic mill capacity constraints and scrap metal supply fluctuations compress margin predictability for bridge superstructure contractors locked into fixed-price design-build contracts.
- Aggregates Supply Concentration:Western states face limited permitted quarry reserves, forcing haul distances exceeding fifty miles and amplifying diesel cost exposure for asphalt paving operations.
- Clean Water Act Compliance Friction:EPA stormwater permitting delays extend pre-construction timelines by six to eighteen months on projects requiring individual NPDES coverage for disturbed acreage.
Strategic Opportunities
- Texas Triangle Megaregion Density:Rapid population growth across Dallas-Houston-San Antonio corridors generates sustained demand for tollway expansions and managed lane conversions with availability-payment structures.
- Composite Material Convergence:Fiber-reinforced polymer bridge decks paired with sensor-embedded concrete create differentiated service-life warranties that command premium pricing in coastal corrosion zones.
- Utility-Relocation Pre-Construction:Early contractor involvement in subsurface utility engineering reduces change-order exposure and positions firms for design-build qualifications on complex urban corridor projects.
Industry Challenges
- Heavy Equipment Operator Scarcity:Union apprenticeship pipelines and military transition programs fail to replenish retiring cohorts, constraining self-perform capacity for pile driving and tunnel boring operations.
- OSHA Trenching Fatality Exposure:Excavation safety violations carry criminal referral risk under enhanced enforcement protocols, elevating insurance premiums and site supervision costs for underground construction segments.
- Legacy Bridge Rating Integration:Load-rating software incompatibility between state DOT systems and federal NBI databases forces manual data reconciliation, delaying rehabilitation prioritization decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Transportation Infrastructure Construction Market |
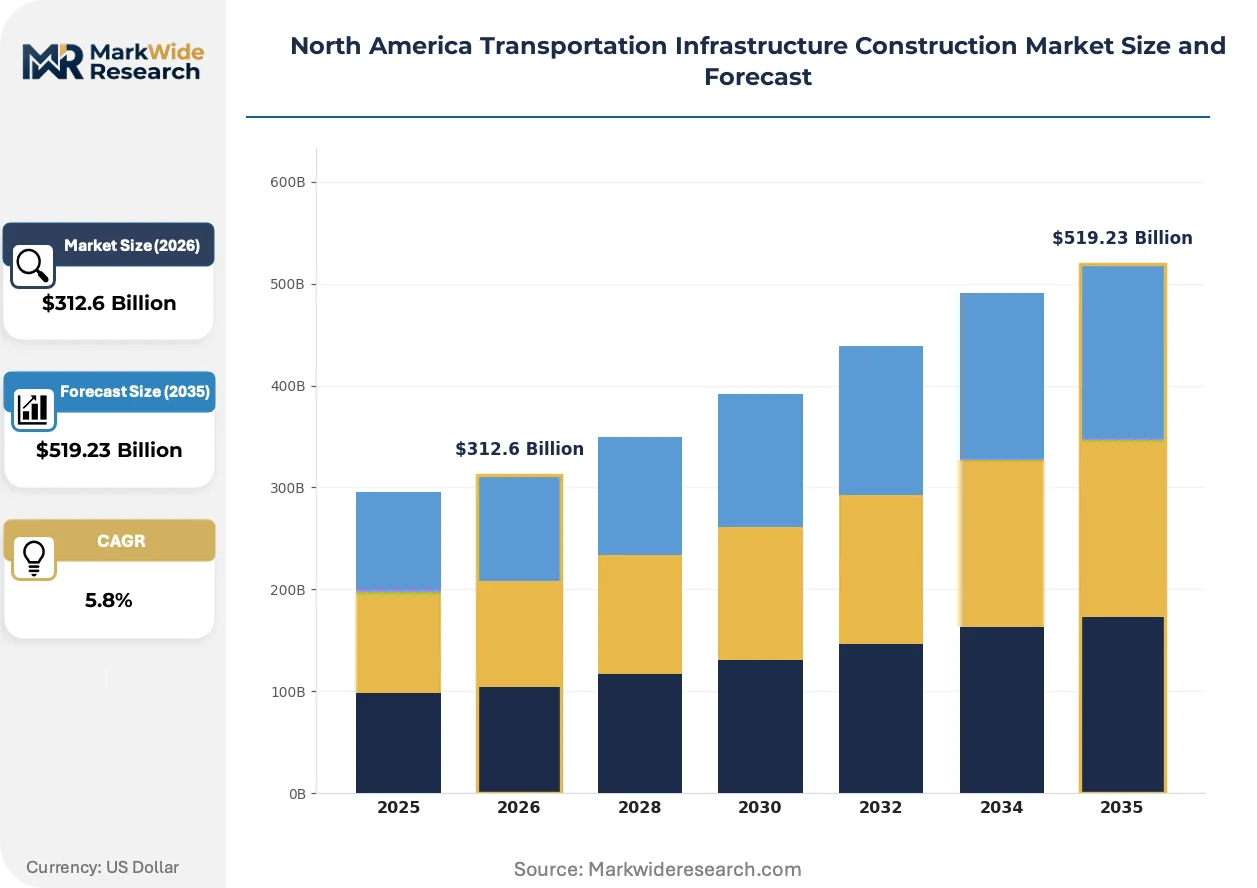
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roads, Bridges, Tunnels, Railways Material Type: Concrete, Asphalt, Steel, Composite Funding Source: Public Funding, Private Investment, PPP, Grants Construction Method: Traditional, Modular, Precast, Hybrid |
| Companies Covered | Bechtel Corporation, ACS Group, Fluor Corporation, AECOM, Kiewit Corporation, Skanska USA, SNC-Lavalin Group Inc., Granite Construction Inc., Tutor Perini Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Transportation Infrastructure Construction Market Evolving Landscape
Digital fabrication and material science advances are compressing traditional construction timelines while federal procurement reforms reward contractors who integrate real-time asset monitoring into long-term maintenance agreements.
Ultra-high-performance concrete is fragmenting conventional cast-in-place bridge deck specifications. State DOTs in coastal hurricane zones are specifying UHPC link slabs and jointless deck systems to eliminate leak paths. The technology is fragmenting competitive positioning between regional ready-mix suppliers and specialized precasters with batch plant certifications.
The Federal Highway Administration's Every Day Counts initiative is accelerating geosynthetic reinforced soil-integrated bridge system adoption. This policy compresses foundation construction from weeks to days on low-volume roadway spans. County and municipal agencies in rural mountain states are the primary adopters, leveraging standardized designs to bypass consultant engineering costs.
Asset management contracts are displacing traditional design-bid-build procurement for major corridor rehabilitation. State DOTs in the Northeast are bundling thirty-year performance warranties with initial construction, transferring pavement and structural maintenance liability to contractor joint ventures. Ontario's Ministry of Transportation provides the reference model for this shift, with Michigan and Pennsylvania agencies adapting contract templates.
North America Transportation Infrastructure Construction Market Segmentation
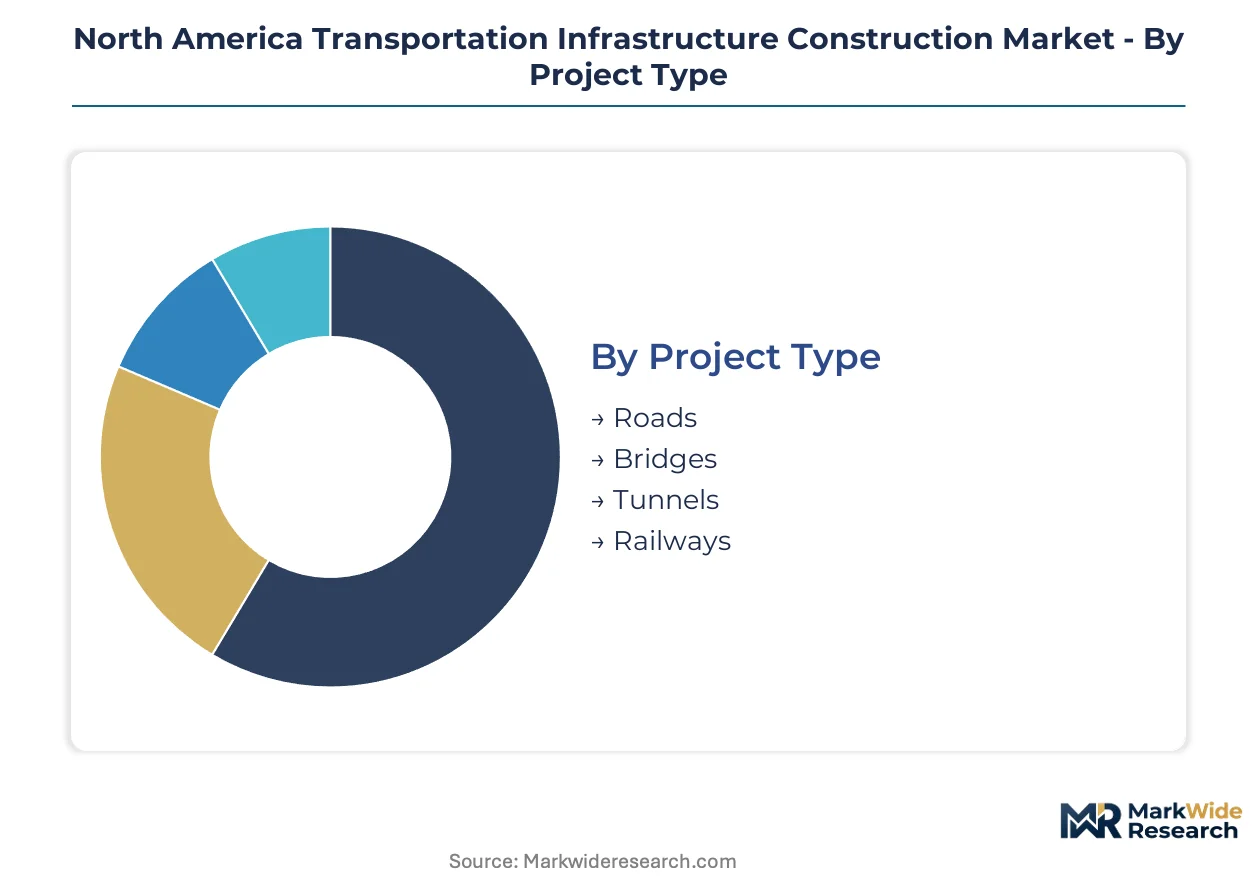
Transportation infrastructure construction segments reflect distinct procurement channels, material supply chains, and regulatory compliance pathways. Understanding these divisions reveals where federal formula funding concentrates versus where private capital and availability-based financing dominate.
Project Type:
Demand flows through distinct procurement channels: state DOTs handle roads and bridges via formula funding, while railroads and tunnel authorities operate through dedicated revenue bonds and private investment structures.
- Roads:Interstate highways and arterial corridors absorb the majority of IIJA formula funding. Texas DOT and Caltrans dominate procurement volume, with managed lane conversions attracting availability-payment structures that shift long-term maintenance liability to contractor consortia.
- Bridges:Structurally deficient inventory drives biennial inspection mandates under FHWA National Bridge Inspection Standards. Accelerated bridge construction techniques compress closure windows on high-traffic spans, commanding premium pricing for specialized contractors with self-perform steel erection capabilities.
- Tunnels:Urban transit relief projects in Seattle, Los Angeles, and Toronto rely on design-build procurement with geotechnical risk transfer. Boring machine mobilization costs and slurry treatment complexity limit viable bidders to heavy civil specialists with equipment ownership.
- Railways:Class I railroads fund intermodal terminal expansion and tunnel clearance programs through operating cash flows. Union Pacific and BNSF Railway procurement bypasses federal environmental review timelines that constrain public highway projects.
Roads dominate installed base by lane-miles. Railways is where expansion concentrates as freight intermodal growth outpaces highway capacity additions.
Material Type:
Material selection tracks project location, load specifications, and lifecycle cost modeling rather than first-cost optimization alone.
- Concrete:Ultra-high-performance formulations with compressive strengths exceeding 18,000 psi are displacing conventional cast-in-place decks in coastal hurricane zones. UHPC link slabs eliminate expansion joints, reducing chloride ingress and extending service intervals.
- Asphalt:Warm-mix and porous asphalt specifications respond to EPA stormwater compliance pressures in the Great Lakes and Chesapeake watersheds. Western states face haul distance penalties exceeding fifty miles where permitted quarry reserves are depleted.
- Steel:Domestic mill capacity constraints and scrap supply volatility compress margin predictability for bridge superstructure contractors. Buy America compliance documentation requirements favor established fabricators with certified supply chain audit trails.
- Composite:Fiber-reinforced polymer bridge decks paired with sensor-embedded concrete enable differentiated service-life warranties. Coastal corrosion environments in Florida and Louisiana justify premium first-cost outlays through reduced maintenance downtime.
Concrete and asphalt command tonnage leadership. Composite is climbing the fastest as state DOTs pilot performance-based specifications in aggressive environments.
Funding Source:
Capital structure determines project velocity, risk allocation, and contractor qualification requirements across the procurement landscape.
- Public Funding:FHWA formula distributions flow through state DOTs with standardized design-bid-build procurement. Michigan and Pennsylvania are adapting Ontario's asset management contract templates that bundle thirty-year performance warranties with initial construction.
- Private Investment:Class I railroads deploy operating cash flows without federal environmental review constraints. Capital deployment velocity exceeds public highway timelines by eighteen to thirty-six months on comparable project scales.
- PPP:Availability-payment structures for managed lane conversions transfer demand risk to public sponsors while contractor consortia assume construction and maintenance performance obligations. Texas Triangle megaregion density sustains tollway expansion pipelines.
- Grants:IIJA discretionary competitive pools reward resilient design standards and domestic content compliance. Applicants with documented Buy America supply chains and accelerated construction capabilities secure preferential scoring.
Public funding retains volume dominance. PPP is gaining share fastest as state DOTs confront maintenance liability backlogs and political resistance to fuel tax increases.
Construction Method:
Method selection reflects schedule compression pressures, site constraints, and labor availability rather than pure cost minimization.
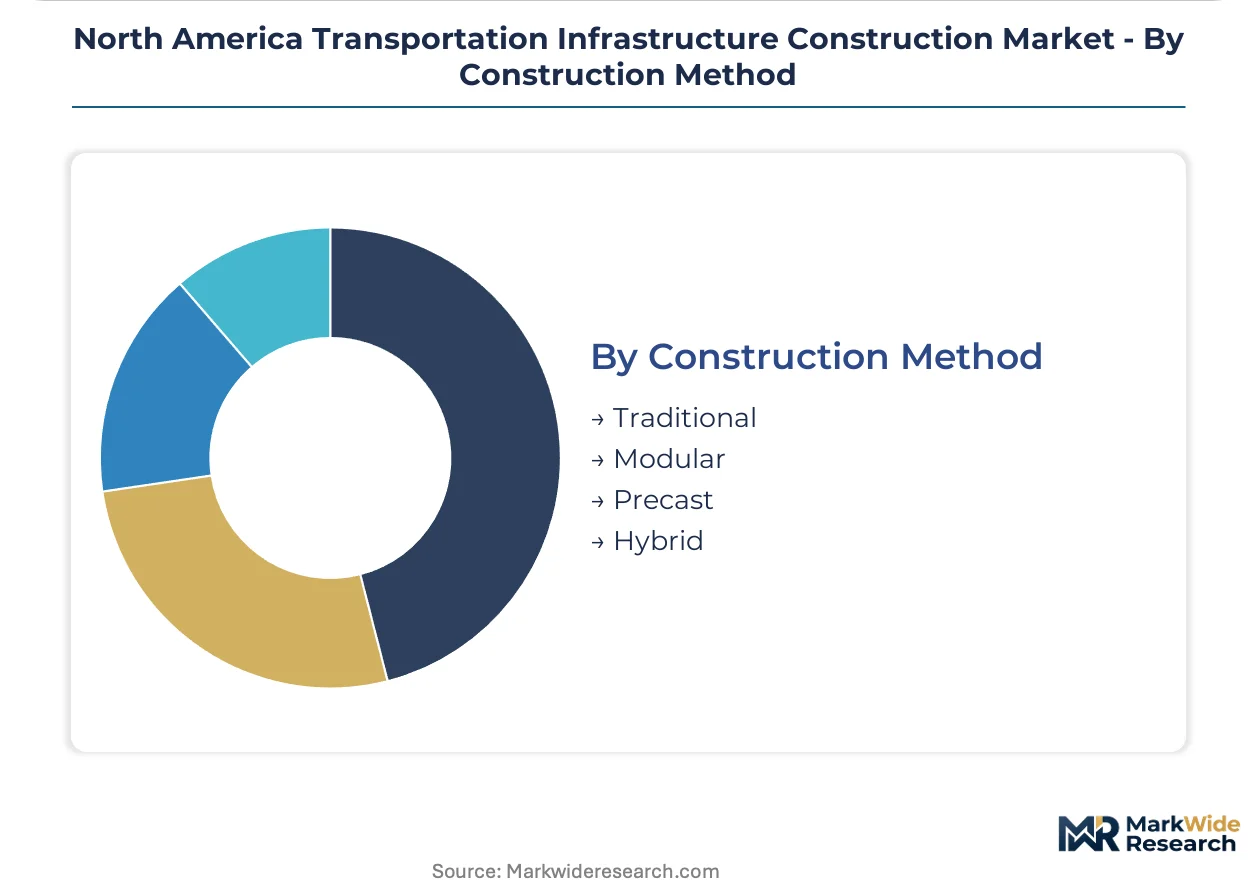
- Traditional:Cast-in-place concrete and stick-built steel erection remain default specifications for rural and low-traffic applications. County and municipal agencies leverage standardized designs to bypass consultant engineering costs on simple span replacements.
- Modular:Prefabricated bridge elements and systems compress on-site construction from weeks to days. FHWA Every Day Counts initiative accelerates adoption among agencies with limited in-house engineering staff.
- Precast:Off-site fabrication with plant-controlled curing conditions delivers consistent quality for high-volume repetitive elements. Specialized precasters with batch plant certifications capture premium positioning as UHPC specifications fragment competitive dynamics.
- Hybrid:Combinations of precast substructures with cast-in-place superstructures balance schedule acceleration and structural integration. Complex urban corridor projects with utility conflict matrices favor early contractor involvement in subsurface utility engineering.
Traditional methods retain installed base leadership. Modular is expanding most quickly as agencies prioritize traffic impact minimization and accelerated project delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractor capacity concentrates in jurisdictions with sustained IIJA funding flows and established accelerated construction protocols. State DOT procurement authority increasingly favors agencies with demonstrated design-build qualifications and Buy America compliance documentation.
United States
The Texas Triangle megaregion generates sustained demand for tollway expansions and managed lane conversions with availability-payment structures. FHWA formula funding transitions concentrate procurement among agencies with accelerated bridge construction capabilities. California's Southern California megaregion anchors heavy civil investment as Caltrans pursues seismic retrofit programs and corridor rehabilitation.
Canada
The Ontario-Quebec corridor drives transnational freight corridor upgrades and St. Lawrence Seaway bridge replacements. Infrastructure Canada channels federal funding toward climate-adaptive design standards through the National Trade Corridors Fund. Toronto's transit expansion and Montreal's Champlain Bridge corridor sustain demand for tunnel and bridge specialists.
Mexico
Northern border states concentrate logistics corridor investment tied to nearshoring manufacturing relocation. SCT infrastructure programs prioritize freight rail capacity expansion along the Mexico City-Querétaro-Monterrey axis. The T-MEC trade framework sustains demand for interstate highway modernization at Laredo-Nuevo Laredo and Otay Mesa-Tijuana crossings.
North America Transportation Infrastructure Construction Market Competitive Landscape
Concentration sits with integrated engineering-procurement-construction firms and heavy civil specialists with self-perform capabilities. The vendor base stratifies across three tiers: global conglomerates with diversified infrastructure portfolios, regional heavy civil contractors with equipment ownership, and specialized bridge or tunnel firms with niche technical qualifications. Strategic moves center on design-build consortium formation and asset management contract bundling that transfers long-term maintenance liability to contractor joint ventures.
Among integrated EPC providers, Bechtel Corporation and Fluor Corporation exemplify the global conglomerate archetype with diversified infrastructure portfolios. Kiewit Corporation and Granite Construction Inc. represent the regional heavy civil specialist tier where self-perform capabilities and equipment ownership anchor competitive positioning. These firms occupy positions where accelerated construction qualifications and Buy America supply chain documentation determine procurement scoring outcomes.
| Leading Market Players |
|---|
| Bechtel Corporation |
| ACS Group |
| Fluor Corporation |
| AECOM |
| Kiewit Corporation |
| Skanska USA |
| SNC-Lavalin Group Inc. |
| Granite Construction Inc. |
| Tutor Perini Corporation |
| Others |
Value Network & Pricing Analysis
Ultra-high-performance concrete displacement of conventional cast-in-place bridge decks simultaneously redraws supply geography toward certified precast batch plants and compresses pricing premiums for regional ready-mix suppliers lacking UHPC qualifications. This substitution dynamic concentrates procurement leverage with specialized fabricators while forcing margin compression on legacy concrete suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs contractor procurement. Price differentiation rests on Buy America compliance certification and accelerated construction capability documentation. Cost compression in standard-tier asphalt paving intensifies because diesel haul penalties exceed fifty miles in Western states with depleted quarry reserves. Municipal agencies exhibit highest price sensitivity on rural low-volume spans, while state DOTs accept premium pricing for coastal hurricane-zone UHPC specifications.
Supply Chain Analysis
Strategic stockpiling of steel bridge components dominates procurement behavior as domestic mill capacity constraints and scrap supply volatility force contractors to lock material positions early. Supply concentrates in the United States, Canada, and Mexico under T-MEC trade framework provisions. Raw material dependencies center on Portland cement, steel rebar, and polymer composites. Single-source vulnerability pervades Western aggregates markets where permitted reserves are exhausted. Distribution runs through state DOT central procurement offices and Class I railroad direct vendor programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against composite material convergence that threatens conventional steel and concrete positioning. Fiber-reinforced polymer bridge decks paired with sensor-embedded concrete represent the encroaching substitute threat.
For Market Incumbents: Compound design-build consortium formation with asset management contract bundling to transfer long-term maintenance liability. Secure UHPC batch plant certifications before coastal state DOTs finalize performance-based specifications. Vertical integration into regional aggregates supply anchors margin defense against haul-distance penalties. For New Entrants and Emerging Players: Anchor in Texas Triangle tollway expansions where availability-payment structures bypass traditional low-bid procurement barriers. Target utility-relocation pre-construction services for complex urban corridor projects with subsurface conflict matrices. Pursue accelerated bridge construction qualifications to access FHWA Every Day Counts initiative pipelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors heavy civil specialists with self-perform equipment ownership. Long-term viability hinges on contractors capturing thirty-year performance warranty contracts that displace traditional design-bid-build procurement. Watch IIJA discretionary grant scoring criteria evolution as the inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| UHPC Batch Plant Certification | Captures premium positioning as coastal state DOTs specify jointless deck systems. |
| Design-Build Consortium Formation | Qualifies contractors for geotechnical risk transfer on urban tunnel programs. |
| Asset Management Contract Bundling | Transfers pavement maintenance liability per Ontario Ministry of Transportation templates. |
| Buy America Supply Chain Documentation | Secures preferential scoring in IIJA discretionary competitive grant pools. |
| Accelerated Bridge Construction Capability | Commands premium pricing for high-traffic span closures under FHWA mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FHWA bridge inventory databases, state DOT procurement records, EPA NPDES permitting filings, and Class I railroad capital expenditure disclosures. Primary interviews incorporated state transportation department procurement officers, heavy civil contractor project executives, precast concrete plant managers, and bridge design engineers. Secondary validation drew from SEC 10-K filings, Infrastructure Investment and Jobs Act funding distribution reports, and American Association of State Highway and Transportation Officials guidance documents. Bottom-up project pipeline aggregation triangulates against top-down federal funding allocation analysis.
Segmentation dimensions modeled include project type, material category, funding source, and construction method across the projection horizon. The analytical framework incorporates load-bearing specification tiers, seismic resilience ratings, and climate-adaptive design standard adoption curves. CAGRs derive from project-level procurement volume aggregation and federal formula funding transition trajectories. Forecast inputs integrate IIJA discretionary grant award velocities and Class I railroad intermodal terminal expansion announcements.
Material uncertainties — federal funding reauthorization delays, domestic steel mill capacity expansions, and EPA stormwater permitting timeline compression — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained IIJA implementation and stable Buy America compliance thresholds. Revision becomes warranted when IIJA formula funding transitions toward competitive discretionary grants at rates exceeding baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
Overhead Conductor Market
Infrastructure Construction
United States Transportation Infrastructure Construction Market
Infrastructure Construction
China Transportation Infrastructure Construction Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
Qatar Transportation Infrastructure Construction Market
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
Africa Pipeline Construction Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
Vietnam Infrastructure Market