
 Smart Pipeline Networks Market | 2026-2036
Smart Pipeline Networks Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pipeline Networks Market Insights
The EU Green Deal is restructuring capital allocation across European pipeline infrastructure, compelling operators to replace legacy monitoring with continuous emission-tracking systems. Siemens AG leverages its industrial automation portfolio to dominate digital twin deployments for gas transmission corridors. Schneider Electric SE anchors its position through edge computing architectures that process sensor data at compressor stations. Honeywell International Inc. competes on integrated SCADA-to-analytics platforms that unify control rooms across multi-jurisdictional networks.
Smart pipeline networks encompass sensor-embedded conduit systems, communication backbones, and predictive software layers that monitor pressure, flow, temperature, and structural integrity in real time, typically operating at data refresh rates below 100 milliseconds to enable automated valve actuation. Their primary purpose is to eliminate unplanned outages, reduce commodity losses, and prevent catastrophic failures in energy and fluid transport infrastructure. SCADA systems and digital twins capture the dominant share of technology spending, as operators prioritize centralized visibility over distributed intelligence. Wireless sensor networks represent the fastest-expanding technology category, driven by battery-life improvements and mesh-protocol reliability in remote terrain. Among applications, gas transmission commands the largest absolute investment, while water supply infrastructure shows the steepest adoption curve as drought-stressed municipalities retrofit aging distribution grids.
The EPA enforces methane performance standards that mandate optical gas imaging surveys and continuous monitoring at new and modified compressor stations, directly expanding the addressable market for fiber optic sensing and machine learning analytics. The EU AI Act imposes risk-classification requirements on automated pipeline control systems, compelling vendors to document algorithmic decision pathways for safety-critical valve operations. Pipeline operators, energy producers, and municipal utilities must now evaluate vendor compliance portfolios alongside technical specifications when procuring next-generation monitoring infrastructure.
Market Dynamics
The EU Green Deal's methane emission thresholds are forcing pipeline operators to retire intermittent inspection regimes in favor of continuous fiber-optic and acoustic monitoring systems, compressing procurement cycles and elevating compliance documentation requirements.
Growth Catalysts
- EPA Methane Performance Standards:Mandatory optical gas imaging and continuous monitoring at compressor stations expands demand for distributed sensing arrays and machine-learning analytics platforms.
- Saudi Aramco trunk line mandates:Real-time leak detection requirements across the kingdom's hydrocarbon transmission network accelerate sensor deployment in high-temperature, high-pressure environments.
- Wireless sensor networks:Battery-life improvements and mesh-protocol reliability enable monitoring in remote terrain previously unreachable by cabled infrastructure.
Market Restraints
- Fiber optic sensing hardware:Specialized cable and interrogator unit costs limit retrofit economics for municipal water utilities with constrained capital budgets.
- Sensor supply concentration:MEMS pressure transducer manufacturing clusters in East Asia create vulnerability to trade flow disruptions and extended lead times.
- Cybersecurity compliance friction:The EU AI Act's risk-classification requirements for automated valve control systems extend vendor qualification timelines and documentation burdens.
Strategic Opportunities
- India water distribution grids:Aging municipal infrastructure and federal smart city funding create white space for pressure-monitoring retrofits in drought-stressed states.
- Hydrogen blending readiness:Pipeline operators preparing for hydrogen-natural gas mixtures require upgraded flow sensors and material compatibility testing protocols.
- Edge-to-cloud convergence:Integration of compressor station edge computing with centralized digital twin platforms enables predictive maintenance contracts as recurring revenue streams.
Industry Challenges
- SCADA integration complexity:Multi-vendor control room unification demands specialized protocol translation and cybersecurity hardening that stretches internal engineering teams.
- Certification timeline compression:The EU AI Act's documentation requirements for algorithmic decision pathways in safety-critical systems collide with operator urgency to deploy automated response capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pipeline Networks Market |
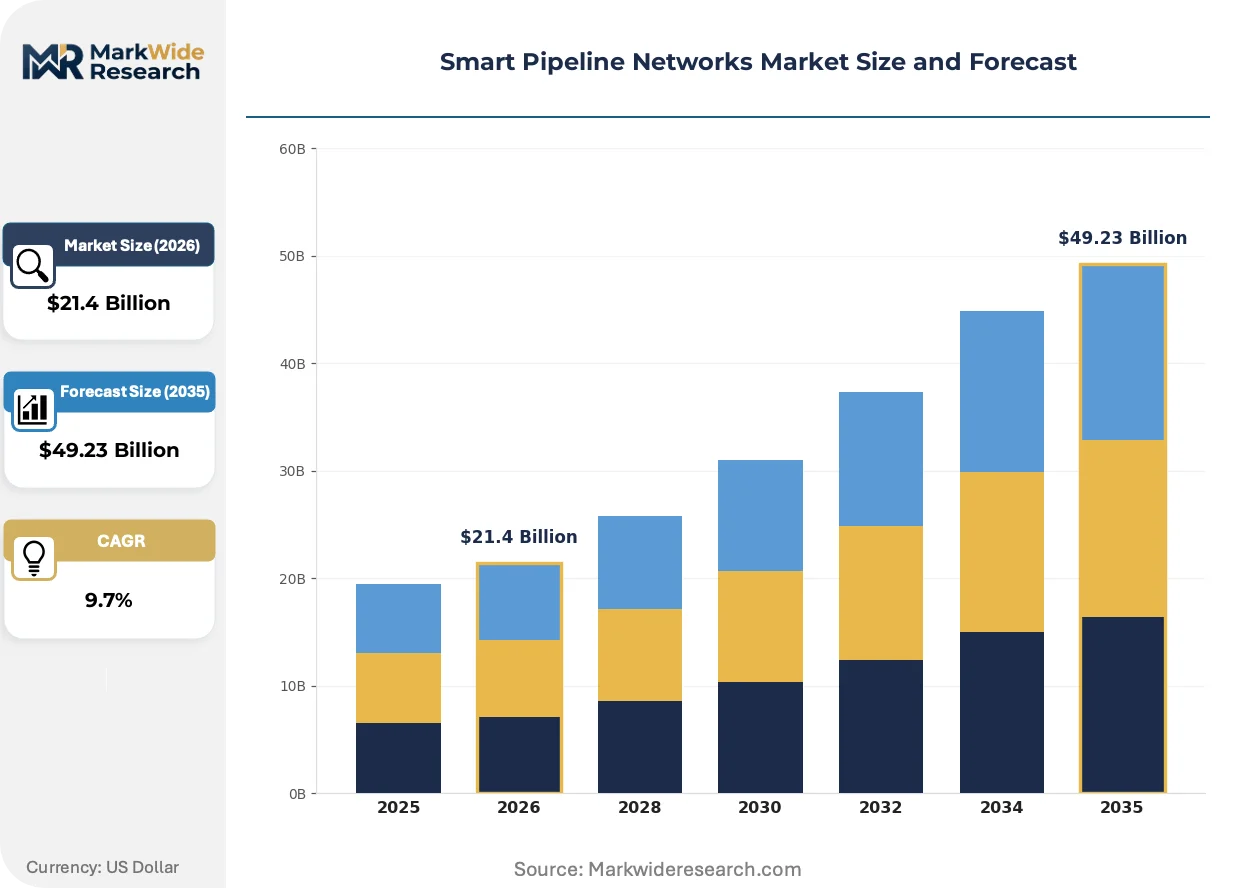
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $49.23 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wireless Sensor Networks, SCADA Systems, Fiber Optic Sensing, Digital Twins, Machine Learning Analytics, Edge Computing Application: Oil Transport, Gas Transmission, Water Supply, Chemical Distribution, District Heating, Wastewater Management End User: Pipeline Operators, Energy Producers, Municipal Utilities, Chemical Manufacturers, Infrastructure Managers, Water Authorities Deployment Type: Underground Pipelines, Submarine Pipelines, Onshore Infrastructures, Compressor Stations, Metering Stations, Distribution Terminals |
| Companies Covered | Siemens AG, Schneider Electric SE, Honeywell International Inc., ABB Ltd., Emerson Electric Co., General Electric Company, Rockwell Automation, Inc., Yokogawa Electric Corporation, Xylem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pipeline Networks Market Trends and Innovations
Pipeline monitoring is migrating from scheduled physical inspections toward autonomous sensor networks that trigger immediate operator alerts and automated valve actuation, collapsing response windows from days to seconds.
Fiber optic distributed acoustic sensing is integrating vibration pattern recognition along entire conduit lengths, replacing point-source pressure transducers. Gas transmission operators in the North Sea and Permian Basin are deploying these systems at scale, with refresh rates below 100 milliseconds enabling automated isolation of rupture events before commodity volumes escalate.
The EU AI Act imposes mandatory risk documentation on machine learning models governing safety-critical valve operations. Vendors must now submit algorithmic decision pathway records to notified bodies, extending product development cycles but creating compliance moats for firms with established regulatory affairs capabilities.
Asset owners are consolidating vendor relationships to reduce integration fragmentation, preferring single-source SCADA-to-analytics platforms over best-of-breed component assembly. This concentration is most pronounced in Germany and the Netherlands, where transmission system operators face simultaneous pressure from the EU Green Deal timelines and domestic grid decarbonization mandates.
Smart Pipeline Networks Market Segmentation
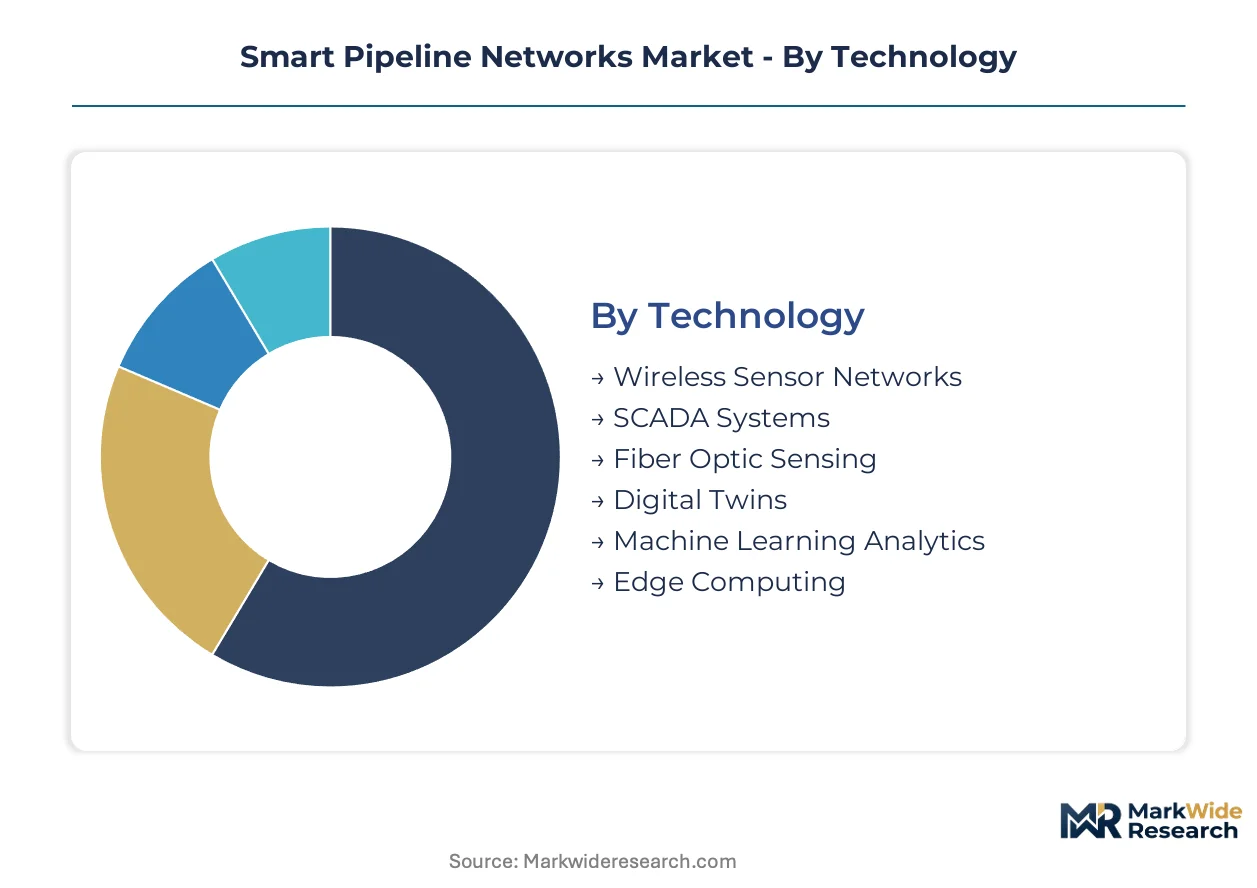
Smart pipeline networks fragment across four intersecting dimensions that determine procurement priorities and vendor positioning. Technology choices dictate integration complexity, while application type drives regulatory exposure and sensor specification requirements.
Technology:
Supply concentrates in industrial automation conglomerates with bundled platform offerings rather than point-solution specialists.
- SCADA Systems:Centralized control architectures that aggregate pressure, flow, and temperature telemetry across multi-kilometer networks. Demand clusters in Saudi Aramco and ADNOC trunk line retrofits where compressor station visibility is mandatory under national methane mandates.
- Digital Twins:Physics-based simulation layers that mirror physical pipeline behavior for predictive maintenance. Siemens AG dominates deployments across German and Dutch transmission corridors where EU Green Deal timelines compress procurement cycles.
- Wireless Sensor Networks:Mesh-protocol arrays enabling monitoring in remote terrain without cabled infrastructure. Battery-life improvements are expanding addressable geography.
- Fiber Optic Sensing:Distributed acoustic and temperature measurement along entire conduit lengths using specialized cable and interrogator units.
- Machine Learning Analytics:Pattern recognition algorithms for leak detection and anomaly classification, now subject to EU AI Act documentation requirements.
- Edge Computing:Localized data processing at compressor stations to reduce latency for automated valve actuation.
Today's leader: SCADA Systems. Tomorrow's challenger: Digital Twins.
Application:
Cost tier differentiation separates high-complexity hydrocarbon transport from municipal water retrofit economics.
- Gas Transmission:High-pressure, high-temperature networks requiring continuous methane monitoring and automated isolation capabilities. EU Green Deal thresholds and EPA performance standards are restructuring procurement criteria across European and North American corridors.
- Water Supply:Aging distribution grids in drought-stressed regions where pressure-monitoring retrofits address non-revenue water losses. India smart city funding is accelerating deployment in Maharashtra and Gujarat states.
- Oil Transport:Crude and refined product pipelines with leak detection mandates in Saudi Arabia and the UAE.
- Chemical Distribution:Corrosive fluid networks requiring material-compatible sensors and specialized safety protocols.
- District Heating:Urban thermal distribution systems with seasonal load variation and temperature cycling stress.
- Wastewater Management:Gravity-fed and pressurized collection systems with hydrogen sulfide corrosion monitoring requirements.
Gas Transmission commands absolute investment volume; Water Supply offers the steepest expansion trajectory.
End User:
Customer type determines budget authority, technical sophistication, and regulatory compliance burden.
- Pipeline Operators:Transmission system owners with centralized engineering teams and multi-decade asset horizons. German and Dutch operators face simultaneous EU Green Deal and domestic decarbonization pressures.
- Energy Producers:Integrated oil and gas companies with captive pipeline networks and internal SCADA standardization.
- Municipal Utilities:City-owned water authorities with constrained capital budgets and federal funding dependency.
- Chemical Manufacturers:Process industry operators with hazardous material transport and site-specific safety protocols.
- Infrastructure Managers:Third-party asset operators with performance-based contracts and outcome accountability.
- Water Authorities:Regional and national entities in arid climates mandating sensor-integrated distribution systems.
Pipeline Operators consolidate vendor relationships; Municipal Utilities fragment procurement across funding cycles.
Deployment Type:
Geographic and structural context dictates sensor environmental protection, communication backbone, and maintenance access requirements.
- Underground Pipelines:Buried conduit systems requiring subsurface sensor installation and cathodic protection integration.
- Submarine Pipelines:Offshore and subsea installations with pressure-rated housings and satellite or acoustic communication links.
- Onshore Infrastructures:Surface-mounted pipeline segments with accessible maintenance points and cellular connectivity.
- Compressor Stations:Mechanical facilities with rotating equipment vibration monitoring and EPA-mandated continuous emission tracking.
- Metering Stations:Custody transfer points with flow measurement accuracy requirements and fiscal metering integration.
- Distribution Terminals:Multi-product delivery hubs with valve automation and inventory management system interfaces.
Compressor Stations anchor near-term sensor density; Submarine Pipelines represent the highest technical barrier to entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in industrial automation hubs anchor regional deployment capacity for sensor-integrated pipeline systems. Munich, Houston, and Singapore host concentrated workforces capable of integrating fiber-optic sensing with legacy SCADA architectures. These clusters determine which geographies absorb technology transfer first.
United States
EPA methane performance standards mandate continuous monitoring at compressor stations across the Permian Basin and Appalachian shale corridors. The IRA's clean energy tax credits accelerate fiber-optic sensing retrofits in Texas and Louisiana trunk line networks. Houston anchors engineering deployment teams serving midstream operators under federal emission thresholds.
Germany
EU Green Deal timelines compress procurement cycles for transmission system operators managing the SoutH2 hydrogen corridor preparations. The EU AI Act imposes documentation requirements on automated valve control systems deployed across Bavarian and North Rhine-Westphalian pipeline intersections. Siemens AG leverages Munich-based engineering capacity to dominate digital twin implementations.
Saudi Arabia
Saudi Aramco's real-time leak detection mandates drive sensor deployment across the kingdom's high-temperature, high-pressure hydrocarbon trunk lines. SFDA-equivalent process safety regulations govern hazardous material monitoring protocols in Eastern Province processing clusters. Dhahran-based technical centers coordinate procurement for remote desert transmission corridors.
India
Smart city funding under the Ministry of Housing and Urban Affairs accelerates pressure-monitoring retrofits in Maharashtra and Gujarat municipal water grids. BIS certification requirements for industrial IoT devices shape vendor qualification timelines for distribution network upgrades. Mumbai and Ahmedabad anchor implementation capacity for drought-stressed western state utilities.
Netherlands
Domestic grid decarbonization mandates intersect with EU Green Deal compliance deadlines for Gasunie transmission corridors. REACH chemical safety regulations influence sensor material specifications for hydrogen-blending readiness programs. Rotterdam and Groningen host concentrated engineering teams integrating edge computing at compressor stations.
Smart Pipeline Networks Market Competitive Landscape
Capital-heavy industrial automation conglomerates compete with asset-light sensor specialists for procurement decisions in pipeline infrastructure. The vendor base concentrates around bundled platform providers rather than point-solution developers, creating tiered competitive dynamics. Three archetypes dominate: diversified automation conglomerates with SCADA-to-analytics integration, specialized sensing hardware manufacturers, and edge computing architects with compressor station deployments. Strategic moves center on vendor relationship consolidation by asset owners and M&A activity to close portfolio gaps in fiber-optic interrogation systems.
Within the diversified automation tier, Siemens AG, Schneider Electric SE, and Honeywell International Inc. anchor competitive positioning through bundled platform offerings. Siemens AG exemplifies the industrial conglomerate archetype leveraging Munich-based engineering density. Schneider Electric SE occupies a position emphasizing edge computing architectures for distributed intelligence. Honeywell International Inc. represents integrated control room unification across multi-jurisdictional networks. These three entities collectively illustrate how regulatory compliance portfolios now outweigh pure technical specifications in procurement evaluations.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric SE |
| Honeywell International Inc. |
| ABB Ltd. |
| Emerson Electric Co. |
| General Electric Company |
| Rockwell Automation, Inc. |
| Yokogawa Electric Corporation |
| Xylem |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between EU AI Act-compliant control systems and legacy SCADA architectures manifests in both pricing stratification and supply chain sourcing patterns, with compliant platforms commanding premium positioning while non-compliant hardware faces accelerated obsolescence in European procurement cycles.
Pricing Analysis
Bundled platform-versus-unbundled component splits dominate pricing architecture, with Siemens AG and Schneider Electric SE capturing premium tiers through integrated SCADA-to-analytics offerings while point-solution vendors compete on discrete sensor hardware. Price differentiation rests on certification tier—EU AI Act documentation capabilities versus baseline CE marking—and vertical integration depth in fiber-optic interrogator manufacturing. Cost compression in municipal water utility segments intensifies as Indian smart city funding caps project budgets, while pipeline operators in Saudi Aramco networks exhibit lowest price sensitivity due to national mandate urgency and hydrocarbon revenue backing.
Supply Chain Analysis
EU AI Act qualification requirements gate supplier eligibility, compressing vendor pools to industrial automation conglomerates with established notified body relationships. MEMS pressure transducer manufacturing clusters in Taiwan, South Korea, and Japan anchor component supply, while specialized fiber-optic cable production centers in Germany and the United States feed distributed sensing deployments. Supply chain vulnerability concentrates in single-source dependency for high-temperature interrogator units. Distribution runs through authorized system integrators with compressor station deployment expertise rather than direct OEM-to-operator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in smart pipeline networks hinge on software-layer value capture as hardware commoditization accelerates, with predictive maintenance contracts and digital twin subscriptions displacing capital equipment sales as primary revenue drivers.
For Market Incumbents: Anticipate regulatory documentation burdens becoming permanent competitive moats by accelerating EU AI Act compliance investments ahead of smaller rivals. Defensive positioning requires backward integration into fiber-optic interrogator manufacturing to reduce exposure to East Asian component lead times, while channel control through certified system integrator networks limits emerging player access to Saudi Aramco and ADNOC trunk line procurements. For New Entrants and Emerging Players: Enter via white-space targeting in Indian municipal water distribution grids, where BIS certification pathways remain less congested than European notified body queues and federal smart city funding creates procurement velocity. Maharashtra and Gujarat states offer most penetrable entry points given drought-stress urgency and existing pilot program infrastructure. Go-to-market positioning should emphasize wireless sensor network deployments that bypass fiber-optic retrofit cost barriers constraining incumbent platform sales. For Investors and Strategic Acquirers: Consolidation pressure builds where EU AI Act documentation capabilities fragment across sub-scale sensor specialists unable to sustain regulatory affairs overhead. Long-term viability favors platforms with recurring revenue foundations in predictive maintenance contracts and edge-to-cloud convergence architectures. Acquisition target archetypes include fiber-optic sensing hardware specialists with interrogator unit IP and established compressor station deployment track records. Signal to watch: ADNOC and Saudi Aramco procurement standardization around single-source platform requirements.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Documentation capabilities create procurement moats in German and Dutch transmission corridors. |
| Backward Integration into Interrogator Manufacturing | In-house production of fiber-optic sensing hardware reduces East Asian supply vulnerability. |
| Predictive Maintenance Contract Scaling | Recurring revenue streams from digital twin subscriptions displace capital equipment cyclicality. |
| Wireless Sensor Network Geographic Expansion | Battery-life improvements enable addressable market expansion into remote Indian and Middle Eastern terrain. |
| Hydrogen Blending Readiness Programs | Upgraded flow sensors and material compatibility testing capture Gasunie SoutH2 corridor preparations. |
Research Methodology
Multiple input streams—primary interviews with pipeline control engineers, SCADA procurement officers, and municipal utility directors; secondary validation through EPA methane performance standard filings, EU Green Deal implementation documents, and Saudi Aramco technical procurement specifications—were reconciled through bottom-up sensor deployment quantification and top-down infrastructure investment aggregation.
Data-stream reconciliation anchored the analytical framework across technology, application, end-user, and deployment type segmentations, with CAGRs derived from infrastructure replacement cycle timing and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporated compressor station buildout schedules in the Permian Basin and smart city funding allocation patterns in Maharashtra and Gujarat states.
Inputs from notified body certification databases and national oil company procurement portals were available through the study window; gaps in real-time wireless sensor network field performance data introduce uncertainty bands around battery-life improvement trajectories. Forecasts reflect documented assumptions regarding EU AI Act implementation timelines and EPA enforcement continuity. A model refresh is warranted upon material change in hydrogen blending protocol standardization or MEMS transducer supply chain disruption severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Infrastructure
Smart Infrastructure Market
Smart Infrastructure
Smart Concrete Market
Smart Infrastructure
Construction 4.0 Market
Smart Infrastructure
Global IoT in Construction Market
Smart Infrastructure
Asia-Pacific Smart Building Market
Smart Infrastructure
Smart Airport Construction Market
Smart Infrastructure
US Smart Building Market
Smart Infrastructure
Smart Hydrants Market
Smart Infrastructure
Infrastructure Solution Integration Service Market
Smart Infrastructure
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market
Smart Infrastructure
IoT in Commercial Construction Market
Smart Infrastructure
Big Data in Construction Market
Smart Infrastructure
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market