
 Moisture Resistant Gypsum Board Market | 2026-2036
Moisture Resistant Gypsum Board Market Size, Share, and Industry Trends Forecast 2026-2036
Moisture Resistant Gypsum Board Market Insights
North American gypsum producers is broadening output of treated-core boards to serve elevated specification rates across Gulf Coast and Southeast Atlantic states. Georgia-Pacific Building Products leverages its integrated paper-faced liner mills to control raw material quality from pulp to finished board. Saint-Gobain sustains a dense plant network across the eastern seaboard that anchors regional supply security. Knauf competes through specialized formulations targeting commercial bathroom and kitchen envelope assemblies.
Moisture resistant gypsum board consists of a gypsum dihydrate core impregnated with water-repellent additives, typically silicone or wax emulsions, then encased in moisture-resistant green-tinted paper facers; manufacturers engineer it to achieve core absorption below five percent when tested per ASTM C473 for applications in high-humidity interior environments. The product type dimension shows fire-resistant variants commanding premium positioning due to layered glass-mat facers that satisfy multifamily and hospitality code requirements, while standard moisture-resistant grades occupy volume leadership in residential basement finishing. Application segmentation reveals healthcare settings generating the fastest specification velocity as Joint Commission standards and FGI Guidelines for Design and Construction of Hospitals mandate moisture-impervious wall assemblies in sterile processing and patient shower zones.
ASTM International governs physical property testing through C1396 and C473 protocols that determine board flexural strength and water absorption thresholds, while the EPA oversees VOC emissions from adhesive and coating adjuncts through TSCA Title VI formaldehyde standards. OSHA construction standards indirectly shape demand by mandating mold remediation protocols that elevate replacement rates in water-damaged commercial buildings. Stakeholders must monitor evolving state-level stretch codes in California and New York that increasingly reference enhanced moisture performance as prerequisite for green building certification tiering.
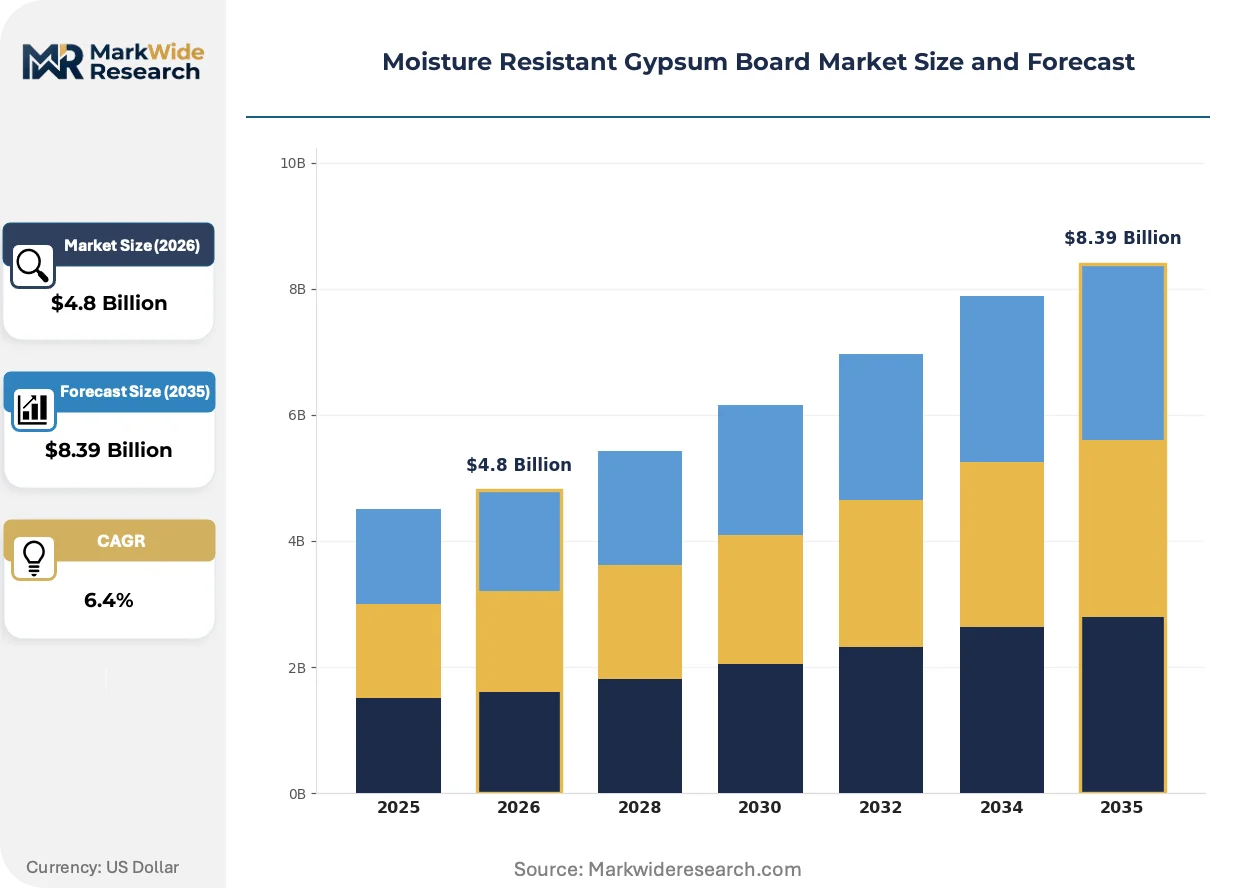
Market Dynamics
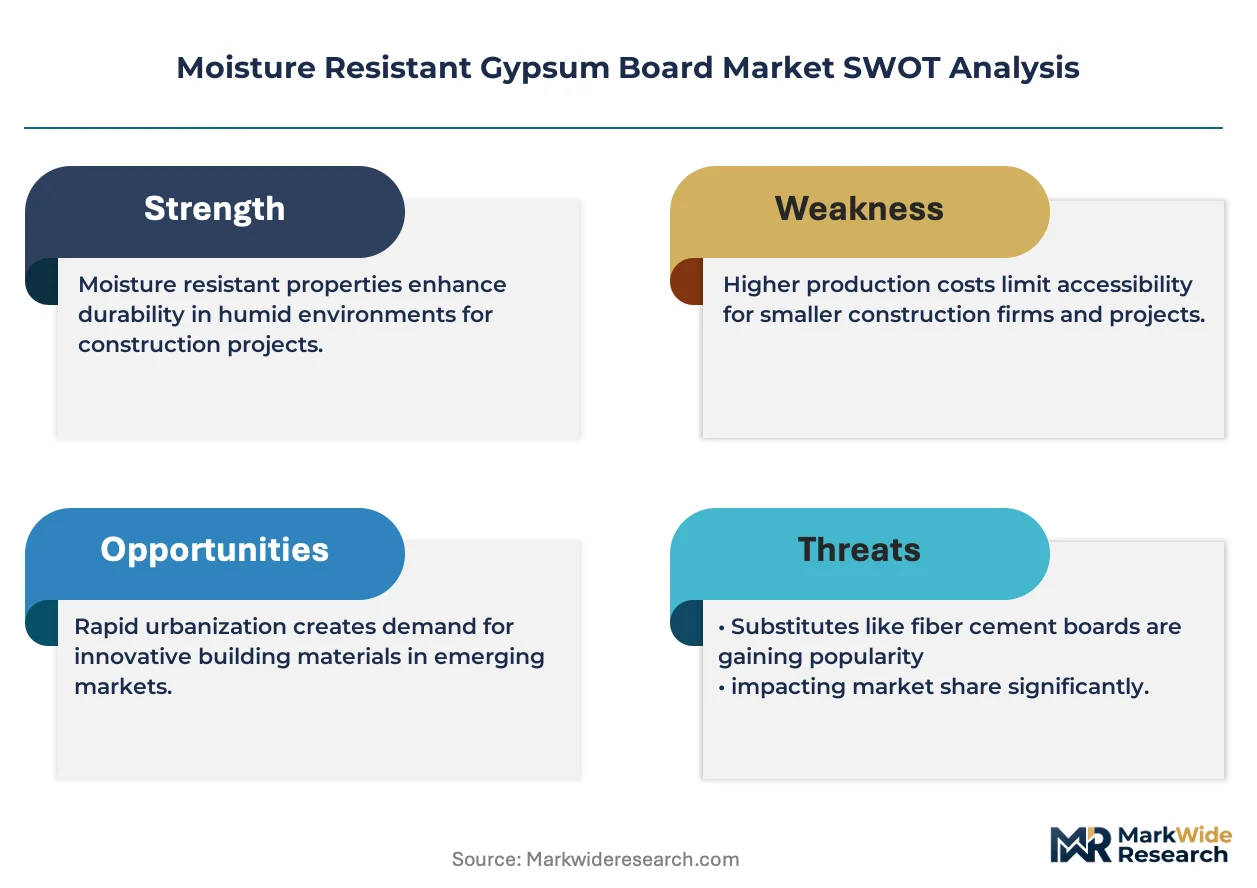
Building code ratchets across hurricane-prone coastal zones are forcing rapid specification upgrades from standard to moisture-resistant gypsum cores, compressing product lifecycles and rewiring contractor procurement habits.
Growth Catalysts
- FGI Guidelines for Design and Construction of Hospitals:Mandates for moisture-impervious wall assemblies in sterile processing zones drive specification velocity in post-acute care construction.
- Silicone-treated core formulations:ASTM C1396 certification requirements push manufacturers toward higher-grade water-repellent chemistry that expands addressable project scope.
- Gulf Coast humidity zones:Sustained above-average specification rates in Florida, Louisiana, and Texas coastal counties create concentrated demand pull for treated-core boards.
Market Restraints
- Paper-faced liner supply concentration:Integrated pulp-to-board producers control critical raw material quality, limiting second-tier manufacturer access to certified liner stock.
- Glass-mat facer cost premium:Fire-resistant variants with layered glass-mat construction command substantial price elevation over standard moisture-resistant grades, compressing volume penetration in cost-sensitive residential basement finishing.
- TSCA Title VI formaldehyde standards:EPA oversight of VOC emissions from adhesive adjuncts adds compliance burden and testing overhead for coating formulations.
Strategic Opportunities
- California and New York stretch codes:State-level green building certification tiering increasingly references enhanced moisture performance as prerequisite, creating regulatory tailwind for premium-grade products.
- Patient shower zone assemblies:Healthcare construction's infection-control protocol tightening opens specification white space for specialized envelope systems in hospital renovation cycles.
- Direct-to-contractor digital channels:Procurement platform penetration among regional drywall distributors enables disintermediation of traditional two-step distribution for large commercial projects.
Industry Challenges
- ASTM C473 testing protocol complexity:Core absorption validation below five percent requires specialized laboratory capacity that constrains new entrant certification timelines.
- OSHA mold remediation mandate compliance:Construction standards mandating replacement protocols for water-damaged commercial buildings create irregular demand spikes that stress production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moisture Resistant Gypsum Board Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Fire-Resistant, Soundproof, Impact-Resistant Application: Commercial Buildings, Residential Buildings, Industrial Facilities, Healthcare Settings Thickness: 1/2 inch, 5/8 inch, 3/4 inch, 1 inch Form: Boards, Panels, Sheets, Tile |
| Companies Covered | Georgia-Pacific Building Products, Boral, Saint-Gobain, Yoshino Gypsum, Siniat, Knauf, USG, Beijing New Building Material, LafargeHolcim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moisture Resistant Gypsum Board Market Trends and Innovations
Material science advances in core impregnation chemistry and facer lamination are compressing the performance gap between commodity moisture-resistant boards and premium fire-rated systems, rewiring value-engineering decisions on multifamily and hospitality projects.
Glass-mat facer technology is expanding into mid-tier commercial specifications previously served by paper-faced moisture-resistant grades. Hospitality developers in Florida and Gulf Coast Texas are specifying glass-mat systems for corridor and elevator shaft assemblies to satisfy NFPA 285 continuous insulation requirements without separate fire-barrier layers. The technology is expanding into residential basement markets as code officials in coastal counties begin accepting glass-mat products as dual-purpose moisture and fire barriers, compressing contractor material stocking complexity.
EPA TSCA Title VI enforcement is tightening formaldehyde emission thresholds for adhesive systems used in paper facer lamination. Manufacturers are reformulating polyvinyl acetate and urea-formaldehyde binders to meet composite wood product standards originally designed for particleboard and MDF. The regulatory pressure is most acute for producers serving California Air Resources Board jurisdictions, where third-party certification to CARB Phase 2 standards has become a de facto national specification filter.
Specification authority is migrating from general contractors to building envelope consultants on large commercial projects. Consultants in the Southeast Atlantic states are writing performance-based moisture-resistance specifications that reference ASTM C1396 but allow equivalent proprietary formulations, displacing traditional brand-prescriptive procurement. This behavioral shift is most visible in healthcare and institutional verticals where risk transfer to design professionals has accelerated post-pandemic.
Moisture Resistant Gypsum Board Market Segmentation
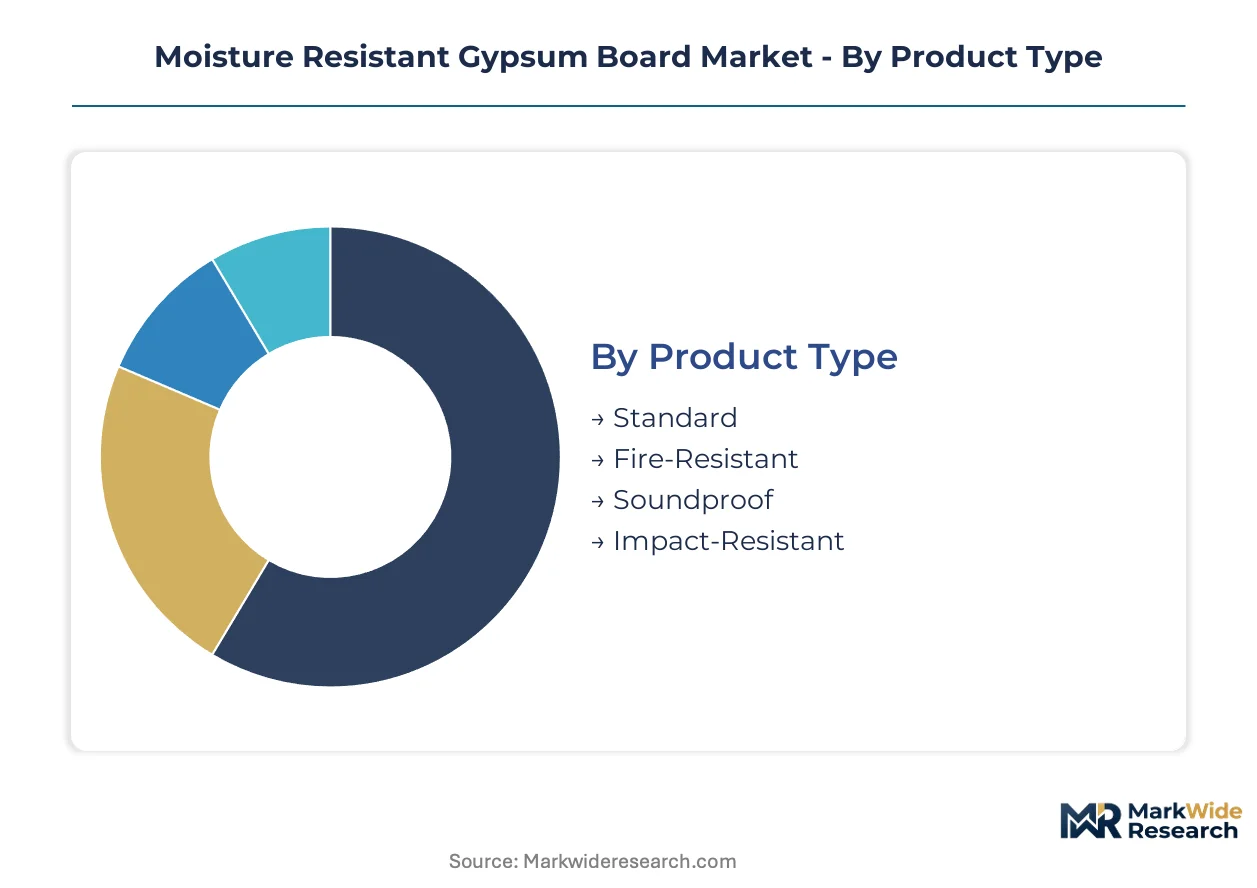
Segmentation in moisture resistant gypsum board reveals how specification authority migrates across project types and performance tiers. Manufacturers configure core chemistry, facer materials, and dimensional formats to match distinct code environments and installation protocols.
Product Type:
Standardization dominates commodity construction while specialized cores command premium positioning in regulated verticals.
- Standard:Silicone or wax-impregnated gypsum dihydrate core with green-tinted moisture-resistant paper facers achieves sub-five percent absorption per ASTM C473. Residential basement finishing across Gulf Coast states drives volume concentration as hurricane-resistant building codes elevate baseline specifications.
- Fire-Resistant:Layered glass-mat facers replace paper liners to satisfy NFPA 285 continuous insulation requirements without separate fire-barrier layers. Multifamily and hospitality developers in Florida corridor assemblies specify this dual-purpose configuration despite substantial cost elevation over standard grades.
- Soundproof:Denser core formulations with laminated mass-loaded barriers target party-wall assemblies in urban multifamily construction.
- Impact-Resistant:Reinforced facer composites serve high-traffic institutional corridors where surface durability protocols exceed standard board ratings.
Volume leader: Standard. Steepest expansion trajectory: Fire-Resistant as glass-mat technology penetrates mid-tier commercial specifications.
Application:
Code stringency varies sharply across end-use environments, concentrating demand pull in regulated institutional verticals.
- Commercial Buildings:Office and retail envelope assemblies specify moisture-resistant cores in mechanical room and loading dock zones where humidity exposure exceeds interior norms. Building envelope consultants in Southeast Atlantic states increasingly write performance-based specifications that displace brand-prescriptive procurement.
- Healthcare Settings:Joint Commission standards and FGI Guidelines mandate moisture-impervious wall assemblies in sterile processing and patient shower zones. Post-acute care facility construction generates fastest specification velocity as infection-control protocols tighten.
- Residential Buildings:Basement finishing and bathroom envelope applications concentrate in coastal humidity zones where local amendments to IRC elevate moisture-performance requirements.
- Industrial Facilities:Food processing and pharmaceutical manufacturing cleanrooms specify treated-core boards for wash-down compatibility.
Dominant by project count: Commercial Buildings. Expanding most quickly: Healthcare Settings as renovation cycles accelerate.
Thickness:
Dimensional selection tracks structural load requirements and fire-rating hourlies rather than moisture performance alone.
- 1/2 inch:Standard residential interior partition specification where moisture resistance supplements rather than replaces structural sheathing.
- 5/8 inch:Type X fire-rated assemblies default to this thickness; commercial code compliance across hotel and multifamily corridors sustains above-average specification rates.
- 3/4 inch:Enhanced sag resistance serves ceiling applications in high-humidity mechanical spaces.
- 1 inch:Specialized shaft-wall assemblies and area separation walls in institutional high-rises.
Highest shipment volume: 1/2 inch. Premium positioning concentrates: 5/8 inch where fire-moisture dual certification commands specification priority.
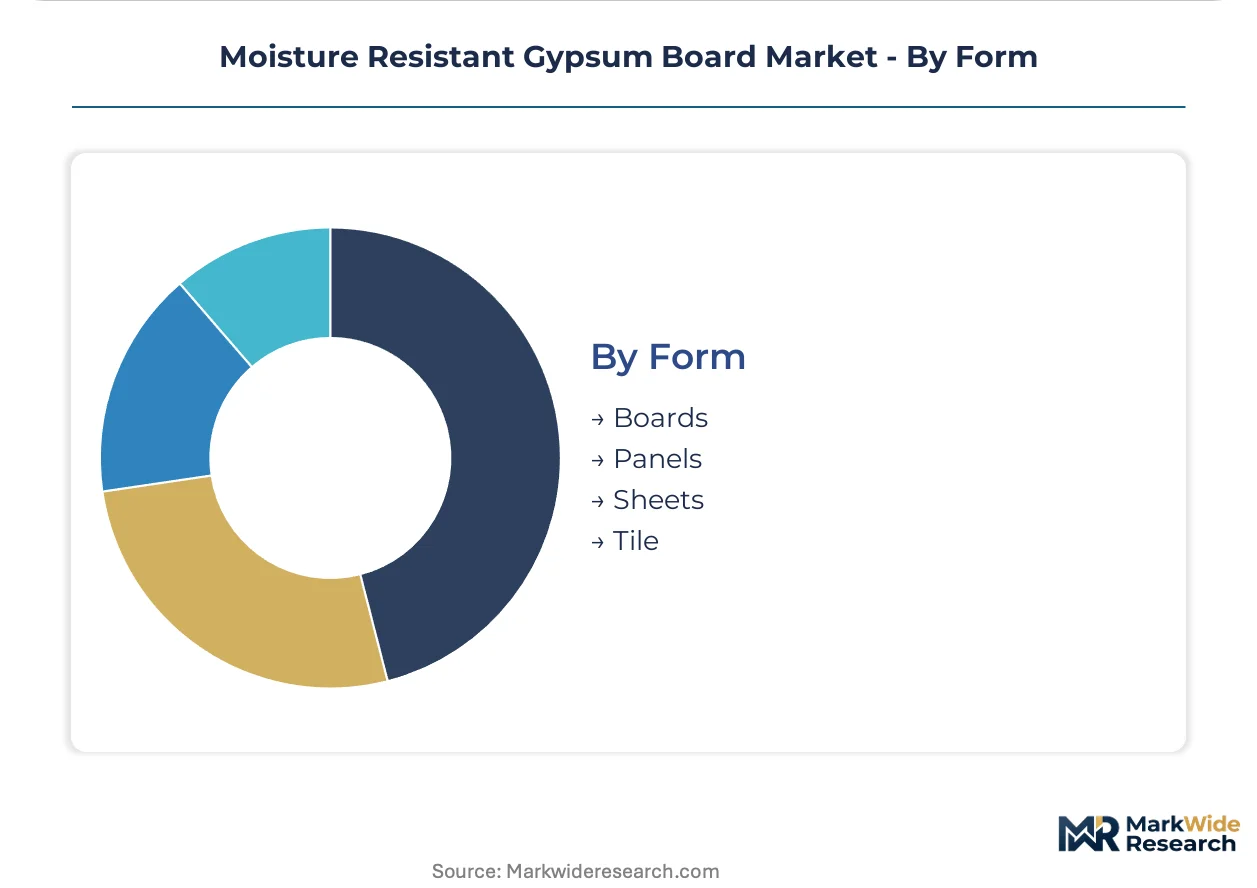
Form:
Format flexibility determines distribution channel access and contractor stocking economics.
- Boards:Standard 4×8 and 4×12 foot dimensions dominate commodity residential and commercial drywall distribution.
- Panels:Pre-finished or pre-cut configurations serve modular construction and prefabricated bathroom pods.
- Sheets:Oversized formats for industrial cladding and exterior soffit applications.
- Tile:Dimensionally stable substrate for wet-area ceramic tile backing in shower assemblies.
Distribution concentration: Boards. Format innovation focus: Panels as offsite construction penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural gypsum deposits in Nova Scotia and synthetic gypsum from coal-fired power plants in the Ohio River Valley anchor North American supply security for treated-core board production.
United States
Hurricane-resistant building codes across Florida, Louisiana, and Texas coastal counties sustain elevated specification rates for moisture-resistant grades. EPA TSCA Title VI enforcement tightens formaldehyde emission thresholds for adhesive systems in paper facer lamination. Georgia-Pacific Building Products leverages integrated pulp-to-board operations across the Southeast to control raw material quality from liner production through finished board.
Germany
Energy-efficient building renovation programs under the EU Green Deal accelerate demand for high-performance envelope assemblies in multifamily housing. REACH regulations govern chemical additives in silicone-treated core formulations, pushing manufacturers toward compliant water-repellent chemistry. Industrial clusters in North Rhine-Westphalia concentrate gypsum processing capacity serving Benelux and Northern European export markets.
China
Urban basement finishing in coastal humidity zones around Shanghai and Guangzhou expands addressable volume for standard moisture-resistant grades. GB standards and MIIT technical regulations establish core absorption and flexural strength benchmarks for construction-grade gypsum products. The Yangtze River Delta hosts integrated manufacturing complexes combining synthetic gypsum recovery from power generation with board production.
Japan
Seismic-resistant building codes in Tokyo and Osaka metropolitan areas specify treated-core boards for high-humidity mechanical spaces in commercial high-rises. METI energy conservation standards incentivize moisture-impervious wall assemblies that reduce HVAC load in humid summer conditions. Yoshino Gypsum anchors domestic supply from production facilities concentrated in the Kanto and Kansai industrial corridors.
Australia
Coastal humidity exposure in Queensland and New South Wales drives specification upgrades in residential and commercial construction. The country's national building regulator mandates moisture performance prerequisites for green building certification tiering. Industrial gypsum processing clusters in Victoria and Western Australia serve resource sector construction in mining and LNG facility expansion.
Moisture Resistant Gypsum Board Market Competitive Landscape
Global majors compete with regional champions across formulation technology and distribution reach. The vendor base organizes around integrated pulp-to-board producers, specialty chemical formulators, and regional building material distributors. Three archetypes dominate: integrated liner producers controlling upstream paper supply, formulation specialists commanding premium fire-rated segments, and scale-driven commodity producers competing on logistics efficiency. Capacity expansion and portfolio diversification toward glass-mat fire-rated systems represent the dominant competitive moves reshaping positioning.
Among North American integrated producers, Georgia-Pacific Building Products and USG exemplify the archetype of captive liner supply controlling raw material quality from pulp through finished board. Saint-Gobain occupies a position representing dense plant network strategies across the eastern seaboard. Knauf sits within the specialty formulation tier targeting commercial envelope assemblies.
| Leading Market Players |
|---|
| Georgia-Pacific Building Products |
| Boral |
| Saint-Gobain |
| Yoshino Gypsum |
| Siniat |
| Knauf |
| USG |
| Beijing New Building Material |
| LafargeHolcim |
| Others |
Pricing and Supply Chain Analysis
Recovered paper price indices and linerboard futures cascade through moisture-resistant gypsum board supply chains into three distinct pricing tiers, with silicone-treated core formulations commanding premium positioning over standard wax-impregnated grades. Raw material volatility in green-tinted facer stock concentrates pricing power among integrated pulp-to-board producers across the United States Southeast, compressing margin flexibility for second-tier manufacturers dependent on spot liner purchases.
Pricing Analysis
Warranty-backed moisture-performance guarantees separate premium glass-mat facer systems from unbundled standard grades in contractor procurement decisions. Three-tier pricing structure across premium, standard, and economy levels tracks ASTM C1396 certification tiers and fire-rating hourlies, with Type X assemblies carrying substantial elevation over residential basement specifications. Cost compression in standard-grade residential channels is intensifying because of paper-faced liner supply concentration among integrated producers. Price-sensitive single-family homebuilders in Gulf Coast states drive volume procurement of economy-tier silicone-treated boards, while least-sensitive healthcare facility developers specify warrantied glass-mat systems for patient shower zone assemblies.
Supply Chain Analysis
Skilled technician availability in Nova Scotia synthetic gypsum processing plants and Ohio River Valley coal-combustion byproduct recovery facilities constrains rapid capacity scaling for treated-core board production. Supply concentrates in the United States, China, and Germany, with each geography drawing from distinct raw material bases: natural gypsum deposits, power-plant synthetic gypsum, and industrial desulfurization byproducts. Critical dependencies include green-tinted moisture-resistant paper facers, silicone and wax emulsion chemistries, and glass-mat liner rolls. Single-source vulnerability in certified liner stock creates supply chain risk during hurricane-season demand spikes. Distribution runs through two-step building material distributors serving regional drywall contractors, with direct-to-contractor digital channels gaining penetration in large commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASTM C473 testing protocol complexity and certification timeline barriers are forcing sub-scale formulators out of moisture-resistant gypsum board manufacturing, consolidating viable production among integrated majors with captive laboratory capacity.
For Market Incumbents: Acquire certified liner production assets to secure upstream control over green-tinted moisture-resistant paper facer quality from pulp through finished board. Expand glass-mat facer capacity in Florida and Texas coastal counties to capture specification upgrades in hospitality corridor assemblies. Defend against emerging Chinese synthetic gypsum producers by embedding Joint Commission compliance expertise into healthcare sector sales engineering.
For New Entrants and Emerging Players: Begin with specialized envelope system formulations for patient shower zone renovations in post-acute care facilities, the most penetrable application segment given infection-control protocol tightening and specification white space. Target California and New York stretch code jurisdictions where enhanced moisture performance prerequisites for green building certification tiering create regulatory tailwind for premium-grade entrants. Pursue direct-to-contractor digital procurement platform partnerships to bypass entrenched two-step distribution relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap formulators with existing ASTM C1396 certification and underutilized laboratory capacity in the United States Southeast. Long-term viability in this market hinges on backward integration into liner production or exclusive supply agreements with integrated pulp mills. Watch for inflection in state-level stretch code adoption velocity as the signal to reassess premium-grade capacity deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Paper Facer Production | Captive liner supply secures ASTM C473 certification capacity against raw material shortages. |
| Glass-Mat Facer Capacity Expansion | Dual-purpose fire-moisture systems capture NFPA 285 specification upgrades in Florida hospitality. |
| Healthcare Sector Sales Engineering Investment | Joint Commission compliance expertise penetrates fastest-growing sterile processing zone segment. |
| Direct-to-Contractor Digital Platform Partnership | Disintermediation of two-step distribution accelerates large commercial project procurement capture. |
| Silicone-Treated Core Formulation R&D | Sub-five percent absorption chemistry expands addressable scope under tightening FGI Guidelines. |
Research Methodology
Multi-period observation of ASTM C1396 certification timelines, silicone emulsion pricing spreads, and Gulf Coast specification rates anchored the trend analysis, supplemented by interviews with gypsum plant managers, building envelope consultants, regional drywall distributor procurement leads, and healthcare facility construction directors. Secondary validation drew from EPA TSCA Title VI enforcement disclosures, SEC 10-K filings of integrated building products majors, customs data on paper facer liner trade flows, and state-level stretch code adoption tracking. Bottom-up project pipeline enumeration across healthcare, hospitality, and residential verticals triangulated against top-down gypsum board production capacity utilization estimates.
Input-output matrices mapping synthetic gypsum recovery volumes to treated-core board output, paper facer liner supply concentration indices, and specification rate differentials by coastal humidity zone drove segment-level volume and value projections across the analysis window. Segmentation dimensions modeled include product type tier, application vertical, thickness specification, and regional building code stringency cluster. CAGRs derived from regression analysis of historical specification penetration rates against code adoption curves, with forecast sensitivity tested against hurricane frequency scenarios and stretch code expansion assumptions.
Underlying measurement precision varies by segment; healthcare application data carries tighter precision than residential basement finishing given more centralized project reporting. Forecasts reflect assumptions about FGI Guidelines enforcement continuity, EPA formaldehyde threshold stability, and linerboard supply concentration persistence. Material deviation in state-level stretch code adoption velocity, hurricane-season demand spike severity, or integrated producer capacity discipline warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Roofing Liners Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
TMT Steel Bar Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Asphalt Modifiers Market
Building & Construction Materials
Concrete Resurfacer Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
Steel Casing Pipes Market
Building & Construction Materials
Limestone Aggregates Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market