
 Italy Transportation Infrastructure Construction Market | 2026-2036
Italy Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Transportation Infrastructure Construction Market Foresight
A shortage of specialized tunneling engineers and bridge structural specialists is collapsing project timelines across northern Italy's alpine corridor. WeBuild leverages its heritage in complex civil engineering to secure megaproject tenders in the Brenner Base Tunnel alignment. Salcef Group specializes in railway track laying and maintenance, anchoring its order book to Ferrovie dello Stato Italiane modernization programs. Rizzani de Eccher competes through integrated design-build capabilities that reduce interface risk on multi-contractor sites.
Italy transportation infrastructure construction encompasses the planning, engineering, and physical assembly of roadways, rail networks, aviation facilities, and waterway crossings using load-bearing concrete formulations, weathering-grade steel alloys, and polymer-modified asphalt binders engineered for seismic zones and Mediterranean climate exposure. The primary purpose is to reduce logistics friction across the Italian peninsula's mountainous topography while connecting industrial clusters to EU trans-European transport networks. Railway and highway project types command the largest share of public capital allocation, with bridges representing the highest margin pool due to specialized substructure expertise requirements. Sustainable construction methods are gaining traction as PNRR disbursement rules tie funding to lifecycle carbon assessments and recycled material quotas.
Italy's Ministry of Infrastructure and Transport coordinates with the European Commission's TEN-T program to align national project pipelines with EU corridor completion deadlines, while the National Recovery and Resilience Plan imposes strict environmental and digitalization conditionalities on fund release. The Italian Anti-Corruption Authority (ANAC) enforces procurement transparency rules that reshape bidding strategies and consortium formation patterns for infrastructure contracts exceeding EU threshold values. Stakeholders must monitor how PNRR spending acceleration deadlines interact with construction capacity constraints and raw material cost volatility to calibrate project delivery commitments and subcontractor risk allocation.
Market Dynamics
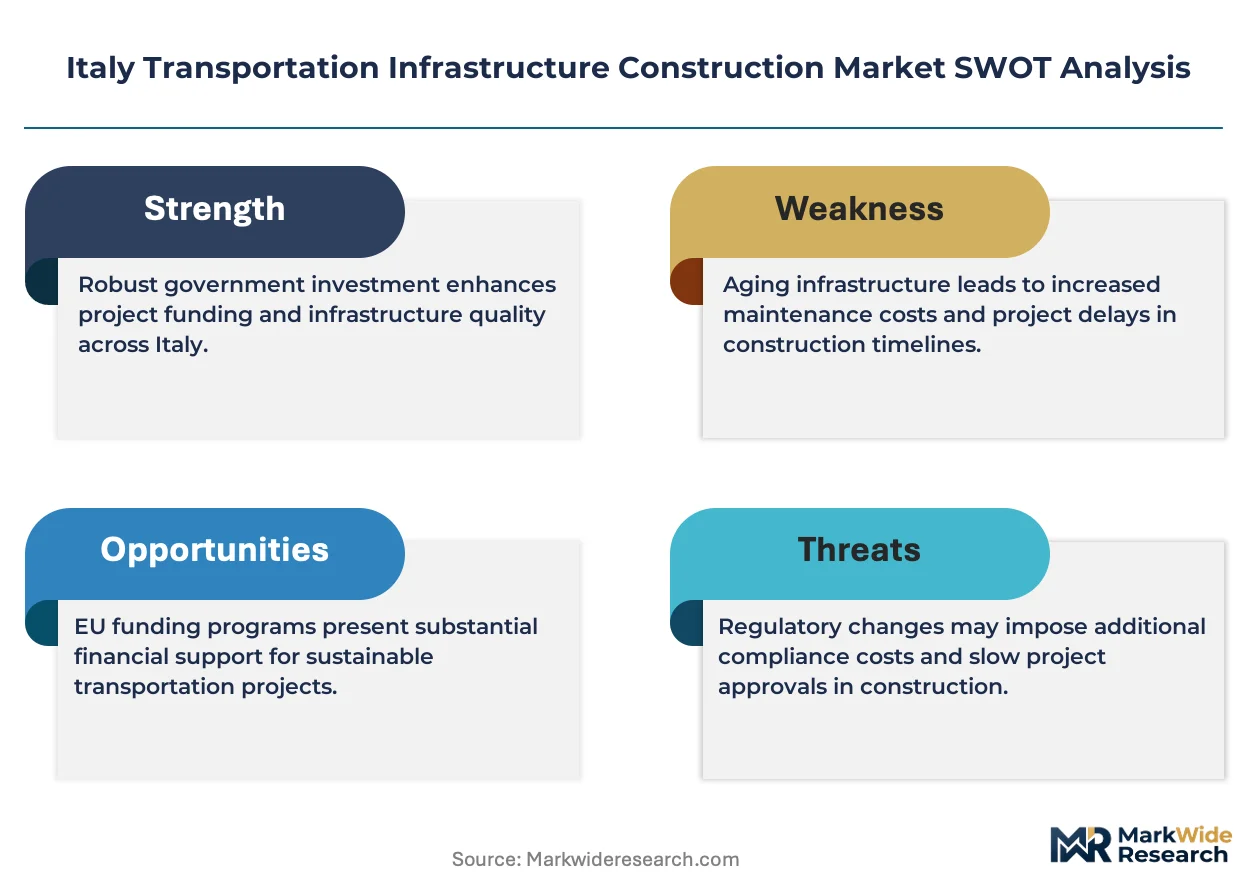
The Italian transportation infrastructure construction market is being fundamentally restructured by the National Recovery and Resilience Plan's conditional disbursement framework, which ties EU cohesion fund release to lifecycle carbon assessments and recycled material quotas. This creates a dual pressure: accelerating project pipelines while enforcing sustainability compliance that reshapes material procurement and contractor qualification requirements.
Growth Catalysts
- TEN-T corridor alignment:The European Commission's trans-European transport network program mandates completion deadlines that compress procurement cycles and expand contract volumes for cross-border rail links.
- Seismic-resistant material specifications:Polymer-modified asphalt binders and weathering-grade steel alloys engineered for Mediterranean climate exposure and earthquake zones are unlocking reconstruction tenders in high-risk zones.
- Milan-Turin-Genoa industrial triangle concentration:Port connectivity upgrades and high-speed rail expansion in this northern cluster concentrate public capital allocation and attract specialized engineering consortia.
Market Restraints
- Specialized labor scarcity:A collapsed pipeline of tunneling engineers and bridge structural specialists extends project timelines across the alpine corridor, inflating wage costs and delaying milestone payments.
- Raw material cost volatility:Weathering-grade steel alloy prices fluctuate with energy input costs, compressing margins on fixed-price public contracts where indexation clauses are restricted by ANAC procurement rules.
- EU threshold procurement complexity:Contracts exceeding defined value thresholds trigger mandatory transparency protocols that lengthen bid preparation cycles and disqualify smaller regional contractors.
Strategic Opportunities
- Digital twin integration:BIM-to-field workflow convergence with IoT sensor networks enables predictive maintenance contracts that extend revenue streams beyond construction completion.
- Southern Italy corridor development:Underinvested rail links connecting Calabria and Sicily to mainland networks represent untapped project pipelines as PNRR funds redirect toward territorial cohesion objectives.
- Circular construction mandates:Recycled concrete aggregate quotas in public tenders create first-mover advantages for contractors with established demolition material recovery partnerships.
Industry Challenges
- Multi-contractor interface risk:Design-build integration complexity escalates when Ferrovie dello Stato Italiane parcels megaprojects into separate civil works and systems installation lots.
- Substructure expertise certification:Bridge foundation specialists face extended qualification timelines under updated Ministry of Infrastructure technical protocols, narrowing the eligible bidder pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Transportation Infrastructure Construction Market |
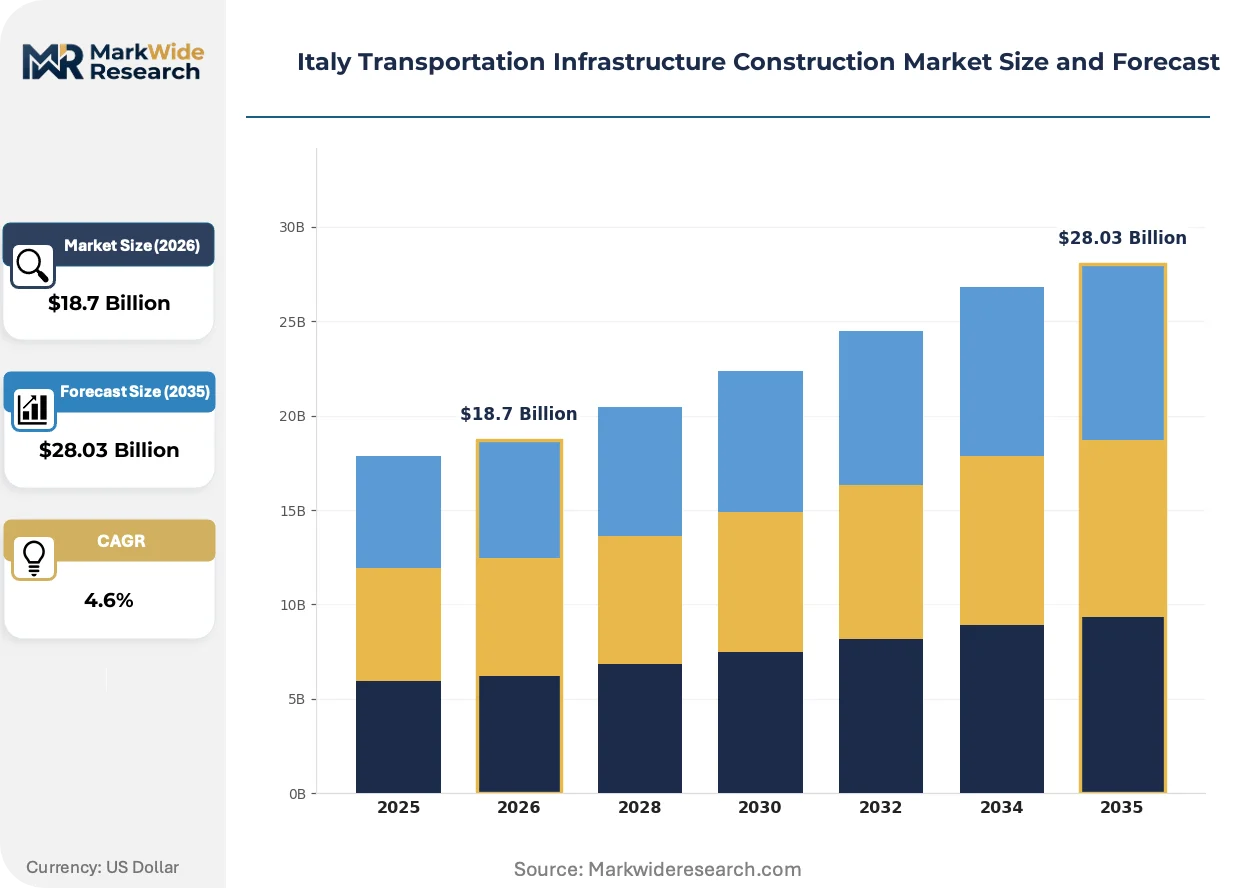
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Highways, Railways, Bridges, Airports Construction Method: Traditional, Modular, Prefabricated, Sustainable Material Type: Concrete, Steel, Asphalt, Composites End User: Government, Private Sector, NGOs, Consortiums |
| Companies Covered | Astaldi, Impresa Pizzarotti, WeBuild, Colas Rail Italia, Itinera, Ferrovie dello Stato Italiane (FS Group), Rizzani de Eccher, Ghella, Salcef Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Transportation Infrastructure Construction Market Shifts & Advancements
Construction methodology in Italy is pivoting toward predictive asset management and material circularity, driven by fund-release conditionality and the compression of acceptable project delivery windows. Three distinct shifts are restructuring competitive capability requirements.
Prefabricated bridge segment manufacturing is miniaturizing on-site assembly requirements for alpine corridor crossings. Contractors are adopting factory-cast concrete elements with embedded post-tensioning ducts to reduce high-altitude casting operations. WeBuild and Salcef Group are expanding captive precasting yard capacity to compress weather-dependent construction windows.
CSRD reporting obligations are mandating embodied carbon disclosure for infrastructure projects above defined value thresholds. Italian concessionaires must now document Scope 3 emissions from steel and cement procurement, reshaping supplier selection criteria. The Brenner Base Tunnel alignment contractors are piloting blockchain-tracked material provenance systems to satisfy audit requirements.
Consortium formation patterns are fragmenting as ANAC transparency rules expose bid-rigging vulnerabilities. Mid-sized regional contractors are abandoning traditional joint ventures with national primes in favor of specialized subcontractor roles. Procurement officers at Ferrovie dello Stato Italiane are responding with unbundled lot structures that separate civil works from track laying and electrification systems.
Italy Transportation Infrastructure Construction Market Segmentation
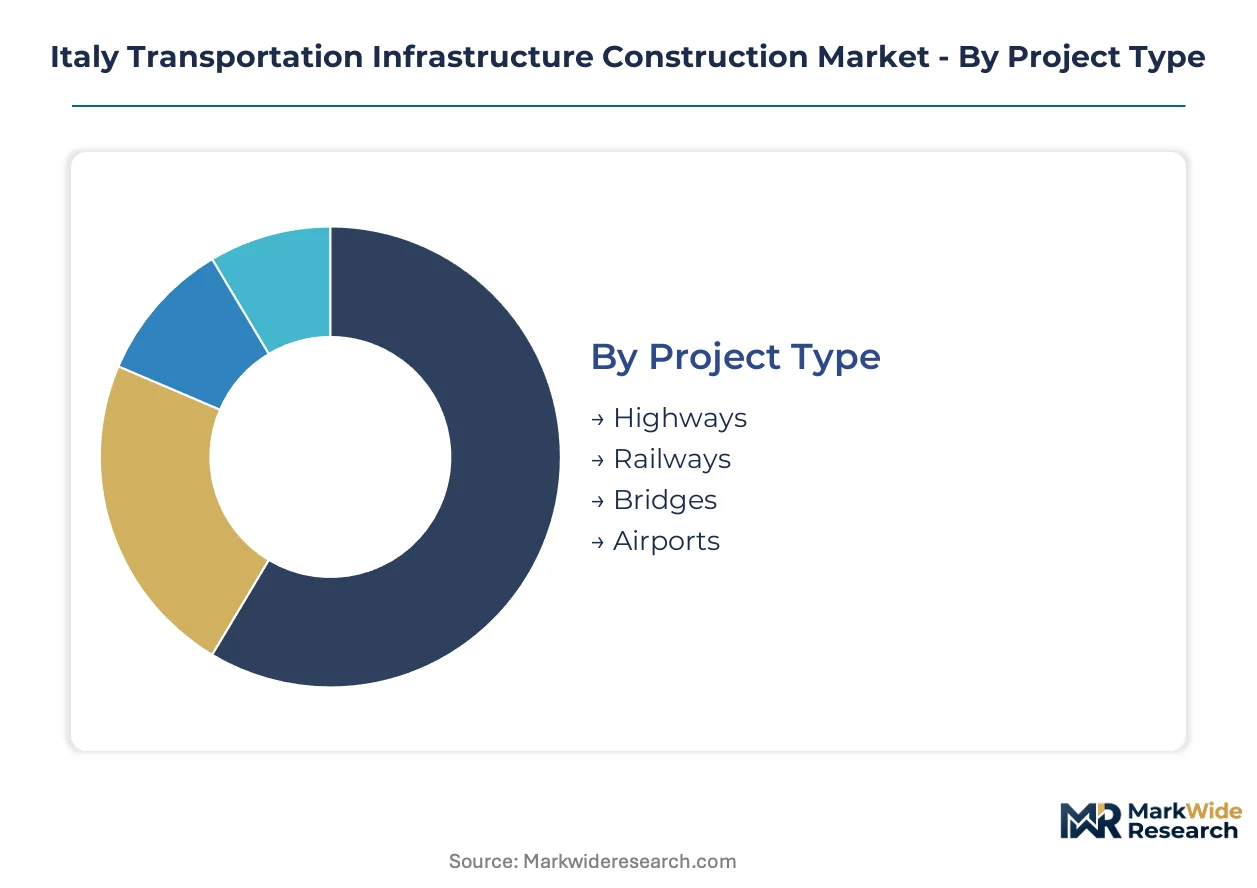
Segmentation reveals how PNRR disbursement rules and TEN-T corridor deadlines reshape contractor specialization requirements across Italy's transportation infrastructure market. Material specifications, procurement methods, and end-user risk profiles determine bid eligibility and margin structures.
Project Type:
Regulatory differentiation under Italy's Ministry of Infrastructure technical protocols and EU TEN-T mandates creates divergent qualification barriers across project categories.
- Railways:High-speed and conventional rail networks require seismic-resistant track bed engineering and electrification system integration. Demand concentrates in the Milan-Turin-Genoa triangle where Ferrovie dello Stato Italiane accelerates corridor modernization to meet EU completion deadlines.
- Highways:Polymer-modified asphalt binders engineered for Mediterranean climate exposure and heavy freight loads define material specifications. Alpine corridor expansions face collapsed timelines due to tunneling engineer shortages and geological complexity.
- Bridges:Substructure expertise requirements create the highest margin pool through specialized foundation engineering and post-tensioning protocols.
- Airports:Runway resurfacing and terminal expansion projects follow ENAC technical standards with strict noise abatement and carbon footprint disclosure requirements.
Railways handles the majority of throughput; Bridges is expanding most quickly on share as specialized engineering scarcity inflates contract values.
Construction Method:
Cost tier differentiation separates capital-intensive prefabrication investments from labor-dependent traditional approaches, with PNRR recycled material quotas favoring methods with embedded circularity.
- Prefabricated:Factory-cast concrete segments with embedded post-tensioning ducts minimize high-altitude casting operations. WeBuild and Salcef Group expand captive precasting yard capacity to compress weather-dependent construction windows in alpine zones.
- Sustainable:Lifecycle carbon assessments and recycled concrete aggregate quotas are mandatory for PNRR-funded contracts. Blockchain-tracked material provenance systems satisfy CSRD audit requirements on large infrastructure projects.
- Traditional:Cast-in-place concrete and on-site steel assembly dominate smaller regional contracts below EU procurement thresholds.
- Modular:Standardized component systems reduce interface risk on multi-contractor sites but require upfront design standardization investment.
Traditional construction still dominates contract volume; Sustainable methods are climbing the fastest as fund-release conditionality hardens.
Material Type:
Volume concentration in concrete and steel reflects load-bearing requirements, while composite adoption tracks bridge lightweighting demands and corrosion resistance specifications.
- Concrete:Load-bearing formulations with recycled aggregate content satisfy PNRR quotas. Precast segment manufacturing miniaturizes on-site assembly for alpine corridor crossings.
- Steel:Weathering-grade alloys engineered for seismic zones and Mediterranean exposure face price volatility tied to energy input costs, compressing margins on fixed-price public contracts.
- Asphalt:Polymer-modified binders for high-traffic highways require specialized mixing plant certification under Ministry of Infrastructure protocols.
- Composites:Fiber-reinforced polymer elements reduce dead loads on long-span bridge structures in seismic zones.
Concrete absorbs the largest material procurement volumes; Composites are gaining share fastest in bridge superstructure applications.
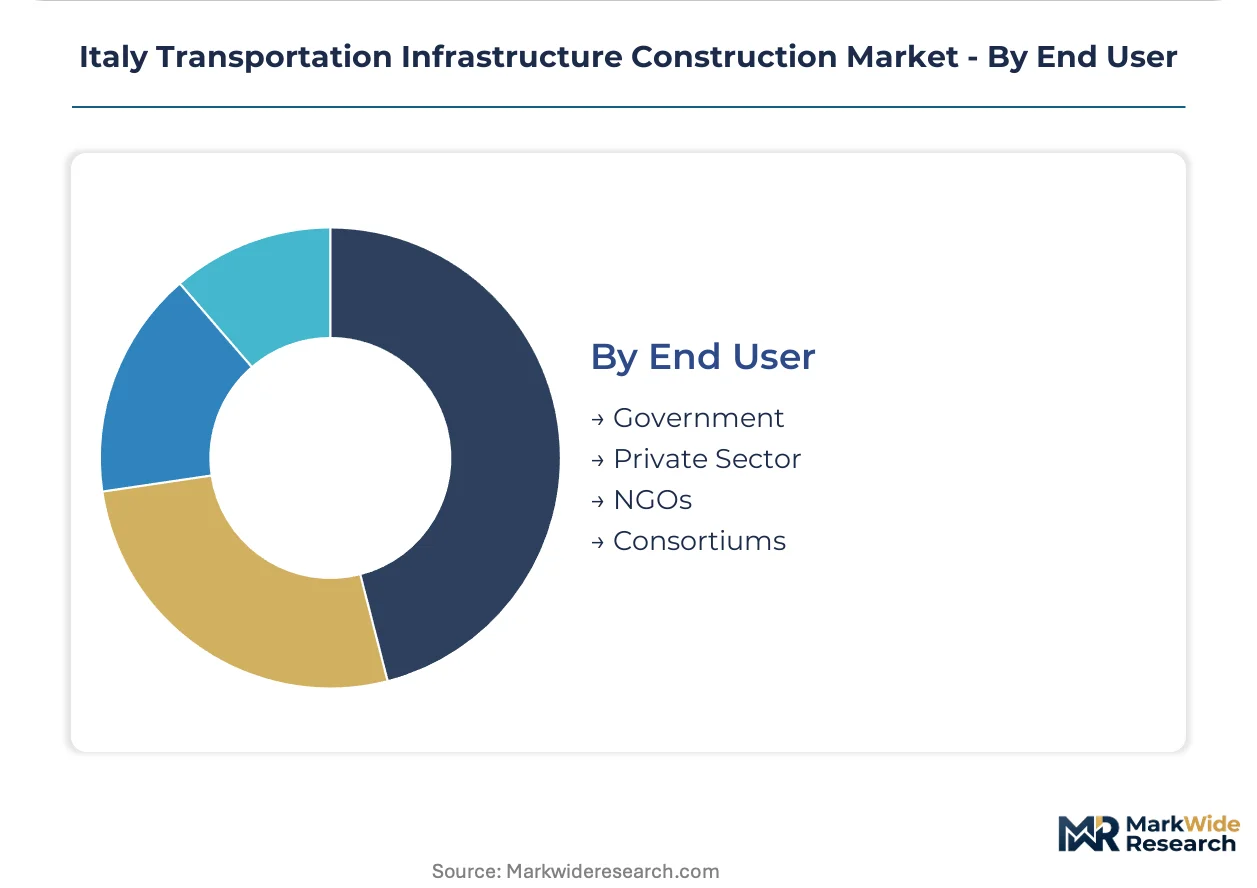
End User:
Customer type determines risk allocation, payment security, and qualification complexity, with ANAC transparency rules reshaping consortium formation patterns.
- Government:Ferrovie dello Stato Italiane and Ministry of Infrastructure contracts impose strict environmental and digitalization conditionalities. EU threshold procurement triggers mandatory transparency protocols that lengthen bid preparation cycles.
- Consortiums:Multi-contractor joint ventures fragment as ANAC rules expose bid-rigging vulnerabilities, with mid-sized regional contractors abandoning traditional partnerships for specialized subcontractor roles.
- Private Sector:Concessionaire-led projects require CSRD Scope 3 emissions disclosure for steel and cement procurement, reshaping supplier selection criteria.
- NGOs:Limited infrastructure involvement concentrates on rural accessibility and cycling network projects with smaller contract scales.
Government contracts command the dominant share of capital allocation; Consortium structures are shifting fastest as transparency rules force unbundled lot structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ministry of Infrastructure and Transport anchors national project coordination through PNRR disbursement frameworks that tie EU cohesion fund release to sustainability compliance across Italy's transportation construction sector.
Lombardy
High-speed rail expansion and Milan Metro line extensions absorb the majority of regional capital allocation. The Lombardy regional government aligns procurement with TEN-T corridor deadlines through accelerated environmental permitting. The Milan hub concentrates design-build consortia bidding on multi-billion euro track modernization programs.
Piedmont
Turin orbital highway upgrades and alpine tunnel maintenance contracts drive demand for seismic-resistant concrete formulations. ANAC transparency rules reshape bidding strategies for contracts exceeding EU threshold values. The Susa Valley corridor hosts Brenner Base Tunnel alignment works where tunneling engineer scarcity inflates wage costs.
Veneto
Port of Venice dredging and hinterland rail connections attract weathering-grade steel procurement for marine exposure applications. CSRD reporting obligations mandate embodied carbon disclosure for infrastructure above defined value thresholds. The Mestre-Marghera industrial zone anchors specialized civil engineering consortia.
Emilia-Romagna
Bologna high-speed rail node expansion and Apennine highway tunnels require polymer-modified asphalt binders for heavy freight loads. Recycled concrete aggregate quotas in public tenders favor contractors with established demolition material recovery partnerships. The Po Valley logistics corridor concentrates precast segment manufacturing capacity.
Lazio
Rome ring road modernization and Fiumicino airport connectivity upgrades follow strict ENAC technical standards. The National Recovery and Resilience Plan imposes digitalization conditionalities on fund release for capital projects. The Tiber Valley industrial belt hosts consortium headquarters coordinating nationwide megaproject bids.
Italy Transportation Infrastructure Construction Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Italy's transportation infrastructure construction market. Tier-one contractors capture megaproject tenders through design-build capabilities that reduce interface risk on multi-contractor sites. Tier-two specialists anchor order books to specific material systems or geographic corridors. Dominant competitive moves include captive precasting yard expansion and BIM-to-field workflow integration for predictive maintenance contract extensions.
Among integrated civil engineering groups, WeBuild exemplifies the heritage-backed megaproject archetype through complex alpine corridor positioning. Salcef Group occupies the railway systems specialization tier with track laying and maintenance expertise anchored to Ferrovie dello Stato Italiane programs. Rizzani de Eccher represents the design-build integration archetype that minimizes subcontractor coordination friction on unbundled public contracts.
| Leading Market Players |
|---|
| Astaldi |
| Impresa Pizzarotti |
| WeBuild |
| Colas Rail Italia |
| Itinera |
| Ferrovie dello Stato Italiane (FS Group) |
| Rizzani de Eccher |
| Ghella |
| Salcef Group |
| Others |
Supply & Pricing Matrix
Fixed-price public contracts with restricted indexation clauses lock in material cost exposure for Italian infrastructure contractors while securing Ferrovie dello Stato Italiane procurement budgets against energy-driven steel alloy volatility.
Pricing Analysis
Project-based fixed-price contracts dominate public tenders above EU threshold values, with ANAC procurement rules limiting cost escalation pass-throughs. Price differentiation hinges on contractor certification tier under Ministry of Infrastructure technical protocols and geographic delivery complexity to alpine corridor sites. Cost compression in weathering-grade steel procurement is intensifying because energy input volatility outpaces contract adjustment mechanisms. Regional contractors below EU thresholds exhibit highest price sensitivity due to limited working capital buffers against raw material spikes.
Supply Chain Analysis
Inventory lead times for polymer-modified asphalt binders stretch across Mediterranean mixing plant certification cycles, compressing project mobilization windows. Supply concentrates in Germany, Turkey, and domestic Italian steel producers for weathering-grade alloys, with China anchoring global cement clinker feedstock. Raw material dependencies center on energy-intensive steel production, specialty chemical additives, and limestone aggregate from Lombardy quarries. Single-source vulnerability runs through Brenner Base Tunnel alignment segments where qualified precasting yards are geographically constrained. Distribution runs through Ferrovie dello Stato Italiane consolidated procurement portals for track materials and Ministry of Infrastructure regional depots for highway contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy transportation infrastructure construction market is accelerating through PNRR fund-release conditionality that ties disbursement to lifecycle carbon assessments and digital twin integration mandates.
For Market Incumbents: Shield design-build integration capabilities against unbundled lot fragmentation by Ferrovie dello Stato Italiane procurement officers. Deepen captive precasting yard capacity in Emilia-Romagna and Piedmont to compress weather-dependent construction windows. Prioritize BIM-to-field workflow certification to capture predictive maintenance contract extensions beyond construction completion.
For New Entrants and Emerging Players: Anchor in Southern Italy corridor development where Calabria and Sicily rail links remain underinvested against territorial cohesion objectives. Target specialized subcontractor roles in bridge substructure engineering where Ministry qualification protocols narrow the eligible bidder pool. Pursue demolition material recovery partnerships to satisfy recycled concrete aggregate quotas in PNRR-funded tenders.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with established railway systems integration expertise and captive supply of seismic-resistant concrete formulations. Long-term viability over the next decade hinges on TEN-T corridor completion deadlines compressing procurement cycles. Monitor CSRD reporting obligation enforcement as the signal for accelerated consolidation around carbon-accounting capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Precasting Yard Expansion | WeBuild and Salcef Group compress alpine weather windows through factory-cast segment manufacturing. |
| BIM-to-Field Workflow Integration | IoT sensor convergence enables predictive maintenance contracts extending revenue beyond project handover. |
| Recycled Aggregate Partnership Development | Demolition material recovery networks satisfy PNRR quotas for circular construction mandates. |
| Bridge Substructure Certification Investment | Specialized foundation expertise captures highest-margin contracts as qualification barriers rise. |
| Southern Corridor Consortium Formation | Calabria-Sicily rail links represent untapped pipelines as cohesion funds redirect southward. |
Research Methodology
A spread of perspectives from project directors at tier-one contractors, procurement officers at Ferrovie dello Stato Italiane, quarry operators in Lombardy, and technical certification leads at the Ministry of Infrastructure converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EU TEN-T program documentation, ANAC procurement transparency filings, and PNRR disbursement tracking databases. Bottom-up project pipeline aggregation triangulated against top-down EU cohesion fund allocation envelopes.
Segmentation dimensions modeled include project type, construction method, material specification, and end-user risk profile across the projection horizon. CAGRs were derived from weighted scenario analysis of fund-release acceleration timelines and construction capacity constraints. Forecast inputs incorporated seismic-resistant material specification adoption curves and CSRD reporting obligation phase-in schedules.
Material uncertainties — PNRR spending deadline extensions, tunneling engineer pipeline recovery, and weathering-grade steel energy input shocks — sit outside the modeled envelope. Forecasts reflect documented assumptions about EU corridor completion mandates and ANAC procurement rule stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
China Transportation Infrastructure Construction Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
Heavy Movable Bridges Market
Infrastructure Construction
Rebar Tier Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
Netherlands Transportation Infrastructure Construction Market
Infrastructure Construction
Concrete Canvas Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
Finland Transportation Infrastructure Construction Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
New Zealand Infrastructure Market