
 Pipeline Monitoring System Market | 2026-2036
Pipeline Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Monitoring System Market Analysis
System integrator channels is reconfiguring how pipeline operators procure monitoring suites. Siemens AG leverages its digital twin platforms to anchor long-term service contracts across European gas networks. Emerson Electric Co. competes through specialized pressure transmitter lines designed for sour service conditions. Honeywell International Inc. controls distribution in the Middle East through localized calibration facilities.
A pipeline monitoring system comprises sensor arrays, telemetry infrastructure, and analytics software engineered to detect leaks, pressure anomalies, and structural degradation across hydrocarbon and fluid transport networks. These systems typically operate at sampling frequencies between 1 Hz and 1000 Hz depending on the criticality of the monitored segment, with fiber optic distributed acoustic sensing achieving spatial resolutions under 10 meters along the pipeline route. Acoustic sensors and pressure sensors occupy the largest installed base due to decades of proven performance in rupture detection, while fiber optic technology represents the fastest-expanding category as operators seek distributed temperature and strain profiling without electrical power at the sensing point. SCADA architectures remain the dominant integration layer though IoT-native platforms are displacing legacy polling systems in greenfield water utility projects.
The US PHMSA mandates risk-based integrity management programs for gas transmission operators exceeding defined pipeline mileage thresholds. In Europe, the EU Methane Regulation imposes measurement, reporting, and verification protocols that directly expand demand for continuous emissions monitoring hardware. China's MEE enforces GB standard compliance for hazardous chemical pipeline corridors, creating specification requirements that favor domestic certification holders. Stakeholders must weigh the capital cost of retrofitting existing SCADA networks against the operational flexibility of cloud-native IoT architectures as regulatory deadlines tighten.
Market Dynamics
Midstream operators face intensifying pressure to eliminate methane venting while water utilities confront aging infrastructure failures, forcing simultaneous capital deployment across leak detection hardware and predictive analytics platforms.
Growth Catalysts
- EU Methane Regulation:The measurement, reporting, and verification protocols mandate continuous emissions monitoring hardware across European gas transmission corridors, directly expanding procurement volumes for optical gas imaging and sensor networks.
- Fiber optic distributed sensing:Operators in the Permian Basin corridor deploy distributed acoustic and temperature sensing to achieve spatial resolutions under 10 meters without electrical power at monitoring points, slashing installation costs in hazardous zones.
- Water utility infrastructure:North American municipalities accelerate leak detection deployments as non-revenue water losses exceed 15 percent in aging distribution systems, creating sustained demand for pressure transient analysis equipment.
Market Restraints
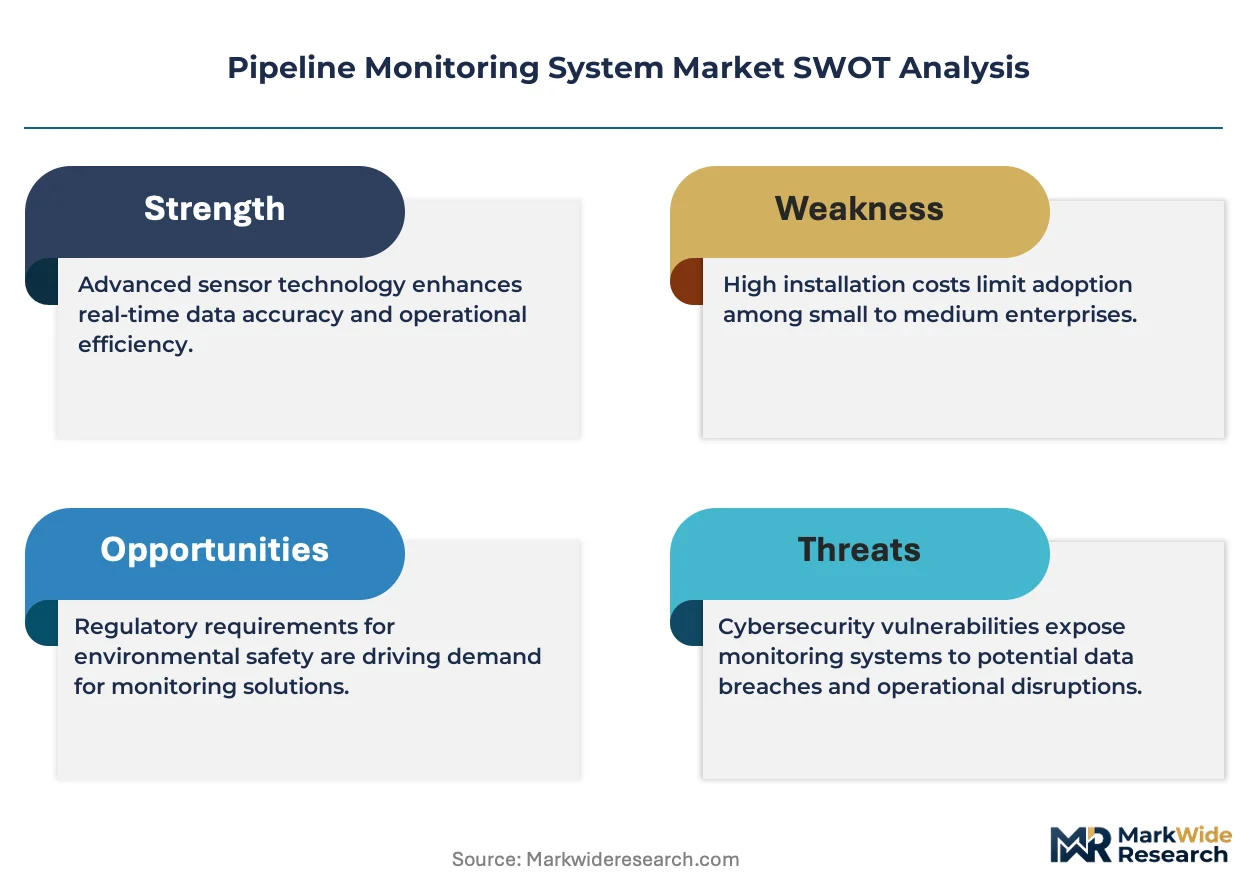
- SCADA retrofit capital burden:Legacy polling architectures in hydrocarbon networks require substantial hardware replacement to interface with IoT-native platforms, compressing near-term upgrade budgets.
- Rare earth magnet supply:Neodymium and dysprosium price volatility affects electromagnetic acoustic transducer manufacturing, concentrating input cost risk with Chinese processing facilities.
- Subsea cable technical limits:Deepwater pipeline segments beyond 3,000 meters depth exceed current fiber optic pressure vessel ratings, forcing reliance on battery-powered autonomous underwater vehicles with limited endurance.
Strategic Opportunities
- India hazardous chemical corridors:The country's petroleum regulator mandates pipeline integrity management for caustic soda and ammonia transport routes, opening specification competitions for corrosion monitoring systems.
- Digital twin convergence:Integration of real-time sensor feeds with computational fluid dynamics models enables predictive rupture simulation, creating recurring software licensing revenue streams alongside hardware sales.
- Cloud-native IoT architectures:Greenfield water utility projects bypass traditional SCADA procurement through subscription-based telemetry platforms, shifting vendor relationships from capital sales to operational expenditure models.
Industry Challenges
- Distributed sensing calibration:Fiber optic systems require specialized technicians capable of interpreting Rayleigh backscatter signatures, creating talent scarcity in remote pipeline stations.
- PHMSA certification timelines:Gas transmission operators face compressed schedules to implement risk-based integrity management programs, straining third-party verification capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Monitoring System Market |
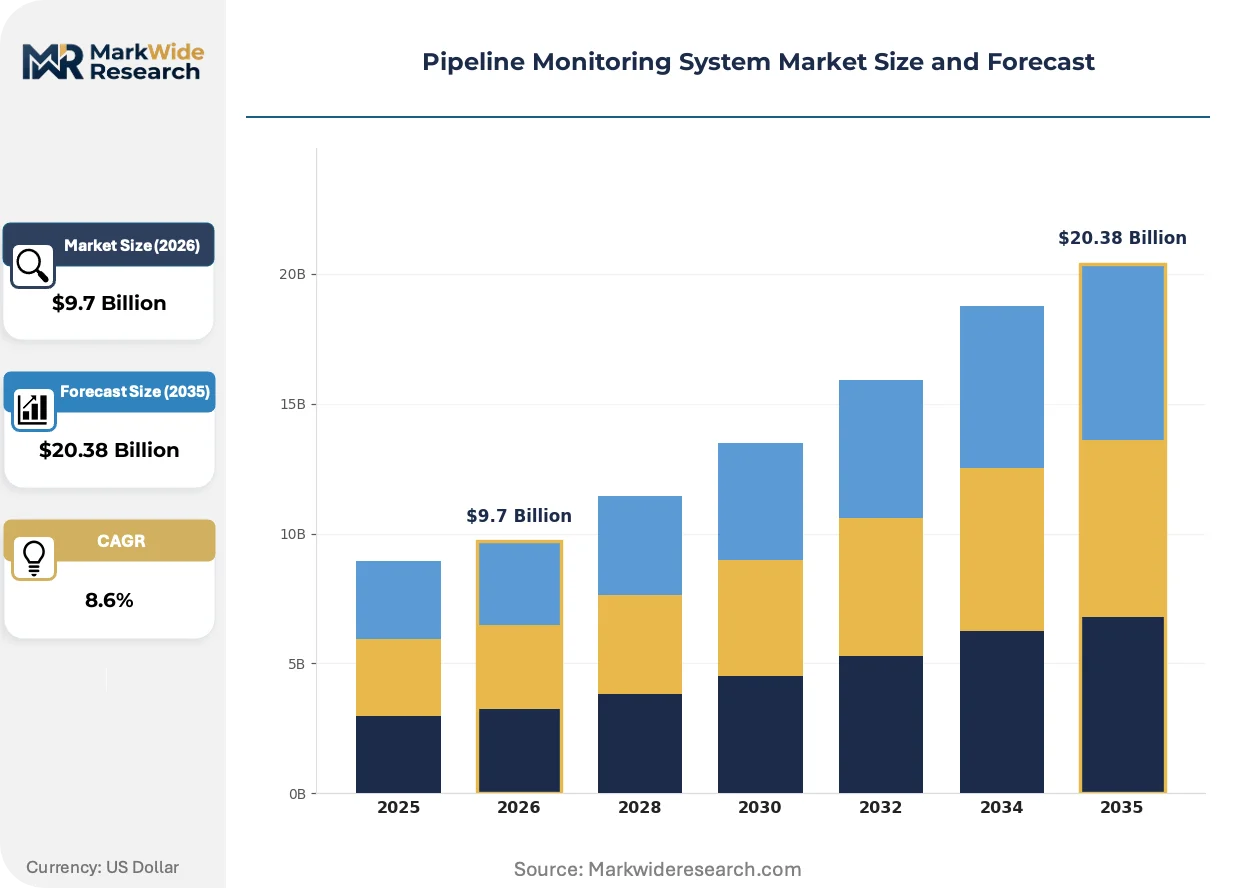
| Market Size in 2026 | $9.7 Billion |
| Market Size in 2035 | $20.38 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic Sensors, Flow Meters, Pressure Sensors, Temperature Sensors Technology: IoT, SCADA, Ultrasonic, Fiber Optic End User: Oil & Gas, Chemicals, Water Utilities, Mining Installation: Onshore, Offshore, Underground, Aboveground |
| Companies Covered | Siemens AG, Rockwell Automation Inc., ABB Ltd., ORBCOMM Inc., GE Vernova Inc., Emerson Electric Co., Schneider Electric SE, Yokogawa Electric Corporation, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Monitoring System Market Emerging Trajectories
Sensor fusion architectures and edge computing deployments are compressing detection latency while regulatory mandates force hardware refresh cycles across both hydrocarbon and water infrastructure networks.
Machine learning inference at the edge is rendering obsolete centralized SCADA polling architectures that introduced 30-second to 5-minute latency in rupture detection. Permian Basin midstream operators now deploy GPU-equipped telemetry nodes capable of processing acoustic signatures locally. This shift compresses alarm generation from minutes to milliseconds, eliminating the need for dedicated control room infrastructure at remote compressor stations.
The EU Methane Regulation imposes measurement, reporting, and verification protocols that directly expand hardware procurement for continuous emissions monitoring. Industrial consequence includes mandatory optical gas imaging deployment at compressor stations and processing facilities. Gas transmission operators in Germany and the Netherlands accelerate replacement of intermittent manual surveys with fixed sensor networks to meet quarterly reporting deadlines.
Water utilities unbundle after-sales service contracts from initial hardware procurement, separating sensor installation from multi-year calibration and data analytics subscriptions. Municipal buyers in Texas and California now evaluate total cost of ownership across 10-year horizons rather than capital expenditure alone. This behavioral shift favors vendors with localized technical service presence over equipment manufacturers lacking regional maintenance infrastructure.
Pipeline Monitoring System Market Segmentation
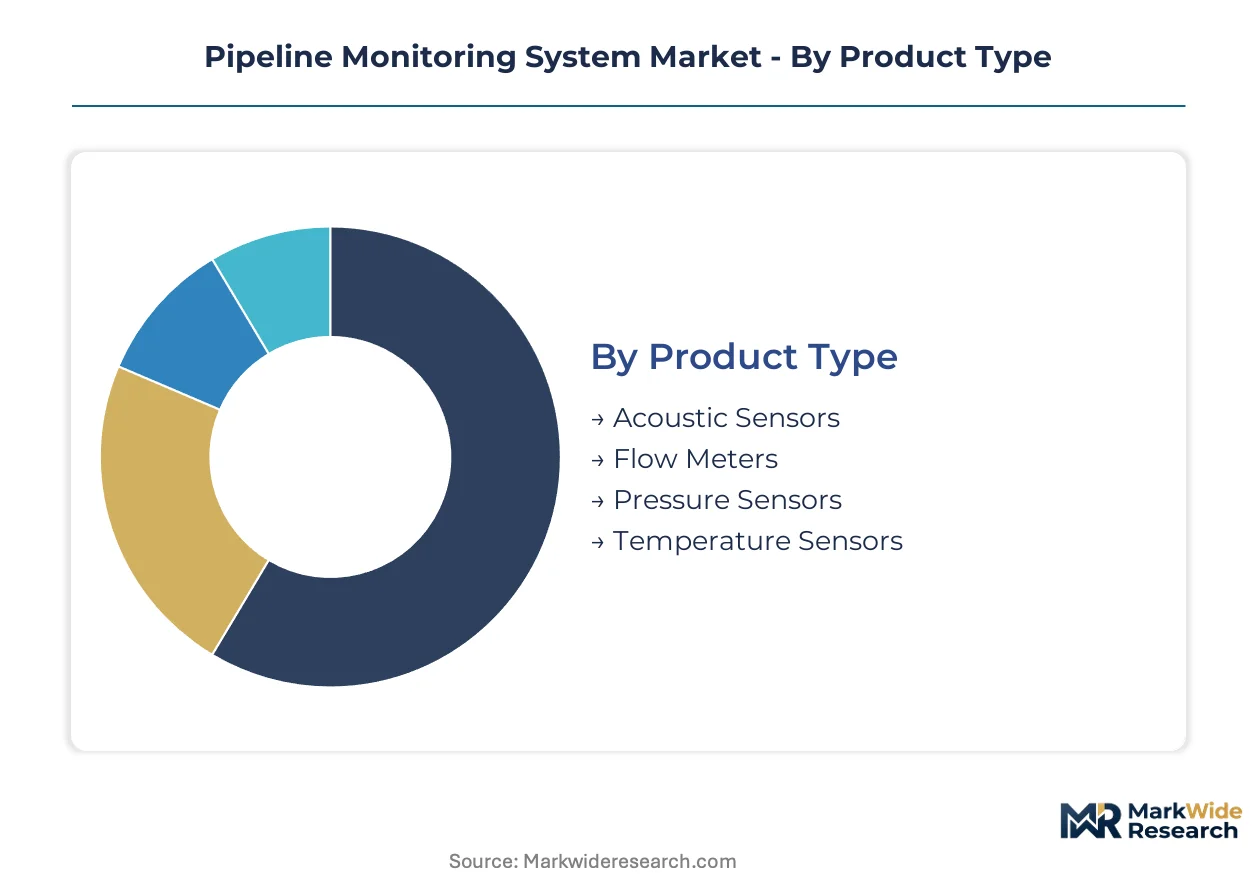
Pipeline monitoring system procurement varies sharply by fluid type, environmental exposure, and integration architecture. Operators match sensor technology to specific failure modes—rupture detection in gas transmission versus corrosion tracking in chemical corridors—creating distinct specification requirements across segments.
Product Type:
Acoustic and pressure sensors dominate leak detection deployments across hydrocarbon networks, while temperature and flow instrumentation serve specialized integrity management functions.
- Acoustic Sensors:Piezoelectric and fiber-optic hydrophone arrays detect pressure wave signatures from wall fractures and third-party strikes. Permian Basin midstream operators deploy these at 500-meter intervals to achieve sub-second rupture identification on high-consequence gas transmission lines.
- Pressure Sensors:Differential and absolute pressure transmitters engineered for sour service conditions track transient events indicating blockages or leaks. Water utilities in Texas and California specify these for non-revenue water reduction programs targeting distribution systems exceeding 15 percent loss rates.
- Flow Meters:Ultrasonic and Coriolis meters quantify throughput discrepancies signaling theft or structural compromise. Chemical corridor operators in India deploy these for caustic soda pipeline integrity verification.
- Temperature Sensors:Distributed fiber optic temperature sensing profiles thermal anomalies from friction or external interference. Subsea installations beyond 3,000 meters depth face pressure vessel limitations, constraining deployment.
The dominant share belongs to pressure sensors, while acoustic sensor deployment is expanding most quickly as distributed fiber architectures displace point-source instrumentation.
Technology:
Integration layer selection determines capital structure and operational flexibility, with legacy SCADA architectures competing against cloud-native alternatives in greenfield projects.
- SCADA:Proprietary polling architectures remain entrenched in existing hydrocarbon networks, requiring substantial retrofit investment to interface with modern analytics platforms. German gas transmission operators face compressed PHMSA-equivalent deadlines for risk-based integrity management compliance.
- Fiber Optic:Distributed acoustic and temperature sensing achieves spatial resolutions under 10 meters without electrical power at monitoring points. Permian Basin operators slash installation costs in hazardous zones through this technology.
- IoT:Subscription-based telemetry platforms enable greenfield water utilities to bypass traditional capital procurement. Municipal buyers in North America evaluate total cost of ownership across decade-long horizons.
- Ultrasonic:Non-intrusive flow measurement and wall thickness monitoring serves corrosion tracking in chemical transport corridors. China's MEE enforces GB standard compliance favoring domestic certification holders.
SCADA retains installed base dominance, though IoT architectures are climbing the fastest as operational expenditure models displace upfront capital sales.
End User:
Regulatory intensity and infrastructure age create divergent procurement timelines across fluid transport sectors.
- Oil & Gas:Methane venting elimination mandates from the EU Methane Regulation and US PHMSA drive continuous emissions monitoring hardware deployment. Optical gas imaging and fixed sensor networks replace intermittent manual surveys.
- Water Utilities:Aging distribution infrastructure in North American municipalities accelerates leak detection investment. California and Texas utilities separate sensor installation from multi-year calibration subscriptions.
- Chemicals:Hazardous material corridor regulations in India mandate integrity management for ammonia and caustic soda routes. Corrosion monitoring systems face specification competitions among domestic and international vendors.
- Mining:Slurry pipeline monitoring addresses abrasive wear and environmental containment requirements. Remote site locations favor self-powered sensing architectures.
Oil and gas commands the largest procurement volumes, while water utilities are gaining share fastest as municipal infrastructure replacement cycles intensify.
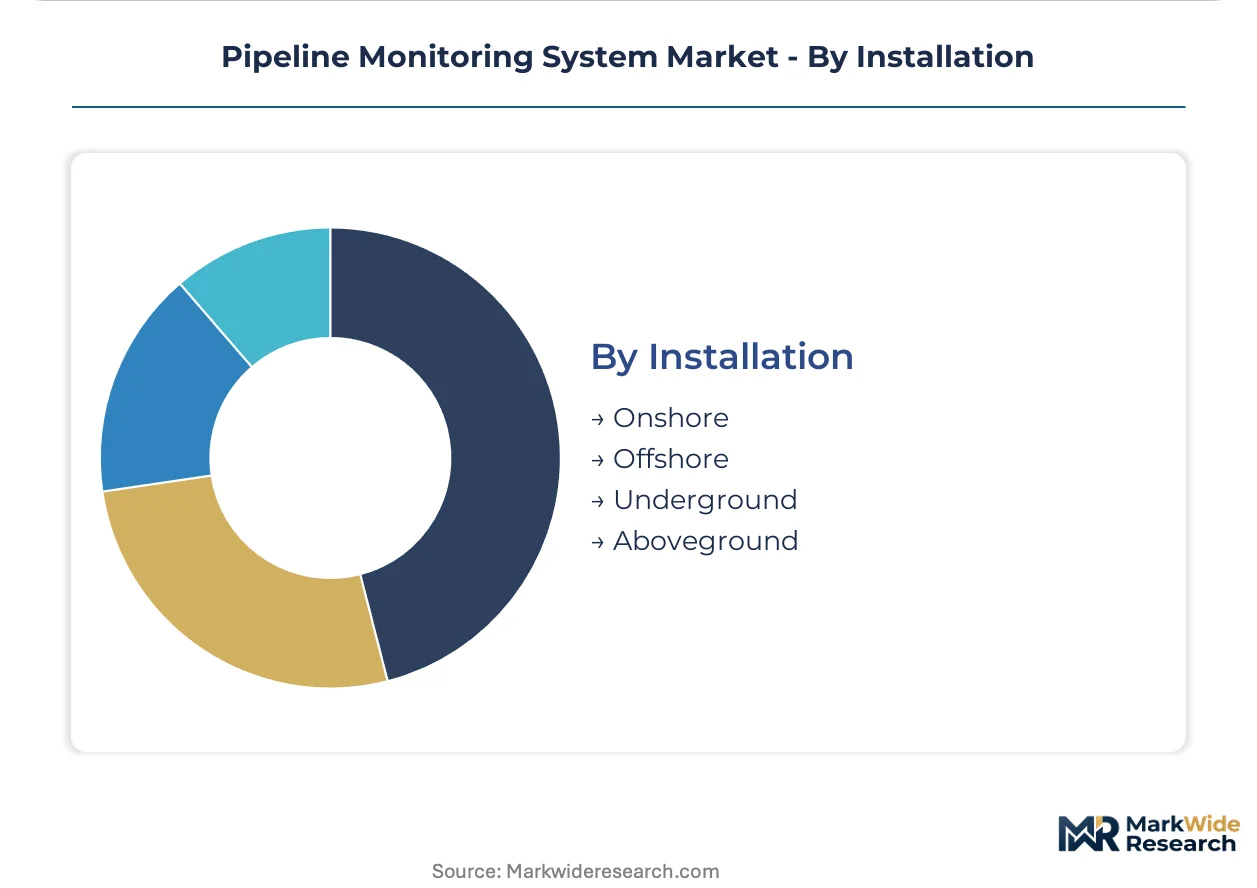
Installation:
Environmental exposure dictates sensor packaging, power availability, and maintenance access economics.
- Onshore:Above-ground and buried pipeline segments across the Permian Basin and European gas corridors support standard telemetry infrastructure with routine technician access.
- Underground:Urban water distribution networks and chemical pipelines in dense industrial zones require non-intrusive monitoring methods. Fiber optic sensing eliminates electrical ignition risks.
- Aboveground:Exposed crossings and compressor station interconnects enable simpler sensor installation but increase third-party damage exposure.
- Offshore:Deepwater segments beyond 3,000 meters exceed current fiber optic pressure ratings. Battery-powered autonomous underwater vehicles provide limited-endurance alternatives.
Onshore installation retains volume leadership, though underground deployment is expanding most quickly as urban infrastructure replacement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Pipeline and Hazardous Materials Safety Administration anchors regulatory pressure across the largest installed base of hydrocarbon transport infrastructure. Integrity management mandates compress implementation timelines for operators from the Permian Basin to the Marcellus Shale.
United States
PHMSA's tightened gas transmission rules and methane venting crackdowns drive hardware procurement across Texas and Louisiana corridors. The Permian Basin midstream sector deploys distributed acoustic sensing at 500-meter intervals to achieve sub-second rupture identification. Houston anchors vendor technical service operations supporting calibration and maintenance contracts.
Germany
The EU Methane Regulation imposes quarterly measurement, reporting, and verification protocols on gas transmission operators. Industrial clusters along the Rhine-Ruhr corridor accelerate replacement of intermittent manual surveys with fixed optical gas imaging networks. BASF's Ludwigshafen chemical complex demands specialized corrosion monitoring for caustic soda pipeline integrity.
China
The Ministry of Ecology and Environment enforces GB standard compliance for hazardous chemical pipeline corridors. Yangtze River Delta petrochemical operators favor domestic certification holders for pressure transmitter specifications. Sinopec's Shanghai refining complex deploys fiber optic temperature sensing across urban distribution networks to eliminate electrical ignition risks.
India
The Petroleum and Natural Gas Regulatory Board mandates integrity management for ammonia and caustic soda transport routes. Gujarat's chemical belt opens specification competitions among international corrosion monitoring vendors. Reliance Industries' Jamnagar complex drives demand for ultrasonic flow meters quantifying throughput discrepancies.
Netherlands
Rotterdam's port authority enforces continuous emissions monitoring at compressor stations and processing facilities. Gasunie's Groningen network transitions from manual surveys to fixed sensor architectures meeting EU reporting deadlines. Eindhoven's instrumentation cluster supplies calibration services for fiber optic distributed sensing deployments.
Pipeline Monitoring System Market Vendor Landscape
Industrial conglomerates and specialized automation houses split the market through divergent channel strategies. Siemens AG leverages digital twin platforms to anchor long-term service contracts, while Emerson Electric Co. competes through sour-service pressure transmitter lines. Honeywell International Inc. controls Middle East distribution through localized calibration facilities. Consolidation pressure intensifies as system integrator channels reconfigure procurement patterns across European gas networks.
Within the industrial automation tier, Siemens AG, Emerson Electric Co., and Honeywell International Inc. exemplify divergent geographic anchoring strategies. Siemens AG represents the European digital-twin service model, Emerson Electric Co. occupies the North American specialized-instrumentation position, and Honeywell International Inc. anchors Middle East technical service infrastructure. Each exemplifies how vendor relationships shift from capital sales toward operational expenditure models as cloud-native IoT architectures penetrate greenfield water utility projects.
| Leading Market Players |
|---|
| Siemens AG |
| Rockwell Automation Inc. |
| ABB Ltd. |
| ORBCOMM Inc. |
| GE Vernova Inc. |
| Emerson Electric Co. |
| Schneider Electric SE |
| Yokogawa Electric Corporation |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in fiber optic distributed sensing manufacturing across Germany and the Netherlands tightens supplier pricing power while compressing delivery timelines for Permian Basin operators. This utilization squeeze forces buyers into longer-term offtake commitments and shifts vendor relationships from transactional procurement toward embedded service contracts.
Pricing Analysis
Price spreads between European and North American deployments exceed 20 percent due to EU Methane Regulation compliance bundling. Three-tier pricing structure across premium certified, standard industrial, and economy retrofit levels dominates hardware procurement. Cost compression in economy-tier SCADA retrofits is intensifying because water utilities demand subscription-based telemetry alternatives. Municipal buyers in Texas exhibit highest price sensitivity, while German gas transmission operators accept premium positioning for continuous emissions monitoring.
Supply Chain Analysis
Tariff exposure between China and the United States concentrates risk for neodymium and dysprosium inputs feeding electromagnetic acoustic transducer production. Manufacturing draws from Chinese rare earth processing, German precision optics fabrication, and Indian corrosion-resistant alloy casting. Single-source vulnerability in deepwater pressure vessel ratings for fiber optic cables constrains subsea deployment economics. Distribution runs through system integrator channels reconfiguring procurement patterns across European gas networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technician scarcity for Rayleigh backscatter interpretation creates bottlenecks at remote pipeline stations, forcing vendors to embed training and calibration within hardware contracts. This capability gap favors integrated service providers over pure equipment manufacturers.
For Market Incumbents: Build switching-cost moats through digital twin platform anchoring. Siemens AG exemplifies long-term service contract lock-in across European gas networks. Incumbents should deepen backward integration into fiber optic cable manufacturing to secure supply against Chinese rare earth volatility. Certification investment for PHMSA-equivalent compliance in Germany and the Netherlands creates defensive positioning against emerging automation houses.
For New Entrants and Emerging Players: Build out localized calibration infrastructure in Gujarat's chemical belt and Texas water utility corridors. India's hazardous material corridor regulations for ammonia and caustic soda routes represent the most penetrable specification competition. Greenfield water utility projects in California bypassing traditional SCADA procurement offer subscription-based telemetry entry points. Channel partnership with municipal engineering consultants accelerates trust formation against entrenched automation conglomerates.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors bundling sensor installation with decade-long calibration and analytics subscriptions. Long-term viability across the analysis window favors operational expenditure model migration over capital equipment pure-plays. Acquisition target archetype: regional system integrators with embedded relationships in Permian Basin midstream operators. Signal to watch: compressed PHMSA certification timelines straining third-party verification capacity, indicating consolidation pressure among verification service providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Siemens AG anchors long-term service contracts across European gas transmission networks through computational fluid dynamics convergence. |
| Fiber Optic Manufacturing Scale-Up | Backward integration into distributed sensing cable production secures supply chains against Chinese rare earth processing volatility. |
| Cloud-Native IoT Architecture Launch | Subscription-based telemetry platforms displace legacy SCADA procurement in greenfield water utility projects across Texas and California. |
| Localized Calibration Facility Expansion | Honeywell International Inc. controls Middle East distribution through technical service infrastructure anchoring maintenance contracts. |
| Corrosion Monitoring System Certification | India's petroleum regulator mandates integrity management for caustic soda routes, opening specification competitions for compliant vendors. |
Methodological Framework
Cross-validation between regulatory filing analysis and operator procurement documentation anchors the qualitative findings. Primary interviews with pipeline integrity managers, SCADA system engineers, municipal water utility procurement officers, and fiber optic sensing technicians combined with secondary validation from PHMSA enforcement records, EU Methane Regulation implementation guidance, and Sinopec equipment tender disclosures. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensure consistency across volume and value estimates.
Calibration against historical deployment trajectories in the Permian Basin and Rhine-Ruhr corridor validates growth assumptions across the projection horizon. The analytical framework models technology type, end-user sector, installation environment, and regional regulatory intensity as core segmentation dimensions. CAGRs derive from installed base expansion rates and replacement cycle compression under tightening integrity management deadlines. Industry-specific inputs include methane venting elimination mandates and non-revenue water loss reduction targets.
Stress conditions across rare earth magnet price volatility, PHMSA certification timeline compression, and subsea pressure vessel rating limitations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
South America City Gas Distribution Market
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Transmission Housing Demand Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
Heat Interface Unit Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market
Transmission and Distribution
Global Virtual Pipeline Systems Market
Transmission and Distribution
Middle East Gas Pipeline Infrastructure Market
Transmission and Distribution
United States High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Pipeline Transportation Market