
 Europe Active Network Management Market | 2026-2036
Europe Active Network Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Active Network Management Market Analytics
Platform licensing revenue is rewriting margin distribution across the value chain. Siemens AG leverages deep substation automation heritage to anchor hardware-software bundles in Central European utilities. Smarter Grid Solutions competes through specialized distributed energy resource management for wind-rich grids. Schneider Electric extends its building-to-grid integration expertise into active network management deployments.
Active network management comprises real-time software and control hardware that monitors voltage, frequency, and power flow across electricity distribution networks to autonomously balance supply and demand. The technology typically processes sensor data at sub-second intervals to execute capacitor switching, transformer tap adjustments, or load curtailment commands. Software and platforms command the dominant margin pools as recurring subscription models displace perpetual licenses. Grid optimization solutions within the solution type dimension attract accelerating investment as congestion management replaces simple monitoring. Cloud-based and hybrid deployment models are gaining share against on-premises installations where cybersecurity requirements permit.
The EU Green Deal and F-Gas Regulation shape equipment replacement timelines and refrigerant-based switchgear retirement schedules. CE marking and MDR conformity requirements filter non-compliant control hardware from European procurement channels. Stakeholders must track how national regulatory implementation varies between EMA-aligned pharmaceutical load centers and industrial zones governed by ECHA chemical safety protocols.
Market Dynamics
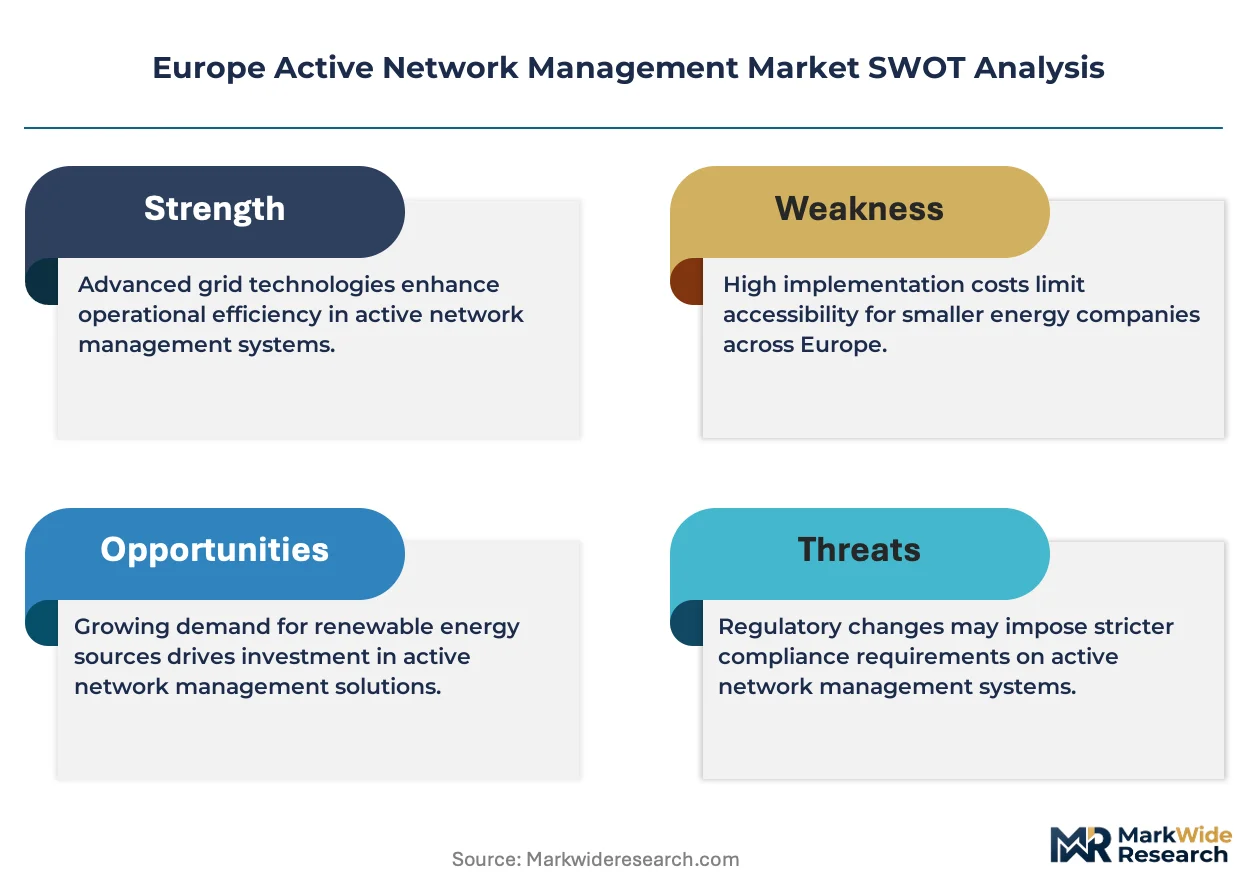
EU Green Deal mandates and F-Gas Regulation deadlines are compressing equipment replacement cycles across European distribution networks, forcing utilities to retire sulfur hexafluoride switchgear and deploy real-time control platforms simultaneously.
Growth Catalysts
- Renewable intermittency management:Wind and solar penetration in Germany's northern coastal zones requires sub-second voltage response capabilities that legacy SCADA cannot deliver.
- F-Gas Regulation phase-out:The 2027 ban on fluorinated greenhouse gases in switchgear accelerates procurement of digitally controlled, SF6-free substation equipment across France and Italy.
- Industrial microgrid expansion:Factory complexes in the Netherlands and Belgium are installing island-capable controls to secure power quality for semiconductor and chemical process loads.
Market Restraints
- Cybersecurity compliance costs:NIS2 Directive implementation forces utilities to segment operational technology networks, adding 15-25% to platform deployment budgets.
- Copper and rare earth price volatility:Power electronics and sensor hardware face input cost pressure from concentrated Chilean copper and Chinese magnet supply.
- Interoperability fragmentation:Proprietary communication protocols between Siemens, ABB, and Schneider Electric legacy systems delay multi-vendor integration timelines.
Strategic Opportunities
- Eastern European grid modernization:Poland and Romania hold substantial backlogs of Soviet-era substation automation requiring complete replacement by 2030.
- Building-to-grid flexibility aggregation:Commercial HVAC and EV charging loads in Nordic cities present untapped demand response capacity for virtual power plant operators.
- AI-driven predictive control:Machine learning convergence with digital twin simulation enables anticipatory rather than reactive network balancing.
Industry Challenges
- Substation automation engineering shortage:European utilities compete for power systems engineers capable of integrating IEC 61850 protocols with cloud architectures.
- CE marking and MDR conformity complexity:Control hardware vendors face extended certification timelines for safety-critical grid applications.
- Multi-decade asset interoperability:New software platforms must communicate with 1980s-era electromechanical protection relays still operational in rural Spanish and Portuguese networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Active Network Management Market |
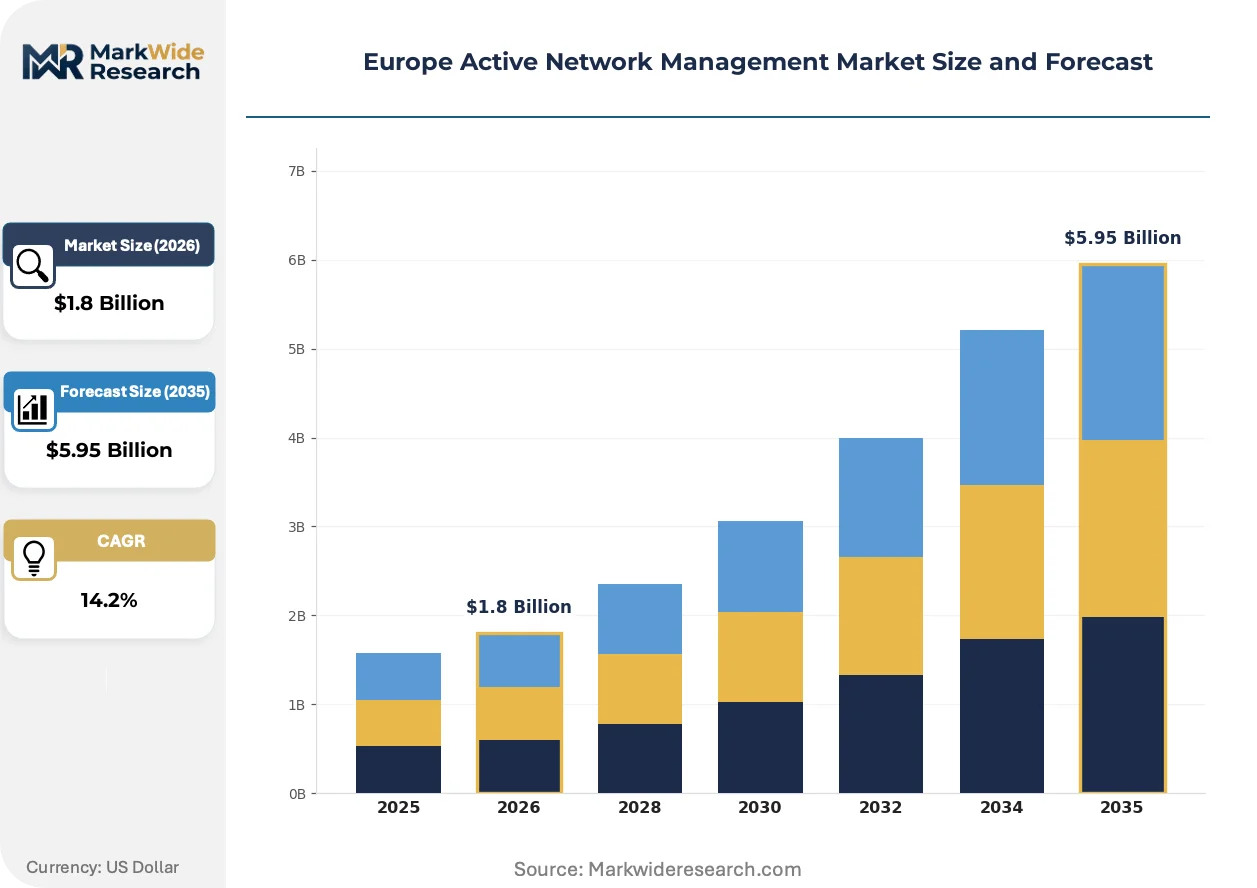
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Platforms Solution Type: Demand Response, Energy Storage, Load Forecasting, Grid Optimization End User: Utilities, Industrial, Commercial, Residential Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | General Electric Company, Cisco Systems Inc, Siemens AG, Oracle Corp, International Business Machines Corp, ABB Ltd, Honeywell International Inc, Smarter Grid Solutions, Schneider Electric, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Active Network Management Market Evolving Landscape
Edge computing architectures are displacing centralized control rooms across European distribution utilities, embedding intelligence directly at transformer substations and feeder nodes.
Containerized microservices running on ruggedized edge hardware are rendering obsolete monolithic SCADA architectures that required dedicated control centers and leased communication circuits. German DSOs including E.ON and EnBW are deploying these platforms at 200+ substations annually. The shift compresses response latency from seconds to milliseconds while eliminating single points of failure.
The EU AI Act's risk classification framework for critical infrastructure is reshaping vendor development roadmaps. Machine learning algorithms deployed for predictive grid control must now demonstrate explainability and human oversight capabilities. French and Italian regulators are requiring algorithmic impact assessments before approving autonomous switching functions, slowing deployment in high-risk categories.
Subscription-based platform licensing is replacing perpetual software purchases among municipal utilities with constrained capital budgets. Dutch and Danish DSOs now favor operational expenditure models that bundle cybersecurity updates and predictive maintenance analytics. This shift concentrates recurring revenue with incumbent vendors possessing established cloud infrastructure while squeezing smaller competitors dependent on upfront license sales.
Europe Active Network Management Market Segmentation
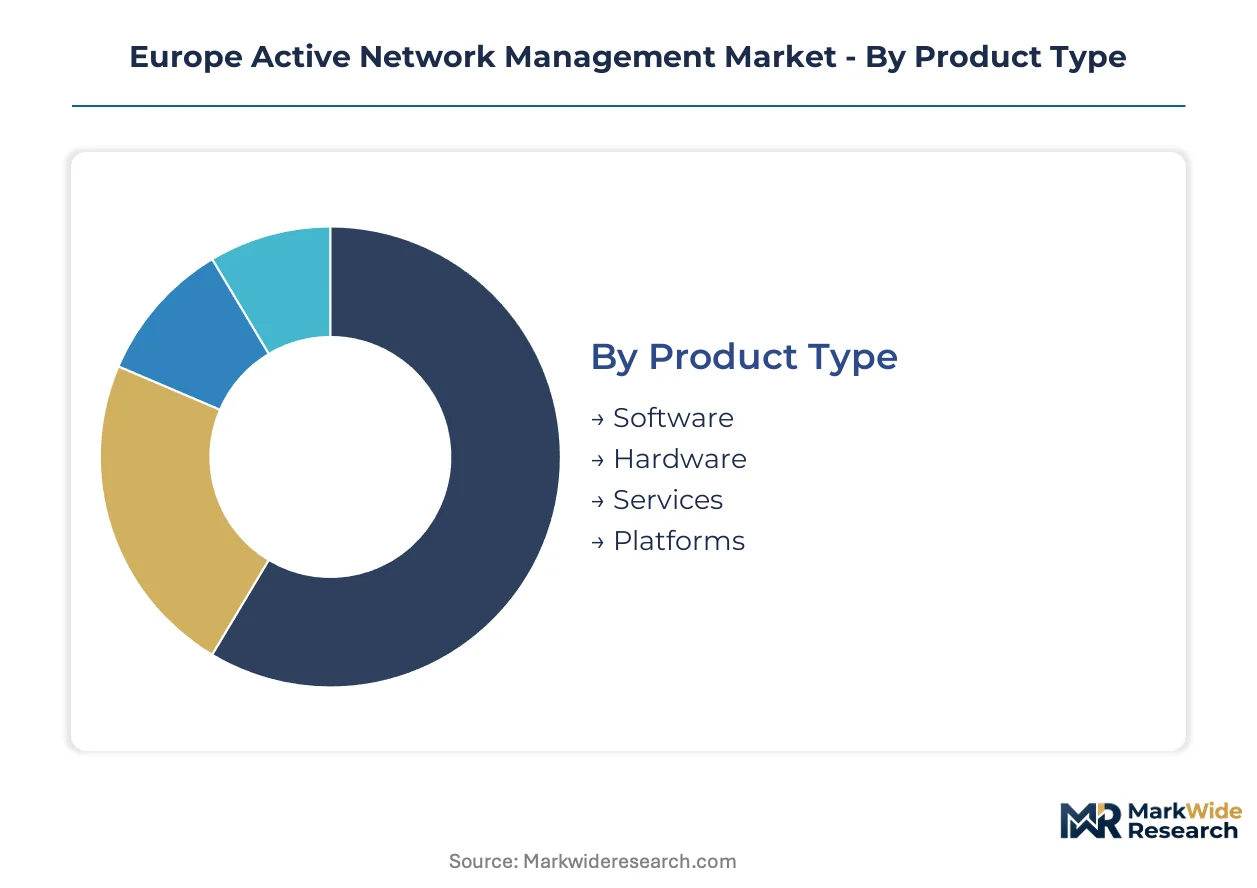
Active network management vendors structure their offerings across four critical dimensions that determine procurement patterns and margin capture. Product type and solution type govern technology architecture decisions, while end user and deployment model shape go-to-market economics and implementation complexity.
Product Type:
Mature hardware categories coexist with emerging platform models that are rewriting revenue recognition across the value chain.
- Software:Real-time control algorithms process voltage and frequency data at millisecond intervals to execute autonomous switching decisions. German and French distribution system operators prioritize subscription-based licensing for grid optimization modules to convert capital expenditure into operational budgets.
- Hardware:Ruggedized controllers, sensors, and communication gateways form the physical layer of active network management deployments. Industrial microgrids in the Netherlands and Belgium drive procurement of IEC 61850-compliant intelligent electronic devices for factory power quality assurance.
- Services:System integration, commissioning, and ongoing technical support ensure interoperability between multi-vendor substation equipment. Eastern European utilities in Poland and Romania rely on external engineering capacity to address local skill shortages.
- Platforms:Unified software ecosystems combine monitoring, control, and analytics into integrated operational technology stacks. Nordic municipal utilities favor cloud-native platforms that bundle cybersecurity updates and predictive maintenance.
Software handles the majority of throughput; Platforms are climbing the fastest on share as subscription models displace perpetual licenses.
Solution Type:
Cost tier differentiation separates commodity monitoring from premium predictive control capabilities that command implementation premiums.
- Demand Response:Automated load curtailment systems modulate industrial and commercial consumption during grid stress events. Commercial HVAC and EV charging operators in Nordic cities aggregate flexibility capacity for virtual power plant participation.
- Energy Storage:Battery management integration enables arbitrage, frequency regulation, and backup power for critical loads. Island-capable controls secure semiconductor and chemical process operations in Dutch industrial zones.
- Load Forecasting:Machine learning models predict consumption patterns to optimize dispatch and reduce peak demand charges. Spanish and Portuguese utilities deploy these tools to manage renewable intermittency in solar-rich southern regions.
- Grid Optimization:Advanced power flow algorithms minimize losses and alleviate congestion across meshed distribution networks. German DSOs in northern coastal wind zones invest heavily in sub-second voltage response capabilities.
Grid Optimization handles the majority of throughput; Demand Response is gaining share fastest as building-to-grid flexibility aggregation matures.
End User:
Customer type determines procurement authority, with utilities holding centralized budgets and industrial users driving technical specification.
- Utilities:Distribution system operators own network infrastructure and mandate interoperability standards across their territories. CE marking and MDR conformity requirements filter non-compliant control hardware from European procurement channels.
- Industrial:Factory complexes and process plants require island-capable microgrids to protect sensitive manufacturing equipment. Chemical and pharmaceutical load centers in Germany's industrial corridor demand voltage stabilization independent of grid conditions.
- Commercial:Office buildings, retail centers, and logistics facilities seek demand response revenue streams and resilience services. Building-to-grid integration expertise from building automation vendors extends into active network management deployments.
- Residential:Single-family and multi-unit dwellings participate through aggregated virtual power plant programs rather than direct control. Smart home energy management interfaces remain nascent outside pilot programs in Denmark and the Netherlands.
Utilities handle the majority of throughput; Industrial is expanding most quickly as factory microgrids proliferate.
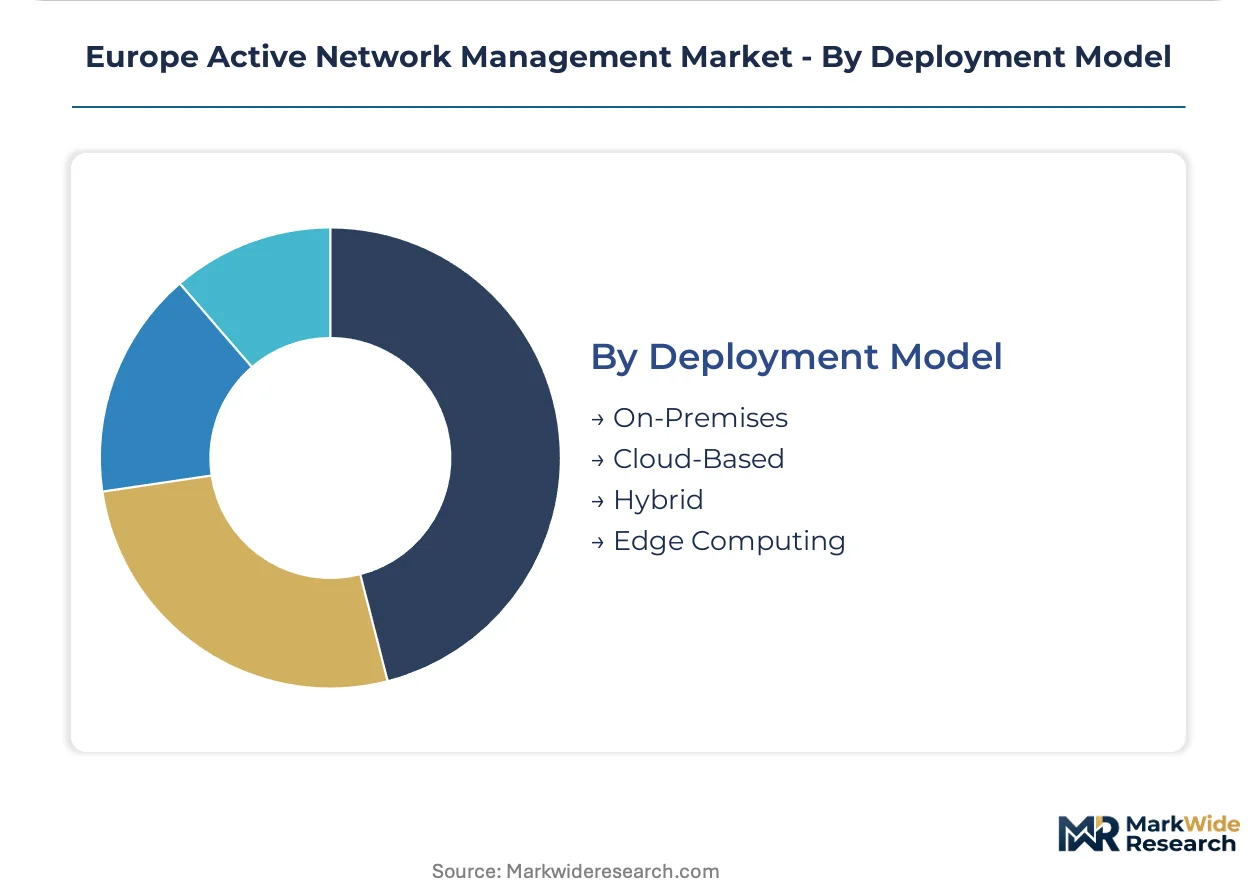
Deployment Model:
Volume concentration favors established on-premises architectures while hybrid models capture growth in security-sensitive applications.
- On-Premises:Dedicated control centers with leased communication circuits remain standard for critical infrastructure operators. NIS2 Directive implementation forces network segmentation that preserves legacy operational technology investments.
- Cloud-Based:Centralized software-as-a-service reduces capital requirements for municipal utilities with constrained budgets. Dutch and Danish DSOs favor operational expenditure models that bundle continuous feature updates.
- Hybrid:Sensitive control functions remain local while analytics and visualization migrate to cloud infrastructure. French and Italian regulators require algorithmic impact assessments before approving autonomous switching in high-risk categories.
- Edge Computing:Containerized microservices deploy directly at transformer substations and feeder nodes. German DSOs including E.ON and EnBW install these platforms at hundreds of substations annually to compress response latency.
On-Premises handles the majority of throughput; Edge Computing shows the steepest expansion trajectory as latency requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and French utilities anchor European procurement volumes for active network management platforms, while Eastern European backlogs and Nordic flexibility aggregation create distinct growth corridors across the continent.
Germany
Distribution system operators in Germany's northern coastal wind zones demand sub-second voltage response capabilities that legacy SCADA cannot deliver. The EU Green Deal and F-Gas Regulation accelerate retirement schedules for sulfur hexafluoride switchgear. Factory microgrids in the industrial corridor around Cologne and the Ruhr region require island-capable controls for chemical and pharmaceutical process loads.
France
French regulators under the EU AI Act mandate algorithmic impact assessments before approving autonomous switching functions in high-risk grid categories. EDF and Enedis prioritize hybrid deployment models where sensitive control functions remain local while analytics migrate to cloud infrastructure. The Provence-Alpes-Côte d'Azur region hosts pilot programs for building-to-grid flexibility aggregation from commercial HVAC systems.
United Kingdom
UK Power Networks and National Grid ESO expand procurement of real-time grid control platforms to manage renewable intermittency from North Sea offshore wind. NIS2 Directive implementation forces network segmentation that adds cybersecurity compliance costs to platform deployment budgets. The Midlands and North England industrial zones drive demand for voltage stabilization independent of grid conditions.
Netherlands
Dutch distribution system operators favor subscription-based platform licensing that converts capital expenditure into operational budgets. The country's national energy regulator accelerates approval timelines for cloud-native platforms bundling cybersecurity updates. Semiconductor fabrication facilities in Eindhoven and chemical process plants in Rotterdam require power quality assurance through intelligent electronic devices.
Poland
Polish utilities hold substantial backlogs of Soviet-era substation automation requiring complete replacement by 2030. CE marking and MDR conformity requirements filter non-compliant control hardware from European procurement channels. Warsaw and the Silesian industrial basin represent concentrated demand for external engineering capacity to address local skill shortages in substation automation.
Europe Active Network Management Market Competitive Landscape
Industrial conglomerates and specialized software vendors split the market into distinct capability tiers. Siemens AG, ABB Ltd, and Schneider Electric anchor the hardware-software bundle segment through deep substation automation heritage. Smarter Grid Solutions occupies a specialized position in distributed energy resource management for wind-rich grids. Competitive moves concentrate on M&A activity targeting edge computing capabilities and strategic partnerships bundling cybersecurity with platform licensing.
Within the industrial conglomerate tier, Siemens AG and ABB Ltd represent archetypal players leveraging decades of substation equipment relationships to anchor integrated operational technology stacks. Schneider Electric extends building-to-grid integration expertise into active network management deployments, exemplifying cross-sector capability transfer. Among specialized software vendors, Smarter Grid Solutions occupies a position focused on distributed energy resource management for renewable-intensive grids. These three companies collectively illustrate the market's bifurcation between scale-driven hardware-software bundles and niche predictive control specialization.
| Leading Market Players |
|---|
| General Electric Company |
| Cisco Systems Inc |
| Siemens AG |
| Oracle Corp |
| International Business Machines Corp |
| ABB Ltd |
| Honeywell International Inc |
| Smarter Grid Solutions |
| Schneider Electric |
| Others |
Value Network & Pricing Analysis
Chilean copper and Chinese rare earth magnet supply concentration anchors hardware cost structures, while software margin pools concentrate with vendors controlling cloud infrastructure and recurring subscription platforms. The downstream split between capital-constrained municipal utilities and industrial microgrid operators creates divergent pricing power dynamics across deployment archetypes.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for algorithmic grid control systems, separating explainable low-risk automation from high-risk autonomous switching requiring regulatory impact assessments. Three-tier pricing structure across premium certified, standard compliant, and economy monitored levels reflects CE marking complexity and cybersecurity bundling. Cost compression in economy tiers is intensifying because NIS2 Directive compliance forces 15-25% budget additions for network segmentation. Municipal utilities in the Netherlands and Denmark exhibit highest price sensitivity, favoring operational expenditure models; German industrial corridor buyers prioritize island-capable controls regardless of premium positioning.
Supply Chain Analysis
Extended payment terms from German and French distribution system operators strain component suppliers, accelerating supply-chain finance facility adoption among power electronics vendors. Manufacturing concentrates in Germany, China, and South Korea for intelligent electronic devices and magnet-dependent sensors. Hardware production draws from Chilean copper, Chinese rare earth elements, and Taiwanese semiconductor components. Single-source vulnerability in rare earth processing creates exposure to export restriction shocks. Distribution runs through systems integrators and direct utility procurement channels, with Eastern European markets relying heavily on external engineering capacity for commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-native platform entrants bundling cybersecurity and predictive analytics, threatening traditional hardware-software bundle economics. Defense requires insulating recurring revenue streams while capturing edge computing growth corridors.
For Market Incumbents: Insulate subscription platform revenue through embedded cybersecurity update bundling that locks municipal utilities into operational expenditure relationships. Deepen backward integration into edge computing hardware production to capture latency-sensitive German wind zone deployments. Counter Smarter Grid Solutions' distributed energy resource specialization by acquiring predictive control algorithm capabilities.
For New Entrants and Emerging Players: Build out white-space positions in Eastern European grid modernization, where Polish and Romanian Soviet-era replacement backlogs exceed local engineering capacity. Target hybrid deployment models for French and Italian regulators requiring local control function retention with cloud analytics migration. Lead with algorithmic explainability tooling that accelerates EU AI Act compliance timelines for high-risk autonomous switching categories.
For Investors and Strategic Acquirers: Capital is best deployed toward edge computing specialists with IEC 61850 protocol expertise and containerized microservice architectures. Long-term viability across the analysis window favors vendors bridging operational technology-IT convergence with demonstrated utility deployment scale. Monitor algorithmic impact assessment approval velocity at French and Italian regulators as inflection indicator for high-risk category market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified operational technology stacks displace fragmented SCADA architectures at German DSOs. |
| Acquisition of Specialist Firm | Edge computing capabilities address sub-second latency requirements in northern coastal wind zones. |
| Strategic Partnership | Cybersecurity bundling with platform licensing captures NIS2 Directive compliance budgets. |
| Geographic Expansion | Eastern European engineering capacity addresses Polish and Romanian automation backlogs. |
| Product Launch | Explainable AI control modules accelerate EU AI Act high-risk category approvals. |
Research Methodology
The analysis maps software platforms, hardware controllers, and services integration, each validated through distribution system operator planning officers, substation automation engineers, and industrial microgrid operators. Primary interviews with utility procurement managers and EPC contractors combined secondary validation from ENTSO-E transparency data, national regulatory filings, and IEC standard committee documentation. Bottom-up deployment tracking and top-down market sizing triangulate volume estimates across the projection horizon.
Assumptions held EU Green Deal implementation timelines and F-Gas Regulation phase-out schedules fixed while varying renewable penetration rates and cybersecurity compliance cost trajectories. Segmentation dimensions modeled include product type, solution type, end user category, and deployment architecture across the analysis window. CAGRs derive from utility capital expenditure plans and industrial microgrid investment pipelines, with German offshore wind integration timelines and Dutch cloud-native platform adoption curves as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed platform entrants or state-sponsored Chinese automation vendors would shift outcomes. Macroeconomic deviation in copper and rare earth pricing, regulatory acceleration of EU AI Act enforcement, or breakthrough solid-state transformer commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Power Transmission Cables Market
Transmission and Distribution
Pipeline Monitoring System Market
Transmission and Distribution
Power Transmission Tower Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
India HVDC Transmission Systems Market
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
Water Storage System Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
North America DC Distribution Network Market
Transmission and Distribution
HVDC Transmission Systems Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Underground Cabling EPC Market