
 Transmission Housing Demand Market | 2026-2036
Transmission Housing Demand Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission Housing Demand Market Analytics
Passenger car electrification is shifting demand away from traditional multi-speed automatic housings toward single-speed reduction gear enclosures. BorgWarner leverages its powertrain electronics integration to compete in electrified architectures. Aisin Corporation anchors Japanese OEM supply chains with precision-machined aluminum housings. ZF Friedrichshafen dominates European commercial vehicle transmission housing production through captive foundry capacity.
Transmission housing denotes the rigid structural enclosure that contains gear sets, shafts, bearings, and lubrication circuits, typically manufactured from die-cast aluminum alloy A380 or compacted graphite iron to achieve tensile strengths exceeding 300 MPa while maintaining dimensional stability under cyclic thermal loads. Its primary purpose is to protect internal powertrain components, retain lubricating oil, and manage heat dissipation in rotational power transfer systems. Aluminum material grades command the largest volume share due to OEM lightweighting mandates, though cast iron sustains margin pools in heavy-duty commercial applications where fatigue resistance outweighs mass reduction targets. Machining technology leads value-added processing for tight-tolerance bearing bores, while 3D printing occupies emerging prototyping and repair segments for custom housing geometries.
EPA fuel economy regulations and EU F-Gas restrictions on fluorinated greenhouse gases shape material selection and sealing system designs across North American and European supply chains. China's MIIT dual carbon goals enforce energy intensity benchmarks on domestic foundries supplying transmission castings. Stakeholders must monitor evolving powertrain electrification rates to calibrate capacity investments between traditional multi-speed and single-speed e-axle housing architectures.
Market Dynamics
Passenger vehicle electrification is compressing demand for multi-speed automatic housings while amplifying single-speed e-axle enclosure requirements. This powertrain transition is forcing foundries to reallocate die-casting capacity between legacy transmission architectures and electrified powertrain components.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:OEMs in the United States are substituting aluminum A380 die castings for cast iron to achieve mass reduction targets in passenger car powertrains.
- China MIIT dual carbon goals:Energy intensity benchmarks on domestic foundries are accelerating investment in electric melting furnaces and regenerative thermal oxidizers for emission control.
- E-axle housing demand:Electric vehicle powertrain adoption among passenger car OEMs is generating pull for single-speed reduction gear enclosures with integrated thermal management.
Market Restraints
- Primary aluminum price volatility:LME aluminum price swings above fifteen percent annually are compressing margin pools for independent die-casting suppliers without backward integration into smelting operations.
- Foundry concentration in Germany:European commercial vehicle transmission housing supply chains exhibit heavy reliance on captive foundry capacity controlled by tier-one powertrain integrators.
- EU F-Gas restrictions:Fluorinated greenhouse gas limitations on sealing system designs are extending validation timelines for new transmission housing gasket and O-ring specifications.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for advanced automotive technology components are attracting greenfield die-casting investments to serve domestic OEM assembly operations.
- 3D printing repair segments:Directed energy deposition processes are enabling custom housing geometries for remanufacturing and aftermarket replacement in heavy-duty commercial fleets.
- Powertrain electronics convergence:Integration of inverter and motor controller enclosures with reduction gear housings is opening white space for mechatronics-capable suppliers.
Industry Challenges
- CNC machining skill scarcity:Tight-tolerance bearing bore finishing requires journeyman-level machinists that foundries struggle to recruit in manufacturing clusters across the United States and Germany.
- Multi-material joining certification:Aluminum-to-steel laser welding for hybrid housing assemblies demands new weld procedure qualification protocols that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission Housing Demand Market |
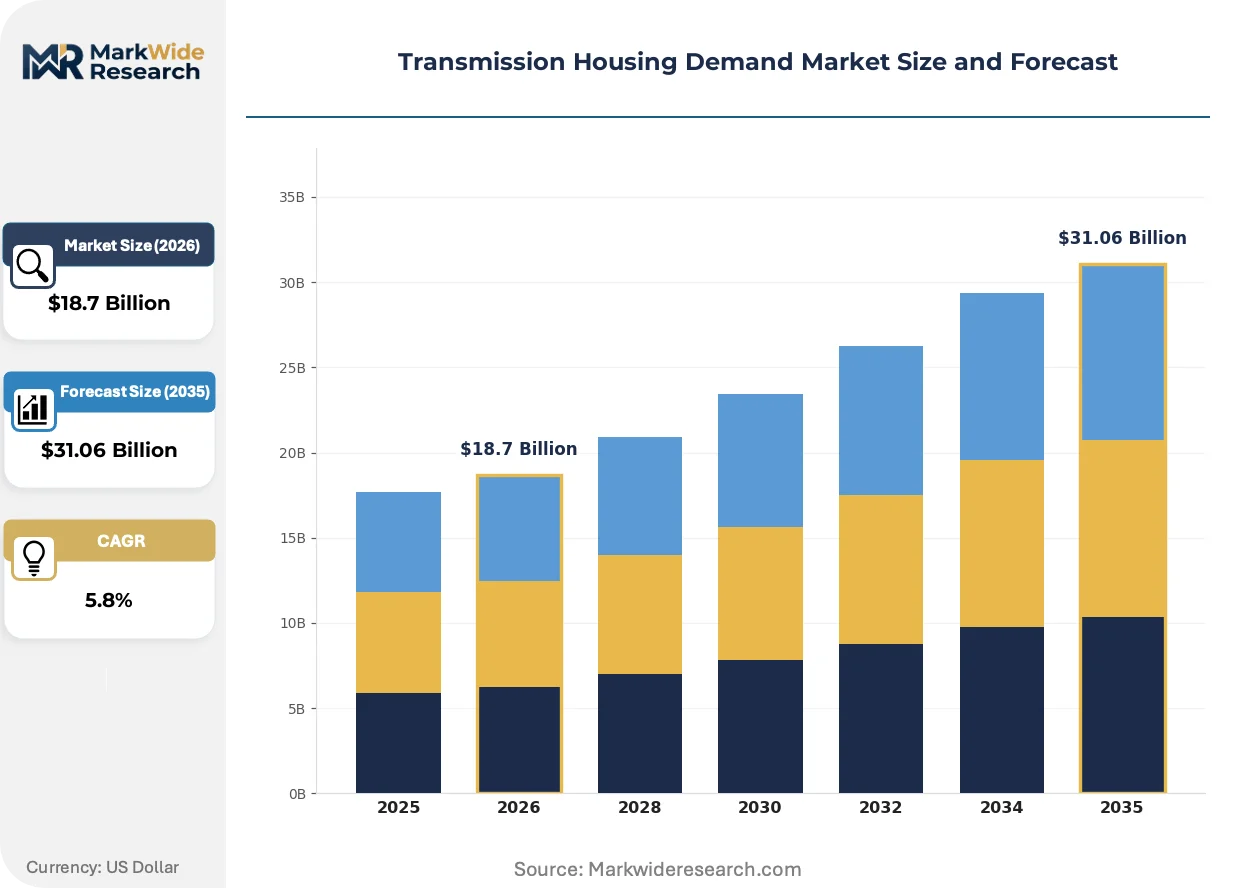
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automotive, Aerospace, Marine, Industrial Equipment Material: Aluminum, Steel, Cast Iron, Composite Size: Small, Medium, Large, Custom Technology: Machining, Injection Molding, 3D Printing, Stamping |
| Companies Covered | BorgWarner, American Axle & Manufacturing, Aisin Corporation, GKN Automotive, Carraro Group, Magna International, Schaeffler Group, Dana Incorporated, ZF Friedrichshafen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission Housing Demand Market Evolving Landscape
Material substitution and manufacturing process evolution are redefining transmission housing performance specifications. Electrification is compressing product lifecycles while amplifying thermal management requirements.
High-pressure die-cast aluminum alloy A380 with vacuum-assisted venting is overtaking traditional gravity-fed sand casting for passenger car transmission housings. OEM lightweighting mandates in Europe and North America are accelerating adoption rates. This process shift is enabling wall thickness reductions below three millimeters while maintaining structural rigidity under cyclic thermal loads.
EU F-Gas Regulation amendments are restricting hydrofluorocarbon-based sealing materials in transmission gasket systems. Compound suppliers are reformulating fluoroelastomer specifications to comply with GWP thresholds below 150. Commercial vehicle manufacturers in Germany are qualifying hydrogenated nitrile butadiene rubber alternatives ahead of passenger car programs.
Fleet operators are unbundling transmission housing remanufacturing from dealer service networks. Independent rebuilders in the United States are sourcing bare housings directly from foundries for in-house machining and assembly. This channel disintermediation is most visible in Class 8 truck aftermarket supply chains serving long-haul carriers.
Transmission Housing Demand Market Segmentation
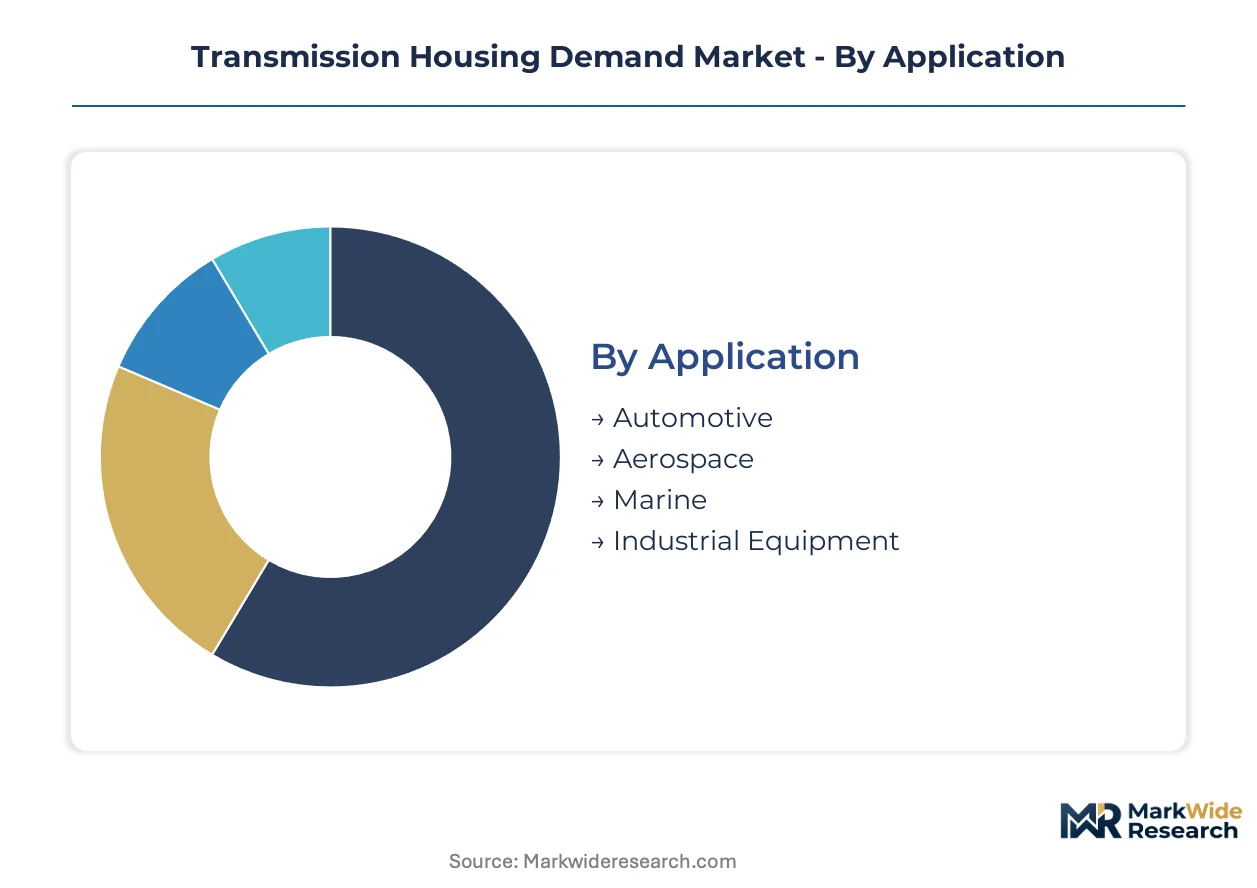
Transmission housing procurement decisions pivot on thermal load requirements, weight reduction mandates, and powertrain electrification timelines. Material selection and manufacturing technology choices determine supplier qualification pathways and foundry capacity allocation. Each segmentation dimension carries distinct margin structures and technical barriers to entry.
Application:
End-use thermal cycling intensity and regulatory exposure dictate housing specification tiers across buyer segments.
- Automotive:Die-cast aluminum alloy A380 dominates passenger car and commercial vehicle programs where OEM lightweighting mandates intersect with high-volume die-casting economics. Demand bifurcates between multi-speed automatic housings for internal combustion powertrains and single-speed reduction gear enclosures for battery-electric architectures. China's MIIT dual carbon goals and EPA Corporate Average Fuel Economy standards enforce material substitution toward aluminum in this segment.
- Aerospace:Precision-machined aluminum housings for auxiliary power units and gearbox assemblies require AS9100 certification and NDT validation protocols. Weight-critical applications in regional jet turboprop transmissions drive titanium alloy adoption despite cost premiums. Boeing and Airbus tier-one suppliers in Wichita, Kansas and Toulouse, France anchor demand concentration.
- Marine:Saltwater corrosion resistance prioritizes A356 aluminum with chromate conversion coatings or marine-grade stainless steel in outboard motor lower units. Pleasure craft outboard engines from Mercury Marine and Yamaha Motor concentrate procurement in Wisconsin and Japan manufacturing clusters.
- Industrial Equipment:Forklift transmission housings and construction machinery powertrain enclosures tolerate higher mass for durability, sustaining gray iron casting demand. Caterpillar and Komatsu captive foundries in Illinois and Osaka control supply chain access.
Volume sits with Automotive; growth tilts toward Aerospace as urban air mobility programs expand.
Material:
Strength-to-weight ratios and foundry energy intensity shape raw material selection across cost-performance tiers.
- Aluminum:High-pressure die-cast A380 with vacuum-assisted venting achieves tensile strengths exceeding 320 MPa while enabling wall thickness below three millimeters. European and North American passenger car OEMs specify this grade for EPA and EU CO2 compliance. LME price volatility above fifteen percent annually compresses independent supplier margins.
- Cast Iron:Compacted graphite iron delivers fatigue resistance for Class 8 truck transmissions where duty cycles exceed one million kilometers. ZF Friedrichshafen and Daimler Truck captive foundries in Germany control European supply. Energy intensity benchmarks under China's MIIT regulations disadvantage independent iron foundries without electric melting furnace investment.
- Steel:Forged alloy steel housings survive extreme shock loads in mining truck powertrains. Limited to low-volume specialty applications due to machining cost penalties versus cast alternatives.
- Composite:Carbon fiber-reinforced polymer prototypes for motorsport transmission enclosures demonstrate thirty percent mass reduction potential. Thermoplastic stampability remains unproven at automotive production volumes.
Aluminum claims volume leadership; cast iron defends margin pools in heavy-duty commercial segments.
Size:
Tooling amortization schedules and batch economics determine competitive positioning across dimensional categories.
- Medium:Passenger car automatic transmission housings occupy this tier with standardized die-cast tooling platforms enabling multi-OEM program sharing. Tooling investments recover across million-unit annual volumes.
- Large:Commercial vehicle and off-highway equipment housings require custom die designs with slower cycle times. Captive foundry integration dominates due to dedicated tooling risk concentration.
- Small:Motorcycle and powersports transmission enclosures leverage existing aluminum die-casting infrastructure with minimal incremental capital.
- Custom:Prototype and aftermarket remanufacturing tolerates CNC machining from solid billet at unit economics incompatible with serial production.
Medium size categories absorb majority capital deployment; custom segments expand through 3D printing repair applications.
Technology:
Dimensional tolerance requirements and surface finish specifications filter supplier capabilities across process alternatives.
- Machining:Five-axis CNC finishing of bearing bores achieves ISO IT6 tolerances mandatory for gearbox shaft alignment. Journeyman machinist scarcity in United States and German manufacturing clusters constrains capacity expansion.
- Injection Molding:Thermoplastic structural foam prototypes enable design validation before die-cast tooling commitment. Limited to non-structural beauty covers and cable routing channels.
- 3D Printing:Directed energy deposition repairs cracks in cast iron commercial vehicle housings without full replacement. Fleet operators in North American long-haul trucking adopt this for remanufacturing cost reduction.
- Stamping:Hybrid aluminum-steel assemblies laser-weld stamped cover plates to cast main housings. Multi-material joining certification protocols extend product launch timelines.
Machining commands value-added processing; 3D printing gains traction fastest in aftermarket repair channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones and automotive manufacturing clusters concentrate transmission housing production in countries with integrated foundry-to-assembly supply chains. Tax incentives and proximity to OEM final assembly plants drive capacity location decisions. Regulatory pressure on emissions and fuel economy shapes material substitution patterns across manufacturing hubs.
China
Domestic EV powertrain adoption generates demand for single-speed reduction gear enclosures among passenger car OEMs. MIIT dual carbon goals enforce energy intensity benchmarks on foundries supplying transmission castings. Yangtze River Delta manufacturing clusters around Shanghai anchor die-casting capacity serving BYD and SAIC Motor assembly operations.
Germany
Commercial vehicle transmission housing production relies on captive foundry capacity controlled by tier-one powertrain integrators. EU F-Gas Regulation restricts fluorinated greenhouse gases in sealing system designs. Baden-Württemberg industrial corridors around Stuttgart concentrate precision-machining capabilities for tight-tolerance bearing bores.
United States
EPA Corporate Average Fuel Economy standards mandate aluminum substitution for cast iron in passenger car powertrains. Independent rebuilders in long-haul trucking corridors source bare housings directly from foundries for remanufacturing. Midwest manufacturing clusters in Michigan and Ohio retain machining expertise for Class 8 truck transmission assemblies.
Japan
Precision-machined aluminum housings anchor domestic OEM supply chains with exacting dimensional stability requirements. METI industrial policy supports foundry modernization for electrified powertrain component production. Aichi Prefecture manufacturing zones around Toyota City concentrate tier-one supplier operations for hybrid and battery-electric architectures.
India
PLI scheme incentives for advanced automotive technology components attract greenfield die-casting investments. Domestic OEM assembly operations in passenger and commercial vehicle segments drive localization requirements. Tamil Nadu and Gujarat automotive corridors near Chennai and Ahmedabad host expanding foundry capacity for transmission castings.
Transmission Housing Demand Market Competitive Landscape
Top-tier vendors anchor integrated powertrain systems, while mid-tier specialists concentrate on discrete housing fabrication. The vendor base stratifies across captive foundry operators serving OEMs directly and independent suppliers competing on machining precision. Three archetypes dominate: integrated powertrain houses with in-house casting, aluminum die-casting specialists with automotive certification, and commercial vehicle remanufacturing channels. Competitive moves center on capacity reallocation between multi-speed automatic and single-speed e-axle architectures, plus selective backward integration into smelting operations.
Within the integrated powertrain tier, BorgWarner and ZF Friedrichshafen exemplify vendors with captive electronics-housing convergence capabilities. Aisin Corporation occupies a position representing Japanese OEM supply chain anchoring with precision-machining heritage. These three entities sit within the competitive set where electrification is compressing traditional transmission housing demand while amplifying thermal management-integrated enclosure requirements.
| Leading Market Players |
|---|
| BorgWarner |
| American Axle & Manufacturing |
| Aisin Corporation |
| GKN Automotive |
| Carraro Group |
| Magna International |
| Schaeffler Group |
| Dana Incorporated |
| ZF Friedrichshafen |
| Others |
Value Network & Pricing Analysis
LME aluminum ingot costs cascade through three distinct pricing tiers as die-cast A380 feedstock moves from smelter to captive foundry to independent machining house. Spot price volatility above fifteen percent annually compresses margin pools for non-integrated suppliers serving passenger car OEMs with EPA fuel economy mandates.
Pricing Analysis
Lead-time compression commands premium pricing in transmission housing procurement, with spot inventory availability discounting against twelve-week tooled-delivery schedules. Contract-based long-term offtake dominates automotive OEM relationships, while independent rebuilders transact on commodity spot markets for bare castings. Price differentiation rests on ISO/TS 16949 certification tier and volume scale, with Class 8 truck fleets showing highest price sensitivity due to total cost of ownership pressures. Cost compression in the independent supplier tier is intensifying because primary aluminum price swings transfer directly to unhedged buyers.
Supply Chain Analysis
Dual-sourcing qualification mandates from German commercial vehicle OEMs require tier-one powertrain integrators to maintain approved foundry relationships in Germany, China, and the United States simultaneously. Raw material dependencies center on primary aluminum ingot, compacted graphite iron feedstock, and vacuum-assisted die-casting tooling. Single-source vulnerability concentrates in Baden-Württemberg captive foundry capacity controlled by ZF Friedrichshafen. Distribution runs through OEM direct procurement for original equipment, with independent rebuilders sourcing bare housings via foundry-direct channels for aftermarket remanufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transmission housing demand sits in a technology-transition phase as single-speed e-axle enclosures displace multi-speed automatic housings. High-pressure die-cast aluminum with integrated thermal management is replacing legacy sand-cast iron architectures.
For Market Incumbents: Deploy captive electronics-housing convergence capabilities to defend against powertrain electrification compressing traditional transmission volumes. Backward integration into electric melting furnace capacity mitigates China's MIIT energy intensity benchmarks disadvantaging independent foundries. Channel control through direct OEM platform engineering relationships protects margin pools against spot-market pricing erosion.
For New Entrants and Emerging Players: India's PLI scheme for advanced automotive technology components opens a window for greenfield die-casting investment serving domestic OEM assembly operations. White-space targets include single-speed reduction gear enclosures for battery-electric passenger cars and 3D printing repair services for Class 8 truck fleet operators. A go-to-market angle anchored in mechatronics integration capability bypasses incumbent machining expertise moats.
For Investors and Strategic Acquirers: MIIT dual carbon goal enforcement acceleration is the leading indicator that Chinese foundry consolidation will create acquisition opportunities. Long-term viability favors suppliers with demonstrated e-axle thermal management integration and multi-material joining certification. The signal to monitor is OEM platform engineering staff expansion for battery-electric architectures versus internal combustion powertrain teams.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electric Melting | MIIT energy benchmarks favor foundries with regenerative thermal oxidizer investment over legacy coke-fired capacity. |
| E-Axle Thermal Management Integration | BorgWarner and ZF Friedrichshafen leverage powertrain electronics convergence for single-speed enclosure qualification. |
| Multi-Material Joining Certification | Aluminum-to-steel laser welding protocols extend product launch timelines for hybrid housing assemblies. |
| 3D Printing Repair Service Buildout | Directed energy deposition enables crack repair in cast iron commercial vehicle housings without full replacement. |
| Geographic Manufacturing Footprint Expansion | Tamil Nadu and Gujarat automotive corridors attract greenfield capacity for transmission casting localization. |
Research Methodology
Document review covered SEC 10-K filings from powertrain suppliers, EPA fuel economy compliance databases, and EU F-Gas Regulation amendment texts, complemented by interviews with tier-one supplier procurement directors, OEM platform engineers, and independent foundry operators. Secondary validation drew from vehicle production databases, IHS Markit registration data, and LME aluminum price series. Bottom-up die-casting capacity modeling triangulated against top-down OEM powertrain platform forecasts.
Cross-referencing historical die-casting capacity utilization against expert panel input on electrification timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include propulsion architecture, material grade tier, manufacturing process technology, and regional production cluster. CAGRs were derived from unit volume projections weighted by content-per-vehicle shifts between multi-speed automatic and single-speed e-axle designs. Industry-specific inputs incorporated MIIT foundry energy intensity benchmarks and EPA Corporate Average Fuel Economy standard stringency trajectories.
The model assumes a particular technology adoption path for battery-electric passenger car powertrains; alternative pathways for hybrid architecture persistence would alter the outlook for multi-speed automatic housing demand. Forecasts reflect assumptions on aluminum substitution rates and e-axle thermal management integration timelines. Deviation in EPA regulatory stringency or EU F-Gas sealing material restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
Fixed Series Compensation Market
Transmission and Distribution
Pantograph Disconnector Market
Transmission and Distribution
North America DC Distribution Network Market
Transmission and Distribution
Global Virtual Pipeline Systems Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market