
 US Electricity Transmission and Distribution Market | 2026-2036
US Electricity Transmission and Distribution Market Size, Share, and Industry Trends Forecast 2026-2036
US Electricity Transmission and Distribution Market Insights
Texas generator fleets is pivoting toward higher-capacity transmission corridors to accommodate utility-scale solar and wind ingress. Duke Energy leverages its Carolinas footprint to sustain regulated returns on transmission infrastructure. American Electric Power anchors its strategy in the 11-state footprint where it controls the largest transmission network. Dominion Energy differentiates through offshore wind interconnection projects in Virginia coastal waters.
US electricity transmission and distribution encompasses high-voltage infrastructure moving power from generators to substations and lower-voltage networks delivering electricity to end users, with typical transmission lines operating at 69 kV to 765 kV and distribution systems stepping down to 4-35 kV for commercial and residential delivery. Smart grid technology leads capital deployment as utilities modernize aging infrastructure with digital monitoring and automated switching capabilities. Underground cable installations represent the fastest-growing installation category in dense urban corridors where right-of-way constraints limit overhead expansion.
FERC, NERC, and state public utility commissions shape market access through interconnection standards, reliability mandates, and rate-case approvals that determine return on equity for infrastructure investments. EPA power plant rules and state renewable portfolio standards indirectly drive transmission buildout by locating generation far from load centers. Stakeholders must monitor interconnection queue reform outcomes and state-level cost allocation disputes that will determine which projects secure financing and timeline certainty.
Market Dynamics
FERC Order 2023 is compressing interconnection timelines from five years to three, forcing utilities to front-load transmission planning while data center load growth in Northern Virginia and Texas ERCOT territory strains existing corridor capacity.
Growth Catalysts
- Interconnection Queue Reform:FERC Order 2023 mandates cluster study processes that accelerate generator tie-in approvals, reducing timeline uncertainty for renewable developers awaiting transmission access.
- Data Center Load Concentration:Hyperscale facilities in Loudoun County and Prince William County are driving 2-3 GW of incremental transmission demand requiring substation upgrades and new 345 kV corridors.
- Offshore Wind Interconnection:Coastal Virginia offshore wind projects require submarine cable landings and onshore converter stations, creating specialized high-voltage infrastructure demand.
Market Restraints
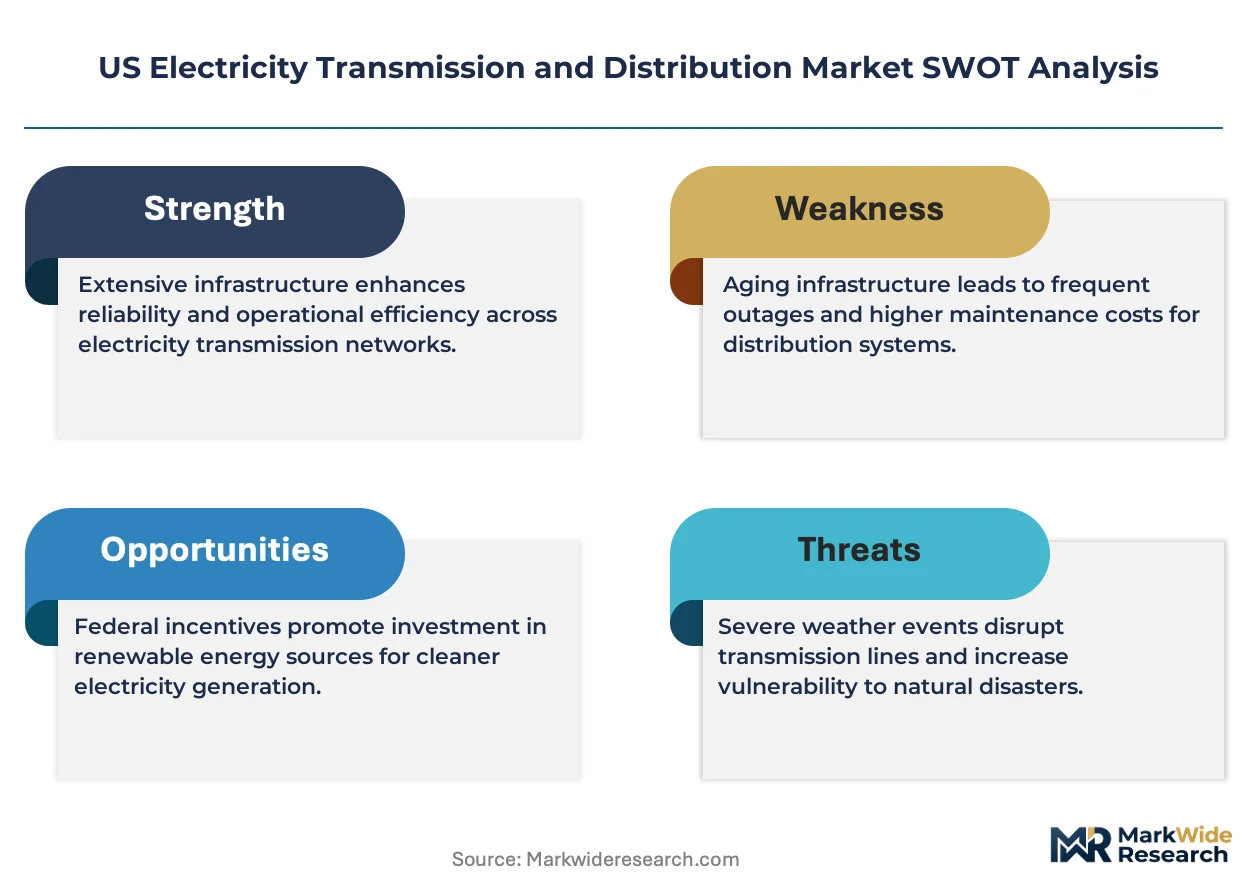
- Copper and Aluminum Price Volatility:Transmission conductor costs swing with London Metal Exchange pricing, compressing project margins for utilities with fixed-rate base approvals.
- Transformer Manufacturing Concentration:Domestic transformer production capacity concentrates among three domestic manufacturers, creating 18-24 month lead times for 500 kV+ units.
- Siting and Permitting Friction:National Environmental Policy Act review timelines for interstate transmission corridors routinely extend beyond state utility commission rate-case cycles.
Strategic Opportunities
- Grid-Enhancing Technologies:Dynamic line rating systems and topology optimization software unlock 20-40% additional capacity on existing corridors without new right-of-way acquisition.
- Battery Storage Co-location:Texas ERCOT and California CAISO markets favor transmission-connected storage that arbitrages congestion pricing and provides ancillary services.
- Underground Urban Distribution:Right-of-way constraints in Manhattan, Boston, and San Francisco corridors favor 115 kV and 230 kV cable installations over overhead rebuilds.
Industry Challenges
- Specialized Workforce Scarcity:High-voltage substation commissioning engineers and live-line technicians are retiring faster than apprenticeship programs replace them.
- Legacy SCADA Integration:Utilities operating 1980s-era control systems face cybersecurity compliance gaps when merging with modern digital monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Electricity Transmission and Distribution Market |
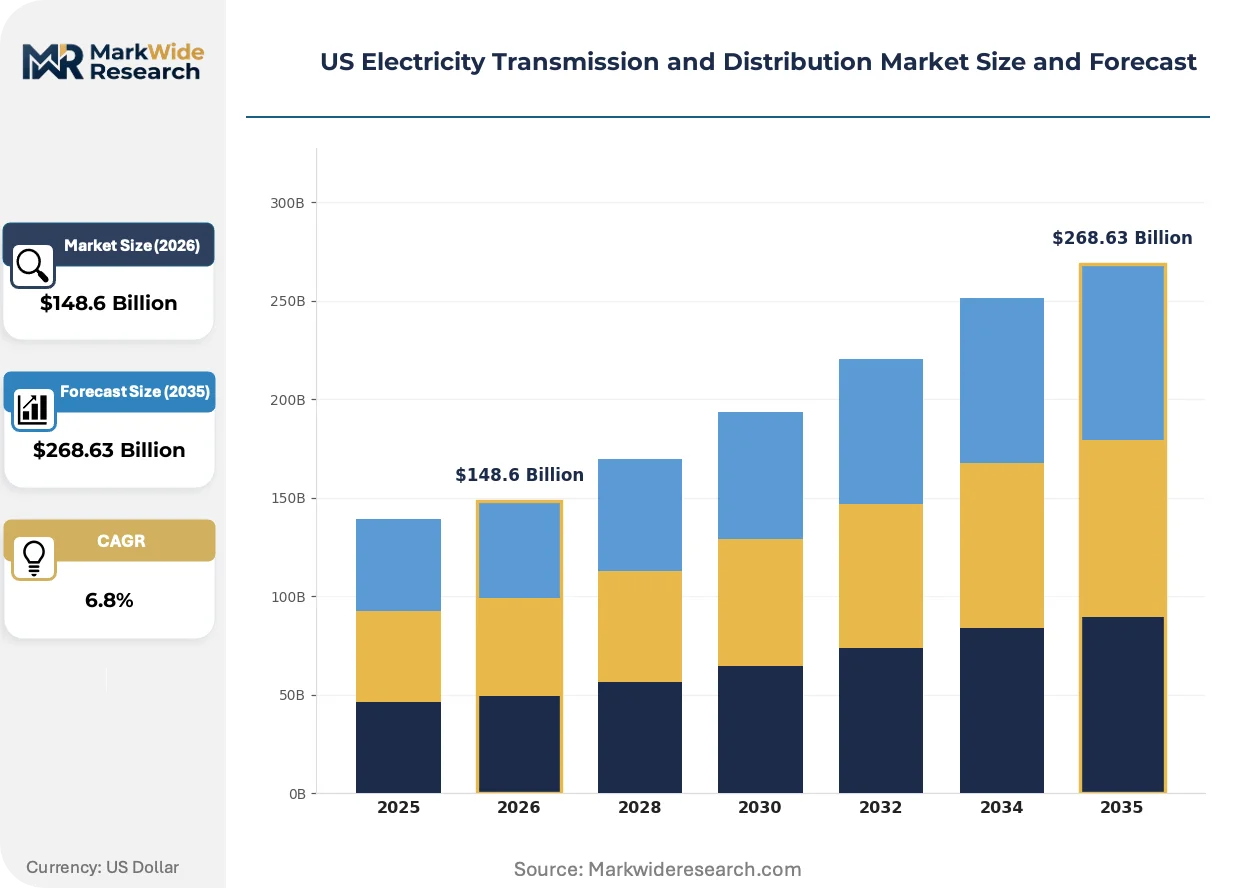
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $268.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Overhead Lines, Underground Cables, Smart Grids, Voltage Regulators End User: Residential, Commercial, Industrial, Utilities Installation: New Installations, Upgrades, Maintenance, Emergency Repairs Service Type: Consulting, Design, Operations, Asset Management |
| Companies Covered | Dominion Energy, PPL Corporation, American Electric Power, New York Power Authority, Lower Colorado River Authority, Duke Energy, Xcel Energy, Ameren, Southern Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Electricity Transmission and Distribution Market Trends and Innovations
Digital substation architectures are displacing copper-wired protection schemes, compressing commissioning timelines while enabling remote diagnostics that reduce truck-roll frequency for rural utilities.
Silicon carbide power electronics are electrifying medium-voltage distribution networks by enabling compact solid-state transformers that step 13.8 kV directly to 480 V for commercial customers. Duke Energy and Southern California Edison are piloting 1 MVA units in data center clusters. The technology eliminates liquid-filled transformer maintenance while enabling bidirectional power flow for rooftop solar aggregation.
EPA power plant rules and state renewable portfolio standards are forcing coal retirement schedules that outpace transmission buildout timelines. PJM Interconnection faces 8 GW of generation retirements without replacement transmission to import replacement power from wind-rich western zones. Utilities are responding with accelerated regional transmission organization filings for multi-value projects.
Data center operators are procuring transmission service directly through negotiated transmission service agreements rather than relying on utility default service. Northern Virginia developers now contract for 500 MW+ blocks of firm transmission rights before facility construction. This bypasses traditional retail rate recovery models and concentrates credit risk assessment among independent system operators.
US Electricity Transmission and Distribution Market Segmentation
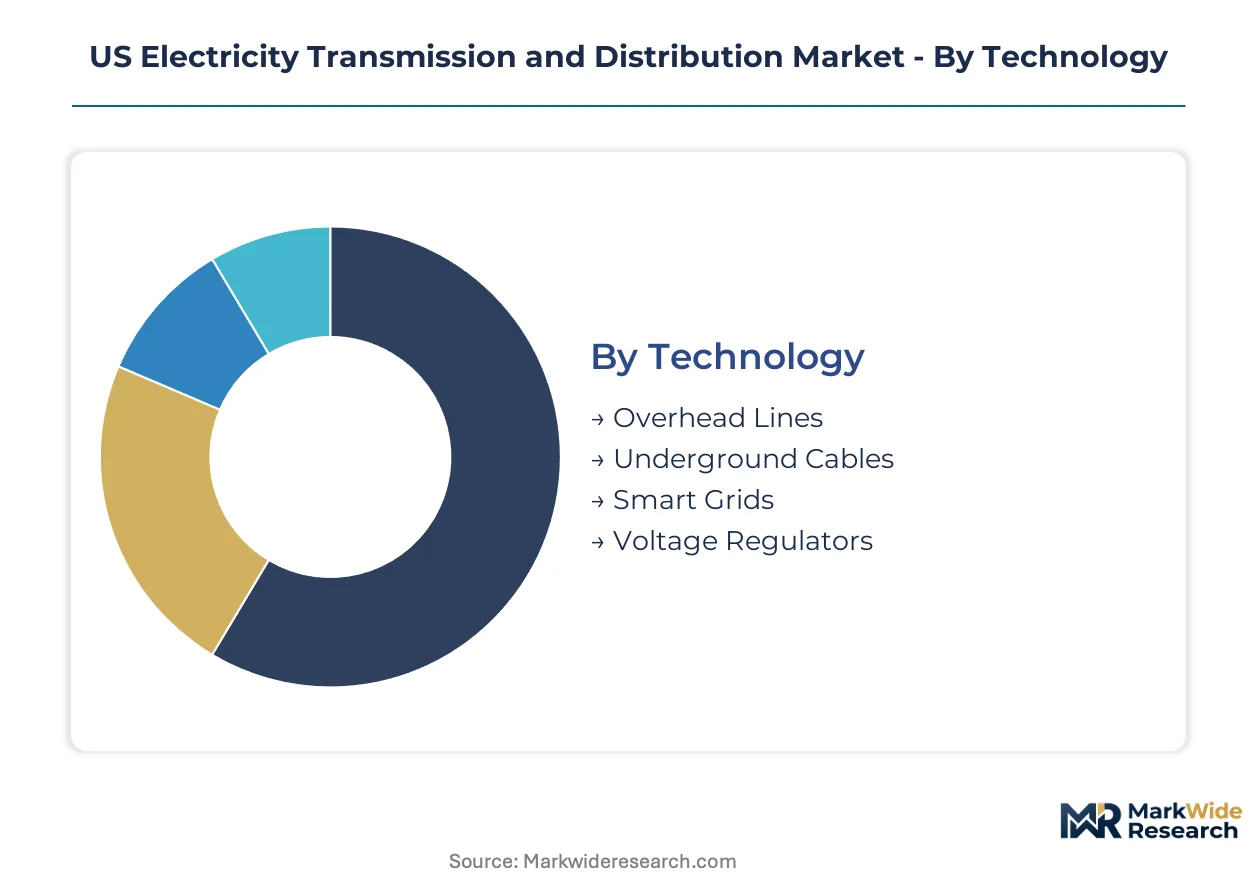
Segmentation of US electricity transmission and distribution infrastructure reveals how regulatory requirements, capital intensity, and operational complexity vary across technical and service dimensions. Each category carries distinct FERC and state utility commission compliance burdens that shape procurement patterns and vendor qualification criteria.
Technology:
Overhead Lines certification falls under FERC interconnection standards and NERC reliability mandates, while Smart Grids trigger additional cybersecurity compliance under CIP-013 supply chain standards.
- Overhead Lines:Conventional steel lattice and monopole structures carrying 69 kV to 765 kV across long-distance corridors. Demand concentrates in Texas ERCOT and Great Plains wind zones where right-of-way acquisition remains feasible and cost-per-mile economics favor aerial construction over buried alternatives.
- Underground Cables:XLPE-insulated and HPFF pipe-type systems operating at 115 kV to 500 kV in dense urban corridors. Manhattan, Boston, and San Francisco drive procurement where overhead permits face insurmountable municipal opposition and aesthetic constraints override capital cost premiums.
- Smart Grids:Digital monitoring platforms with AMI, DMS, and ADMS architectures enabling real-time feeder reconfiguration.
- Voltage Regulators:Step-voltage and induction-type units maintaining ±10% voltage bandwidth across distribution feeders.
Overhead Lines sits at the top of the volume ranking, with Underground Cables climbing the fastest.
End User:
Cost tier stratification separates capital-intensive utility infrastructure from behind-the-meter commercial installations, with industrial loads commanding the highest per-connection engineering standards.
- Utilities:Investor-owned, municipal, and cooperative entities owning transmission assets subject to FERC rate-base regulation and state return-on-equity approvals. PJM, ERCOT, and CAISO member utilities concentrate procurement of 345 kV+ infrastructure where regional transmission organization cost allocation determines project viability.
- Industrial:Heavy manufacturing, data centers, and petrochemical facilities requiring dedicated 138 kV substations and firm transmission service agreements. Northern Virginia hyperscale campuses and Texas Permian Basin load growth are forcing expedited 345 kV corridor upgrades outside standard utility planning cycles.
- Commercial:Retail, office, and institutional buildings served by 4-35 kV distribution networks with demand response enrollment.
- Residential:Single-family and multi-family dwellings connected through 120/240 V secondary distribution with smart meter penetration.
Utilities command the dominant share of annual capital deployment, while Industrial connections are expanding most quickly.
Installation:
Application urgency differentiates scheduled capital programs from reactive maintenance, with emergency repairs bypassing standard procurement protocols and commanding labor rate premiums.
- New Installations:Greenfield transmission corridors and substations requiring full NEPA environmental review, state siting approvals, and FERC interconnection agreements. Texas ERCOT and offshore Virginia wind zones concentrate activity where generator interconnection queues drive parallel transmission buildout.
- Upgrades:Capacity additions to existing corridors through reconductoring, series compensation, and substation transformer replacement. PJM and SPP regions prioritize 345 kV upgrades to accommodate western wind imports replacing retiring coal baseload.
- Maintenance:Vegetation management, insulator washing, and thermal imaging programs preserving reliability metrics.
- Emergency Repairs:Storm restoration and forced outage response mobilizing mutual assistance crews under Edison Electric Institute protocols.
New Installations absorb the largest share of transmission capital, with Upgrades gaining share fastest as reconductoring economics improve.
Service Type:
Customer type fragmentation separates asset-owning utilities from non-wire alternative providers, with consulting and design services concentrating among specialized engineering firms holding NERC reliability credentials.
- Operations:Control room management, switching operations, and real-time dispatch services performed by RTOs and vertically integrated utilities. CAISO and ERCOT operations centers concentrate specialized workforce with FERC market-based rate authority and NERC CIP-005 cyber access controls.
- Design:Transmission planning, substation engineering, and protection scheme development requiring professional engineering licensure and FERC Part 35 interconnection experience. Offshore Virginia and California offshore wind projects are pulling design capacity toward submarine cable and converter station specialization.
- Consulting:Regulatory strategy, cost allocation analysis, and interconnection queue navigation for generator developers.
- Asset Management:Condition-based maintenance programs and replacement prioritization algorithms extending infrastructure life.
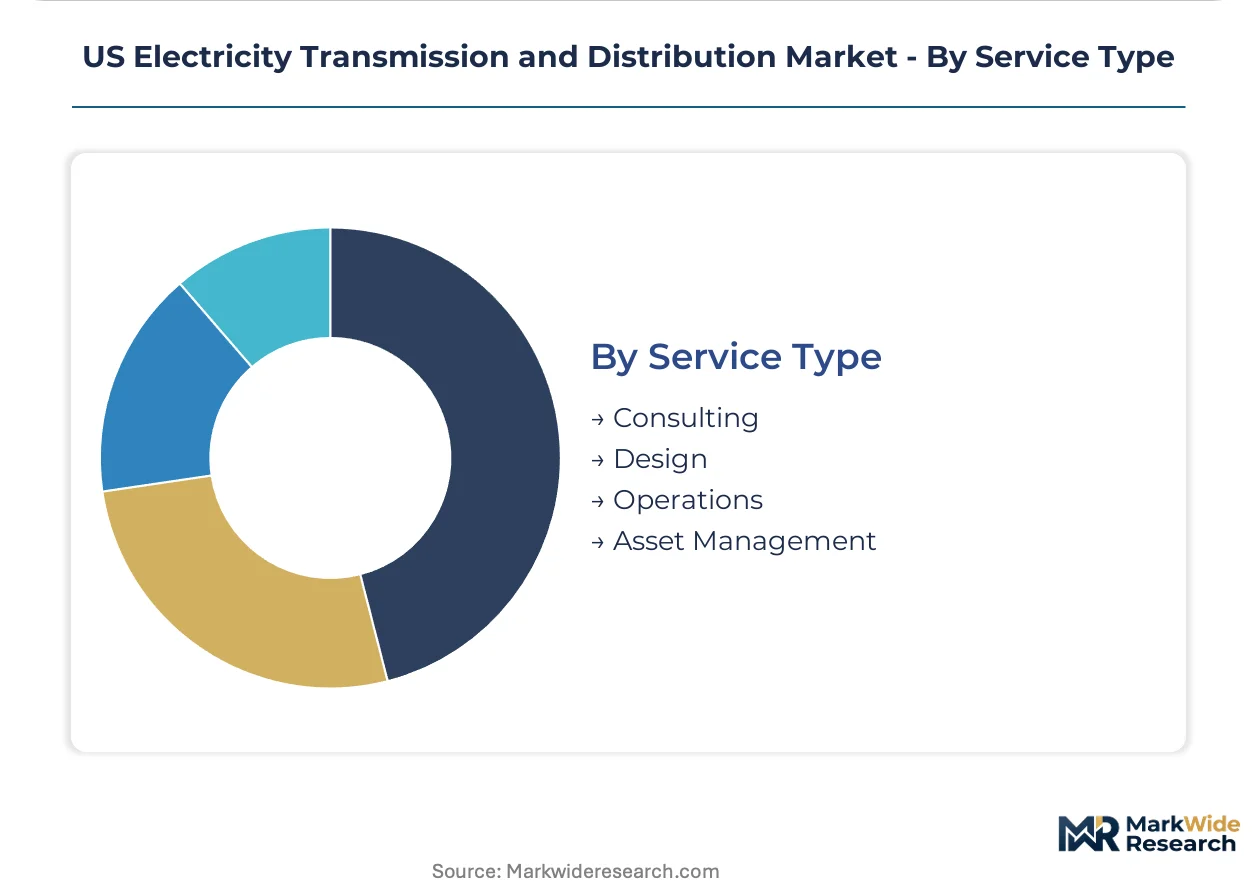
Operations represents the largest service revenue pool, with Design experiencing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transmission infrastructure investment migrates toward jurisdictions with streamlined permitting and cost-recovery mechanisms, creating regulatory arbitrage between states with accelerated siting processes and those with protracted review cycles.
Texas
ERCOT territory absorbs the bulk of utility-scale solar and wind interconnection requests, with Permian Basin oilfield electrification and data center clusters around Dallas-Fort Worth driving 345 kV corridor expansion. The Public Utility Commission of Texas oversees competitive renewable energy zones that socialize transmission costs across ratepayers. Houston and Austin metro areas concentrate hyperscale facility development requiring dedicated substations and firm transmission service agreements.
Virginia
Data center load growth in Loudoun and Prince William counties strains existing 230 kV infrastructure, forcing expedited upgrades outside standard planning cycles. The Virginia State Corporation Commission approves rate-base treatments for offshore wind interconnection investments. Coastal waters off Virginia Beach host submarine cable landings and converter stations for utility-scale offshore wind projects.
California
CAISO market participants face transmission constraints between northern hydro resources and southern load centers, with wildfire risk driving undergrounding mandates in high-threat districts. The California Public Utilities Commission enforces renewable portfolio standards that locate generation far from coastal demand. Los Angeles and San Francisco corridors favor 115 kV cable installations where overhead permits face municipal opposition.
Carolinas
Duke Energy's regulated footprint sustains returns on transmission infrastructure serving manufacturing reshoring and battery plant development. The North Carolina Utilities Commission and South Carolina Public Service Commission coordinate cost allocation for interstate projects. Charlotte and Research Triangle Park clusters drive distribution upgrade cycles for commercial and industrial load growth.
New York
Congestion pricing in downstate zones accelerates transmission buildout to import Canadian hydro and upstate wind resources. The New York State Public Service Commission implements clean energy standard mandates requiring zero-emission imports. New York City underground cable networks require specialized 345 kV XLPE installations where right-of-way constraints preclude overhead alternatives.
US Electricity Transmission and Distribution Market Competitive Landscape
Established utilities occupy the standard tier with rate-base regulated returns; emerging grid technology vendors pursue competitive transmission and distributed energy resource integration. Market structure concentrates around vertically integrated holding companies with interstate footprints and independent transmission developers seeking merchant project opportunities. Strategic archetypes include RTO-aligned utilities leveraging cost socialization, state-regulated entities capturing renewable energy credit premiums, and technology specialists deploying grid-enhancing software. Dominant competitive moves encompass regional transmission organization filings for multi-value projects and strategic partnerships with offshore wind developers for converter station rights.
Among the utility holding company tier, Dominion Energy and American Electric Power represent archetypal interstate transmission network operators, while Duke Energy occupies a position within the regulated Southeast cluster. These entities exemplify scale-driven infrastructure ownership models where FERC rate-base authority and state commission return approvals determine capital deployment pacing. Xcel Energy and Southern Company sit within the complementary tier of utilities balancing renewable generation integration with legacy system reliability obligations.
| Leading Market Players |
|---|
| Dominion Energy |
| PPL Corporation |
| American Electric Power |
| New York Power Authority |
| Lower Colorado River Authority |
| Duke Energy |
| Xcel Energy |
| Ameren |
| Southern Company |
| Others |
Pricing and Supply Chain Analysis
Copper and aluminum conductor costs cascade from London Metal Exchange pricing through utility procurement tiers, compressing margins on fixed-rate base approvals while transformer manufacturers pass through 18-24 month lead time premiums to project developers.
Pricing Analysis
Direct-to-utility contracting eliminates distributor margins that characterize smaller commercial installations. Price differentiation rests on NERC CIP-013 cybersecurity certification tiers and transformer MVA ratings. Cost compression in standard-voltage infrastructure intensifies because fixed-rate base approvals lock in returns before commodity swings. Municipal cooperatives exhibit highest price sensitivity due to limited balance sheet capacity, while hyperscale data center operators accept premium pricing for firm transmission service agreements.
Supply Chain Analysis
Transformer core steel supply rests on Japanese and South Korean specialty metal producers with limited domestic alternatives. High-voltage cable insulation compounds draw from German and Belgian chemical manufacturers, while aluminum conductor sourcing concentrates among Chinese and Canadian smelters. Single-source vulnerability in 500 kV+ transformer winding capacity exposes project timelines to manufacturing bottlenecks. Distribution runs through utility direct procurement with EPC contractor intermediation for substation assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US electricity transmission and distribution market compounds steadily as electrification mandates and data center load growth create durable infrastructure demand across regulatory cycles.
For Market Incumbents: Cement rate-base expansion through accelerated FERC Part 345 filings for multi-value transmission projects before interconnection queue reform saturates corridor capacity. Defend against merchant transmission developers by securing offshore wind converter station rights in Virginia coastal waters. Prioritize vertical integration into grid-enhancing technology software to capture recurring revenue streams beyond steel-in-the-ground returns.
For New Entrants and Emerging Players: Begin with dynamic line rating and topology optimization software deployments that unlock latent capacity without right-of-way acquisition. Target Texas ERCOT congestion pricing arbitrage opportunities where transmission-connected battery storage lacks incumbent utility ownership. Pursue negotiated transmission service agreements directly with Northern Virginia hyperscale developers bypassing traditional retail rate recovery.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized substation commissioning engineering capability concentrates among retiring workforce cohorts. Frame long-term viability around regulated utility holding companies with interstate FERC footprint authority and state commission rate-case momentum. Watch interconnection queue reform implementation speed as inflection indicator for developer credit risk and project finance availability.
| Strategic Initiative | Industry Significance |
|---|---|
| FERC Multi-Value Transmission Filing | Secures cost socialization across RTO member utilities for renewable integration corridors. |
| Offshore Wind Converter Station Partnership | Locks in submarine cable landing rights and HVDC interconnection capacity ahead of lease rounds. |
| Grid-Enhancing Technology Acquisition | Adds software-based capacity optimization to hardware-centric utility service portfolios. |
| Transformer Manufacturing Backward Integration | Reduces 18-24 month lead time exposure through captive core steel and winding capacity. |
| Data Center Direct Service Agreement | Bypasses traditional rate-base recovery with negotiated firm transmission rights contracts. |
Research Methodology
Coverage spans Texas ERCOT, PJM Interconnection, California CAISO, and Southeast regulated territories, with primary inputs from each. Utility planning officers, independent power producer project developers, EPC contractors, and grid operators supplied forward capital deployment intentions. FERC filings, EIA generation and transmission data, regional transmission organization interconnection queue databases, and state utility commission rate-case records provided secondary validation. Bottom-up project pipelines and top-down infrastructure investment forecasts underwent triangulation.
Rate-of-change decomposition separates volume growth in conductor miles and substation installations from value expansion in smart grid digitalization and voltage class upgrades. Segmentation dimensions encompass technology type, end user category, installation purpose, and service delivery model. CAGRs derive from utility capital expenditure guidance, generator interconnection queue trajectories, and load growth projections across the analysis window. FERC Order 2023 implementation pace and data center power demand forecasts constitute industry-specific model inputs.
Several conditions sit outside the modeled scope, including NEPA litigation outcomes for interstate corridors, copper price volatility extremes, and federal tax credit extension decisions. Forecasts reflect assumptions about regulatory stability and supply chain normalization. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Flexible AC Transmission Systems Market
Transmission and Distribution
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Power Transmission Cables Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
Transmission Housing Demand Market
Transmission and Distribution
Substation Grounding System Market
Transmission and Distribution
Pipeline Monitoring System Market
Transmission and Distribution
Power Transmission Tower Market
Transmission and Distribution
Middle East Gas Pipeline Infrastructure Market
Transmission and Distribution
Electric Power Transmission and Distribution Equipment Market