
 Pipeline Transportation Market | 2026-2036
Pipeline Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Transportation Market Analysis
A shift from single-source engineering-procurement contracts toward multi-source consortium arrangements is rebalancing capital deployment across major pipeline projects. Kinder Morgan leverages its extensive interstate network to sustain fee-based cash flow stability across volatile commodity cycles. TC Energy Corporation anchors Canadian export strategy through its cross-border Keystone system and affiliated storage assets. Bechtel Corporation competes on lump-sum turnkey execution for complex terrain crossings and offshore tie-ins.
Pipeline transportation comprises the bulk movement of liquids and gases through sealed tubular conduits, typically operating at pressures between 600 and 1,440 psi for crude oil trunk lines and up to 1,500 psi for natural gas transmission, with diameters ranging from 8 to 48 inches depending on throughput requirements. The technology dimension shows smart pipeline monitoring and automated control systems capturing disproportionate capital allocation as operators replace manual inspection regimes with real-time digital infrastructure. Natural gas pipelines generate the steadiest tariff revenue streams, while leak detection technology commands premium pricing due to tightening environmental liability frameworks.
The US Department of Transportation's Pipeline and Hazardous Materials Safety Administration mandates integrity management programs for high-consequence areas, while the EPA enforces methane performance standards under the Clean Air Act that directly shape compressor station design and maintenance protocols. In Canada, the CER oversees cross-border projects with binding conditions on Indigenous consultation and environmental protection. Stakeholders must weigh the capital efficiency of brownfield expansions against the permitting certainty of greenfield routes as regulatory timelines extend and community opposition intensifies.
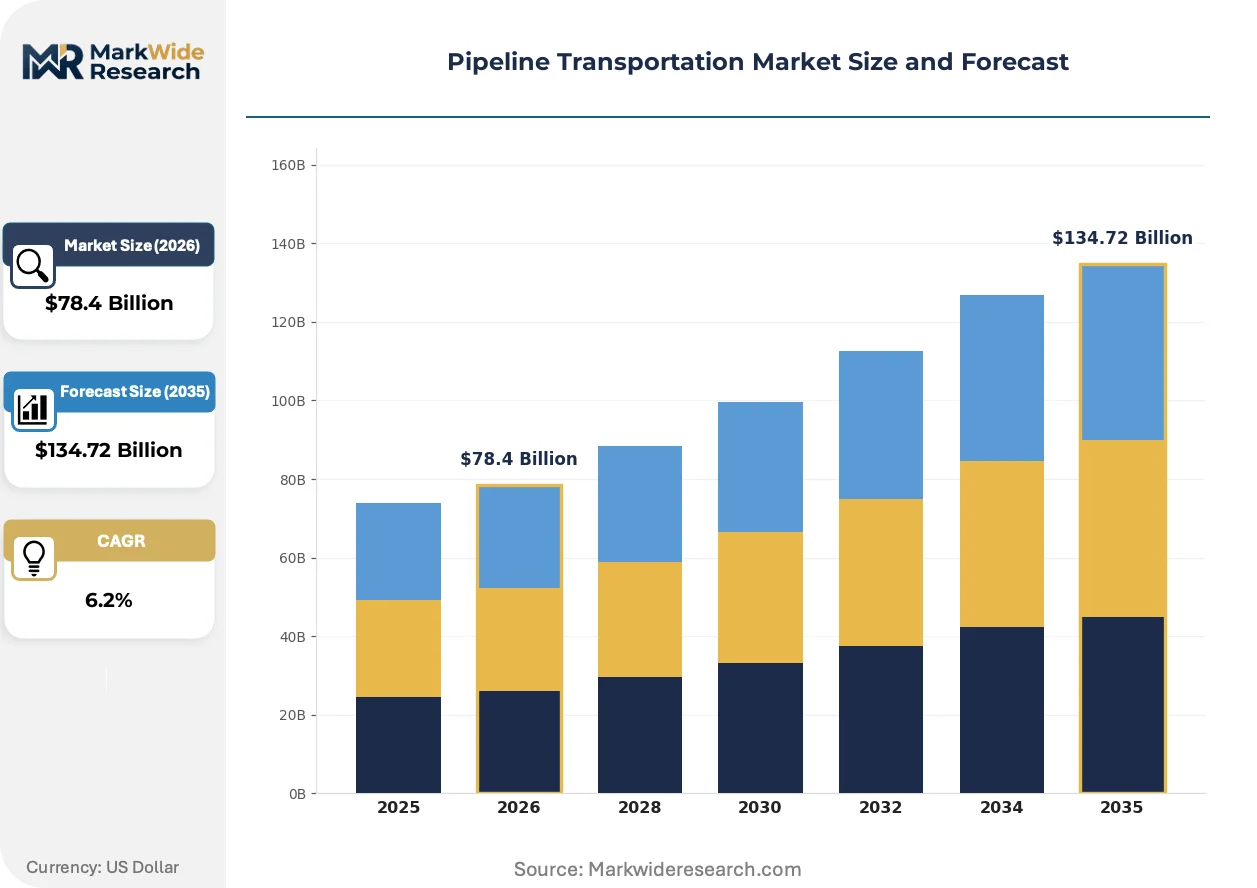
Market Dynamics
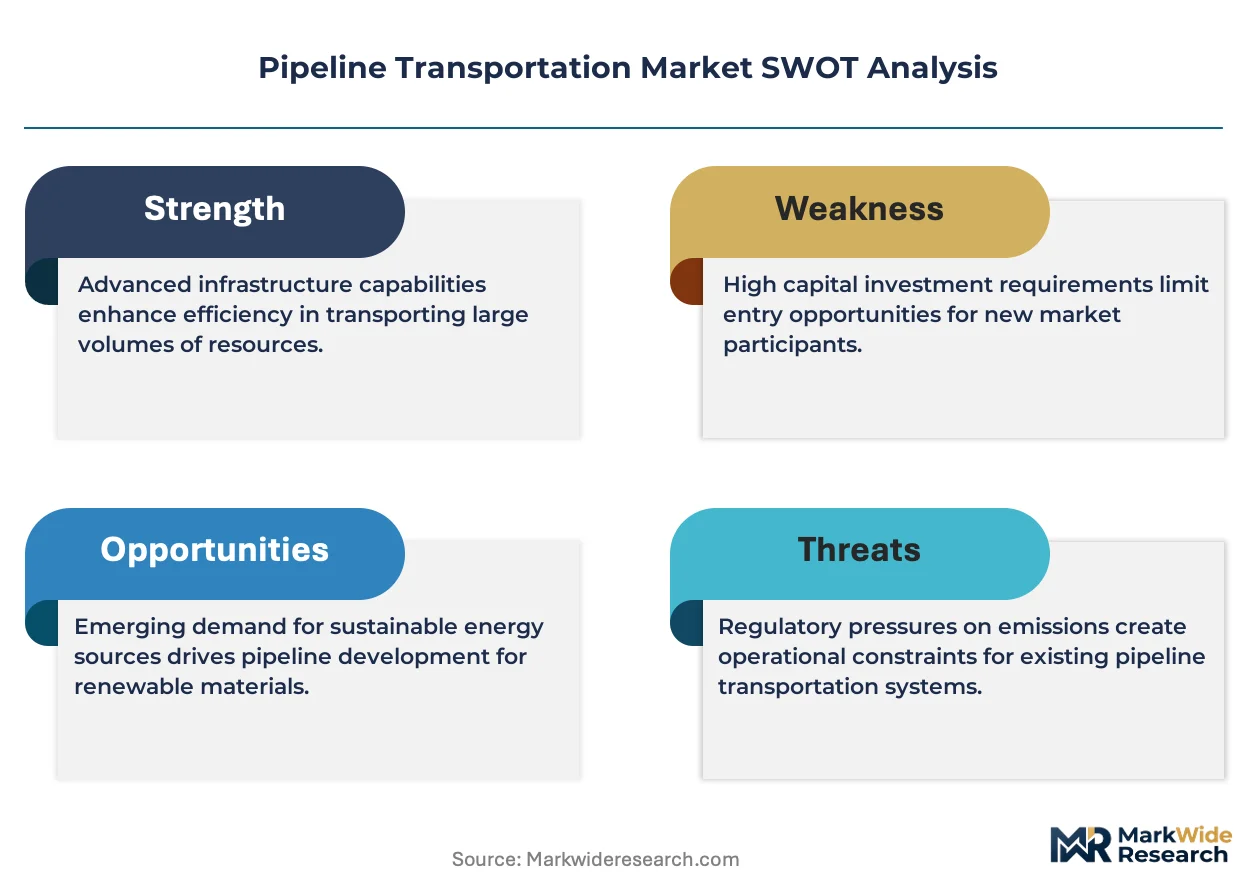
Regulatory tightening around methane emissions and leak detection mandates is compressing capital deployment timelines while accelerating replacement of manual inspection regimes with automated digital infrastructure across trunk line networks.
Growth Catalysts
- PHMSA Integrity Management Programs:The US Department of Transportation mandates systematic risk assessment for high-consequence areas, forcing operators to upgrade aging infrastructure and expand monitoring capabilities.
- Permian Basin Takeaway Constraints:Capacity bottlenecks between West Texas shale basins and Gulf Coast export terminals are triggering newbuild announcements and brownfield expansions.
- Fiber-Optic Distributed Acoustic Sensing:Real-time leak detection technology is displacing scheduled aerial patrols and reducing response times to third-party damage events.
Market Restraints
- Specialized Steel Plate Concentration:High-grade line pipe sourcing depends on a limited supplier base in Japan and South Korea, creating input cost volatility and delivery uncertainty for large-diameter projects.
- Indigenous Consultation Timelines:Canada's CER binding conditions on environmental protection and community engagement extend permitting cycles by 24-36 months for cross-border routes.
- Electrification Substitution:Battery storage and grid expansion in Germany and California are compressing natural gas demand growth in power generation segments.
Strategic Opportunities
- Hydrogen Pipeline Repurposing:Germany's EU Green Deal funding streams support conversion of existing natural gas networks to hydrogen blending, creating asset life extension opportunities.
- Carbon Capture Transport Infrastructure:Emerging CO2 trunk line demand from industrial clusters in Texas and Louisiana requires new metallurgy standards and compression technology.
- AI-Driven Predictive Maintenance:Machine learning algorithms analyzing pressure transient data are converging with drone-based external inspection to reduce unplanned outage frequency.
Industry Challenges
- Weld Inspector Certification Bottlenecks:ASME Section IX qualified radiographic interpreters face acute shortages, delaying construction schedules in the US Gulf Coast corridor.
- Legacy SCADA Integration Complexity:Brownfield automation upgrades must interface with 1980s-era control architectures, multiplying commissioning risk and cybersecurity exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Transportation Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Crude Oil, Natural Gas, Refined Products, Water Technology: Smart Pipeline Monitoring, Pressure Sensors, Automated Control Systems, Leak Detection End User: Utilities, Manufacturing, Energy Producers, Waste Management Pipe Material: Steel, Polyethylene, PVC, Composite |
| Companies Covered | PJSC Transneft, Primoris Services Corporation, Kinder Morgan, McDermott International, TechnipFMC plc, TC Energy Corporation, Energy Transfer, Bechtel Corporation, Pembina Pipeline Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Transportation Market Emerging Trajectories
Digital infrastructure deployment is compressing operational response times while regulatory frameworks harden liability exposure for emissions and safety incidents.
Distributed fiber-optic sensing is integrating real-time temperature, strain, and acoustic monitoring along entire pipeline lengths. Major trunk line operators in the Permian-to-Gulf corridor are deploying this technology at 40% of newbuild mileage. The shift is integrating continuous surveillance that eliminates patrol gaps and enables predictive intervention before leaks surface.
Germany's tightening F-Gas Regulation and methane performance standards under the US EPA Clean Air Act are reshaping compressor station design. New builds must incorporate zero-bleed pneumatic controllers and enhanced vapor recovery units. Midstream operators in North Dakota and Alberta are retrofitting existing facilities to avoid enforcement exposure and maintain social license.
Long-term throughput contracting is fragmenting as LNG exporters and hydrogen developers seek shorter tenors with volume flexibility. This behavior is displacing traditional ship-or-pay structures that underpinned project finance. The pattern is most visible in Texas, where offtake agreements now average 8-10 years versus historical 15-20 year commitments.
Pipeline Transportation Market Segmentation
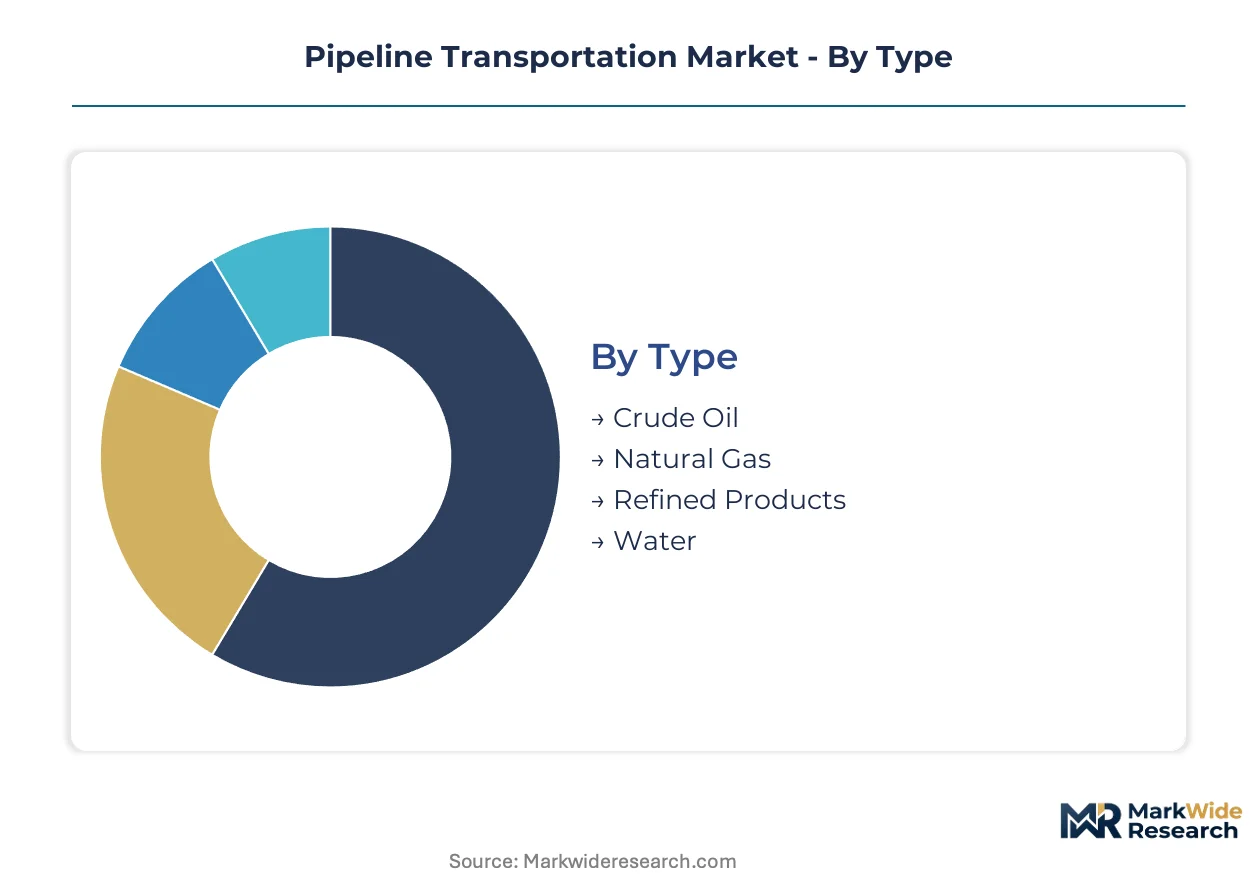
Pipeline transportation segmentation reveals how capital deployment, regulatory exposure, and technology adoption vary across fluid types and infrastructure configurations. Understanding these divisions clarifies where tariff revenue concentrates and where automation investment delivers the strongest returns.
Type:
Capital intensity varies sharply by fluid characteristics, with pressure requirements and corrosion risk driving diameter selection and metallurgy standards.
- Crude Oil:Heavy sour grades require corrosion-resistant alloys and heating systems for viscosity management. Permian-to-Gulf Coast trunk lines dominate newbuild announcements as takeaway constraints persist.
- Natural Gas:Dry gas transmission operates at higher pressures than liquid lines, demanding thicker wall specifications and more frequent compressor stations. Appalachian and Marcellus shale output feeds this segment's expansion.
- Refined Products:Multi-product batching systems transport gasoline, diesel, and jet fuel through common lines with sequenced deliveries. Colonial Pipeline's restart protocols illustrate operational complexity.
- Water:Lower-pressure specifications govern municipal and industrial water distribution, with PVC and concrete alternatives displacing steel in non-potable applications.
Natural gas absorbs the bulk of installed capacity; crude oil is expanding most quickly.
Technology:
Deployment patterns track regulatory enforcement intensity, with EPA methane rules and PHMSA integrity mandates shaping procurement priorities.
- Smart Pipeline Monitoring:Integrated SCADA platforms aggregate pressure, flow, and temperature data across distributed networks. Fiber-optic sensing deployments are accelerating in high-consequence areas.
- Pressure Sensors:Real-time transient detection enables predictive intervention before rupture events. Gulf Coast operators are retrofitting legacy lines with wireless sensor networks.
- Automated Control Systems:Remote valve actuation and compressor optimization reduce manual patrol requirements. Cybersecurity hardening adds implementation cost.
- Leak Detection:Computational pipeline monitoring software analyzes mass balance discrepancies to flag potential releases. Regulatory liability frameworks are compressing acceptable response timelines.
Leak detection commands premium pricing; smart pipeline monitoring is gaining share fastest.
End User:
Contract structures and volume predictability separate segments, with take-or-pay commitments versus interruptible service creating divergent risk profiles.
- Utilities:Gas distribution companies anchor base-load throughput with long-term transportation agreements. Local distribution company consolidation is concentrating buying power.
- Manufacturing:Petrochemical complexes and fertilizer plants require dedicated feedstock lines with purity specifications. Gulf Coast industrial clusters drive demand.
- Energy Producers:Exploration and production companies seek flexible gathering and trunk line access with volume swing provisions. Shale drillers prioritize low per-unit transport costs.
- Waste Management:Produced water disposal and CO2 sequestration transport represent emerging demand with distinct metallurgy and pressure requirements.
Energy producers absorb the bulk of installed capacity; waste management is climbing the fastest.
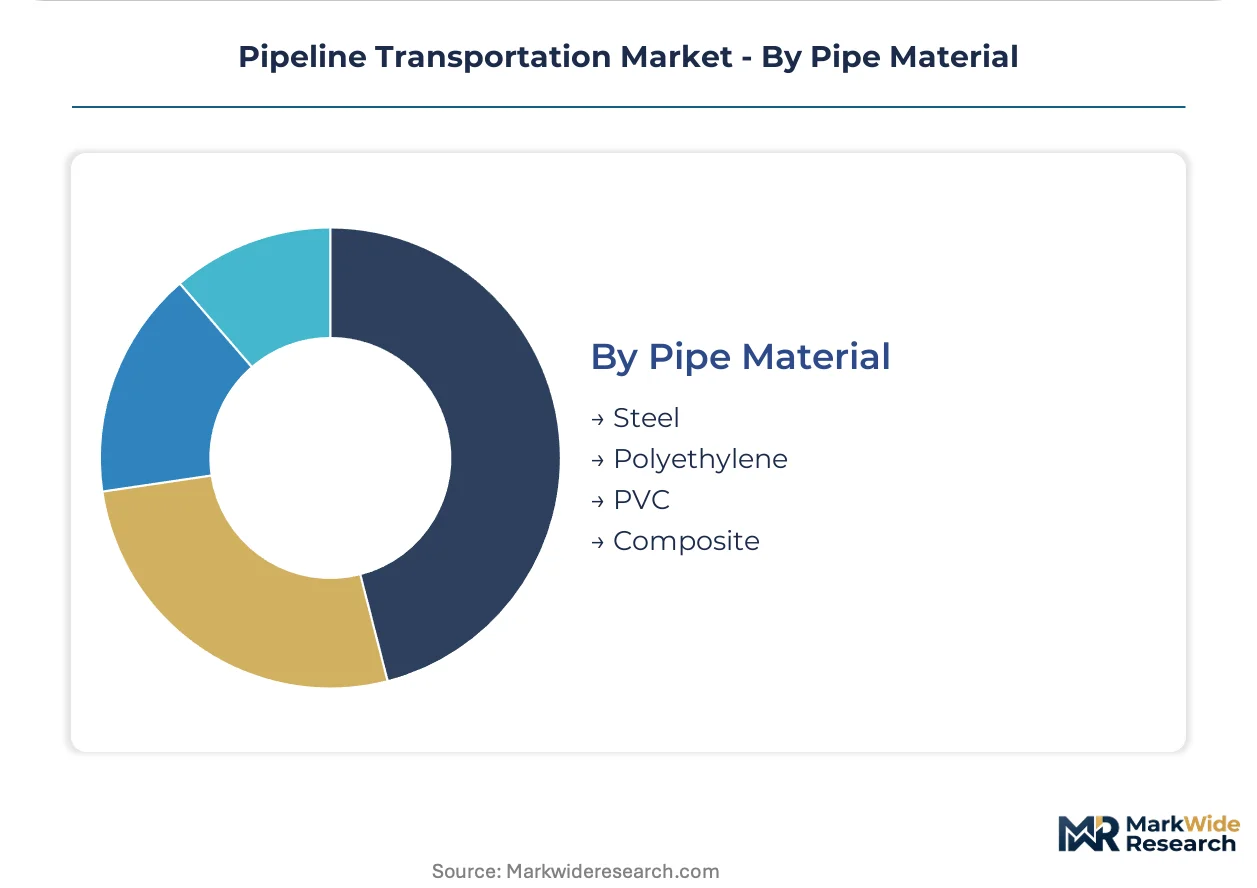
Pipe Material:
Material selection balances pressure rating, corrosion resistance, and installation logistics across terrain and fluid compatibility constraints.
- Steel:High-strength line pipe dominates trunk line construction, with API 5L specifications governing grade selection. Japanese and South Korean mills concentrate supply.
- Polyethylene:Flexible pipe systems reduce installation cost in gathering networks and distribution laterals. Fusion welding protocols require specialized crew certification.
- PVC:Limited to low-pressure water and wastewater applications with strict temperature and pressure envelopes. Municipal procurement favors corrosion immunity.
- Composite:Reinforced thermoplastic pipe offers corrosion resistance with reduced weight for offshore tie-ins and sour service conditions. Qualification testing extends lead times.
Steel absorbs the bulk of installed capacity; composite is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shale basins in West Texas anchor North American trunk line expansion. Pipeline operators route Permian crude toward Gulf Coast export terminals. European hydrogen conversion projects reshape legacy natural gas corridors.
United States
PHMSA integrity mandates and EPA methane performance standards drive compressor station retrofits across the Permian-to-Gulf Coast corridor. The Department of Transportation enforces systematic risk assessment protocols for high-consequence areas. Houston-area industrial clusters concentrate newbuild announcements as takeaway capacity constraints persist.
Canada
The Canada Energy Regulator imposes binding conditions on Indigenous consultation and environmental protection for cross-border routes. TC Energy Corporation anchors export strategy through its Keystone system and affiliated storage assets. Alberta's oil sands production feeds pipeline demand toward British Columbia tidewater and US Midwest refineries.
Germany
EU Green Deal funding streams support conversion of existing natural gas networks to hydrogen blending under tightening F-Gas Regulation standards. Industrial clusters in the Ruhr region pilot carbon capture transport infrastructure with new metallurgy requirements. Federal network agencies accelerate permitting for repurposed hydrogen corridors.
Saudi Arabia
Master Gas System expansions and crude oil trunk line extensions serve petrochemical complexes along the Gulf Coast. The national oil company maintains integrated pipeline networks connecting Eastern Province production with Red Sea export terminals. Yanbu industrial city anchors downstream throughput demand.
Australia
Coal seam gas pipelines from Queensland fields feed LNG export facilities at Gladstone. The national energy regulator oversees third-party access regimes for transmission networks. Western Australia's Pilbara region concentrates iron ore slurry pipeline operations with specialized corrosion management protocols.
Pipeline Transportation Market Vendor Landscape
Global majors compete with regional champions across capital deployment and regulatory navigation capabilities. The vendor base separates into integrated midstream operators, turnkey engineering contractors, and specialized construction consortia. Strategic archetypes include fee-based cash flow stabilizers, lump-sum turnkey executors, and consortium-based project aggregators. Dominant competitive moves encompass brownfield expansion versus greenfield permitting strategies and smart monitoring technology licensing partnerships.
Among North American midstream operators, Kinder Morgan, TC Energy Corporation, and Energy Transfer occupy positions spanning interstate network ownership and cross-border export infrastructure. Kinder Morgan exemplifies the fee-based cash flow archetype through extensive interstate network operations. TC Energy Corporation anchors Canadian export positioning through cross-border system integration. Energy Transfer represents scale-driven gathering and trunk line consolidation across multiple shale basins. Engineering specialists including Bechtel Corporation and TechnipFMC plc sit within the turnkey execution tier for complex terrain crossings and offshore tie-ins.
| Leading Market Players |
|---|
| PJSC Transneft |
| Primoris Services Corporation |
| Kinder Morgan |
| McDermott International |
| TechnipFMC plc |
| TC Energy Corporation |
| Energy Transfer |
| Bechtel Corporation |
| Pembina Pipeline Corporation |
| Others |
Supply Flow & Price Mechanics
API 5L grade certification tiers bifurcate procurement economics between X70/X80 high-strength specifications for trunk lines and lower-grade alternatives for gathering networks, with premium metallurgy commanding bundled integrity warranties while commodity grades trade on spot steel plate indices. This divergence concentrates supply planning around Japanese and South Korean mill allocations for large-diameter projects while compressing margins on standard-grade construction through competitive bidding.
Pricing Analysis
Warranty bundling separates turnkey EPC contracts with decade-long corrosion guarantees from unbundled material-supply arrangements where operators assume installation risk. Project-based lump-sum structures dominate greenfield trunk lines, with price differentiation driven by API certification grade and compressor station automation scope. Cost compression in standard-grade gathering systems is intensifying as polyethylene alternatives displace steel in lower-pressure applications. Midstream operators exhibit highest price sensitivity on long-haul capacity additions, while petrochemical off-takers accept premium pricing for dedicated feedstock lines with purity guarantees.
Supply Chain Analysis
Weld inspector certification shortages in the US Gulf Coast and Alberta are extending crew mobilization timelines for ASME Section IX qualified radiographic interpreters. High-strength line pipe draws from Japanese and South Korean mill capacity, with nickel-alloy inputs and specialized plate coating systems resting on concentrated metallurgical supply bases. Single-source vulnerability runs through limited qualified suppliers for large-diameter X80 grade. Distribution runs through engineering-procurement-construction consortia for complex terrain crossings, with direct mill relationships dominating standard-grade procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over smart monitoring technology and specialized construction labor anchors competitive positioning. Players are pursuing backward integration into fiber-optic sensing systems and predictive maintenance platforms to capture recurring revenue streams.
For Market Incumbents: Anticipate margin compression from automated inspection technologies by acquiring specialized leak detection software providers before valuation multiples expand. Consolidate brownfield expansion capacity in the Permian-to-Gulf corridor where permitting certainty exceeds greenfield alternatives. Reinforce regulatory compliance capabilities as PHMSA integrity mandates and EPA methane enforcement harden liability exposure.
For New Entrants and Emerging Players: Capture hydrogen pipeline repurposing opportunities in Germany's Ruhr industrial cluster where EU Green Deal funding de-risks conversion capital. Target carbon capture transport infrastructure in Texas and Louisiana industrial corridors where emerging CO2 trunk line standards create first-mover positioning. Lead with AI-driven predictive maintenance platforms that interface with legacy SCADA architectures without full system replacement.
For Investors and Strategic Acquirers: Re-rating potential sits with midstream operators possessing integrated storage and export terminal assets given throughput contracting fragmentation toward shorter-tenor agreements. Long-term viability favors fee-based cash flow models over commodity-exposed gathering systems. Watch for inflection in FERC certificate issuance timelines as indicator of greenfield permitting velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Fiber-Optic Sensing Deployment | PHMSA high-consequence area mandates are accelerating real-time monitoring adoption across Permian trunk lines. |
| Hydrogen Pipeline Conversion | Germany's F-Gas Regulation amendments are unlocking EU funding for natural gas network repurposing. |
| Carbon Capture Transport Buildout | Texas industrial clusters require new metallurgy standards for CO2 compression and sequestration logistics. |
| Predictive Maintenance Platform Integration | Machine learning algorithms analyzing pressure transient data are reducing unplanned outage frequency. |
| Specialized Labor Certification Programs | ASME Section IX interpreter shortages are constraining construction schedules in the Gulf Coast corridor. |
Methodological Framework
Independent corroboration across pipeline operator integrity management filings, FERC certificate applications, and EPC contractor project databases underwrites the qualitative findings. Primary interviews with midstream asset managers, PHMSA compliance officers, compressor station engineering leads, and line pipe procurement directors combined with secondary validation from DOT incident reports, EPA methane performance disclosures, and customs steel import records. Bottom-up project aggregation and top-down infrastructure capacity modeling triangulate volume estimates.
Rate-of-change decomposition separates baseline replacement demand from newbuild capacity additions across the projection horizon. Segmentation dimensions include fluid type, pressure rating tier, automation technology level, and regional regulatory framework cluster. CAGRs derive from throughput volume forecasts indexed to shale production trajectories and export terminal commissioning schedules, with compressor station retrofit cycles and smart monitoring penetration curves as industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrification substitution rates and hydrogen infrastructure policy commitments. Assumptions reflect current regulatory enforcement trajectories and commodity export demand patterns. Material deviation in FERC permitting velocity or EU hydrogen funding allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
Power Transmission Cables Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
Gas Insulated Substation Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Electrical Substation Management Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Flexible AC Transmission Systems Market
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
HVDC Transmission Systems Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Power Transmission Lines and Towers Market
Transmission and Distribution
High Voltage Direct Current (HVDC) Transmission System Market
Transmission and Distribution
South-East Asia DC Distribution Network Market