
 New Energy Battery Structural Parts Market | 2026-2036
New Energy Battery Structural Parts Market Size, Share, and Industry Trends Forecast 2026-2036
New Energy Battery Structural Parts Market Insights
Multi-source procurement among battery OEMs is shifting from captive in-house production toward qualified external suppliers for structural components. Shenzhen Kedali Industry leverages its aluminum extrusion expertise to supply precision battery casings for domestic EV programs. SANGSIN EDP anchors its position through die-casting capabilities that serve Korean and expanding European customer bases. Contemporary Amperex Technology Co. competes by maintaining captive production of structural parts while selectively outsourcing non-core components to manage capacity cycles.
New energy battery structural parts encompass the mechanical enclosures, electrical interfaces, thermal barriers, and mounting assemblies that protect lithium-ion cells and manage heat dissipation in electrochemical systems. These components typically employ aluminum alloys with 2-6 mm wall thickness formed through high-pressure die casting or progressive stamping to achieve crash-resistant sealing against IP67 ingress standards. Battery casings fabricated from aluminum dominate value pools due to their strength-to-weight ratio and compatibility with thermal runaway containment protocols. Die casting occupies the fastest-expanding process segment as manufacturers adopt integrated multi-cavity molds to reduce joint lines and improve dimensional repeatability for large-format prismatic cells.
China's NMPA enforces GB standards for battery structural integrity and thermal propagation resistance, while the EU's CE marking and F-Gas Regulation impose material traceability and sealing performance criteria on imported components. The US NHTSA and EPA coordinate on crash-test protocols and end-of-life recyclability rules that affect casing design specifications. Stakeholders must monitor how evolving safety certification timelines and regional content requirements reshape supplier qualification thresholds and capital deployment priorities.
Market Dynamics
Large-format prismatic cell architectures are compressing component counts and forcing die-casting investments toward 6,000-ton press capacities. OEM procurement teams now disqualify suppliers lacking integrated thermal management fabrication capabilities.
Growth Catalysts
- EU F-Gas Regulation:Sealing performance mandates for thermal barriers are accelerating fluoropolymer gasket qualification programs among European tier suppliers.
- Aluminum-silicon alloy advances:High-fluidity casting grades are enabling 2 mm wall thicknesses that reduce housing mass without sacrificing crash resistance.
- Jiangsu and Guangdong clusters:Die-casting and stamping concentration around CATL and BYD facilities is compressing logistics costs and qualification timelines for qualified suppliers.
Market Restraints
- Primary aluminum price volatility:LME aluminum swings above $2,400 per tonne are compressing margin structures for fixed-price OEM contracts.
- Tooling lead times:Multi-cavity mold fabrication stretches 18-24 months, creating capacity mismatches against cell format transitions.
- IP concentration in large-tonnage press design:Japanese and German equipment builders control 6,000-ton+ die-casting press technology, constraining Chinese supplier expansion.
Strategic Opportunities
- US IRA domestic content credits:Battery component assembly in North America qualifies for $35 per kWh tax credits, attracting greenfield die-casting investments.
- Solid-state cell formats:Next-generation lithium-metal architectures require pressure-resistant housings that command premium positioning against incumbent pouch designs.
- Direct-to-OEM digital channels:Configurator platforms for custom battery tray geometries are compressing traditional tier-2 distributor roles in European supply chains.
Industry Challenges
- GB 38031 certification timelines:China's NMPA thermal propagation testing protocols extend qualification cycles 8-12 months beyond prior GB standards.
- Simulation talent scarcity:CFD modeling for thermal runaway containment requires specialized electrochemical-thermal-mechanical multiphysics expertise that outstrips graduate program output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Energy Battery Structural Parts Market |
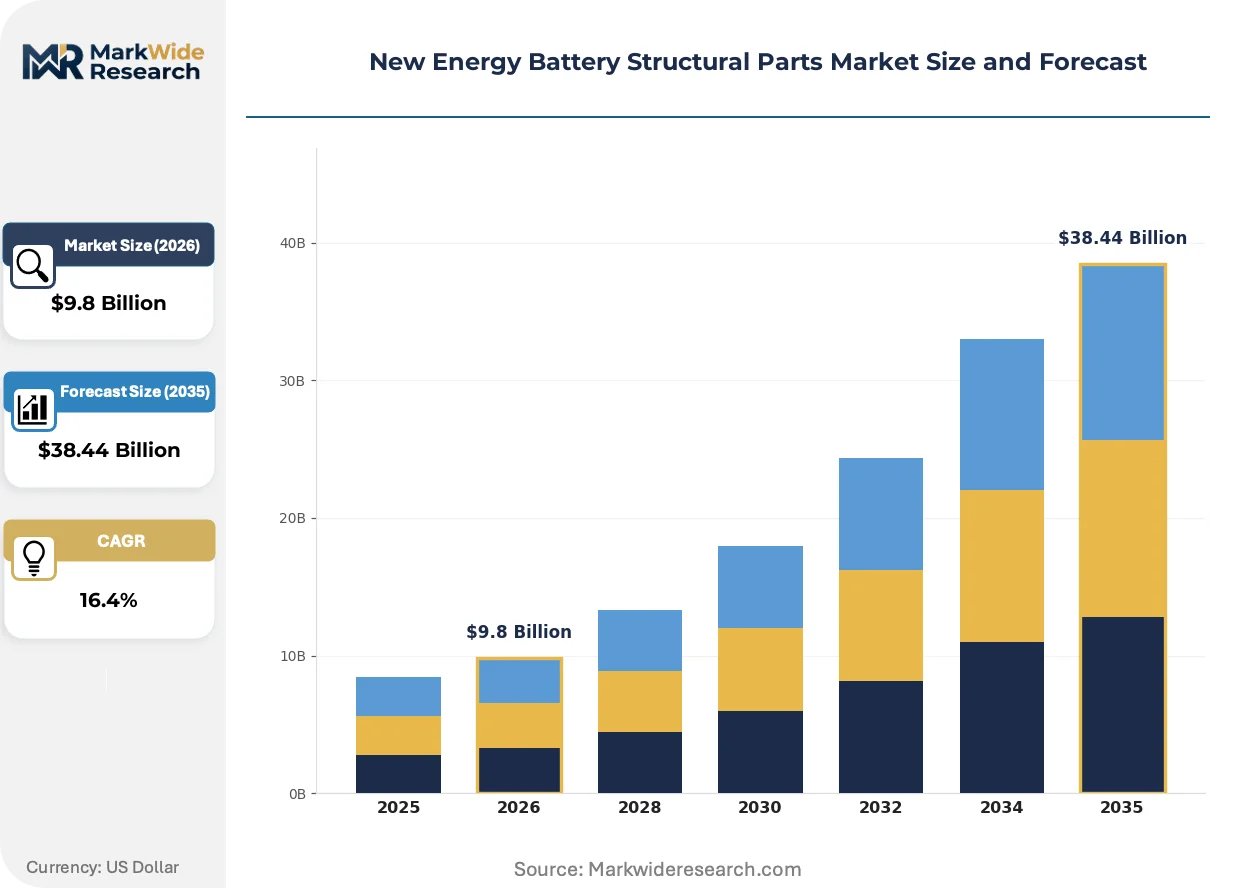
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $38.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Battery Casings, Connectors, Insulation Materials, Supports Manufacturing Process: Injection Molding, Die Casting, Stamping, Machining Material Type: Aluminum, Steel, Polymer Composites, Copper End User: Electric Vehicles, Energy Storage Systems, Consumer Electronics, Industrial Equipment |
| Companies Covered | Shenzhen Kedali Industry, SANGSIN EDP, Zhenyu Technology, Wuxi Jinyang New Material, Zhongrui Electronic Technology, Shenzhen Everwin Precision, Fuji Springs, Contemporary Amperex Technology Co., LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Energy Battery Structural Parts Market Trends and Innovations
Process integration and material substitution are collapsing the traditional separation between thermal management and structural enclosure functions. Suppliers now compete on single-piece casting complexity rather than assembly integration.
Integrated cooling channel die-casting is electrifying battery housing design by embedding serpentine fluid passages directly into aluminum floor pans. European premium EV platforms from Munich and Stuttgart are adopting this approach for 800V architectures. The technology is electrifying competitive positioning by eliminating separate cold plate assemblies and compressing bill-of-material costs.
China's GB 38031-2020 thermal propagation standard is mandating 5-minute no-fire thresholds that force multi-layer barrier integration into housing floors. NMPA enforcement through 2024 has disqualified suppliers lacking laser-welded sandwich panel capabilities. Korean cell producers serving European OEMs are accelerating aluminum-ceramic composite adoption to meet both GB and UN ECE R100 convergence timelines.
Cell-to-pack elimination of module frames is concentrating procurement authority at cell maker engineering teams rather than tier-1 integrators. CATL and BYD technical specifications now dictate housing tolerance bands that previously sat with vehicle platform architects. This concentration is most visible in Chinese Jiangsu province, where housing suppliers maintain resident engineers at cell maker R&D centers.
New Energy Battery Structural Parts Market Segmentation
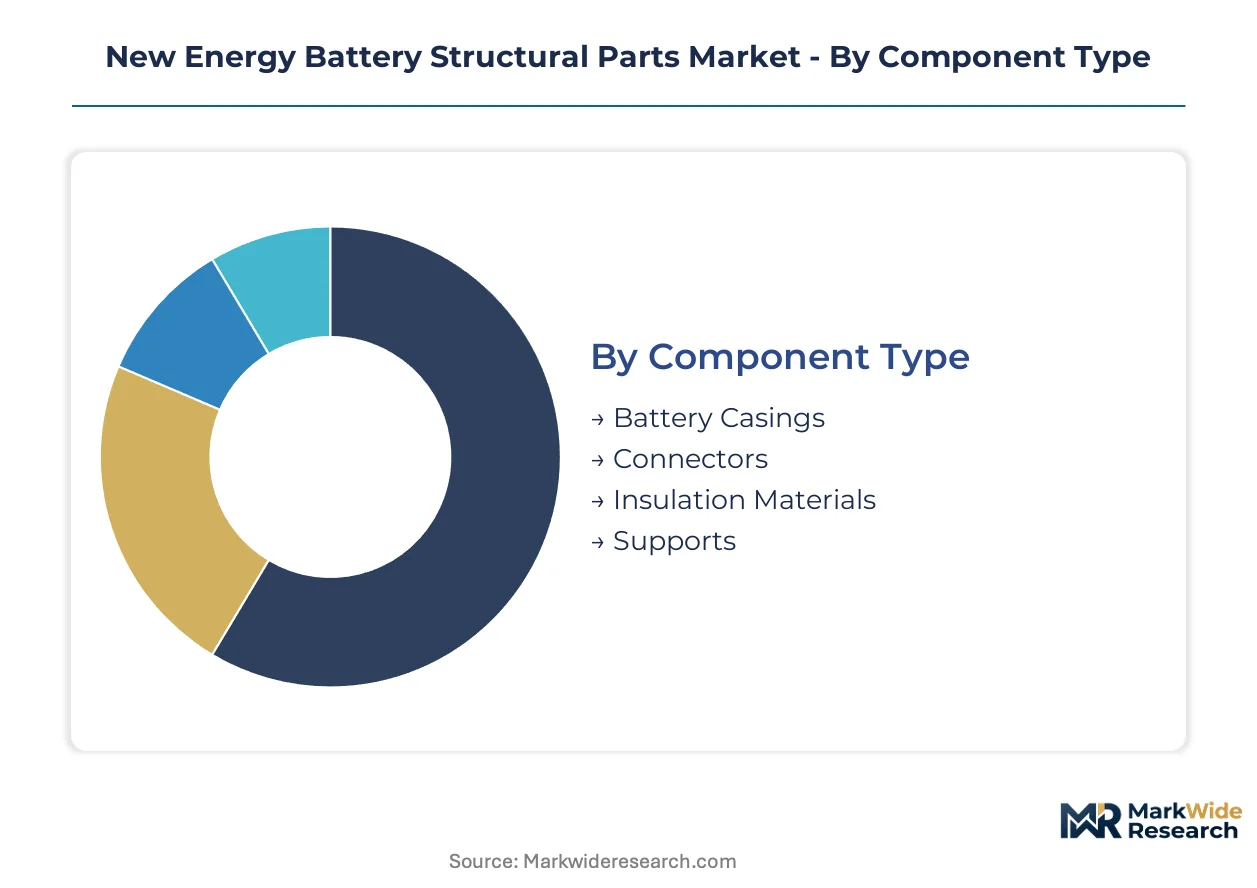
Structural parts procurement increasingly hinges on matching manufacturing process capabilities to cell format requirements. Buyers segment suppliers by their ability to integrate thermal management functions and meet regional certification standards.
Component Type:
Die-cast aluminum enclosures dominate value capture as OEMs consolidate multi-part assemblies into single-piece designs.
- Battery Casings:Aluminum alloy housings with 2-6 mm wall thickness formed through high-pressure die casting achieve IP67 sealing and crash resistance. CATL and BYD procurement concentrates in Jiangsu and Guangdong province clusters where die-casting suppliers maintain resident engineering teams.
- Connectors:Electrical interfaces integrate current-carrying terminals with structural mounting functions. Demand is concentrating for high-voltage 800V architectures as European premium EV platforms from Munich and Stuttgart adopt integrated cooling channel designs.
- Insulation Materials:Multi-layer thermal barriers incorporating ceramic composites and fluoropolymer gaskets meet GB 38031-2020 five-minute no-fire propagation mandates.
- Supports:Mounting brackets and frame assemblies attach battery packs to vehicle chassis structures. Korean cell producers serving European OEMs are accelerating aluminum-ceramic composite qualification for UN ECE R100 convergence.
Battery Casings leads on scale; Connectors leads on momentum.
Manufacturing Process:
Process selection determines which suppliers qualify for large-format prismatic cell programs requiring dimensional repeatability.
- Die Casting:High-pressure aluminum forming through 6,000-ton presses enables integrated multi-cavity molds that reduce joint lines. Japanese and German equipment builders control press technology above this threshold, constraining Chinese supplier expansion.
- Stamping:Progressive forming of aluminum sheet delivers cost-efficient volume production for standard cell formats. Jiangsu province stamping clusters compress logistics costs for CATL supply chains.
- Injection Molding:Polymer composite housings serve consumer electronics and industrial equipment applications with lower thermal load requirements.
- Machining:CNC finishing operations achieve tight tolerance bands for connector interfaces and precision mounting points.
Die Casting commands the steepest expansion trajectory; Stamping maintains the broadest installed base.
Material Type:
Aluminum-silicon alloy advances are collapsing the traditional separation between structural and thermal functions.
- Aluminum:High-fluidity casting grades enable 2 mm wall thicknesses that reduce housing mass without sacrificing crash resistance. LME price swings above $2,400 per tonne compress margin structures for fixed-price OEM contracts.
- Steel:Cold-rolled high-strength grades retain niche applications in heavy commercial vehicles where mass penalties are secondary to cost.
- Polymer Composites:Glass-fiber reinforced thermoplastics serve consumer electronics battery enclosures and secondary structural elements.
- Copper:Busbar and terminal applications leverage electrical conductivity for high-current connector assemblies.
Aluminum leads on scale; Polymer Composites leads on momentum.
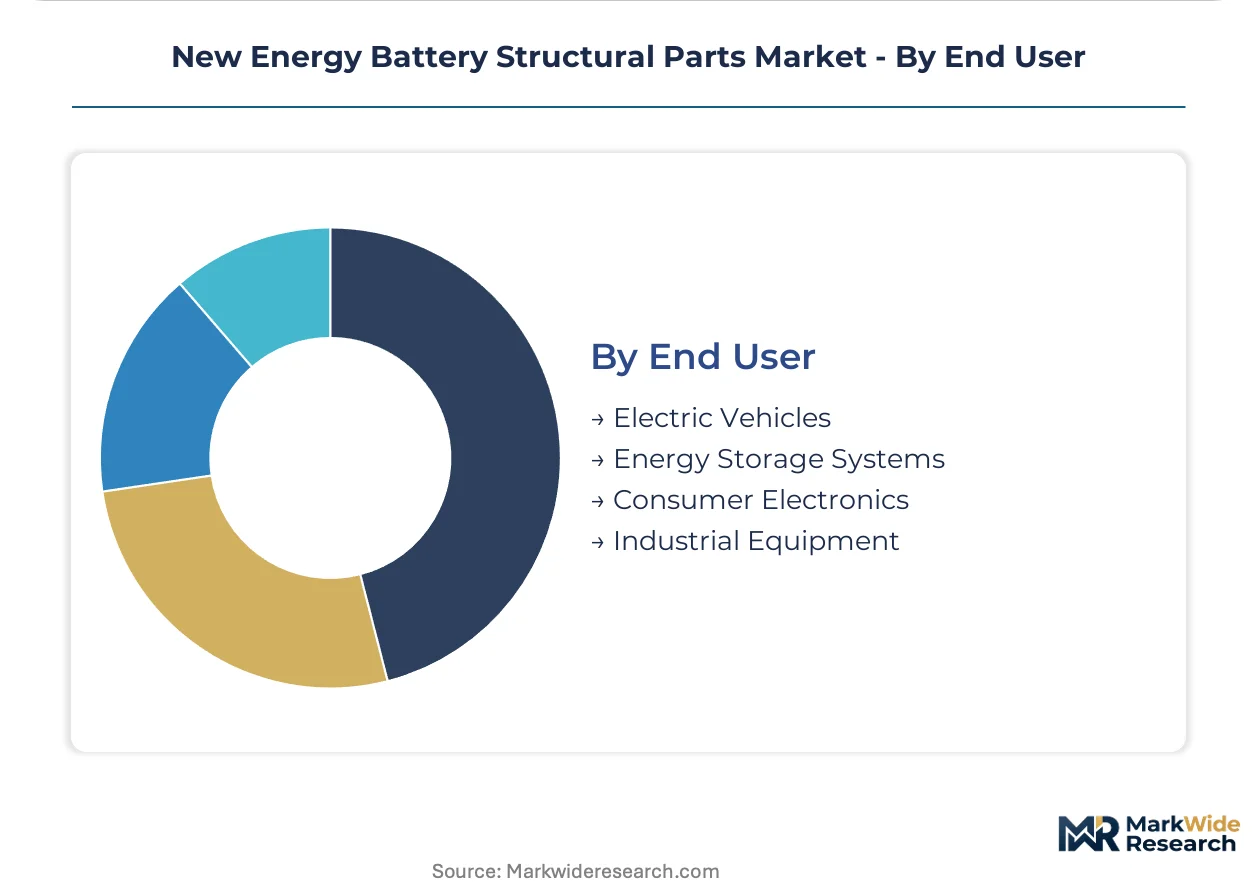
End User:
Cell-to-pack elimination of module frames is concentrating procurement authority at cell maker engineering teams rather than tier-1 vehicle integrators.
- Electric Vehicles:Passenger and commercial vehicle platforms specify housings with integrated cooling channels for 800V architectures. US IRA domestic content credits attract greenfield die-casting investments for North American assembly.
- Energy Storage Systems:Grid-scale battery installations require pressure-resistant housings for lithium-metal solid-state cell formats.
- Consumer Electronics:Smartphone and laptop applications prioritize polymer composite enclosures for weight minimization.
- Industrial Equipment:Forklift and stationary power systems specify steel-reinforced casings for mechanical durability in factory environments.
Electric Vehicles leads on scale; Energy Storage Systems leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province anchors structural parts production through die-casting clusters serving CATL and BYD supply chains. China's NMPA GB 38031-2020 thermal propagation standards are compressing qualification timelines for housing suppliers across four additional national markets.
China
CATL and BYD procurement concentrates in Jiangsu and Guangdong province clusters where die-casting suppliers maintain resident engineering teams. NMPA enforcement of GB 38031-2020 five-minute no-fire thresholds through 2024 has disqualified suppliers lacking laser-welded sandwich panel capabilities. Shenzhen and Wuxi housing fabricators now co-locate R&D personnel at cell maker technical centers to compress design iteration cycles.
Germany
Premium EV platforms from Munich and Stuttgart specify housings with integrated cooling channels for 800V architectures. EU F-Gas Regulation sealing performance mandates accelerate fluoropolymer gasket qualification programs among domestic tier suppliers. Bavarian and Baden-Württemberg automotive clusters attract Korean cell producers seeking aluminum-ceramic composite sourcing for UN ECE R100 convergence.
United States
IRA domestic content credits attract greenfield die-casting investments for North American battery component assembly. NHTSA crash-test protocols coordinate with EPA end-of-life recyclability rules that affect casing design specifications. Midwest and Southeast manufacturing corridors expand housing fabrication capacity to serve Tesla, Ford, and GM cell-to-pack programs.
South Korea
LG Chem and domestic cell producers accelerate aluminum-ceramic composite adoption to meet converging GB and UN ECE R100 timelines. MFDS alignment with international battery safety standards streamlines export certification for structural component suppliers. Gyeonggi-do and Busan-Ulsan industrial zones concentrate die-casting investments serving expanding European OEM customer bases.
Japan
METI technology roadmaps prioritize pressure-resistant housing designs for next-generation solid-state cell formats. JIS standards for battery structural integrity inform domestic supplier qualification thresholds that exceed baseline ISO requirements. Kanto and Kansai manufacturing belts maintain precision stamping capabilities for high-tolerance connector interfaces in hybrid vehicle applications.
New Energy Battery Structural Parts Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated thermal management fabrication capabilities. The supplier base stratifies between captive cell maker production and qualified external specialists. Three archetypes dominate: aluminum extrusion specialists, high-tonnage die-casting operators, and captive in-house manufacturers. Capacity expansion and strategic partnerships represent the dominant competitive moves as OEM procurement teams disqualify suppliers lacking integrated cooling channel capabilities.
Among Chinese fabricators, Shenzhen Kedali Industry and Wuxi Jinyang New Material occupy positions within the aluminum extrusion and precision forming tier. SANGSIN EDP anchors the Korean supplier archetype serving European expansion. Contemporary Amperex Technology Co. exemplifies the captive manufacturer model that maintains in-house structural parts production while selectively outsourcing non-core components.
| Leading Market Players |
|---|
| Shenzhen Kedali Industry |
| SANGSIN EDP |
| Zhenyu Technology |
| Wuxi Jinyang New Material |
| Zhongrui Electronic Technology |
| Shenzhen Everwin Precision |
| Fuji Springs |
| Contemporary Amperex Technology Co. |
| LG Chem |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production among cell makers anchors supply positioning while compressing pricing power for external suppliers serving CATL and BYD programs. This integration choice concentrates procurement authority at Jiangsu and Guangdong engineering centers, forcing tier-2 fabricators to absorb LME aluminum volatility through fixed-price contracts.
Pricing Analysis
Primary aluminum cost pass-through dominates contract structures, with LME swings above $2,400 per tonne squeezing margin structures for suppliers locked into multi-year OEM agreements. Three-tier pricing structure across premium, standard, and economy levels separates laser-welded sandwich panel suppliers meeting GB 38031-2020 from conventional die-casters. Cost compression in standard-grade housings is intensifying because cell-to-pack elimination of module frames concentrates volume at fewer qualified vendors. Energy storage system buyers exhibit highest price sensitivity due to project-financing constraints, while premium European EV platforms tolerate premium positioning for integrated cooling channel designs.
Supply Chain Analysis
Freight cost optimization drives co-location of die-casting suppliers within 50 kilometers of CATL and BYD facilities in Jiangsu and Guangdong provinces. Supply concentration spans China, South Korea, and Germany, with raw material flows drawing from primary aluminum smelters, fluoropolymer gasket specialists, and ceramic composite producers. Single-source vulnerability in 6,000-ton press technology—controlled by Japanese and German equipment builders—constrains Chinese supplier expansion. Distribution runs through direct OEM procurement channels that bypass traditional tier-2 distributors, particularly for cell-to-pack programs where engineering teams dictate housing specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. OEM procurement teams now disqualify suppliers lacking integrated thermal management fabrication, elevating specification thresholds for structural component qualification.
For Market Incumbents: Hedge aluminum price exposure through long-term offtake agreements with Jiangsu smelters rather than spot-market procurement. Defend margin position by adding 6,000-ton press capacity in Guangdong clusters before Japanese equipment builders extend delivery lead times. Certification investment in GB 38031-2020 laser-welded sandwich panels represents the critical defensive lever against Korean aluminum-ceramic composite entrants. For New Entrants and Emerging Players: North American energy storage system integrators present the most penetrable buyer archetype given IRA domestic content credit eligibility and limited qualified local supply. Target solid-state cell format housing requirements where pressure-resistant designs command premium positioning absent entrenched competition. A direct-to-OEM digital configurator platform for custom battery tray geometries compresses traditional European distributor roles and accelerates technical qualification timelines. For Investors and Strategic Acquirers: Roll-up economics work for aluminum extrusion specialists with resident engineering capabilities because cell maker R&D center co-location creates sticky supplier relationships resistant to price-only competition. Five-to-ten year viability hinges on thermal runaway containment technology transitions rather than commodity stamping scale. The signal to watch is NMPA enforcement pace for GB 38031-2020 five-minute no-fire thresholds, which will accelerate supplier consolidation as qualification costs exclude smaller fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Cooling Channel Die-Casting Investment | Eliminates separate cold plate assemblies for 800V European premium EV platforms from Munich and Stuttgart. |
| Resident Engineering Team Deployment | Compresses design iteration cycles at CATL and BYD R&D centers in Jiangsu province. |
| GB 38031-2020 Certification Program | Qualifies suppliers for NMPA thermal propagation mandates that disqualify conventional housing fabricators. |
| North American Greenfield Die-Casting Facility | Captures IRA $35 per kWh domestic content credits for battery component assembly. |
| Aluminum-Ceramic Composite Qualification | Meets converging GB and UN ECE R100 timelines for Korean cell producers serving European OEMs. |
Research Methodology
Direct dialogue with battery platform engineers, tier-1 supplier procurement directors, die-casting plant managers, and NMPA regulatory consultants grounded qualitative findings in operational reality. Secondary validation drew from customs trade data, SEC filings of listed battery component suppliers, GB standards documentation, and EU F-Gas Regulation implementation guidance. Bottom-up cell format demand modeling and top-down OEM procurement budget analysis provided cross-referenced triangulation.
Bottom-up volume aggregation across die-casting, stamping, injection molding, and machining process segments anchored the analytical lens, with top-down OEM platform content-per-vehicle estimates providing consistency checks. Segmentation dimensions spanned component type, manufacturing process, material grade, and end-use application, with regional regulatory cluster effects modeled separately. CAGRs derived from installed capacity expansion timelines, cell format transition curves, and qualification cycle compression factors across the projection horizon.
Underlying measurement precision varies by segment; die-cast aluminum enclosures and integrated cooling channel designs carry tighter precision than polymer composite consumer electronics applications due to concentrated OEM procurement data availability. Forecasts reflect assumptions about NMPA enforcement consistency, LME aluminum price bands, and 6,000-ton press delivery schedules that could shift with equipment builder order backlogs or trade policy adjustments. Stakeholders should weight assumptions against their own operating context and supplier qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
Solar Containers Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Automotive Battery Plate Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
China Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Raw Materials Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
Smart Battery Swap Station Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
Battery-As-A-Service Market