
 US HVDC Transmission System Market | 2026-2036
US HVDC Transmission System Market Size, Share, and Industry Trends Forecast 2026-2036
US HVDC Transmission System Market Insights
Offshore wind integration is rebalancing the utility procurement mix toward submarine HVDC installations. Siemens Energy anchors North American converter station supply through specialized manufacturing footprints in the Southeast. General Electric competes on integrated turbine-to-grid offerings for Atlantic Coast lease areas. Prysmian Group dominates submarine cable qualification for deep-water export corridors.
High-voltage direct current transmission systems convert alternating current to DC for efficient long-distance power transfer above 100 kV, using line-commutated or voltage-source converter topologies to minimize resistive losses across hundreds of miles. Voltage source converter installations now lead new US project awards due to superior grid-forming capabilities and black-start resilience. Modular multilevel converter architectures are capturing premium-margin segments where utilities require harmonic performance for sensitive load interconnection. Submarine installations command specialized engineering pools as Atlantic offshore wind buildouts deepen cable-laying demand.
FERC interconnection standards, NERC reliability criteria, and IEEE 1547-2018 grid integration requirements collectively shape converter specification, testing protocols, and market access timelines for HVDC projects. State renewable portfolio mandates in New York, New Jersey, and Massachusetts directly translate into solicitations for subsea transmission links. Stakeholders must monitor FERC rulemaking on cost allocation for multi-state transmission lines, as these determinations will decide which project clusters secure financing commitment ahead of construction windows.
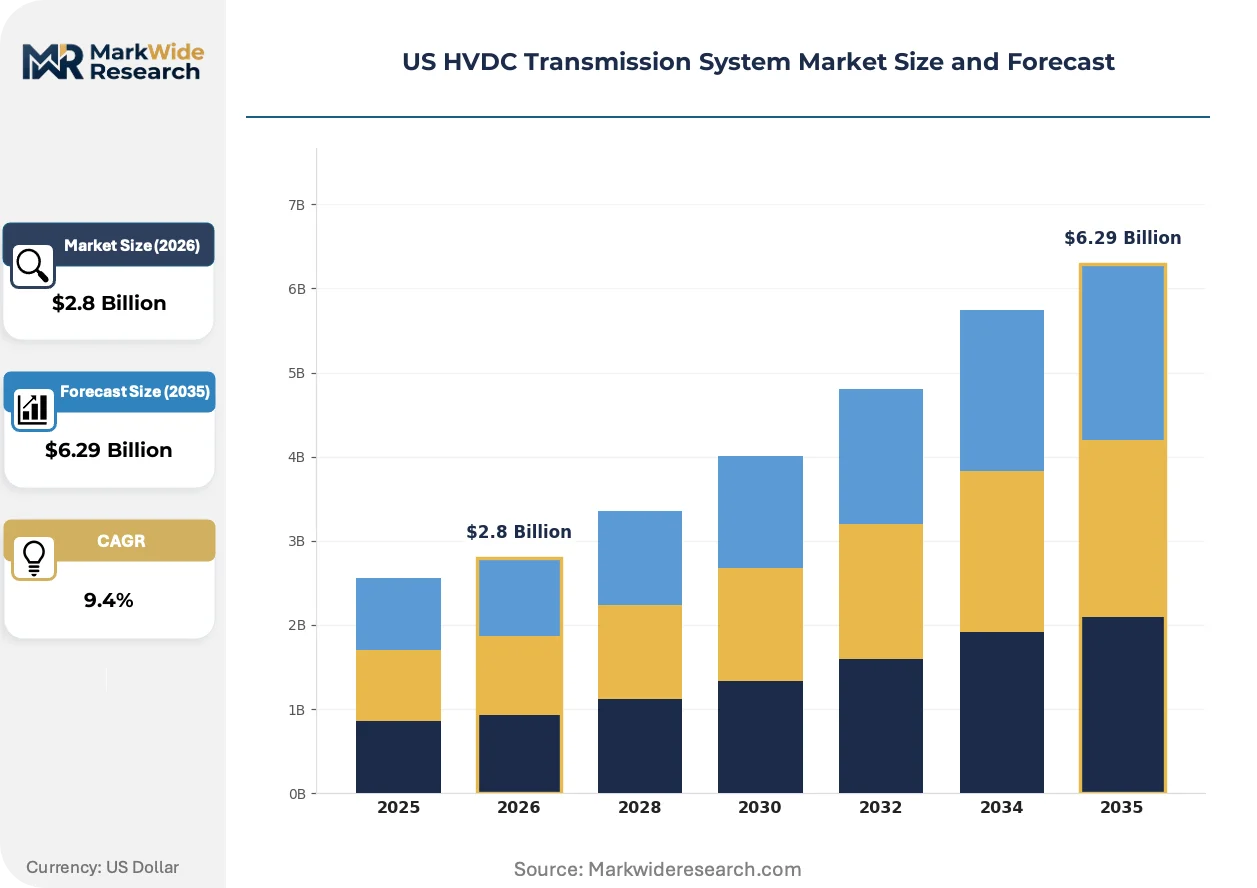
Market Dynamics
Voltage source converter technology is displacing line-commutated converter architectures across Atlantic Coast interconnection projects, compressing engineering timelines and reshaping supplier qualification requirements.
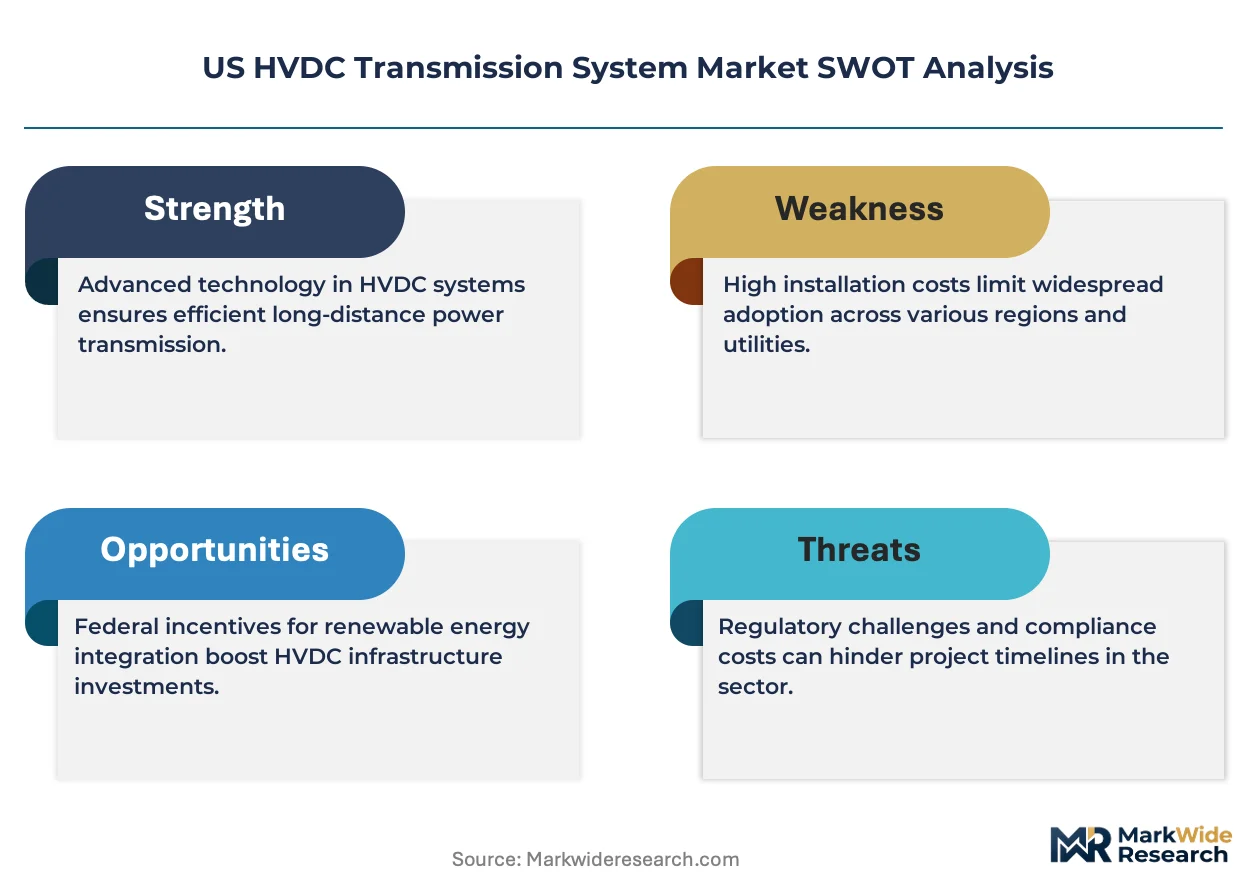
Growth Catalysts
- Offshore Wind Procurement Mandates:State renewable portfolio standards in New York, New Jersey, and Massachusetts mandate subsea transmission links for lease area power evacuation.
- FERC Order 2023:Interconnection queue reforms accelerate project processing timelines, reducing developer carry costs and improving financing visibility.
- Texas Coastal Load Centers:Industrial demand concentration along the Gulf Coast creates anchor points for long-distance HVDC corridors from remote generation.
Market Restraints
- Submarine Cable Supply Concentration:Deep-water cable manufacturing capacity concentrates among European suppliers, creating lead-time vulnerability for Atlantic projects.
- Copper and Rare Earth Input Volatility:Converter station construction faces commodity price exposure through lanthanide-dependent magnetic components.
- Multi-State Cost Allocation Friction:FERC rulemaking uncertainty on interstate transmission cost recovery mechanisms delays financing commitment for regional projects.
Strategic Opportunities
- Grid-Forming Inverter Retrofit:Existing AC transmission corridors present upgrade potential for black-start capable converter installations.
- California-Nevada Intertie Expansion:Western renewable export pathways remain underdeveloped relative to coastal buildouts.
- Modular Multilevel Converter Standardization:IEEE and IEC harmonization efforts create pathway for reduced certification burden and accelerated deployment.
Industry Challenges
- Specialized Marine Installation Labor:Cable-laying vessel crew and subsea jointing technicians operate under severe supply constraint.
- NERC CIP Cybersecurity Compliance:Converter control system certification timelines extend project commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US HVDC Transmission System Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Line Commutated Converter, Voltage Source Converter, Modular Multilevel Converter, Hybrid Converter Application: Interconnection, Long-Distance Transmission, Grid Stabilization, Renewable Integration End User: Electric Utilities, Independent Power Producers, Transmission Service Operators, System Operators Installation Type: Overhead, Underground, Submarine, Substation |
| Companies Covered | ABB, Toshiba Energy Systems & Solutions, Siemens Energy, Prysmian Group, NKT A/S, General Electric, Mitsubishi Electric Corporation, Schneider Electric, Hitachi Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US HVDC Transmission System Market Trends and Innovations
Converter topology evolution and procurement model restructuring are compressing supplier margins while expanding addressable project scale. Atlantic offshore wind integration requirements dominate engineering specification.
Modular multilevel converter architecture is integrating silicon carbide power semiconductors to achieve higher switching frequencies with reduced harmonic distortion. Offshore wind developers specify these systems for sensitive load interconnection at coastal substations. The technology is integrating turbine-scale generation directly into HVDC export circuits without intermediate AC collection platforms.
FERC Order 2023 interconnection reforms are standardizing study process timelines and cost allocation frameworks for transmission projects exceeding 100 kV. Developers gain financing certainty through predictable queue positions. Texas and Atlantic seaboard projects demonstrate earliest compliance adoption due to concentrated renewable buildout.
Utility procurement teams are consolidating converter station and submarine cable awards into single-source engineering-procurement-construction contracts. Traditional equipment supply arrangements fragment under integrated project delivery pressure. New York and New Jersey offshore wind solicitations exhibit this bundling most prominently.
US HVDC Transmission System Market Segmentation
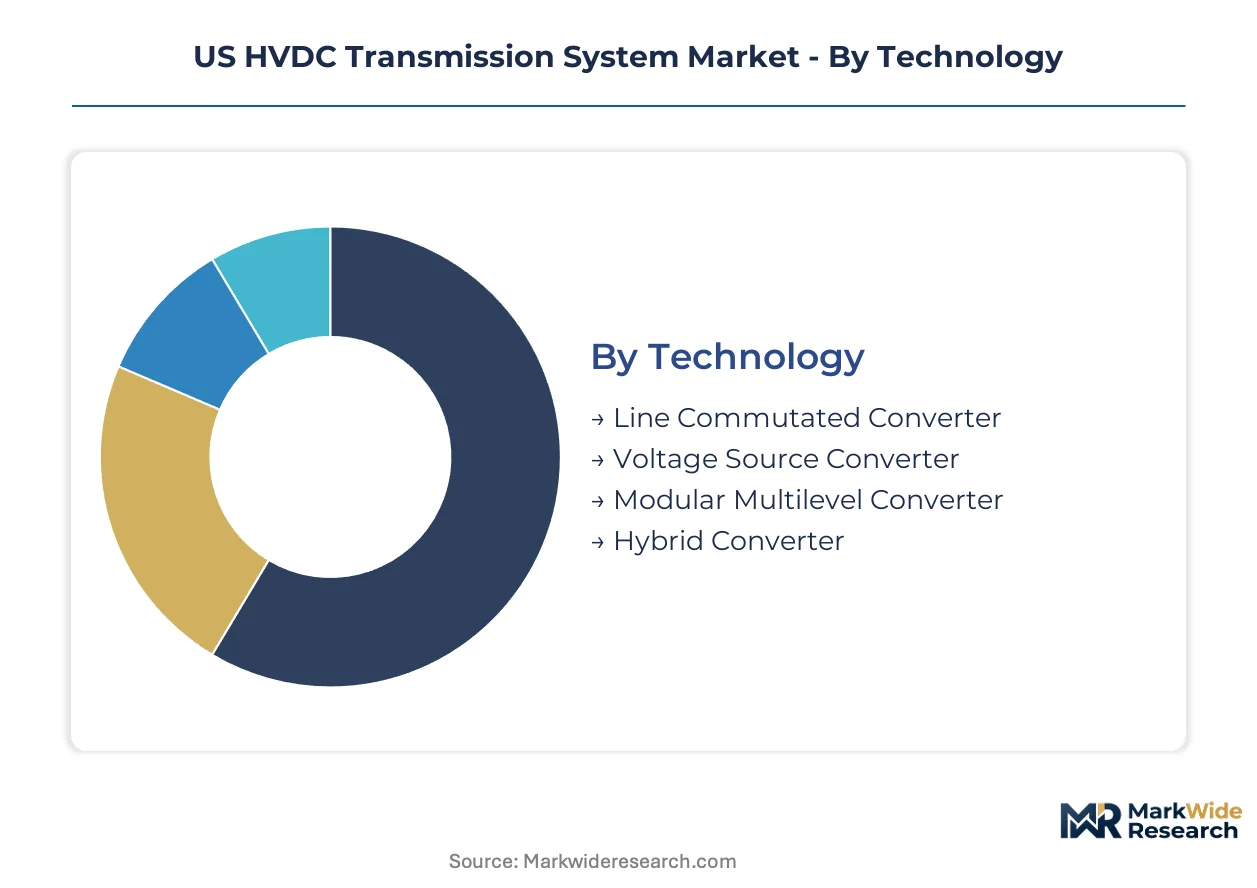
HVDC procurement patterns fragment sharply across technology generations and installation environments. Converter topology selection dictates supplier qualification, while installation type determines labor specialization and permitting complexity.
Technology:
Supply concentration among European converter manufacturers shapes technology adoption timelines for US developers.
- Voltage Source Converter:Self-commutating semiconductor bridges enable black-start capability and weak-grid connection. Atlantic offshore wind developers specify VSC for lease area export circuits due to superior grid-forming performance.
- Modular Multilevel Converter:Stacked submodule architecture achieves near-sinusoidal output without filtering. Texas coastal utilities favor MMC for harmonic-sensitive industrial load centers requiring precise voltage control.
- Line Commutated Converter:Thyristor-based rectification dominates legacy installations with stiff AC grids. Existing corridor upgrades preserve LCC infrastructure where converter replacement economics favor retention.
- Hybrid Converter:Combined LCC-VSC topologies balance cost and controllability for specific intertie applications.
Voltage Source Converter absorbs the bulk of installed capacity; Modular Multilevel Converter is expanding most quickly.
Application:
Cost tier differentiation separates high-complexity subsea interconnections from terrestrial long-distance corridors.
- Renewable Integration:Offshore wind evacuation and remote solar export require DC collection and conversion. New Jersey and Massachusetts procurement mandates concentrate demand for subsea renewable links.
- Interconnection:Asynchronous grid coupling between ISOs and balancing authorities. PJM-ERCOT intertie studies demonstrate FERC Order 2023 queue processing benefits for interconnection applicants.
- Long-Distance Transmission:Bulk power transfer from remote generation to coastal load centers. Texas Gulf Coast industrial demand anchors corridor development from West Texas renewable zones.
- Grid Stabilization:Frequency containment and oscillation damping through HVDC back-to-back stations.
Renewable Integration commands premium engineering resources; Interconnection is gaining share fastest.
End User:
Customer type determines procurement scale and contract structure for converter station awards.
- Electric Utilities:Investor-owned and public power entities with integrated transmission ownership. Consolidated Edison and Dominion Energy drive Atlantic Coast submarine cable procurement through bundled EPC contracts.
- Transmission Service Operators:Independent grid managers with FERC-jurisdictional tariff authority. MISO and SPP evaluate HVDC for seam elimination between asynchronous interconnections.
- Independent Power Producers:Renewable developers seeking generator-tied transmission solutions. Offshore wind lease holders negotiate converter capacity reservations during interconnection queue entry.
- System Operators:Balancing authorities with reliability coordination responsibilities.
Electric Utilities retain dominant procurement volume; Transmission Service Operators are climbing the fastest.
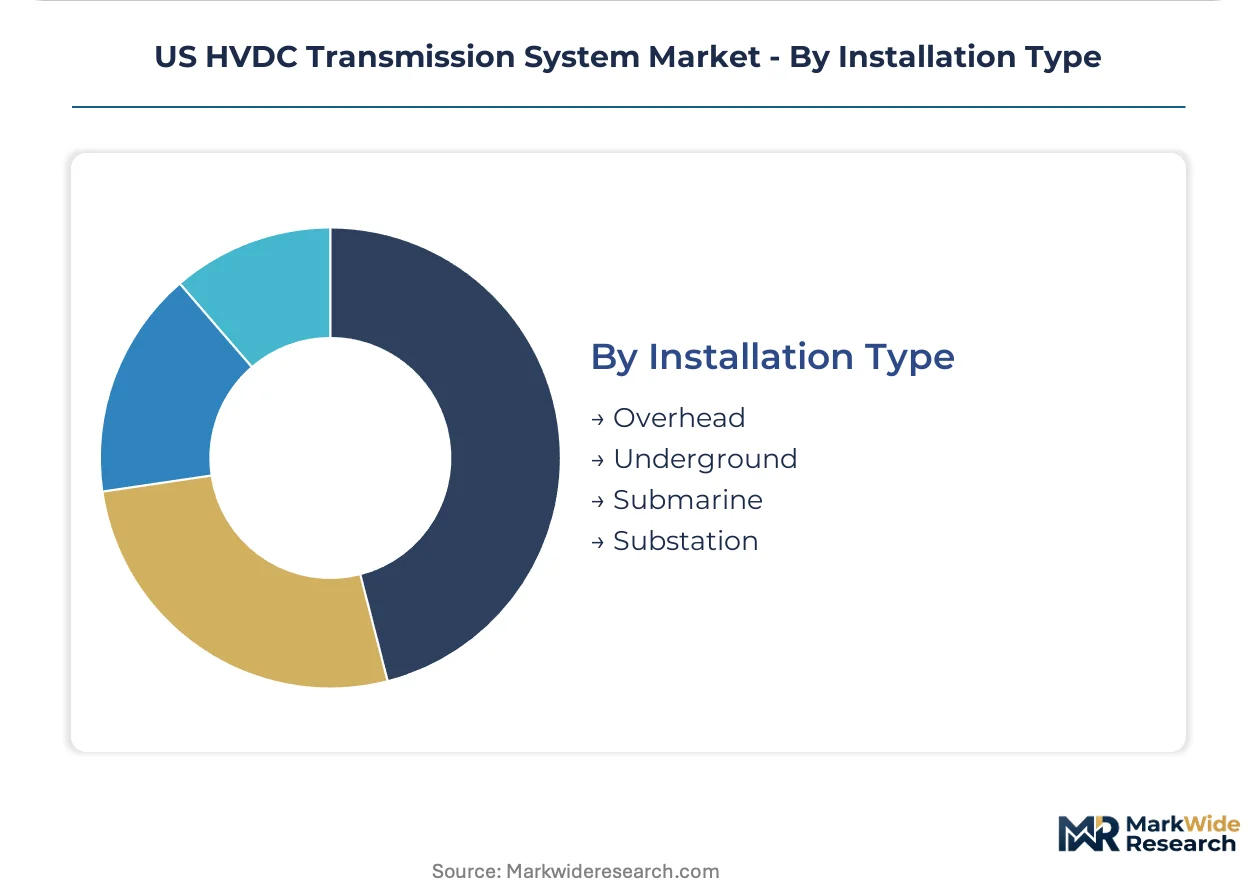
Installation Type:
Marine engineering specialization creates supply bottlenecks distinct from terrestrial construction.
- Submarine:Deep-water cable-laying and subsea jointing for offshore wind export. Atlantic seabed corridors from New York Bight to Massachusetts require specialized vessel fleets under severe crew constraint.
- Overhead:Conventional tower and conductor installation for terrestrial corridors. Texas and Western states favor overhead for cost efficiency across long distances with available right-of-way.
- Underground:Urban and environmentally constrained routing through direct-buried or duct-bank construction.
- Substation:Converter station and switchyard infrastructure for AC-DC interface.
Submarine installation absorbs the bulk of capital deployment; Overhead maintains steady expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified opportunity zones along the Atlantic seaboard and Gulf Coast are concentrating HVDC infrastructure investment through federal tax incentives and accelerated depreciation schedules.
Texas Gulf Coast
Industrial load centers from Houston to Corpus Christi anchor demand for long-distance corridors linking West Texas renewable zones to coastal manufacturing. ERCOT interconnection studies under FERC Order 2023 are accelerating queue processing for converter station proposals. Port of Houston infrastructure supports cable import logistics for submarine installation projects.
Mid-Atlantic Seaboard
New Jersey and New York offshore wind lease areas mandate subsea transmission links for power evacuation to coastal substations. State renewable portfolio standards in both jurisdictions require procurement timelines that compress converter station delivery schedules. New York Bight cable corridors are advancing through consolidated utility procurement.
New England Corridor
Massachusetts and Connecticut procurement mandates are driving bundled EPC contracts for submarine cable and converter station packages. ISO-NE interconnection standards require grid-forming capabilities that favor voltage source converter specifications. Boston-area substations are being upgraded for HVDC interface capacity.
California-Nevada Border
Western renewable export pathways from Nevada solar zones to California load centers remain underdeveloped relative to Atlantic buildouts. CAISO intertie studies evaluate asynchronous coupling for seam elimination between balancing authorities. Desert Southwest converter station sites are being scouted for future corridor development.
Southeast Atlantic
Virginia and North Carolina offshore wind planning is creating early-stage demand for submarine cable qualification. Dominion Energy transmission ownership positions the utility for integrated procurement of converter capacity. Hampton Roads port infrastructure is being assessed for cable-laying vessel staging.
US HVDC Transmission System Market Competitive Landscape
Top-tier vendors anchor converter station supply through specialized manufacturing footprints, while cable specialists concentrate deep-water qualification capabilities. European engineering heritage dominates high-voltage component production, with Asian conglomerates competing on integrated system offerings. Strategic archetypes include full-system integrators, component specialists, and cable-laying contractors. Consolidated EPC contracting and silicon carbide semiconductor integration represent the dominant competitive moves reshaping procurement patterns.
Among European-headquartered engineering groups, ABB, Siemens Energy, and Prysmian Group exemplify the tripartite structure of converter technology, system integration, and submarine cable specialization. These entities occupy positions that span the value chain from semiconductor switching to marine installation, representing archetypes that US developers must engage through bundled or unbundled procurement structures depending on project risk allocation preferences.
| Leading Market Players |
|---|
| ABB |
| Toshiba Energy Systems & Solutions |
| Siemens Energy |
| Prysmian Group |
| NKT A/S |
| General Electric |
| Mitsubishi Electric Corporation |
| Schneider Electric |
| Hitachi Energy |
| Others |
Pricing and Supply Chain Analysis
European engineering conglomerates with sovereign-backed capital structures anchor converter station manufacturing, translating concentrated ownership into disciplined pricing and multi-year contracting horizons that buffer commodity volatility. Their integrated financing arms extend payment terms to utility buyers while locking in rare earth supply through captive offtake agreements.
Pricing Analysis
Premium pricing for expedited converter station delivery compresses margins for developers facing FERC Order 2023 queue deadlines, while spot-market cable inventory trades at discounts during European factory maintenance windows. Project-based long-term contracting dominates, with price differentiation driven by IEC 61850 certification tier and harmonic performance guarantees. Pricing pressure intensifies as silicon carbide semiconductor shortages extend lead times for modular multilevel converter orders. Independent power producers exhibit acute price sensitivity relative to integrated utilities with captive balance sheet capacity.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Rotterdam and Singapore cable storage terminals to US coastal staging ports, with Port of Houston emerging as the dominant Gulf Coast node. Converter manufacturing concentrates in Germany, Switzerland, and Japan, while submarine cable extrusion feeds from Italy, Norway, and South Korea. The supply chain draws from lanthanide deposits in China and Malaysia for magnetic components, plus copper cathode from Chile and Peru. Single-source vulnerability in deep-water cable-laying vessel fleets poses structural risk. Distribution runs through EPC contractors with integrated marine installation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Voltage source converter technology is displacing line-commutated architectures across Atlantic Coast projects, compressing engineering timelines and reshaping supplier qualification requirements for a market in active technology transition.
For Market Incumbents: Cement converter station market share through backward integration into silicon carbide semiconductor sourcing, countering emerging Asian power electronics challengers. Expand Southeast manufacturing footprints to satisfy domestic content preferences in New York and New Jersey offshore wind solicitations. Prioritize NERC CIP cybersecurity certification investment to extend commissioning schedule advantages over unqualified competitors.
For New Entrants and Emerging Players: Launch via specialized marine installation subcontracting relationships targeting the California-Nevada intertie expansion corridor, where incumbent saturation remains lowest. White-space opportunities concentrate in grid-forming inverter retrofit of existing AC corridors and modular multilevel converter standardization consulting for IEEE-IEC harmonization efforts. Target Texas coastal industrial load centers through direct EPC partnerships with Gulf Coast port authorities.
For Investors and Strategic Acquirers: Distressed-cycle entries favor cable-laying vessel operators with Atlantic seabed qualification and stranded asset repositioning potential in the Mid-Atlantic region. Long-term viability hinges on exposure to FERC-jurisdictional multi-state cost allocation resolutions. Monitor FERC rulemaking on interstate transmission cost recovery mechanisms as the decisive financing commitment inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Semiconductor Integration | Enables higher switching frequencies for MMC installations serving harmonic-sensitive Texas industrial loads. |
| Submarine Cable Manufacturing Scale-Up | Addresses Atlantic offshore wind lead-time vulnerability through European supplier capacity expansion. |
| Grid-Forming Inverter Certification Program | Accelerates NERC CIP compliance timelines for converter control system deployments. |
| Integrated EPC Contracting Consolidation | Captures bundled procurement preference in New York and New Jersey utility solicitations. |
| Multi-State Cost Allocation Advocacy | Shapes FERC rulemaking outcomes to unlock financing for regional HVDC corridor development. |
Research Methodology
Independent corroboration across FERC interconnection filings, EIA generation datasets, and offshore wind lease area procurement records underwrites the qualitative findings presented herein. Primary interviews with utility transmission planning officers, IPP project developers, EPC contractors, and converter station engineering directors combined with secondary validation from NERC reliability assessments, IEEE standards documentation, and state renewable portfolio mandate filings. Bottom-up project pipeline enumeration and top-down infrastructure investment flow analysis provided cross-verification.
Historical reference periods spanning completed Atlantic Coast interconnection projects anchored the forecast window to observable construction timelines and commissioning patterns. The analytical framework modeled segmentation across converter topology, installation environment, end-user type, and regional regulatory cluster throughout the projection horizon. CAGRs derived from capacity-weighted project announcements and utility capital expenditure guidance, with FERC Order 2023 queue velocity and state mandate compliance deadlines as key forecast inputs.
Commodity price volatility in copper and rare earth markets, FERC cost allocation rulemaking delays, and submarine cable vessel availability constraints are the dominant revision risks to the outlook presented. Forecasts reflect documented assumptions regarding interconnection queue processing efficiency and state procurement timeline adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
Global Industrial Distribution Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
United States High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
Natural Gas Refueling Infrastructure Market
Transmission and Distribution
Mobile Substation Market
Transmission and Distribution
North America DC Distribution Network Market
Transmission and Distribution
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
Power Transmission Lines and Towers Market