
 Saudi Arabia Refined Petroleum Products Market | 2026-2036
Saudi Arabia Refined Petroleum Products Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Refined Petroleum Products Market Analytics
Aviation sector offtake is hardening as Saudi Arabia expands airport capacity and pilgrimage traffic normalizes. Saudi Aramco leverages its Ras Tanura and Yanbu refining complexes to anchor domestic jet fuel supply. Petro Rabigh specializes in petrochemical-integrated refining, extending its product slate beyond conventional fuels. Shell PLC competes through retail network density along the Riyadh-Jeddah corridor.
Refined petroleum products are hydrocarbon outputs from crude oil distillation and conversion processes, typically meeting specifications for sulfur content, octane rating, or cetane index depending on end use. These products power internal combustion engines, industrial furnaces, and aviation turbines across the Kingdom's energy-intensive economy. Gasoline and diesel retain the largest volume shares given Saudi Arabia's vehicle fleet expansion and freight movement, while jet fuel exhibits the steepest trajectory as aviation capacity doubles at multiple airports. The industrial end-user segment commands premium margins due to long-term direct supply contracts with Jubail's petrochemical complex operators.
SFDA oversees fuel quality standards for consumer protection, while the Saudi Standards, Metrology and Quality Organization (SASO) enforces technical regulations on gasoline and diesel imports. The Saudi Energy Efficiency Center mandates minimum performance criteria for heating fuels, compressing demand for high-sulfur residual products. Stakeholders must monitor Royal Commission for Jubail and Yanbu environmental directives, as these local regulators impose stricter emissions limits than national baselines and will determine refinery upgrade priorities.
Market Dynamics
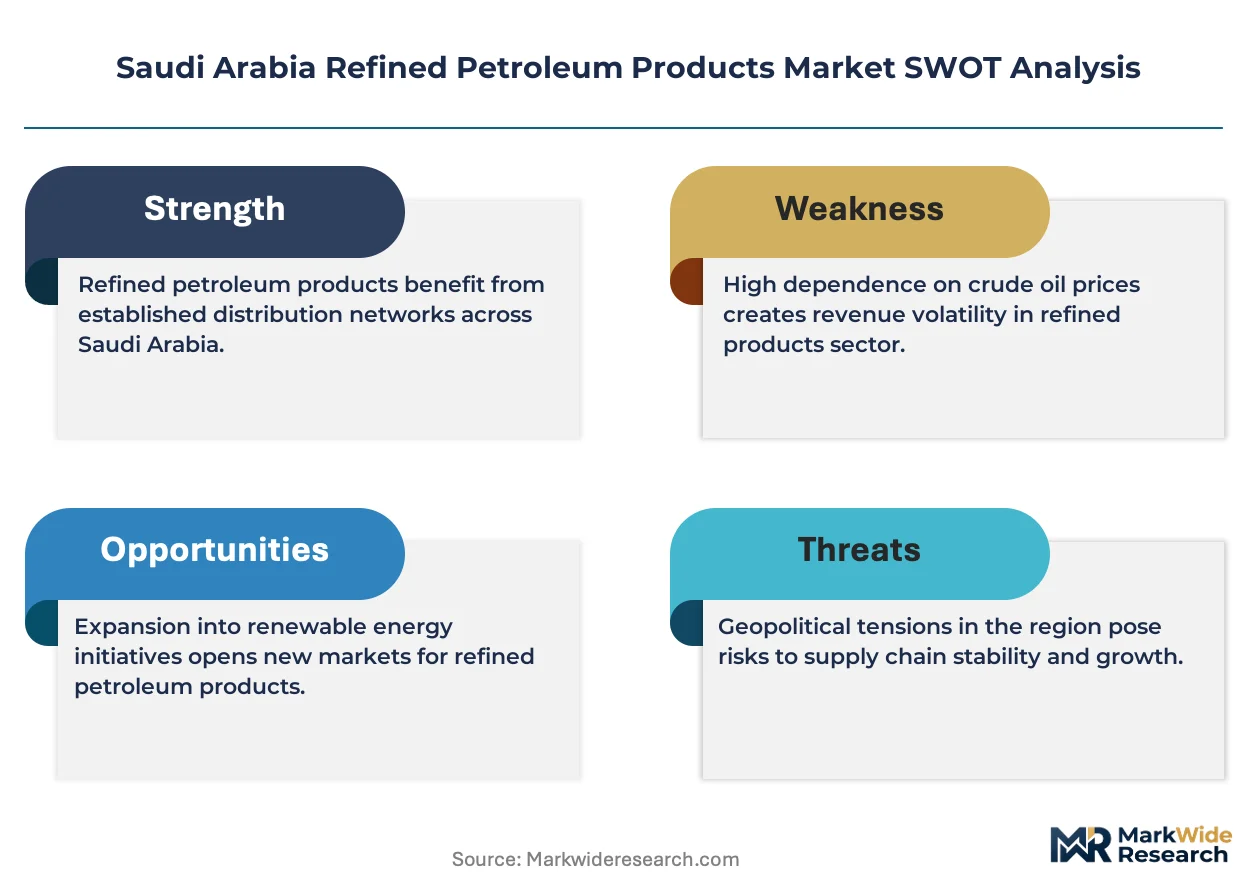
The Saudi Energy Efficiency Center's tightening building codes and sulfur specifications are compressing demand for high-sulfur residual fuels while redirecting investment toward hydrocracking and desulfurization upgrades at Ras Tanura and Yanbu complexes.
Growth Catalysts
- Aviation capacity expansion:King Abdulaziz International Airport and pilgrimage traffic normalization are hardening jet fuel offtake. Domestic refining complexes are prioritizing kerosene hydrotreater investments to capture this demand.
- SASO gasoline and diesel import regulations:Technical specifications on imported fuels are protecting domestic refinery margins. Local producers are capturing volume that previously flowed from Bahrain and UAE traders.
- Jubail petrochemical integration:Direct supply contracts between refineries and adjacent chemical operators are creating captive demand for naphtha and LPG feedstocks. This integration locks in long-term offtake agreements.
Market Restraints
- Crude sulfur content volatility:Heavy sour crude processing requirements at Saudi refineries expose margins to Arab Heavy- Arab Light price differentials. Feedstock quality shifts directly compress middle distillate yields.
- Royal Commission environmental directives:Stricter emissions limits at Jubail and Yanbu industrial cities are forcing unplanned catalyst replacements and flue-gas treatment investments ahead of regulatory deadlines.
- Electric vehicle penetration in Riyadh:Municipal fleet electrification targets and charging infrastructure rollout are capping gasoline demand growth in the Kingdom's largest consumption center.
Strategic Opportunities
- Asir Province distribution gaps:Limited retail network density south of Abha creates whitespace for independent marketers. Pipeline extensions from Jazan could unlock this geography.
- Marine fuel 0.5% sulfur compliance:IMO bunker fuel regulations are redirecting high-sulfur fuel oil demand toward VLSFO production. Yanbu's coker complex can pivot to capture Red Sea shipping traffic.
- Hydrogen refinery integration:Blue hydrogen production using captured CO2 from steam methane reforming is converging with refining operations. This pairing opens carbon credit revenue streams.
Industry Challenges
- Specialized hydrocracking operator scarcity:Advanced unit operations requiring dual-catalyst management and high-pressure hydrogen handling face talent shortages. Technical training pipelines have not kept pace with capacity additions.
- SFDA fuel quality certification timelines:New additive package approvals for gasoline octane enhancement face extended laboratory testing protocols. Product launch schedules slip pending regulatory clearance.
- Legacy DCS integration with digital twins:Ras Tanura's distributed control systems require substantial middleware investment to connect with real-time optimization platforms. Cybersecurity hardening adds implementation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Refined Petroleum Products Market |
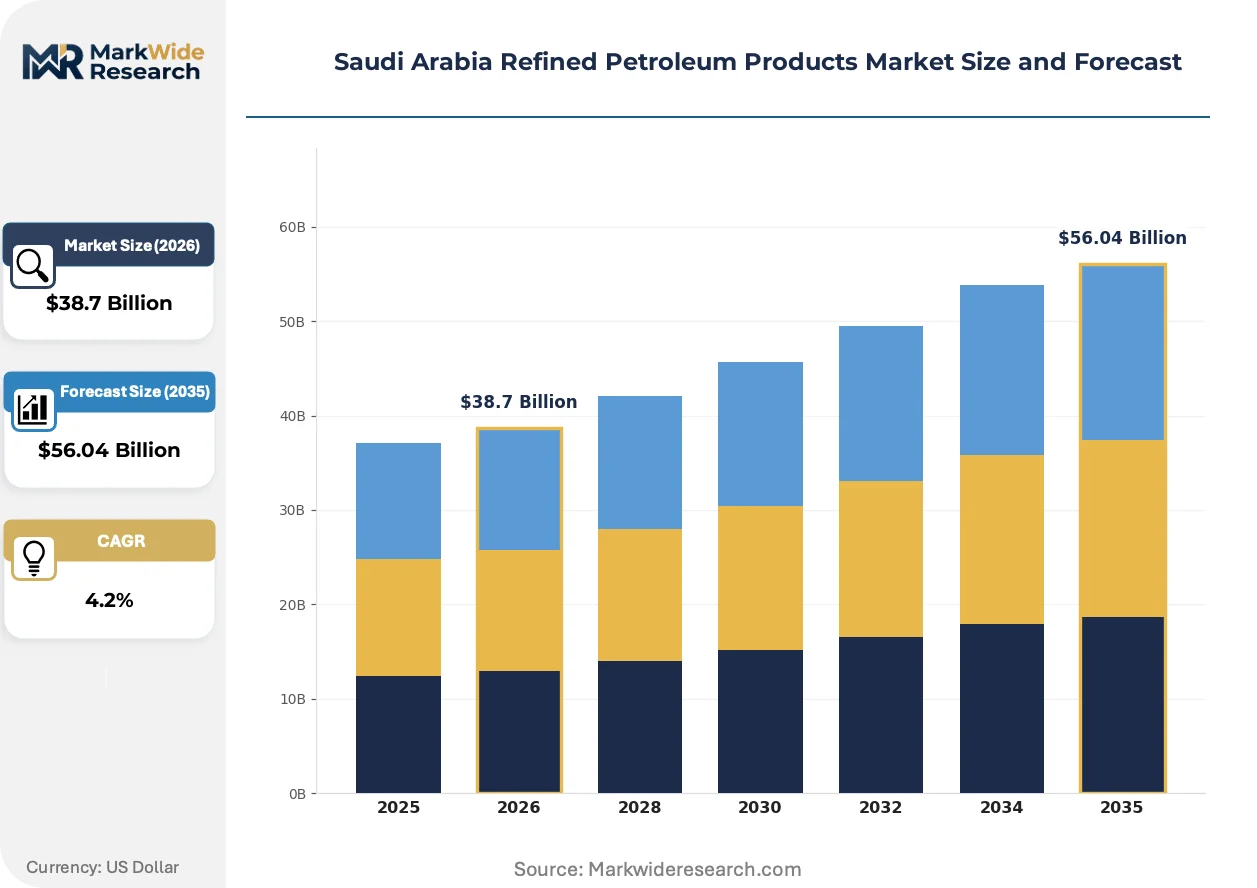
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Kerosene, Jet Fuel Distribution Channel: Retail Stations, Wholesale, Direct Supply, E-commerce End User: Transport, Industrial, Residential, Commercial Application: Power Generation, Transportation, Heating, Aviation |
| Companies Covered | Saudi Arabian Oil Company (Saudi Aramco), Arabian Petroleum Supply Company (APSCO), Chevron Corporation, Shell PLC, TotalEnergies SE, ExxonMobil Corporation, Petro Rabigh, Eni S.p.A., Marathon Petroleum Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Refined Petroleum Products Market Evolving Landscape
Refinery digitalization and carbon intensity tracking are reshaping operational priorities across Saudi Arabia's downstream sector. Technology deployment now centers on yield optimization and emissions verification rather than pure throughput expansion.
Advanced process control systems using machine learning algorithms are integrating with existing hydrocracker and reformer units. Yanbu and Jubail operators are deploying these platforms to predict catalyst deactivation and optimize hydrogen recycle rates. The technology is integrating real-time sensor data with planning systems, compressing the gap between laboratory analysis and unit setpoint adjustments from hours to minutes.
Saudi Energy Efficiency Center mandates on heating fuel specifications are forcing residual fuel oil producers to blend down sulfur content or exit the product category entirely. Industrial buyers in the Eastern Province must now certify combustion equipment compatibility with lower-viscosity alternatives. Large commercial consumers are responding by retrofitting furnaces or switching to natural gas where pipeline access permits.
Direct supply contracting between refineries and end-users is displacing spot market purchases for diesel and jet fuel volumes. Airlines and logistics operators are negotiating multi-year offtake agreements with Ras Tanura and Jazan suppliers, locking in volume commitments in exchange for price bands. This pattern is most visible in the aviation sector, where pilgrimage carriers are securing fuel security for seasonal demand spikes.
Saudi Arabia Refined Petroleum Products Market Segmentation
Segmentation in Saudi Arabia's refined petroleum products market reveals how product specifications, delivery mechanisms, and end-use requirements fragment demand across distinct commercial channels. Refiners configure output slates and pricing structures around these divisions, with regulatory pressure from SASO and the Saudi Energy Efficiency Center tightening specification boundaries between categories.
Product Type:
Buyers differentiate primarily by combustion performance requirements and sulfur tolerance thresholds, with transport fleets and industrial boilers imposing divergent quality standards.
- Gasoline:Blended to 91 and 95 octane ratings for spark-ignition engines, with SASO-mandated benzene limits below 1% by volume. Volume sits with private vehicle owners in Riyadh and Jeddah; electrification of municipal fleets is capping expansion in the capital corridor.
- Diesel:Cetane-indexed fuel for compression-ignition engines and stationary power, with 10 ppm sulfur caps enforced at Yanbu and Ras Tanura loading racks. Highway freight operators along the Riyadh-Jeddah corridor anchor offtake, though rail electrification is displacing long-haul diesel demand.
- Kerosene:Illuminating and heating grade with flash point specifications above 38°C, consumed in rural residential clusters lacking natural gas distribution.
- Jet Fuel:Kerosene-range distillate meeting Jet A-1 freezing point and smoke point criteria for turbine combustion. King Abdulaziz International Airport hardening and pilgrimage carrier fleet expansion are concentrating demand growth here.
Volume sits with Gasoline; growth tilts toward Jet Fuel.
Distribution Channel:
Channel selection tracks buyer scale and storage infrastructure, with large consumers bypassing retail markups through direct refinery contracting.
- Retail Stations:Branded and independent forecourts serving vehicle owners with immediate consumption needs. Shell PLC network density dominates the Riyadh-Jeddah corridor.
- Wholesale:Bulk deliveries to distributors and secondary marketers with intermediate storage capacity. Eastern Province traders supply interior regions lacking pipeline access.
- Direct Supply:Pipeline and dedicated tanker deliveries from Ras Tanura, Yanbu, and Jazan complexes to large industrial and aviation consumers. Jubail petrochemical operators lock in naphtha and LPG volumes through captive offtake agreements.
- E-commerce:Digital platforms for lubricant and specialty product ordering, with delivery logistics concentrated in metropolitan zones.
Direct Supply commands margin concentration; Retail Stations face electrification compression.
End User:
End-user categories align with regulatory exposure and contract duration, with industrial buyers securing multi-year supply security against spot volatility.
- Transport:Fleet operators and individual vehicle owners consuming gasoline, diesel, and jet fuel. Aviation carriers at King Abdulaziz International Airport are hardening seasonal offtake around pilgrimage peaks.
- Industrial:Petrochemical feedstock buyers, mining operators, and manufacturing facilities in Jubail and Yanbu industrial cities. Royal Commission environmental directives are forcing furnace fuel switching from residual oils to natural gas where pipeline access permits.
- Residential:Household heating and cooking demand in Asir Province and other regions beyond natural gas grid coverage. Saudi Energy Efficiency Center building codes are compressing high-sulfur heating oil consumption.
- Commercial:Retail, hospitality, and service sector fuel requirements concentrated in urban centers.
Industrial users lock in premium margins; Transport exhibits the steepest demand trajectory.
Application:
Application segmentation reflects combustion technology and emissions control requirements, with each use case imposing distinct specification and certification burdens.
- Power Generation:Diesel and residual fuel oils for grid backup and off-grid industrial facilities. Saudi Energy Efficiency Center mandates are redirecting capacity toward natural gas and renewables.
- Transportation:Road, rail, and marine fuel consumption governed by SASO import regulations and IMO sulfur caps for Red Sea bunkering.
- Heating:Residential and commercial space heating in highland regions, with sulfur content specifications tightening under efficiency center directives.
- Aviation:Turbine fuel for domestic and international carriers, with King Abdulaziz International Airport capacity expansion driving kerosene hydrotreater investments at domestic refineries.
Transportation anchors volume scale; Aviation climbs the fastest on capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Saudi Arabia's Eastern Province refining clusters, while consumption distributes across coastal urban corridors and inland pilgrimage routes. Domestic refining capacity exceeds local demand, positioning the Kingdom as a net exporter of middle distillates and residual fuels.
Eastern Province
Jubail and Ras Tanura host the Kingdom's densest refining infrastructure, with integrated petrochemical complexes consuming naphtha and LPG feedstocks. The Royal Commission for Jubail and Yanbu enforces emissions limits stricter than national baselines, forcing furnace fuel switching from high-sulfur residual oils to natural gas where pipeline access permits. Ras Tanura's hydrocracker investments target aviation kerosene output for King Abdulaziz International Airport expansion.
Riyadh
The capital corridor anchors gasoline and diesel consumption for private vehicle fleets and municipal operations. Municipal fleet electrification targets and charging infrastructure rollout are capping gasoline demand growth in the Kingdom's largest consumption center. The Saudi Energy Efficiency Center's building codes compress heating oil specifications for commercial developments across the metropolitan zone.
Western Region
Yanbu's Red Sea refining complex serves pilgrimage traffic and marine bunkering demand along the Jeddah-Mecca corridor. IMO 0.5% sulfur bunker fuel regulations redirect high-sulfur fuel oil demand toward VLSFO production at Yanbu's coker complex. Shell PLC's retail network density dominates forecourt supply along the Riyadh-Jeddah highway corridor.
Asir Province
Limited retail network density south of Abha creates whitespace for independent marketers in this highland residential heating market. SFDA fuel quality standards and SASO technical regulations govern product import and distribution licensing for interior regions lacking pipeline access. Pipeline extensions from Jazan could unlock this geography for direct refinery supply contracting.
NEOM Northwest
The giga-project zone is emerging as a testbed for hydrogen refinery integration and carbon capture deployment alongside conventional fuel supply. Saudi Energy Efficiency Center mandates on heating fuel specifications apply to construction-phase temporary power and permanent district heating systems. Blue hydrogen production using captured CO2 from steam methane reforming converges with planned refining operations in this zone.
Saudi Arabia Refined Petroleum Products Market Competitive Landscape
Top-tier vendors anchor integrated refining and petrochemical operations, while mid-tier trading houses and independent marketers compete on distribution reach. State-affiliated producers control upstream crude allocation and downstream refining capacity. Three archetypes dominate: integrated national oil companies with captive feedstock access, international majors leveraging retail network density, and petrochemical-integrated refiners specializing in feedstock supply. Competitive moves center on hydrocracker capacity additions and direct supply contracting with aviation and industrial off-takers.
Among state-affiliated operators, Saudi Arabian Oil Company (Saudi Aramco) anchors the national refining infrastructure through Ras Tanura and Yanbu complexes. Petro Rabigh occupies a position exemplifying petrochemical-integrated refining specialization, extending product slates beyond conventional fuels into naphtha and LPG feedstocks. Shell PLC represents the international major archetype, competing through retail network density along the Riyadh-Jeddah corridor rather than upstream crude access.
| Leading Market Players |
|---|
| Saudi Arabian Oil Company (Saudi Aramco) |
| Arabian Petroleum Supply Company (APSCO) |
| Chevron Corporation |
| Shell PLC |
| TotalEnergies SE |
| ExxonMobil Corporation |
| Petro Rabigh |
| Eni S.p.A. |
| Marathon Petroleum Corporation |
| Others |
Value Network & Pricing Analysis
Arab Heavy-Arab Light crude price differentials cascade through Saudi refining economics into three-tier pricing structure across premium, standard, and economy levels. Jet fuel commands premium bands at Ras Tanura loading racks while residual fuel oil discounts deepen under Saudi Energy Efficiency Center sulfur mandates.
Pricing Analysis
Margin tightening in aviation kerosene reflects King Abdulaziz International Airport capacity expansion and pilgrimage carrier offtake hardening. Contract-based long-term offtake agreements dominate, with price differentiation anchored in sulfur content grades and direct pipeline access. Cost-down pressure on high-sulfur residual products accelerates because Royal Commission environmental directives force industrial fuel switching. Municipal fleet operators exhibit highest price sensitivity; Jubail petrochemical buyers show lowest due to captive integration.
Supply Chain Analysis
SASO technical regulations on gasoline and diesel imports are reshaping sourcing toward domestic refinery capture. Supply concentrates in Saudi Arabia, with secondary flows from Bahrain and UAE traders compressing under local-content enforcement. Raw material dependencies center on Arab Heavy crude, hydrogen for hydrotreating, and specialized catalysts for hydrocracking units. Single-source vulnerability sits with Ras Tanura and Yanbu complex concentration. Distribution runs through direct pipeline supply to industrial offtakers, wholesale bulk to interior distributors, and branded retail networks along the Riyadh-Jeddah corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's refined petroleum products market is consolidating around integrated refining-petrochemical complexes, with Royal Commission environmental compliance costs forcing independent marketers toward exit or acquisition.
For Market Incumbents: Cement hydrocracker yield advantages at Yanbu and Ras Tanura through catalyst management digitalization. Lock in aviation offtake via multi-year pilgrimage carrier contracts before Jazan capacity ramps. Defend against Shell PLC retail density through direct supply contracting with Riyadh municipal fleets. For New Entrants and Emerging Players: Capture Asir Province whitespace south of Abha where pipeline extensions from Jazan could displace trucked supply. Target independent marine bunkering at Red Sea ports under IMO 0.5% sulfur compliance windows. Lead with digital procurement platforms for lubricant and specialty product segments. For Investors and Strategic Acquirers: Distressed-cycle entries favor petrochemical-integrated mid-cap refiners in the Eastern Province with stranded naphtha offtake agreements. Long-term viability hinges on hydrogen refinery integration and carbon capture revenue streams. Watch Royal Commission emission limit enforcement timelines as margin compression inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocracker Capacity Addition | Captures aviation kerosene demand from King Abdulaziz International Airport expansion. |
| Direct Supply Agreement | Locks in Jubail petrochemical feedstock volumes against spot market volatility. |
| Retail Network Expansion | Extends forecourt presence along underserved Asir Province corridors. |
| Blue Hydrogen Integration | Pairs steam methane reforming with carbon capture for NEOM zone supply. |
| Marine Fuel 0.5% Sulfur Pivot | Redirects Yanbu coker output toward Red Sea VLSFO bunkering demand. |
Research Methodology
Document review covered customs and trade data, refinery disclosure filings, and Saudi Energy Efficiency Center regulatory releases, complemented by interviews with refinery operations managers, aviation fuel procurement leads at King Abdulaziz International Airport, Jubail petrochemical complex supply planners, and Eastern Province wholesale distributors. Secondary validation drew from SASO technical regulations, Royal Commission environmental directives, and IEA downstream sector reports. Bottom-up volume modeling triangulated against top-down macroeconomic indicators.
Cross-referencing historical throughput data with expert panel input on capacity expansion timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end-user category, and regional production hub. CAGRs derived from trend extrapolation moderated by regulatory intervention assumptions. Industry-specific inputs incorporated crude sulfur content shifts and hydrotreater investment pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electric vehicle penetration rates in Riyadh and hydrogen refinery integration economics. Projections reflect assumptions on pilgrimage traffic normalization and IMO marine fuel enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Performance Oil Sales Market
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
Oil Refinery Market
Petroleum Products
Oil Shale Market
Petroleum Products
Europe Ethane Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market
Petroleum Products
Crude Oil Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
Petroleum Benzine Market
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
Tar Oil Market
Petroleum Products
South Africa Lubricants Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market