
 Heat Interface Unit Market | 2026-2036
Heat Interface Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Interface Unit Market Analysis
Smart-controls integration across premium specification tiers is redrawing competitive boundaries in the Heat Interface Unit landscape. Bosch Thermotechnology leverages its sensor-embedded product lines to dominate connected heating infrastructure across Northern Europe. Danfoss anchors its position through deep manufacturing scale in plate heat exchanger assemblies. Alfa Laval differentiates via specialized marine-to-building technology transfer that extends thermal efficiency benchmarks into commercial district networks.
A heat interface unit functions as a self-contained heat exchange and metering assembly that transfers thermal energy from a central district heating network into individual building circuits, typically operating with primary-to-secondary temperature differentials of 70/40°C and incorporating hydronic decoupling to protect network stability. Plate heat exchanger technology leads installed volume due to compact footprint and modularity, while smart controls represent the fastest-expanding margin pool as remote monitoring and demand-response capabilities become standard procurement requirements. Horizontal units maintain mature penetration in retrofitted multi-residential stock, whereas modular configurations capture new-build specifications seeking future expansion capacity.
EU Green Deal building renovation targets, enforced through national transpositions of the Energy Performance of Buildings Directive, mandate heat metering and temperature control in multi-unit buildings, directly expanding HIU replacement cycles across member states. Ecodesign regulations and CE marking requirements under the F-Gas Regulation constrain refrigerant-based alternatives and reinforce hydronic HIU specification in commercial applications. Stakeholders must monitor how national heat network zoning decisions in France, Germany, and the Netherlands reshape addressable market boundaries for unit suppliers.
Market Dynamics
District heating network densification across Northern European cities is compressing installation timelines and forcing HIU suppliers to modularize production lines for rapid site deployment.
Growth Catalysts
- EU Green Deal transposition:National building renovation targets under the Energy Performance of Buildings Directive mandate heat metering and temperature control in multi-unit buildings, accelerating replacement cycles.
- Smart control integration:Sensor-embedded units with remote monitoring capabilities capture premium specifications as property developers prioritize connected heating infrastructure.
- Urban district heating expansion:Germany's municipal heat network zoning decisions in Berlin, Hamburg, and Munich concentrate new-build demand for modular HIU configurations.
Market Restraints
- Plate heat exchanger supply concentration:Manufacturing scale for compact thermal assemblies clusters with specialized European foundries, creating input bottlenecks during demand surges.
- F-Gas Regulation constraints:Ecodesign and CE marking requirements under EU refrigerant rules eliminate compressor-based alternatives, limiting technology diversification for commercial applications.
- Copper and stainless steel volatility:Raw material price swings for heat exchange surfaces compress margin predictability for standardized unit tiers.
Strategic Opportunities
- Retrofit acceleration in France:National heat network zoning decisions in Paris, Lyon, and Marseille expand addressable market boundaries for replacement HIU suppliers.
- Marine-to-building technology transfer:Specialized thermal efficiency benchmarks from offshore applications migrate into commercial district networks, opening premium specification tiers.
- Demand-response capability standardization:Grid balancing service contracts create new revenue attachment points for smart-controlled units in Scandinavian multi-residential developments.
Industry Challenges
- Hydronic engineering talent scarcity:Specialized commissioning expertise for primary-to-secondary temperature differential optimization lags installation volume growth.
- Legacy building integration complexity:Horizontal unit retrofits in aging multi-residential stock require custom piping adaptations that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Interface Unit Market |
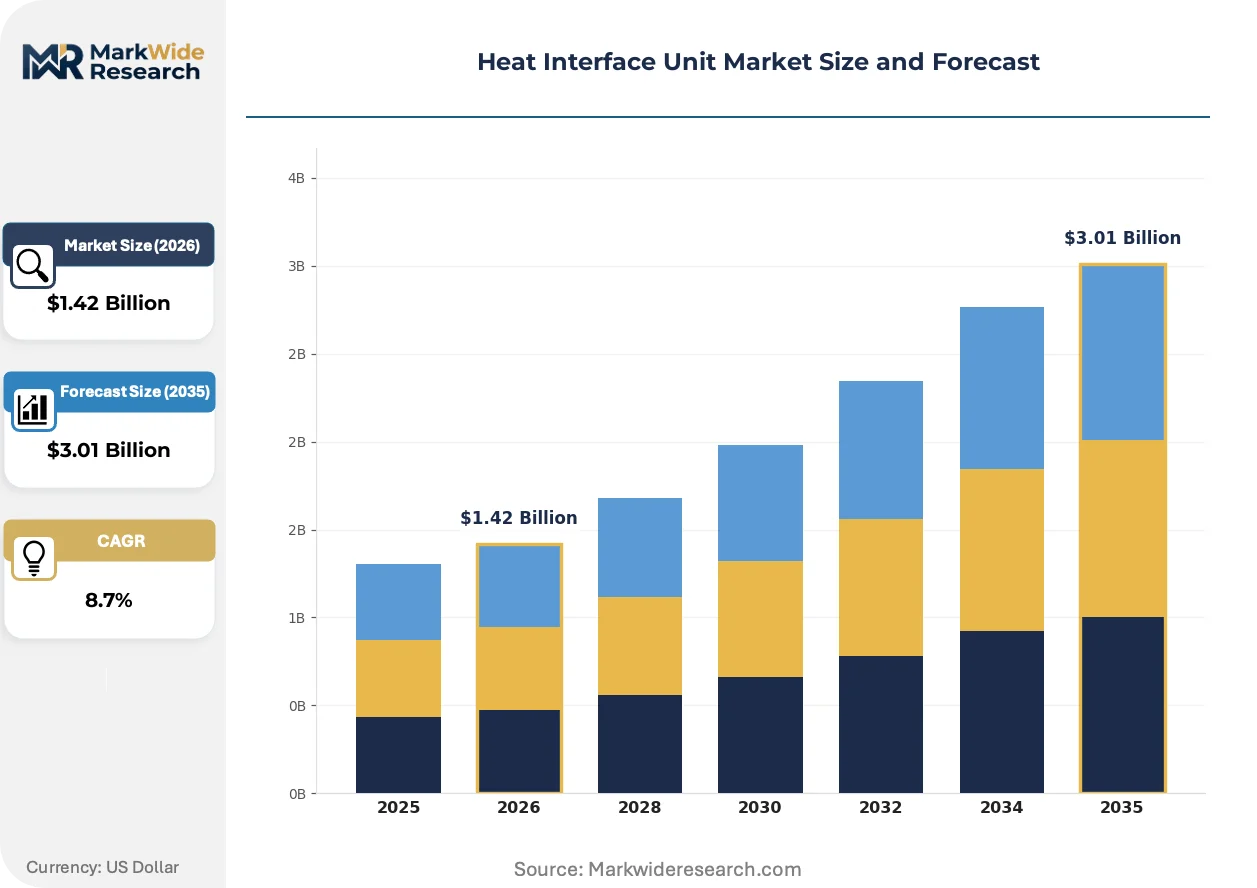
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Units, Horizontal Units, Combined Units, Modular Units Application: District Heating, Residential Heating, Industrial Heating, Commercial Heating Technology: Plate Heat Exchangers, Shell and Tube Heat Exchangers, Electric Heating, Smart Controls End User: Building Owners, Facility Managers, Utilities, Contractors |
| Companies Covered | Bosch Thermotechnology, Dutypoint, Danfoss, Caleffi, Honeywell, Alfa Laval, Kingspan, GIACOMINI, Armstrong Fluid Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Interface Unit Market Emerging Trajectories
Heat interface unit architecture is splitting into divergent specification paths as connected infrastructure demands collide with cost pressures in mass-market retrofits.
Plate heat exchanger technology is bifurcating the product landscape. Compact modular assemblies dominate new-build specifications seeking future expansion capacity. Retrofit installers cling to standardized horizontal configurations for aging building stock. The technology divergence is compressing mid-tier pricing power as buyers sort into performance-optimized versus cost-optimized camps.
EU F-Gas Regulation enforcement through national transpositions reinforces hydronic HIU specification in commercial applications. Ecodesign mandates constrain refrigerant-based alternatives from gaining material share. Germany's federal building codes and France's RT2012 thermal regulations most directly reshape procurement requirements for district heating connection points.
Specification authority is migrating from mechanical contractors to energy service companies. ESCOs bundle HIU procurement with long-term thermal performance guarantees, displacing traditional distributor relationships. This channel shift concentrates most visibly in Denmark and Sweden where district heating operators vertically integrate installation and maintenance functions.
Heat Interface Unit Market Segmentation
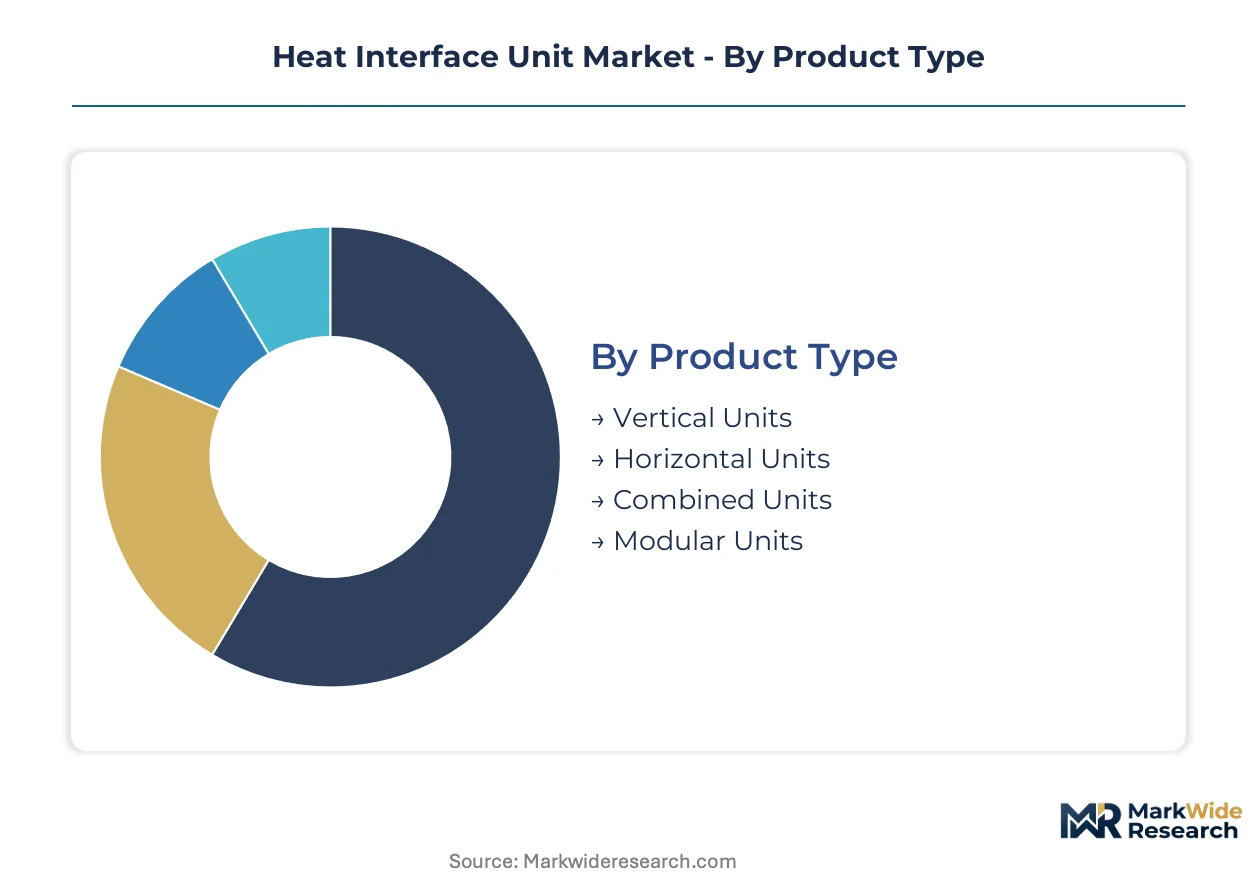
Product architecture in heat interface units fragments across installation constraints, thermal performance tiers, and connectivity specifications. Procurement patterns diverge sharply between retrofit installers prioritizing dimensional compatibility and new-build developers seeking modular expansion capacity.
Product Type:
Margin pools concentrate in modular configurations where future-proofing specifications command premium pricing, while horizontal units compete on replacement cycle volume in aging building stock.
- Vertical Units:Floor-standing assemblies with integrated metering enclosures suit plant room installations in high-rise residential towers. Demand clusters in Germany's urban district heating zones where space constraints favor compact vertical stacking.
- Horizontal Units:Wall-mounted configurations with standardized pipe centers dominate retrofit specifications across Scandinavia's multi-residential stock. Denmark's ESCO-led procurement channels specify these for rapid site deployment in renovation waves.
- Combined Units:Integrated domestic hot water production reduces ancillary equipment costs for small-footprint buildings.
- Modular Units:Expansion-ready chassis with spare capacity ports attract new-build developers in France's heat network zoning expansion areas.
Horizontal units hold installed capacity. Modular units are rotating up the share rankings.
Application:
Volume splits between centralized district infrastructure and distributed building-level heating, with commercial specifications pulling toward higher thermal duty ratings.
- District Heating:Primary-to-secondary heat exchange assemblies with hydronic decoupling protect network stability across Northern European municipal systems. Germany's federal building codes mandate these connection points in Berlin, Hamburg, and Munich zoning districts.
- Commercial Heating:Higher-capacity units with redundant heat exchanger circuits serve office and retail specifications. France's RT2012 thermal regulations reshape procurement requirements for these installations in Paris and Lyon commercial districts.
- Residential Heating:Single-family and multi-unit dwellings specify compact duty ranges with basic metering.
- Industrial Heating:Process heat applications require specialized materials for aggressive thermal cycling.
District heating anchors current deployment volumes. Commercial heating is climbing the fastest as building efficiency mandates tighten.
Technology:
Smart controls capture expanding margin pools as remote monitoring becomes standard, while plate heat exchanger manufacturing scale concentrates with specialized European foundries.
- Plate Heat Exchangers:Compact brazed or gasketed assemblies with turbulent flow patterns maximize thermal transfer in minimal footprint. Scandinavian multi-residential developers specify these for smart-controlled units with demand-response capability.
- Smart Controls:Sensor-embedded architectures with cloud connectivity enable grid balancing service contracts. EU Green Deal building renovation targets mandate temperature control and metering, directly accelerating replacement cycles for connected units.
- Shell and Tube Heat Exchangers:Robust designs tolerate higher pressure differentials in industrial process applications.
- Electric Heating:Direct resistance elements serve backup or peak-shaving roles where district network capacity is constrained.
Plate heat exchangers dominate installed base. Smart controls represent the steepest expansion trajectory as procurement requirements evolve.
End User:
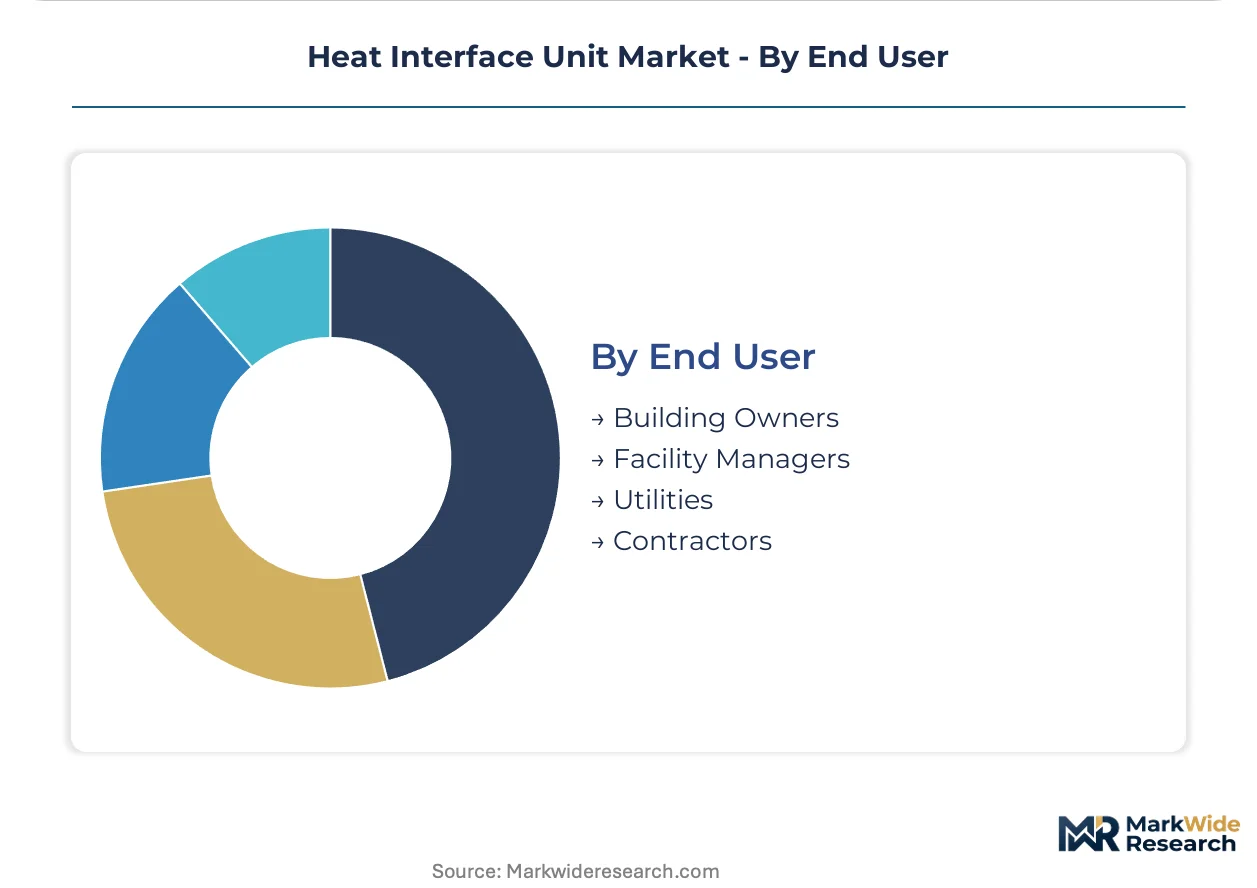
Specification authority is migrating from mechanical contractors to energy service companies, concentrating buying power in vertically integrated channels.
- Utilities:District heating operators in Denmark and Sweden vertically integrate installation and maintenance functions, bundling HIU procurement with long-term thermal performance guarantees.
- Facility Managers:Operational cost accountability drives demand for remote monitoring capabilities across Netherlands commercial building portfolios.
- Building Owners:Capital-constrained decision-makers prioritize first-cost minimization in standardized replacement cycles.
- Contractors:Installation speed and pipe-center compatibility dominate procurement criteria for retrofit project timelines.
Utilities consolidate specification authority. Facility managers are gaining share fastest as outcome-based thermal contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale for compact thermal assemblies clusters with specialized European foundries, creating input bottlenecks during demand surges. Germany, Denmark, and Sweden anchor installed capacity for plate heat exchanger components. France and the Netherlands concentrate specification authority through vertically integrated energy service channels.
Germany
Berlin, Hamburg, and Munich municipal heat network zoning decisions concentrate new-build demand for modular HIU configurations. Federal building codes under the Energy Performance of Buildings Directive mandate heat metering and temperature control in multi-unit buildings. The Rhine-Ruhr industrial corridor hosts dense district heating infrastructure requiring replacement cycle acceleration.
Denmark
ESCO-led procurement channels specify horizontal units for rapid site deployment in renovation waves. National transpositions of EU Green Deal building renovation targets enforce heat metering mandates across multi-residential stock. Copenhagen's district heating operator vertically integrates installation and maintenance functions, bundling HIU procurement with long-term thermal performance guarantees.
Sweden
Scandinavian multi-residential developers specify smart-controlled units with demand-response capability for grid balancing service contracts. The country's building efficiency standards under the Energy Performance of Buildings Directive accelerate replacement cycles for connected infrastructure. Stockholm's municipal heat network densification compresses installation timelines and forces suppliers to modularize production lines.
France
National heat network zoning decisions in Paris, Lyon, and Marseille expand addressable market boundaries for replacement HIU suppliers. RT2012 thermal regulations reshape procurement requirements for commercial district heating connection points. The Île-de-France region concentrates new-build specifications seeking modular expansion capacity for future network growth.
Netherlands
Commercial building portfolio managers drive demand for remote monitoring capabilities across facility management contracts. The country's municipal heat network zoning in Amsterdam, Rotterdam, and Utrecht concentrates district heating infrastructure investment. Dutch ESCOs bundle HIU procurement with outcome-based thermal contracts, displacing traditional distributor relationships.
Heat Interface Unit Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with sensor-embedded architectures commanding premium positioning against standardized horizontal configurations. The vendor base splits across three strategic tiers: diversified industrial conglomerates with heating divisions, specialized hydronics manufacturers with deep plate heat exchanger expertise, and regional fabricators serving retrofit replacement cycles. Consolidation pressure concentrates in the mid-tier as procurement authority migrates toward energy service companies. Dominant competitive moves include backward integration into plate heat exchanger manufacturing and strategic partnerships with district heating operators for long-term service contracts.
Among diversified industrial conglomerates, Bosch Thermotechnology and Honeywell occupy positions spanning connected heating infrastructure across Northern European markets. Danfoss exemplifies the specialized hydronics archetype through manufacturing scale in thermal assemblies. Alfa Laval represents technology transfer specialists migrating marine thermal efficiency benchmarks into commercial district networks. Caleffi and GIACOMINI anchor the European specialist tier with concentrated exposure to Mediterranean retrofit specifications.
| Leading Market Players |
|---|
| Bosch Thermotechnology |
| Dutypoint |
| Danfoss |
| Caleffi |
| Honeywell |
| Alfa Laval |
| Kingspan |
| GIACOMINI |
| Armstrong Fluid Technology |
| Others |
Supply Flow & Price Mechanics
CE marking requirements under the EU F-Gas Regulation gate both supplier qualification and price differentiation simultaneously, compressing refrigerant-based alternatives while elevating hydronic assembly premiums across commercial specifications. Buyers sort into certification-tiered procurement channels where Ecodesign compliance separates premium-connected units from economy horizontal configurations.
Pricing Analysis
The EU Energy Performance of Buildings Directive dictates the pricing tier structure across the Heat Interface Unit landscape, mandating heat metering and temperature control that accelerates replacement cycles for smart-controlled configurations. Pricing stratifies across premium sensor-embedded units, standard plate heat exchanger assemblies, and economy horizontal retrofits, with copper and stainless steel volatility compressing margin predictability at the lower tiers. Cost compression in standardized unit tiers is intensifying because raw material price swings for heat exchange surfaces outpace procurement contract adjustments. ESCO-led buyers in Denmark and Sweden exhibit least price sensitivity due to long-term thermal performance guarantees, while capital-constrained building owners in France's renovation waves drive hardest bargain on first-cost minimization.
Supply Chain Analysis
Inventory buffers for compact thermal assemblies run thin across Northern European supplier networks, with lead times extending during municipal heat network densification surges. Manufacturing scale clusters in Germany, Denmark, and Sweden for plate heat exchanger components, drawing from copper and stainless steel feedstock anchored in German and Belgian foundries. Single-source vulnerability concentrates in specialized European foundries producing brazed plate assemblies. Distribution runs through vertically integrated energy service channels in Scandinavia and mechanical contractor networks in Germany's federal building code zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Heat Interface Unit market is entering a cyclical recovery phase as EU Green Deal building renovation targets mandate replacement cycles across aging multi-residential stock. National transpositions of the Energy Performance of Buildings Directive provide the cyclical anchor.
For Market Incumbents: Shield market position by accelerating backward integration into plate heat exchanger manufacturing to offset foundry supply concentration risks. Deepen channel control through strategic partnerships with district heating operators in Copenhagen and Stockholm for long-term service contracts that displace distributor relationships. Certification investment in smart-control architectures preserves premium positioning against emerging sensor-embedded entrants from adjacent HVAC segments. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany opens procurement channels locked to incumbent suppliers. France's heat network zoning expansion in Paris, Lyon, and Marseille presents the most penetrable white-space for modular HIU configurations seeking future expansion capacity. ESCO bundling strategies in the Netherlands commercial building portfolio segment offer the clearest go-to-market angle for outcome-based thermal contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across smart-control sub-segments as sensor commoditization reduces R&D burn rates. The 5-10 year viability window favors acquisition targets with captive plate heat exchanger supply and established utility partnerships rather than pure-play software layers. Watch national heat network zoning decisions in Berlin, Hamburg, and Munich as the inflection indicator for modular configuration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plate Heat Exchanger Manufacturing | Captive supply of compact thermal assemblies insulates margin stability against German and Belgian foundry bottlenecks. |
| Smart Control Certification Investment | CE marking for sensor-embedded architectures unlocks premium procurement channels under EU Green Deal mandates. |
| ESCO Partnership Development | Long-term thermal performance guarantees with Copenhagen and Stockholm operators displace traditional distributor relationships. |
| Modular Configuration Expansion | Future-proofing specifications in France's heat network zoning areas command pricing premiums from new-build developers. |
| Demand-Response Capability Standardization | Grid balancing service contracts with Scandinavian multi-residential developers create recurring revenue attachment points. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, district heating operator procurement databases, and national building code transpositions across member states. Primary interviews engaged product managers at hydronics manufacturers, specification engineers at ESCOs, and procurement leads at municipal heat network operators. Secondary validation drew from Energy Performance of Buildings Directive national transposition documents, Ecodesign regulation impact assessments, and F-Gas Regulation enforcement records. Bottom-up unit deployment estimates triangulated against top-down district heating infrastructure investment forecasts.
Segmentation dimensions modeled include product architecture, application type, technology tier, and end-user procurement channel across the projection horizon. The analytical framework incorporates installation constraint differentials between retrofit horizontal specifications and new-build modular configurations. CAGRs were derived from replacement cycle acceleration curves under regulatory mandate phasing and smart-control penetration assumptions. Forecast inputs include municipal heat network densification timelines in named German cities and national renovation target enforcement in France and Denmark.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal implementation and stable copper and stainless steel input costs; material deviation in regulatory enforcement or commodity volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Pipeline Transportation Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
Transmission Housing Demand Market
Transmission and Distribution
Pantograph Disconnector Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Flexible AC Transmission Systems Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
Australia High Voltage Direct Current (HVDC) Transmission Systems Market