
 Global Transmission and Distribution Equipment Market | 2026-2036
Global Transmission and Distribution Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transmission and Distribution Equipment Market Insights
Multi-sourcing from regional foundries and component specialists is repositioning supply chain economics for transformer core steel and switchgear assemblies. Siemens Energy AG leverages captive manufacturing in Europe and Asia to sustain delivery reliability for high-voltage substations. ABB Ltd. anchors its competitive stance through deep specialization in digital substation automation and grid-edge control systems. Prysmian Group competes aggressively on cable system integration, bundling underground transmission lines with utility engineering services.
Transmission and distribution equipment encompasses the apparatus used to move electrical energy from generation sources to end-use points, including transformers rated from distribution-class kVA to bulk-power MVA levels, circuit breakers with interrupting capacities up to 63 kA, and gas-insulated switchgear designed for space-constrained urban installations. The primary purpose is to ensure voltage transformation, system protection, and power quality across interconnected grids. Transformers and switchgear command the largest share of product-type revenue, reflecting their irreplaceable role in every substation and their long replacement cycles that concentrate capital spending into cyclical upgrade windows. Smart grid technology within the technology dimension is expanding fastest, driven by utility mandates for real-time monitoring, fault location, and demand-response integration that retrofit conventional systems with sensor and communication layers.
Grid codes from the Federal Energy Regulatory Commission in the United States, the EU Green Deal framework, and the Central Electricity Authority technical standards in India collectively mandate higher efficiency tiers, lower SF6 emissions, and enhanced grid stability provisions that elevate equipment specifications and compliance costs. IEEE and IEC standards for transformer losses and switchgear short-circuit withstand further harmonize product requirements across export markets while creating certification barriers for non-compliant suppliers. Stakeholders must monitor how carbon-border adjustments and domestic content rules reshape sourcing economics for core laminations, insulating fluids, and ceramic bushings.
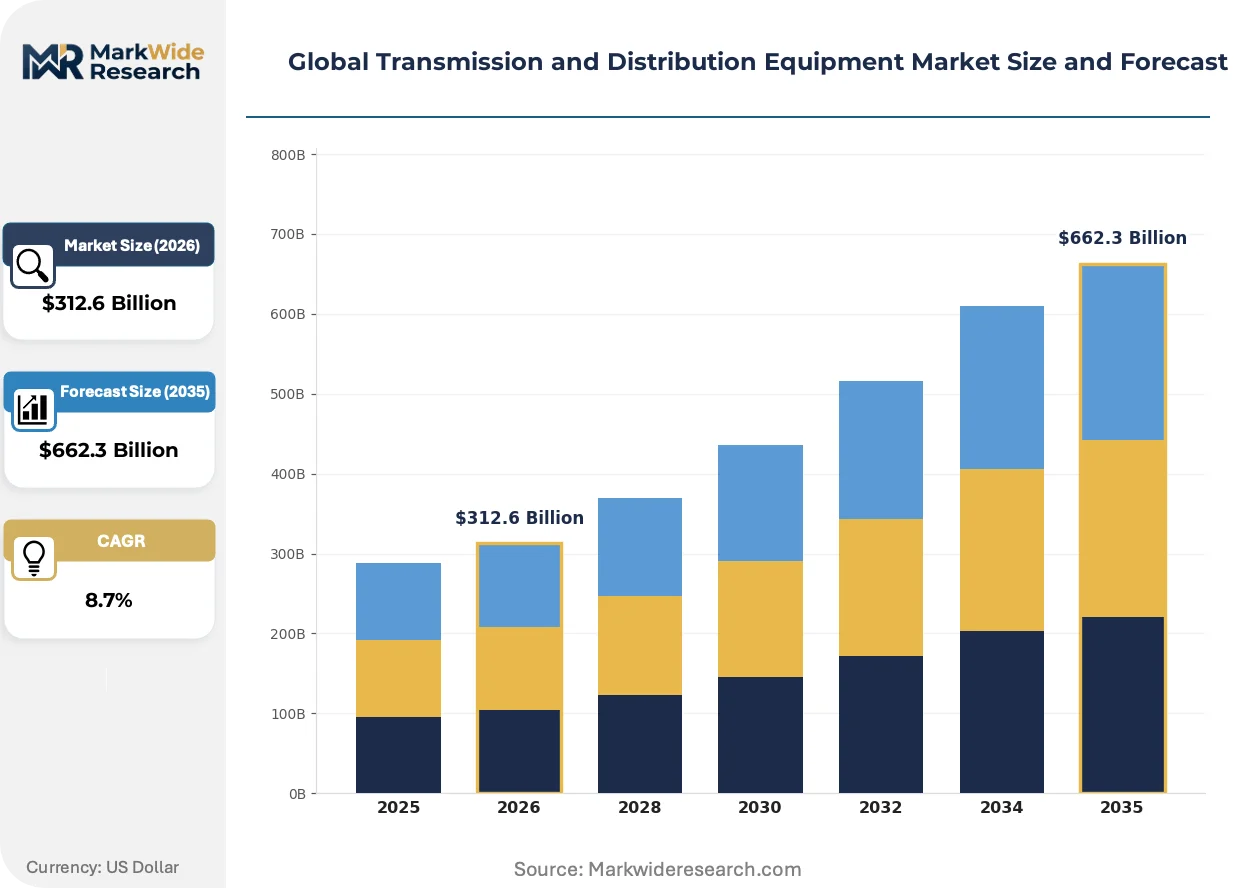
Market Dynamics
Grid modernization mandates from the EU Green Deal and renewable integration targets are compressing equipment replacement cycles while elevating technical specifications for efficiency and emissions compliance.
Growth Catalysts
- Renewable integration mandates:The EU Green Deal and national net-zero targets in Germany, Spain, and Denmark are forcing utilities to upgrade transformer fleets for bidirectional power flows and variable renewable absorption.
- Rural electrification programs:India's Saubhagya scheme and last-mile connectivity initiatives are driving massive procurement of distribution transformers and compact switchgear for underserved villages.
- SF6 phase-down regulations:The EU F-Gas Regulation and EPA voluntary partnership programs are accelerating adoption of vacuum interrupters and dry-air insulation in place of gas-insulated switchgear.
Market Restraints
- Grain-oriented electrical steel concentration:Over 70% of transformer core steel originates from facilities in China and Japan, exposing procurement to export quota volatility and geopolitical supply disruptions.
- Copper and aluminum price volatility:Winding conductors represent 25-35% of transformer manufacturing cost, with LME price swings compressing OEM margins and triggering contract renegotiation clauses.
- Skilled technician scarcity:Installation and commissioning of gas-insulated switchgear requires certified field engineers, with training pipelines in North America and Western Europe failing to match retirement outflows.
Strategic Opportunities
- Digital twin integration:Convergence of IoT sensor networks with physics-based modeling is creating predictive maintenance service contracts that extend OEM revenue streams beyond equipment sales.
- Offshore wind export corridors:Germany's North Sea grid expansion and planned interconnectors to Norway and the United Kingdom are generating demand for high-voltage direct current converter stations and subsea cable systems.
- Secondary market refurbishment:Circular economy incentives under the EU Ecodesign for Sustainable Products Regulation are legitimizing remanufactured transformers for non-critical industrial applications.
Industry Challenges
- Legacy protocol integration:Utilities operating IEC 61850 digital substations must bridge proprietary SCADA systems from the 1990s, creating cybersecurity vulnerabilities and commissioning delays.
- Type certification timelines:IEEE C57.12.00 and IEC 60076-1 testing protocols require 12-18 months for new transformer designs, freezing product development cycles while customer specifications evolve.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transmission and Distribution Equipment Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Breakers, Transformers, Switchgear, Capacitor Banks Installation Type: Indoor, Outdoor, Underground, Overhead End User: Utilities, Industrial Facilities, Commercial Buildings, Data Centers Technology: Smart Grid, Conventional Systems, Automation Solutions, Renewable Integration |
| Companies Covered | ABB Ltd., Siemens Energy AG, Schneider Electric SE, Mitsubishi Electric Corp., Eaton Corp. plc, Hitachi Energy, GE Vernova, Toshiba Corporation, Prysmian Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transmission and Distribution Equipment Market Trends and Innovations
Power electronics and solid-state switching are displacing electromechanical protection systems, while grid-edge intelligence migrates decision-making from centralized control rooms to substation-level automation.
Solid-state transformers based on silicon carbide power modules are decentralizing voltage regulation and power quality management. Data center operators in Northern Virginia and Singapore are piloting these units for harmonic isolation and seamless renewable integration. The technology is decentralizing traditional utility control architectures by enabling peer-to-peer energy transactions within microgrids.
The EU F-Gas Regulation's 2014/2020 amendments are banning SF6 in new medium-voltage switchgear from 2030, with intermediate phase-down quotas beginning in 2026. Manufacturers in Germany and Italy are accelerating vacuum interrupter R&D while retrofitting existing GIS installations with gas recovery protocols. Medium-voltage urban substations face the steepest compliance costs, driving consolidation among European switchgear specialists.
Performance-based service agreements are displacing traditional equipment procurement with guaranteed uptime contracts. Industrial buyers in Brazil and South Africa are unbundling transformer maintenance from capital purchases, transferring operational risk to OEM service divisions. Mining and metals processing verticals in Western Australia and Chile show the fastest contract structure migration, pressured by remote location maintenance cost inflation.
Global Transmission and Distribution Equipment Market Segmentation
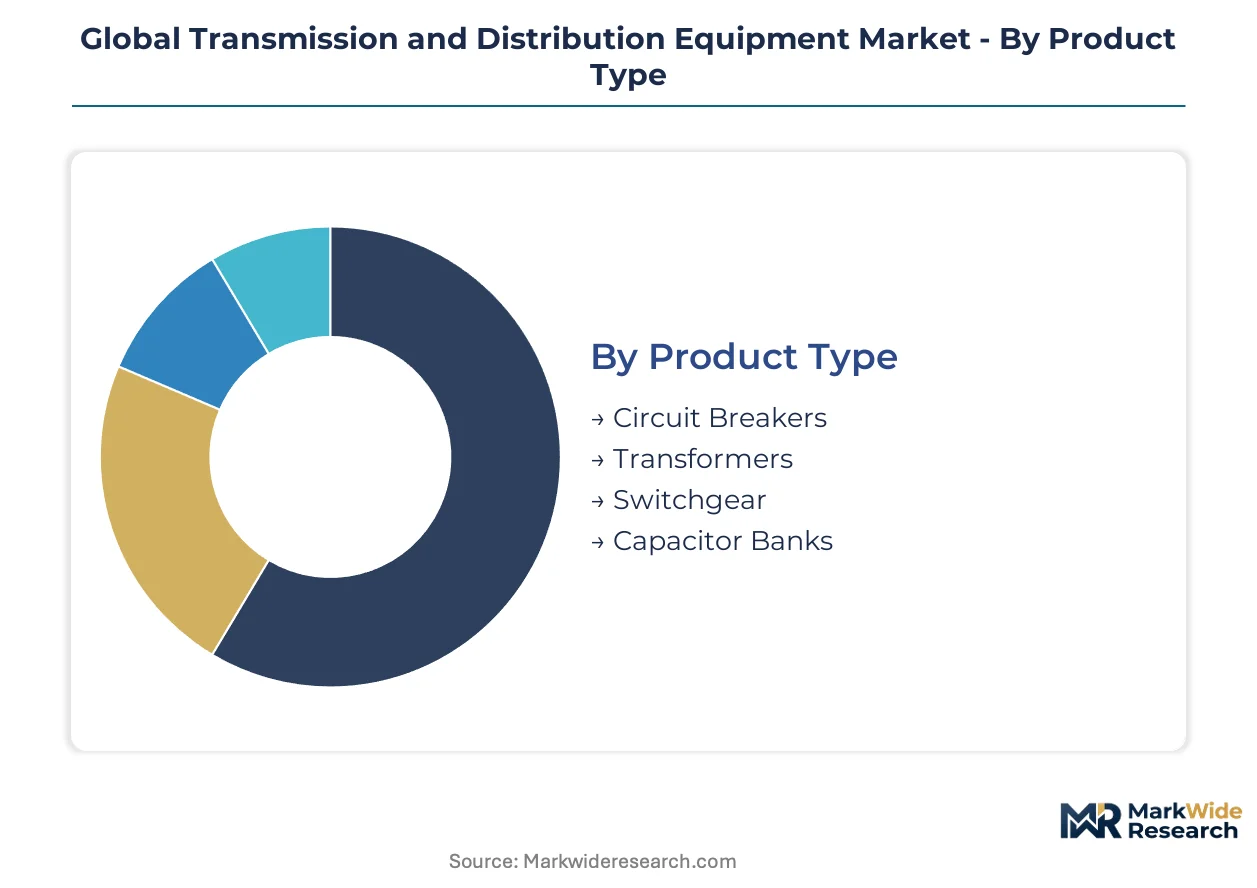
Equipment specification varies sharply across deployment contexts. Procurement cycles, technical standards, and margin structures diverge based on voltage class, environmental exposure, buyer sophistication, and grid architecture maturity.
Product Type:
Capital intensity and replacement cycles separate buyers in this category. Large utilities amortize bulk-power assets over decades while industrial users prioritize compact footprint and rapid commissioning.
- Transformers:Distribution-class units rated 10 kVA to 50 MVA dominate procurement volume for rural electrification and urban substation densification. India's Central Electricity Authority mandates efficiency tiers that elevate core steel specifications and procurement costs for state distribution companies.
- Switchgear:Gas-insulated and air-insulated assemblies protect against fault currents up to 63 kA. European utilities face the steepest compliance pressure as EU F-Gas Regulation phase-downs force vacuum interrupter adoption ahead of 2030 deadlines.
- Circuit Breakers:Electromechanical and solid-state interrupting devices clear line faults within 3-5 cycles. Mining operations in Chile and Western Australia specify high-altitude and corrosive-environment variants.
- Capacitor Banks:Reactive power compensation modules stabilize voltage on long rural feeders and renewable-rich grids. German transmission system operators deploy switched capacitor installations along North Sea wind export corridors.
Volume sits with Transformers; growth tilts toward Switchgear as SF6 regulations accelerate technology transition.
Installation Type:
Site constraints and land scarcity determine capital allocation priorities. Dense urban centers pay premium economics for space-efficient configurations versus rural deployments optimizing for access and ventilation.
- Outdoor:Open-air substations with live-tank circuit breakers and oil-immersed transformers dominate transmission-level installations. Brazilian utilities favor outdoor compounds for Amazon basin hydroelectric export lines.
- Indoor:Metal-enclosed switchgear and dry-type transformers occupy climate-controlled buildings. Singapore's urban substation densification program mandates indoor GIS installations to preserve land value in central business districts.
- Underground:Subsurface vaults and direct-buried cable systems eliminate visual impact. Amsterdam and Copenhagen district heating electrification projects specify underground 150 kV substations beneath commercial developments.
- Overhead:Lattice towers and conductor strings traverse rural and mountainous terrain. India's Green Energy Corridors deploy overhead 765 kV lines for Rajasthan solar park evacuation.
Outdoor commands installed base; underground climbs fastest as urban land constraints intensify.
End User:
Risk tolerance and technical staffing depth distinguish procurement behavior. Vertically integrated utilities self-specify versus facility managers outsourcing engineering to EPC contractors.
- Utilities:Transmission and distribution system operators specify IEC and IEEE standards for interoperability. Germany's four TSOs coordinate procurement for synchronous zone stability and offshore wind integration.
- Industrial Facilities:Steel, cement, and chemical plants require reliable medium-voltage distribution for continuous processes. Saudi Aramco's industrial city developments specify 34.5 kV gas-insulated switchgear for refinery complexes.
- Data Centers:Hyperscale cloud operators demand 99.999% uptime with redundant substation feeds. Northern Virginia's Ashburn-Dulles corridor hosts the densest concentration of 115 kV customer-owned substations globally.
- Commercial Buildings:High-rise developments and hospital campuses prioritize compact dry-type transformers and arc-resistant switchgear. Dubai's mega-project pipeline specifies K-rated units for harmonic-rich LED and VFD loads.
Utilities anchor procurement volume; data centers expand most quickly on cloud infrastructure buildouts.
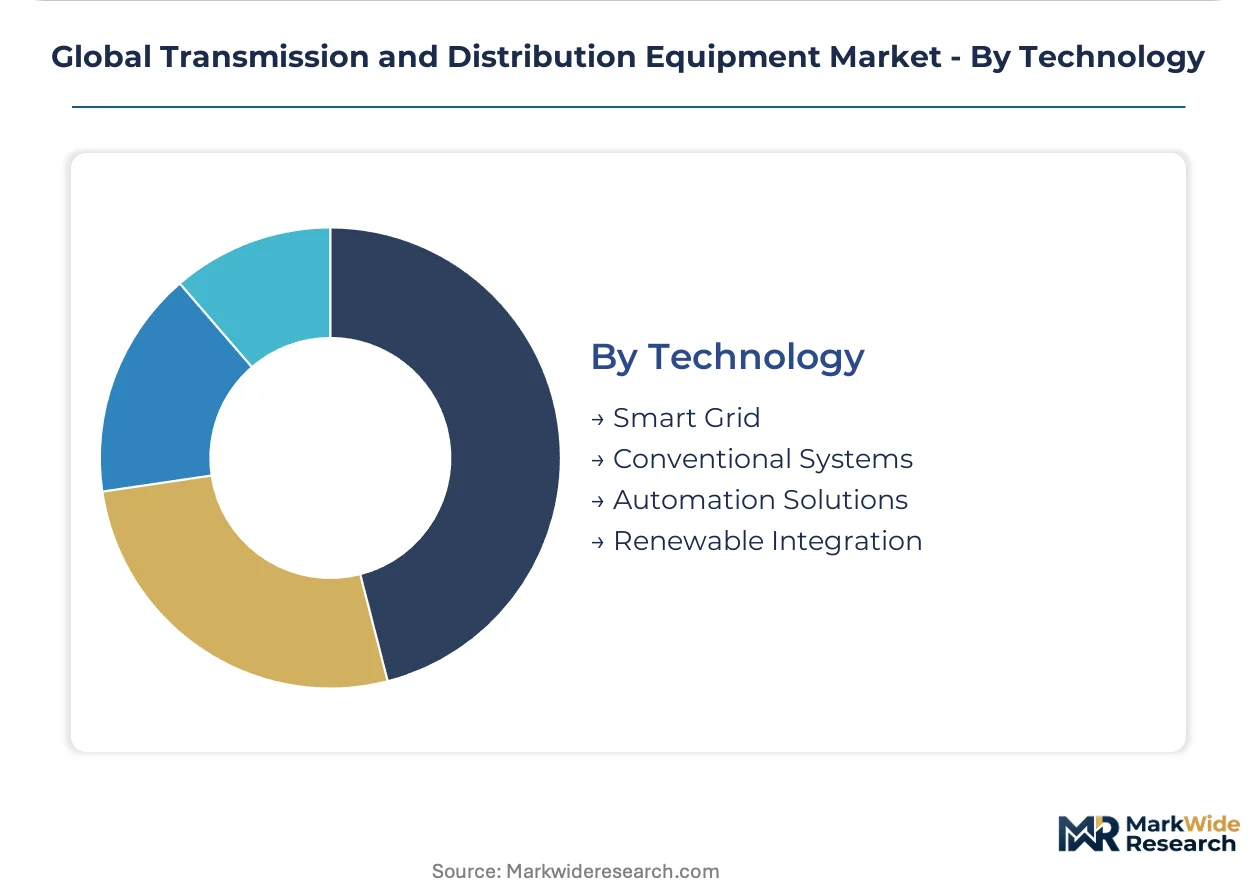
Technology:
Digital maturity separates investment horizons. Conservative operators extend conventional asset life while early adopters retrofit sensor layers and edge computing.
- Smart Grid:AMI, fault location isolation and restoration, and demand-response platforms overlay communication networks on legacy infrastructure. Italy's Enel pioneered continental-scale smart meter deployment exceeding 40 million units.
- Conventional Systems:Electromechanical protection and manually operated disconnectors persist in budget-constrained markets. Sub-Saharan African utilities prioritize cost-minimization over automation in rural electrification phases.
- Automation Solutions:IEC 61850 digital substations replace copper wiring with fiber-optic process buses. ABB and Siemens compete for turnkey digital substation contracts in Australia's National Electricity Market.
- Renewable Integration:Grid-forming inverters, STATCOMs, and synchronous condensers stabilize variable generation. Spain's Red Eléctrica procures advanced inverter controls for Canary Islands wind-diesel hybrid systems.
Conventional Systems retain installed base dominance; smart grid gains share fastest on regulatory mandates for visibility and control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grain-oriented electrical steel from Nippon Steel's Japanese foundries and Chinese state-owned mills anchors Asia-Pacific supply chains for transformer laminations, while German rolling mills and Indian cold-rolling facilities compete for European and Middle Eastern procurement.
United States
FERC Order 2222 and state-level renewable portfolio standards are forcing grid operators to upgrade interconnection capacity for utility-scale solar and offshore wind. The Infrastructure Investment and Jobs Act directs $65 billion toward grid hardening and smart meter deployment. ERCOT's Texas grid and CAISO's California network face the steepest transformer procurement pressure from data center cluster expansion in Dallas-Fort Worth and Silicon Valley.
Germany
The four transmission system operators—50Hertz, Amprion, TenneT, and TransnetBW—coordinate procurement for North Sea offshore wind export corridors requiring HVDC converter stations. EU Green Deal national binding targets mandate 80% renewable electricity by 2030, compressing equipment replacement cycles. Siemens Energy anchors high-voltage substation manufacturing in Berlin and Nuremberg while competing for Baltic Sea interconnector contracts.
India
CEA technical standards and the Revamped Distribution Sector Scheme are driving massive distribution transformer procurement for rural electrification completion. State distribution companies in Maharashtra, Gujarat, and Tamil Nadu face binding loss-reduction targets that accelerate smart meter and compact switchgear deployment. Green Energy Corridors in Rajasthan and Karnataka require 765 kV overhead lines for solar park evacuation.
China
Dual carbon goals and 14th Five-Year Plan grid investment targets are expanding ultra-high voltage transmission networks to connect western renewable bases with eastern load centers. State Grid Corporation and China Southern Power Grid dominate procurement for 1,100 kV AC and 800 kV DC projects. Transformer core steel concentration in Baosteel and Wuhan facilities exposes global buyers to export quota volatility.
Brazil
ANEEL's grid modernization mandates and Amazon basin hydroelectric integration are driving outdoor substation construction for Belo Monte and Madeira river transmission corridors. Mining operations in Minas Gerais and Pará specify corrosion-resistant switchgear for remote maintenance constraints. Performance-based service contracts are displacing traditional equipment procurement in the industrial sector.
Global Transmission and Distribution Equipment Market Competitive Landscape
Global majors compete with regional champions across technology licensing and local manufacturing partnerships. The vendor base clusters around three strategic tiers: integrated electrical conglomerates with captive component supply, specialized switchgear and cable manufacturers with deep vertical expertise, and emerging Asian fabricators competing on cost-adjusted delivery schedules. Consolidation pressure intensifies as SF6 phase-down regulations and digital substation standards elevate R&D thresholds. Dominant competitive moves include captive manufacturing expansion in Southeast Asia and strategic partnerships for solid-state transformer commercialization.
Among European-based integrated suppliers, ABB Ltd. and Siemens Energy AG exemplify the full-spectrum archetype spanning high-voltage substations through grid-edge automation. Schneider Electric SE represents the energy management specialization tier with deep building-to-grid integration capabilities. These three anchors demonstrate how geographic manufacturing distribution and technology portfolio breadth determine competitive positioning across procurement cycles driven by regulatory compliance and renewable integration mandates.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens Energy AG |
| Schneider Electric SE |
| Mitsubishi Electric Corp. |
| Eaton Corp. plc |
| Hitachi Energy |
| GE Vernova |
| Toshiba Corporation |
| Prysmian Group |
| Others |
Pricing and Supply Chain Analysis
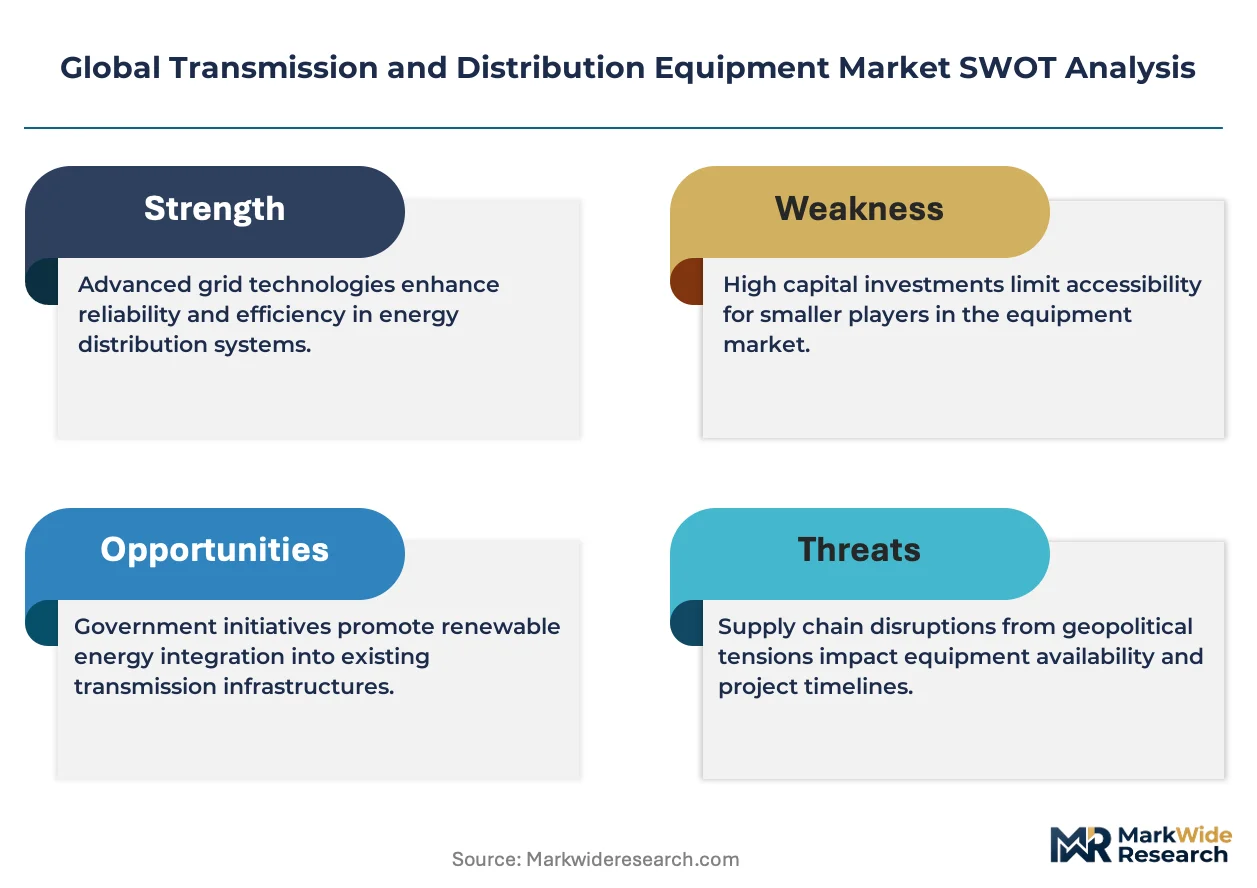
EU F-Gas Regulation phase-down mandates for SF6-free switchgear are forcing procurement departments to absorb premium pricing for vacuum interrupter technology while suppliers scramble to qualify alternative insulation systems, compressing margins across medium-voltage equipment tiers.
Pricing Analysis
Warranty and commissioning service bundling separates premium transformer OEMs from unbundled commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects IEC 61850 certification status and grain-oriented electrical steel grade. Pricing pressure stems from copper and aluminum LME volatility eroding fixed-price contract profitability. State distribution companies in India exhibit highest price sensitivity, while German TSOs prioritize guaranteed delivery schedules over unit cost.
Supply Chain Analysis
IEC 60076-1 and IEEE C57.12.00 certification gates limit qualified suppliers for utility-scale transformer cores. Manufacturing concentrates in China, Japan, and Germany for grain-oriented electrical steel laminations. Production draws from captive foundries in India and Southeast Asia for switchgear assemblies. Single-source vulnerability in Japanese cold-rolling mills exposes global procurement to export quota disruptions. Distribution runs through EPC contractors and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grain-oriented electrical steel capacity constraints in Japanese and Chinese mills prop equipment pricing, insulating incumbent margins despite raw material volatility.
For Market Incumbents: Deepen backward integration into transformer core steel through joint ventures with Indian cold-rolling facilities. Expand captive manufacturing in Southeast Asia to circumvent Chinese export quota volatility. Prioritize IEC 61850 digital substation certification investments to defend against Asian fabricators competing on cost-adjusted delivery. For New Entrants and Emerging Players: Digital channel partnerships with industrial procurement platforms offer route-to-market for refurbished transformer secondary markets. Target Brazilian mining operations and Saudi Aramco industrial complexes with performance-based service contracts rather than capital sales. White space exists in solid-state transformer pilot deployments for hyperscale data centers. For Investors and Strategic Acquirers: The window for entry favors regional switchgear specialists with vacuum interrupter R&D capabilities ahead of EU F-Gas deadlines. Long-term viability hinges on exposure to offshore wind HVDC converter station procurement cycles. Watch German TSO coordination announcements for North Sea corridor awards as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Switchgear Transition | Vacuum interrupter R&D investments position suppliers for EU F-Gas Regulation compliance deadlines. |
| Digital Substation Certification | IEC 61850 qualification gates separate premium automation providers from commodity electromechanical suppliers. |
| Core Steel Joint Ventures | Indian cold-rolling partnerships reduce exposure to Chinese and Japanese export quota volatility. |
| Performance-Based Service Contracts | Uptime guarantees transfer operational risk to OEMs while capturing recurring revenue from Brazilian mining clients. |
| Offshore Wind HVDC Buildout | German TSO procurement for North Sea corridors generates demand for converter stations and subsea cable systems. |
Research Methodology
Document review covered FERC orders, EU Green Deal framework texts, and CEA technical standards, complemented by interviews with utility planning officers, EPC contractors, transformer OEM procurement teams, and grid operators. Secondary sources included EIA capacity data, IEA grid investment reports, and customs records for grain-oriented electrical steel trade flows. Bottom-up equipment procurement tracking and top-down regulatory mandate analysis were triangulated for cross-validation.
Historical deployment patterns were cross-referenced against panel input from transmission system operators across the analysis window. Segmentation modeled voltage class, installation environment, end-user sophistication, and technology maturity dimensions. CAGRs derived from equipment replacement cycle compression and renewable integration mandate intensity. Forecast inputs incorporated transformer loss standard tier adoption curves and SF6 phase-down compliance timelines.
The model holds under stable regulatory enforcement trajectories; deviation in EU F-Gas Regulation implementation pace or Chinese export quota policy would shift equipment availability and pricing assumptions. A model refresh is warranted upon material change in German TSO offshore wind corridor procurement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
DC Distribution Network Market
Transmission and Distribution
North America DC Distribution Network Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Fixed Series Compensation Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Modular Sub-Station Market