
 Middle East Gas Pipeline Infrastructure Market | 2026-2036
Middle East Gas Pipeline Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Gas Pipeline Infrastructure Market Insights
The EU Green Deal's extraterritorial methane emission benchmarks is hardening procurement standards for Gulf gas exporters. Saudi Aramco leverages integrated upstream-to-midstream control across the Ghawar and Hasbah fields to sustain cost advantages in high-pressure trunkline construction. QatarEnergy anchors its North Field expansion with subsea and onshore pipeline corridors designed for ultra-large diameter hydrogen-ready transport. ADNOC Gas Transmission dominates the UAE's onshore transmission grid with automated leak detection systems that comply with tightening European import standards.
Middle East gas pipeline infrastructure encompasses the steel, composite, and ductile iron conduit systems, typically rated for pressures between 40 and 100 bar, that transport natural gas from wellhead gathering nodes through processing facilities to end-use terminals. Steel transmission pipelines with large and extra-large diameters occupy the dominant share of capital deployment given their role in high-volume, long-haul corridors linking Qatar's North Field to liquefaction trains and Saudi Arabia's Eastern Province to industrial cities. Distribution networks serving power generation applications represent the fastest-expanding segment as Saudi Arabia, the UAE, and Kuwait convert baseload power plants from liquid fuels to natural gas firing.
Saudi Arabia's national regulator, the Saudi Standards, Metrology and Quality Organization, mandates API 5L and ASME B31.8 compliance for all new steel pipeline construction, while the UAE's civil defense authorities enforce NFPA 59A standards for liquefied natural gas adjacent infrastructure. The International Organization for Standardization's ISO 13628 series for subsea production systems shapes procurement specifications for Qatar's offshore gathering lines. Stakeholders must monitor how evolving EU methane performance standards will cascade into contractual clauses for Middle East gas exports destined for European terminals.
Market Dynamics
EU Green Deal methane benchmarks are cascading into procurement clauses for Gulf gas exports, forcing pipeline operators to retrofit leak detection and compress construction timelines for hydrogen-ready corridors.
Growth Catalysts
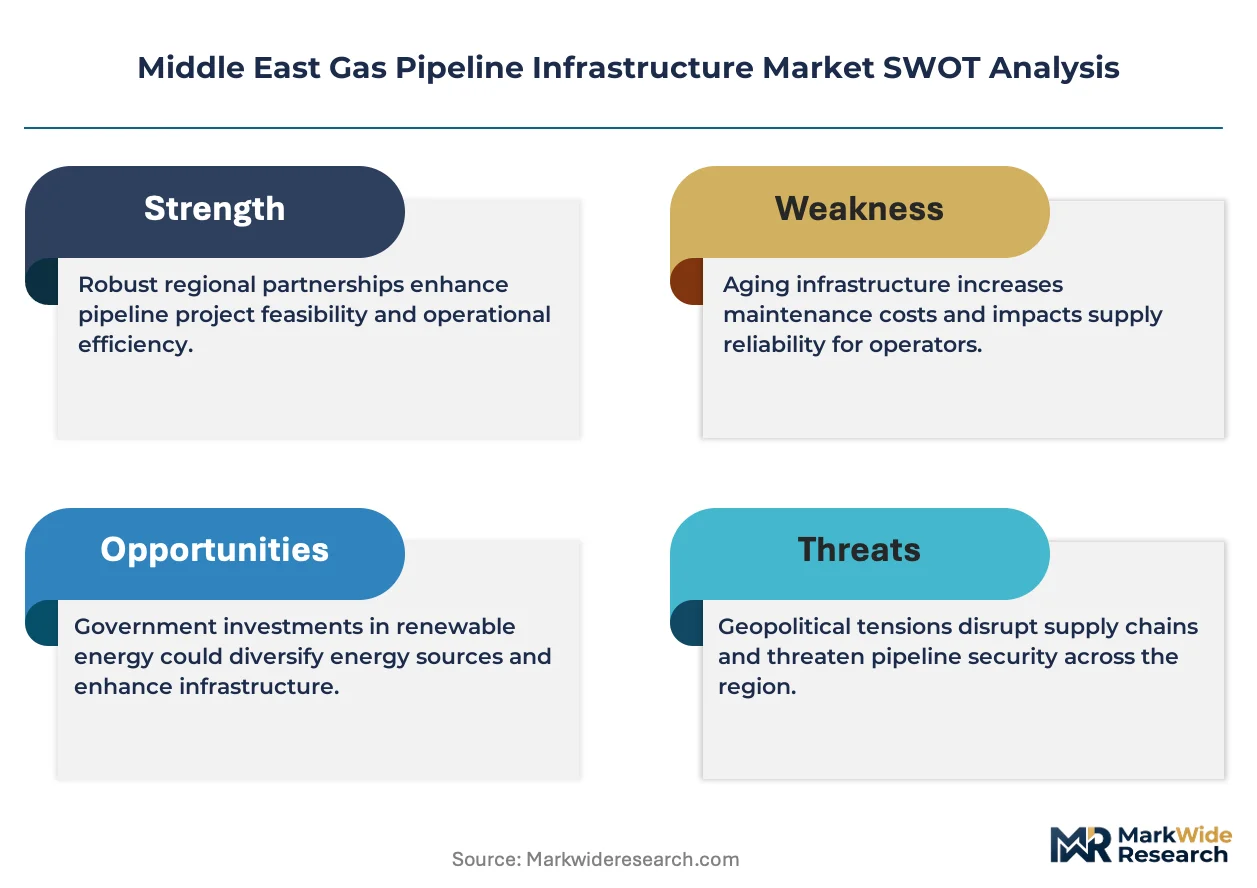
- Power generation fuel switching:Saudi Arabia, Kuwait, and the UAE are converting baseload plants from liquid fuels to natural gas firing, creating concentrated demand for distribution network expansion.
- API 5L and ASME B31.8 mandates:Saudi Standards, Metrology and Quality Organization compliance requirements are standardizing steel pipeline quality, reducing procurement friction for cross-border trunkline projects.
- North Field expansion:QatarEnergy's ultra-large diameter corridor construction is establishing engineering templates for hydrogen-ready transport across Gulf Cooperation Council states.
Market Restraints
- Alloy steel input volatility:High-grade line pipe steel prices fluctuate with nickel and molybdenum markets, compressing margins for fixed-price EPC contracts.
- European import standard divergence:EU methane performance benchmarks are tightening faster than Gulf certification timelines, creating compliance gaps for export-bound infrastructure.
- Subsea installation bottlenecks:Specialized vessel availability for Qatar's offshore gathering lines concentrates project risk with a limited contractor pool.
Strategic Opportunities
- Hydrogen blending retrofit:Existing high-pressure trunklines in Saudi Arabia's Eastern Province can accommodate hydrogen admixture with material upgrades, extending asset lifecycles.
- Automated leak detection:ADNOC Gas Transmission's sensor network model offers replication potential for Kuwait and Bahrain distribution grids seeking European market access.
- Industrial city anchor demand:Jubail and Yanbu petrochemical complexes are expanding offtake capacity, creating dedicated pipeline corridors with predictable volume commitments.
Industry Challenges
- Welding technician scarcity:API 1104-certified pipeline welders are concentrated with established contractors, creating recruitment competition for new trunkline projects.
- Hydrogen embrittlement assessment:Existing ASME B31.8 compliance frameworks lack validated protocols for high-pressure hydrogen transport, delaying material specification finalization.
- Cross-border coordination:GCC states maintain divergent civil defense approval timelines for border-crossing pipelines, extending project development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Gas Pipeline Infrastructure Market |
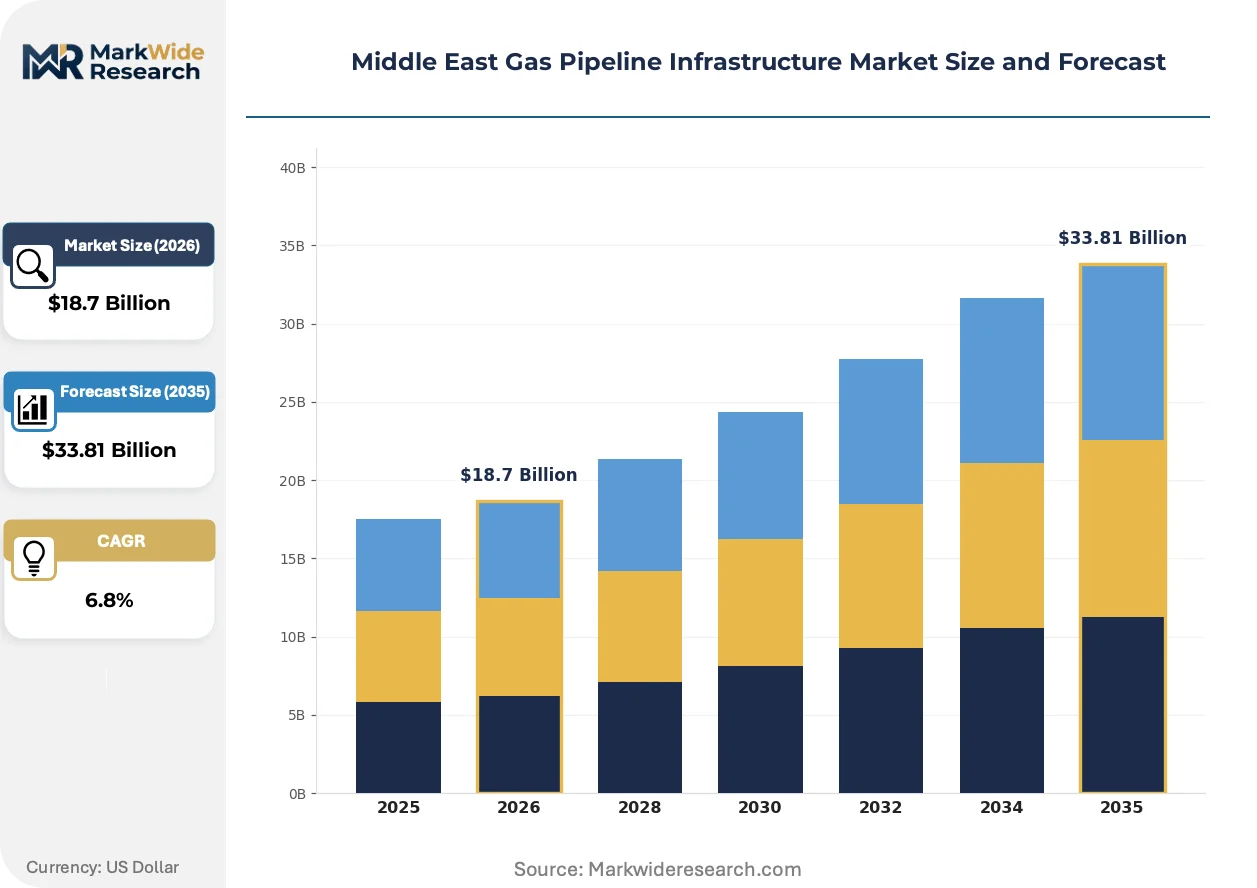
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pipeline Type: Transmission, Distribution, Gathering, Export Material: Steel, Plastic, Composite, Ductile Iron Diameter: Small, Medium, Large, Extra Large Application: Industrial, Commercial, Residential, Power Generation |
| Companies Covered | Saudi Aramco, QatarEnergy, National Iranian Oil Company, ADNOC Gas Transmission, Shell plc, ExxonMobil Corporation, TotalEnergies SE, Chevron Corporation, Enbridge Inc., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Gas Pipeline Infrastructure Market Trends and Innovations
Pipeline construction is pivoting toward hydrogen compatibility and real-time monitoring, with material science and digital instrumentation converging to meet European export standards.
Composite reinforcement systems are modularizing steel pipeline construction for high-pressure hydrogen service. Saudi Aramco's trunkline projects are piloting fiber-reinforced polymer wraps at flange joints and stress concentration points. This modularizing approach compresses field welding requirements while enabling future hydrogen blend upgrades without full pipeline replacement.
EU Green Deal methane emission benchmarks are hardening contractual performance clauses for Gulf exporters. Pipeline operators must now demonstrate continuous leak monitoring and repair response protocols to maintain offtake agreements with European utilities. QatarEnergy's North Field expansion is embedding these requirements into subsea gathering line specifications, with ISO 13628 procurement standards incorporating methane intensity thresholds.
Power utilities are consolidating procurement through long-term offtake agreements rather than spot market purchases. Saudi Electricity Company and Emirates Water and Electricity Company are signing fifteen to twenty-year gas delivery contracts, shifting volume risk onto pipeline operators and favoring integrated upstream-to-midstream players. This concentration is most visible in Saudi Arabia's Eastern Province, where industrial city demand anchors trunkline economics.
Middle East Gas Pipeline Infrastructure Market Segmentation
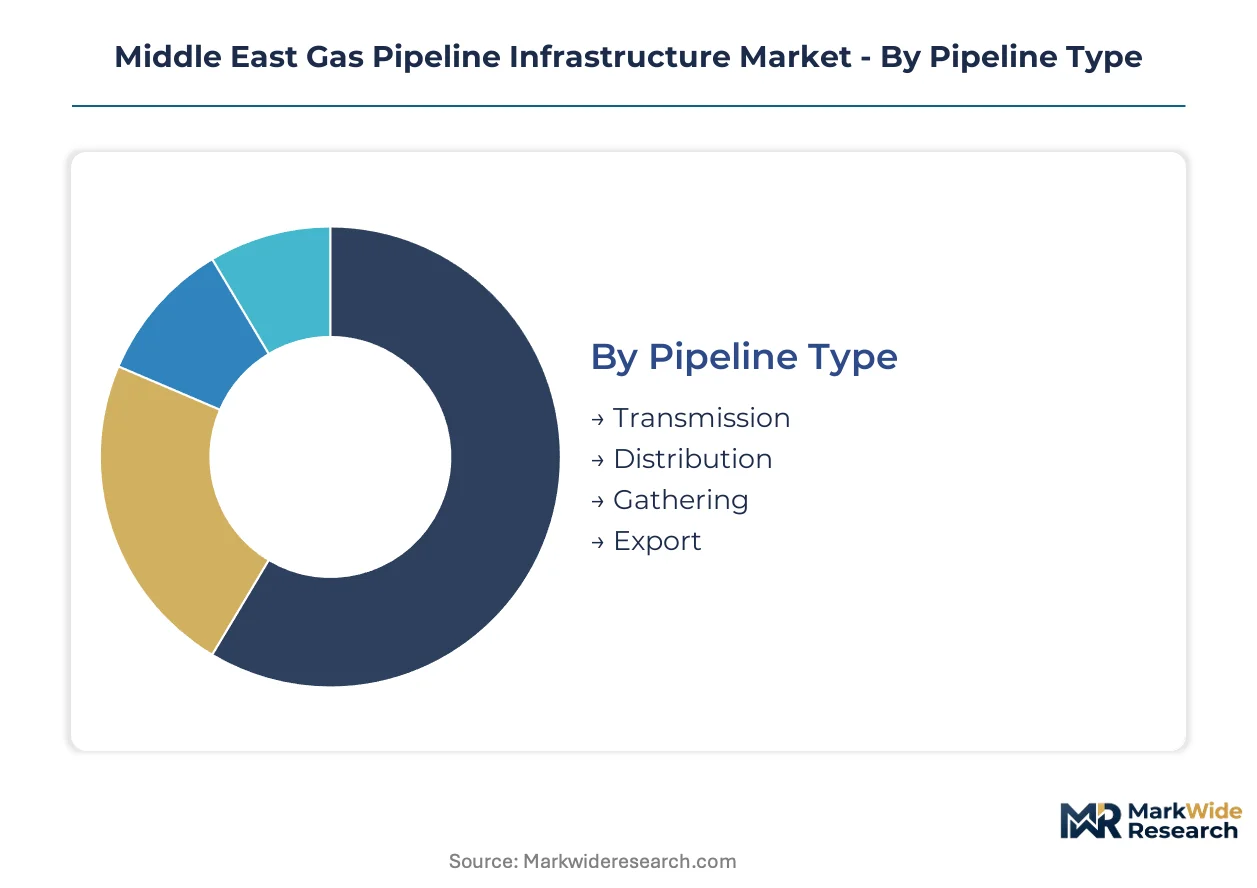
Pipeline infrastructure investment across the Gulf Cooperation Council states follows distinct technical specifications that determine material selection, pressure ratings, and construction methodologies. Understanding how these segments intersect reveals where capital deployment concentrates and which engineering standards dominate procurement decisions.
Pipeline Type:
Pressure ratings and flow volumes dictate the structural hierarchy of conduit systems, with each category serving a distinct node in the hydrocarbon value chain.
- Transmission:High-pressure steel corridors rated for 70-100 bar transport processed gas from treatment facilities to industrial terminals and city gate stations. Saudi Aramco's Eastern Province trunklines anchor regional deployment, with Ghawar field connections sustaining the heaviest volume corridors.
- Distribution:Medium-pressure networks operating at 4-16 bar deliver gas to end-use facilities through progressively smaller diameter lines. Kuwait's Ministry of Electricity and Water is expanding distribution reach to power generation facilities as part of fuel switching programs.
- Gathering:Wellhead collection systems aggregate raw production for initial processing. QatarEnergy's North Field offshore lines follow ISO 13628 procurement specifications for subsea gathering infrastructure.
- Export:Dedicated corridors feed liquefaction trains and cross-border delivery points. ADNOC Gas Transmission operates the UAE's primary export linkages to Fujairah and other terminal facilities.
Mature deployment sits with Transmission. Newer deployment is concentrated in Distribution.
Material:
Corrosion resistance, pressure tolerance, and hydrogen compatibility drive material selection decisions across Gulf project portfolios.
- Steel:API 5L-certified line pipe dominates high-pressure service, with X70 and X80 grades specified for QatarEnergy's ultra-large diameter corridors. Saudi Standards, Metrology and Quality Organization mandates govern all new steel construction.
- Composite:Fiber-reinforced polymer systems are modularizing flange joints and stress concentration points for future hydrogen blend compatibility. Saudi Aramco pilots these wraps at retrofit-sensitive locations.
- Plastic:Polyethylene and PVC variants serve low-pressure distribution laterals where flexibility and corrosion immunity outweigh pressure requirements.
- Ductile Iron:Municipal distribution networks in older UAE and Bahrain installations employ cast iron successors for moderate-pressure urban service.
Steel commands established deployment. Composite systems are climbing the fastest as hydrogen-ready specifications harden.
Diameter:
Flow economics and construction logistics create tiered investment thresholds that separate trunkline projects from lateral extensions.
- Extra Large:Diameters exceeding 48 inches accommodate QatarEnergy's North Field expansion corridors, designed for hydrogen-ready transport with wall thicknesses exceeding 25 millimeters.
- Large:30-48 inch lines connect Saudi Arabia's Eastern Province processing facilities to Jubail and Yanbu industrial cities, anchoring predictable volume commitments.
- Medium:12-30 inch specifications serve inter-city transmission and major industrial offtake points across Kuwait and the UAE.
- Small:Lines under 12 inches complete the final distribution leg to commercial and residential meters.
Extra Large diameter deployment is accelerating fastest. Small diameter networks represent the most mature installed base.
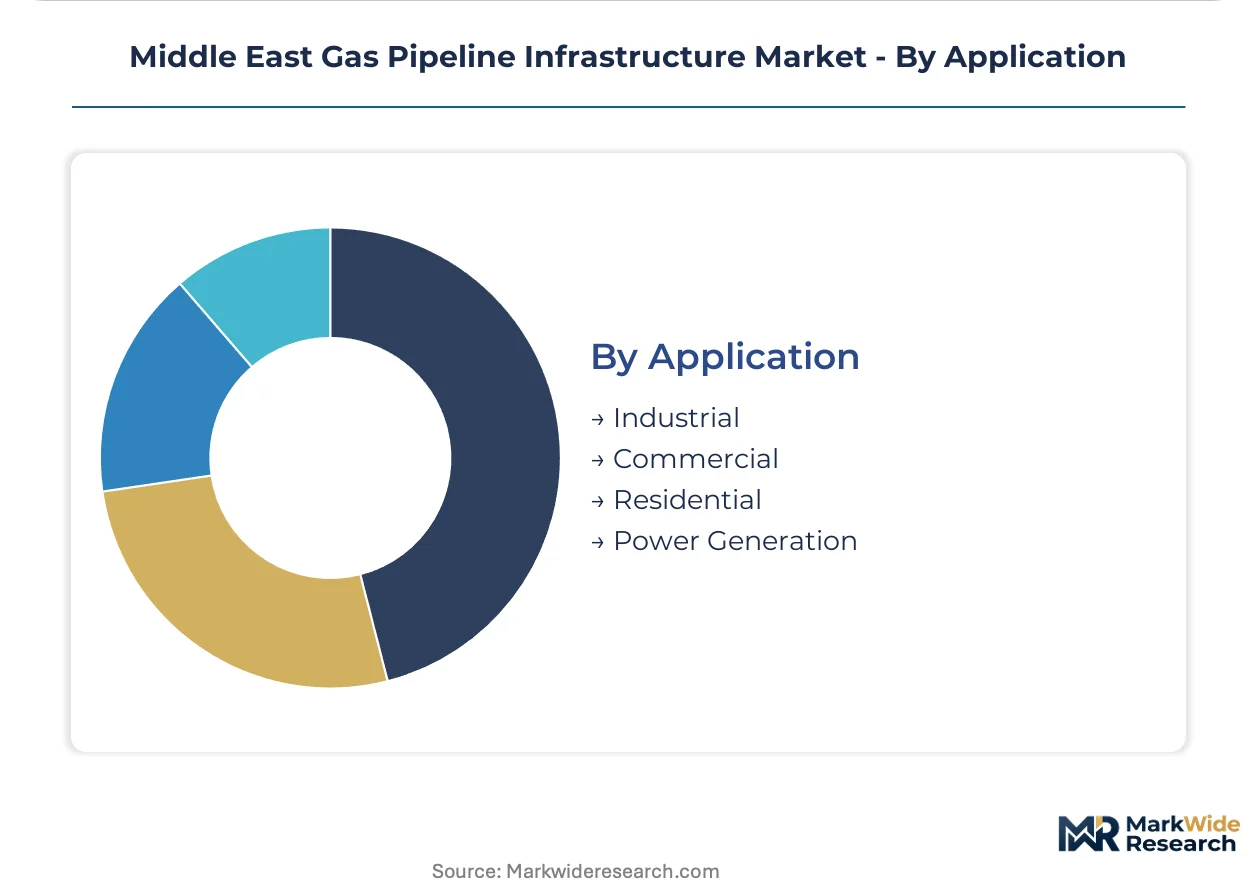
Application:
End-use demand profiles determine pressure requirements, reliability standards, and contractual structures for pipeline operators.
- Power Generation:Baseload gas-fired plants require uninterrupted delivery with strict pressure stability. Saudi Electricity Company and Emirates Water and Electricity Company are signing fifteen to twenty-year offtake agreements that shift volume risk onto midstream operators.
- Industrial:Petrochemical complexes at Jubail, Yanbu, and Ruwais anchor dedicated corridor economics with predictable demand baselines.
- Commercial:Hotels, hospitals, and retail facilities require moderate-pressure service with redundant supply paths.
- Residential:Metered household connections represent the lowest pressure tier, with distribution density determining project viability.
Industrial applications anchor mature infrastructure. Power generation is gaining share fastest as fuel switching accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East produces substantially more natural gas than it consumes, creating export-oriented infrastructure concentrated around supergiant fields while domestic distribution networks expand to displace oil-fired power generation.
Saudi Arabia
Saudi Electricity Company is converting baseload plants from crude oil direct burn to natural gas firing, driving distribution network expansion into the Central and Western regions. The Saudi Standards, Metrology and Quality Organization mandates API 5L and ASME B31.8 compliance for all new steel pipeline construction. Jubail and Yanbu industrial cities anchor dedicated trunkline corridors with predictable petrochemical offtake volumes.
Qatar
QatarEnergy's North Field expansion requires ultra-large diameter corridors designed for hydrogen-ready transport to future-proof export capacity. ISO 13628 procurement specifications govern subsea gathering line construction for offshore production systems. Ras Laffan Industrial City concentrates liquefaction train feedstock infrastructure with dedicated export pipeline networks.
United Arab Emirates
ADNOC Gas Transmission dominates onshore transmission with automated leak detection systems that comply with tightening European import standards. The UAE's civil defense authorities enforce NFPA 59A standards for liquefied natural gas adjacent infrastructure. Ruwais industrial complex and Fujairah export terminals anchor high-volume corridor economics.
Kuwait
Kuwait's Ministry of Electricity and Water is expanding distribution reach to power generation facilities as part of comprehensive fuel switching programs. The country's national oil company directs midstream investment priorities through integrated planning frameworks. Al-Zour refinery and associated petrochemical complexes are driving dedicated pipeline corridor development.
Iran
National Iranian Oil Company maintains extensive gathering and transmission networks connecting supergiant South Pars field production to domestic industrial demand centers. International sanctions constrain access to advanced leak detection and compression technologies required for European market compliance. Asaluyeh petrochemical special economic zone anchors the largest concentration of gas processing and derivative production infrastructure.
Middle East Gas Pipeline Infrastructure Market Competitive Landscape
The competitive structure tilts toward state-controlled national oil companies with integrated upstream-to-midstream control. Saudi Aramco and QatarEnergy leverage captive field access to sustain cost advantages in high-pressure trunkline construction. Two strategic archetypes dominate: integrated national champions with full value chain ownership, and international oil company joint venture partners providing technical expertise. Competitive moves concentrate on hydrogen-ready corridor pre-positioning and automated monitoring system deployment to satisfy European methane benchmarks.
Within the national champion tier, Saudi Aramco exemplifies integrated upstream-to-midstream control across the Ghawar and Hasbah fields. QatarEnergy occupies a parallel position anchoring North Field expansion with subsea and onshore corridor construction. ADNOC Gas Transmission represents the specialized transmission grid operator model with automated compliance infrastructure. International oil companies including Shell plc and TotalEnergies SE sit within joint venture and technical partnership roles rather than direct infrastructure ownership.
| Leading Market Players |
|---|
| Saudi Aramco |
| QatarEnergy |
| National Iranian Oil Company |
| ADNOC Gas Transmission |
| Shell plc |
| ExxonMobil Corporation |
| TotalEnergies SE |
| Chevron Corporation |
| Enbridge Inc. |
| Others |
Pricing and Supply Chain Analysis
State-controlled national oil companies concentrate procurement authority for high-pressure trunkline projects, anchoring contract-based long-term offtake agreements as the dominant pricing model across Gulf Cooperation Council states. Saudi Aramco and QatarEnergy leverage integrated upstream-to-midstream control to compress supplier margins through volume commitments spanning fifteen to twenty-year horizons.
Pricing Analysis
Margin tightening in fixed-price EPC contracts reflects alloy steel input volatility, particularly nickel and molybdenum price swings that compress contractor returns. Three-tier pricing structure across API 5L X80 premium grades, X70 standard specifications, and lower-grade economy alternatives segments procurement by pressure rating and hydrogen compatibility requirements. Cost-down pressure on distribution network operators accelerates because power utilities are consolidating procurement through consolidated offtake agreements rather than spot market purchases. Midstream operators serving Saudi Electricity Company and Emirates Water and Electricity Company exhibit lowest price sensitivity due to captive demand anchors, while specialized subsea installation contractors face highest price sensitivity given limited vessel availability.
Supply Chain Analysis
Regional distribution centers for high-grade line pipe steel concentrate in South Korea, Japan, and Germany, with mill-direct procurement dominating ultra-large diameter orders for QatarEnergy's North Field expansion. Raw material dependencies rest on nickel-molybdenum alloy feedstocks, API-certified steel plate, and specialized subsea coating systems. Single-source vulnerability concentrates with specialized offshore installation vessels for Qatar's ISO 13628-compliant gathering lines. Distribution runs through hub-and-spoke patterns anchored at Jebel Ali and Ras Laffan industrial zones, with just-in-time delivery to construction corridors across Saudi Arabia's Eastern Province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU Green Deal methane benchmarks force smaller operators into compliance-driven exits. National champions with integrated field-to-terminal control will absorb stranded midstream assets.
For Market Incumbents: Acquire automated leak detection technology platforms to satisfy tightening European import standards before contractual clauses harden. Saudi Aramco should extend fiber-reinforced polymer wrap pilot programs across Ghawar field connections, preempting hydrogen embrittlement risks that threaten ASME B31.8 compliance timelines. Defensive consolidation of API 1104-certified welding contractor pools will lock in scarce technical capacity ahead of QatarEnergy's North Field construction peak.
For New Entrants and Emerging Players: Technical partnership channels with European engineering firms offer the fastest credibility pathway for hydrogen-ready corridor specifications. White-space targets concentrate in Kuwait's distribution network expansion and Bahrain's automated monitoring retrofit programs, where state operator capacity constraints create procurement openings. Go-to-market positioning should emphasize ISO 13628 subsea expertise transferable from North Sea or West African project portfolios.
For Investors and Strategic Acquirers: The window for entry favors midstream technology specialists with hydrogen compatibility intellectual property. Long-term viability hinges on five-to-ten-year positioning for hydrogen blend transport infrastructure rather than pure methane economics. Acquisition targets should demonstrate validated protocols for high-pressure hydrogen service under evolving ASME frameworks. The signal to watch is EU methane performance benchmark enforcement velocity cascading into Gulf export contract renegotiation cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Corridor Pre-Positioning | QatarEnergy's ultra-large diameter templates establish engineering standards across GCC states for future blend transport. |
| Automated Leak Detection Deployment | ADNOC Gas Transmission's sensor network model enables European market access compliance for export-bound infrastructure. |
| API 1104-Certified Welder Pool Consolidation | Scarcity of qualified technicians concentrates project risk with established contractors holding captive capacity. |
| Composite Reinforcement System Piloting | Saudi Aramco's fiber-reinforced polymer wraps modularize field construction while enabling future hydrogen upgrades. |
| Long-Term Offtake Agreement Structuring | Fifteen to twenty-year contracts with Saudi Electricity Company shift volume risk onto integrated upstream-to-midstream operators. |
Research Methodology
Multi-period observation of pipeline construction contract awards, steel import volumes, and regulatory filing trajectories anchored the trend analysis, supplemented by interviews with EPC contract managers, utility procurement officers at Saudi Electricity Company and Emirates Water and Electricity Company, pipeline welding contractor supervisors, and national oil company planning executives. Secondary validation drew from customs and trade data for alloy steel imports, API certification registries, SEC filings for exposed engineering firms, and FERC documentation for Gulf export terminal connections. Bottom-up project pipeline enumeration triangulated against top-down infrastructure investment forecasts from energy ministry disclosures.
Input-output matrices modeled capacity additions across transmission, distribution, gathering, and export pipeline types, intersecting with material specifications, diameter classes, and application segments. CAGRs were derived from regression analysis of historical construction spend against announced project timelines, with segmentation by pressure rating, hydrogen compatibility tier, and regional regulatory cluster. Forecast inputs incorporated alloy steel price volatility indices, specialized vessel availability schedules, and EU methane benchmark enforcement probability weights.
Caveats apply where international sanctions disruption, subsea installation vessel scheduling conflicts, or accelerated EU methane standard adoption could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Australia High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
India HVDC Transmission Systems Market
Transmission and Distribution
Transmission and Distribution Fault Detection Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Natural Gas Storage Technologies Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
South America City Gas Distribution Market
Transmission and Distribution
Surge Tank Market
Transmission and Distribution
High Voltage Direct Current (HVDC) Transmission System Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Electricity Transmission Infrastructure Market