
 Transmission Line Market | 2026-2036
Transmission Line Market Size, Share, and Industry Trends Forecast 2026-2036
Transmission Line Market Intelligence
A shift from single-source to multi-source conductor procurement is hardening among European and Asian grid operators. Prysmian Group leverages its submarine cable expertise to anchor Mediterranean offshore wind interconnection projects. KEC International competes aggressively on EPC bundling for India's Green Energy Corridors. Sumitomo Electric Industries specializes in superconducting and high-temperature low-sag conductors for constrained urban routes.
Transmission lines are engineered conductor systems—typically aluminum alloy or composite-cored—designed to transport electrical power across distances from hundreds of meters to thousands of kilometers, with voltage ratings spanning 66 kV to 800 kV and beyond. AC Transmission Lines occupy the mature volume base, while DC Transmission Lines represent the fastest-growing margin pool as subsea and long-distance land corridors multiply. Underground installations command premium pricing in dense European and Japanese corridors where right-of-way constraints eliminate overhead options.
Grid operators in Germany navigate KBA-adjacent federal network agency permitting for cross-state HVDC corridors, while China's SAMR enforces updated GB standards on conductor thermal ratings and mechanical loading. India's CEA mandates centralized scheduling and dispatch protocols that shape transmission asset planning timelines. Stakeholders must monitor how evolving national security reviews of critical grid infrastructure reshape supplier qualification and domestic content requirements.
Market Dynamics
Grid operators face mounting pressure to integrate variable renewable generation while China's MIIT conductor efficiency mandates force rapid cable technology turnover across procurement portfolios.
Growth Catalysts
- Renewable Interconnection Mandates:India's Green Energy Corridors program requires massive interstate transmission expansion to evacuate solar and wind power from resource-rich states to demand centers.
- Submarine HVDC Deployments:Offshore wind clusters in the North Sea and Mediterranean drive specialized subsea cable demand for cross-border power exchange.
- Composite Core Adoption:High-temperature low-sag conductors enable doubled power throughput on existing right-of-way corridors without structural tower replacement.
Market Restraints
- Aluminum Price Volatility:Primary aluminum smelter curtailments in Yunnan and Quebec inject raw material cost uncertainty into conductor manufacturing economics.
- Right-of-Way Acquisition:Agricultural land compensation disputes in India and Germany's KBA-adjacent federal permitting timelines extend project commissioning by 18-36 months.
- Technical Obsolescence Risk:AC overhead lines face displacement pressure from HVDC alternatives in corridors exceeding 600 kilometers, stranding incumbent asset bases.
Strategic Opportunities
- Urban Underground Conversion:Dense Japanese and European metropolitan corridors where overhead construction is prohibited command 3-4x pricing premiums for XLPE-insulated circuits.
- Superconducting Pilot Networks:Sumitomo Electric's magnesium diboride demonstrations in Seoul and Frankfurt validate zero-resistance urban distribution at commercial scale.
- EU Green Deal Alignment:REPowerEU financing windows prioritize cross-border interconnectors that reduce gas-dependent generation, reshaping project development pipelines.
Industry Challenges
- Specialized Installation Workforce:Tension stringing crews for 800 kV UHVDC corridors require certification regimes that fewer than twelve contractors globally maintain.
- Legacy SCADA Integration:Digital twin deployment for predictive line rating depends on retrofitting fiber optic temperature monitoring onto galvanized steel hardware from 1980s-era construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transmission Line Market |
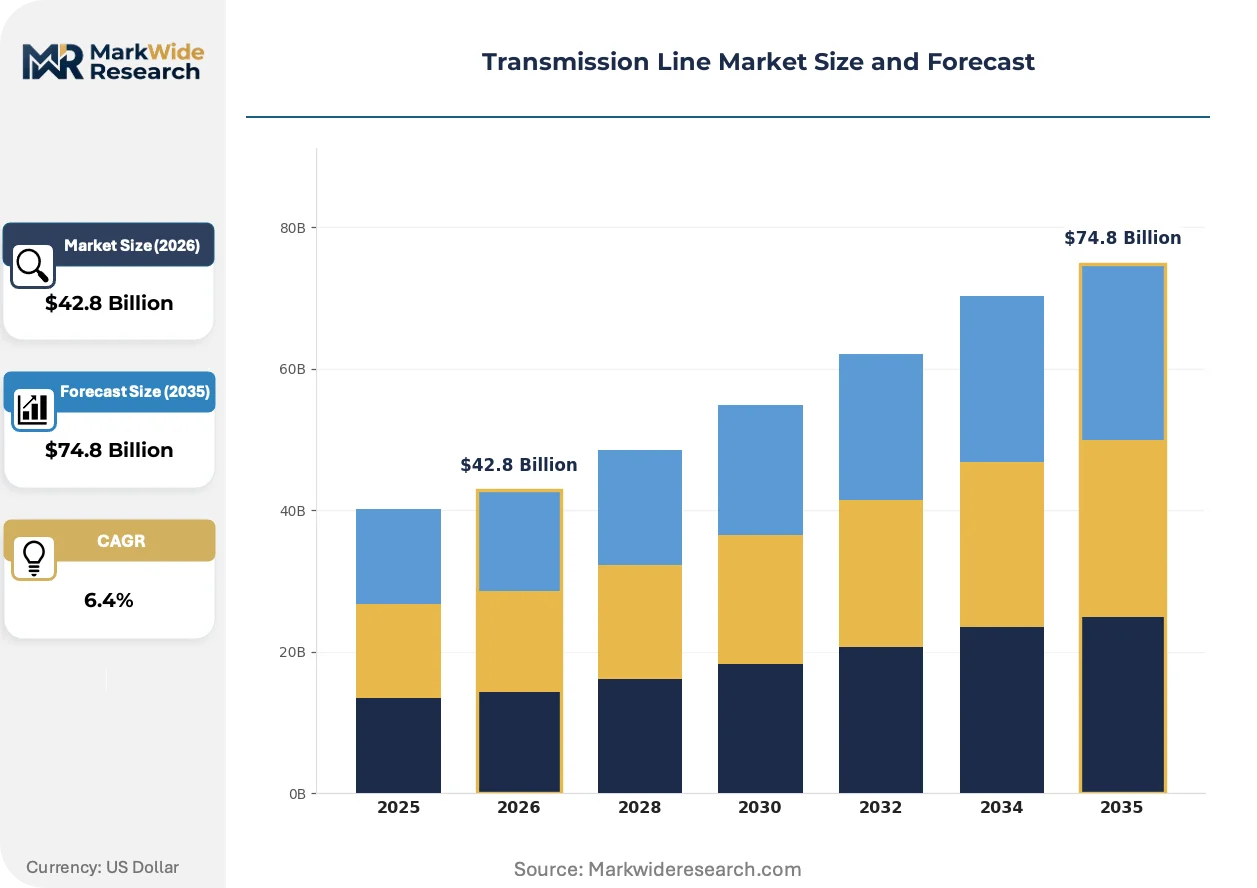
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Transmission Lines, DC Transmission Lines, High Voltage Transmission Lines, Submarine Cables Installation Type: Overhead, Underground, Hybrid, Floating End User: Utilities, Industrial, Commercial, Renewable Energy Technology: HVDC, FACTS, Transmission Towers, Cable Systems |
| Companies Covered | Prysmian Group, LAMIFIL, ZTT International, KEC International, Bekaert, Sumitomo Electric Industries, CTC Global, Skipper Limited, Nexans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transmission Line Market Strategic Shifts & Innovations
Digitalization of grid infrastructure is compressing maintenance cycles and enabling dynamic thermal rating systems that extract latent capacity from existing conductors without physical upgrade.
Dynamic line rating systems leveraging real-time weather telemetry and conductor sag monitoring are automating transmission asset utilization decisions previously based on static seasonal assumptions. European TSOs including TenneT and RTE deploy these platforms to defer reconductoring investments. The technology is automating clearance between physical thermal limits and conservative planning margins that historically stranded 15-30 percent of circuit capacity.
China's SAMR enforcement of updated GB/T conductor standards tightens thermal cycling test protocols and mechanical loading specifications for composite core qualification. Domestic manufacturers must retest existing product lines against accelerated aging criteria. High-voltage corridors in Sichuan and Gansu provinces face procurement delays as suppliers complete recertification.
Multi-year framework agreements are displacing project-specific tendering as state transmission utilities in India consolidate conductor procurement under central agency pooling mechanisms. Developers of interstate Green Energy Corridors negotiate aggregate volumes spanning 24-36 month delivery windows. This concentration is visible in Maharashtra and Gujarat, where MSETCL and GETCO have shifted from 50+ annual tenders to single-source master contracts with tier-one cable producers.
Transmission Line Market Segmentation
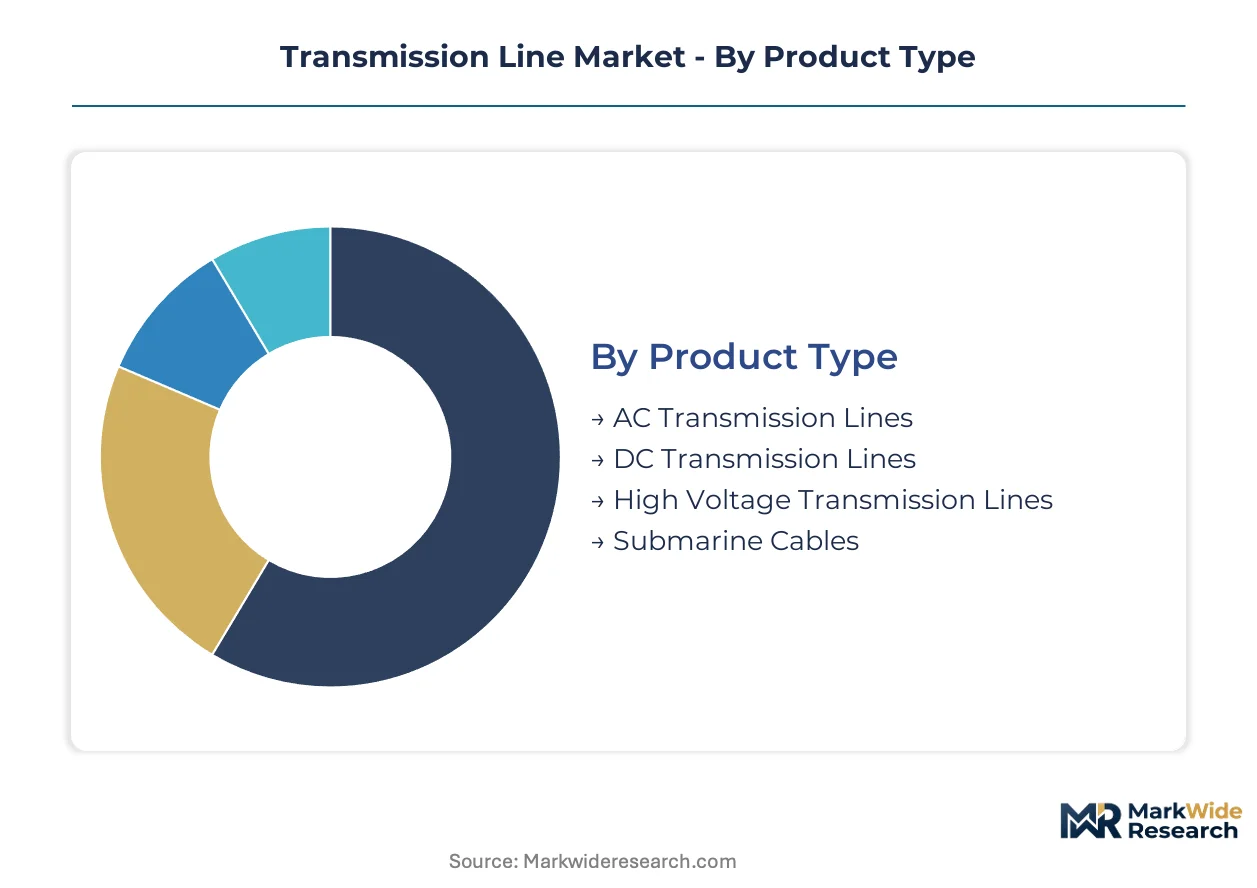
Transmission line procurement decisions hinge on voltage requirements, terrain constraints, and regulatory environments. Each segmentation dimension carries distinct technical specifications and supplier qualification thresholds that reshape competitive positioning.
Product Type:
Standardization dominates bulk AC procurement while DC corridors demand bespoke engineering for specific distance and seabed conditions.
- AC Transmission Lines:Aluminum conductor steel-reinforced designs remain the volume backbone, with composite core variants gaining traction under China's MIIT efficiency mandates. India's state transmission utilities execute centralized procurement for interstate corridors through MSETCL and GETCO master contracts.
- DC Transmission Lines:Voltage source converter technology enables asynchronous grid interconnection across Germany's cross-state corridors and Southeast Asian maritime links. Submarine HVDC deployments for North Sea offshore clusters command specialized manufacturing capabilities held by fewer than six suppliers globally.
- High Voltage Transmission Lines:400 kV and above ratings require tension stringing crews with certified 800 kV UHVDC experience.
- Submarine Cables:XLPE-insulated circuits for Mediterranean offshore wind command 3-4x overhead pricing premiums.
Most installed capacity flows through AC Transmission Lines. Expansion is steepest in DC Transmission Lines.
Installation Type:
Right-of-way economics separate mature overhead markets from premium underground corridors where land scarcity eliminates conventional construction.
- Overhead:Lattice steel towers and monopoles cover 90 percent of existing route-kilometers, with reconductoring projects doubling throughput on existing structures using high-temperature low-sag conductors. Agricultural land compensation disputes in India extend commissioning timelines by 18-36 months.
- Underground:Dense Japanese and European metropolitan corridors prohibit overhead construction, creating captive demand for XLPE-insulated circuits at substantial pricing premiums. Frankfurt and Seoul pilot superconducting magnesium diboride networks validating zero-resistance distribution.
- Hybrid:Mixed overhead-underground routing navigates urban periphery constraints.
- Floating:Offshore wind substation connections employ dynamic cables for water depths exceeding 60 meters.
Overhead retains dominant volume share. Underground claims the steepest margin expansion trajectory.
End User:
Procurement scale concentrates with state-backed transmission utilities while renewable developers drive technology turnover through Green Energy Corridor mandates.
- Utilities:India's CEA-mandated centralized scheduling protocols shape asset planning timelines for state transmission utilities executing interstate corridor projects. Multi-year framework agreements now displace project-specific tendering under central agency pooling mechanisms.
- Renewable Energy:Solar and wind developers in Rajasthan and Gujarat require evacuation infrastructure to connect resource-rich generation zones to Maharashtra and Tamil Nadu demand centers. REPowerEU financing prioritizes cross-border interconnectors reducing gas-dependent generation.
- Industrial:Captive power users and heavy manufacturing facilities procure dedicated 66-132 kV connections.
- Commercial:Data centers and urban commercial complexes drive underground distribution demand in metropolitan cores.
Utilities account for dominant procurement volumes. Renewable Energy developers are expanding most quickly.
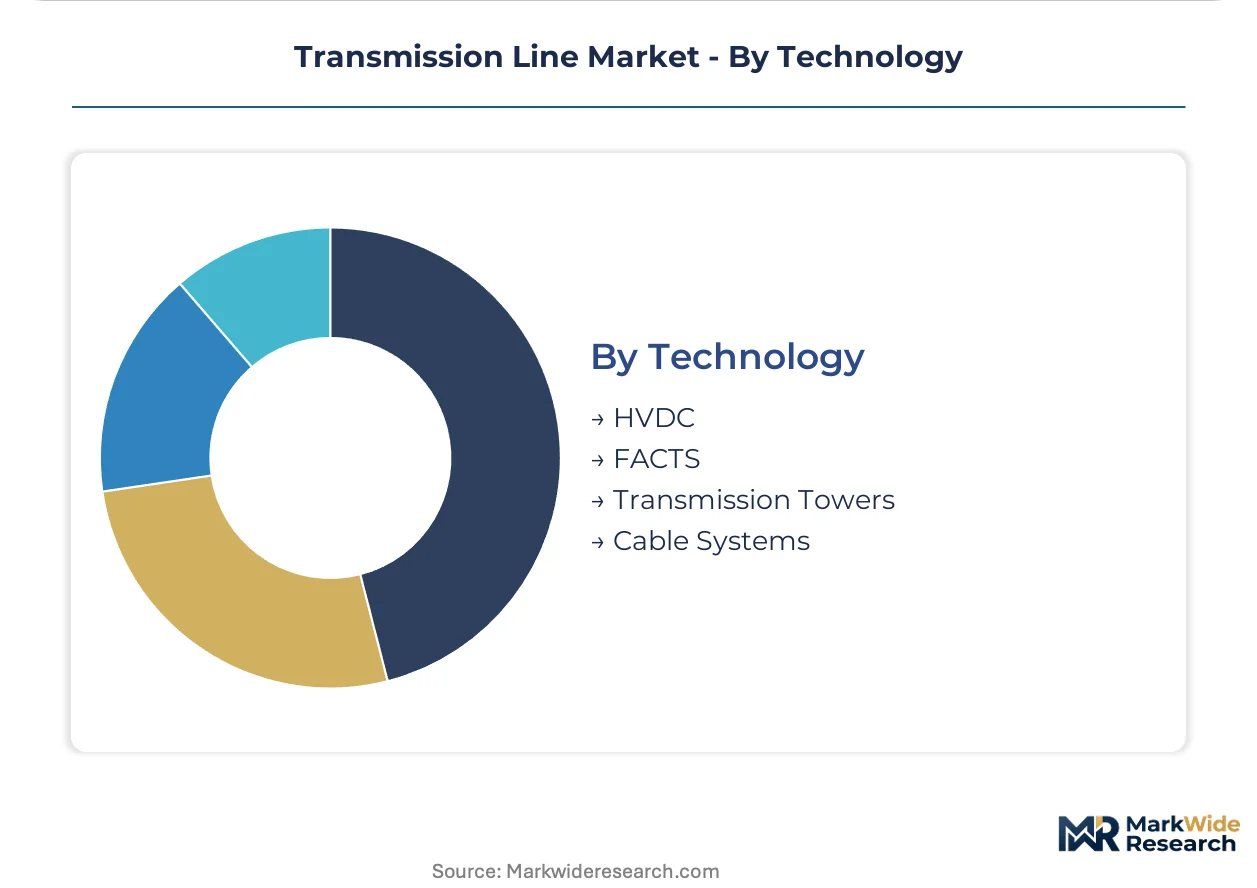
Technology:
Hardware maturity varies from century-old transmission tower designs to digitally integrated FACTS systems enabling dynamic grid stabilization.
- HVDC:Voltage source converters and line-commutated converters enable long-distance land corridors exceeding 600 kilometers and subsea links where AC synchronous stability fails. Germany's KBA-adjacent federal network agency permitting shapes cross-state corridor development timelines.
- Cable Systems:XLPE-insulated extruded dielectric cables displace oil-filled paper designs across 220-500 kV underground installations. China's SAMR-enforced GB/T standards tighten thermal cycling protocols and mechanical loading specifications for composite core qualification.
- FACTS:Static VAR compensators and synchronous conditors provide reactive power support for renewable integration.
- Transmission Towers:Galvanized steel lattice structures face digital twin retrofit requirements for predictive line rating deployment.
Cable Systems carry dominant installed base. HVDC is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping conductor procurement patterns as manufacturers migrate production to jurisdictions with streamlined certification regimes and lower compliance overhead. Cost-of-compliance gaps between European TSO qualification protocols and Asian factory acceptance standards are accelerating contract manufacturing concentration in Southeast Asia.
China
MIIT conductor efficiency mandates and SAMR-enforced GB/T thermal cycling protocols are forcing domestic manufacturers to retest product lines against accelerated aging criteria. Sichuan and Gansu provinces face procurement delays as suppliers complete recertification for high-voltage corridor projects.
India
State transmission utilities execute massive interstate corridor projects under CEA-mandated centralized scheduling protocols. Maharashtra and Gujarat have shifted from fragmented tendering to single-source master contracts with tier-one cable producers for Green Energy Corridor infrastructure.
Germany
KBA-adjacent federal network agency permitting shapes cross-state HVDC corridor development timelines. Agricultural land compensation disputes and federal permitting extend project commissioning by 18-36 months in corridors connecting North Sea offshore clusters to southern demand centers.
Japan
METI oversight of urban underground conversion creates captive demand for XLPE-insulated circuits in dense metropolitan corridors where overhead construction is prohibited. Seoul and Frankfurt pilot superconducting networks validating zero-resistance distribution at commercial scale.
United States
FERC interconnection queue reforms and state-level renewable portfolio standards drive transmission buildout to accommodate utility-scale solar and wind. Specialized tension stringing crews for 800 kV UHVDC corridors face certification scarcity that constrains deployment velocity.
Transmission Line Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue superconducting and composite-core specializations. The market structures around three tiers: integrated cable conglomerates with submarine expertise, regional EPC bundlers with utility relationships, and technology specialists commanding premium positioning in constrained urban routes. Two competitive moves dominate: multi-year framework agreements displacing project-specific tendering, and backward integration into aluminum smelting to hedge raw material volatility.
Within the integrated-tier segment, Prysmian Group and Nexans represent European-anchored conglomerates with submarine cable capabilities. KEC International exemplifies the regional EPC-bundler archetype competing on turnkey execution for corridor projects. Sumitomo Electric Industries occupies a specialist position in high-performance conductor technologies for urban constraint applications.
| Leading Market Players |
|---|
| Prysmian Group |
| LAMIFIL |
| ZTT International |
| KEC International |
| Bekaert |
| Sumitomo Electric Industries |
| CTC Global |
| Skipper Limited |
| Nexans |
| Others |
Cost & Logistics Intelligence
State transmission utilities in India and Germany concentrate procurement authority through multi-year framework agreements, anchoring contract-based long-term offtake pricing that insulates tier-one manufacturers from spot aluminum volatility while squeezing margins on standardized AC conductor volumes.
Pricing Analysis
Distributor margins for specialized submarine HVDC cables absorb 12-18 percentage points before utility delivery, while direct-to-utility channels for overhead AC lines trade volume discounts against master contract security. Three-tier pricing structure across premium composite-core, standard ACSR, and economy-grade aluminum conductors reflects certification tier and thermal rating performance. Cost compression in standard AC tiers intensifies because China's SAMR-mandated retesting floods recertified supply into spot markets. Renewable developers with Green Energy Corridor mandates show highest price sensitivity; submarine HVDC buyers with fewer than six qualified suppliers globally show lowest.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale demand from India's MSETCL and GETCO master contracts, while specialized EPC bundlers aggregate European offshore wind procurement. Manufacturing concentrates in China, India, and Italy for conductor cores; Malaysia and Vietnam for cable extrusion and armor. Raw material flows draw from primary aluminum smelters in Yunnan and Quebec, steel rod from Chinese integrated mills, and carbon fiber composite cores from Japanese specialty chemical producers. Single-source vulnerability sits with magnesium diboride superconducting wire feedstock for urban pilot networks. Distribution runs through state utility procurement pools in India, TenneT and RTE framework agreements in Europe, and project-specific EPC contracts for subsea deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Transmission Line Market compounds steadily as renewable interconnection mandates across India, Germany, and Southeast Asia create durable procurement visibility for transmission infrastructure through the projection horizon.
For Market Incumbents: Deepen backward integration into primary aluminum smelting to hedge Yunnan and Quebec curtailment volatility that erodes conductor manufacturing economics. Expand certified 800 kV UHVDC tension stringing crew capacity to capture Germany's North Sea-to-south corridor buildout before specialized labor scarcity constrains deployment velocity. Composite-core technology turnover from China's MIIT mandates threatens incumbent ACSR-heavy portfolios.
For New Entrants and Emerging Players: Superconducting magnesium diboride pilot networks in Seoul and Frankfurt offer technology-first wedge into premium urban underground segments where overhead construction prohibitions eliminate incumbent overhead specialists. Target Japan's METI-supervised metropolitan conversion corridors and European REPowerEU-financed cross-border interconnectors as most penetrable white-space geographies. Pursue joint development agreements with Sumitomo Electric or CTC Global for technology licensing rather than greenfield R&D.
For Investors and Strategic Acquirers: Integrated utility conglomerates with captive transmission development arms are the most active acquirer in this space, seeking EPC bundlers with pre-qualified utility relationships. Five-to-ten year viability hinges on exposure to India's Green Energy Corridor execution pace and European offshore wind interconnection timelines. Watch for aluminum price volatility spikes and SAMR recertification completion rates in Sichuan and Gansu as inflection indicators for supplier margin compression and procurement delay risks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Smelting | Captive supply of primary metal hedges Yunnan and Quebec curtailment volatility affecting conductor economics. |
| Master Contract Consolidation | Multi-year framework agreements with MSETCL and GETCO secure volume visibility against fragmented tendering erosion. |
| Superconducting Pilot Scale-Up | Magnesium diboride network validation in Seoul and Frankfurt unlocks premium urban underground pricing tiers. |
| Specialized Workforce Certification | 800 kV UHVDC tension stringing crew accreditation captures Germany's cross-state HVDC corridor buildout demand. |
| Submarine Cable Manufacturing Expansion | XLPE-insulated circuit capacity serves Mediterranean offshore wind clusters commanding 3-4x overhead premiums. |
Research Approach
Direct dialogue with utility planning officers, EPC contractor procurement leads, grid operator asset managers, and conductor manufacturer sales directors grounded qualitative findings. Secondary validation combined customs and trade data for aluminum and steel rod flows, CEA and FERC regulatory filings, IEA transmission investment databases, and project development tracking for Green Energy Corridor and North Sea offshore wind interconnections. Bottom-up and top-down triangulation cross-checked utility procurement volumes against national renewable capacity targets and corridor completion schedules.
Bottom-up modeling aggregated segment-level demand from voltage rating, installation type, and end-user procurement patterns across the projection horizon. Top-down validation anchored total market expansion to national transmission investment forecasts from India's CEA, Germany's Bundesnetzagentur, and China's National Energy Administration. Segmentation dimensions modeled include AC versus DC technology, overhead versus underground installation, utility versus renewable developer end-use, and regional regulatory framework clusters. CAGRs derived from utility capital expenditure trajectories, aluminum price scenario testing, and project pipeline probability-weighting for permitted versus contested corridors.
The model holds under sustained renewable interconnection mandate enforcement and aluminum price bands within historical volatility ranges; deviation in federal permitting timeline extensions beyond 36 months or acute smelter curtailment would shift corridor completion schedules and procurement timing. Forecasts reflect assumptions on technology substitution rates, regulatory enforcement consistency, and raw material supply continuity. Periodic stress-testing of base assumptions against aluminum futures curves and permitted project conversion rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
High Voltage Direct Current (HVDC) Transmission System Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
India HVDC Transmission Systems Market
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Global Oil Storage Fee Rental Market
Transmission and Distribution
Ring Main Unit Market