
 Electric Two Wheeler Charging Station Market | 2026-2036
Electric Two Wheeler Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Two Wheeler Charging Station Market Foresight
The electric two-wheeler charging infrastructure is recalibrating around a sharp split between premium battery-swapping networks and commodity plug-in posts. Gogoro Inc. dominates swap-station deployment through proprietary form-factor control and dense urban clustering. Ather Energy Pvt. Ltd. differentiates via integrated home-workplace charging software tied to its vehicle ecosystem. SUN Mobility Pvt. Ltd. anchors fleet-swap operations with modular battery architecture designed for commercial two-wheeler operators.
An electric two-wheeler charging station delivers controlled DC or AC power to light electric motorcycles and scooters, typically operating at 1 kW to 25 kW output with CCS2, GB/T, or proprietary connector protocols depending on regional vehicle standards. Rapid charging infrastructure commands premium placement economics in commercial corridors where dwell-time minimization determines fleet operator adoption. Private home charging retains volume leadership across installation types due to overnight residential tariff structures, while workplace charging emerges as the fastest-growing segment as employers bundle parking benefits with sustainability mandates. Subscription payment models concentrate recurring revenue pools, though pay-per-use dominates in markets with irregular rider utilization patterns.
India's CEA mandates technical standards for EV supply equipment, while BIS certification governs connector interoperability and safety testing for domestic installations. The EU Green Deal's transport electrification targets and F-Gas Regulation on cooling systems for charging hardware shape product design requirements across European deployments. Stakeholders must monitor how network-model regulations evolve around data portability mandates and open-protocol requirements that could erode proprietary swap-system advantages.
Market Dynamics
Battery-swapping networks are compressing capital deployment timelines by eliminating home-charging infrastructure gaps in dense urban corridors. This shift restructures competitive advantage around proprietary connector ecosystems and real-estate access rather than hardware manufacturing scale.
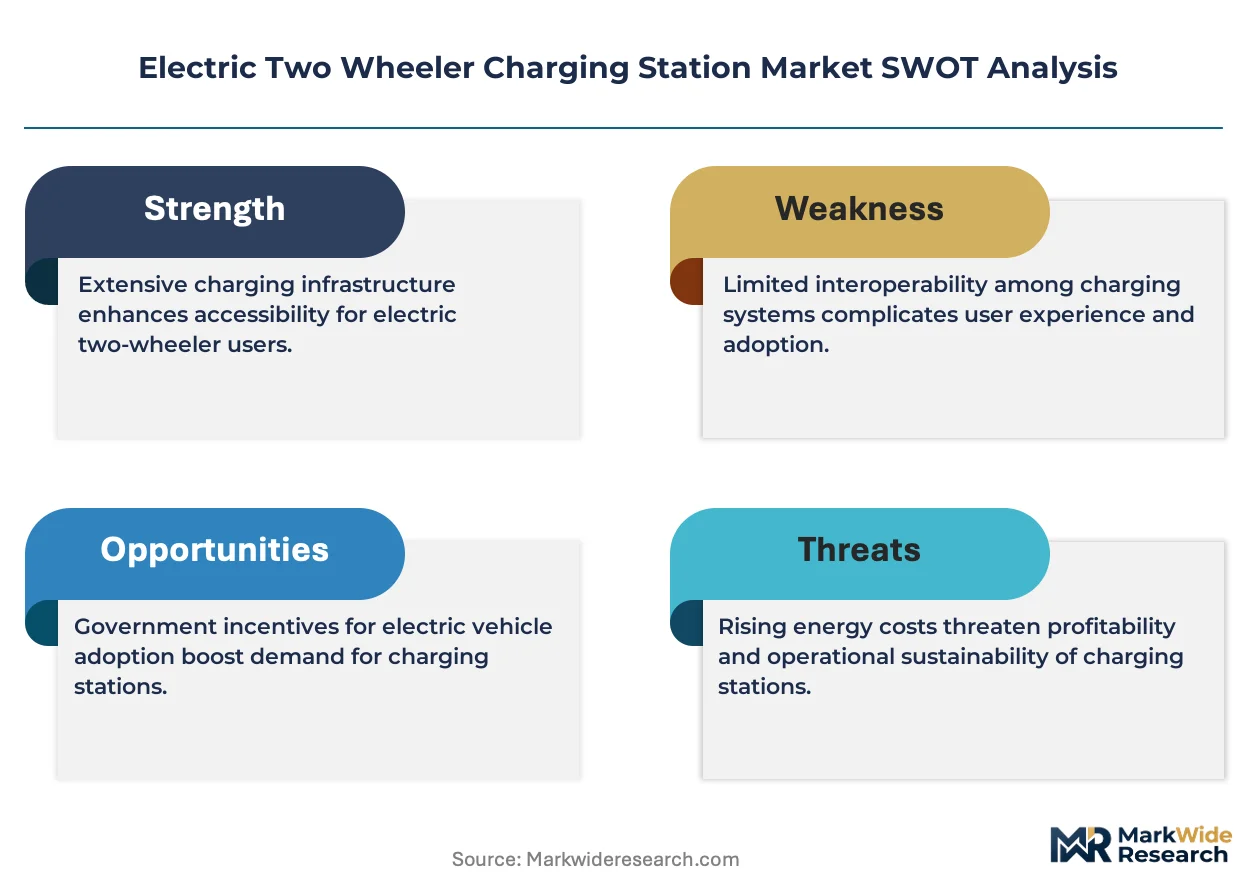
Growth Catalysts
- Fleet electrification mandates:Logistics operators across Southeast Asian capitals are converting two-wheeler delivery fleets to electric powertrains, creating concentrated demand for high-throughput swap stations.
- India's PLI scheme:Domestic manufacturing incentives for electric mobility components are reducing import dependency for charging hardware and battery packs.
- Urban air quality frameworks:Municipal low-emission zones in Vietnamese and Indonesian cities are banning internal combustion two-wheelers from central business districts.
Market Restraints
- Lithium price volatility:Battery pack costs fluctuate with spot lithium carbonate pricing, squeezing swap-station operator margins on leased battery assets.
- Real estate concentration:Prime commercial corridor sites for rapid charging hubs cluster in a handful of metropolitan property markets, inflating lease costs.
- Grid capacity constraints:Distribution network operators in emerging markets lack substation headroom for simultaneous high-power charging clusters.
Strategic Opportunities
- Workplace charging bundling:Corporate sustainability mandates in Indian tech parks are creating employer-subsidized installation demand.
- Interoperability protocols:Open battery form-factor standards under discussion by BIS could unlock multi-brand swap network participation.
- Renewable pairing:Solar canopy integration at swap stations reduces grid dependency and aligns with EU Green Deal carbon accounting requirements.
Industry Challenges
- Electrical technician scarcity:Certified EV supply equipment installers remain concentrated in major metropolitan labor markets, slowing rural deployment.
- Multi-standard certification complexity:Manufacturers must navigate parallel BIS, CEA, and IEC testing protocols for connector safety and electromagnetic compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Two Wheeler Charging Station Market |
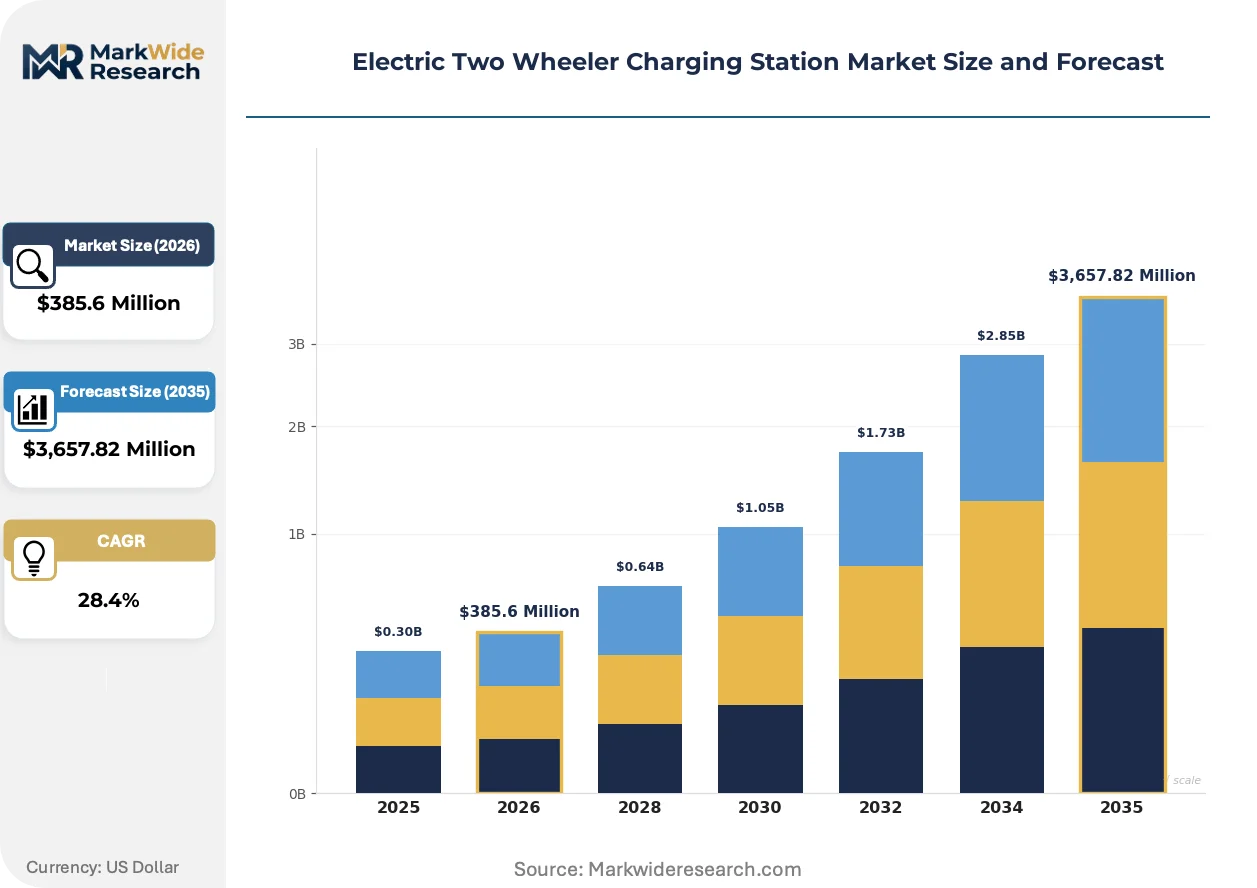
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $3,657.82 Million |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charging Type: Rapid Charging, Standard Charging, Wireless Charging, Solar Charging Installation Type: Public Charging, Private Charging, Workplace Charging, Home Charging Payment Method: Subscription Model, Pay-per-Use, Flat Rate, Mobile App Payment Network Model: Open Network, Proprietary Network, Hybrid Network, Others |
| Companies Covered | Gogoro Inc., SUN Mobility Pvt. Ltd., Ather Energy Pvt. Ltd., Ola Electric Mobility Pvt. Ltd., Hero MotoCorp Ltd., Hero Electric Vehicles Pvt. Ltd., Yulu Energy Network, ChargeZone, Statiq, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Two Wheeler Charging Station Market Shifts & Advancements
Modular battery architecture and software-defined charging protocols are fragmenting competitive moats that once depended on proprietary hardware lock-in. Network operators now compete on data integration and energy management rather than connector exclusivity.
Vehicle-to-grid bidirectional charging hardware is decentralizing energy storage economics by allowing two-wheeler batteries to arbitrage peak pricing and provide grid stabilization services. Fleet operators in Singapore and Tokyo are piloting aggregated battery pools that discharge during evening demand spikes. This capability compresses total cost of ownership calculations by adding revenue streams beyond mobility.
The EU F-Gas Regulation is accelerating refrigerant transitions in charging station thermal management systems, forcing redesigns of high-power cooling loops. Equipment manufacturers must phase out hydrofluorocarbon-based cooling in favor of CO2 or hydrocarbon alternatives. Swap-station networks in Germany and the Netherlands are front-running compliance to secure Green Deal-aligned public procurement preferences.
Subscription billing for charging access is displacing pay-per-use models among regular commuters who demand predictable mobility costs. Aggregator platforms in Vietnam and Indonesia are bundling swap-network access with insurance and maintenance into flat monthly rates. This shift concentrates customer lifetime value capture and reduces churn for network operators with dense station footprints.
Electric Two Wheeler Charging Station Market Segmentation
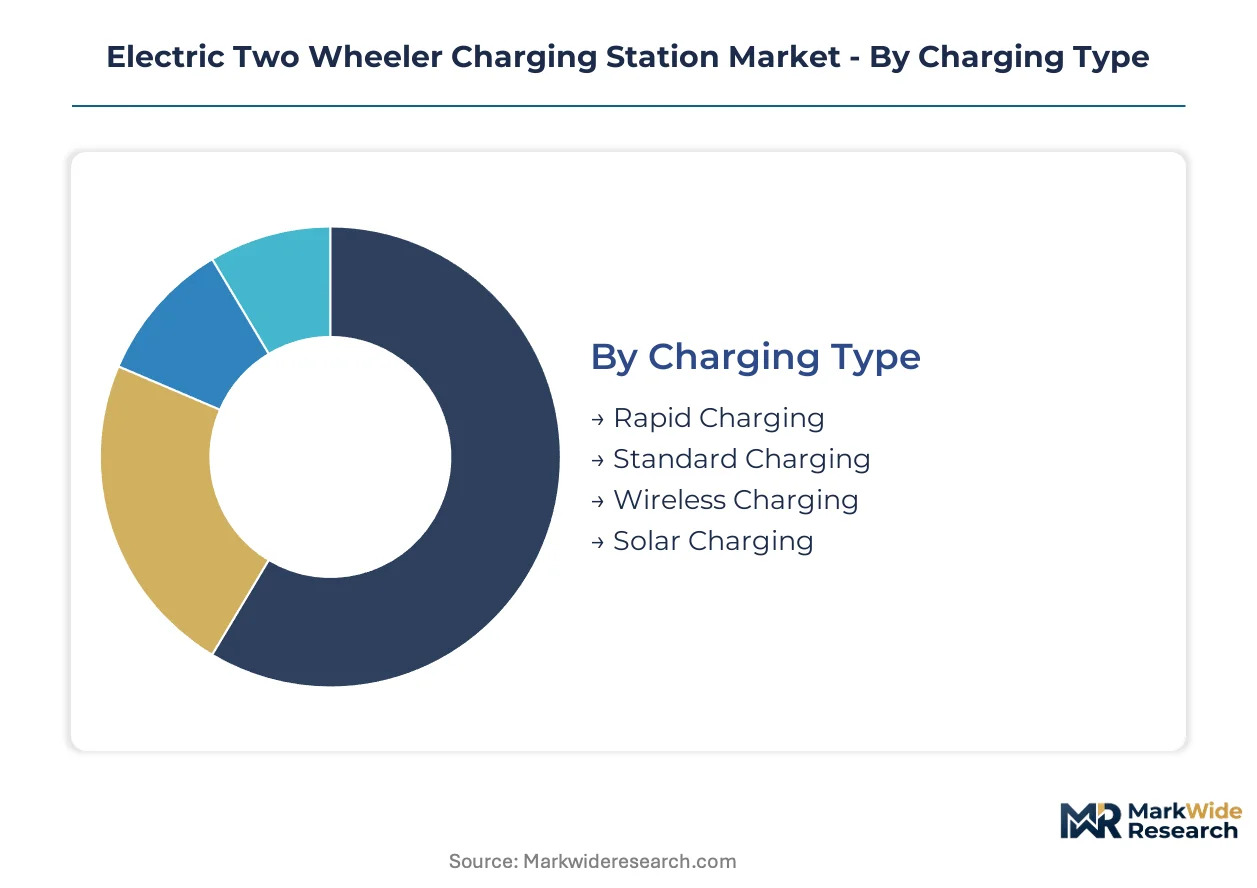
Charging infrastructure for electric two-wheelers fragments across competing deployment models and revenue architectures. Each segment carries distinct capital intensity, utilization economics, and regulatory exposure that shapes operator strategy.
Charging Type:
Volume deployment concentrates in low-cost standard installations while premium rapid networks capture fleet operator spend.
- Rapid Charging:DC fast-charging hardware delivers 10-25 kW output for commercial corridors where delivery fleets minimize dwell time. Operators in Vietnam's Ho Chi Minh City cluster these stations at logistics hubs to serve Gogoro-style swap-compatible vehicles.
- Standard Charging:AC Level 2 equipment at 1-7 kW dominates residential and workplace installations due to lower grid connection costs. India's CEA technical standards govern connector safety for these mass-market deployments.
- Wireless Charging:Inductive pad systems eliminate connector wear for premium scooter segments. Pilot programs in Singapore test integration with automated parking infrastructure.
- Solar Charging:Canopy-mounted photovoltaic arrays reduce grid dependency at off-grid swap stations. EU Green Deal carbon accounting favors these configurations for public procurement eligibility.
Today's leader: Standard Charging. Tomorrow's challenger: Rapid Charging.
Installation Type:
Customer access patterns split between captive private infrastructure and monetized public networks.
- Public Charging:Street-side and retail parking installations serve irregular riders with pay-per-use pricing. Municipal low-emission zones in Jakarta and Bangkok mandate these deployments in central business districts.
- Private Charging:Gated community and fleet depot installations serve predictable user bases with subscription billing. Real estate developers in India's Bangalore tech corridors bundle these with residential sales.
- Workplace Charging:Employer-subsidized parking bay installations are expanding most quickly as corporate sustainability mandates spread across Southeast Asian multinational campuses.
- Home Charging:Overnight residential sockets retain volume leadership due to favorable tariff structures and zero incremental real estate cost.
Home Charging anchors current volume. Workplace Charging offers the steepest expansion trajectory.
Payment Method:
Revenue model selection tracks rider utilization frequency and price sensitivity.
- Subscription Model:Flat monthly rates bundle unlimited access with insurance and maintenance. Aggregator platforms in Indonesia concentrate customer lifetime value through this structure.
- Pay-per-Use:Per-kWh or per-minute billing serves occasional riders with irregular patterns. This model dominates public station networks where churn risk exceeds acquisition cost.
- Flat Rate:Fixed per-session pricing simplifies cost prediction for short-distance commuters. Limited deployment due to margin compression on high-consumption sessions.
- Mobile App Payment:QR-code and wallet integration enables seamless interoperability across multi-brand networks. India's UPI infrastructure accelerates adoption of this method.
Subscription Model captures recurring revenue pools. Mobile App Payment enables network interoperability.
Network Model:
Competitive moats depend on protocol openness versus proprietary control over connector ecosystems.
- Open Network:Multi-brand interoperability protocols allow any compatible vehicle to access charging hardware. BIS discussions in India could mandate this structure for swap-station participation.
- Proprietary Network:Exclusive connector form-factors lock users into integrated vehicle-station ecosystems. Gogoro's dense urban clustering in Taipei and Hanoi exemplifies this approach.
- Hybrid Network:Core proprietary stations supplemented by roaming agreements with third-party operators. Ather Energy deploys this model across Indian metropolitan corridors.
- Others:Emerging consortium models and municipal concession arrangements without standardized classification.
Proprietary Network dominates current deployment. Open Network gains regulatory momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled electrical technicians and certified EV supply equipment installers concentrate in major metropolitan labor markets, anchoring deployment capacity across priority corridors. Their geographic clustering shapes where charging infrastructure scales fastest.
India
Fleet electrification mandates and corporate sustainability programs in tech parks drive employer-subsidized workplace installations. The CEA technical standards and BIS certification govern connector safety and interoperability testing for domestic deployments. Bangalore's tech corridors bundle residential charging with new developments while Maharashtra's logistics hubs anchor battery-swapping networks for delivery operators.
Vietnam
Motorcycle-dense urban centers generate concentrated demand for high-throughput swap stations displacing home charging. Municipal low-emission zones in Ho Chi Minh City ban internal combustion two-wheelers from central business districts. The city's logistics corridors cluster Gogoro-style swap networks serving delivery fleets with minimal dwell-time requirements.
Indonesia
Aggregator platforms bundle swap-network access with insurance and maintenance into flat monthly subscription rates. Jakarta's central business district mandates public charging deployments under air quality frameworks. The capital's retail parking installations serve irregular riders with pay-per-use pricing structures.
Singapore
Vehicle-to-grid bidirectional charging pilots allow aggregated two-wheeler battery pools to arbitrage peak pricing and provide grid stabilization services. The Land Transport Authority's electrification targets shape fleet operator conversion timelines. Automated parking infrastructure in Marina Bay tests wireless inductive pad integration for premium scooter segments.
Germany
The EU F-Gas Regulation accelerates refrigerant transitions in charging station thermal management systems, forcing high-power cooling loop redesigns. Green Deal-aligned public procurement preferences reward early compliance with carbon accounting requirements. Swap-station networks in Berlin and Rotterdam front-run hydrofluorocarbon phase-outs to secure municipal contracts.
Electric Two Wheeler Charging Station Market Competitive Landscape
Capital-heavy producers compete with asset-light designers and network operators across divergent margin structures. The vendor base splits between integrated vehicle-station ecosystems and standalone hardware fabricators. Three archetypes dominate: proprietary swap-network operators controlling connector form-factors, software-integrated charging platform providers, and modular battery architecture specialists serving fleet conversions. Geographic expansion and strategic partnerships constitute the dominant competitive moves as operators race for prime commercial corridor real estate.
Within the proprietary network tier, Gogoro Inc. exemplifies dense urban clustering through exclusive ecosystem control. SUN Mobility Pvt. Ltd. and Ather Energy Pvt. Ltd. represent contrasting Indian approaches—modular fleet-swap operations versus integrated home-workplace charging software tied to vehicle ecosystems. These three entities anchor the competitive landscape without exhausting its structural variation.
| Leading Market Players |
|---|
| Gogoro Inc. |
| SUN Mobility Pvt. Ltd. |
| Ather Energy Pvt. Ltd. |
| Ola Electric Mobility Pvt. Ltd. |
| Hero MotoCorp Ltd. |
| Hero Electric Vehicles Pvt. Ltd. |
| Yulu Energy Network |
| ChargeZone |
| Statiq |
| Others |
Supply & Pricing Matrix
Modular battery architecture standardization simultaneously compresses manufacturing cost curves and fragments supplier concentration across Southeast Asian assembly hubs. This dual effect erodes proprietary swap-network pricing power while opening procurement leverage for multi-source battery pack sourcing.
Pricing Analysis
Bundled subscription services versus unbundled pay-per-use transactions split pricing architectures across user archetypes. Subscription models dominate fleet operator relationships where predictable mobility costs outweigh per-session price sensitivity, while pay-per-use structures serve irregular riders in public station networks. Price differentiation rests on swap-station density and software integration depth rather than hardware specifications alone. Pricing pressure stems from lithium carbonate spot volatility squeezing leased-battery margins. Fleet operators exhibit lowest price sensitivity due to total cost of ownership calculations incorporating dwell-time savings.
Supply Chain Analysis
Freight cost inflation across maritime routes from China, South Korea, and Taiwan is reshaping regional inventory positioning strategies for charging hardware manufacturers. Lithium-ion cell production concentrates in Chinese and South Korean gigafactories, while power electronics and thermal management components source from Taiwanese semiconductor foundries. Supply chain risk centers on single-source vulnerability for proprietary connector form-factors controlled by dominant swap-network operators. Distribution runs through integrated vehicle-station ecosystem partnerships rather than independent channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric two-wheeler charging station market compounds steadily as municipal fleet electrification mandates lock in infrastructure deployment timelines across Southeast Asian capitals.
For Market Incumbents: Lock in prime commercial corridor real estate through long-term municipal concessions before open-protocol regulations erode proprietary connector advantages. Deepen backward integration into battery pack assembly to offset lithium price volatility exposure. Gogoro-style ecosystem control faces regulatory threat from India's BIS interoperability discussions. For New Entrants and Emerging Players: Vehicle-to-grid bidirectional hardware offers a technology-first wedge into Singapore and Tokyo pilot programs where aggregated battery pools arbitrage peak grid pricing. Target workplace charging installations in Indian tech parks where employer sustainability mandates subsidize capital deployment. Pursue solar canopy integration as a differentiated procurement pitch for EU Green Deal-aligned municipal contracts. For Investors and Strategic Acquirers: Roll-up economics work for regional swap-station operators because fragmented real estate access across Vietnamese and Indonesian cities prevents single-network dominance. Long-term viability hinges on regulatory acceptance of proprietary versus open network models. Monitor BIS protocol rulings as the critical inflection signal for multi-brand participation rights.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swap Network Expansion | Dense urban clustering in Ho Chi Minh City and Jakarta secures fleet operator lock-in through minimal dwell-time service. |
| Workplace Charging Partnership | Employer-subsidized installations in Bangalore tech corridors bundle sustainability mandates with residential real estate sales. |
| Solar Canopy Integration | Photovoltaic array deployment satisfies EU F-Gas Regulation carbon accounting for Green Deal public procurement eligibility. |
| Vehicle-to-Grid Hardware Deployment | Bidirectional charging pilots in Singapore enable aggregated battery pools to arbitrage peak pricing and stabilize grid demand. |
| Open Protocol Certification Investment | BIS interoperability compliance positions operators for India's potential multi-brand swap-station participation mandates. |
Research Methodology
Multiple input streams — fleet operator procurement directors, charging hardware engineering leads, municipal transport planning officers, and battery supply chain managers — were reconciled against regulatory filing databases and customs trade records. Primary fieldwork captured deployment timelines and utilization economics across swap-station networks. Secondary validation drew from CEA technical standards documentation, EU Green Deal transport electrification targets, and BIS certification protocols. Bottom-up station deployment counts and top-down market sizing were cross-referenced for triangulation.
Historical deployment trajectories were cross-referenced against expert panel assessments of regulatory acceleration scenarios across the projection horizon. Segmentation dimensions modeled include charging type, installation category, payment architecture, and network protocol openness. CAGRs were derived from installed base expansion curves and revenue-per-station economics. Forecast inputs incorporated lithium price scenario modeling and grid capacity constraint assessments for emerging market distribution networks.
The model holds under continued municipal low-emission zone expansion and fleet electrification mandate enforcement; deviation in lithium supply disruption severity or open-protocol regulatory adoption timing would shift infrastructure mix assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Germany EV Charging Infrastructure Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Western Europe Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Battery Swap Station Market
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Wireless Electric Vehicle Charger Market
Electric Vehicle Charging
EV Charging Infrastructure Market
Electric Vehicle Charging
Battery Liquid Cooling Plates for Electric Vehicle Market
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
United Kingdom Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
DC Chargers Market
Electric Vehicle Charging
Electric Vehicle Battery Charger Market