
 South America Battery Management System Market | 2026-2036
South America Battery Management System Market Size, Share, and Industry Trends Forecast 2026-2036
South America Battery Management System Market Analytics
Silicon carbide is recalibrating power electronics economics across South American battery management architectures by displacing traditional silicon-based MOSFETs in high-voltage traction applications. Texas Instruments leverages its analog semiconductor heritage to anchor design wins with Brazilian EV assemblers seeking localized sourcing. Continental Engineering Services competes through systems integration capabilities that span cell characterization through pack-level thermal management.
A battery management system monitors cell voltage, temperature, and state-of-charge while executing balancing algorithms to preserve pack longevity and prevent thermal runaway in multi-cell configurations. Lithium-ion product configurations dominate procurement volumes given their lock-in with electric vehicle platforms across the Mercosur trade zone. Active technology architectures capture expanding share as OEMs prioritize energy recovery efficiency over passive resistor-dissipation methods in premium electric vehicle segments.
ANVISA establishes electromagnetic compatibility and safety testing protocols for medical-grade backup power systems employing battery management subsystems. Brazil's Rota 2030 automotive regime mandates escalating local content thresholds that reshape supplier qualification criteria for foreign component manufacturers. Stakeholders must track lithium carbonate refining commitments in Argentina's Catamarca and Jujuy provinces against cathode plant buildout timelines to calibrate capacity planning.
Market Dynamics
Silicon carbide power semiconductors are compressing thermal management overhead in high-voltage battery packs, forcing incumbent suppliers to redesign architectures around faster switching frequencies and reduced cooling mass. This displacement cascades through cell balancing circuits, firmware stacks, and thermal interface materials across Brazilian and Argentine assembly lines.
Growth Catalysts
- ANVISA electromagnetic compatibility mandates:Medical-grade backup power installations in São Paulo and Rio de Janeiro health networks require certified battery management subsystems, creating a qualified supplier tier.
- Argentina lithium triangle refining:Cathode precursor plants in Catamarca and Jujuy provinces are anchoring localized demand for grid-scale storage systems with integrated management electronics.
- Active balancing algorithms:OEMs in Brazil's premium electric vehicle segments are specifying energy recovery circuits that outperform passive resistor methods in pack longevity metrics.
Market Restraints
- Silicon carbide substrate costs:Wafer processing expenses for 650V and 1200V devices remain elevated versus silicon MOSFET alternatives, constraining mid-market pack economics.
- Lithium carbonate price volatility:Argentine salar brine extraction disruptions transmit directly to cell cost structures, compressing management system budget allocations.
- Rota 2030 local content thresholds:Escalating domestic value-add requirements disqualify foreign component suppliers lacking Brazilian manufacturing footprints.
Strategic Opportunities
- Chilean grid storage procurement:Utility-scale solar-plus-storage tenders in Atacama and Antofagasta regions specify battery management architectures sized for 100MWh-plus installations.
- Wireless cell monitoring integration:Mesh network topologies eliminating high-voltage isolation barriers are converging with cloud-based predictive maintenance platforms.
- Colombian electric bus incentives:Bogotá and Medellín fleet electrification programs mandate 12-year battery warranties, requiring advanced state-of-health estimation firmware.
Industry Challenges
- Embedded systems firmware talent scarcity:Battery algorithm development requires expertise in Kalman filtering and electrochemical modeling that concentrates in São Paulo's semiconductor corridor.
- ANVISA certification timelines:Medical-grade backup power approvals stretch 14-18 months, freezing design iterations and supplier qualification cycles.
- Legacy CAN bus integration:Industrial equipment retrofits in Argentina's mining belt demand backward-compatible communication stacks that fragment development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Battery Management System Market |
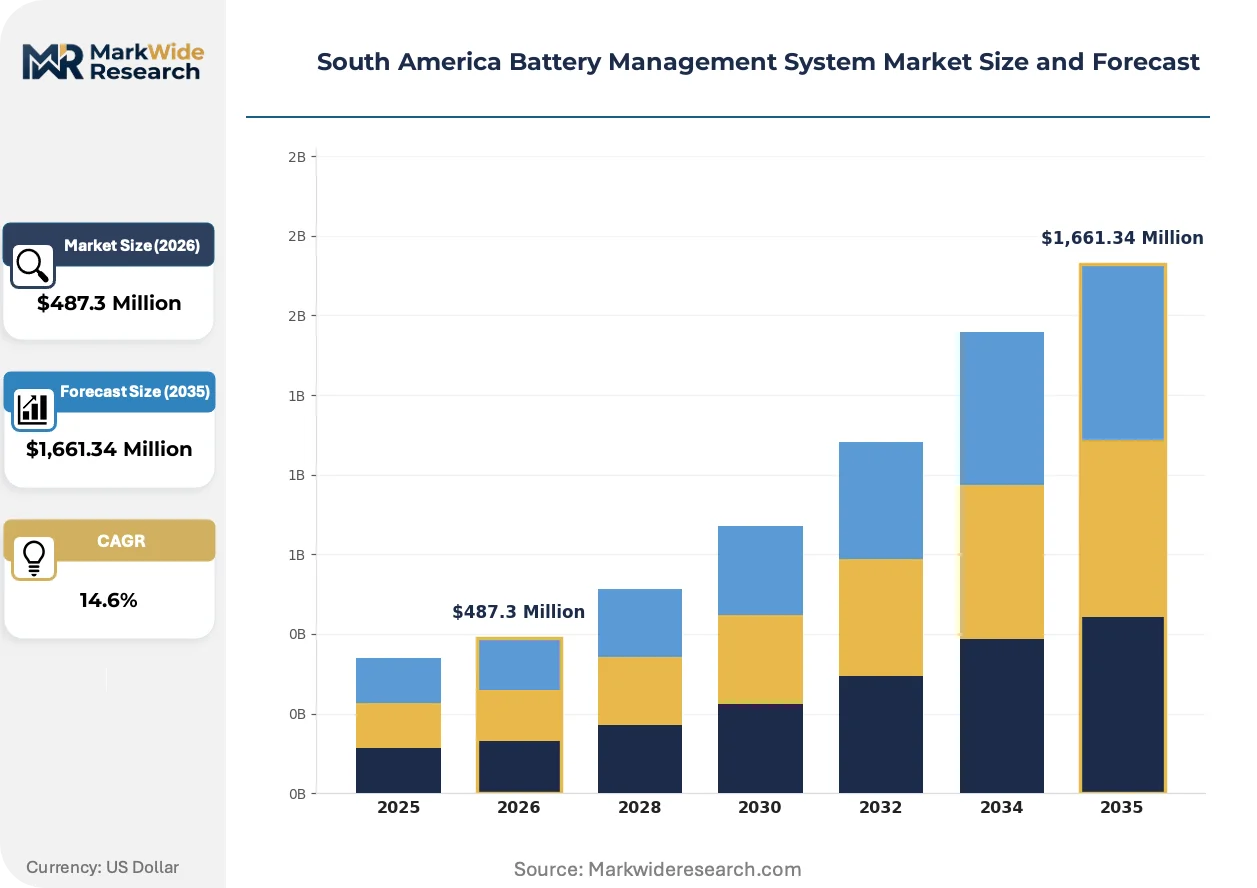
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Others End User: Automotive, Consumer Electronics, Renewable Energy, Industrial Technology: Passive, Active, Hybrid, Digital Application: Electric Vehicles, Energy Storage Systems, Uninterruptible Power Supplies, Telecommunications |
| Companies Covered | Sensata Technologies Inc, Renesas Electronics Corporation, SK Innovation Co Ltd, DENSO Corporation, BYD Co Ltd, Panasonic Corporation, Bosch Corporation, Continental Engineering Services, Texas Instruments, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Battery Management System Market Evolving Landscape
Edge computing architectures are redistributing computational load from centralized pack controllers to distributed cell monitoring units, collapsing latency in fault detection loops. This topology shift demands new firmware security models and over-the-air update infrastructures.
Distributed intelligence architectures using ARM Cortex-M4 microcontrollers at each cell module are decentralizing state estimation from the master controller. Brazilian EV assemblers are qualifying these topologies for 400V and 800V platforms to reduce wiring harness mass and improve fault isolation granularity. The structural consequence is compressing tier-one supplier margins as module-level electronics commoditize faster than pack-level integration.
Brazil's Rota 2030 automotive regime is tightening local content verification through blockchain-tracked component provenance systems. Industrial consequence includes mandatory Brazilian assembly of printed circuit boards and power semiconductors for incentive eligibility. Premium passenger EV segments are responding by qualifying domestic EMS providers for management system manufacturing.
Fleet operators across Mercosur trade zones are unbundling battery management hardware from long-term service contracts, shifting capital expenditure models toward per-kilometer availability pricing. Leasing channels and energy-as-a-service providers are displacing direct OEM sales in municipal bus and last-mile delivery segments. This pattern is most visible in São Paulo's electric bus procurement, where operators specify management system performance guarantees independent of vehicle OEM warranties.
South America Battery Management System Market Segmentation
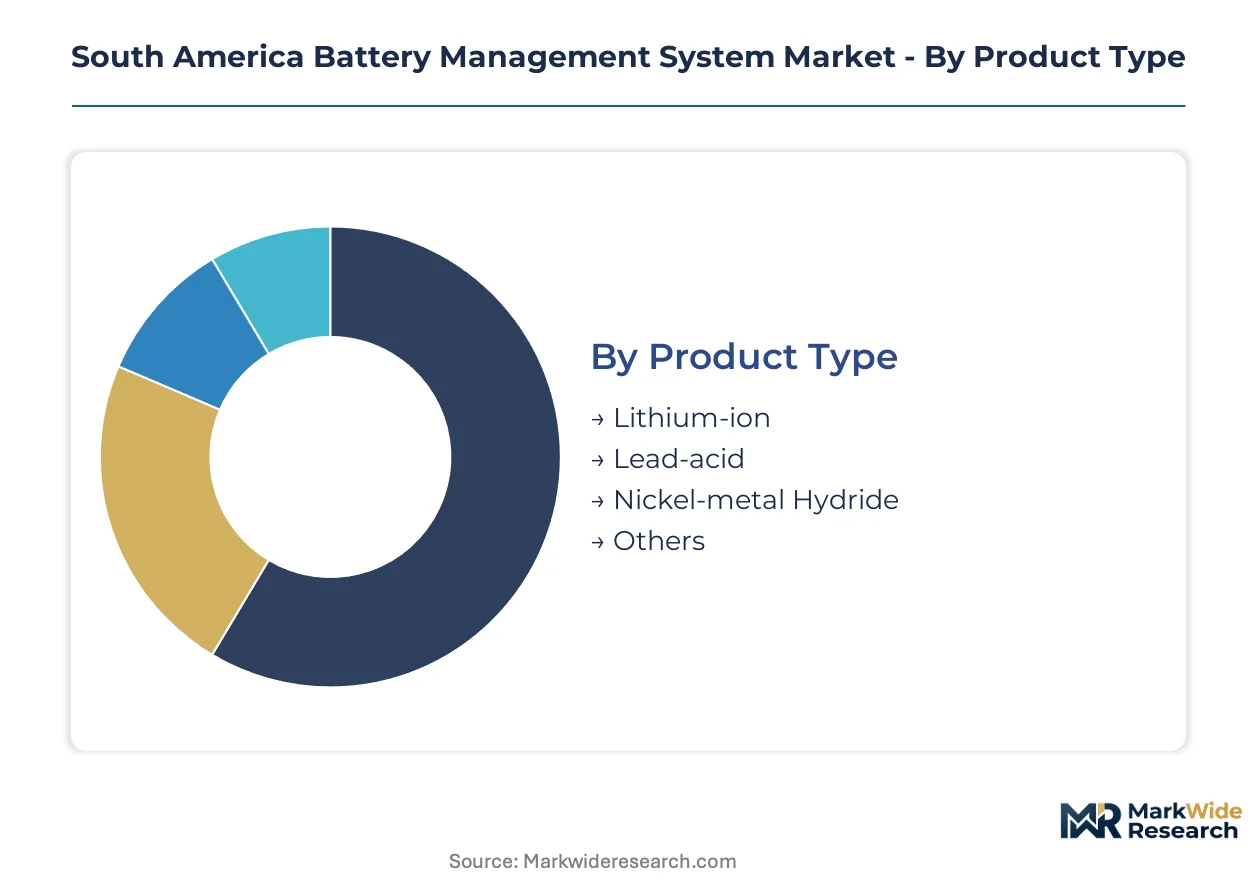
Battery management system architectures diverge sharply across South American deployment contexts. Cell chemistry, balancing topology, and end-use duty cycles each reshape component specifications and supplier qualification pathways.
Product Type:
Volume procurement concentrates on mature chemistries with established recycling infrastructure, while premium segments chase energy density gains.
- Lithium-ion:Dominates high-voltage traction applications across Brazilian EV assembly lines. São Paulo fleet operators specify NMC and LFP variants for 400V bus platforms, with active balancing circuits mandatory under 12-year warranty terms.
- Lead-acid:Retains cost advantage in backup power and starter battery replacements. Argentine mining operations in Catamarca province specify flooded and AGM configurations for heavy-duty equipment, though lithium substitution accelerates in underground electrification projects.
- Nickel-metal Hydride:Hybrid electric vehicle legacy installations in Colombian urban transit maintain residual demand. Toyota-dominated supplier relationships constrain new design wins.
- Others:Sodium-ion pilot programs in Chilean grid storage and solid-state R&D partnerships in Brazilian university corridors occupy pre-commercial niches.
Today's leader: Lithium-ion. Tomorrow's challenger: Sodium-ion.
End User:
Application-specific duty cycles fragment firmware requirements and thermal management architectures.
- Automotive:Brazilian Rota 2030 compliance drives localized PCB assembly and ANVISA electromagnetic certification for medical-grade vehicle variants. Passenger EVs and electric buses split procurement between 400V and 800V platforms.
- Renewable Energy:Argentine lithium triangle cathode plants anchor demand for grid-scale storage in Catamarca and Jujuy provinces. Utility-scale solar-plus-storage tenders specify 100MWh-plus management architectures.
- Consumer Electronics:Smartphone and laptop battery packs concentrate in São Paulo's electronics corridor, with UN 38.3 transportation testing mandatory for export logistics.
- Industrial:Forklift electrification in Mercosur free trade zones and mining equipment retrofits in Chile's Atacama region drive ruggedized enclosure specifications.
Automotive commands current procurement volumes; renewable energy claims the steepest expansion trajectory.
Technology:
Balancing methodology directly determines pack longevity, energy recovery efficiency, and bill-of-materials cost structure.
- Active:Energy recovery circuits using inductor or capacitor transfer outperform passive dissipation in premium Brazilian EV segments. São Paulo electric bus operators mandate active architectures for warranty eligibility.
- Passive:Resistor-based bleeding dominates cost-sensitive lead-acid replacements and consumer electronics. Colombian last-mile delivery fleets specify passive systems for sub-50V auxiliary packs.
- Hybrid:Selective active-passive switching addresses mixed-load industrial applications in Argentine manufacturing belts.
- Digital:Model-predictive control firmware and cloud-connected diagnostics emerge in Chilean utility storage and Brazilian telecommunication backup installations.
Active architectures gain share fastest in automotive; digital layers are penetrating utility and telecom verticals.
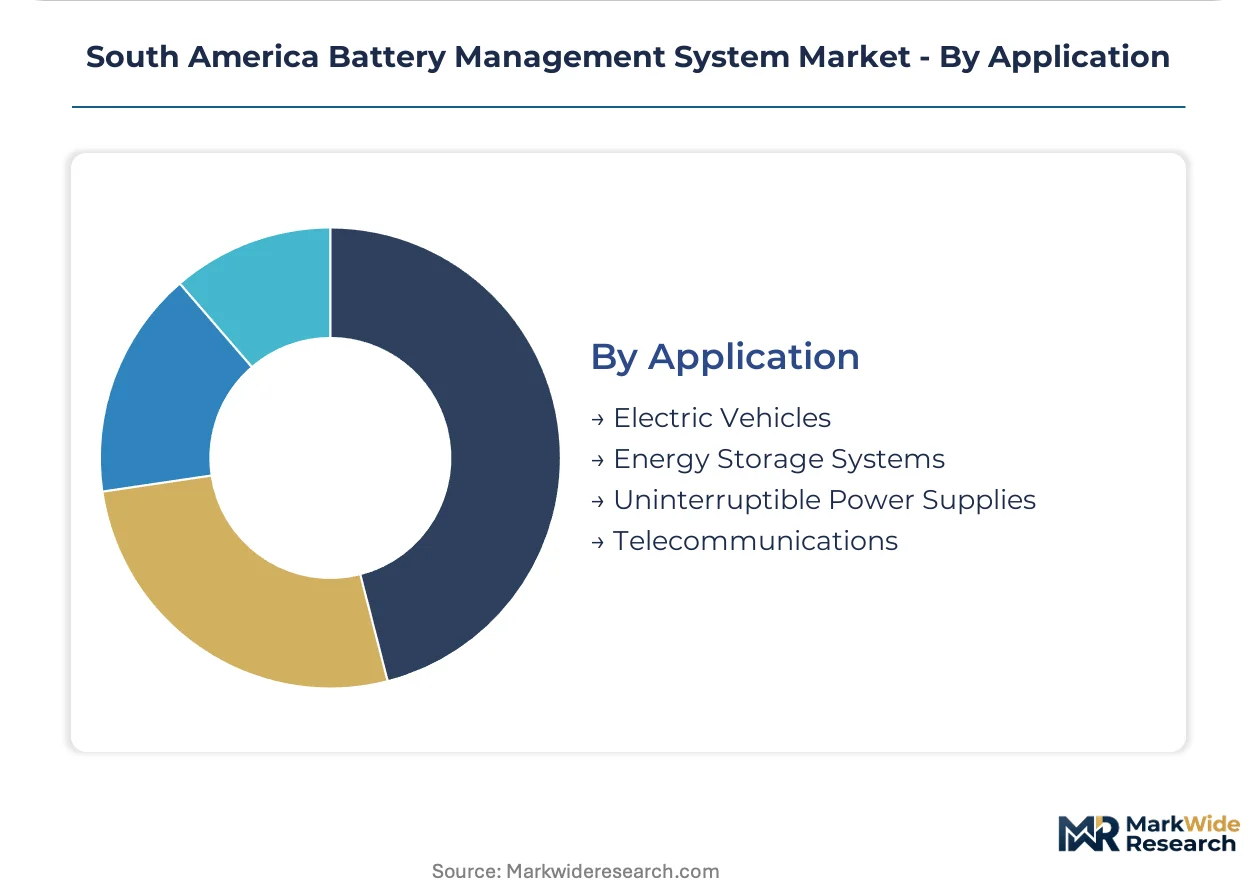
Application:
Voltage tier and safety integrity level requirements segment supplier capabilities.
- Electric Vehicles:400V and 800V traction packs require ASIL-D functional safety and silicon carbide power stage integration. Brazilian assemblers qualify domestic EMS providers under Rota 2030 local content rules.
- Energy Storage Systems:Grid-scale installations in Chile's Atacama and Antofagasta regions demand modular architectures with wireless cell monitoring and predictive maintenance platforms.
- Uninterruptible Power Supplies:São Paulo and Rio de Janeiro health networks require ANVISA-certified medical-grade backup systems with 14-18 month approval timelines.
- Telecommunications:Colombian mountain corridor base stations and Brazilian rural connectivity programs specify wide-temperature-range operation and diesel-hybrid integration.
Electric vehicles anchor revenue concentration; energy storage systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's automotive corridor anchors South American battery management system demand through electric bus procurement and passenger EV assembly lines. Brazilian Rota 2030 local content rules and ANVISA electromagnetic certification reshape supplier qualification pathways across the continent.
Brazil
São Paulo fleet operators specify active balancing architectures for 400V electric bus platforms under 12-year warranty mandates. Rota 2030 escalates domestic value-add thresholds, forcing foreign suppliers to establish Brazilian PCB assembly and semiconductor packaging operations. The ABC Paulista manufacturing belt concentrates EMS providers qualifying for incentive-linked management system production.
Argentina
Catamarca and Jujuy provinces anchor cathode precursor plant buildouts that drive grid-scale storage demand with integrated management electronics. The country's national mining and energy regulator oversees lithium carbonate refining commitments against battery project timelines. Salta province clusters are emerging as demand concentration zones for utility-scale installations serving regional power grids.
Chile
Atacama and Antofagasta regions host utility-scale solar-plus-storage tenders specifying 100MWh-plus battery management architectures. The country's national energy commission structures auction mechanisms that favor modular, wireless-enabled monitoring systems. Santiago's engineering services corridor supplies firmware talent for predictive maintenance platforms deployed in northern desert installations.
Colombia
Bogotá and Medellín electric bus incentives mandate extended battery warranties requiring advanced state-of-health estimation firmware. The national transport ministry's fleet electrification programs specify management system performance guarantees independent of vehicle OEM coverage. Antioquia department's manufacturing base is developing local assembly capacity for telecommunications backup systems.
Peru
Lima's mining equipment electrification projects drive demand for ruggedized battery management systems in underground operations. The country's national mining regulator establishes safety protocols for lithium-ion traction systems in confined extraction environments. Arequipa's industrial corridor is qualifying suppliers for forklift fleet conversions serving Mercosur free trade logistics.
South America Battery Management System Market Competitive Landscape
Global majors compete with regional champions across technology integration and local compliance capabilities. The supplier base stratifies between semiconductor originators, tier-one automotive integrators, and domestic EMS qualifiers under Brazil's Rota 2030 regime. Three archetypes dominate: analog semiconductor specialists with design win relationships, systems integrators spanning cell characterization through thermal management, and battery cell manufacturers with captive electronics divisions. Consolidation pressure is accelerating through strategic partnerships and capacity localization mandates.
Within the semiconductor archetype, Texas Instruments anchors design win relationships with Brazilian assemblers seeking localized sourcing pathways. Continental Engineering Services occupies a position exemplifying systems integration capabilities that span firmware stacks through pack-level thermal architectures. Sensata Technologies Inc represents the tier-one automotive supplier segment with established electromagnetic certification expertise. These three entities illustrate how competitive positioning converges on Rota 2030 compliance and ANVISA qualification timelines.
| Leading Market Players |
|---|
| Sensata Technologies Inc |
| Renesas Electronics Corporation |
| SK Innovation Co Ltd |
| DENSO Corporation |
| BYD Co Ltd |
| Panasonic Corporation |
| Bosch Corporation |
| Continental Engineering Services |
| Texas Instruments |
| Others |
Value Network & Pricing Analysis
Brazilian electric bus fleet operators concentrate procurement decisions under 12-year warranty mandates, anchoring a contract-based long-term offtake pricing model that ties management system costs to availability guarantees rather than per-unit hardware transactions. São Paulo's Rota 2030 compliance requirements feed back into supplier selection, compressing margins for foreign component manufacturers lacking localized PCB assembly operations.
Pricing Analysis
Silicon carbide wafer processing expenses transmit directly to pack-level quotations, with input-cost pass-through most visible in 800V traction architectures where substrate costs dominate bill-of-materials structures. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified automotive systems from industrial-grade backup power units and cost-sensitive consumer electronics. Cost compression in mid-market segments is intensifying because Argentine lithium carbonate price volatility squeezes cell procurement budgets and diverts capital from management electronics. Fleet operators in municipal bus programs exhibit highest price sensitivity, while grid-scale utility storage developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Reverse-logistics flows for end-of-life battery packs remain underdeveloped across South America, constraining secondary material recovery and inflating virgin component demand. Manufacturing concentration centers on China for lithium-ion cell supply, Taiwan for power semiconductors, and Brazil for final PCB assembly under Rota 2030 local content verification. Raw material dependencies rest on Chilean lithium brine extraction, Australian spodumene concentrates, and refined cobalt from Central African sources. Single-source vulnerability in silicon carbide substrate supply creates chokepoint exposure for high-voltage traction system assemblers. Distribution runs through tier-one automotive integrators and domestic EMS providers qualified under Brazilian incentive regimes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where São Paulo electric bus operators now specify active balancing architectures and predictive maintenance firmware as baseline requirements, elevating technical qualification thresholds above pure cost competition.
For Market Incumbents: Anticipate margin compression from silicon carbide commoditization by securing captive supply agreements with Taiwanese substrate manufacturers and accelerating firmware differentiation through edge computing architectures. Defensive consolidation should target Brazilian EMS providers with established Rota 2030 qualification pathways, as foreign competitors lacking local assembly footprints face systematic disqualification from incentive-linked procurement. For New Entrants and Emerging Players: Wireless cell monitoring mesh topologies offer a technology-first wedge into Chilean utility-scale storage tenders where incumbent wiring harness architectures create installation cost disadvantages. White-space targets include Colombian telecommunications backup systems requiring wide-temperature diesel-hybrid integration, and Peruvian underground mining electrification projects demanding ruggedized safety enclosures. A certification-first go-to-market strategy front-loading ANVISA electromagnetic compatibility documentation accelerates supplier qualification timelines. For Investors and Strategic Acquirers: Tier-one automotive semiconductor suppliers are the most active acquirer in this space, consolidating analog design houses with established Brazilian OEM relationships. Long-term viability hinges on positioning for post-lithium chemistries and solid-state transitions. Acquisition target archetypes include firmware specialists with Kalman filtering expertise concentrated in São Paulo's semiconductor corridor. Monitor lithium carbonate refining commitments in Catamarca and Jujuy provinces against cathode plant construction timelines as the critical inflection signal for grid-scale storage demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Stage Integration | Texas Instruments and Renesas displace silicon MOSFETs in 800V Brazilian EV platforms through faster switching frequencies. |
| Rota 2030 Local Content Compliance | Foreign suppliers establish Brazilian PCB assembly operations to qualify for automotive incentive programs. |
| ANVISA Certification Investment | Medical-grade backup power manufacturers front-load 14-18 month electromagnetic compatibility approval timelines. |
| Wireless Cell Monitoring Deployment | Chilean utility-scale tenders specify mesh architectures eliminating high-voltage isolation barriers in Atacama installations. |
| Active Balancing Firmware Development | São Paulo electric bus operators mandate energy recovery circuits outperforming passive resistor methods under warranty terms. |
Research Methodology
Coverage spans Brazil, Argentina, Chile, Colombia, and Peru, with primary inputs from each market combining structured interviews with battery system procurement managers at São Paulo fleet operators, firmware engineering directors in Santiago's semiconductor corridor, and regulatory affairs specialists navigating ANVISA certification pathways. Secondary validation draws from ANVISA electromagnetic compatibility filings, Brazil's Rota 2030 local content disclosure databases, Chilean national energy commission auction records, and Argentine mining regulator lithium project registrations. Bottom-up cell and pack shipment estimates triangulate against top-down electric vehicle production forecasts and grid-scale storage tender awards.
Granularity-level modeling disaggregates volume and value outputs across chemistry type, balancing topology, voltage tier, and end-use application throughout the projection horizon. Segmentation dimensions include lithium-ion versus emerging sodium-ion configurations, active versus passive versus hybrid balancing methodologies, 400V versus 800V platform architectures, and automotive versus renewable energy versus industrial duty cycles. CAGRs derive from curve-fitting historical procurement patterns against announced cathode plant buildout timelines and electric bus fleet electrification commitments. Industry-specific forecast inputs incorporate silicon carbide adoption curves in traction inverters and wireless monitoring penetration rates in utility storage.
The model holds under stable lithium carbonate refining commitments and Rota 2030 local content threshold enforcement; deviation in Argentine salar brine extraction disruptions or Brazilian incentive program restructuring would shift capacity installation timelines. Forecasts reflect assumptions regarding cathode precursor plant operationalization in Catamarca and Jujuy provinces and ANVISA certification backlog clearance rates. Practitioners should monitor lithium carbonate spot price volatility and Rota 2030 blockchain-tracked component provenance system implementation for early signals of supply constraint or qualification bottleneck emergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Japan Surge Protector Market
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
Global Rugged Power Supply Market
Power Systems
Global Next Generation Power Semiconductors Market
Power Systems
DC Power Supplies Market
Power Systems
Organic Fixed Power Capacitors Sales Market
Power Systems
Battery Electronic Control Unit Market
Power Systems
Voltage Stabilizer System Market
Power Systems
Modular Uninterrupted Power Supplies (UPS) Market
Power Systems
Intelligent Power Module (IPM) Market
Power Systems
Charge Pumps Market
Power Systems
Asia-Pacific IGBT and Super Junction MOSFET Market
Power Systems
Power Inverter Market
Power Systems
Low Voltage Drives Market
Power Systems
Surface Mounted Medium Voltage Distribution Panel Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market