
 Asia-Pacific DC Distribution Networks Market | 2026-2036
Asia-Pacific DC Distribution Networks Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific DC Distribution Networks Market Outlook
Market Context
China's dual carbon goals are repositioning the cost-of-entry calculus for DC distribution equipment suppliers across the Asia-Pacific. ABB Ltd leverages its manufacturing scale to anchor supply contracts for high-voltage DC switchgear in Chinese grid modernization projects. Huawei Digital Power Technologies Co., Ltd. competes through in-house production of power conversion modules that reduce dependency on imported semiconductor components. Siemens Ltd differentiates by integrating digital twin capabilities into its DC distribution control platforms for Southeast Asian data center operators.
Technical Definition and Structural Segments
Asia-Pacific DC Distribution Networks encompass low-to-medium voltage power distribution systems that transmit direct current electricity through switchgears, circuit breakers, and relay panels, typically operating at 1500 V DC or below for commercial and industrial environments. These networks eliminate AC-DC conversion stages, reducing energy losses by 10-20% in data center and telecom applications where native DC loads predominate. Switchgears command the largest product type share due to their critical role in fault isolation and protection across utility-scale renewable installations. Data centers represent the fastest-growing end user segment as hyperscale operators in Singapore, Japan, and Australia deploy 380 V DC architectures to improve power usage effectiveness. Digital control technology concentrates margin pools because software-defined power management commands premium pricing over electromechanical alternatives.
Regulatory Frame and Outlook
MIIT in China and CEA in India are tightening efficiency standards for DC distribution equipment deployed in renewable integration and industrial settings, forcing manufacturers to recertify products against updated loss-factor thresholds. Japan's METI has issued technical guidelines for DC microgrids that influence procurement specifications across Northeast Asian utility tenders. BIS certification requirements in India create non-tariff barriers that favor domestic assembly partnerships over pure import strategies. Stakeholders must monitor how Australia's grid interconnection rules and emerging state-level renewable mandates reshape DC distribution specifications before committing to regional manufacturing footprints.
Market Dynamics
China's dual carbon mandates and India's renewable integration targets are compressing procurement timelines for DC distribution equipment across the Asia-Pacific, forcing suppliers to recertify products against tightened loss-factor thresholds while scaling manufacturing footprints.
Growth Catalysts
- MIIT efficiency mandates:China's updated loss-factor standards for grid-tied equipment are disqualifying legacy AC-DC conversion architectures from state-backed tenders.
- Hyperscale data center buildouts:Operators in Singapore and Australia are specifying 380 V DC bus architectures to eliminate conversion losses in compute-dense facilities.
- CEA renewable integration rules:India's Central Electricity Authority is mandating DC-ready distribution infrastructure for solar parks above 250 MW capacity.
Market Restraints
- IGBT and SiC supply concentration:Power semiconductor fabrication for DC switchgear concentrates in Taiwan and South Korea, exposing procurement to geopolitical disruption.
- BIS certification timelines:India's Bureau of Indian Standards requires 18-24 month testing cycles for imported DC protection equipment, delaying market entry.
- Copper price volatility:Busbar and conductor materials constitute 35-40% of switchgear BOM costs, squeezing margin predictability for project-based contracts.
Strategic Opportunities
- Vietnam manufacturing corridor:Industrial zone developers in Bac Ninh and Hai Phong are soliciting DC microgrid infrastructure for export-oriented electronics assembly.
- Marine and offshore electrification:Port authorities in Japan and South Korea are specifying shore power systems using medium-voltage DC distribution for container terminals.
- PLI scheme localization:India's production-linked incentive scheme for advanced chemistry cell manufacturing is creating captive demand for DC factory distribution networks.
Industry Challenges
- Power electronics engineering scarcity:Design of solid-state DC circuit breakers requires specialized expertise in arc interruption physics that outpaces regional university output.
- Legacy AC infrastructure lock-in:Retrofit projects in established industrial zones face coordination complexity with existing electromechanical protection schemes.
- Interoperability certification gaps:Absence of unified IEC standards for DC microgrid communication protocols forces custom integration engineering per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific DC Distribution Networks Market |
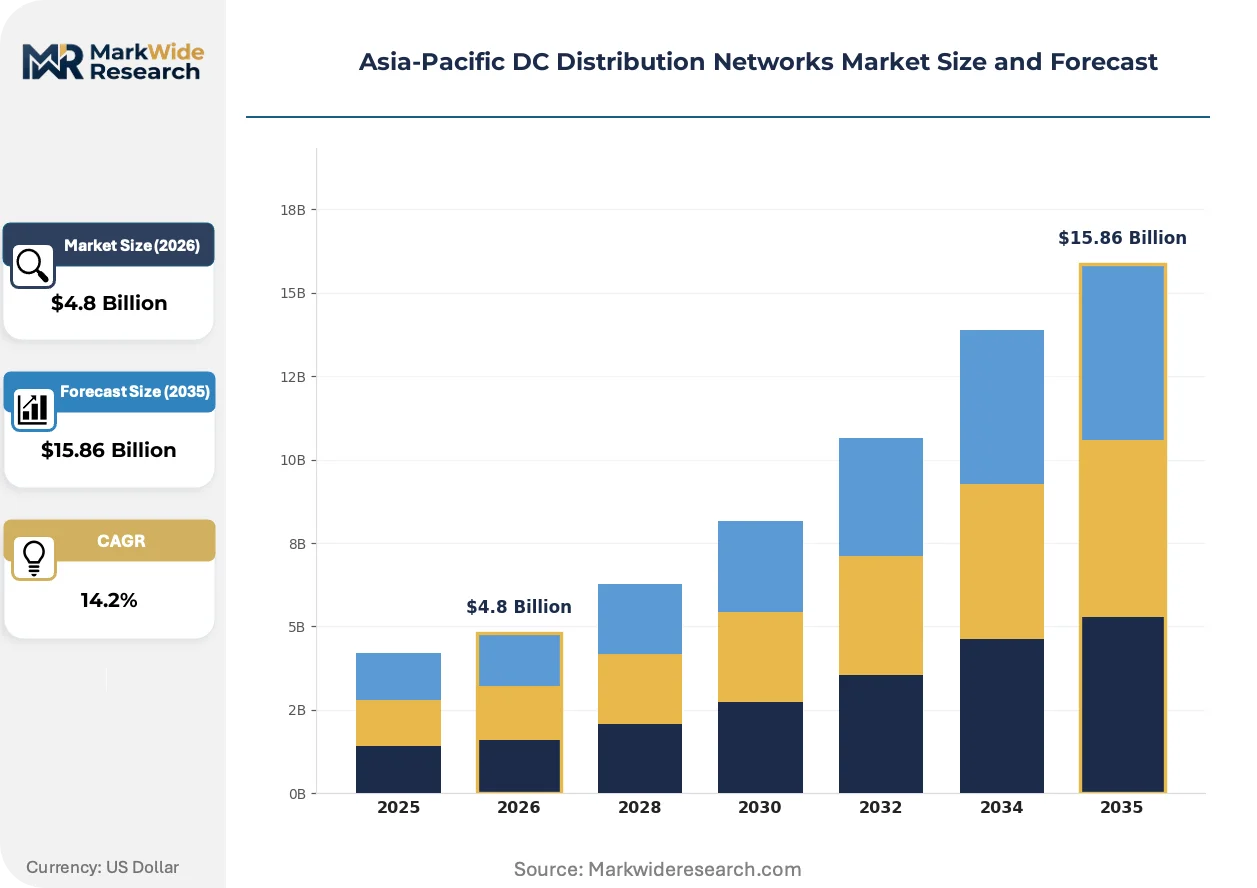
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transformers, Switchgears, Circuit Breakers, Relay Panels Installation Type: Outdoor, Indoor, Enclosed, Modular End User: Telecom, Data Centers, Industrial Facilities, Commercial Buildings Technology: Digital Control, Remote Monitoring, Automated Systems, Energy Management |
| Companies Covered | ABB Ltd, Siemens Ltd, Vertiv Group Corp, Eaton Corporation PLC, Secheron Sa, Delta Electronics, Inc., Huawei Digital Power Technologies Co., Ltd., Mitsubishi Electric Corporation, Hitachi Energy Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific DC Distribution Networks Market Strategic Shifts
Modular power conversion architectures and software-defined control systems are displacing centralized electromechanical switchgear across Asia-Pacific industrial and data center applications, compressing deployment timelines and enabling predictive maintenance models.
Solid-state circuit breaker technology is modularizing fault protection in medium-voltage DC networks. Japanese heavy electrical manufacturers are piloting 1500 V DC silicon carbide breakers for rail electrification retrofits. This modularity is enabling containerized substation designs that slash on-site commissioning from weeks to days.
METI's technical guidelines for DC microgrids issued in 2023 are reshaping procurement specifications across Northeast Asian utility tenders. The framework mandates bidirectional power flow capability and cyber-physical security protocols. Data center operators in Tokyo and Osaka are now requiring IEC 62443-4-2 certification for DC distribution control systems.
Hyperscale operators are consolidating supplier relationships around integrated power conversion and thermal management vendors. Singapore-based colocation providers are negotiating multi-year DC infrastructure contracts with performance-guarantee clauses. This concentration is most visible in Australia's eastern states, where renewable-powered data center projects specify single-source accountability for power architecture.
Asia-Pacific DC Distribution Networks Market Segmentation
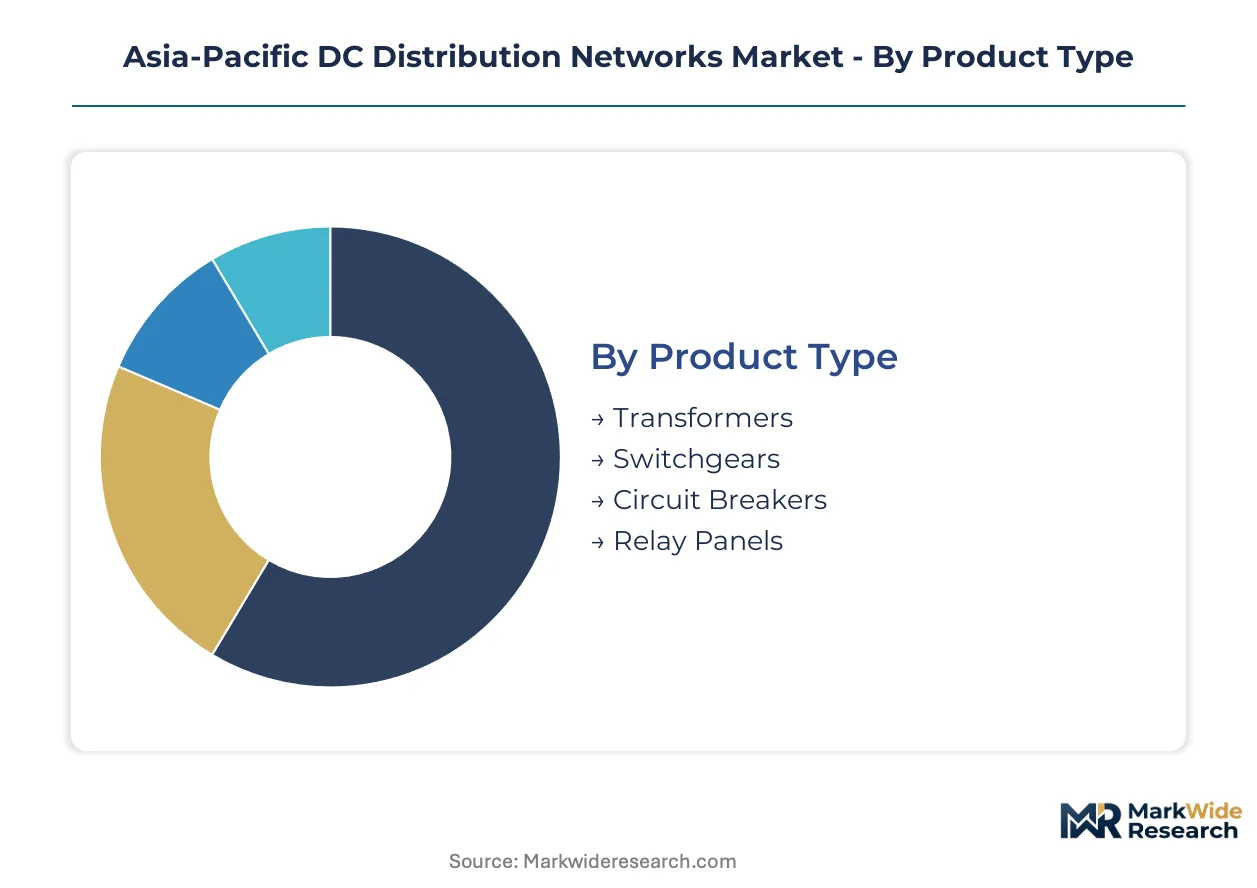
DC distribution networks in Asia-Pacific fragment across four structural dimensions that determine procurement economics. Product type and installation configuration shape capital outlay and maintenance regimes, while end-user verticals and control technology stratify margin profiles.
Product Type:
Buyers differentiate primarily by fault-current handling requirements and voltage class, with utility-scale renewable tenders demanding higher interrupting capacity than commercial installations.
- Switchgears:Metal-enclosed assemblies housing busbars, circuit breakers, and protective relays for fault isolation in medium-voltage DC networks. Demand clusters in Chinese grid modernization projects and Indian solar parks above 250 MW, where MIIT and CEA mandates disqualify electromechanical alternatives.
- Circuit Breakers:Solid-state and hybrid interruption devices rated for 1500 V DC and below, eliminating arc flash hazards in data center bus architectures. Singaporean hyperscale operators specify these for 380 V DC compute halls to reduce conversion stage losses.
- Transformers:DC-DC conversion choppers and buck-boost stages for voltage level translation in microgrid applications.
- Relay Panels:Protection and control assemblies coordinating overcurrent and differential protection schemes across distributed generation nodes.
Volume sits with Switchgears; growth tilts toward Circuit Breakers.
Installation Type:
Site constraints and environmental exposure dictate enclosure specifications, with coastal humidity and seismic zones driving material selection.
- Outdoor:Weather-resistant switchgear lineups with IP65 ingress protection and anti-corrosion coatings for utility substations and solar farm collection points. Deployment concentrates in Australian renewable zones and Indian desert solar parks where ambient temperatures exceed 45°C.
- Modular:Skid-mounted or containerized power conversion substations enabling rapid deployment and future relocation. Japanese data center developers in Osaka and Tokyo favor these for phased capacity expansion with minimized civil works.
- Indoor:Switchgear assemblies for climate-controlled electrical rooms in commercial and industrial facilities.
- Enclosed:Compact integrated units for space-constrained urban installations and retrofit applications.
Outdoor commands current procurement volumes; Modular is expanding most quickly.
End User:
Power density requirements and reliability tiers separate buyers, with uptime guarantees driving specification stringency.
- Data Centers:Hyperscale and colocation facilities deploying 380 V DC bus architectures to eliminate AC-DC conversion losses in compute-dense environments. Singapore, Sydney, and Tokyo operators specify IEC 62443-4-2 certified control systems following METI guidelines.
- Telecom:Mobile network operators and tower companies requiring -48 V DC distribution for base station power and battery backup integration.
- Industrial Facilities:Process plants and manufacturing sites with captive renewable generation and DC motor loads.
- Commercial Buildings:High-rise developments and district cooling plants integrating DC microgrids for HVAC and lighting.
Data Centers anchor premium pricing; Industrial Facilities show steepest expansion trajectory.
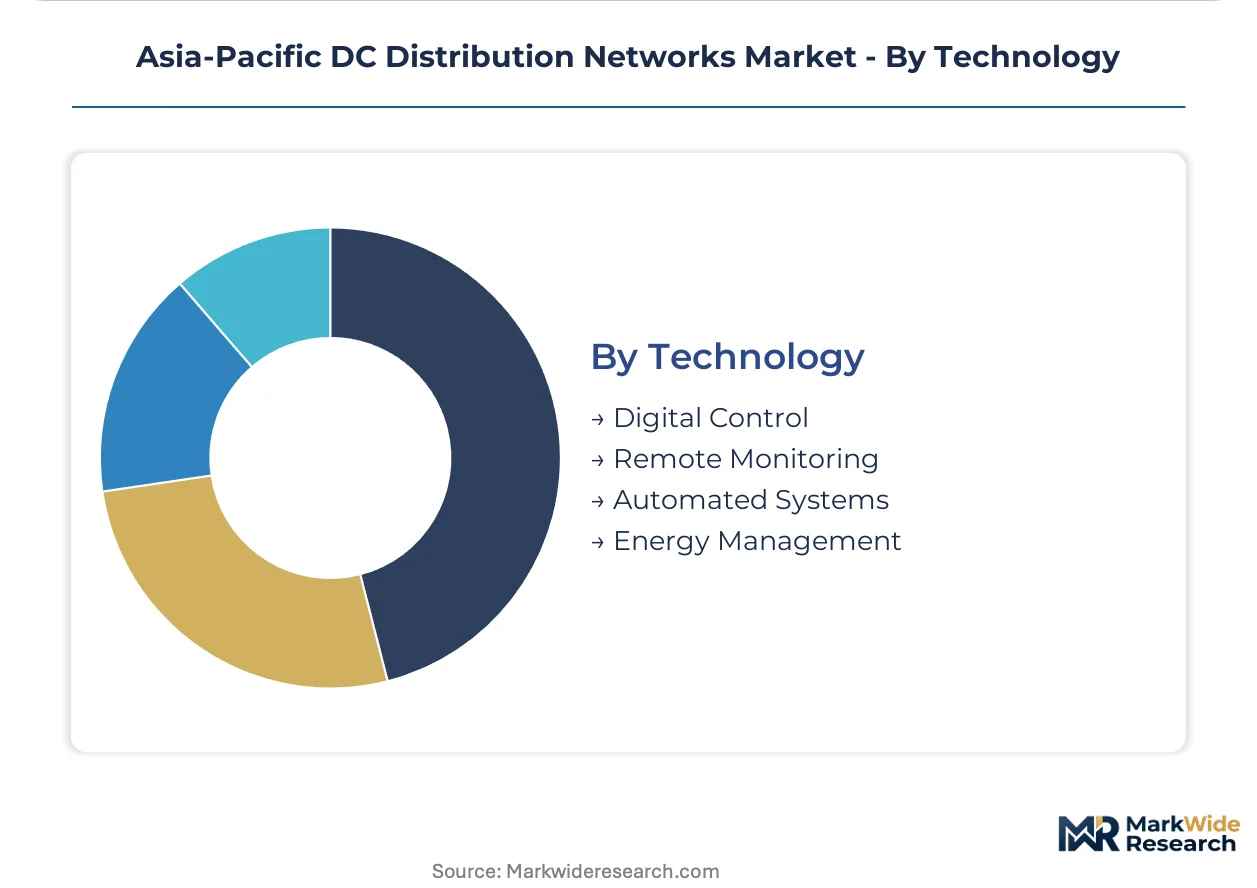
Technology:
Control sophistication determines maintenance economics and operational visibility, with software-defined architectures commanding 15-25% price premiums.
- Digital Control:Microprocessor-based protection relays and programmable logic controllers enabling adaptive protection settings and event logging. Australian grid interconnection rules now mandate these for renewable integration projects above 100 MW.
- Remote Monitoring:SCADA and cloud-connected diagnostics reducing truck rolls and enabling predictive maintenance for distributed assets.
- Automated Systems:Self-healing network reconfiguration and automatic transfer schemes for critical load continuity.
- Energy Management:Optimization algorithms balancing generation, storage, and load dispatch across multi-node DC microgrids.
Digital Control dominates current shipments; Energy Management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China compresses the largest procurement volumes for DC distribution equipment, with state-backed grid modernization and dual carbon mandates forcing rapid infrastructure turnover across provincial utilities and industrial zones.
China
MIIT efficiency standards are disqualifying legacy AC-DC conversion architectures from state-backed tenders. Provincial grid operators in Jiangsu and Guangdong are accelerating procurement of high-voltage DC switchgear for renewable integration clusters. Manufacturing scale advantages anchor supply contracts for domestic equipment suppliers serving these modernization projects.
India
CEA renewable integration rules mandate DC-ready distribution infrastructure for solar parks above 250 MW capacity. BIS certification timelines of 18-24 months for imported protection equipment favor domestic assembly partnerships over pure import strategies. Rajasthan and Gujarat desert solar parks are driving concentrated demand for outdoor-rated switchgear assemblies.
Japan
METI technical guidelines for DC microgrids issued in 2023 mandate bidirectional power flow capability and cyber-physical security protocols. Data center operators in Tokyo and Osaka now require IEC 62443-4-2 certification for DC distribution control systems. Osaka-based developers favor modular containerized substations for phased capacity expansion.
Singapore
Hyperscale operators are specifying 380 V DC bus architectures to eliminate conversion losses in compute-dense facilities. Colocation providers are negotiating multi-year DC infrastructure contracts with performance-guarantee clauses. The city-state's tropical humidity and space constraints drive demand for compact enclosed switchgear designs.
Australia
Grid interconnection rules now mandate digital control systems for renewable integration projects above 100 MW. Eastern states renewable-powered data center projects specify single-source accountability for power architecture. Queensland and New South Wales utility-scale solar zones are deploying outdoor-rated DC collection systems for high-temperature ambient conditions.
Asia-Pacific DC Distribution Networks Market Competitive Environment
Chinese producers anchor one tier through manufacturing scale and domestic certification advantages; European and Japanese specialists hold premium positioning through digital control integration and reliability engineering. The vendor base stratifies across three tiers: diversified electrical conglomerates with full portfolio coverage, power electronics specialists with semiconductor integration capabilities, and regional system integrators with local certification relationships. Competitive moves concentrate on strategic partnerships with data center developers and capacity expansion in Vietnam and India to circumvent tariff and certification barriers.
Among diversified electrical conglomerates, ABB Ltd and Siemens Ltd represent archetypes of scale-driven positioning with integrated digital twin and control platform offerings. Huawei Digital Power Technologies Co., Ltd. exemplifies the power electronics specialist tier through in-house semiconductor production capabilities that reduce import dependency. These three entities anchor distinct competitive vectors within the regional market structure.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens Ltd |
| Vertiv Group Corp |
| Eaton Corporation PLC |
| Secheron Sa |
| Delta Electronics, Inc. |
| Huawei Digital Power Technologies Co., Ltd. |
| Mitsubishi Electric Corporation |
| Hitachi Energy Ltd |
| Others |
Value Chain & Pricing Dynamics
Solid-state circuit breaker technology is compressing cost economics while redrawing supplier power across the Asia-Pacific DC distribution networks landscape, as silicon carbide module production concentrates manufacturing advantage among vertically integrated power electronics specialists.
Pricing Analysis
Volume concentrates in standardized switchgear assemblies for utility-scale solar parks, while margins pool in digital control platforms and solid-state protection devices for hyperscale data centers. Three-tier pricing structure across IEC 62443-certified premium, MIIT-compliant standard, and non-certified economy levels separates buyers by reliability tier and cyber-physical security requirements. Cost compression in copper-intensive busbar assemblies is intensifying because metal price volatility now constitutes 35-40% of bill-of-materials exposure. Industrial facility buyers in India and Vietnam exhibit highest price sensitivity due to project-based procurement cycles, whereas Singaporean colocation operators prioritize performance-guarantee clauses over unit cost.
Supply Chain Analysis
Regional distribution centers in Singapore, Shanghai, and Tokyo anchor hub-and-spoke fulfillment patterns for DC protection equipment across Southeast Asian project sites. Power semiconductor fabrication draws from Taiwan, South Korea, and Japan, while copper busbar processing and electromechanical component assembly centers on China and India. Single-source vulnerability in silicon carbide wafer supply creates exposure to geopolitical disruption and export control tightening. Distribution runs through authorized system integrators with BIS or MIIT certification relationships rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific DC distribution networks market sits in a technology-transition phase where software-defined control architectures are displacing electromechanical relay systems, forcing incumbents and challengers to recalibrate capability investments around semiconductor integration and predictive maintenance platforms.
For Market Incumbents: Lock in long-term supply contracts for silicon carbide modules before capacity constraints tighten, while accelerating certification of digital twin platforms against METI's cyber-physical security protocols to defend against emerging power electronics specialists with in-house semiconductor production. Prioritize backward integration into power conversion module manufacturing to reduce exposure to Taiwan and South Korean foundry concentration. For New Entrants and Emerging Players: Enter via Vietnam's Bac Ninh and Hai Phong industrial corridors, where export-oriented electronics assembly is generating captive demand for DC microgrid infrastructure with minimal incumbent saturation. Target modular containerized substation configurations for Japanese data center developers seeking phased capacity expansion, leveraging partnerships with regional EPC contractors already embedded in METI-compliant procurement channels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified electrical conglomerates seeking semiconductor integration capabilities and Asia-Pacific certification relationships. Long-term viability favors power electronics specialists with captive SiC module supply and software-defined control platforms over pure-play electromechanical component manufacturers. Watch for inflection when CEA mandates extend DC-ready infrastructure requirements below the current 250 MW solar park threshold.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Module Production | Reduces dependency on Taiwan and South Korean foundry capacity for DC switchgear fabrication. |
| MIIT Efficiency Certification Investment | Unlocks state-backed tender participation in Jiangsu and Guangdong grid modernization projects. |
| Modular Containerized Substation Development | Addresses Japanese data center demand for rapid deployment with minimized civil engineering. |
| Digital Twin Platform Integration | Commands 15-25% pricing premiums through predictive maintenance and adaptive protection settings. |
| Vietnam Manufacturing Footprint Expansion | Circumvents India's 18-24 month BIS certification timelines for imported protection equipment. |
Study Parameters
Regulatory filings from MIIT, CEA, and METI, customs trade databases, and utility procurement tender records formed the secondary backbone for market sizing and policy trajectory assessment. Primary interviews with power electronics engineering directors, data center infrastructure procurement leads, utility grid planning officers, and EPC project managers in China, India, Japan, and Singapore validated technical adoption timelines and pricing dynamics. Bottom-up unit economics for switchgear, circuit breaker, and control system shipments were triangulated against top-down utility capex and hyperscale data center construction forecasts.
Bottom-up modeling segmented volume and value across product type, installation configuration, end-user vertical, and control technology sophistication, then reconciled against macro-level renewable integration targets and data center power capacity pipelines. CAGRs were derived from regression analysis of historical procurement patterns against regulatory mandate implementation schedules and semiconductor supply expansion trajectories. Forecast inputs incorporated copper price volatility assumptions, BIS certification timeline distributions, and METI guideline adoption curves across Northeast Asian utility tenders.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Taiwan Strait logistics disruption or accelerated CEA mandate expansion to sub-250 MW solar installations. Periodic stress-testing of base assumptions against MIIT efficiency standard revision schedules and hyperscale operator consolidation patterns is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Silicon-Controlled Rectifier (SCR) Market
Power Systems
Three Phase Micro Inverters Market
Power Systems
Laptop Battery Market
Power Systems
Thyristor Surge Protectors Market
Power Systems
Flyback Transformer Market
Power Systems
South America DC Distribution Network Market
Power Systems
Transformer Tap Changers and Voltage Control Relay Market
Power Systems
Surface Mounted Medium Voltage Distribution Panel Market
Power Systems
US Variable Frequency Drive Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
Semiconductor Rectifier Market
Power Systems
Ultrafast Rectifiers Market
Power Systems
Asia Pacific Battery Management System Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Intelligent Power Module (IPM) Market